
 Automotive Digital Instrument Cluster Market | 2026-2036
Automotive Digital Instrument Cluster Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Digital Instrument Cluster Market Analysis
The split between premium full-digital suites and cost-optimized combination clusters is realigning procurement strategies across the supply base. Continental AG leverages its integrated display-controller capabilities to anchor high-margin programs with European OEMs. Robert Bosch GmbH competes through manufacturing scale across multiple TFT and OLED supply tiers. Nippon Seiki Co., Ltd. specializes in precision analog-digital hybrid architectures for mass-market Asian platforms.
An automotive digital instrument cluster constitutes an electronic display system replacing or supplementing traditional mechanical gauges, typically integrating LCD, OLED, or projection technology to render vehicle speed, battery state, navigation, and advanced driver-assistance alerts on screens ranging from seven to fifteen inches. Its primary purpose is to consolidate safety-critical and convenience information within the driver's line of sight while enabling software-defined reconfiguration across vehicle programs. Full digital display configurations now lead value generation as OEMs standardize twelve-inch and larger formats for electric vehicle architectures. OLED technology segments command premium positioning due to contrast ratios and power efficiency in daylight-readable automotive environments, while LCD retains volume dominance across mid-range passenger and commercial applications.
The National Highway Traffic Safety Administration in the United States and the European Union's General Safety Regulation collectively mandate standardized warning symbology and minimum display legibility, directly shaping cluster interface design and validation protocols. China's Ministry of Industry and Information Technology enforces GB standards for electromagnetic compatibility and display flicker that constrain import market access. Stakeholders must monitor diverging regional certification timelines for software-over-the-air update capabilities as regulators debate whether instrument cluster graphics constitute safety-critical firmware subject to type-approval lockdown.
Market Dynamics
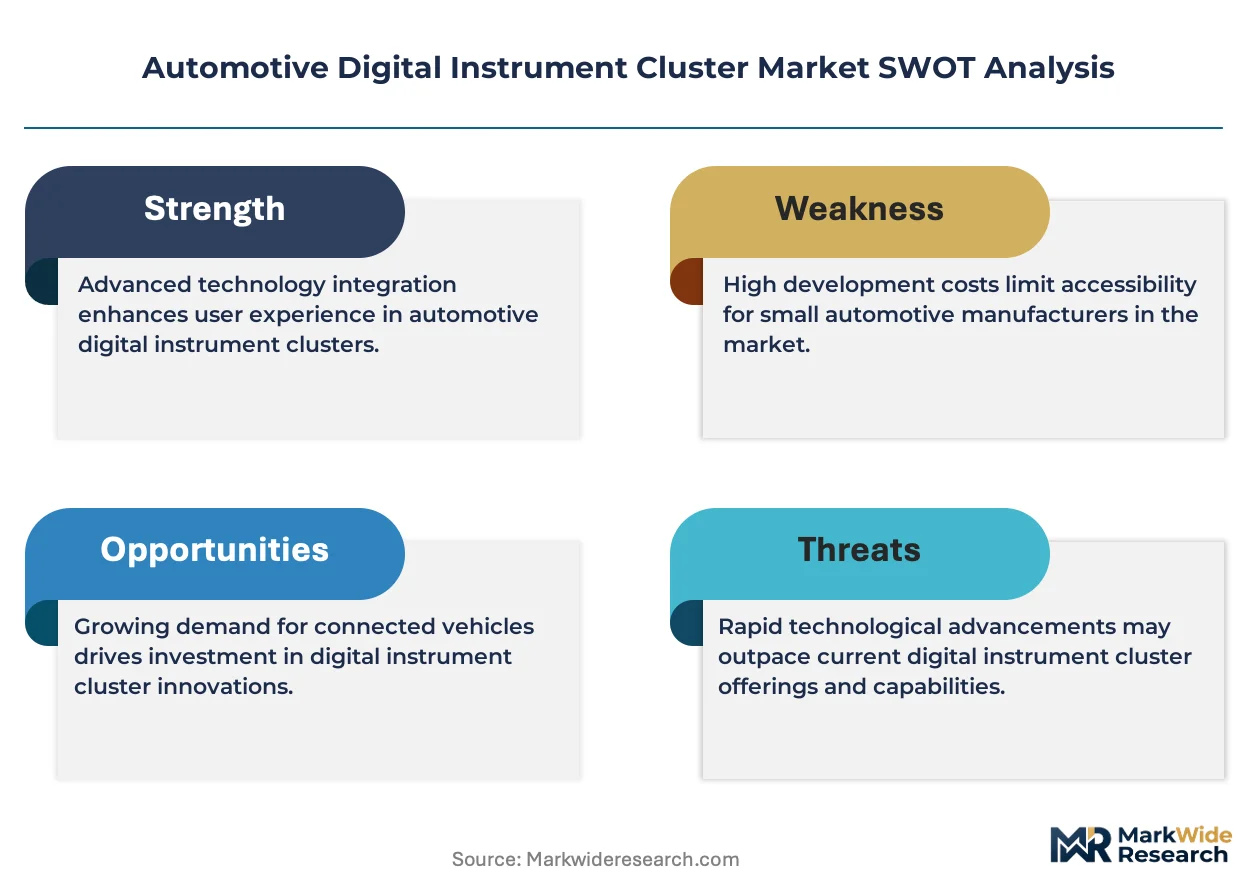
Software-defined vehicle architectures are compressing hardware refresh cycles as OEMs prioritize over-the-air updatable display systems over fixed-function instrument clusters. This shift restructures supplier relationships toward firmware-capable tier-1s and away from pure hardware manufacturers.
Growth Catalysts
- EU General Safety Regulation:Mandated standardized warning symbology and minimum legibility requirements force OEMs toward full-digital clusters with configurable alert zones, eliminating analog gauge retention.
- 12-inch OLED penetration:Electric vehicle platforms in Germany and China specify high-contrast, daylight-readable displays for battery state and navigation integration, pulling premium display procurement forward.
- NHTSA type-approval pathways:Clarified validation protocols for reconfigurable driver information systems reduce regulatory uncertainty for US-market cluster deployments.
Market Restraints
- TFT-LCD panel concentration:Display substrate supply concentrates among Korean and Taiwanese foundries, exposing OEMs to single-source risk for mid-range cluster volumes.
- Automotive-grade OLED yield constraints:Burn-in mitigation and temperature cycling requirements limit viable suppliers to two dominant panel makers, constraining price competition.
- GB electromagnetic compatibility testing:China's MIIT certification timelines for display flicker and radiated emissions add six to nine months to import market entry for non-domestic suppliers.
Strategic Opportunities
- Commercial vehicle digitization:Fleet operators in the United States and Germany seek telematics-integrated instrument clusters for route optimization and driver behavior monitoring, a segment still dominated by analog-digital hybrids.
- Head-up display convergence:Windshield projection systems merging with cluster graphics create unified augmented reality navigation experiences for premium electric vehicles.
- Software-over-the-air monetization:Subscription-enabled cluster themes and feature unlocks generate recurring revenue streams beyond initial hardware procurement.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-B certification expertise for graphics rendering pipelines commands premium salaries, delaying program timelines for tier-2 suppliers.
- Legacy vehicle integration complexity:CAN bus protocol fragmentation across model years requires extensive backward compatibility testing for replacement cluster retrofits.
- Intellectual property fragmentation:Touch gesture patents held by consumer electronics firms create licensing friction for cluster interface designers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Digital Instrument Cluster Market |
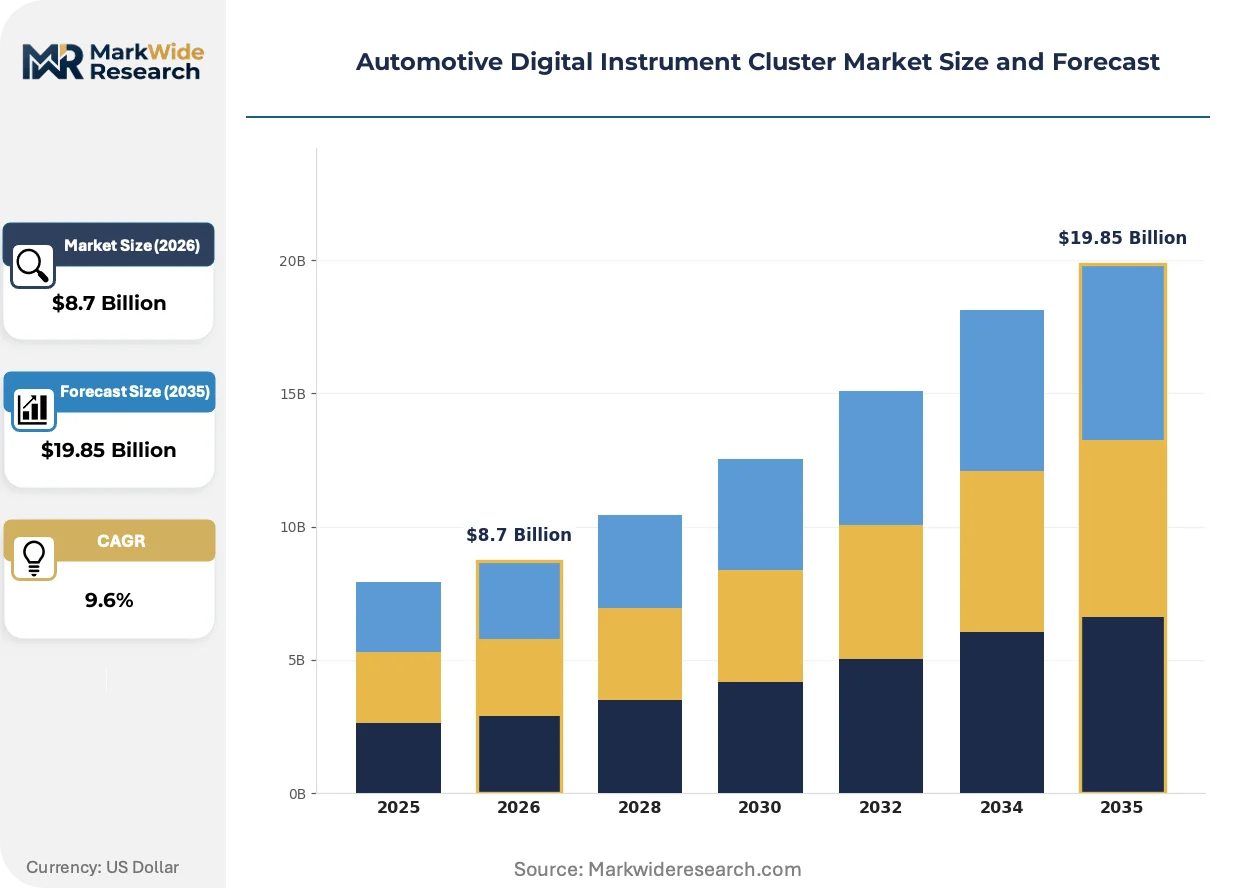
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.85 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Digital Display, Head-Up Display, Analog-Digital Combination, TFT Display End User: OEMs, Aftermarket Suppliers, Tier-1 Manufacturers, Vehicle Assemblers Technology: LCD, OLED, LED, Projection Technology Size: 7 Inch, 10 Inch, 12 Inch, 15 Inch |
| Companies Covered | Denso Corporation, Aptiv PLC, Continental AG, Hyundai Mobis, Panasonic Automotive, Robert Bosch GmbH, Marelli, Nippon Seiki Co., Ltd., Visteon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Digital Instrument Cluster Market Emerging Trajectories
Display subsystem architectures are fragmenting into domain-specific compute modules as OEMs decouple instrument cluster graphics from centralized infotainment stacks. This decomposition enables independent update cadences and supplier selection.
MicroLED backlighting is modularizing cluster display construction by separating emitter arrays from driver substrates, allowing tier-1s to source components from specialized vendors rather than captive panel suppliers. German premium OEMs pilot this architecture for 2027 model year electric vehicles. The technology is modularizing supply chain relationships and compressing display module lead times from fourteen weeks to eight.
NHTSA's 2024 updated Federal Motor Vehicle Safety Standard 101 tightens legibility requirements for secondary information displays, directly impacting font rendering and contrast ratio specifications. Cluster software teams must revalidate human-machine interface libraries against revised photometric test protocols. US-market full-digital configurations face the steepest compliance burden, accelerating adoption of pre-certified graphics middleware.
Fleet procurement departments now specify outcome-based service contracts tying cluster hardware availability to uptime guarantees rather than capital expenditure schedules. Leasing companies and rental fleet operators in Germany lead this shift, pressuring tier-1s to absorb obsolescence risk. This model concentrates purchasing authority among large fleet aggregators and marginalizes small-volume OEM direct sales.
Automotive Digital Instrument Cluster Market Segmentation
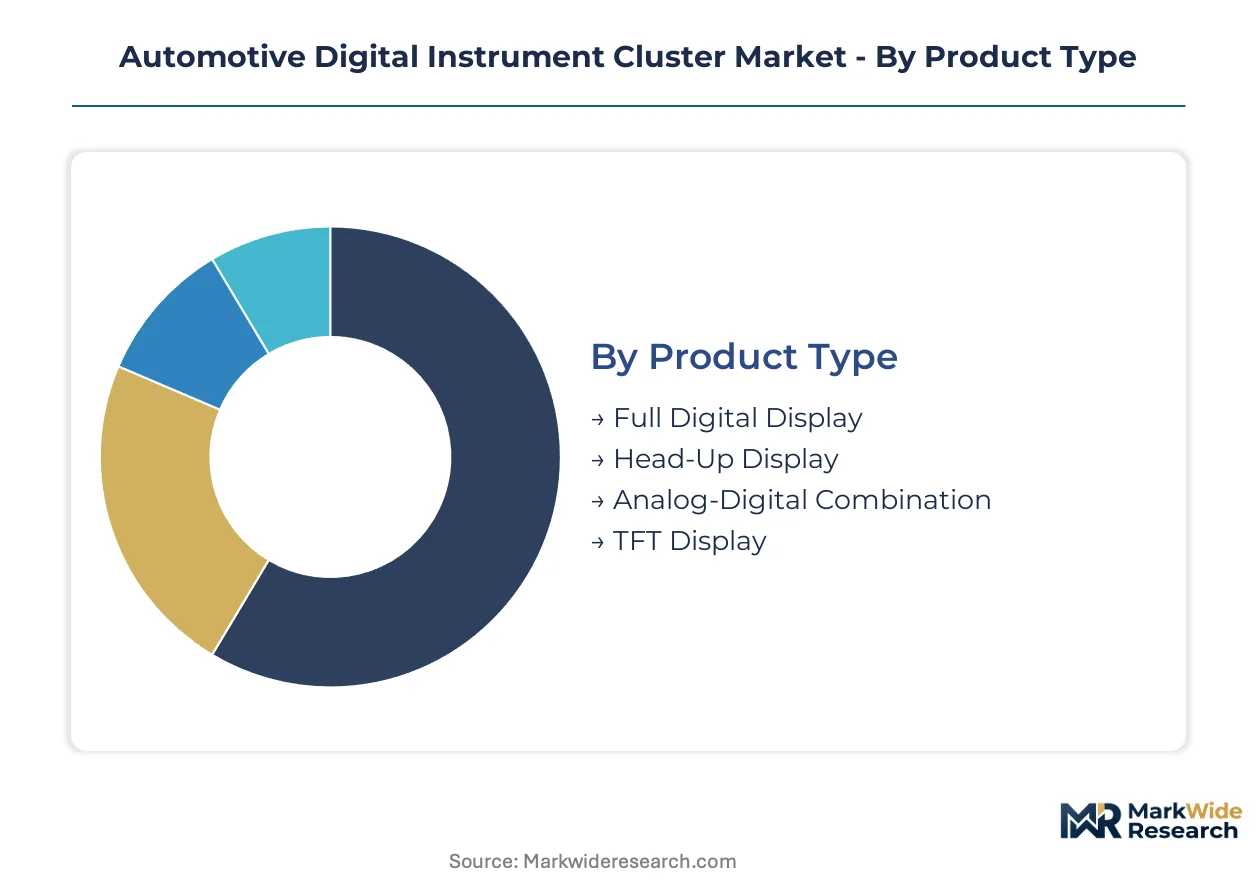
Procurement patterns in automotive digital instrument clusters diverge sharply across product architectures and display technologies. OEMs segment their sourcing strategies based on reconfigurability requirements, safety certification tiers, and integration complexity with centralized vehicle compute platforms.
Product Type:
Supply concentration among German and Korean panel foundries shapes availability and lead times for each cluster architecture variant.
- Full Digital Display:Reconfigurable screen systems replacing all mechanical gauges with software-rendered instruments, typically twelve-inch or larger. Electric vehicle platforms in Germany and China specify these for battery state visualization and navigation integration, pulling procurement toward premium OLED-capable suppliers.
- Head-Up Display:Windshield projection systems rendering speed and navigation cues within the driver's forward sightline. US premium OEMs accelerate adoption as NHTSA tightens legibility requirements for secondary information displays, compressing validation timelines.
- Analog-Digital Combination:Hybrid architectures retaining mechanical gauges alongside embedded digital screens. Mass-market Asian platforms favor these for cost containment and supply chain flexibility.
- TFT Display:Thin-film transistor LCD configurations dominating mid-range passenger volumes. Korean and Taiwanese substrate concentration exposes OEMs to single-source risk during demand spikes.
Today's leader: Full Digital Display. Tomorrow's challenger: Head-Up Display.
End User:
Customer type determines firmware update responsibility, warranty exposure, and regulatory liability distribution across the value chain.
- OEMs:Vehicle manufacturers specifying cluster architectures during platform development. German and Chinese electric vehicle OEMs drive twelve-inch full-digital procurement as NHTSA and EU safety mandates harden requirements.
- Aftermarket Suppliers:Replacement cluster providers serving legacy vehicle retrofits. CAN bus protocol fragmentation across model years forces extensive backward compatibility testing, delaying program timelines.
- Tier-1 Manufacturers:Integrated system suppliers managing display-controller-firmware bundles. These entities absorb obsolescence risk under emerging outcome-based service contracts from German fleet operators.
- Vehicle Assemblers:Contract manufacturers integrating pre-specified cluster modules. Their procurement authority concentrates on cost-optimized TFT-LCD configurations for volume production.
Fleet operators and OEMs currently dominate purchasing volume. Tier-1s are gaining share fastest through firmware-capable integrated offerings.
Technology:
Display substrate chemistry determines power efficiency, daylight readability, and automotive-grade qualification burden.
- LCD:Liquid crystal display technology retaining volume dominance across mid-range passenger and commercial applications. Mature supply chains and lower qualification costs sustain procurement preference for cost-sensitive programs.
- OLED:Organic light-emitting diode panels commanding premium positioning due to contrast ratios and power efficiency. Burn-in mitigation and temperature cycling requirements limit viable suppliers to two dominant panel makers, constraining price competition.
- LED:Direct-view LED arrays for specialized commercial vehicle applications requiring extreme brightness. Niche penetration concentrates in heavy-duty trucking segments.
- Projection Technology:Micro-mirror and laser scanning systems enabling head-up display functionality. German premium OEMs pilot augmented reality navigation convergence for upcoming electric vehicle architectures.
LCD maintains current volume leadership. OLED climbs the fastest as electric vehicle platforms proliferate.
Size:
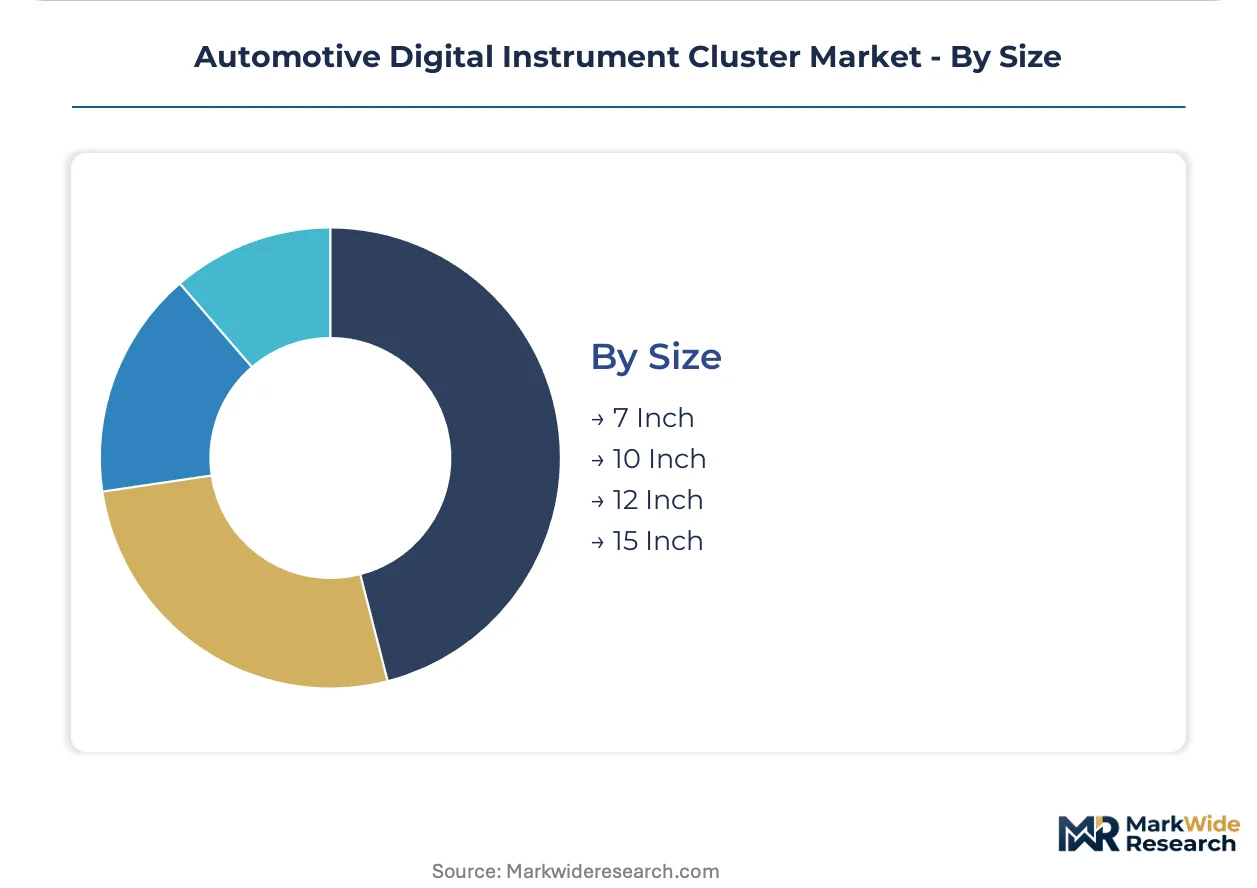
Screen diagonal measurement directly correlates with information density requirements and safety-critical alert zone allocation.
- 7 Inch:Compact configurations for economy passenger segments and commercial vehicle retrofits. Cost-optimized TFT-LCD substrates dominate this specification tier.
- 10 Inch:Mid-range standardization point balancing reconfigurability with dashboard packaging constraints. Asian mass-market platforms concentrate procurement here.
- 12 Inch:Premium electric vehicle baseline enabling split-screen battery monitoring alongside navigation. German and Chinese OEMs specify this format for new platform launches.
- 15 Inch:Maximum reconfigurable canvas for luxury segments integrating cluster and infotainment graphics. Limited supplier qualification constrains procurement flexibility.
Twelve-inch configurations anchor current premium procurement. Fifteen-inch formats face steepest expansion trajectory as display-controller integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Functional safety engineers cluster in Stuttgart, Munich, and Wolfsburg, anchoring Europe's dominance in ASIL-certified cluster firmware development. Asian display substrate foundries concentrate process engineers in Seoul and Taichung, while Silicon Valley software talent drives augmented reality integration for US premium OEMs.
United States
NHTSA's 2024 FMVSS 101 update tightens legibility requirements for secondary information displays, forcing OEMs toward pre-certified graphics middleware. Electric vehicle startups in Austin and the Bay Area accelerate twelve-inch full-digital procurement for battery state visualization. Detroit's tier-1 engineering centers absorb validation workload for reconfigurable driver information systems.
Germany
KBA type-approval protocols for software-over-the-air updates create compliance complexity for instrument cluster graphics. BMW and Mercedes-Benz electric architectures in Munich and Stuttgart specify OLED-capable twelve-inch configurations. Continental AG and Robert Bosch GmbH anchor high-margin supply relationships through integrated display-controller capabilities.
China
MIIT enforces GB electromagnetic compatibility standards that add six to nine months to import market entry for non-domestic suppliers. NIO, XPeng, and BYD in Shenzhen and Shanghai drive premium OLED procurement for new energy vehicle platforms. Domestic panel foundries in Hefei and Beijing expand automotive-grade TFT-LCD capacity for mid-range volumes.
Japan
METI's automotive software standards influence cluster firmware architecture for export-market vehicles. Toyota and Honda in Toyota City and Tokyo retain hybrid analog-digital configurations for mass-market cost containment. Nippon Seiki Co., Ltd. specializes in precision hybrid architectures serving Asian platform requirements.
South Korea
Korean display substrate concentration exposes OEMs to single-source risk during demand spikes for mid-range cluster volumes. Hyundai Mobis and Samsung Display in Seoul and Suwon anchor domestic electric vehicle cluster supply. Government battery subsidies accelerate local OEM procurement of reconfigurable full-digital systems.
Automotive Digital Instrument Cluster Market Vendor Landscape
Top-tier vendors anchor integrated display-controller-firmware bundles, while mid-tier specialists compete on manufacturing scale across multiple TFT and OLED supply tiers. The supplier base fragments between firmware-capable tier-1s absorbing obsolescence risk and pure hardware manufacturers facing compressed margins. Three archetypes dominate: integrated system suppliers, display substrate specialists, and precision hybrid architects. M&A activity concentrates on graphics middleware acquisitions, while capacity expansion focuses on automotive-grade OLED foundry investment.
Among German-based integrated suppliers, Continental AG and Robert Bosch GmbH occupy positions exemplifying the firmware-capable tier-1 archetype. Nippon Seiki Co., Ltd. represents the precision hybrid specialist segment serving cost-sensitive mass-market platforms. These three entities illustrate how geographic clustering around Stuttgart and Tokyo shapes competitive positioning through proximity to OEM engineering centers and regulatory expertise.
| Leading Market Players |
|---|
| Denso Corporation |
| Aptiv PLC |
| Continental AG |
| Hyundai Mobis |
| Panasonic Automotive |
| Robert Bosch GmbH |
| Marelli |
| Nippon Seiki Co., Ltd. |
| Visteon Corporation |
| Others |
Supply Flow & Price Mechanics
Display substrate costs cascade from Korean and Taiwanese foundries through three distinct procurement tiers, with automotive-grade OLED qualification burden separating premium twelve-inch configurations from cost-optimized TFT-LCD alternatives in mass-market sourcing.
Pricing Analysis
Bundled firmware-controller-display packages command premium positioning against unbundled hardware-only procurement. Three-tier pricing structure across premium OLED, standard TFT-LCD, and economy hybrid configurations reflects ASIL-B certification investment and volume scale. Price differentiation hinges on software-over-the-air capability and after-sales service bundling. Cost compression in mid-range TFT segments intensifies as Chinese domestic panel capacity expands, while fleet operators in Germany exhibit lowest price sensitivity under outcome-based service contracts.
Supply Chain Analysis
China's local-content rules for MIIT GB certification are reshaping sourcing patterns toward Hefei and Beijing foundries. Korean and Taiwanese substrate concentration draws from specialized glass and semiconductor inputs, creating single-source vulnerability during demand spikes. Tariff exposure runs through cross-border controller chip shipments. Distribution runs through tier-1 system integrators absorbing obsolescence risk under long-term fleet service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU General Safety Regulation compliance costs in Germany diverge from China's accelerated domestic certification pathways, creating margin differential for suppliers with dual-qualification capabilities.
For Market Incumbents: Extend firmware-capable integrated offerings to capture outcome-based fleet contracts in Germany. Vertical integration into graphics middleware defends margin position against pure hardware competitors facing ASIL-B certification engineer scarcity. Capacity addition in Hefei hedges against Korean substrate concentration risk.
For New Entrants and Emerging Players: Begin with commercial vehicle digitization in the United States, where analog-digital hybrid replacement demand remains underpenetrated. Target telematics-integrated configurations for route optimization applications. A direct fleet sales channel bypasses entrenched tier-1 relationships with legacy OEMs.
For Investors and Strategic Acquirers: Consolidation pressure builds where functional safety expertise clusters in Stuttgart and Wolfsburg against fragmented hardware manufacturing across Asia. Long-term viability favors acquisition targets with ISO 26262 certification pipelines and established KBA type-approval track records. Monitor NHTSA software-over-the-air regulatory clarity as inflection indicator for valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enables over-the-air cluster updates that unlock recurring revenue streams beyond hardware sales. |
| Battery Supply Agreement | Secures OLED panel allocation for electric vehicle platforms specifying twelve-inch configurations. |
| Geographic Manufacturing Footprint | Establishes Hefei production to satisfy MIIT GB electromagnetic compatibility certification timelines. |
| Platform Standardization | Reduces ASIL-B validation burden across multiple OEM programs using common graphics middleware. |
| Charging Infrastructure Partnership | Integrates battery state visualization with route planning for fleet operator procurement decisions. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and dealership operations managers against secondary validation from vehicle production databases, IHS Markit registration data, NHTSA FMVSS filings, and KBA type-approval records. Bottom-up cluster shipment modeling and top-down automotive electronics spend analysis provided triangulation anchors.
Historical reference periods anchored the projection horizon through comparable-cycle analysis of electric vehicle platform launches and regulatory mandate implementation timelines. Segmentation dimensions spanned vehicle class, propulsion architecture, display technology tier, and regional production cluster. CAGRs derived from fitted growth curves applied to technology penetration assumptions across the modeling period. Industry-specific inputs included OLED yield improvement trajectories and firmware update monetization adoption curves.
Several conditions sit outside the modeled scope, including potential NHTSA reclassification of cluster graphics as safety-critical firmware subject to type-approval lockdown, and unforeseen GB standard revisions extending MIIT certification timelines. Forecasts reflect documented assumptions about regulatory pathway stability and display substrate supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive Steering Wheel Switch Market
Automotive Circuit Systems
Automotive Gear Position Sensor Market
Automotive Circuit Systems
Automotive Interface Chip Market
Automotive Circuit Systems
Dual Circuit Brakes System Market
Automotive Circuit Systems
In-Vehicle Computer System Market
Automotive Circuit Systems
Ignition Control Module Market
Automotive Circuit Systems
Backlit and Icon-Based Switch Systems for Commercial Vehicles Market
Automotive Circuit Systems
Global Automotive Control Panel Market
Automotive Circuit Systems
Japan Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Automotive Integrated Control Panel Market
Automotive Circuit Systems
Global Automotive Side Turn Indicator Market
Automotive Circuit Systems
Automotive Idle Air Control Valve Market
Automotive Circuit Systems
Automotive Pressure Switch Market
Automotive Circuit Systems
Automotive Oil Pressure Control Valve Market
Automotive Circuit Systems
Driveline Control Systems and Devices Market
Automotive Circuit Systems
Automotive Digital Isolators Market