
 Japan Automotive Adaptive Lighting System Market | 2026-2036
Japan Automotive Adaptive Lighting System Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Automotive Adaptive Lighting System Market Foresight
Modular headlamp platform bundling is shifting how Japanese OEMs procure adaptive lighting, collapsing separate high-beam and low-beam sourcing into single integrated modules. Stanley Electric Co. Ltd leverages its captive LED chip fabrication in Tsukuba to control cost architecture across matrix and laser product lines. Koito Manufacturing Co. Ltd anchors the premium OEM channel through long-term supply agreements with Toyota and Lexus assembly plants. Valeo Group competes by importing European glare-free algorithms while localizing actuator production in Yokohama.
Automotive adaptive lighting systems combine steerable or dimmable light sources with camera and radar inputs to project dynamic beam patterns that match road curvature, oncoming traffic, and weather conditions without driver intervention. These systems typically operate within voltage ranges of 12-48V and integrate CAN-bus communication protocols to synchronize with vehicle dynamics sensors in real time. Matrix LED modules command the dominant share of product type revenue due to their balance of precision dimming and thermal efficiency, while laser light configurations represent the fastest-expanding segment as Lexus and Nissan deploy them in flagship platforms. Intelligent lighting technology leads the technology dimension through its fusion of machine vision with predictive beam shaping, whereas glare-free high beam functions concentrate margin pools in the luxury vehicle segment where regulatory compliance meets brand differentiation.
METI enforces JIS D 5500 vehicle lighting standards that mandate minimum illuminance and glare limits, directly determining which adaptive technologies gain type approval for domestic sale. PMDA collaborates with METI on photobiological safety assessments for laser-based headlamp systems, creating a dual-gate compliance pathway for advanced light sources. Japan's Ministry of Land, Infrastructure, Transport and Tourism (MLIT) incorporates adaptive beam performance into its safety rating protocols, incentivizing OEM fitment. Stakeholders must monitor how METI's anticipated alignment with UNECE automated driving frameworks reshapes lighting-sensor integration requirements.
Market Dynamics
Matrix LED module consolidation is collapsing traditional high-beam and low-beam sourcing into unified procurement packages, forcing Japanese OEMs to renegotiate long-standing supplier relationships around integrated platform architectures rather than discrete component contracts.
Growth Catalysts
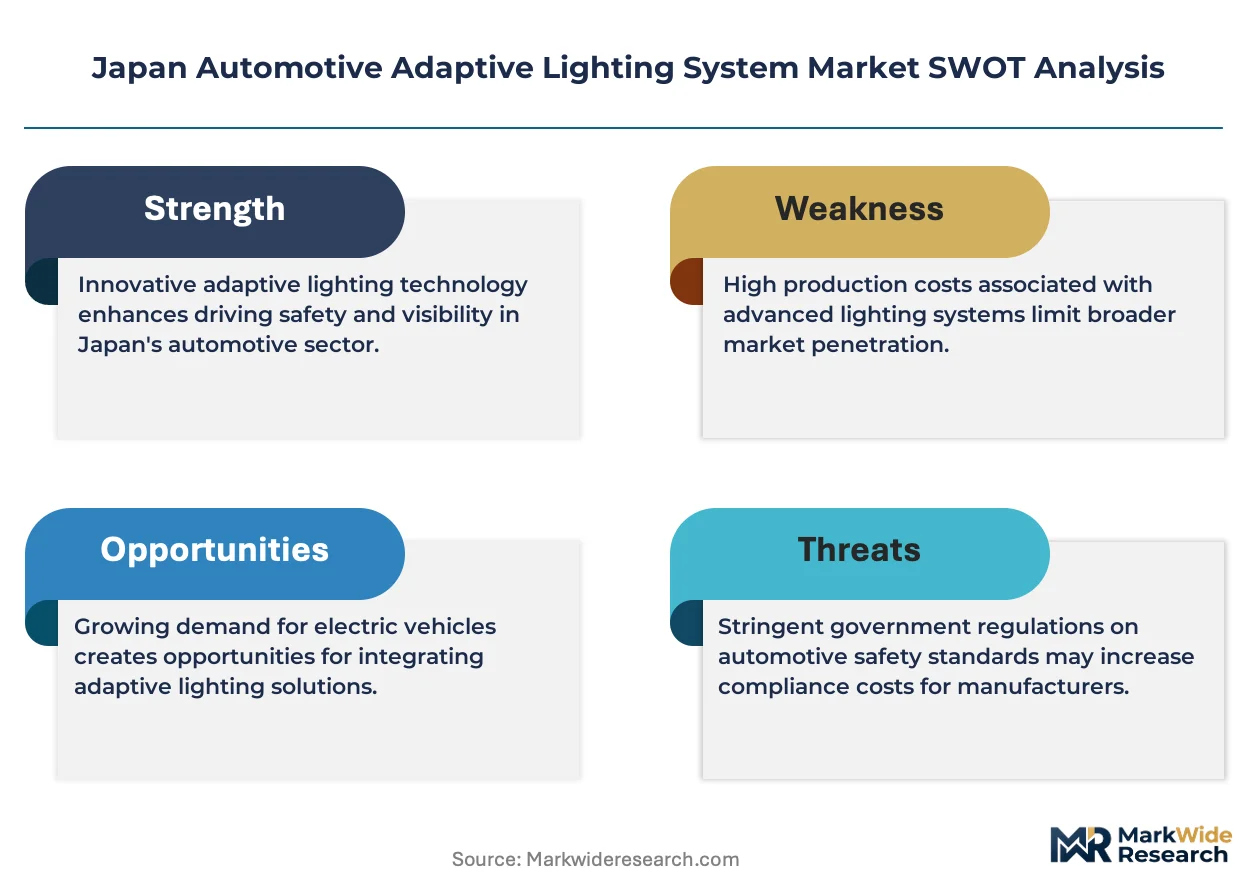
- METI JIS D 5500 alignment:Tightening beam precision mandates accelerate sensor-integrated headlamp adoption across domestic assembly lines.
- Premium passenger car segment:Lexus and Toyota flagship platforms drive matrix LED volume through brand differentiation requirements.
- Machine vision convergence:Predictive beam shaping algorithms fuse camera inputs with vehicle dynamics data for real-time road matching.
Market Restraints
- LED chip supply concentration:Captive fabrication capacity at Tsukuba limits second-source options for domestic tier-two suppliers.
- Laser photobiological compliance:PMDA dual-gate assessment pathways extend type-approval timelines for advanced light source introductions.
- 48V electrical architecture transition:Legacy 12V vehicle fleets constrain retrofit market penetration for high-power adaptive modules.
Strategic Opportunities
- Kanto regional cluster:Dense OEM assembly concentration around Toyota City and Yokohama enables just-in-sequence module delivery models.
- MLIT safety rating integration:Adaptive beam performance metrics in vehicle assessment protocols incentivize fitment across mid-tier nameplates.
- Radar-camera sensor fusion:Convergence of millimeter-wave and optical inputs creates new subsystem bundling opportunities for tier-one integrators.
Industry Challenges
- Embedded software talent scarcity:Shortage of automotive lighting control engineers delays algorithm localization for glare-free functions.
- Legacy CAN-bus integration:Real-time synchronization with existing vehicle dynamics networks requires extensive validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Automotive Adaptive Lighting System Market |
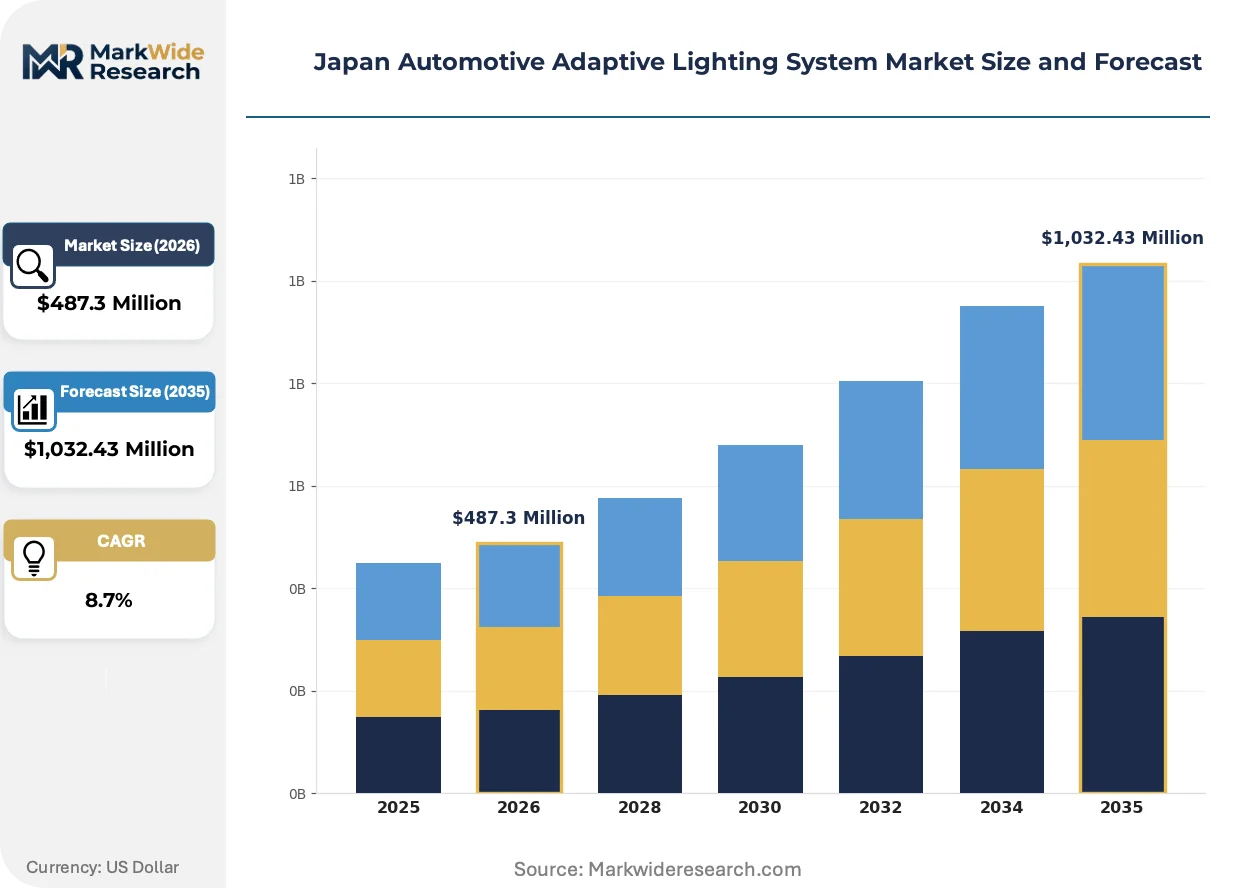
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Matrix LED, Laser Lights, Adaptive Xenon, Halogen Technology: Intelligent Lighting, Night Vision, Automatic Dimming, Glare-Free High Beam End User: OEMs, Aftermarket Customers, Luxury Vehicle Segment, Commercial Vehicles Application: Passenger Cars, SUVs, Light Trucks, Heavy Duty Trucks |
| Companies Covered | Stanley Electric Co. Ltd, Valeo Group, Koito Manufacturing Co. Ltd, Texas Instruments, Magneti Marelli SpA, HELLA KGaA Hueck & Co., OsRam Licht AG, ZKW Group, Koninklijke Philips N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Automotive Adaptive Lighting System Market Shifts & Advancements
Adaptive lighting is transitioning from standalone convenience features to integrated safety subsystems, with hardware-software bundling and regulatory compliance emerging as the primary axes of supplier competition.
Digital micromirror device technology is integrating pixel-level beam control with thermal management substrates. Tier-one suppliers in Aichi Prefecture are adopting this architecture for next-generation matrix modules. The technology is integrating previously separate optical and electronic design workflows into unified platform engineering.
METI's anticipated alignment with UNECE automated driving frameworks is tightening sensor-lighting integration requirements. Domestic OEMs must demonstrate predictive beam response to pedestrian and cyclist detection inputs. Premium nameplates in the Kanto region are accelerating compliance investments ahead of formal adoption timelines.
Fleet procurement of adaptive lighting is consolidating around multi-year platform agreements rather than annual component sourcing. Japanese OEMs are compressing supplier bases to capture volume discounts on integrated modules. This concentration is most visible in Toyota's tier-one relationships across its Nagoya and Kyushu assembly networks.
Japan Automotive Adaptive Lighting System Market Segmentation
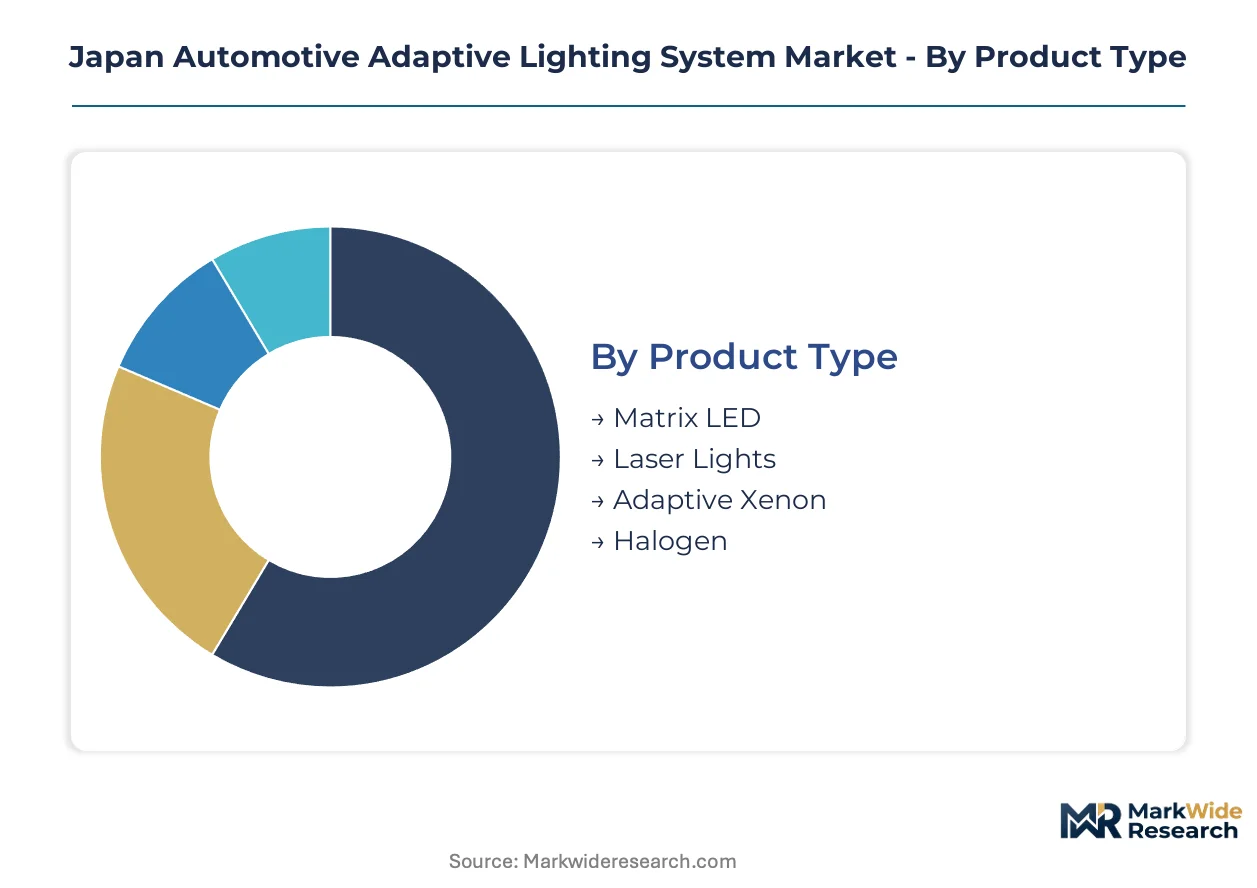
Adaptive lighting procurement in Japan follows distinct upgrade cycles across vehicle platforms, with OEMs timing module refreshes to coincide with model-year redesigns and electrical architecture transitions. Segmentation reveals how beam technology choices cascade through pricing tiers and regulatory compliance pathways.
Product Type:
Replacement cycles for headlamp modules accelerate as JIS D 5500 precision mandates render older optical designs obsolete, compressing the effective service life of discrete high-beam and low-beam configurations.
- Matrix LED:Precision-dimmable LED arrays with individual pixel control enable dynamic beam shaping without mechanical actuators. Toyota and Lexus assembly lines in Aichi Prefecture specify these modules for mid-tier and premium nameplates facing MLIT safety rating incentives.
- Laser Lights:Laser diode excitation of phosphor substrates delivers high-intensity illumination with compact optical packaging. PMDA photobiological assessments extend type-approval timelines, limiting near-term volume to flagship Lexus platforms where brand differentiation justifies compliance investment.
- Adaptive Xenon:High-intensity discharge sources with servo-controlled reflectors retain fitment in legacy vehicle programs.
- Halogen:Tungsten-halogen technology with basic leveling actuators persists in commercial vehicle segments with extended model cycles.
Volume placements concentrate in Matrix LED configurations; the faster expansion belongs to Laser Lights as PMDA pathways mature.
Technology:
Cost tier differentiation separates basic convenience functions from integrated safety subsystems requiring sensor fusion and predictive algorithms.
- Intelligent Lighting:Machine vision fusion with vehicle dynamics data enables predictive beam shaping that anticipates road curvature and traffic conditions. Kanto-region premium OEMs specify this technology for compliance with anticipated METI alignment to UNECE automated driving frameworks.
- Glare-Free High Beam:Camera-driven selective dimming of matrix segments masks oncoming vehicles while maintaining peripheral illumination. Lexus channels concentrate margin capture here through brand-exclusive algorithm licensing.
- Night Vision:Infrared projection overlays integrated with headlamp control modules for pedestrian detection.
- Automatic Dimming:Basic high-beam deactivation triggered by ambient light sensors and forward-facing photodetectors.
Revenue pools deepen in Intelligent Lighting; aftermarket retrofit demand clusters around Automatic Dimming for legacy fleets.
End User:
Customer type determines procurement modality, with captive OEM supply chains operating on fundamentally different contract structures than fragmented aftermarket channels.
- OEMs:Original equipment manufacturers procure through multi-year platform agreements with integrated module suppliers. Toyota's tier-one relationships with Stanley Electric and Koito Manufacturing anchor volume concentration across Nagoya and Kyushu assembly networks.
- Luxury Vehicle Segment:Dedicated premium nameplate engineering teams specify custom beam algorithms and exclusive optical designs. Lexus development centers in Kanagawa Prefecture drive specification intensity for glare-free and predictive lighting functions.
- Aftermarket Customers:Independent service channels face constraints from 48V architecture transition and embedded software validation requirements.
- Commercial Vehicles:Fleet operators prioritize durability and standardization over adaptive feature depth.
Platform bundling intensity peaks with OEMs; specification autonomy concentrates in the Luxury Vehicle Segment.
Application:
Vehicle mass and duty cycle dictate thermal management requirements and actuator durability specifications for adaptive lighting modules.
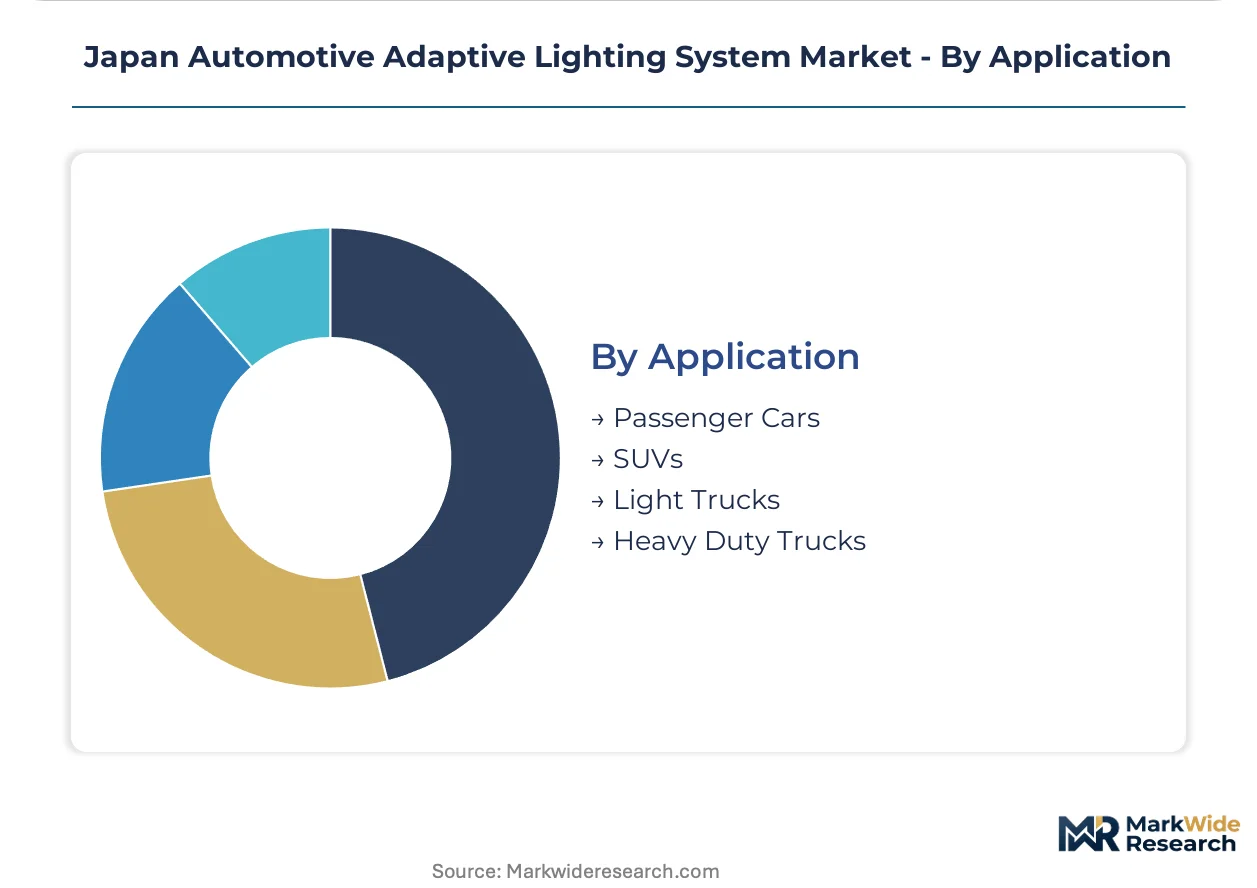
- Passenger Cars:Sedan and hatchback platforms with 12V and 48V electrical architectures represent the primary fitment volume for matrix LED modules. MLIT safety rating integration incentivizes adaptive beam fitment across mid-tier nameplates previously specified with static headlamps.
- SUVs:Higher ride heights and wider track dimensions demand enhanced horizontal beam sweep range and cornering illumination depth. Domestic OEMs in the Kanto region accelerate SUV-specific module development for export and domestic consumption.
- Light Trucks:Utility-focused platforms balance adaptive feature content with cost constraints in commercial-adjacent segments.
- Heavy Duty Trucks:Severe-duty thermal environments and vibration exposure limit adaptive technology penetration.
Specification density runs highest in Passenger Cars; module durability requirements stiffen most acutely for Heavy Duty Trucks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's automotive adaptive lighting system market concentrates production in the Chubu and Kanto industrial belts while consumption tracks vehicle assembly volumes across domestic OEM networks. Regional supply chains cluster around tier-one module suppliers with captive LED fabrication and localized actuator manufacturing.
Kanto/Tokyo
Premium passenger car assembly plants in Toyota City and Yokohama drive matrix LED module procurement through just-in-sequence delivery contracts. METI enforces JIS D 5500 beam precision standards that accelerate sensor-integrated platform adoption. Stanley Electric's Tsukuba fabrication complex supplies captive LED chips to tier-one integrators across the Greater Tokyo industrial corridor.
Kansai/Osaka
Legacy automotive component manufacturing in Osaka Prefecture supports adaptive xenon and halogen module production for commercial vehicle segments. MLIT safety rating protocols incentivize adaptive beam fitment in mid-tier nameplates assembled at regional plants. Koito Manufacturing anchors supply relationships with Toyota and Lexus development centers in Kanagawa Prefecture.
Chubu/Nagoya
Toyota Motor's Nagoya assembly network concentrates demand for intelligent lighting systems with predictive beam shaping algorithms. PMDA photobiological safety assessments for laser-based headlamps create compliance bottlenecks for flagship platform introductions. Domestic OEMs in Aichi Prefecture accelerate digital micromirror device adoption for next-generation matrix modules.
Kyushu
Export-oriented vehicle plants in Fukuoka and Oita Prefectures specify adaptive lighting modules for North American and European market compliance. 48V electrical architecture transitions lag in legacy 12V fleets, constraining retrofit penetration. Regional suppliers face embedded software talent scarcity that delays glare-free function localization.
Tohoku
Automotive parts manufacturing in Miyagi Prefecture supplies thermal management substrates for LED module assemblies. METI's anticipated alignment with UNECE automated driving frameworks tightens sensor-lighting integration requirements for pedestrian detection compliance. Tier-two suppliers in the region struggle with second-source LED chip access from Tsukuba-dominated fabrication capacity.
Japan Automotive Adaptive Lighting System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Japan's adaptive lighting value chain, creating a tiered structure where captive LED fabrication confers cost architecture control. The market consolidates around three strategic archetypes: integrated module suppliers with in-house chip production, European algorithm licensors with localized actuator manufacturing, and component specialists targeting retrofit channels. Dominant competitive moves include multi-year platform agreement renegotiations and embedded software talent acquisition.
Among integrated Japanese suppliers, Stanley Electric Co. Ltd and Koito Manufacturing Co. Ltd exemplify the captive-fabrication archetype through Tsukuba-based LED chip production and long-term OEM supply relationships. Valeo Group represents the European-licensor model, importing glare-free algorithms while maintaining Yokohama actuator production. These three companies anchor the competitive structure through divergent approaches to hardware-software bundling and regulatory compliance investment.
| Leading Market Players |
|---|
| Stanley Electric Co. Ltd |
| Valeo Group |
| Koito Manufacturing Co. Ltd |
| Texas Instruments |
| Magneti Marelli SpA |
| HELLA KGaA Hueck & Co. |
| OsRam Licht AG |
| ZKW Group |
| Koninklijke Philips N.V. |
| Others |
Supply & Pricing Matrix
LED chip fabrication costs at Tsukuba cascade through three pricing tiers as Stanley Electric's captive production feeds module integrators serving Toyota's premium nameplates while tier-two suppliers absorb margin compression from limited second-source options.
Pricing Analysis
Cost-down pressure on matrix LED modules accelerates because METI's tightening JIS D 5500 precision mandates force rapid sensor integration upgrades. Three-tier pricing structure across premium, standard, and economy levels separates Lexus-exclusive glare-free algorithms from mid-tier predictive beam systems and basic automatic dimming retrofit kits. Price differentiation rests on certification grade for PMDA photobiological compliance and volume scale in multi-year platform agreements. Aftermarket channels exhibit highest price sensitivity as 48V architecture transitions strand legacy 12V fleet upgrade demand.
Supply Chain Analysis
Regional distribution centers in Aichi and Kanagawa Prefectures operate hub-and-spoke patterns feeding just-in-sequence module delivery to Toyota City and Yokohama assembly plants. Geographic supply concentration centers on Japan, Germany, and China for LED chips, actuator motors, and machine vision sensors. Raw material dependencies include gallium nitride substrates, rare-earth phosphors, and automotive-grade silicon for camera processors. Single-source vulnerability from Tsukuba-dominated LED fabrication creates supply chain risk. Distribution runs through tier-one integrators with direct OEM platform contracts rather than fragmented wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as METI's anticipated UNECE alignment forces adaptive lighting suppliers to absorb compliance investment burdens that weaker tier-two players cannot shoulder.
For Market Incumbents: Cement platform bundling dominance by securing exclusive multi-year agreements with Toyota and Lexus development centers ahead of formal UNECE framework adoption. Deepen backward integration into sensor fusion software to defend against European algorithm licensors expanding Yokohama actuator production. Prioritize embedded software talent acquisition in Kanto regional clusters where engineering scarcity delays glare-free function localization. For New Entrants and Emerging Players: Digital aftermarket channels targeting legacy 12V fleet retrofit demand offer the most penetrable entry vector as OEM procurement consolidates around integrated module suppliers. Focus white-space capture on commercial vehicle segments with extended model cycles where halogen-to-LED upgrade paths face less tier-one competition. Pursue direct-to-installer distribution partnerships bypassing concentrated tier-one supply relationships. For Investors and Strategic Acquirers: PMDA laser photobiological approval announcements are the leading indicator that flagship platform compliance investments will accelerate market share concentration among pre-qualified suppliers. Frame long-term viability around five-to-ten year automotive electrical architecture transition windows where 48V adoption determines adaptive lighting content per vehicle. Target acquisition profiles at tier-two module assemblers with established MLIT safety rating validation but lacking captive LED fabrication.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Toyota's module consolidation across Nagoya and Kyushu networks compresses supplier bases into integrated architectures. |
| Sensor-Lighting Integration Investment | METI's UNECE alignment mandates predictive beam response to pedestrian detection inputs for type approval. |
| Backward Integration into LED Fabrication | Stanley Electric's Tsukuba captive production controls cost architecture across matrix and laser product lines. |
| Geographic Manufacturing Footprint Expansion | Valeo's Yokohama actuator localization reduces tariff exposure while maintaining European algorithm licensing. |
| Software-Defined Lighting Development | Machine vision convergence with vehicle dynamics data enables real-time predictive beam shaping for premium nameplates. |
Research Methodology
Vehicle production databases, JIS regulatory filings, and IHS Markit registration data formed the secondary backbone for market sizing validation. Primary interviews with tier-one supplier procurement managers, OEM platform engineers, aftermarket distributors, and METI regulatory affairs specialists combined with secondary validation through bottom-up and top-down triangulation approaches.
Bottom-up volume modeling across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions reconciled against top-down market value estimates. CAGRs derived from segment-level growth trajectory analysis incorporating electrical architecture transition timelines and regulatory compliance phase-in schedules. Forecast inputs included MLIT safety rating integration pace and PMDA laser approval pathway maturation.
The model holds under stable METI regulatory alignment timelines; deviation in UNECE framework adoption schedules or LED fabrication capacity expansion would shift volume concentration patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Driveline Control Systems and Devices Market
Automotive Circuit Systems
Automotive Integrated Control Panel Market
Automotive Circuit Systems
Global Automotive Display System Market
Automotive Circuit Systems
Automotive Horn Systems Market
Automotive Circuit Systems
South Korea Automotive Relay Market
Automotive Circuit Systems
Automotive LED Light Market
Automotive Circuit Systems
Automotive Throttle Position Sensor Market
Automotive Circuit Systems
Automotive Pressure Switch Market
Automotive Circuit Systems
Automotive Steer-by-Wire Actuator Market
Automotive Circuit Systems
Traction Control System Market
Automotive Circuit Systems
Automotive Ignition System Market
Automotive Circuit Systems
Automotive Graphic Display Controller Market
Automotive Circuit Systems
Global Automotive Engine Management System Market
Automotive Circuit Systems
Automotive Interface Chip Market
Automotive Circuit Systems
Ignition Control Module Market
Automotive Circuit Systems
Automotive Launch Control System Market