
 Automotive Immobilizer Market | 2026-2036
Automotive Immobilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Immobilizer Market Outlook
UN Regulation No. 116 is rebalancing the cost-of-entry calculus for immobilizer suppliers by mandating standardized anti-theft device certification across type-approved vehicles. Robert Bosch GmbH leverages its integrated electronics manufacturing to sustain price competitiveness in factory-installed systems. Denso Corporation anchors its position through deep OEM relationships in Japan and North America. Continental AG differentiates via modular immobilizer platforms that span multiple vehicle electrical architectures.
An automotive immobilizer is an electronic security device that prevents engine start-up without authorized key recognition, typically employing transponder chips operating at 125 kHz or 433 MHz frequencies within key fobs or smart cards. Its primary commercial purpose is to reduce vehicle theft incidence and satisfy insurer and regulatory compliance requirements for type-approved automobiles. Passive immobilizers dominate volume due to their seamless driver experience and zero-action operation, while smart immobilizers integrating biometric authentication represent the fastest-expanding margin pool as luxury OEMs seek differentiated security propositions. RFID technology leads installation counts across all product categories, though CAN-Bus integration is displacing standalone immobilizer modules as centralized vehicle electronics consolidate.
The U.S. NHTSA maintains Federal Motor Vehicle Theft Prevention Standards that shape product design requirements for domestic market access, while EU REACH compliance constrains material selection for transponder housings and circuit substrates. India's BIS certification mandates and China's GB standards for vehicle anti-theft devices create parallel compliance obligations for suppliers serving those production bases. Stakeholders must monitor divergence between regional cybersecurity standards for connected immobilizers and legacy electromagnetic compatibility requirements as vehicle architectures evolve.
Market Dynamics
CAN-Bus integration is compressing standalone immobilizer architectures into centralized vehicle electronics stacks, forcing suppliers to abandon module-level margins and compete on semiconductor integration density.
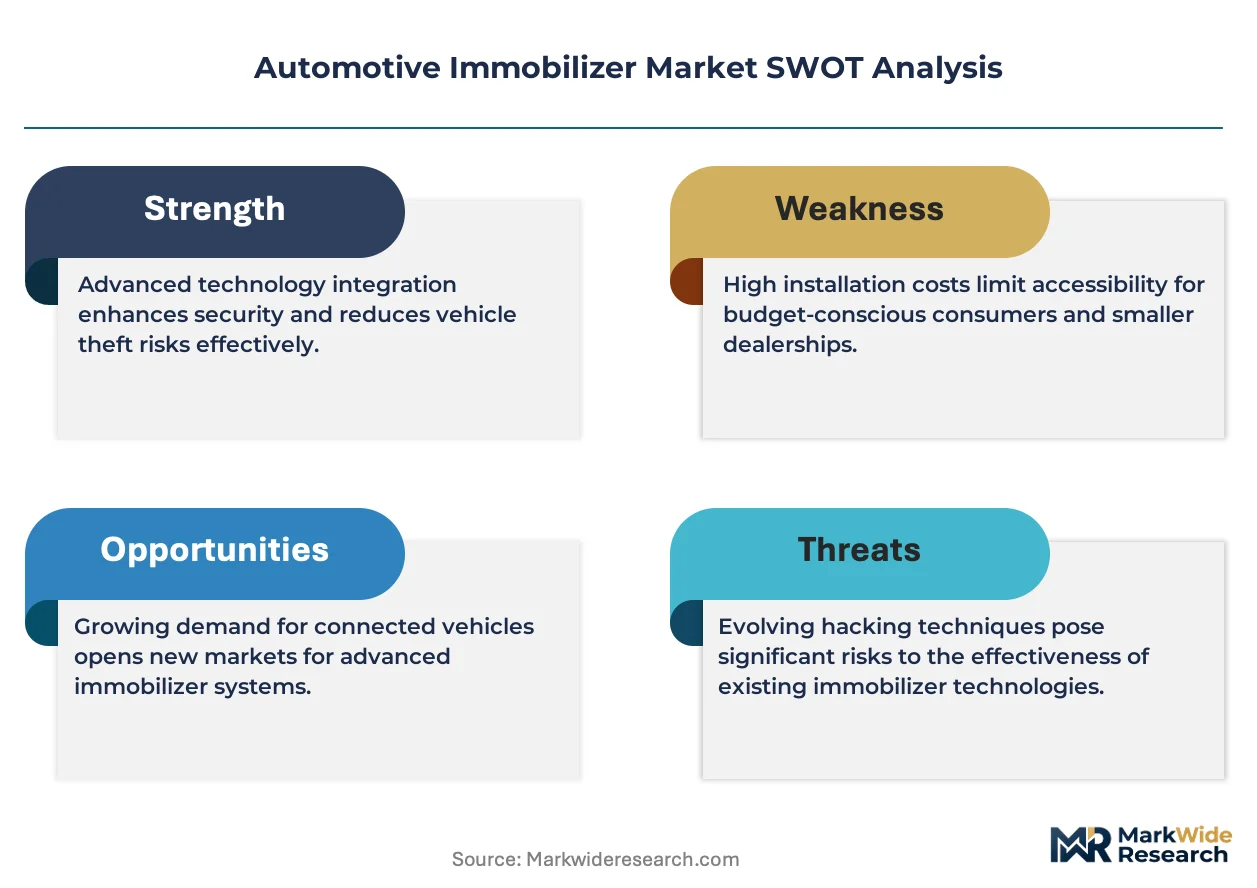
Growth Catalysts
- Mandatory anti-theft regulations:China's GB standards and India's BIS certification now require factory-installed immobilizers on all new passenger vehicles, eliminating optionality for cost-sensitive OEMs.
- RFID transponder cost curves:125 kHz and 433 MHz chipsets have crossed price thresholds that enable penetration into economy vehicle segments previously served by mechanical locks.
- Insurer risk-pricing models:Brazilian and South African underwriters now mandate immobilizer verification before issuing comprehensive coverage on used vehicles, stimulating aftermarket retrofit demand.
Market Restraints
- Semiconductor supply concentration:Transponder chip fabrication clusters in Taiwan and South Korea expose immobilizer suppliers to single-source vulnerability during foundry allocation cycles.
- Legacy vehicle incompatibility:Pre-2000 vehicle architectures lack CAN-Bus infrastructure, capping addressable retrofit volume in mature vehicle parcs.
- Substitution by smartphone-based access:Bluetooth Low Energy and UWB digital keys threaten dedicated transponder hardware as OEMs consolidate around phone-as-key ecosystems.
Strategic Opportunities
- Biometric authentication convergence:Fingerprint and facial recognition integration with immobilizer logic creates premium-tier differentiation for luxury OEMs seeking security positioning.
- Aftermarket channel expansion:Authorized dealer networks in Mexico and Indonesia remain underpenetrated relative to theft incidence, offering first-mover installation service contracts.
- Cybersecurity certification tailwinds:UN Regulation No. 116's expanded scope to connected immobilizers creates compliance services revenue for testing laboratories.
Industry Challenges
- Embedded software talent scarcity:Cryptographic protocol engineering for immobilizer-to-ECU authentication exceeds available automotive cybersecurity labor pools in Eastern European development centers.
- Homologation timeline compression:EU REACH substance restrictions and electromagnetic compatibility testing now run in parallel rather than sequence, stretching certification resources.
- Legacy system integration friction:Hybrid architectures supporting both CAN-Bus and standalone immobilizer modules require dual-stack validation, multiplying firmware complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Immobilizer Market |
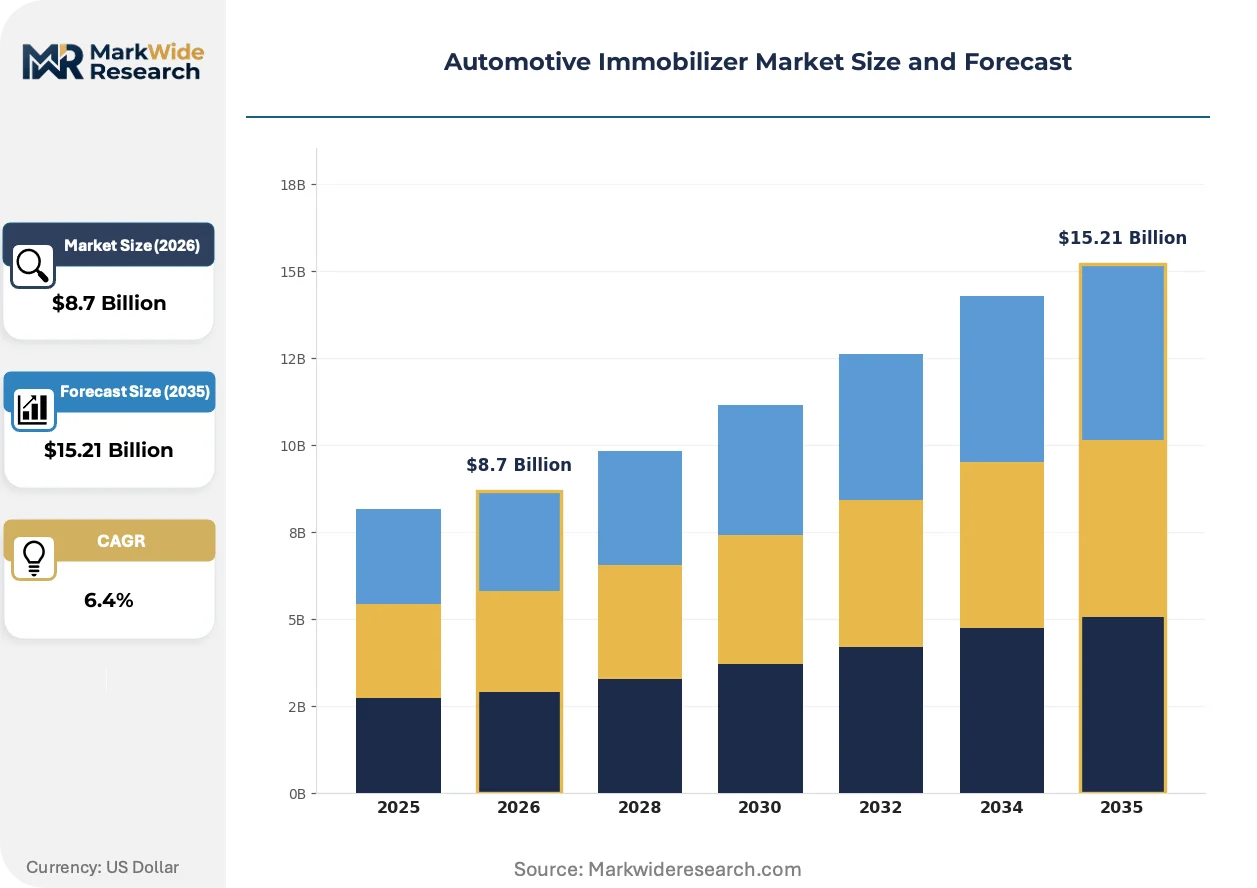
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Immobilizers, Active Immobilizers, Smart Immobilizers, Remote-Controlled Immobilizers End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Technology: RFID, Biometric, GPS, CAN-Bus Installation: Factory-Installed, Dealer-Installed, DIY Kits, Professional Services |
| Companies Covered | Valeo SA, Denso Corporation, Robert Bosch GmbH, Alps Alpine Co., Ltd., Hella KGaA Hueck & Co., Continental AG, Mitsubishi Electric Corporation, ZF Friedrichshafen AG, Delphi Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Immobilizer Market Strategic Shifts
Immobilizer hardware is dissolving into domain-controller electronics, with security functions migrating from dedicated modules to body-control unit firmware. This shift redefines supplier value capture and certification boundaries.
Transponder-based authentication is modularizing around software-defined key hierarchies that separate cryptographic cores from RF front-ends. Tier-1 suppliers now license immobilizer algorithms to semiconductor vendors rather than shipping finished modules. This architecture enables OEMs to source transponder chips directly while retaining supplier responsibility for security certification, compressing the addressable hardware market.
UN Regulation No. 116's expanded certification scope to electronic vehicle immobilizers harmonizes type-approval requirements across EU member states and aligned markets. The regulation mandates standardized theft-resistance testing protocols that previously varied by national authority. Aftermarket suppliers serving Poland and Spain must now maintain single certification documentation rather than parallel national approvals, reducing compliance overhead for cross-border distributors.
Fleet operators and commercial vehicle lessors now demand centralized immobilizer override capabilities for recovery and logistics management, displacing driver-centric key authentication. This procurement pattern prioritizes telematics-integrated immobilizer systems with cloud-accessible lock/unlock APIs. Brazil's cargo transport sector exhibits the most pronounced shift, with fleet management platforms bundling immobilizer control into subscription-based vehicle monitoring services.
Automotive Immobilizer Market Segmentation
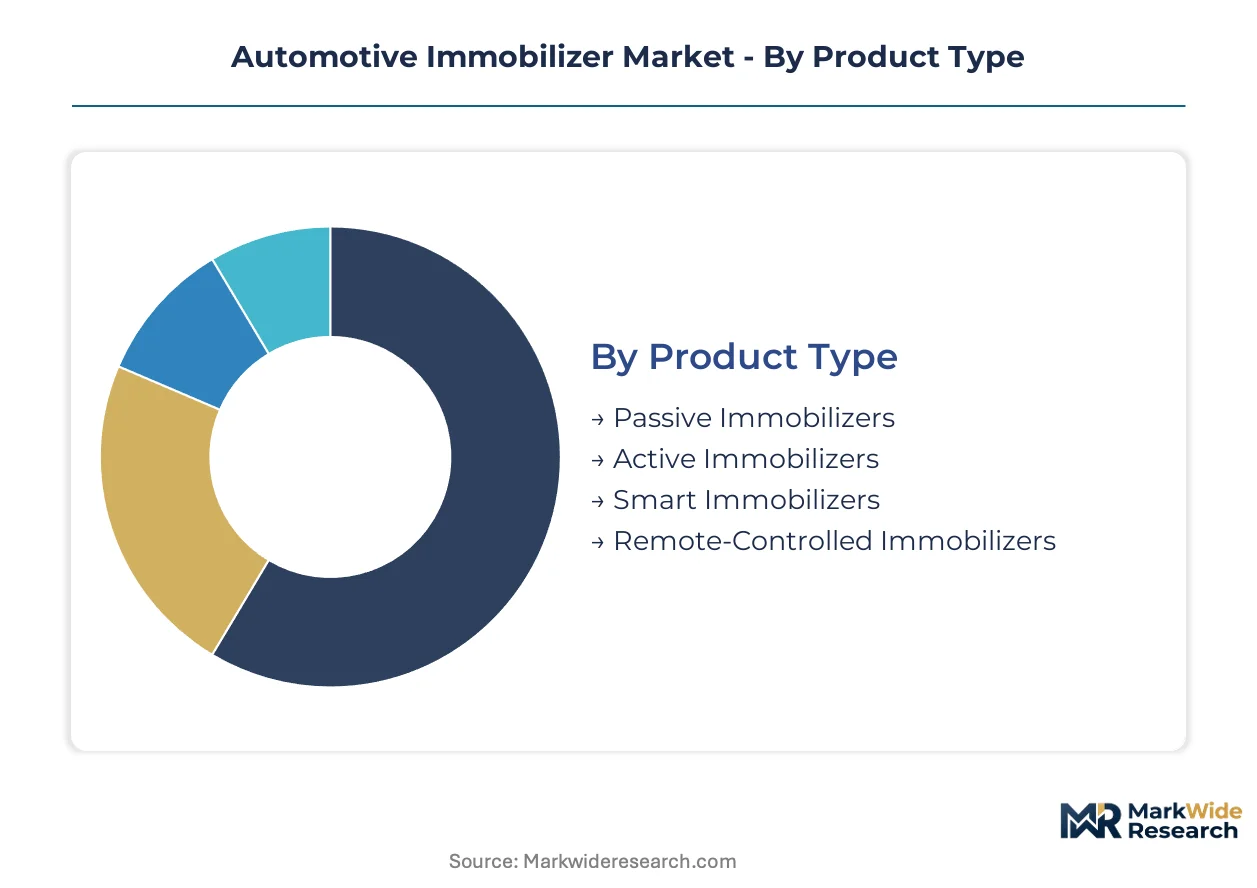
Immobilizer segmentation reveals divergent margin structures across integration depths. Factory-embedded systems command premium pricing through OEM certification requirements, while aftermarket channels compete on installation speed and retrofit compatibility.
Product Type:
Passive immobilizers dominate embedded architectures with zero-action operation, while smart variants require active biometric enrollment and cloud credential management.
- Passive Immobilizers:Transponder chips at 125 kHz or 433 MHz frequencies authenticate automatically when the driver enters the vehicle. Chinese and Indian OEMs mandate these for all new passenger vehicles under GB standards and BIS certification, eliminating mechanical key systems from factory builds.
- Smart Immobilizers:Fingerprint and facial recognition modules integrate with body-control unit firmware for multi-factor authentication. Luxury OEMs in Germany and Japan deploy these for security differentiation, though biometric sensor costs constrain penetration below premium tiers.
- Active Immobilizers:Require deliberate driver action such as button presses or code entry before engine start.
- Remote-Controlled Immobilizers:Enable fleet operators to disable vehicles via telematics platforms for recovery and logistics management.
Volume placements concentrate in passive immobilizers; the faster expansion belongs to smart immobilizers.
End User:
OEM procurement patterns favor semiconductor-integrated solutions over standalone modules, compressing Tier-1 supplier margins while expanding algorithm licensing opportunities.
- OEMs:Factory-installed specifications demand electromagnetic compatibility validation under UN Regulation No. 116. Volkswagen Group and Toyota Motor Corporation source transponder chips directly while retaining suppliers for security certification, fragmenting traditional module revenue.
- Tier-1 Suppliers:Robert Bosch GmbH and Denso Corporation anchor positions through integrated electronics manufacturing and deep OEM relationships in Japan and North America. These suppliers now license immobilizer algorithms rather than shipping finished hardware.
- Aftermarket Providers:Brazilian and South African underwriters mandate immobilizer verification for comprehensive coverage on used vehicles.
- Vehicle Assemblers:Contract manufacturers in Mexico and Thailand integrate immobilizer functions during final assembly.
Procurement is shifting toward OEM direct chip sourcing; aftermarket channels in Brazil and South Africa exhibit the steepest expansion trajectory.
Technology:
RFID retains installation leadership while CAN-Bus integration dissolves dedicated immobilizer modules into centralized vehicle electronics.
- RFID:125 kHz and 433 MHz transponder chipsets have crossed price thresholds enabling economy vehicle penetration. Taiwan and South Korean foundries concentrate fabrication, exposing suppliers to single-source vulnerability during allocation cycles.
- CAN-Bus:Security functions migrate from standalone modules to body-control unit firmware, redefining supplier value capture. This architecture eliminates module-level margins and forces competition on semiconductor integration density.
- Biometric:Fingerprint and facial recognition integration creates premium-tier differentiation.
- GPS:Enables geofencing and remote disable capabilities for fleet recovery applications.
RFID dominates current installation counts; biometric authentication is gaining share fastest among emerging technologies.
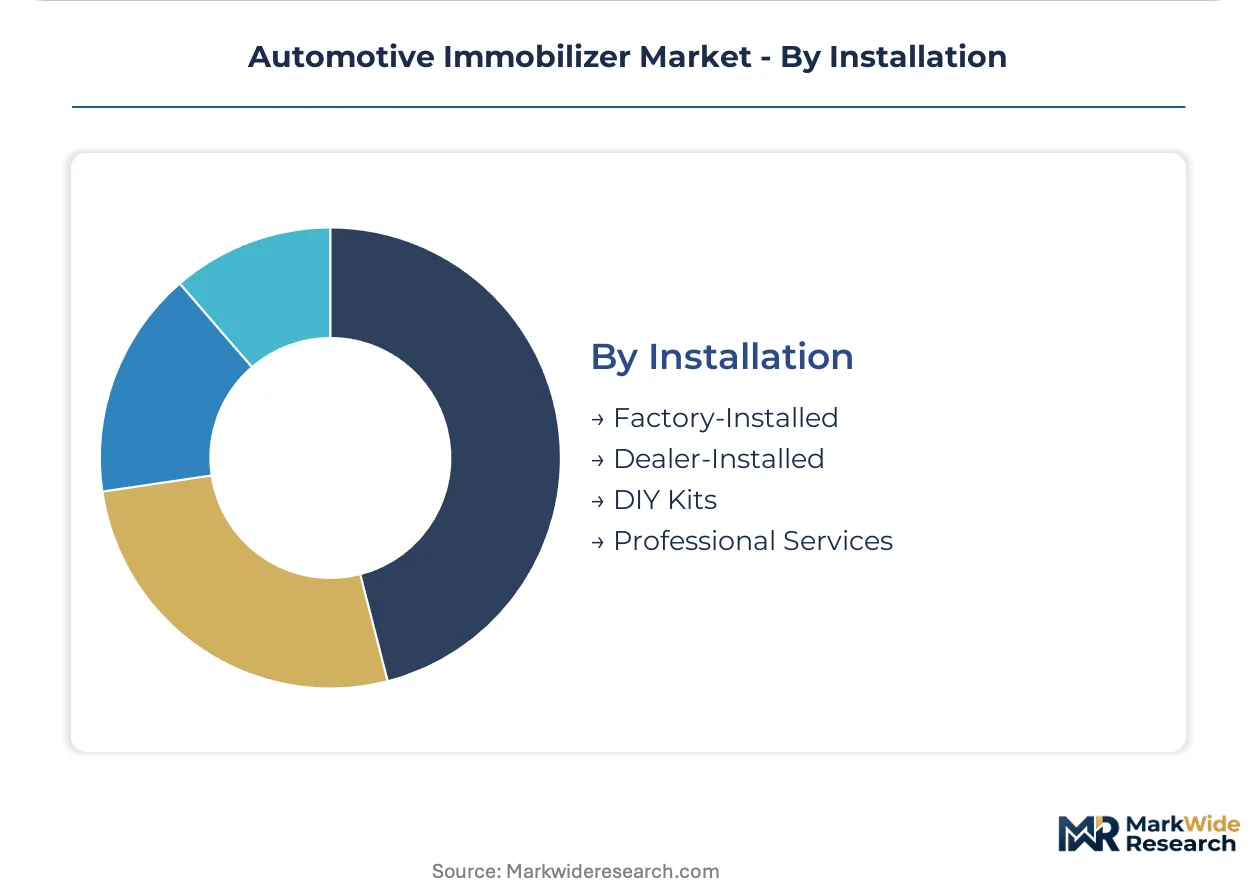
Installation:
Factory installation locks in regulatory compliance at vehicle type-approval stage, while dealer channels capture retrofit demand from insurer mandates.
- Factory-Installed:Mandatory under China's GB standards and India's BIS certification for all new passenger vehicles. OEMs integrate immobilizer logic during body-control unit programming, eliminating post-assembly optionality.
- Professional Services:Authorized dealer networks in Mexico and Indonesia remain underpenetrated relative to theft incidence. Installation service contracts bundle immobilizer retrofit with telematics subscription for fleet operators in Brazil's cargo transport sector.
- Dealer-Installed:Serves used-vehicle channels where factory systems are absent or non-compliant.
- DIY Kits:Limited to simple relay-interrupt systems on pre-2000 vehicles lacking CAN-Bus infrastructure.
Factory-installed systems capture the volume base; professional services in Latin America and Southeast Asia climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Mexico and Thailand concentrate contract manufacturing capacity for immobilizer integration during final vehicle assembly. These zones attract Tier-1 suppliers seeking proximity to export-oriented OEM production hubs.
China
Passenger vehicle OEMs in the Yangtze River Delta expand factory-installed immobilizer penetration as mandatory GB standards tighten. MIIT enforcement of anti-theft device certification eliminates optionality for cost-sensitive domestic brands. Shanghai-based electronics clusters now supply transponder chips directly to Volkswagen Group and Toyota joint ventures.
Germany
Luxury OEMs in Bavaria and Baden-Württemberg deploy biometric-enabled smart immobilizers for security differentiation. KBA homologation under UN Regulation No. 116 harmonizes type-approval requirements across EU member states. Stuttgart's automotive electronics corridor hosts algorithm licensing operations for centralized body-control unit firmware.
United States
NHTSA Federal Motor Vehicle Theft Prevention Standards shape product design requirements for domestic market access. Michigan and Ohio-based OEM engineering centers specify CAN-Bus integrated architectures over standalone modules. Detroit-area suppliers now compete on semiconductor integration density rather than module-level margins.
Brazil
Cargo transport fleet operators in São Paulo demand telematics-integrated immobilizer systems with cloud-accessible lock/unlock APIs. ANVISA-aligned insurer mandates require immobilizer verification before comprehensive coverage issuance on used vehicles. The Campinas electronics cluster supports aftermarket retrofit installation service contracts.
India
Maruti Suzuki and Hyundai Motor India mandate BIS-certified immobilizers across all new passenger vehicle builds. Tamil Nadu and Gujarat manufacturing corridors integrate security logic during body-control unit programming. Pune-based component suppliers license authentication algorithms to domestic semiconductor vendors.
Automotive Immobilizer Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across factory-installed and aftermarket channels. The supplier base exhibits tiered concentration, with integrated electronics manufacturers holding OEM certification advantages while regional installers capture retrofit demand. Three archetypes dominate: diversified automotive electronics conglomerates, specialized transponder technology licensors, and aftermarket installation service networks. Competitive moves center on algorithm licensing partnerships and backward integration into semiconductor sourcing.
Among diversified automotive electronics conglomerates, Robert Bosch GmbH and Denso Corporation exemplify the integrated manufacturing archetype that anchors OEM relationships through certification depth. Continental AG occupies a position representing modular platform specialists spanning multiple vehicle electrical architectures. These three entities sit within the tier characterized by direct OEM engineering collaboration and UN Regulation No. 116 compliance responsibility.
| Leading Market Players |
|---|
| Valeo SA |
| Denso Corporation |
| Robert Bosch GmbH |
| Alps Alpine Co., Ltd. |
| Hella KGaA Hueck & Co. |
| Continental AG |
| Mitsubishi Electric Corporation |
| ZF Friedrichshafen AG |
| Delphi Technologies |
| Others |
Value Chain & Pricing Dynamics
EU REACH substance restrictions on transponder housings and circuit substrates gate qualified supply access while commanding premium-tier pricing for compliant material streams. OEMs sourcing factory-installed systems face dual certification overhead that compresses margin pools for non-compliant competitors.
Pricing Analysis
Short lead-time premiums apply to transponder chip orders from Taiwan and South Korean foundries during allocation-constrained cycles, while spot inventory discounts emerge when OEMs direct-source at volume. Three-tier pricing structure across premium, standard, and economy levels separates biometric-enabled smart immobilizers from RFID-based passive systems from relay-interrupt retrofit kits. Price differentiation hinges on UN Regulation No. 116 certification grade and electromagnetic compatibility validation depth. Cost compression in economy passive immobilizers is intensifying because Chinese OEMs mandate factory installation under GB standards. Aftermarket retrofit channels in Brazil and South Africa exhibit the highest price sensitivity due to insurer-mandated coverage requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Volkswagen Group and Toyota Motor Corporation, while authorized dealer networks distribute aftermarket retrofit kits in Latin America and Southeast Asia. Taiwan, South Korea, and China concentrate transponder chip fabrication, exposing immobilizer suppliers to single-source vulnerability during foundry allocation cycles. Raw material dependencies include rare-earth elements for antenna substrates, epoxy resins for housing encapsulation, and copper for coil windings. Distribution runs through Tier-1 integrated electronics manufacturers who license algorithms rather than ship finished modules, compressing traditional hardware margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UN Regulation No. 116 certification creates a barrier-to-entry moat that rewards compliant players with OEM engineering collaboration access while excluding unqualified competitors from type-approved vehicle programs.
For Market Incumbents: To counter smartphone-based digital key substitution threatening dedicated transponder hardware, Robert Bosch GmbH and Denso Corporation should deepen backward integration into semiconductor sourcing for captive chip supply security. Tier-1 suppliers must also invest in cryptographic protocol engineering talent pools to defend firmware certification responsibilities as OEMs fragment traditional module revenue through direct chip sourcing. For New Entrants and Emerging Players: Cargo transport fleet operators in Brazil's São Paulo corridor represent an underserved buyer archetype demanding telematics-integrated immobilizer systems with cloud-accessible APIs. New entrants should prioritize installation service contracts bundling immobilizer retrofit with subscription-based vehicle monitoring platforms, leveraging ANVISA-aligned insurer mandates as the go-to-market entry mechanism. For Investors and Strategic Acquirers: Tier-1 suppliers licensing immobilizer algorithms to semiconductor vendors rather than shipping finished hardware is the leading indicator that value capture is migrating from hardware modules to software certification services. Long-term viability favors acquisition targets with embedded cybersecurity certification capabilities and established UN Regulation No. 116 compliance track records, with biometric authentication convergence serving as the primary inflection signal for premium-tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Licensing Partnership | Enables Continental AG to capture recurring revenue from semiconductor vendors sourcing transponder chips. |
| Biometric Authentication Integration | Positions Denso Corporation for luxury OEM security differentiation in Germany and Japan. |
| Aftermarket Channel Expansion | Captures insurer-mandated retrofit demand in Brazil and South Africa where theft rates remain elevated. |
| Semiconductor Backward Integration | Reduces single-source vulnerability to Taiwan and South Korean foundry allocation cycles. |
| Cybersecurity Certification Services | Creates compliance revenue streams from UN Regulation No. 116 expanded scope to connected immobilizers. |
Study Parameters
Independent corroboration across OEM platform engineering directors, Tier-1 supplier procurement leads, aftermarket distributor operations managers, and vehicle theft insurance underwriters underwrites the qualitative findings. Primary interviews with these stakeholders combined secondary validation from vehicle production databases, IHS Markit registration data, UN Regulation No. 116 certification records, and SEC filings from listed automotive electronics suppliers. Bottom-up segmentation modeling and top-down market sizing triangulate volume and value estimates.
Comparable-period anchoring to historical immobilizer installation rates by vehicle class and propulsion architecture calibrated the forecast framework across the analysis window. Segmentation dimensions modeled include product type, end user category, technology platform, installation channel, and regional production cluster. CAGRs were derived from fitted growth curves incorporating RFID transponder cost curve trajectories, mandatory regulatory adoption timelines, and fleet telematics integration penetration patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to smartphone-based digital key substitution rates and semiconductor foundry capacity allocation cycles. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and OEM sourcing pattern stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Inertial Systems Market
Automotive Safety and Security Systems
Car Camera Cleaning Systems Market
Automotive Safety and Security Systems
Automatic Emergency Braking System (AEBS) Market
Automotive Safety and Security Systems
Automotive Driver Drowsiness Detection System Market
Automotive Safety and Security Systems
Automotive Crash Barriers Market
Automotive Safety and Security Systems
Global Automotive Safety System Market
Automotive Safety and Security Systems
Vehicle Occupancy Detection System Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System and Adaptive Cruise Control (ACC) System Market
Automotive Safety and Security Systems
Automotive Intelligent Headlight System Market
Automotive Safety and Security Systems
Smart Motorcycle Helmet Market
Automotive Safety and Security Systems
Global Automotive Parking Sensors Market
Automotive Safety and Security Systems
Global Automotive Hill Descent Control Market
Automotive Safety and Security Systems
South Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
North America Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Driver Alert System Market
Automotive Safety and Security Systems
Automotive Personal Assistance System Market