
 NDT in Automotive & Transportation Market | 2026-2036
NDT in Automotive & Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
NDT in Automotive & Transportation Market Insights
German inspection equipment manufacturers is pivoting toward portable phased-array ultrasonic systems for EV chassis validation. Baker Hughes Company leverages its digital flaw-detection software to anchor long-term contracts with European automakers. SGS SA competes through its global laboratory network, while Bureau Veritas specializes in rail infrastructure certification across Asia.
Non-destructive testing in automotive and transportation encompasses ultrasonic, eddy current, magnetic particle, and radiographic methods that detect subsurface defects without material destruction, typically resolving flaws at resolutions between 0.1 mm and 2 mm depending on modality and substrate density. These techniques serve primarily to prevent catastrophic failures in safety-critical components such as brake calipers, suspension arms, and battery enclosures before vehicles enter service. Ultrasonic testing leads the technology segment due to its penetration depth in aluminum-intensive EV platforms, while eddy current testing grows fastest as copper winding inspection expands in electric motor manufacturing. Component inspection commands the largest application share because powertrain electrification multiplies the count of individually validated parts per vehicle.
EU Green Deal mandates and REACH substance restrictions are tightening material traceability requirements that NDT providers must document across supply chains. Germany's KBA and France's ANSM enforce divergent type-approval testing protocols that fragment service standardization. Japan's METI publishes updated JIS standards for hydrogen fuel cell vessel inspection, adding another compliance layer for multi-market suppliers. Stakeholders must monitor which regulatory body gains harmonization momentum first, as that geography will set the template for cross-border inspection reciprocity.
Market Dynamics
Powertrain electrification is fragmenting inspection protocols as aluminum-intensive EV chassis and copper-dense motor windings demand modality-specific validation workflows that legacy steel-focused NDT infrastructure cannot accommodate.
Growth Catalysts
- EU Battery Passport Mandate:Germany's KBA enforces traceable defect documentation across cell-to-pack manufacturing, compelling ultrasonic testing expansion at every assembly tier.
- Aluminum Casting Volume:EV platform lightweighting multiplies inspection points per vehicle body, with structural battery enclosures alone requiring 12-18 discrete validation sequences.
- Phased-Array Ultrasonic Maturation:Portable systems now resolve 0.1 mm flaws in multi-thickness aluminum extrusions, enabling inline deployment that radiographic methods cannot match for speed.
Market Restraints
- Helium Supply Concentration:Leak detection for hydrogen fuel cell vessels depends on scarce helium feedstock, with Qatar and Algeria controlling 42% of global refining capacity and prices subject to export quota volatility.
- France-Germany Protocol Divergence:ANSM and KBA maintain incompatible type-approval documentation standards, forcing dual certification costs for cross-border component suppliers.
- Copper Eddy Current Depth Limits:Surface-breaking crack detection in hairpin motor windings fails below 3 mm penetration, requiring destructive sectioning for subsurface void validation.
Strategic Opportunities
- India PLI Scheme Alignment:Domestic EV manufacturing incentives under the Production Linked Incentive scheme create first-mover positioning for inspection service providers near Chennai and Pune assembly corridors.
- Digital Twin Integration:Real-time NDT data feeds into predictive maintenance models for commercial fleets, compressing warranty claim cycles and opening subscription revenue streams.
- Hydrogen Vessel Certification:Japan's METI JIS standards for 700-bar storage tanks establish template protocols that South Korean and Australian regulators are adopting, creating harmonized export pathways.
Industry Challenges
- Phased-Array Operator Certification:EN ISO 9712 Level 2 qualification requires 800+ supervised inspection hours, creating 18-month pipeline delays as training capacity lags equipment deployment.
- Legacy Radiographic Facility Stranding:Film-based X-ray infrastructure in Eastern European supplier parks cannot pivot to computed radiography without six-figure darkroom retrofit investments that margin-stressed Tier 2s defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NDT in Automotive & Transportation Market |
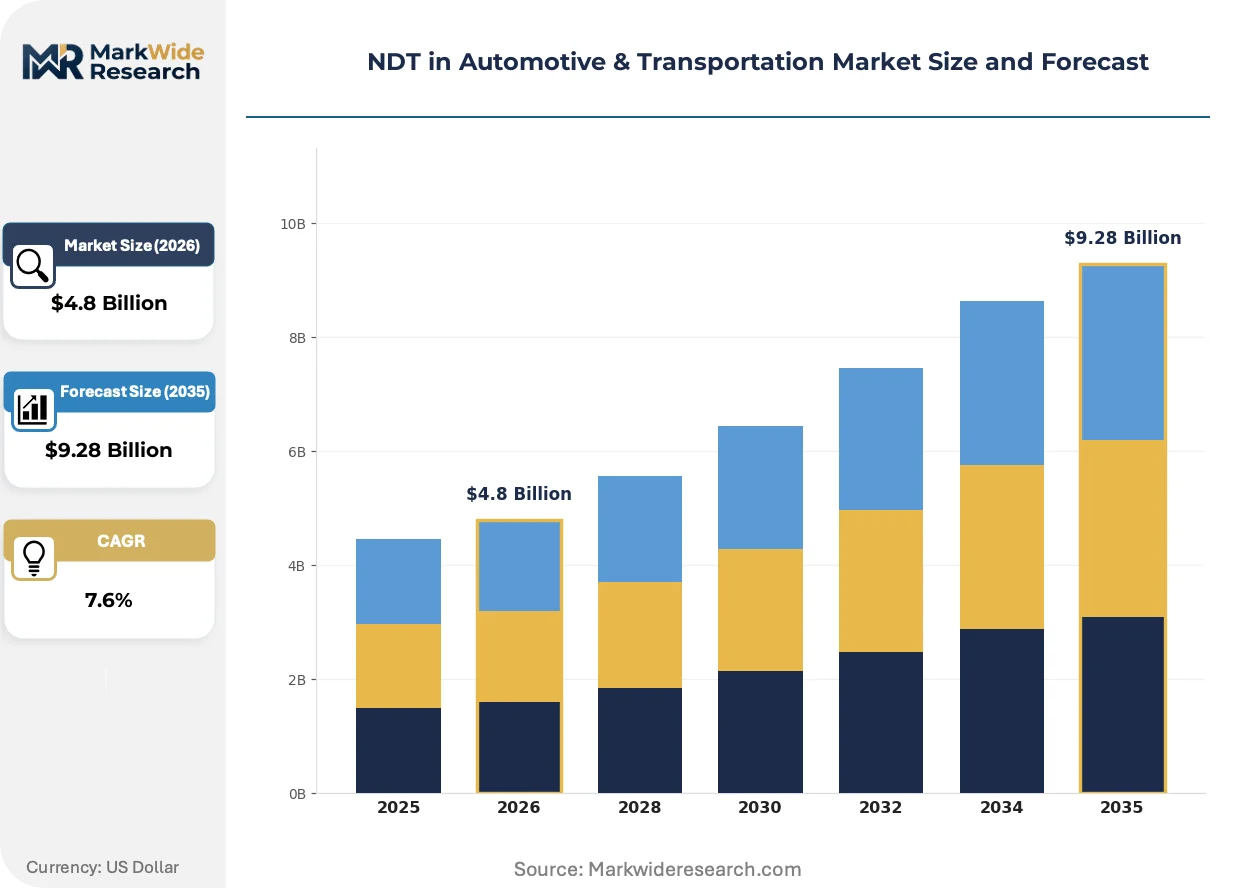
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ultrasonic Testing, Eddy Current Testing, Magnetic Particle Inspection, Radiographic Testing Application: Component Inspection, Structural Integrity, Safety Assessment, Quality Control End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Service Type: Consulting, Training, Equipment Rental, On-site Services |
| Companies Covered | Baker Hughes Company, Mistras Group Inc., SGS SA, Intertek Group plc, Applus Services SA, Bureau Veritas, Olympus Corporation, TÜV SÜD AG, DEKRA SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NDT in Automotive & Transportation Market Trends and Innovations
Artificial intelligence inference at the inspection edge is compressing defect classification cycles from hours to seconds, while regulatory pressure on material provenance forces data architecture investments that reshape competitive differentiation around traceability depth rather than detection sensitivity alone.
Machine-learning-enhanced ultrasonic analysis is automating anomaly recognition in battery weld seams, with BMW and Mercedes-Benz production lines in Stuttgart and Munich deploying neural networks trained on 2 million+ labeled discontinuity images. The technology compresses false-positive rates below 3% versus 12-15% for human interpretation, enabling single-operator monitoring of four parallel inspection stations.
REACH substance restrictions on cadmium-bearing contrast agents are eliminating magnetic particle options for aerospace-grade steel component validation, forcing automotive suppliers toward fluorescent penetrant alternatives that require longer dwell times and UV booth infrastructure. Germany's TÜV and France's LCIE have issued conflicting transition timelines, with German OEMs accelerating compliance six months ahead of French counterparts.
Buyers are consolidating inspection spend under long-term outcome-based agreements that tie vendor compensation to zero-defect delivery rather than per-test fees. Tier 1 suppliers in China's Yangtze Delta now demand 36-month master service contracts with penalty clauses for missed detection events, displacing spot-market transactional relationships that dominated pre-2020 procurement patterns. This shift concentrates vendor selection around balance-sheet capacity to absorb warranty exposure.
NDT in Automotive & Transportation Market Segmentation
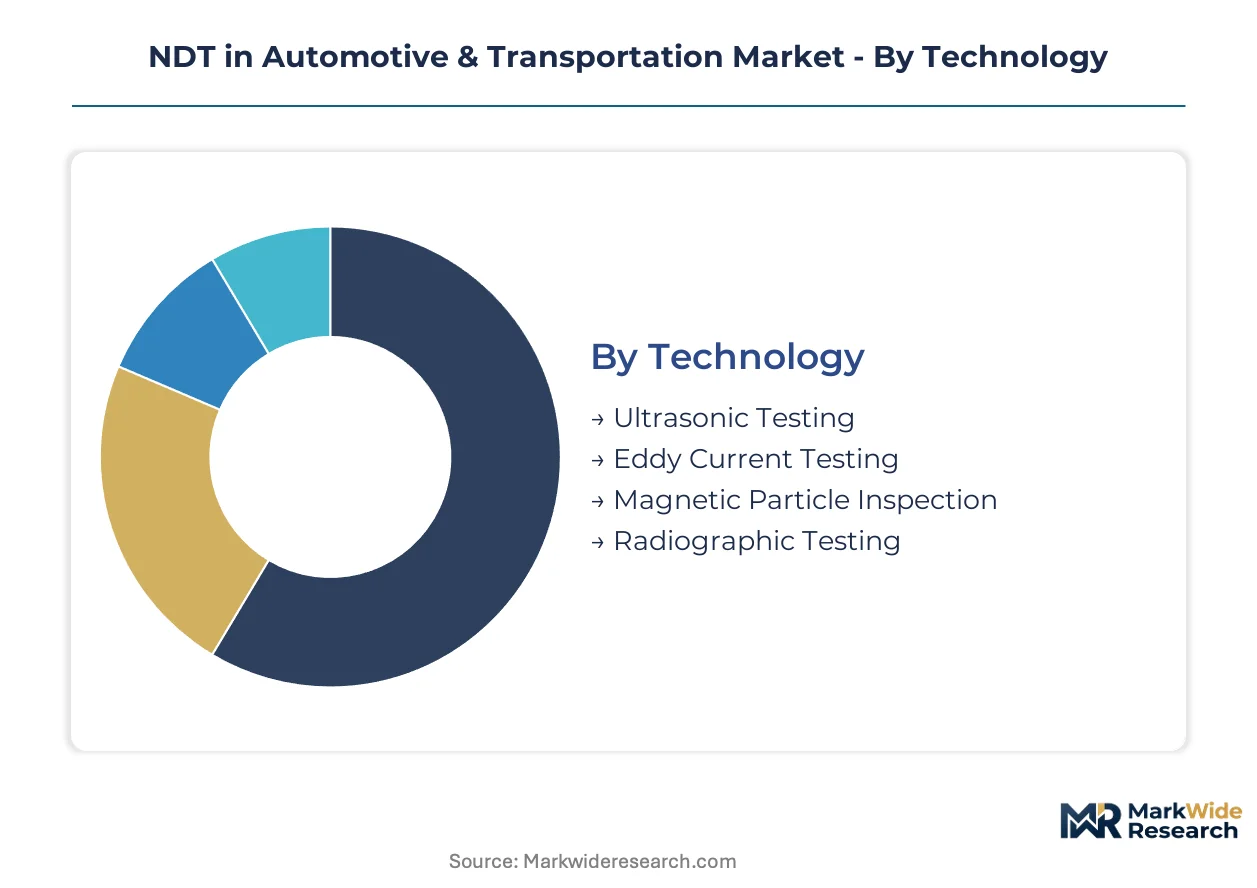
NDT procurement patterns in automotive and transportation diverge sharply across technology modalities and service delivery models. Capital deployment, regulatory compliance burdens, and supply chain positioning vary by segment in ways that reshape vendor selection criteria and contract structures.
Technology:
Capital intensity clusters around modalities requiring specialized hardware arrays and software infrastructure, with portable system development demanding sustained R&D commitment.
- Ultrasonic Testing:Phased-array systems transmit high-frequency sound waves through aluminum castings and composite laminates to map internal discontinuities. German EV battery pack manufacturers in Stuttgart and Munich deploy these units inline for EU Battery Passport traceability, with each installation requiring six-figure capital outlays for multi-probe configurations.
- Eddy Current Testing:Electromagnetic induction detects surface-breaking cracks and conductivity variations in conductive materials. Copper hairpin winding inspection for electric motors in China's Suzhou manufacturing corridor drives demand, though penetration depth limitations below 3 mm force complementary destructive testing protocols for subsurface void validation.
- Magnetic Particle Inspection:Ferromagnetic substrate validation using magnetic field distortion and particle aggregation.
- Radiographic Testing:X-ray and gamma-ray imaging for dense material penetration where ultrasonic methods attenuate.
Most installed capacity flows through Ultrasonic Testing. Expansion is steepest in Eddy Current Testing.
Application:
Validation scope determines staffing ratios and certification requirements, with component-level work multiplying touchpoints per vehicle platform.
- Component Inspection:Individual part validation across powertrain, chassis, and electrical subsystems. Powertrain electrification multiplies inspection points per vehicle, with structural battery enclosures alone requiring 12-18 discrete validation sequences at aluminum casting suppliers serving BMW and Mercedes-Benz production lines.
- Structural Integrity:Frame, monocoque, and suspension assembly assessment for crashworthiness compliance. German KBA type-approval protocols mandate full-vehicle structural scanning for EV platforms, with inspection stations concentrated in Wolfsburg and Ingolstadt assembly corridors.
- Safety Assessment:Brake, steering, and occupant protection system validation.
- Quality Control:Process monitoring and statistical process control integration.
Revenue concentration sits with Component Inspection. Safety Assessment is gaining share fastest as autonomous vehicle liability frameworks tighten.
End User:
Procurement authority and technical specification control shift dramatically across the value chain, with OEMs dictating standards that cascade to supplier tiers.
- OEMs:Brand-holding manufacturers with captive inspection laboratories and vendor qualification authority. Volkswagen Group and Toyota Motor Corporation maintain centralized NDT specification teams that pre-approve supplier inspection protocols, with compliance audits conducted at Tier-1 facilities in Mexico and Thailand.
- Tier-1 Suppliers:Component and subsystem manufacturers subject to OEM-mandated validation requirements. China's Yangtze Delta suppliers now demand 36-month master service contracts with penalty clauses for missed detection events, displacing spot-market transactional relationships.
- Aftermarket Providers:Post-warranty inspection and remanufacturing validation services.
- Vehicle Assemblers:Final assembly line integration and end-of-line quality gates.
Contract value aggregates at OEMs. Steepest growth in outsourced spend occurs at Tier-1 Suppliers.
Service Type:
Revenue model stability varies by offering, with asset-heavy rental and on-site deployment contrasting against knowledge-based consulting and training.
- Consulting:Protocol design, regulatory pathway navigation, and inspection program architecture. EU Green Deal material traceability requirements and REACH substance restrictions force data architecture investments that reshape competitive differentiation around traceability depth.
- Training:Operator certification and competency maintenance under EN ISO 9712 and ASNT guidelines. Phased-array Level 2 qualification demands 800+ supervised inspection hours, creating 18-month pipeline delays as training capacity lags equipment deployment across Eastern European supplier parks.
- Equipment Rental:Short-term hardware access for project-specific validation campaigns.
- On-site Services:Deployed technician teams for inspection execution at customer facilities.
Margin stability favors Consulting. Volume expansion concentrates in On-site Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands higher inspection equipment density per assembly line than China, yet China's eastern manufacturing corridor processes greater absolute validation volumes for domestic EV production.
China
EV battery pack manufacturers in Shanghai and Suzhou expand ultrasonic testing protocols to serve domestic production lines. MIIT enforces GB standards for new energy vehicle safety that mandate traceable defect documentation. NDT service providers cluster around the Yangtze River Delta to capture Tier-1 supplier contracts with penalty clauses for missed detection events.
Germany
Aluminum-intensive EV platforms multiply inspection points per vehicle body at Stuttgart and Munich assembly corridors. KBA enforces divergent type-approval testing protocols that fragment service standardization across EU borders. Phased-array ultrasonic systems deploy inline for EU Battery Passport compliance, with structural battery enclosures requiring 12-18 discrete validation sequences.
United States
OEM captive laboratories in Detroit and Tennessee pre-approve supplier inspection protocols for powertrain electrification. NHTSA maintains autonomous vehicle liability frameworks that tighten safety assessment requirements. Tier-1 facilities in Mexico face dual certification complexity when supplying components northward.
Japan
Hydrogen fuel cell vessel inspection protocols emerge under METI JIS standards for 700-bar storage tanks. Copper hairpin winding inspection for electric motors drives eddy current testing demand in Nagoya manufacturing clusters. South Korean and Australian regulators adopt these template protocols, creating harmonized export pathways for Japanese equipment suppliers.
India
Domestic EV manufacturing incentives under the PLI scheme create first-mover positioning for inspection service providers. BIS aligns with international standards for component validation as Chennai and Pune assembly corridors expand. Training capacity lags equipment deployment, creating 18-month pipeline delays for phased-array operator certification.
NDT in Automotive & Transportation Market Competitive Landscape
German producers anchor one tier of equipment supply; Japanese specialists hold advanced sensor architecture. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive NDT divisions, pure-play inspection service networks, and precision equipment manufacturers. Consolidation concentrates among testing service providers, while equipment fabrication retains fragmentation. Competitive moves emphasize long-term outcome-based contracts and digital twin integration for predictive maintenance subscriptions.
Within the diversified industrial tier, Baker Hughes Company and Olympus Corporation exemplify equipment-software integration strategies. SGS SA occupies a position representing the global laboratory network archetype. Bureau Veritas anchors specialized certification services for rail infrastructure. These three entities collectively illustrate how competitive differentiation shifts toward traceability depth and balance-sheet capacity to absorb warranty exposure.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Mistras Group Inc. |
| SGS SA |
| Intertek Group plc |
| Applus Services SA |
| Bureau Veritas |
| Olympus Corporation |
| TÜV SÜD AG |
| DEKRA SE |
| Others |
Pricing and Supply Chain Analysis
Helium spot prices at the Ras Laffan benchmark cascade through hydrogen fuel cell vessel inspection costs, compressing margins for leak-detection service providers and forcing tiered pricing stratification across premium certified and standard uncertified validation tiers.
Pricing Analysis
Distributor markup layers separate equipment manufacturers from end-user pricing, with phased-array ultrasonic systems commanding premium positioning against legacy radiographic alternatives. Price differentiation rests on EN ISO 9712 operator certification tier and software-enabled digital twin integration depth. Cost compression in standard ultrasonic probe segments is intensifying because Chinese domestic suppliers are flooding the Yangtze Delta with unbranded hardware. Tier-1 suppliers in Germany exhibit lowest price sensitivity due to warranty exposure absorption requirements, while Indian PLI-scheme beneficiaries negotiate aggressively on training and consulting bundles.
Supply Chain Analysis
Single-source vulnerability sits with Qatar and Algeria for helium refining capacity that feeds hydrogen vessel leak detection protocols. Hardware fabrication concentrates in Germany, Japan, and China, with sensor arrays and piezoelectric crystals drawing from specialized foundries in Nagoya and Stuttgart. Regulatory restriction risk looms through EU Battery Passport documentation mandates that fragment component traceability systems. Distribution runs through OEM-captive laboratories in Stuttgart, Detroit, and Shanghai, with Tier-1 supplier parks in Mexico and Thailand adding intermediary complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through AI-augmented inspection automation that collapses labor intensity per validation sequence, while premium-tier demand concentrates around digital twin-enabled predictive maintenance subscriptions.
For Market Incumbents: Cement long-term outcome-based contracting structures with European automakers before KBA-ANSM protocol divergence hardens into permanent compliance fragmentation. Acquire phased-array training capacity in Eastern European supplier parks to resolve 18-month operator certification bottlenecks. Vertical integration into edge-AI software stacks defends against pure-play analytics entrants. For New Entrants and Emerging Players: Machine-learning defect classification offers a technology-first wedge into battery weld seam validation, where BMW and Mercedes-Benz production lines have demonstrated scalable deployment. White-space concentrates in India's Chennai and Pune corridors under PLI scheme alignment, with hydrogen vessel certification protocols emerging as a harmonized export pathway. Lead with 36-month master service contracts featuring penalty-backed zero-defect guarantees to displace spot-market incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play inspection service networks possessing balance-sheet capacity to absorb warranty exposure from Tier-1 suppliers. Long-term viability favors entities with demonstrated EU Battery Passport compliance architecture and established METI JIS certification pathways. Watch for phased-array operator training capacity expansion as the inflection signal for market share capture feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Real-time NDT data feeds into predictive maintenance models for commercial fleets, compressing warranty cycles. |
| Backward Integration into Sensor Arrays | In-house piezoelectric crystal production reduces dependency on Nagoya and Stuttgart foundry supply. |
| EU Battery Passport Compliance Architecture | Traceable defect documentation systems anchor long-term contracts with KBA-regulated German automakers. |
| Phased-Array Training Capacity Expansion | Resolving 18-month EN ISO 9712 Level 2 certification pipelines unlocks inline deployment revenue. |
| Hydrogen Vessel Certification Harmonization | METI JIS template protocols adopted by South Korean and Australian regulators create exportable service standards. |
Research Methodology
Direct dialogue with NDT equipment procurement managers at Tier-1 suppliers, OEM platform engineering directors, and EN ISO 9712 certification body administrators grounded qualitative findings. Secondary validation drew from KBA type-approval documentation, MIIT GB standard publications, METI JIS revision notices, and vehicle production registration databases. Bottom-up inspection service revenue estimates triangulated against top-down EV platform aluminum intensity projections.
Bottom-up modeling segmented revenue across ultrasonic, eddy current, magnetic particle, and radiographic modalities, then cross-referenced against powertrain electrification content-per-vehicle trajectories. Top-down validation applied regional production cluster analysis across Stuttgart, Shanghai, Detroit, and Nagoya corridors. CAGRs were derived from installation base expansion rates and modality-specific pricing trajectories across the analysis window. Forecast inputs incorporated EU Battery Passport implementation timelines and helium supply concentration risk factors.
The model holds under stable regulatory harmonization momentum; deviation in KBA-ANSM protocol divergence or Qatar-Algeria helium export restrictions would shift equipment deployment timelines. Forecasts reflect documented assumptions regarding EV platform aluminum penetration and phased-array operator training capacity expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Automotive Emission Analyzer Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
Diagnostic Tools for Evs Market
Automotive Testing and Simulation
Automotive Emission Test Equipment Market
Automotive Testing and Simulation
On-Board Data Logger and Road Test Equipment System Market
Automotive Testing and Simulation
Vehicle Testing Equipment Market
Automotive Testing and Simulation
Automotive Driving Simulators Market
Automotive Testing and Simulation
Fleet Over-the-Air Software Update Validation Test Platforms Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Market
Automotive Testing and Simulation
Torque Gauge Market
Automotive Testing and Simulation
Motor Testing Equipment Market
Automotive Testing and Simulation
Wheel Alignment Equipment Market
Automotive Testing and Simulation
Electric Vehicle Edrive Test Equipment Market
Automotive Testing and Simulation
Autonomous Valet Parking System Scenario-Based Test Equipment Market
Automotive Testing and Simulation
Vehicle Scanner Market
Automotive Testing and Simulation
Torque Testers Market