
 Turbine Housing for Automobile Market | 2026-2036
Turbine Housing for Automobile Market Size, Share, and Industry Trends Forecast 2026-2036
Turbine Housing for Automobile Market Insights
Modular turbocharger packaging is restructuring procurement patterns across vehicle platforms. Garrett Motion leverages integrated manifold-turbine housing assemblies to reduce thermal losses and assembly steps for OEM customers. BorgWarner sustains engineering partnerships with European and Asian automakers through variable geometry architectures. Bosch anchors its position via captive foundry capacity for nickel-resist ductile iron castings used in heavy-duty applications.
Turbine housing for automobile denotes the stationary shroud enclosing the turbine wheel in exhaust-driven forced induction systems, typically cast from austenitic ductile iron or aluminum-silicon alloys to withstand gas temperatures exceeding 900°C and cyclic thermal fatigue. Its primary function channels exhaust kinetic energy onto the turbine blades while maintaining aerodynamic efficiency and structural integrity under pressure pulsation. Cast iron formulations dominate heavy-duty and high-thermal-load segments where creep resistance and oxidation tolerance command premium positioning, while aluminum variants penetrate light-duty platforms where mass reduction drives material substitution. Variable geometry installations represent the fastest-expanding configuration category as actuated vane mechanisms enable broader engine map efficiency across speed-load conditions.
EPA tailpipe regulations and the EU F-Gas framework shape product specifications by mandating leak-tight sealing surfaces and compatible refrigerant circuit interfaces in hybrid-boosted architectures. China's MEE enforces Stage VI-b particulate limits that force turbine housing designs toward higher boost pressures and integrated exhaust aftertreatment mounting. Stakeholders must monitor divergence between regional emissions certification timelines and foundry capacity allocation across material grades to avoid qualification bottlenecks.
Market Dynamics
Modular turbocharger packaging is restructuring procurement patterns across vehicle platforms. Integrated manifold-turbine housing assemblies reduce thermal losses and assembly steps, forcing suppliers to consolidate casting and machining competencies under single-source contracts.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Passenger vehicle OEMs expand turbocharged engine portfolios to meet tightening fleet efficiency mandates. High-pressure cast turbine housings enable higher boost ratios without displacement penalties.
- China Stage VI emissions compliance:MEE enforcement of Stage VI-b particulate limits forces turbine housing designs toward higher boost pressures and integrated exhaust aftertreatment mounting. Foundries serving domestic automakers upgrade nickel-resist ductile iron capacity.
- Aluminum-silicon alloy substitution:Light-duty platforms prioritize mass reduction over absolute thermal tolerance. Cast aluminum variants penetrate passenger car segments where gas temperatures remain below 850°C.
Market Restraints
- Nickel and molybdenum input volatility:Austenitic ductile iron formulations depend on alloy additions whose prices fluctuate with stainless steel and superalloy demand cycles. Foundry margins compress when raw material costs spike without pass-through clauses.
- German supplier ecosystem concentration:Bosch and Continental anchor captive foundry networks in Baden-Württemberg and Bavaria. Tier 2 casting houses outside this cluster face qualification barriers for OEM direct supply.
- Creep resistance ceiling in aluminum variants:Aluminum-silicon alloys soften above 350°C sustained operation. Heavy-duty and performance applications remain locked to cast iron despite mass penalties.
Strategic Opportunities
- India PLI scheme for auto components:Production-linked incentives for advanced automotive technology attract turbocharger housing investments. Domestic foundries serving Maruti Suzuki and Tata Motors expand high-pressure die casting lines.
- Hybrid-boosted architectures:48V mild-hybrid systems integrate electric assist with exhaust-driven turbos. Dual-boost configurations demand compact turbine housings with refrigerant circuit interfaces.
- Variable geometry mechanism convergence:Actuated vane systems merge with electronic boost control. Integrated actuator-turbine housing modules replace discrete component sourcing.
Industry Challenges
- Thermal fatigue simulation expertise:Cyclic loading above 900°C requires advanced finite element analysis capabilities. Foundries lack sufficient computational fluid dynamics specialists to accelerate qualification timelines.
- Stage VI-b certification synchronization:China's MEE approval cycles for new housing geometries lag behind engine platform launches. OEMs face vehicle homologation delays when foundry capacity misaligns with test schedule.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turbine Housing for Automobile Market |
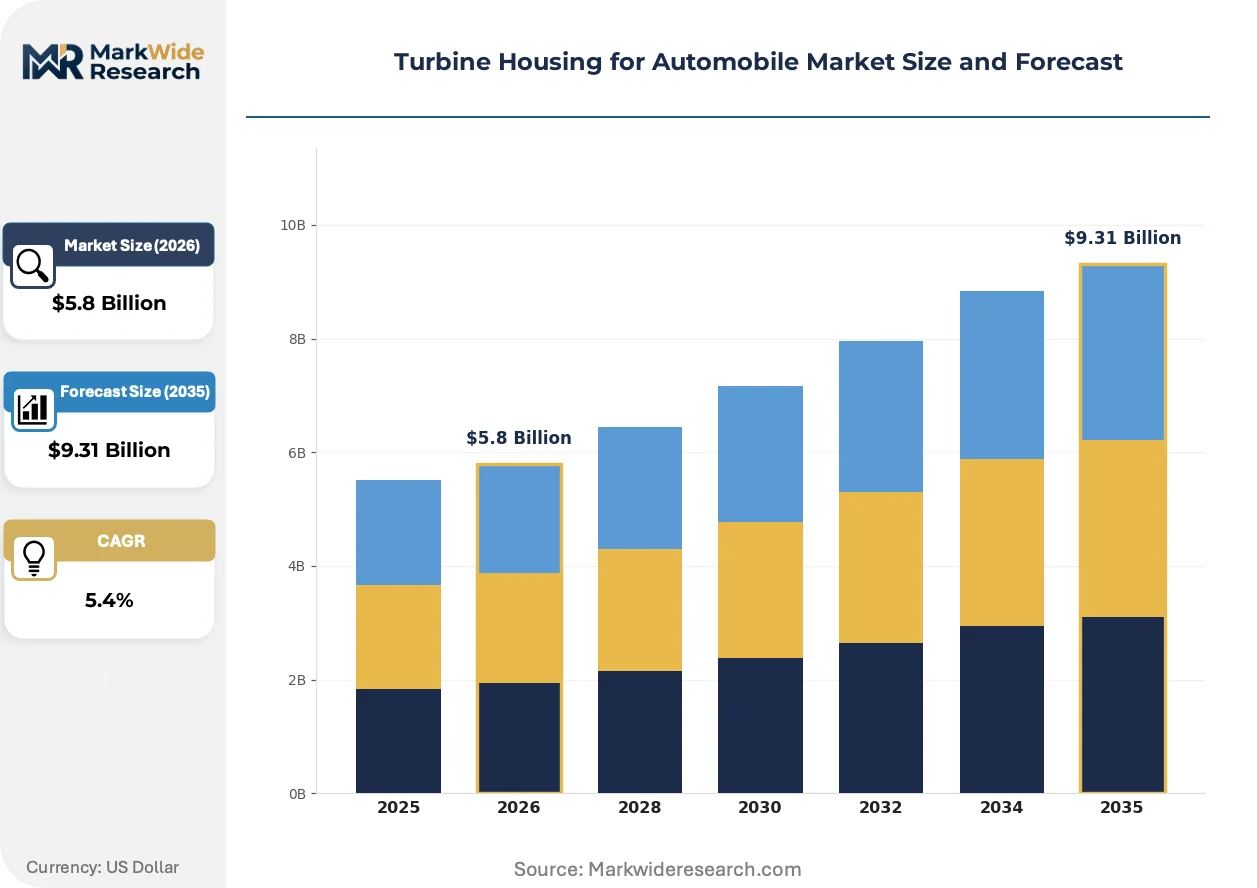
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.31 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Turbocharger, Twin-scroll, Variable Geometry, Single-scroll Material: Aluminum, Cast Iron, Steel, Composite Installation: Direct Mount, Remote Mount, Integrated Systems, Standalone Units End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers |
| Companies Covered | Garrett Motion, BorgWarner, Bosch, CIE Automotive, Le Belier, Linamar, Teksid, Aisin Takaoka, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turbine Housing for Automobile Market Trends and Innovations
Material-process convergence and regulatory stringency are compressing development cycles for turbine housing architectures. Suppliers must simultaneously advance thermal performance, mass efficiency, and emissions integration.
Integrated manifold-turbine housing assemblies are integrating exhaust routing and turbocharger mounting into single castings. Passenger vehicle OEMs in Germany and Japan adopt these modules to eliminate gasket interfaces and reduce assembly labor. Garrett Motion and BorgWarner engineering partnerships accelerate this consolidation by co-developing thermal management strategies with automakers.
EU F-Gas framework restrictions on fluorinated greenhouse gases are reshaping sealing surface specifications. Leak-tight interfaces between turbine housings and refrigerant circuits become mandatory in hybrid-boosted systems. European OEMs specify compatible elastomer grades and surface finishes that withstand R-1234yf exposure during thermal cycling.
Buyer concentration among platform-sharing alliances is compressing supplier negotiation cycles. Volkswagen Group and Renault-Nissan-Mitsubishi consolidate turbocharger sourcing across multiple brands. Tier 1 suppliers face annual price-down targets while absorbing tooling amortization across shrinking per-platform volumes.
Turbine Housing for Automobile Market Segmentation
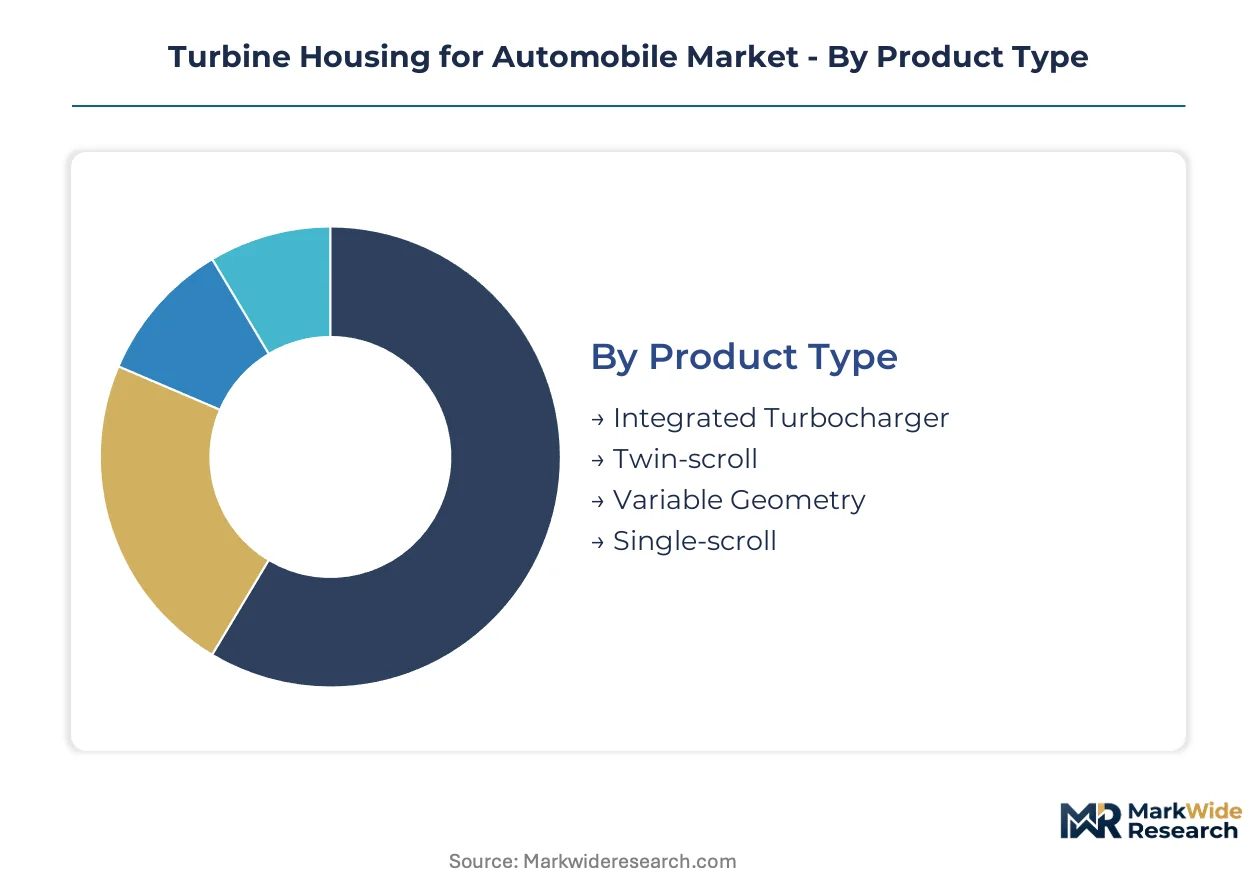
Turbine housing architectures fragment across thermal load requirements, manufacturing constraints, and OEM platform strategies. Material selection and packaging geometry determine foundry capital allocation and supplier qualification pathways.
Product Type:
Supply concentration tilts toward integrated assemblies as Garrett Motion and BorgWarner consolidate casting and machining under single-source contracts.
- Integrated Turbocharger:Combines turbine housing, compressor cover, and bearing housing into one cast module. Passenger vehicle OEMs in Germany and Japan adopt these units to eliminate gasket interfaces and reduce assembly labor on high-volume platforms.
- Variable Geometry:Actuated vane mechanisms enable broader engine map efficiency across speed-load conditions. China Stage VI-b enforcement accelerates demand for these configurations in domestic automaker portfolios.
- Twin-scroll:Separates exhaust pulses to reduce turbo lag in four-cylinder engines.
- Single-scroll:Simpler casting geometry serves cost-sensitive applications and replacement markets.
Today's leader: Integrated Turbocharger. Tomorrow's challenger: Variable Geometry.
Material:
Cost tiers separate thermal performance grades, with nickel-resist formulations commanding premium positioning against aluminum substitution in light-duty segments.
- Cast Iron:Austenitic ductile iron formulations withstand sustained temperatures exceeding 900°C. Heavy-duty applications and performance platforms in Germany's automotive belt specify these grades for creep resistance and oxidation tolerance.
- Aluminum:Aluminum-silicon alloys reduce mass by 40-50% versus iron equivalents. Passenger car segments where gas temperatures remain below 850°C drive foundry investment in high-pressure die casting capacity.
- Steel:Fabricated steel housings serve aftermarket replacement and racing applications.
- Composite:Ceramic matrix and polymer composites remain developmental for extreme thermal management.
Cast Iron retains volume leadership. Aluminum gains share fastest in light-duty OEM specifications.
Installation:
Application requirements dictate packaging geometry, with engine bay thermal management and aftertreatment integration driving configuration selection.
- Integrated Systems:Manifold-turbine housing assemblies merge exhaust routing and turbocharger mounting into single castings. Volkswagen Group and Renault-Nissan-Mitsubishi platform-sharing alliances specify these modules to reduce part count.
- Direct Mount:Traditional flange-mounted configurations dominate established engine architectures and service replacement.
- Remote Mount:Separates turbocharger from exhaust manifold for packaging flexibility in hybrid architectures.
- Standalone Units:Discrete turbine housings serve aftermarket rebuilders and custom applications.
Integrated Systems anchor new platform development. Remote Mount expands with 48V mild-hybrid packaging constraints.
End User:
Customer type determines margin structure and contract duration, with captive foundry networks serving OEM direct supply against merchant producers feeding aftermarket channels.
- OEMs:Volkswagen Group, Stellantis, and Toyota Motor Corporation specify turbine housings through multi-year platform contracts. Annual price-down targets compress supplier margins while tooling amortization stretches across shrinking per-platform volumes.
- Tier-1 Suppliers:Bosch and Continental anchor captive foundry networks in Baden-Württemberg and Bavaria, supplying integrated assemblies to OEM assembly plants.
- Vehicle Assemblers:Contract manufacturers and emerging market producers source through Tier-1 intermediaries.
- Aftermarket Providers:Independent distributors and rebuilders serve replacement demand with reverse-engineered or licensed geometries.
OEMs command specification authority. Aftermarket Providers capture residual value in vehicle parc aging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turbocharger manufacturing scaled in Germany's automotive belt during the 1980s as Bosch and Continental developed captive foundry networks for high-pressure cast components. Foundry capacity subsequently dispersed to China and India as emissions regulations tightened across multiple jurisdictions.
China
Domestic automakers expand turbocharged portfolios to meet MEE Stage VI-b particulate limits. The country's environmental ministry enforces stricter certification cycles than previous standards. Foundry clusters in Shanghai and Chongqing upgrade nickel-resist ductile iron capacity for higher boost pressure designs.
Germany
Volkswagen Group and BMW specify integrated manifold-turbine housing assemblies across platform-sharing alliances. KBA enforces type approval protocols that synchronize with EU F-Gas framework sealing requirements. Bosch anchors supplier ecosystems in Baden-Württemberg and Bavaria with captive casting operations.
United States
EPA Corporate Average Fuel Economy standards drive passenger vehicle OEMs toward downsized turbocharged engines. NHTSA coordinates safety certification with emissions timelines. Manufacturing concentrates in Michigan and Ohio where Tier 1 suppliers feed Detroit Three assembly plants.
India
Maruti Suzuki and Tata Motors expand turbocharged offerings in compact passenger segments. The government's PLI scheme for auto components attracts high-pressure die casting investments. Foundry capacity expands in Tamil Nadu and Gujarat to serve domestic OEM procurement.
Japan
Toyota Motor Corporation and Honda Motor integrate turbochargers into hybrid-boosted architectures. METI oversees harmonization with international emissions protocols. Industrial clusters in Aichi and Shizuoka prefectures maintain precision casting expertise for thermal fatigue resistance.
Turbine Housing for Automobile Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material-grade specialization and captive foundry ownership. The market structure consolidates around Tier 1 suppliers with backward integration into casting operations and Tier 2 merchant foundries serving aftermarket channels. Strategic archetypes include integrated system suppliers with captive metallurgy capabilities, specialized high-pressure die casters for aluminum variants, and diversified automotive component conglomerates with turbocharger divisions. Dominant competitive moves encompass capacity expansion in nickel-resist ductile iron grades and strategic partnerships for variable geometry mechanism integration.
Within the integrated system supplier tier, Garrett Motion and BorgWarner occupy positions defined by engineering partnerships with European and Asian OEM platforms. Bosch exemplifies the captive-foundry archetype through in-house production of nickel-resist formulations. These three companies represent distinct competitive vectors: Garrett Motion anchors North American and European platform development, BorgWarner sustains variable geometry technology positioning, and Bosch leverages German manufacturing cluster proximity for OEM direct supply.
| Leading Market Players |
|---|
| Garrett Motion |
| BorgWarner |
| Bosch |
| CIE Automotive |
| Le Belier |
| Linamar |
| Teksid |
| Aisin Takaoka |
| Mitsubishi Heavy Industries |
| Others |
Pricing and Supply Chain Analysis
Computational fluid dynamics specialists concentrated in Germany's automotive belt create labor-cost differentials that widen pricing spreads between premium nickel-resist formulations and standard aluminum variants. Tier 2 foundries outside Baden-Württemberg and Bavaria absorb margin compression from qualification barriers while captive operations at Bosch and Continental sustain premium positioning.
Pricing Analysis
Three-tier pricing structure across premium nickel-resist ductile iron, standard austenitic cast iron, and economy aluminum-silicon alloy grades separates OEM direct supply from aftermarket channels. Price differentiation hinges on thermal fatigue certification cycles and captive foundry ownership. Cost compression in aluminum variants is intensifying because passenger car OEMs prioritize mass reduction over absolute creep resistance. Aftermarket rebuilders exhibit highest price sensitivity; Volkswagen Group and BMW platform contracts show lowest.
Supply Chain Analysis
Nickel and molybdenum supply rests on South African mining operations and Russian ferroalloy producers, with secondary refining concentrated in China and Finland. Foundries draw from specialty alloy distributors, high-purity pig iron sources, and ceramic core suppliers for complex casting geometries. Single-source vulnerability runs through nickel-resist formulation patents held by German metallurgical specialists. Distribution runs through Tier 1 integrated suppliers to OEM assembly plants, with merchant foundries serving aftermarket channels via independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
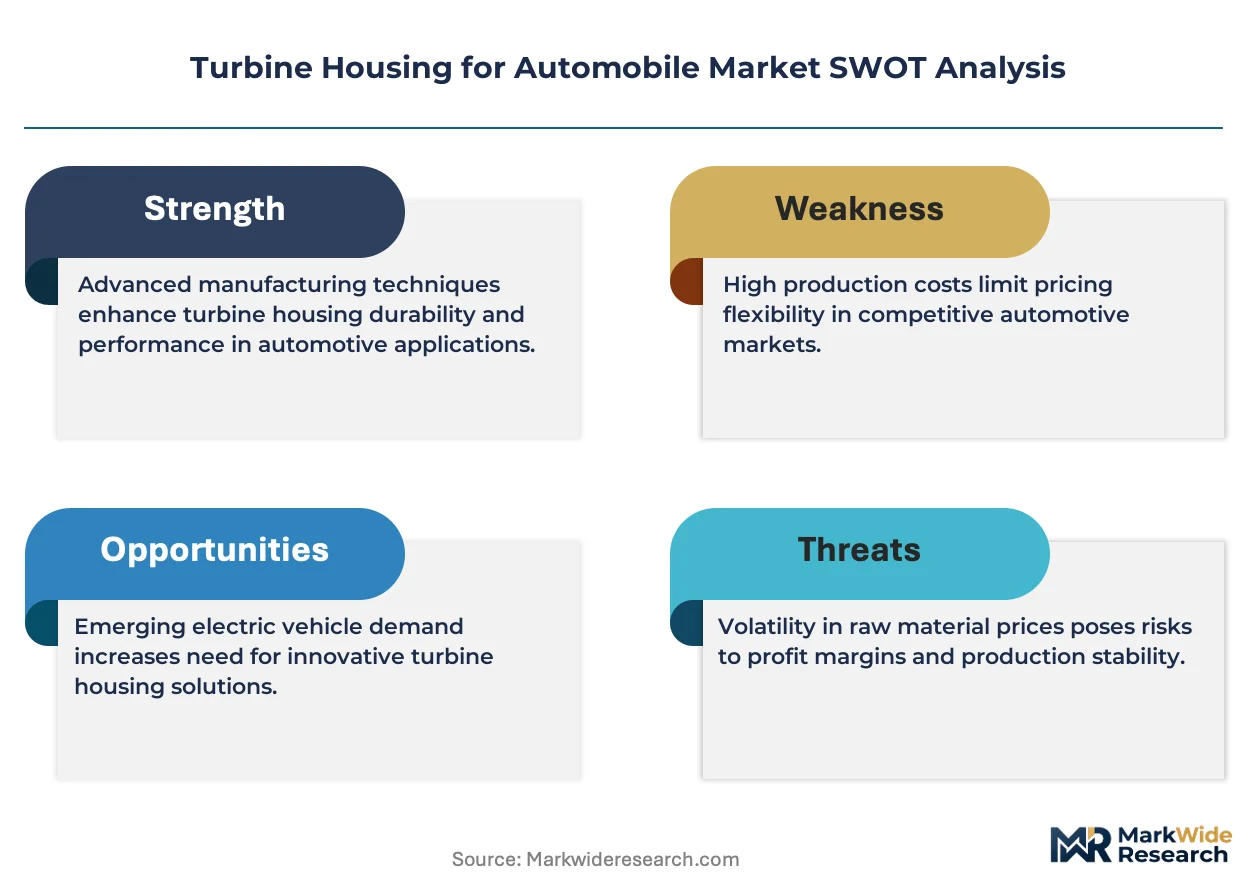
Margin expansion in turbine housing supply hinges on aluminum alloy substitution accelerating cost-down trajectories in light-duty segments while nickel-resist grades capture premium thermal performance positioning.
For Market Incumbents: To counter foundry capacity misalignment with China Stage VI-b certification timelines, anchor qualification pipelines with MEE pre-submission protocols and expand captive nickel-resist capacity in Baden-Württemberg. Deepen backward integration into high-pressure die casting for aluminum variants to capture light-duty platform share from Garrett Motion and BorgWarner partnerships. For New Entrants and Emerging Players: Direct sourcing platforms for Tier 2 foundries offer the fastest penetration route into OEM supply chains excluded from German supplier ecosystems. Target India's PLI scheme beneficiaries in Tamil Nadu and Gujarat with high-pressure die casting partnerships for Maruti Suzuki and Tata Motors procurement. Lead with thermal fatigue simulation services to accelerate qualification timelines for domestic Chinese automakers. For Investors and Strategic Acquirers: Tier 1 automotive component conglomerates with turbocharger divisions are the most active acquirers in this space, seeking captive foundry assets to secure nickel-resist supply. Long-term viability favors integrated system suppliers with backward metallurgy control over merchant aluminum casters facing creep resistance ceilings. Watch for MEE Stage VI-b enforcement acceleration as the inflection signal for premium-grade capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Expansion | Bosch's nickel-resist capacity in Bavaria locks in Volkswagen Group platform contracts against Tier 2 competition. |
| Aluminum Alloy Substitution | High-pressure die casting investments in India PLI zones capture mass-reduction specifications from Maruti Suzuki. |
| Integrated Assembly Partnerships | Garrett Motion's manifold-turbine modules eliminate gasket interfaces for Japanese OEM thermal management targets. |
| Variable Geometry Convergence | Actuated vane mechanism integration with electronic boost control merges discrete component categories under single sourcing. |
| Stage VI-b Pre-Certification | MEE alignment protocols in Shanghai and Chongqing foundries prevent homologation delays for domestic automaker launches. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, foundry operations managers, and thermal fatigue simulation specialists. Secondary validation drew from EPA enforcement databases, China MEE certification filings, EU F-Gas framework documentation, and automotive production registration data. Bottom-up capacity modeling and top-down OEM procurement triangulation anchored volume estimates.
Segment-weighting applied material-grade splits, installation geometry categories, and regional production cluster distributions across the projection horizon. The analytical framework modeled thermal load requirements, manufacturing constraints, and OEM platform strategies as core dimensions. CAGRs derived from foundry capacity utilization curves and emissions regulation phase-in schedules. Industry-specific inputs included nickel-resist alloy price indices and Stage VI-b certification cycle timelines.
The model assumes a particular technology adoption path; alternative pathways for aluminum-silicon alloys exceeding 350°C sustained operation would alter the outlook. Forecasts reflect assumptions about MEE enforcement consistency and EPA CAFE standard continuity. Regulatory divergence, raw material volatility, and thermal fatigue simulation talent scarcity warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Italy Electro Hydraulic Power Steering Market
Powertrain
Crate Engines Market
Powertrain
Automotive Transmission Repair Market
Powertrain
Modular Belt Drive Market
Powertrain
EV Drivetrain Systems Market
Powertrain
South Korea Automotive Engine Oils Market
Powertrain
Global Automotive Dyno Market
Powertrain
Automotive Power Steering Cooler Market
Powertrain
South Korea Electro Hydraulic Power Steering Market
Powertrain
Japan Automotive Engine Oils Market
Powertrain
Europe Turbocharger Market
Powertrain
Automotive Balance Shaft Market
Powertrain
Powertrain Testing Market
Powertrain
Steering Damper Market
Powertrain
UAE Automotive Engine Oils Market
Powertrain
Canada Automotive Engine Oils Market