
 Europe Automotive AHSS Market | 2026-2036
Europe Automotive AHSS Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive AHSS Market Foresight
Software-defined material certification and subscription-based performance tracking is broadening what European steel suppliers monetize beyond tonnage. ArcelorMittal SA leverages its integrated R&D pipeline to anchor next-generation press-hardening formulations for OEM programs. SSAB AB specializes in fossil-free steel variants that compete on carbon-accounted supply chains. ThyssenKrupp AG controls hot-forming technology licensing that extends its influence across Tier-1 stamping networks.
Advanced high-strength steel encompasses grades with tensile strength exceeding 500 MPa, produced through controlled thermomechanical processing and microalloying to achieve superior strength-to-weight ratios for automotive crash structures. Dual Phase steel dominates European volume applications due to its excellent formability and energy absorption in body-in-white assemblies, while Boron Steel commands premium positioning in hot-formed safety cage components where ultimate tensile strength exceeds 1500 MPa. OEM procurement of Ultra High Strength Steel is accelerating fastest among electric vehicle architectures seeking mass reduction for battery range optimization.
The EU Green Deal and REACH frameworks mandate lifecycle carbon disclosure for automotive materials, while ECHA substance restrictions shape alloying element selection across European mills. CE marking requirements for structural automotive components enforce consistent mechanical property certification that filters non-compliant imports. Stakeholders must monitor evolving EU battery regulation harmonization with vehicle lightweighting mandates, as these dual compliance streams will determine which AHSS grades achieve platform qualification across the next product cycle.
Market Dynamics
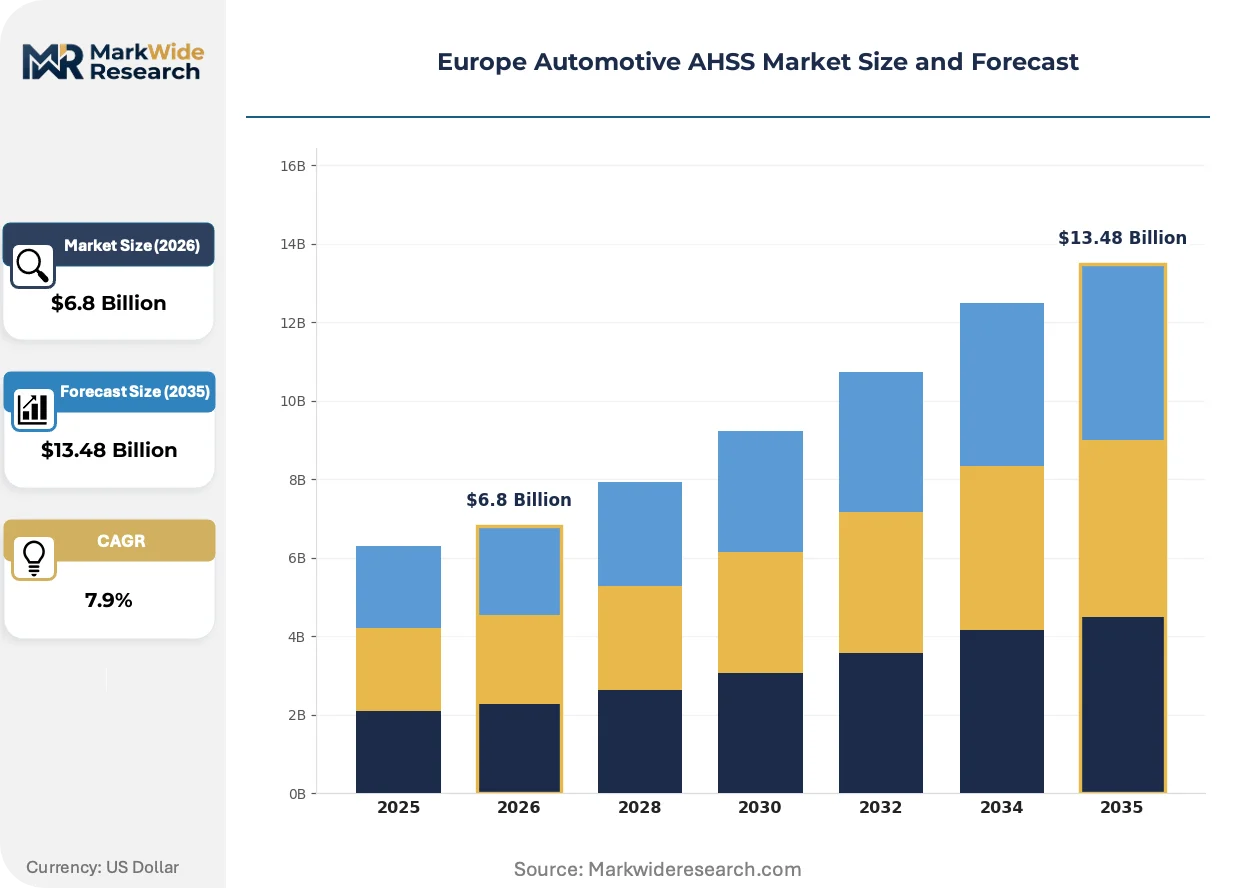
Electric vehicle platform architectures are forcing a wholesale recalibration of material specifications across European OEM body-in-white engineering departments. The EU Green Deal's embodied carbon mandates now penetrate upstream to steel mill emissions disclosures, binding procurement decisions to lifecycle accountability rather than unit cost alone.
Growth Catalysts
- EU Green Deal fleet targets:Updated CO2 emission benchmarks for 2035 are compelling manufacturers to lightweight vehicle structures without sacrificing crash performance, directly expanding AHSS specification volumes in new platform designs.
- Press-hardening technology maturation:Hot-forming process refinements are reducing cycle times and defect rates, enabling broader adoption of 1500+ MPa boron steel grades across mid-volume vehicle programs.
- German-French-Italian production corridors:Dense automotive manufacturing clusters in these three markets concentrate tooling investment and technical workforce pools, accelerating grade qualification timelines for regional mills.
Market Restraints
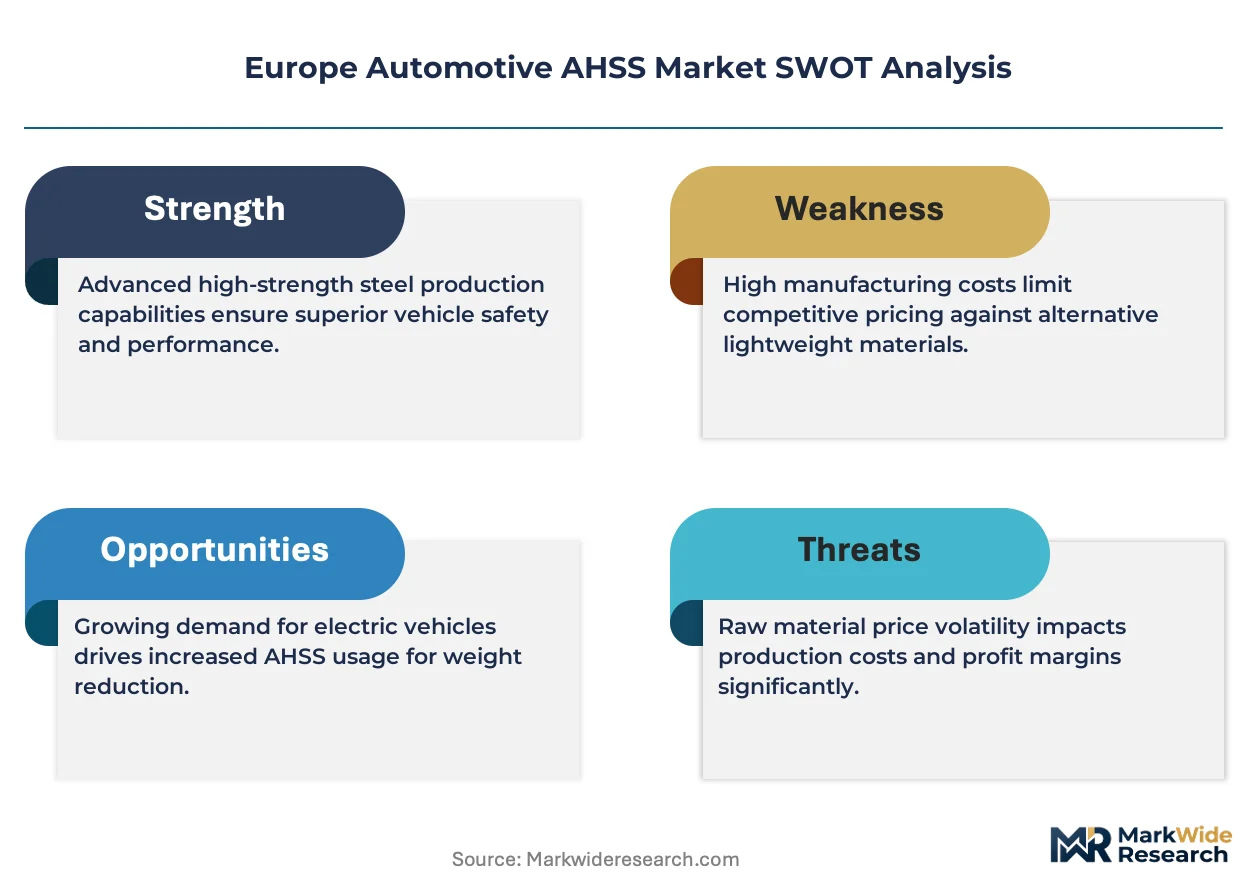
- Alloying element cost volatility:Manganese and molybdenum price swings compress mill margin buffers and destabilize long-term supply contracts with Tier-1 stamping operations.
- Scrap quality degradation:Contaminated ferrous feedstock streams are raising inclusion defect rates in electric arc furnace production, limiting output consistency for the highest strength grades.
- Aluminum substitution in battery enclosures:Extruded aluminum architectures are capturing a growing share of electric vehicle underbody structures where thermal management properties outweigh steel's cost advantage.
Strategic Opportunities
- Eastern European capacity expansion:Poland and Czech Republic automotive clusters remain underpenetrated by certified AHSS supply relative to their assembly volumes, creating whitespace for qualified mill entrants.
- Software-defined certification models:Subscription-based mechanical property tracking and digital twin validation are opening recurring revenue streams beyond commodity tonnage sales.
- REACH-aligned alloying substitution:ECHA substance restriction reviews are creating first-mover advantage for mills with pre-validated chromium-reduced formulations in their development pipelines.
Industry Challenges
- Hot-forming die engineering scarcity:Qualified tooling designers capable of managing thermal gradient control in 900°C press operations command premium wages that strain Tier-1 operational budgets.
- CE marking timeline compression:Accelerated vehicle platform cycles are compressing mechanical property certification windows, forcing mills to front-load validation testing before contract award.
- Multi-material joining complexity:Dissimilar metal welding between AHSS and aluminum components in hybrid body structures is generating rework rates that erode assembly line efficiency targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive AHSS Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.48 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Strength Steel, Ultra High Strength Steel, Boron Steel, Dual Phase Steel Application: Body Structure, Chassis Components, Safety Parts, Fuel Tanks End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Stamping, Welding, Hot Forming, Cold Forming |
| Companies Covered | ThyssenKrupp AG, ArcelorMittal SA, SSAB AB, POSCO Co. Ltd., voestalpine Stahl GmbH, Baoshan Iron & Steel Co. Ltd., Nippon Steel Corporation, Tata Steel Limited, United States Steel Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive AHSS Market Shifts & Advancements
Material informatics and computational thermomechanical modeling are compressing alloy development cycles from years to months. European mills are racing to embed carbon-accounted supply chains into product specifications before regulatory disclosure mandates harden.
Third-generation AHSS grades with retained austenite microstructures are overtaking conventional Dual Phase steels in European electric vehicle programs. OEM body engineering teams at Volkswagen Group and Stellantis are specifying these grades for B-pillar and roof rail applications where strength-ductility balance proves critical. The technology is overtaking legacy martensitic formulations in crash-critical zones previously reserved for boron steel, compressing the premium positioning of 1500 MPa hot-formed parts.
REACH substance restriction evaluations under ECHA's 2024-2026 work program are forcing alloy redesigns across European flat steel producers. Chromium and nickel compound classifications under review threaten to disqualify existing grade formulations from automotive qualification pools. Mills with pre-submitted substitution dossiers are securing preferred supplier status with OEM sustainability procurement teams ahead of formal restriction enactment.
Buyer consolidation among European Tier-1 stamping groups is concentrating contract negotiation leverage into fewer procurement desks. Magna, Gestamp, and Benteler are unbundling traditional mill relationships to source AHSS through carbon-accounted supply chain certificates rather than spot tonnage. This pattern is most visible in German OEM programs where sustainability scorecards now weight supplier selection decisions at parity with unit pricing.
Europe Automotive AHSS Market Segmentation
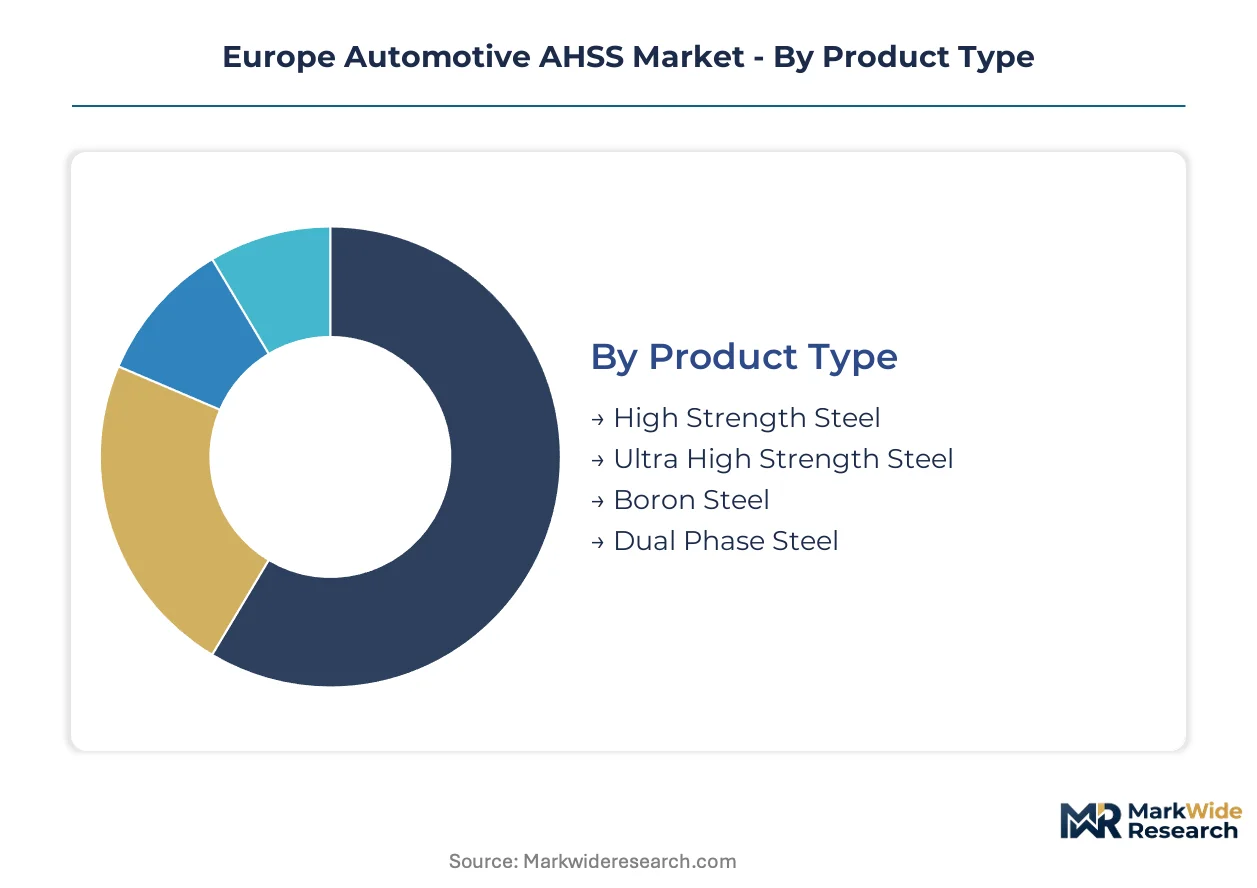
European OEM platform cycles drive replacement-grade specifications every 5-7 years, forcing mills to align AHSS development pipelines with known vehicle architecture transitions. Segmentation clarity separates commodity-grade supply from qualified program-specific material streams.
Product Type:
Upgrade cycles in European body-in-white engineering favor grades that displace legacy mild steel without retooling entire stamping lines.
- Dual Phase Steel:Ferrite-martensite microstructure delivers exceptional formability with tensile strengths of 500-800 MPa. Volkswagen Group and Stellantis specify this grade for floor pan and door inner panels across German and Italian assembly corridors where energy absorption requirements dominate design criteria.
- Boron Steel:Hot-formable 22MnB5 grade achieves 1500+ MPa tensile strength after austenitization and press hardening. BMW and Mercedes-Benz safety cage programs in Bavaria and Baden-Württemberg consume premium volumes for A-pillar and roof rail reinforcements where intrusion resistance is non-negotiable.
- Ultra High Strength Steel:Grades exceeding 980 MPa serve electric vehicle battery protection structures.
- High Strength Steel:Entry-level 300-500 MPa specifications retain volume in non-structural closures.
Dual Phase Steel sits at the top of the volume ranking, with Boron Steel climbing the fastest as hot-forming capacity expands across Tier-1 stamping networks.
Application:
Application segmentation traces load path engineering priorities from crash management through mass reduction targets.
- Body Structure:Monocoque assemblies including floor pans, pillars, and roof rails absorb 40-50% of European AHSS procurement by tonnage. German OEM engineering centers in Wolfsburg and Munich specify mixed-grade solutions balancing stiffness, formability, and weldability across 500+ individual stampings per vehicle.
- Safety Parts:Crash-absorbing front and rear rails, bumper beams, and door beams require precisely calibrated deformation characteristics. French regulatory pressure from KBA-equivalent testing protocols drives adoption of tailored dual-phase grades with controlled yield-to-tensile ratios.
- Chassis Components:Subframe and suspension arm applications favor bake-hardenable formulations.
- Fuel Tanks:Internal high-pressure hydrogen storage vessels for fuel cell vehicles specify specialized ultra-high-strength grades.
Body Structure commands the dominant tonnage position, while Safety Parts expands most quickly as Euro NCAP protocols tighten pedestrian and occupant protection thresholds.
End User:
Customer-type segmentation reveals procurement leverage concentration and technical specification authority.
- OEMs:Volkswagen Group, BMW, Mercedes-Benz, Stellantis, and Renault maintain direct mill relationships for strategic grade development and platform-specific certification. These manufacturers issue material performance specifications that Tier-1 suppliers must source against, concentrating technical influence at the brand engineering level.
- Tier-1 Suppliers:Magna, Gestamp, Benteler, and similar stamping specialists execute 60-70% of actual AHSS procurement volume. Their consolidation across German and French OEM programs has shifted negotiation leverage toward carbon-accounted supply chain certificates rather than spot pricing.
- Vehicle Assemblers:Contract manufacturers and niche EV producers access AHSS through Tier-1 channels.
- Aftermarket Providers:Collision repair and restoration applications represent fragmented, specification-limited demand.
Tier-1 Suppliers transact the largest tonnage volumes, with OEMs capturing the steepest expansion trajectory as direct mill partnerships multiply for electric vehicle platform launches.
Technology:
Process technology segmentation determines equipment investment requirements and regional capability distribution.
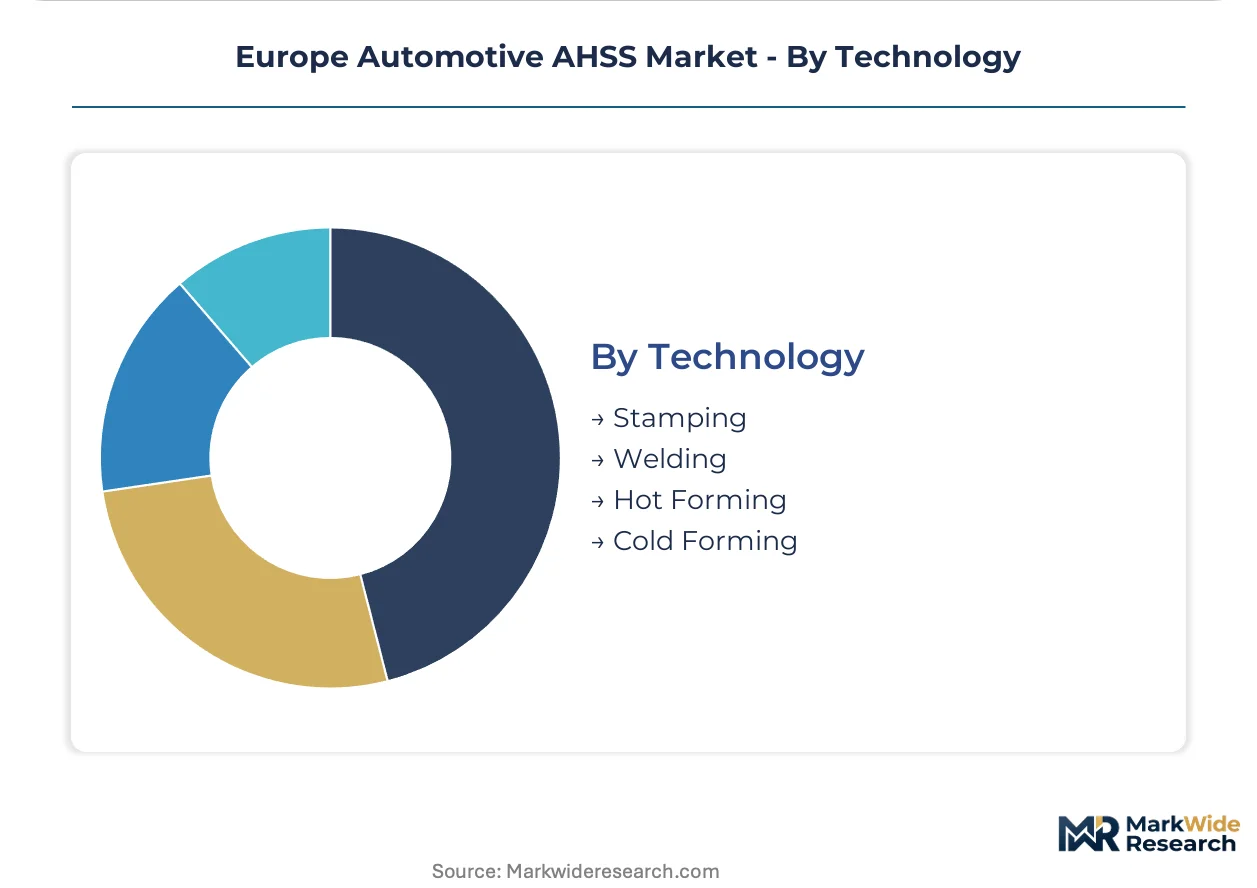
- Hot Forming:Press-hardening at 900°C enables 1500 MPa final strength in complex geometries previously impossible with cold stamping. German Tier-1 networks around Stuttgart and Munich concentrate European hot-forming capacity, with tool engineering scarcity limiting expansion speed.
- Stamping:Conventional mechanical and hydraulic press operations process 70%+ of European AHSS volume across Dual Phase and lower-tier Ultra High Strength grades. Italian automotive clusters in Turin and Milan maintain competitive stamping density for mid-volume vehicle programs.
- Welding:Resistance spot and laser welding of dissimilar AHSS grades demands precise heat input control.
- Cold Forming:Roll forming and hydroforming serve structural sections with modest complexity requirements.
Stamping retains the volume leadership position, with Hot Forming gaining share fastest as boron steel specifications penetrate mid-market electric vehicle architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands greater AHSS specification authority than France, though Italian production corridors match German tonnage in specific vehicle segments. Regulatory pressure from Brussels unifies compliance frameworks across all three markets, yet national industrial policies create divergent capacity investment patterns.
Germany
Volkswagen Group and BMW drive dual-phase and boron steel procurement for electric vehicle platforms launching from Wolfsburg and Munich engineering centers. The KBA enforces type-approval protocols that compress mechanical property certification timelines for mill suppliers. Stuttgart and Baden-Württemberg concentrate hot-forming capacity, with Tier-1 stamping networks expanding press-hardening lines to serve Mercedes-Benz safety cage programs.
France
Stellantis operations in Sochaux and Mulhouse specify tailored AHSS grades for mixed-material body-in-white architectures spanning Peugeot, Citroën, and Opel brands. The EU Green Deal's embodied carbon mandates bind Renault's Douai and Maubeuge facilities to lifecycle disclosure requirements for steel sourcing. Auvergne-Rhône-Alpes hosts specialized tooling engineering clusters serving press-hardening die manufacturers supplying both French and German OEM programs.
Italy
Stellantis maintains high-volume AHSS consumption at Mirafiori and Pomigliano d'Arco assembly plants for Fiat and Alfa Romeo platforms. REACH substance restriction reviews under ECHA's work program force Turin-based engineering teams to validate chromium-reduced grade formulations ahead of formal enactment. Emilia-Romagna's dense automotive supplier network accelerates qualification timelines for regional mills serving mid-volume vehicle programs.
Poland
Assembly operations from Fiat Tychy and Volkswagen Poznań generate underpenetrated AHSS demand relative to installed vehicle production capacity. CE marking requirements for structural automotive components filter non-compliant imports, creating entry barriers for uncertified suppliers. The Silesian and Greater Poland voivodeships concentrate emerging Tier-1 stamping investments as OEMs diversify supply chains eastward from German corridors.
Spain
SEAT-Martorell and Renault-Valladolid facilities specify AHSS grades for export-oriented production serving European and Latin American markets. Spanish national adaptation of EU CO2 fleet targets accelerates lightweighting procurement for hybrid and electric vehicle architectures. Catalonia and Castile and León maintain competitive stamping density, though hot-forming capacity lags German and French industrial clusters.
Europe Automotive AHSS Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated steel mills controlling grade development while Tier-1 stamping groups execute majority tonnage procurement. Market structure tilts toward consolidation at the mill level, where four European-headquartered suppliers anchor regional supply security. Three archetypes dominate: integrated R&D-led mills with captive ore sources, fossil-free steel specialists competing on carbon-accounted supply chains, and technology licensors extracting value from hot-forming process IP. Competitive moves center on strategic partnerships for electric vehicle platform qualification and geographic expansion into underpenetrated Eastern European automotive clusters.
Among the integrated mill tier, ArcelorMittal SA and ThyssenKrupp AG exemplify divergent strategic positioning—one leveraging global R&D scale for next-generation press-hardening formulations, the other controlling critical hot-forming technology licensing across Tier-1 networks. SSAB AB occupies a distinct position as a fossil-free steel specialist, with its carbon-accounted supply chain credentials aligning with OEM sustainability procurement scorecards. These three entities anchor the competitive landscape through their influence over grade qualification timelines and platform-specific certification authority.
| Leading Market Players |
|---|
| ThyssenKrupp AG |
| ArcelorMittal SA |
| SSAB AB |
| POSCO Co. Ltd. |
| voestalpine Stahl GmbH |
| Baoshan Iron & Steel Co. Ltd. |
| Nippon Steel Corporation |
| Tata Steel Limited |
| United States Steel Corporation |
| Others |
Supply & Pricing Matrix
Captive integration into electric arc furnace feedstock streams anchors both supply security and margin control for European AHSS mills facing REACH-aligned alloying substitution mandates. This upstream control insulates Tier-1 contract pricing from manganese and molybdenum volatility while concentrating premium-grade negotiation leverage with German and French OEM procurement desks.
Pricing Analysis
Capacity additions in Poland and the Czech Republic are reshaping price floors for standard-grade Dual Phase steel as new mill entrants compete for CE-marked qualification status. Contract-based long-term offtake dominates strategic procurement between ArcelorMittal, ThyssenKrupp, and Volkswagen Group, with price differentiation resting on carbon-accounted certification tiers and hot-forming technical support bundling. Pricing pressure stems from aluminum substitution in battery enclosures, compressing margins on ultra-high-strength grades. Tier-1 stamping operations exhibit highest price sensitivity due to consolidated buyer leverage, while OEM direct mill partnerships prioritize performance guarantees over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German hot-forming die engineering clusters, where qualified thermal gradient designers command scarcity premiums that strain Tier-1 operational budgets. Geographic supply concentrates in Germany, France, and Italy, with raw material dependencies drawing from Swedish fossil-free iron ore, Ukrainian manganese alloys, and Turkish scrap flows. Supply chain risk centers on REACH substance restriction timelines that could disqualify chromium-nickel formulations before substitution dossiers achieve ECHA approval. Distribution runs through consolidated Tier-1 stamping networks—Magna, Gestamp, Benteler—rather than direct mill-to-OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate in Eastern European automotive corridors, where Polish and Czech assembly volumes outpace certified AHSS supply penetration despite lower labor and energy costs versus German production basins. The EU Green Deal's embodied carbon disclosure mandates create regulatory differentiation between mills with pre-validated low-alloy formulations and legacy suppliers facing ECHA restriction exposure.
For Market Incumbents: Anticipate aluminum substitution threats in battery enclosure applications by accelerating third-generation AHSS development with retained austenite microstructures that match strength-ductility performance. Defensive consolidation should prioritize backward integration into scrap quality control systems, as contaminated ferrous feedstock streams increasingly limit output consistency for 1500 MPa boron grades. Certification investment in chromium-reduced formulations ahead of ECHA's restriction enactment secures preferred supplier positioning with Stellantis and Renault sustainability procurement teams.
For New Entrants and Emerging Players: A mid-tier price-point gap between premium hot-formed boron steel and economy-grade Dual Phase specifications creates entry space for qualified mills serving underpenetrated Polish and Czech Tier-1 stamping investments. White-space targets include software-defined certification models—subscription-based mechanical property tracking and digital twin validation—that extend revenue beyond commodity tonnage. The most penetrable segment is Eastern European electric vehicle platform launches, where OEMs diversify supply chains eastward from German corridors and CE marking requirements filter non-compliant imports.
For Investors and Strategic Acquirers: Roll-up economics work for fossil-free steel specialists because carbon-accounted supply chain credentials now weight supplier selection decisions at parity with unit pricing across German OEM programs. Long-term viability in the 5-10 year window favors acquisition targets with pre-submitted REACH substitution dossiers and established hot-forming technology licensing relationships. The signal to watch is Tier-1 procurement consolidation velocity—Magna, Gestamp, and Benteler unbundling traditional mill relationships for carbon-accounted certificate sourcing indicates structural preference shifts that will concentrate contract flow to qualified low-carbon suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Quality Systems | Mills controlling ferrous feedstock purity reduce inclusion defects that disqualify 1500 MPa boron grades from BMW and Mercedes-Benz safety cage programs. |
| REACH-Aligned Alloying Substitution | Pre-validated chromium-reduced formulations secure preferred supplier status with OEM sustainability procurement teams ahead of ECHA restriction enactment. |
| Software-Defined Certification Models | Subscription-based mechanical property tracking opens recurring revenue streams beyond commodity tonnage sales to Tier-1 stamping networks. |
| Eastern European Capacity Expansion | Polish and Czech automotive clusters remain underpenetrated by certified AHSS supply relative to Fiat Tychy and Volkswagen Poznań assembly volumes. |
| Hot-Forming Technology Licensing | Process IP control extends influence across Tier-1 stamping networks concentrated in Stuttgart and Baden-Württemberg production corridors. |
Research Methodology
Multiple input streams—primary interviews with OEM platform engineers, Tier-1 procurement leads, and mill technical directors; secondary validation through ECHA restriction dossiers, EU customs trade data, and vehicle production databases; plus bottom-up and top-down triangulation—were reconciled to construct segment-level demand estimates. Stakeholder roles engaged included body-in-white engineering directors at Volkswagen Group and Stellantis, hot-forming die designers in Auvergne-Rhône-Alpes clusters, and sustainability procurement specialists evaluating carbon-accounted supply chain certificates. Secondary sources encompassed CE marking compliance records, REACH substance restriction timelines, and IHS Markit vehicle registration data across German, French, and Italian production corridors.
Cross-referencing historical grade adoption curves against expert panel inputs on electric vehicle platform specifications shaped the analytical framework across the projection horizon. Segmentation dimensions modeled included steel grade tier, application load path priority, end-user procurement authority, and process technology requirements. CAGRs were derived from elasticity-adjusted demand projections tied to EU CO2 fleet target compliance trajectories and OEM lightweighting procurement commitments.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery thermal management architectures would alter the outlook by accelerating aluminum substitution in underbody structures. Forecasts reflect assumptions on hot-forming capacity expansion rates, ECHA restriction enactment timing, and scrap quality degradation trends. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Connecting Rod Bearing Market
Automotive Components
Automotive Metal Casting Market
Automotive Components
Torque Vectoring Market
Automotive Components
Germany Automotive Composites Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Automotive Brackets Market
Automotive Components
US Automotive Glass Fiber Composites Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
North America Automotive Heat Shield Market
Automotive Components
Automotive Metal Market
Automotive Components
Aftermarket Automotive Parts & Components Market
Automotive Components
Global Automotive Noise Filter Market
Automotive Components
Sheet Molding Compound (SMC) for Automotive Market
Automotive Components
Automotive Actuators Market
Automotive Components
Germany Automotive Carbon Fiber Composites Market
Automotive Components
Automotive Active Seat Headrests Market