
 Automotive Airbag and Seat Belt Market | 2026-2036
Automotive Airbag and Seat Belt Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Airbag and Seat Belt Market Intelligence
The adoption of high-strength, lightweight woven polyester over traditional nylon fabrics for webbing is consolidating the supply chain for seat belts. This shift favors suppliers with advanced material science capabilities. Autoliv Inc. leverages its significant manufacturing scale in pyrotechnic inflators and airbag cushions. Joyson Safety Systems specializes in integrated safety solutions for global automotive platforms, while ZF Friedrichshafen AG competes with a comprehensive portfolio that includes passive safety systems.
Automotive airbag and seat belt systems are passive safety apparatuses designed to reduce occupant injury during a collision. These systems use pyrotechnic inflators to deploy nylon bags and pre-tensioners to retract seat belt slack in milliseconds. Within the product mix, airbags and seat belts form the foundational segments, while pre-tensioners and load limiters are critical for performance differentiation. The integration of electronic controls is displacing older mechanical technologies, as OEMs demand more sophisticated sensor-based activation.
Regulatory frameworks from bodies like the US National Highway Traffic Safety Administration (NHTSA) and new rules under Europe's General Safety Regulation (GSR) define mandatory equipment levels. These standards compel continuous innovation in crash performance and reliability. Component suppliers must now prioritize investment in adaptive restraint systems that meet future crash test protocols and address diverse occupant sizes and positions.
Market Dynamics
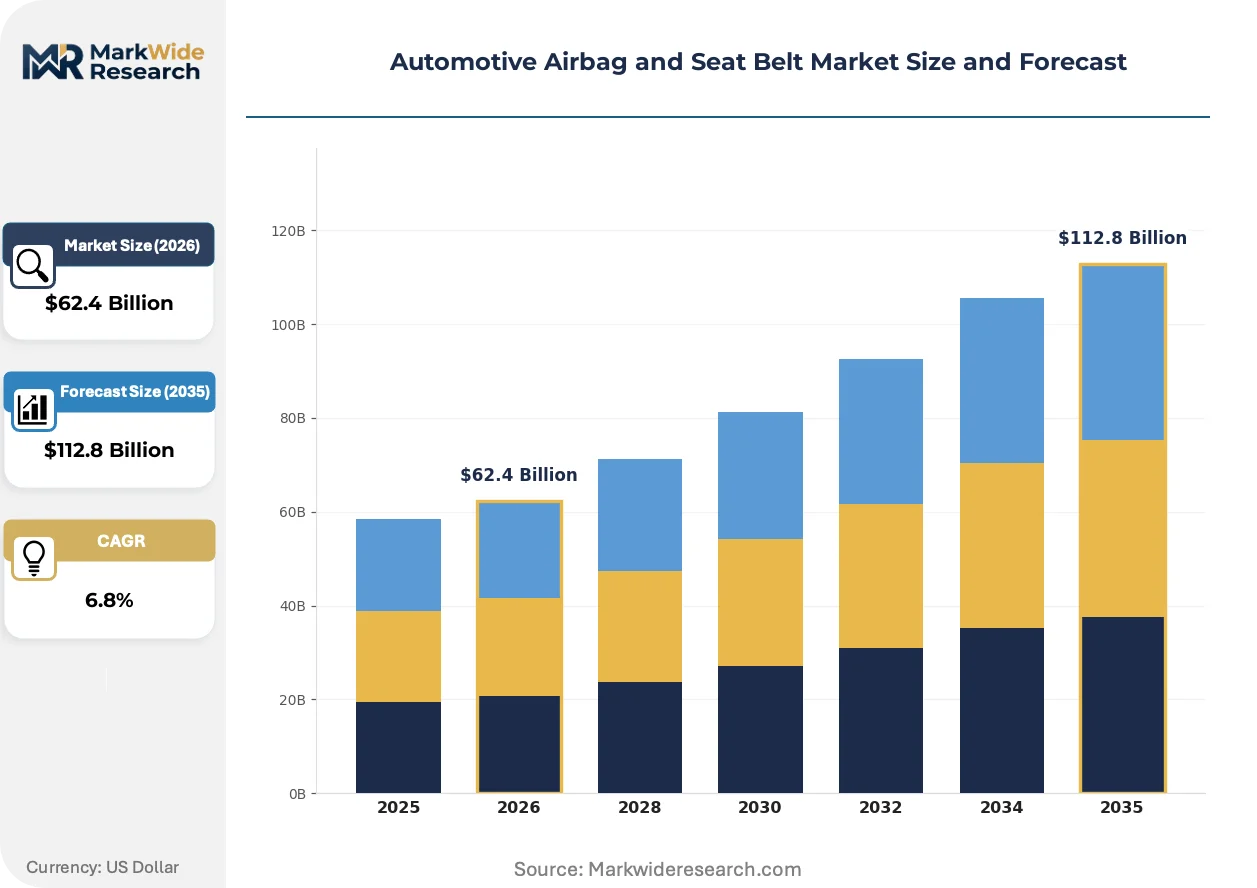
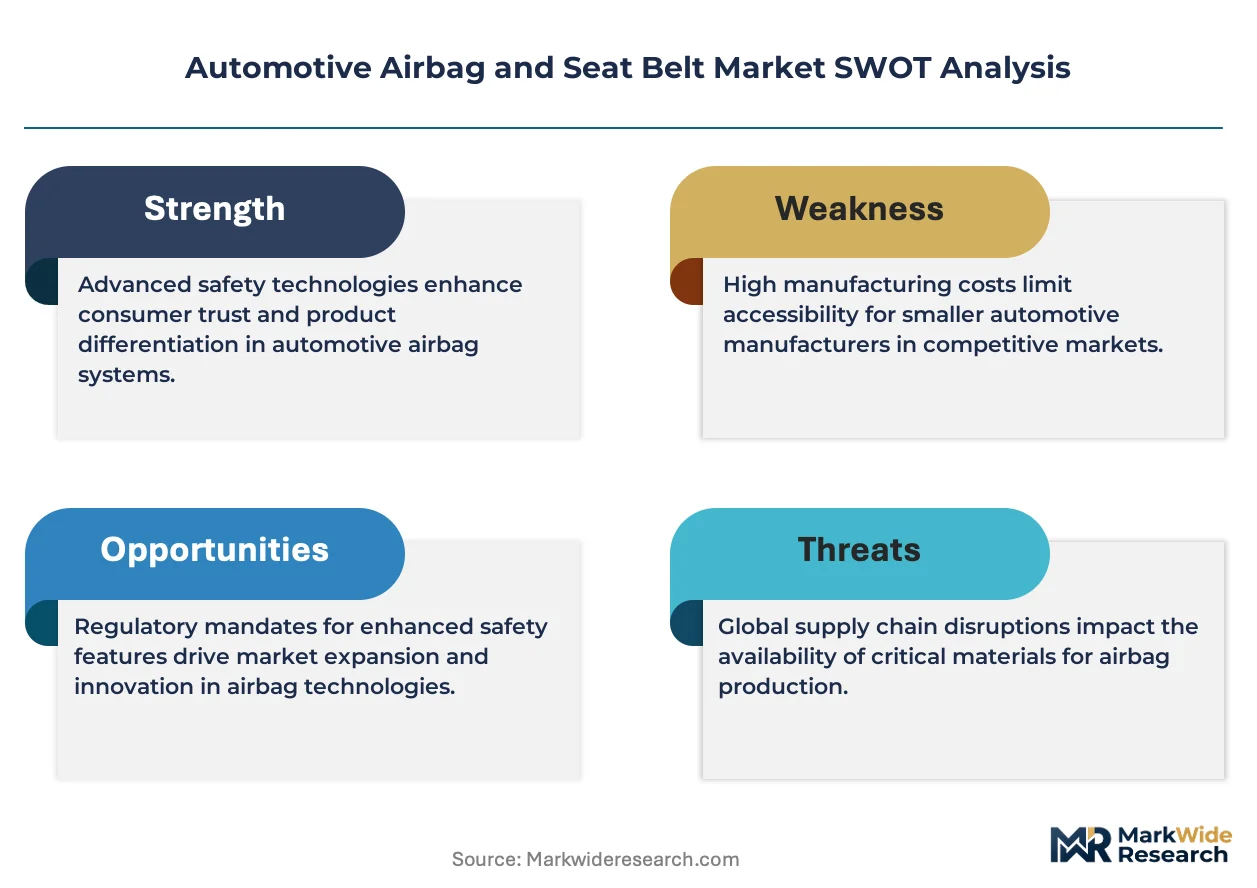
The market's structure is fundamentally shaped by a dual pressure from stringent regulatory mandates and the automotive industry's transition to electric vehicles. Safety standards from the US NHTSA and Europe's GSR are compelling continuous technological upgrades in passive safety systems.
Growth Catalysts
- Regulatory Mandates:Europe's General Safety Regulation (GSR) requires advanced safety features, including improved seat belts and intelligent speed assistance, directly stimulating demand for upgraded passive safety components in all new vehicles sold within the EU.
- Material Science Advances:The shift to high-strength, lightweight woven polyester fabrics from nylon for seat belt webbing enhances performance and durability, favoring suppliers with specialized textile engineering and production capabilities.
- Consumer Expectations in China:Heightened consumer awareness of vehicle safety ratings, amplified by government-backed C-NCAP testing protocols, is a primary demand driver for vehicles equipped with comprehensive airbag and pre-tensioner systems.
Market Restraints
- Input Cost Volatility:The price of essential raw materials, particularly the chemical precursors for pyrotechnic inflator propellants and the high-tenacity yarns for airbag fabrics, is subject to significant fluctuation, impacting component manufacturer margins.
- Supply Chain Concentration:A limited number of global suppliers dominate the production of pyrotechnic inflators, creating a supply bottleneck risk that can impact automotive production schedules if disruptions occur.
- Technical Validation Complexity:The extensive and costly testing required to validate adaptive restraint systems for diverse occupant sizes and seating positions under new crash protocols can delay the introduction of new safety technologies.
Strategic Opportunities
- Emerging Market Penetration:There is a significant opportunity to introduce more advanced systems, such as side-impact and far-side airbags, into mid-range vehicle segments in markets like India and Brazil, where safety regulations are strengthening.
- Sensor Fusion for Adaptive Safety:Integrating biometric sensors and interior cabin monitoring cameras with restraint control modules enables the development of truly adaptive systems that adjust deployment characteristics based on real-time occupant status.
- Autonomous Vehicle Systems:The development of novel restraint solutions for non-traditional seating arrangements in future autonomous vehicles, such as rear-facing or campfire-style layouts, presents a major white-space opportunity for innovation.
Industry Challenges
- Inflator Chemistry Certification:Navigating the long and complex certification pathways for new, more stable, and environmentally friendlier pyrotechnic inflator compounds is a significant operational hurdle for component suppliers.
- System Integration with Vehicle Architectures:Ensuring seamless and fault-free integration of advanced sensor-driven restraint systems with increasingly complex vehicle electronic architectures poses a considerable engineering challenge for OEMs and Tier-1 suppliers.
- Specialized Engineering Talent:A scarcity of engineers with cross-disciplinary expertise in pyrotechnics, material science, and sensor fusion algorithms constrains the pace of research and development for next-generation safety systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Airbag and Seat Belt Market |
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Airbags, Seat Belts, Pre-tensioners, Load Limiters Technology: Inflatable, Pyrotechnic, Mechanical, Electronic End User: OEMs, Aftermarket Suppliers, Automotive Manufacturers, Vehicle Assemblers Installation Type: Factory Installed, Retrofitted, Custom Installed, Standard Installed |
| Companies Covered | DENSO Corporation, Joyson Safety Systems, Autoliv Inc., Tokai Rika Co. Ltd., Toyoda Gosei Co. Ltd., ZF Friedrichshafen AG, Hyundai Mobis Co. Ltd., Robert Bosch GmbH, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Airbag and Seat Belt Market Strategic Shifts & Innovations
The evolution of passive safety is defined by the integration of digital controls and advanced sensor inputs, moving the market from static protection to dynamic, adaptive restraint systems. This shift is particularly pronounced in the electric vehicle segment, where new cabin designs and battery layouts necessitate novel safety solutions.
Adaptive restraint technology uses an array of sensors to detect occupant size, weight, and position before a crash. Automotive OEMs are increasingly specifying these systems for new global platforms, particularly in premium segments and electric vehicles. This technology is absorbing the functions of older, single-stage inflator systems and purely mechanical pre-tensioners, elevating the importance of software and calibration in system performance.
New rules under the US National Highway Traffic Safety Administration's (NHTSA) New Car Assessment Program (NCAP) are introducing more challenging crash test scenarios, such as the oblique frontal crash test. This regulatory action is forcing a redesign of frontal airbag systems to provide better protection for occupants in a wider range of collision types. The curtain and side airbag segments are receiving the most R&D focus to meet these enhanced performance criteria.
Automaker procurement behavior is consolidating around integrated safety modules rather than individual components. This model disrupts the business of smaller, specialized manufacturers of items like airbag cushions or seat belt webbing, favoring large Tier-1 suppliers who can deliver a complete, pre-validated system. This trend is most visible in vehicle platforms developed by German and Japanese OEMs seeking to streamline their global supply chains.
Automotive Airbag and Seat Belt Market Segmentation
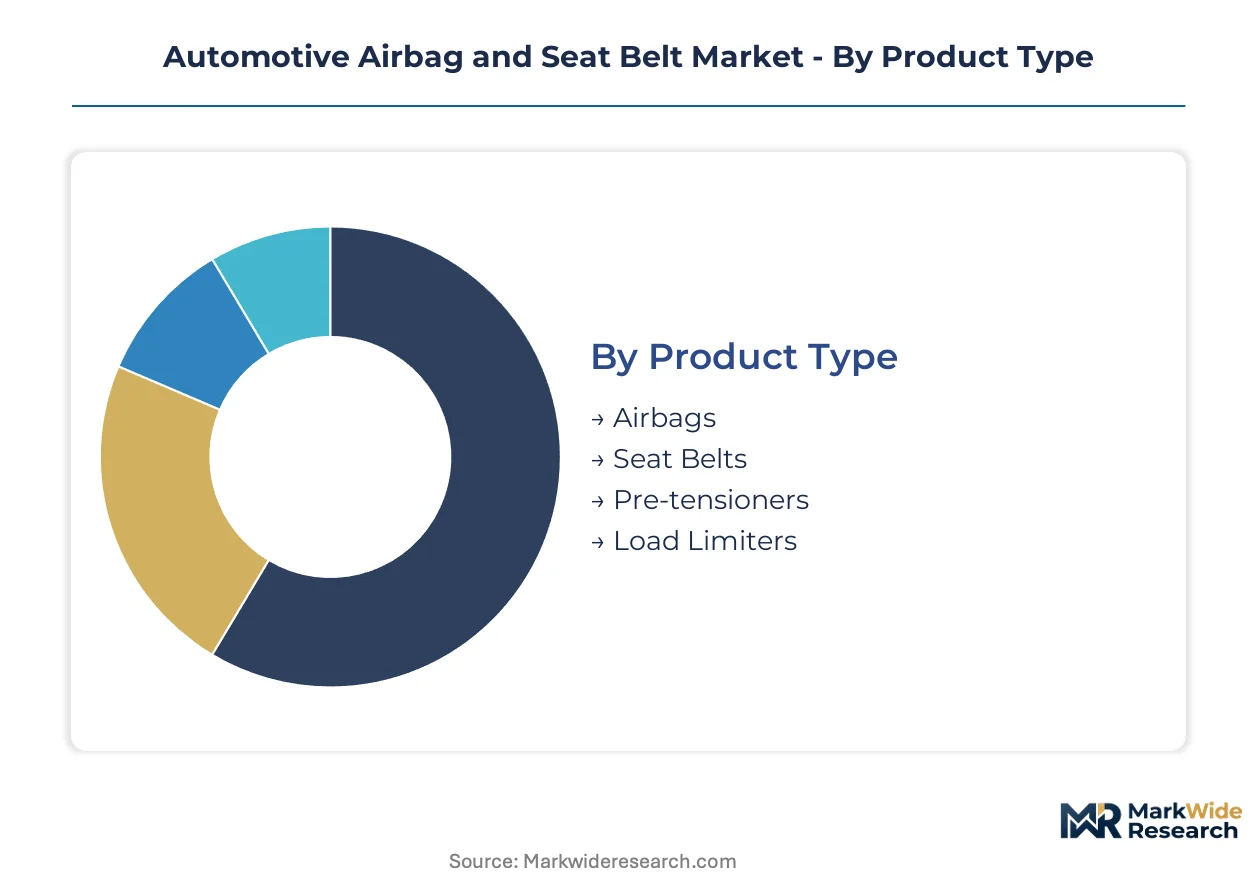
The Automotive Airbag and Seat Belt Market is categorized by critical components and their deployment mechanisms, reflecting the diverse safety requirements across vehicle types. Understanding these distinct segments is essential for tracking technological progress and regulatory compliance within the passive safety ecosystem. Each category highlights specific areas of innovation and market concentration.
Product Type:
The product segmentation delineates between high-volume foundational components and more specialized premium safety enhancements that drive performance differentiation.
- Airbags:These deployable fabric cushions, typically made of nylon or polyester, inflate rapidly with gas from a pyrotechnic inflator to protect occupants during impacts. Demand is concentrating in new vehicle platforms, particularly in China and the European Union, driven by enhanced crash test protocols and consumer safety expectations.
- Seat Belts:Comprising webbing, buckles, and retractors, seat belts restrain occupants and are the primary passive safety device. The shift to high-strength, lightweight woven polyester for webbing is critical, with demand across all vehicle segments globally due to universal safety mandates and continuous material science advancements.
- Pre-tensioners:Devices integrated into seat belt systems that remove slack from the webbing milliseconds before a collision, securing the occupant more firmly.
- Load Limiters:Components designed to reduce the force exerted by the seat belt on an occupant's chest during a severe impact, mitigating injury risk.
Mature deployment sits with Seat Belts, providing fundamental occupant restraint. Newer deployment is concentrated in Pre-tensioners, which enhance the effectiveness of the primary restraint system.
Technology:
This category outlines the maturity and complexity of the underlying mechanisms driving passive safety systems, from established mechanical solutions to advanced electronic controls.
- Electronic:These systems utilize sensors and control modules to precisely manage airbag deployment and seat belt pre-tensioning based on crash severity and occupant characteristics. Their adoption is expanding rapidly within electric vehicles and premium segments, driven by requirements for adaptive restraint systems and sophisticated sensor fusion.
- Pyrotechnic:Utilizing controlled explosive charges, pyrotechnic technology rapidly generates gas to inflate airbags and activate seat belt pre-tensioners. This core technology remains crucial for instantaneous deployment, with suppliers facing challenges in certifying new, environmentally friendlier chemical compounds.
- Inflatable:Refers to the physical airbag cushions themselves, which are designed to inflate upon impact to create a protective barrier for vehicle occupants.
- Mechanical:Traditional seat belt retractors and basic buckle mechanisms that operate without electronic or pyrotechnic assistance.
Electronic technologies are expanding most quickly, enabling adaptive and more intelligent safety responses. Mechanical systems represent the foundational, long-established methods.
End User:
The end-user segmentation reflects the primary purchasers and integrators of automotive airbag and seat belt systems, highlighting distinct procurement behaviors and supply chain relationships.
- OEMs:Original Equipment Manufacturers integrate passive safety systems directly into new vehicles during the assembly process. Their procurement behavior is consolidating around integrated safety modules from large Tier-1 suppliers, particularly for global vehicle platforms.
- Aftermarket Suppliers:These companies provide replacement or upgrade safety components to the repair and maintenance sector after a vehicle's initial sale. Demand in this segment is driven by collision repairs and the need for certified replacement parts.
- Automotive Manufacturers:These entities design and produce complete vehicles, integrating systems from various suppliers. They demand seamless integration and high reliability for complex electronic architectures.
- Vehicle Assemblers:Companies primarily focused on the final assembly of vehicles, often relying on pre-validated safety modules from Tier-1 suppliers.
OEMs dominate procurement for initial vehicle fitment, defining system specifications. Aftermarket Suppliers cater to the ongoing maintenance and repair needs of the existing vehicle fleet.
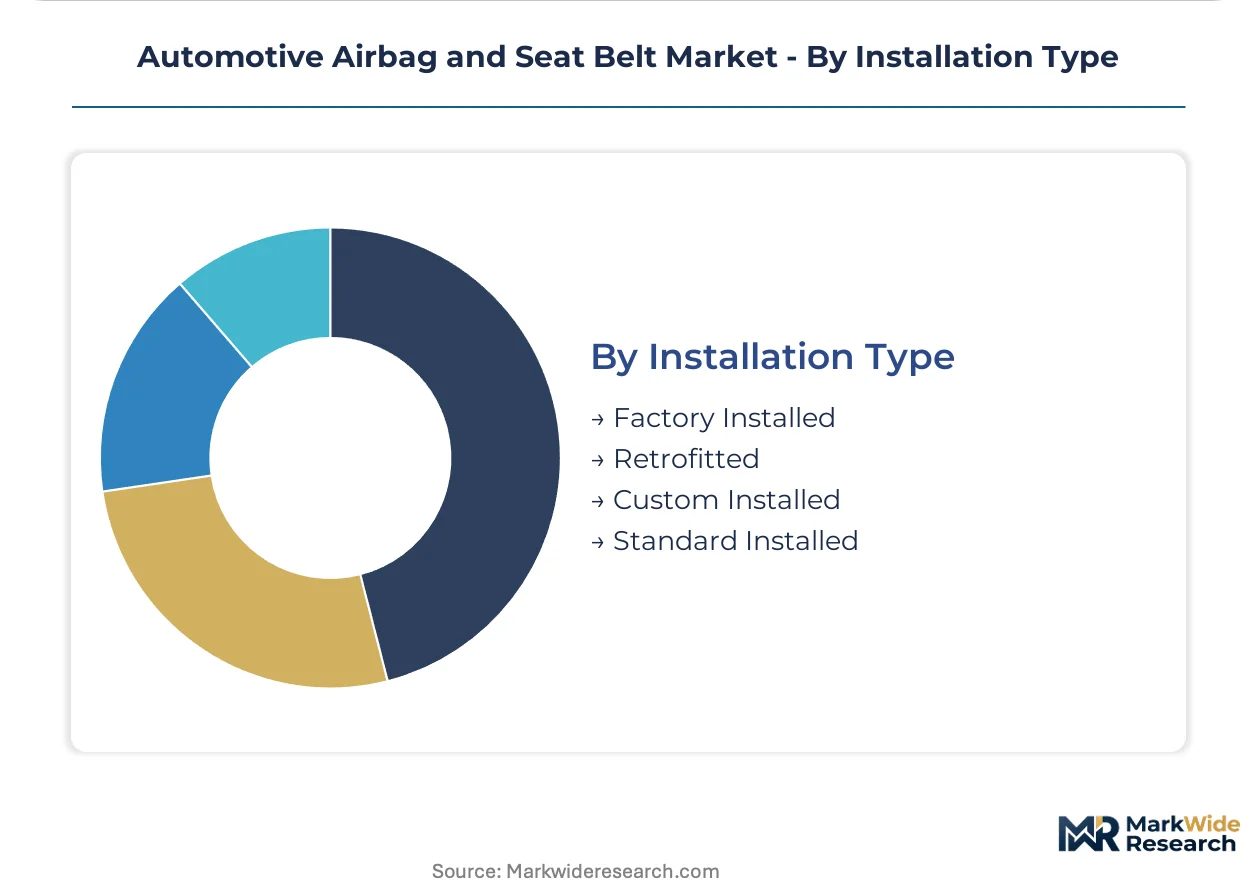
Installation Type:
This category differentiates how safety systems are incorporated into vehicles, influencing product design, regulatory compliance, and market opportunities.
- Factory Installed:Safety systems are integrated as standard equipment during the vehicle manufacturing process, ensuring optimal performance and compliance with initial safety certifications. This type of installation holds the largest volume share in new vehicle production.
- Retrofitted:Installation of safety systems into vehicles after their initial manufacture, typically for older models or specialized applications. This segment presents opportunities in emerging markets where older vehicles are upgraded.
- Custom Installed:Specialized safety system installations tailored for unique vehicle modifications or specific occupant needs, often found in niche or commercial vehicle segments.
- Standard Installed:Refers to safety features that come as part of a basic vehicle package, meeting minimum regulatory requirements without advanced features.
Factory Installed systems hold the largest volume share, ensuring initial vehicle safety. Retrofitted installations address specific post-production needs or upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's vast automotive manufacturing zones, particularly in the Yangtze River Delta, are concentrating significant investment in automotive safety systems. These zones benefit from government incentives and a large domestic market. This concentration drives both localized production and technology adoption for airbags and seat belts.
China
Consumer expectations for vehicle safety ratings, coupled with rapid electric vehicle adoption, drive demand for advanced airbag and seat belt systems. China's C-NCAP testing protocols compel manufacturers to continuously upgrade safety features. Automotive manufacturing clusters in Shanghai and Guangzhou are actively developing and integrating next-generation passive safety solutions.
Germany
German automotive OEMs prioritize high-performance safety systems for their premium and luxury vehicle segments. Europe's General Safety Regulation (GSR) mandates advanced features, including improved seat belts and intelligent speed assistance. The automotive engineering hub in Stuttgart focuses on integrating sophisticated sensor-based adaptive restraint systems.
United States
Demand for advanced safety features in SUVs and light trucks propels the adoption of multi-stage airbags and pre-tensioners. The US National Highway Traffic Safety Administration (NHTSA) continually updates crash test standards, forcing innovation. Detroit's automotive corridor sees significant investment in designing and testing new occupant protection technologies.
India
India's vehicle market exhibits increasing demand for passive safety features, especially in mid-range and compact segments. The Bharat New Vehicle Safety Assessment Program (BNVSAP) aims to elevate safety standards across all new vehicles. Automotive production hubs in Chennai and Pune are expanding local manufacturing capabilities for seat belts and airbags.
Japan
Japanese automakers integrate advanced passive safety solutions into their global vehicle platforms, emphasizing reliability and compact design. Japan's robust safety regulations and consumer focus on quality drive continuous product refinement. The Toyota City region remains a center for research and development in innovative airbag deployment mechanisms.
Automotive Airbag and Seat Belt Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the automotive airbag and seat belt market. This market exhibits a consolidated structure at the Tier-1 supplier level, where a few global players dominate system integration and supply to OEMs. Strategic archetypes include large diversified automotive suppliers offering comprehensive safety solutions, specialized safety system providers focused on restraint technologies, and niche component manufacturers. These companies primarily engage in portfolio diversification and strategic partnerships to enhance their market reach and technological capabilities.
Specialists in integrated safety solutions include Joyson Safety Systems, which provides comprehensive systems for global automotive platforms. Autoliv Inc. exemplifies a major supplier with significant manufacturing scale in pyrotechnic inflators and airbag cushions. ZF Friedrichshafen AG occupies a position as a diversified automotive technology company, offering a broad portfolio that encompasses passive safety systems. These entities represent the deep engineering expertise and manufacturing capabilities required to meet stringent automotive safety standards. Their global presence allows them to serve multiple OEM clients across different continents.
| Leading Market Players |
|---|
| DENSO Corporation |
| Joyson Safety Systems |
| Autoliv Inc. |
| Tokai Rika Co. Ltd. |
| Toyoda Gosei Co. Ltd. |
| ZF Friedrichshafen AG |
| Hyundai Mobis Co. Ltd. |
| Robert Bosch GmbH |
| Continental AG |
| Others |
Cost & Logistics Intelligence
OEM procurement behavior for advanced safety modules drives a contract-based pricing model in the automotive airbag and seat belt market. This concentration allows large Tier-1 suppliers to negotiate long-term agreements with vehicle manufacturers.
Pricing Analysis
Premium pricing for short lead times reflects urgent OEM demand for specific adaptive restraint systems. The dominant pricing model involves contract-based long-term offtake agreements with vehicle manufacturers. Price differentiation stems from quality grade, particularly certification levels required by US NHTSA or Europe's GSR, and the volume scale of orders. Pricing pressure intensifies from OEMs seeking to reduce per-unit costs for mid-range vehicle segments. While OEMs are highly price-sensitive for mass-market vehicles, they exhibit less sensitivity for premium and luxury models integrating advanced safety features.
Supply Chain Analysis
Single-source vulnerability sits with specialized manufacturers of pyrotechnic inflators, creating potential production bottlenecks. The supply chain draws heavily from China, Germany, and Japan for key components. Dependencies include chemical precursors for inflator propellants and high-tenacity yarns for airbag fabrics. Commodity price volatility for these raw materials presents a significant supply chain risk. The dominant distribution model is direct-to-OEM, with Tier-1 suppliers delivering integrated safety modules directly to vehicle assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive airbag and seat belt market is undergoing a technology transition phase. Adaptive restraint systems are rapidly displacing older mechanical and single-stage inflator technologies.
For Market Incumbents:Deepen material science capabilities for high-strength woven polyester webbing to meet evolving safety standards. Incumbents must also expand software development expertise for adaptive restraint systems, addressing the increasing complexity from stricter regulatory mandates like Europe's GSR. Invest in certification for new, environmentally friendlier inflator chemistries to mitigate future compliance risks. Consolidate production through strategic acquisitions of specialized component manufacturers with unique technological advantages.
For New Entrants and Emerging Players:Price-point gaps between premium and economy tiers offer opportunities for specialized component manufacturers. Focus on introducing advanced safety features like side-impact and far-side airbags into mid-range vehicle segments in markets such as India and Brazil. Develop novel restraint solutions for non-traditional seating arrangements in future autonomous vehicles, representing a significant white-space opportunity. A viable go-to-market angle involves partnering with local OEMs for localized production and technology integration.
For Investors and Strategic Acquirers:The window for entry favors strategic acquirers seeking advanced sensor and material science expertise. Long-term viability over a 5-10 year window depends on securing intellectual property in adaptive restraint systems. Target acquisition archetypes include specialized component manufacturers with strong R&D in sensor fusion or novel textile materials. A key signal to watch is OEM investment in fully autonomous vehicle platforms, indicating a shift towards new cabin safety requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Material Science | Enhances performance and durability of seat belt webbing, meeting stringent regulatory requirements. |
| Expand Software Development for Adaptive Systems | Enables precise control of airbag deployment and seat belt pre-tensioning based on real-time occupant data. |
| Certify New Inflator Chemistries | Addresses environmental concerns and regulatory mandates for more stable and eco-friendly pyrotechnic compounds. |
| Develop Novel Autonomous Vehicle Restraints | Captures future market share by innovating safety solutions for non-traditional seating configurations. |
| Form Strategic OEM Partnerships | Secures long-term supply contracts and facilitates integration of advanced safety modules into new vehicle platforms. |
Research Approach
Independent corroboration across OEM platform engineers, Tier-1 supplier R&D leads, and automotive safety regulators underwrites the qualitative findings. Primary interviews with these industry stakeholders provided critical insights into market dynamics and technological advancements. Secondary validation involved comprehensive reviews of vehicle production databases, C-NCAP test results, automotive industry association reports, and patent filings for safety systems. Both bottom-up and top-down triangulation methods were applied to ensure data accuracy.
Comparable historical periods anchored the forecast window, informing projections across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, end user, installation type, vehicle class, and propulsion architecture (EV vs ICE). Compound Annual Growth Rates (CAGRs) were derived using a robust statistical approach, considering factors like projected vehicle production volumes by region and regulatory enforcement schedules as key forecast inputs.
Inputs from vehicle production data and regulatory mandates were available through the study window; gaps in detailed OEM procurement forecasts introduce uncertainty bands. Forecasts reflect assumptions regarding technological adoption rates and market acceptance. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Europe Automotive Night Vision System Market
Automotive Safety and Security Systems
Pedestrian Protection System Market
Automotive Safety and Security Systems
Emergency Vehicle Lights Market
Automotive Safety and Security Systems
Acoustic Vehicle Alerting System Market
Automotive Safety and Security Systems
Automotive Anti-Roll Bar Market
Automotive Safety and Security Systems
Automotive Inspection Tunnels Market
Automotive Safety and Security Systems
Wearable Motorcycle Airbags Market
Automotive Safety and Security Systems
Lane Change Assist Systems Market
Automotive Safety and Security Systems
Automotive Biometric Access System Market
Automotive Safety and Security Systems
AI in-Vehicle Surveillance Market
Automotive Safety and Security Systems
Automotive Radar Applications Market
Automotive Safety and Security Systems
Europe Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Driver Drowsiness Monitoring System Market
Automotive Safety and Security Systems
Europe Pedestrian Detection Systems Market
Automotive Safety and Security Systems
Automotive ABS and ESC Market
Automotive Safety and Security Systems
Seat Belt Pretensioner and Load Limiter Market