
 Automotive Corner Sonar Market | 2026-2036
Automotive Corner Sonar Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Corner Sonar Market Analysis
Fleet operators and commercial vehicle buyers are gaining procurement share as the demand rotation between buyer archetypes is bifurcating between premium passenger OEMs and cost-sensitive fleet channels. Robert Bosch GmbH leverages its integrated manufacturing scale to dominate European OEM supply chains. Continental AG anchors its position through deep R&D intensity in ultrasonic signal processing. Valeo SA competes aggressively on cross-continental channel control, sustaining aftermarket penetration across multiple vehicle classes.
Automotive corner sonar encompasses short-range proximity detection devices, typically operating at ultrasonic frequencies between 40 kHz and 58 kHz, mounted at vehicle corners to enable parking assistance and low-speed collision avoidance. These sensors emit acoustic pulses, measure echo return times, and communicate distance data to central vehicle controllers for driver alerts or automated braking interventions. Rear corner sensors lead installation volumes due to universal fitment across vehicle segments, while blind spot detection commands premium positioning through higher computational integration. Ultrasonic technology occupies the dominant cost tier, though radar-based systems are extending into mid-range trims as sensor fusion architectures standardize.
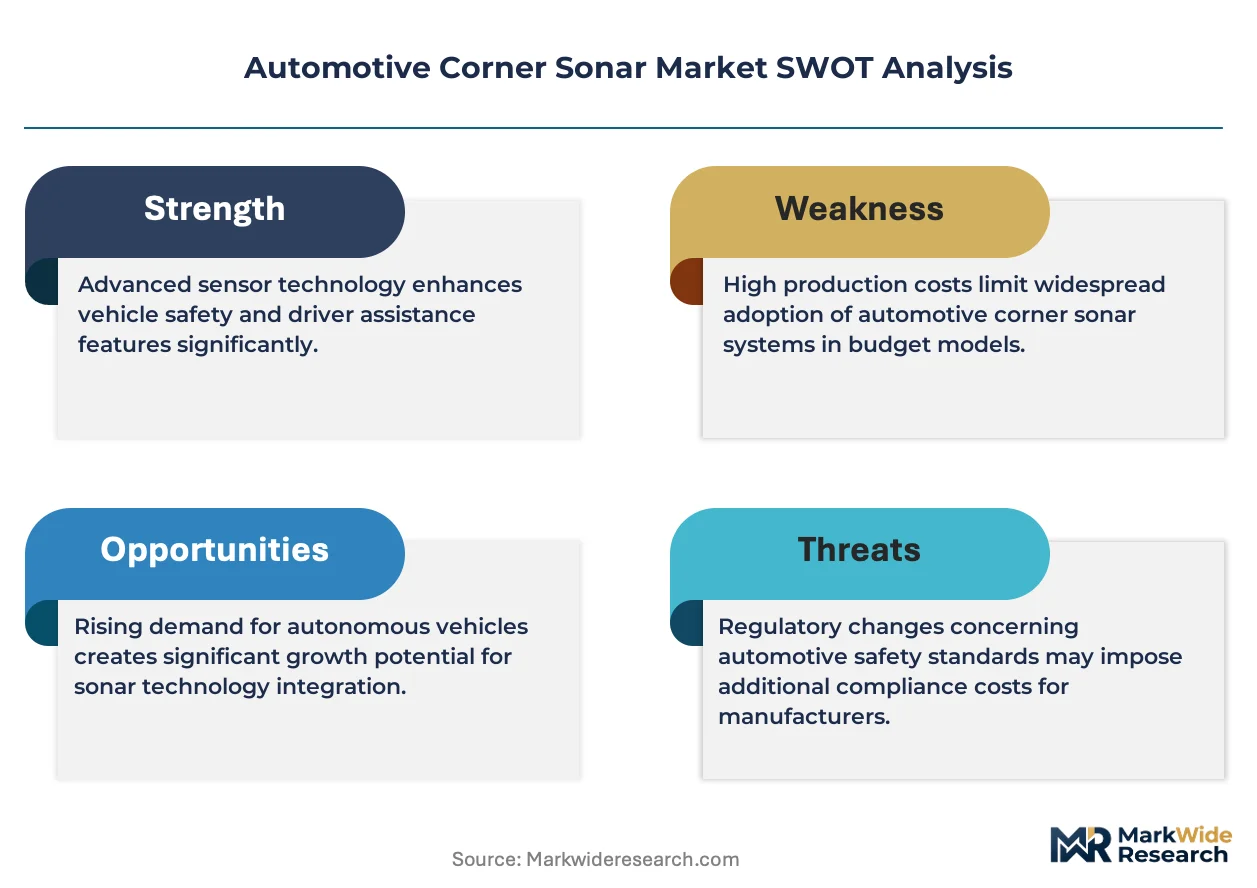
The European Union's General Safety Regulation and the U.S. NHTSA pedestrian safety mandates shape product standards by requiring rear visibility and automatic emergency braking on new vehicles, directly expanding addressable sensor volumes. Japan's METI vehicle safety guidelines and ISO 17386 parking aid standards further codify performance thresholds that OEMs must meet for market access. Stakeholders must monitor how Lidar and camera-based systems displace or complement ultrasonic architectures in next-generation platform designs.
Market Dynamics
Sensor fusion architectures are compressing the standalone ultrasonic sensor value pool as OEMs integrate corner sonar into unified perception stacks alongside radar and camera modules.
Growth Catalysts
- EU General Safety Regulation:Mandates advanced driver-assistance features on new vehicle types, forcing OEMs to quadruple corner sensor fitment rates across passenger and commercial lines.
- Commercial fleet retrofit programs:Logistics operators in Germany and Japan are installing aftermarket parking assistance systems to reduce yard accidents and insurance liabilities.
- Ultrasonic-to-radar migration:Mid-range vehicle trims now specify 77 GHz radar-based corner detection, expanding the addressable hardware market beyond traditional acoustic tiers.
Market Restraints
- Raw material concentration:Piezoelectric ceramic supply chains cluster in Chinese manufacturing zones, exposing tier-one suppliers to input volatility and export control friction.
- Sensor fusion redundancy:Lidar and camera-based perception systems achieve 360-degree coverage without dedicated corner hardware, threatening ultrasonic unit volumes in premium platforms.
- Homologation fragmentation:Divergent UN ECE, NHTSA, and METI testing protocols force sensor manufacturers to maintain three parallel certification tracks, inflating development overhead.
Strategic Opportunities
- India PLI scheme for auto components:Localized sensor manufacturing incentives attract Bosch, Continental, and Valeo to establish captive production for domestic OEMs and export markets.
- Autonomous last-mile delivery:Robotic shuttle operators specify redundant corner detection arrays, creating a new demand vertical outside traditional passenger vehicle procurement.
- Software-defined sensor calibration:Over-the-air tuning of detection thresholds and false-positive filtering enables recurring revenue models from hardware previously sold as one-time components.
Industry Challenges
- Signal processing talent scarcity:OEMs and tier-ones compete for acoustic engineers capable of optimizing beam patterns in multi-sensor interference environments.
- Legacy vehicle integration:Retrofit installations on pre-CAN-bus architectures require analog-to-digital bridge modules, complicating aftermarket product lines and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Corner Sonar Market |
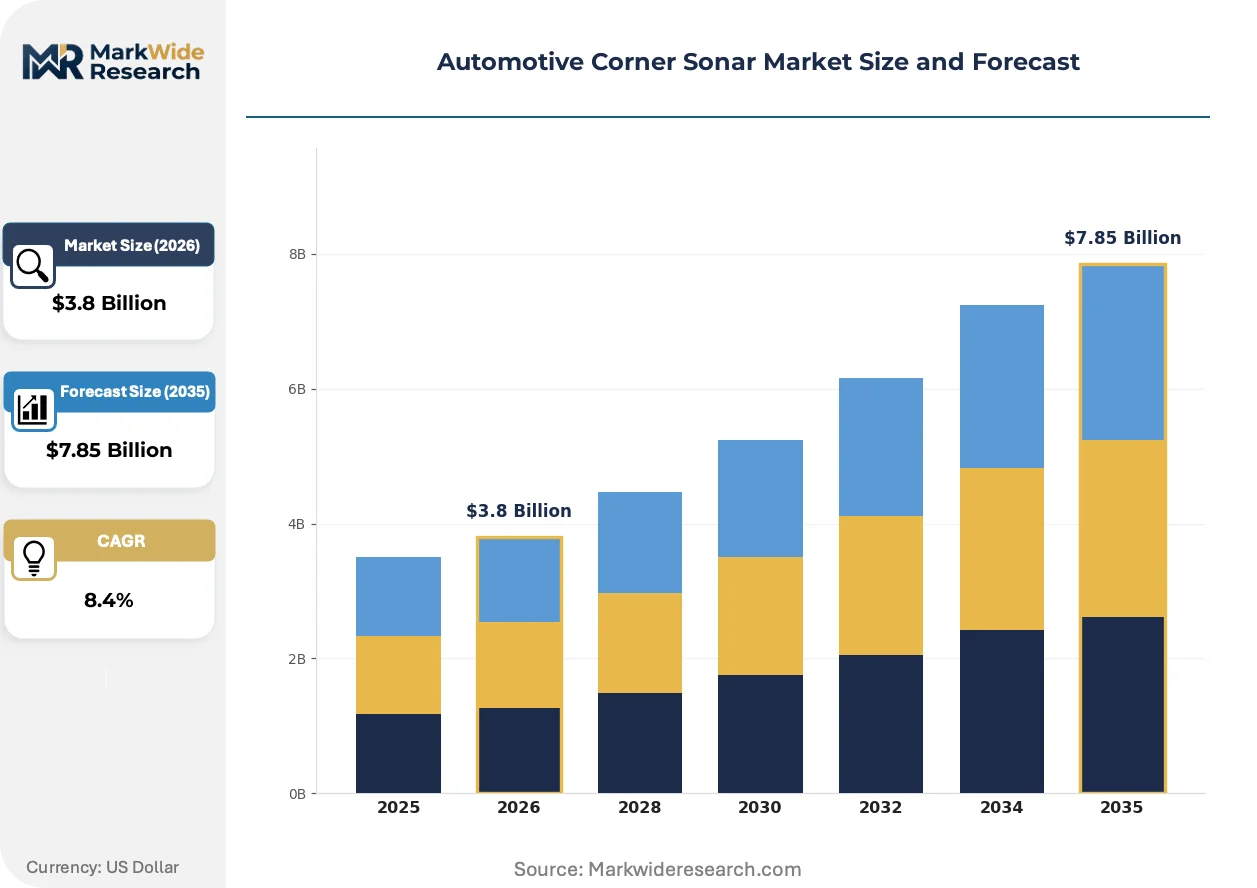
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Corner Sensors, Rear Corner Sensors, Blind Spot Detection, Cross Traffic Alert End User: Passenger Vehicles, Commercial Vehicles, Fleet Operators, OEMs Technology: Ultrasonic, Radar, Lidar, Camera-Based Systems Installation Type: Original Equipment Manufacturer, Aftermarket, Integrated Systems, Standalone Units |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Continental AG, Valeo SA, Aptiv PLC, Aisin Seiki, Magna International Inc., Autoliv Inc., ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Corner Sonar Market Emerging Trajectories
Acoustic sensing architectures are yielding computational priority to multi-modal fusion stacks, compressing the standalone ultrasonic component value chain while elevating software integration margins.
Digital signal processing with machine-learned echo classification is supplanting analog threshold detection in corner sonar modules. Tier-one suppliers in Germany and Japan are shipping programmable ultrasonic controllers to OEMs by late 2024. This transition is compressing hardware differentiation while expanding firmware licensing revenue pools.
Japan's METI vehicle safety guidelines now explicitly reference parking aid performance thresholds that exceed ISO 17386 baseline requirements. Domestic OEMs Toyota and Honda are accelerating sensor specification upgrades to preempt regulatory non-compliance. The premium crossover segment shows fastest response, with 2025 model year platforms adopting dual-frequency ultrasonic arrays.
Fleet procurement departments now specify total cost of ownership metrics including sensor calibration intervals and replacement part availability, displacing traditional upfront unit cost negotiations. Large commercial vehicle lessors in the United States are consolidating supplier relationships to three-year framework agreements with embedded service provisions. This concentration is most visible in Class 8 truck specifications, where corner detection has shifted from optional to standard fitment within eighteen months.
Automotive Corner Sonar Market Segmentation
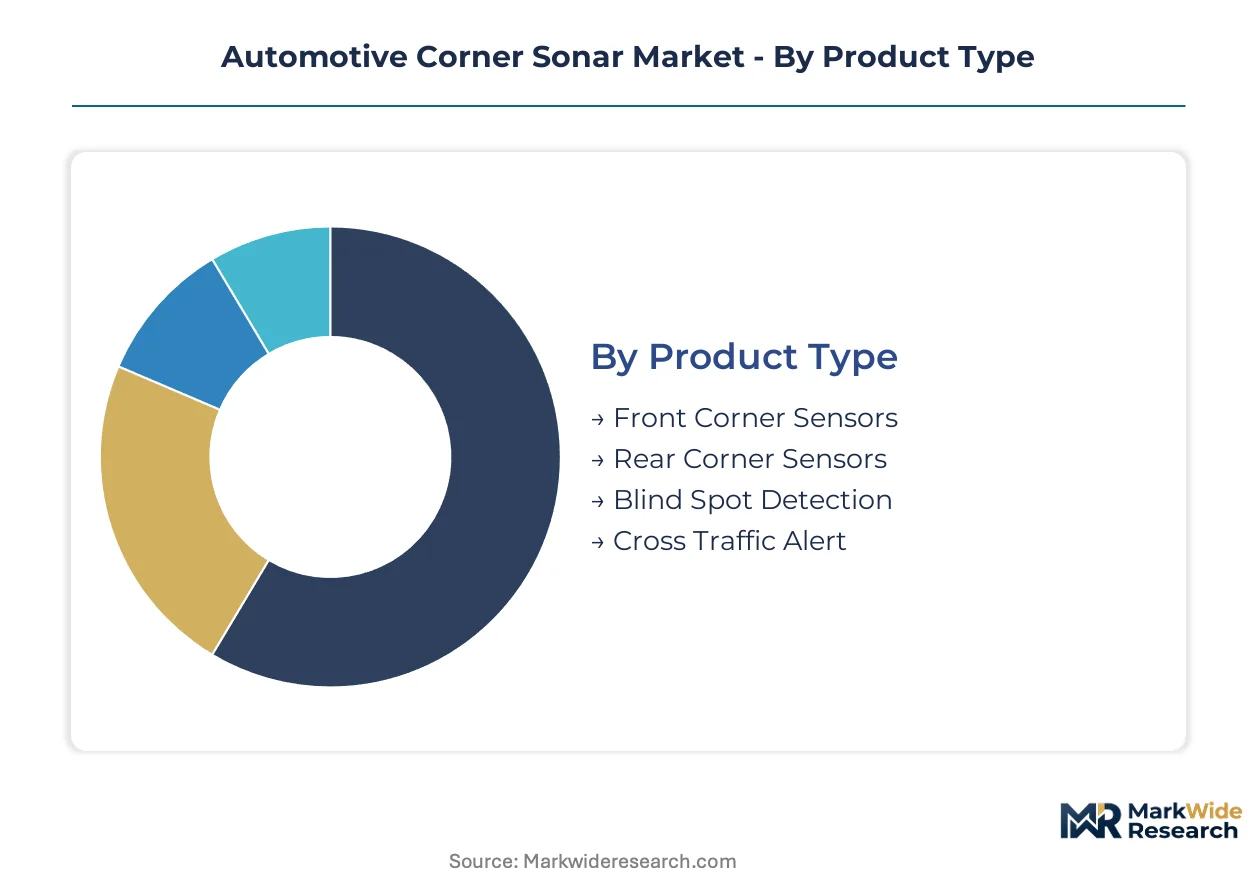
Segmentation in automotive corner sonar reveals distinct procurement channels and technology tiers that reshape supplier strategies. Understanding how sensor types, customer archetypes, and installation modes partition the market exposes where margin pools concentrate and where volume expansion accelerates.
Product Type:
Front corner sensors flow primarily through premium OEM channels with bundled ADAS packages, while rear corner units penetrate mass-market trims through standardized factory fitment. Blind spot detection commands aftermarket premium pricing in retrofit programs.
- Rear Corner Sensors:These 40-58 kHz ultrasonic modules mount on bumper corners to detect obstacles during reverse maneuvers. Demand concentrates in Germany and Japan where OEMs mandate universal fitment across vehicle classes to comply with UN ECE pedestrian safety protocols. Fleet operators in the United States specify these for yard accident reduction.
- Blind Spot Detection:Higher-frequency arrays with wider beam patterns monitor adjacent lanes for vehicle presence. Expansion concentrates in premium crossovers from Toyota and Honda responding to METI guideline upgrades that exceed ISO 17386 baselines. Dual-frequency architectures are gaining specification in 2025 model year platforms.
- Front Corner Sensors:Short-range units for low-speed parking assistance in urban environments.
- Cross Traffic Alert:Rear-quarter radar or ultrasonic systems detecting perpendicular vehicle approaches.
Rear corner sensors dominate installed base. Blind spot detection is where expansion concentrates.
End User:
Cost tiers separate this category: passenger vehicle OEMs optimize per-unit economics at scale, while fleet operators prioritize total cost of ownership metrics including calibration intervals and parts availability.
- OEMs:Vehicle manufacturers specify sensor modules through multi-year supply agreements with embedded firmware licensing. Procurement in Germany, Japan, and the United States drives volume concentration, with tier-one suppliers maintaining captive manufacturing footprints near assembly plants. The EU General Safety Regulation forces quadrupled sensor fitment rates across passenger and commercial lines.
- Fleet Operators:Logistics lessors and commercial vehicle buyers in Germany and Japan install aftermarket parking assistance to reduce insurance liabilities and yard accidents. Large U.S. Class 8 truck lessors now consolidate supplier relationships into three-year framework agreements with embedded service provisions, displacing upfront unit cost negotiations.
- Passenger Vehicles:Private vehicle owners accessing sensors through factory fitment or dealer retrofit.
- Commercial Vehicles:Heavy-duty truck and van operators specifying corner detection for urban delivery safety.
OEMs dominate installed base. Fleet operators are climbing the fastest as procurement authority shifts toward total cost of ownership metrics.
Technology:
Application requirements dictate technology selection: parking assistance tolerates ultrasonic cost structures, while higher-speed scenarios demand radar precision.
- Ultrasonic:Dominant cost tier operating at 40-58 kHz with piezoelectric ceramic transducers. Supply chains cluster in Chinese manufacturing zones, exposing tier-one suppliers to input volatility. Robert Bosch GmbH and Continental AG leverage integrated scale to defend European OEM supply positions.
- Radar:77 GHz corner detection systems extending into mid-range vehicle trims as sensor fusion architectures standardize. This migration expands addressable hardware market beyond traditional acoustic tiers, with Japan and Germany OEMs leading specification shifts.
- Lidar:Emerging in premium autonomous platforms where 360-degree perception redundancy is required.
- Camera-Based Systems:Computer vision alternatives achieving parking assistance without dedicated acoustic hardware.
Ultrasonic dominates installed base. Radar is where expansion concentrates as mid-range trims upgrade from acoustic-only architectures.
Installation Type:
Customer type shapes installation mode: OEMs demand integrated systems with centralized processing, while independent repair channels favor standalone units with simplified calibration.
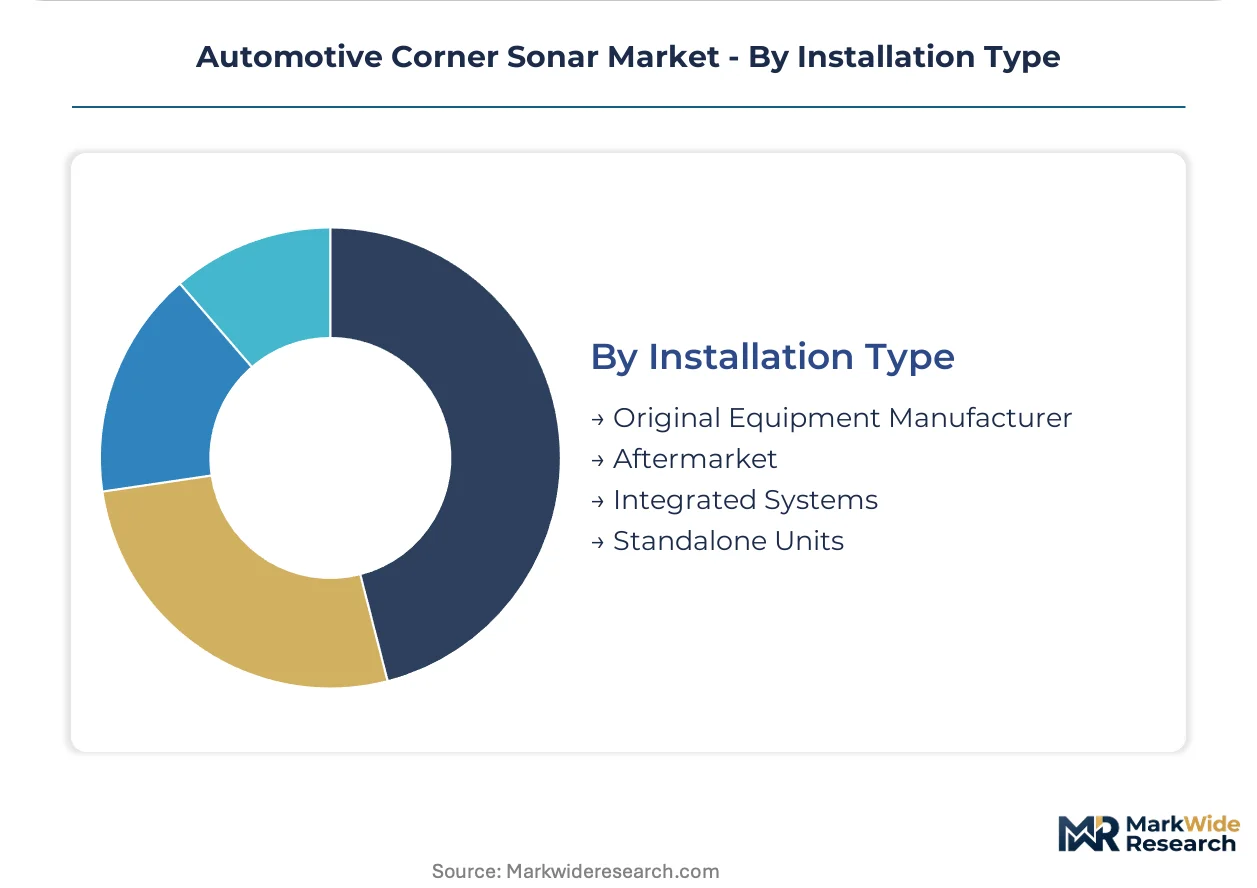
- Original Equipment Manufacturer:Factory-integrated sensors communicating through vehicle CAN bus to central controllers. NHTSA pedestrian safety mandates and EU General Safety Regulation directly expand addressable volumes by requiring rear visibility and automatic emergency braking fitment.
- Aftermarket:Retrofit installations on pre-CAN-bus architectures require analog-to-digital bridge modules, complicating product lines and warranty exposure. Demand concentrates in Germany and Japan where fleet retrofit programs accelerate.
- Integrated Systems:Multi-sensor fusion stacks combining corner sonar with radar and camera modules.
- Standalone Units:Self-contained sensors with local processing for legacy vehicle compatibility.
OEM installation dominates installed base. Aftermarket is where expansion concentrates as fleet retrofit programs accelerate across logistics operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and passenger OEMs concentrate procurement authority in Germany, Japan, and the United States, where tier-one suppliers maintain dense manufacturing footprints and direct vehicle assembly relationships.
Germany
Robert Bosch GmbH and Continental AG anchor European OEM supply chains through integrated manufacturing scale. The EU General Safety Regulation mandates advanced driver-assistance features, forcing quadrupled corner sensor fitment rates across passenger and commercial vehicle lines. Bavaria and Baden-Württemberg host dense supplier clusters where ultrasonic signal processing R&D intensifies.
Japan
Toyota and Honda accelerate sensor specification upgrades to preempt METI vehicle safety guideline requirements that exceed ISO 17386 baselines. The 2025 model year platforms adopt dual-frequency ultrasonic arrays fastest in the premium crossover segment. Kanto and Kansai industrial corridors concentrate Denso Corporation and Aisin Seiki production capacity.
United States
Large Class 8 truck lessors consolidate supplier relationships into three-year framework agreements with embedded service provisions, displacing upfront unit cost negotiations. NHTSA pedestrian safety mandates expand addressable sensor volumes by requiring rear visibility and automatic emergency braking fitment. Michigan and Ohio assembly corridors anchor Magna International and Aptiv PLC manufacturing presence.
China
Piezoelectric ceramic supply chains cluster in eastern manufacturing zones, exposing tier-one suppliers to input volatility and export control friction. Domestic OEMs source corner sonar modules for both factory fitment and aftermarket retrofit programs. Yangtze River Delta and Pearl River Delta production hubs concentrate component fabrication for export markets.
India
The PLI scheme for auto components attracts Bosch, Continental, and Valeo to establish captive production for domestic OEMs and export markets. Localized sensor manufacturing incentives reshape procurement patterns as fleet operators specify total cost of ownership metrics. Maharashtra and Tamil Nadu automotive corridors concentrate new supplier facility investments.
Automotive Corner Sonar Market Vendor Landscape
Player mix skews toward diversified automotive component conglomerates with captive electronics divisions and integrated manufacturing scale. Three structural tiers emerge: European integrated system suppliers with full-stack ADAS portfolios, Japanese precision component specialists with OEM captive relationships, and North American modular suppliers with flexible contract manufacturing. Dominant competitive moves include geographic expansion into India under PLI incentives and sensor fusion architecture partnerships that compress standalone ultrasonic value pools.
Within the European integrated tier, Robert Bosch GmbH, Continental AG, and Valeo SA represent the archetype of full-stack ADAS suppliers with dense manufacturing footprints near German assembly plants. Denso Corporation and Aisin Seiki exemplify Japanese precision component specialists maintaining deep OEM captive relationships. These five entities anchor the competitive structure through differentiated positions in ultrasonic signal processing, cross-continental channel control, and integrated manufacturing scale.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Continental AG |
| Valeo SA |
| Aptiv PLC |
| Aisin Seiki |
| Magna International Inc. |
| Autoliv Inc. |
| ZF Friedrichshafen AG |
| Others |
Supply Flow & Price Mechanics
Long-term framework agreements with embedded service provisions lock in both piezoelectric ceramic supply access and multi-year price visibility for tier-one suppliers serving German and Japanese OEMs. These contracts index raw material costs to regional ceramic price benchmarks while guaranteeing volume commitments across sensor generations.
Pricing Analysis
Cost-plus contracts with ceramic price indexation dominate procurement between tier-one suppliers and OEMs. Pricing stratifies across premium radar-based tiers, standard ultrasonic factory-fitment, and economy aftermarket retrofit levels. Cost compression in ultrasonic modules intensifies as Chinese ceramic suppliers expand capacity. Fleet operators exhibit highest price sensitivity through total cost of ownership negotiations, while premium passenger OEMs prioritize performance consistency over unit economics.
Supply Chain Analysis
Inventory buffers for piezoelectric ceramics stretch to sixteen weeks due to concentration in eastern Chinese manufacturing zones. Component fabrication draws from China, Germany, and Japan for transducer assembly. Single-source vulnerability in ceramic substrate supply creates exposure to export control friction. Distribution runs through captive tier-one logistics networks feeding OEM assembly plants in Bavaria, Kanto, and Michigan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined sensor calibration represents a service-attach opportunity expanding faster than hardware unit sales, with over-the-air tuning enabling recurring revenue from previously transactional components.
For Market Incumbents: Fortify backward integration into piezoelectric ceramic production to offset Chinese supply concentration risk. Deepen firmware licensing architectures to capture software-defined calibration revenue streams. Lidar displacement in premium platforms threatens ultrasonic volume positions. For New Entrants and Emerging Players: UN ECE certification fast-tracks open entry paths into European aftermarket fleet retrofit channels. Target German logistics operators with yard-accident reduction specifications. Pursue white-label manufacturing partnerships with established tier-two distributors lacking in-house signal processing capability. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers with embedded firmware licensing and over-the-air service architectures. Over the extended horizon, acquisition targets should demonstrate software attach rates exceeding hardware shipment growth. Watch for METI guideline enforcement acceleration as inflection signal for specification upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Architecture Partnership | Integrates corner sonar into unified perception stacks alongside radar modules for OEM platform standardization. |
| India PLI Manufacturing Localization | Captures production incentives in Maharashtra and Tamil Nadu corridors for domestic OEM supply and export markets. |
| Software-Defined Calibration Platform | Enables over-the-air threshold tuning and false-positive filtering through recurring firmware licensing revenue models. |
| Dual-Frequency Ultrasonic Array Development | Addresses METI guideline upgrades exceeding ISO 17386 baselines for Toyota and Honda platform specifications. |
| Fleet Retrofit Channel Consolidation | Secures three-year framework agreements with U.S. Class 8 truck lessors embedding service provisions. |
Methodological Framework
A spread of perspectives from OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and fleet operations managers converged on the working assumptions for sensor adoption timelines. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, UN ECE regulatory filings, and customs trade records. Bottom-up sensor shipment estimates triangulated against top-down ADAS content per vehicle projections.
Segmentation dimensions modeled span vehicle class, propulsion architecture, sensor technology tier, OEM procurement channel, and regional production cluster across the projection horizon. CAGRs derived from fitted adoption curves incorporating regulatory mandate phase-in schedules and fleet replacement cycles. Industry-specific inputs include piezoelectric ceramic price indices and firmware licensing attach rate assumptions.
Underlying assumptions cover regulatory enforcement consistency and ceramic supply continuity, with deviation risk concentrated in export control actions and Lidar cost-down acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Asia-Pacific Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Airbag Market
Automotive Safety and Security Systems
Start Stop System Market
Automotive Safety and Security Systems
Vehicle Occupancy Detection System Market
Automotive Safety and Security Systems
Europe Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
United States Automotive Airbag Systems Market
Automotive Safety and Security Systems
Whiplash Protection System Market
Automotive Safety and Security Systems
Asia Pacific Lane Departure Warning Systems Market
Automotive Safety and Security Systems
Air Brake System Market
Automotive Safety and Security Systems
Advanced Suspension Control System Market
Automotive Safety and Security Systems
South Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Engine Braking System Market
Automotive Safety and Security Systems
India Airbag Systems Market
Automotive Safety and Security Systems
Biometric Driver Identification System Market
Automotive Safety and Security Systems
Global Airbag Systems Market