
 Latin America E-Bike Market | 2026-2036
Latin America E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America E-Bike Market Foresight
The capital-intensity divergence between integrated battery producers and import-dependent assemblers is unwinding competitive dynamics across the region. Giant Bicycles Co. Ltd leverages its established distribution infrastructure to anchor premium positioning in urban centers. Caloi sustains domestic manufacturing scale that competes effectively on landed cost against fully imported alternatives. EMOV (Energía en Movimiento) specializes in localized battery-pack assembly, navigating supply chain volatility that disrupts pure-import competitors.
An e-bike combines a conventional bicycle frame with an electric motor, controller, and rechargeable battery pack, typically delivering pedal-assist power up to 250-750 watts depending on regulatory classification. The primary commercial purpose centers on reducing human exertion for urban commuting, cargo transport, and recreational mobility across varied topography. City E-Bikes dominate volume as municipal bike-sharing programs and food-delivery platforms standardize on step-through frames with integrated racks. Cargo E-Bikes represent the fastest-expanding category as logistics operators replace van-based last-mile delivery in congested metropolitan cores. Lithium-ion battery configurations command the technical margin pool due to superior energy density and cycle life compared to lead-acid alternatives still common in price-sensitive segments.
CONTRAN in Brazil, SEMOV in Mexico City, and Chile's Ministry of Transport have each established distinct e-bike classification frameworks that determine motor-power thresholds, helmet requirements, and roadway access permissions. These regulatory architectures directly shape product specification decisions, as manufacturers must calibrate motor controllers and maximum assisted speeds to comply with national type-approval standards rather than deploying uniform global platforms. Stakeholders must monitor pending harmonization discussions between Mercosur and Pacific Alliance regulators, as divergent technical requirements threaten to fragment procurement strategies across the region's largest addressable markets.
Market Dynamics
Fleet electrification mandates across Brazilian and Mexican metropolitan zones are compressing replacement cycles for combustion-powered delivery vehicles, forcing logistics operators to reconfigure capital allocation toward two-wheel electric assets.
Growth Catalysts
- CONTRAN Resolution 823:Brazil's national traffic council established definitive e-bike classification, helmet standards, and roadway access rules that removed legal ambiguity deterring commercial fleet procurement.
- Last-mile logistics densification:Food-delivery platforms and parcel carriers operating in São Paulo and Mexico City are expanding cargo e-bike depots to circumvent congestion charges and fuel price volatility.
- Lithium-ion cell localization:Regional battery-pack assembly operations are reducing import dependency and shortening lead times for fleet operators requiring rapid scale-up.
Market Restraints
- Import concentration for power electronics:Motor controllers and battery management systems remain concentrated in East Asian supply chains, exposing assemblers to currency fluctuation and shipping disruption.
- Lead-acid battery persistence:Price-sensitive consumer segments in secondary cities continue purchasing heavier, shorter-cycle lead-acid configurations that constrain total addressable value capture.
- Divergent national type-approval regimes:Mercosur and Pacific Alliance regulators maintain non-harmonized motor-power thresholds and testing protocols, fragmenting product specification requirements.
Strategic Opportunities
- Chilean Andean tourism corridors:Mountain e-bike rental networks serving Santiago and Valparaíso remain underdeveloped relative to European alpine markets, presenting white-space expansion.
- SEMOV micromobility integration:Mexico City's transport secretariat is expanding protected lane networks and parking infrastructure that directly enables commercial fleet electrification.
- Solar charging convergence:Off-grid photovoltaic installations at delivery depots are pairing with battery-swapping stations to reduce grid dependency in regions with unreliable electrical infrastructure.
Industry Challenges
- Electronics technician scarcity:Maintenance networks lack sufficient trained personnel for diagnostic repair of integrated motor-controller systems, extending vehicle downtime.
- Multi-jurisdiction certification timelines:Manufacturers face sequential testing requirements across Brazil, Mexico, and Chile that delay product launches by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America E-Bike Market |
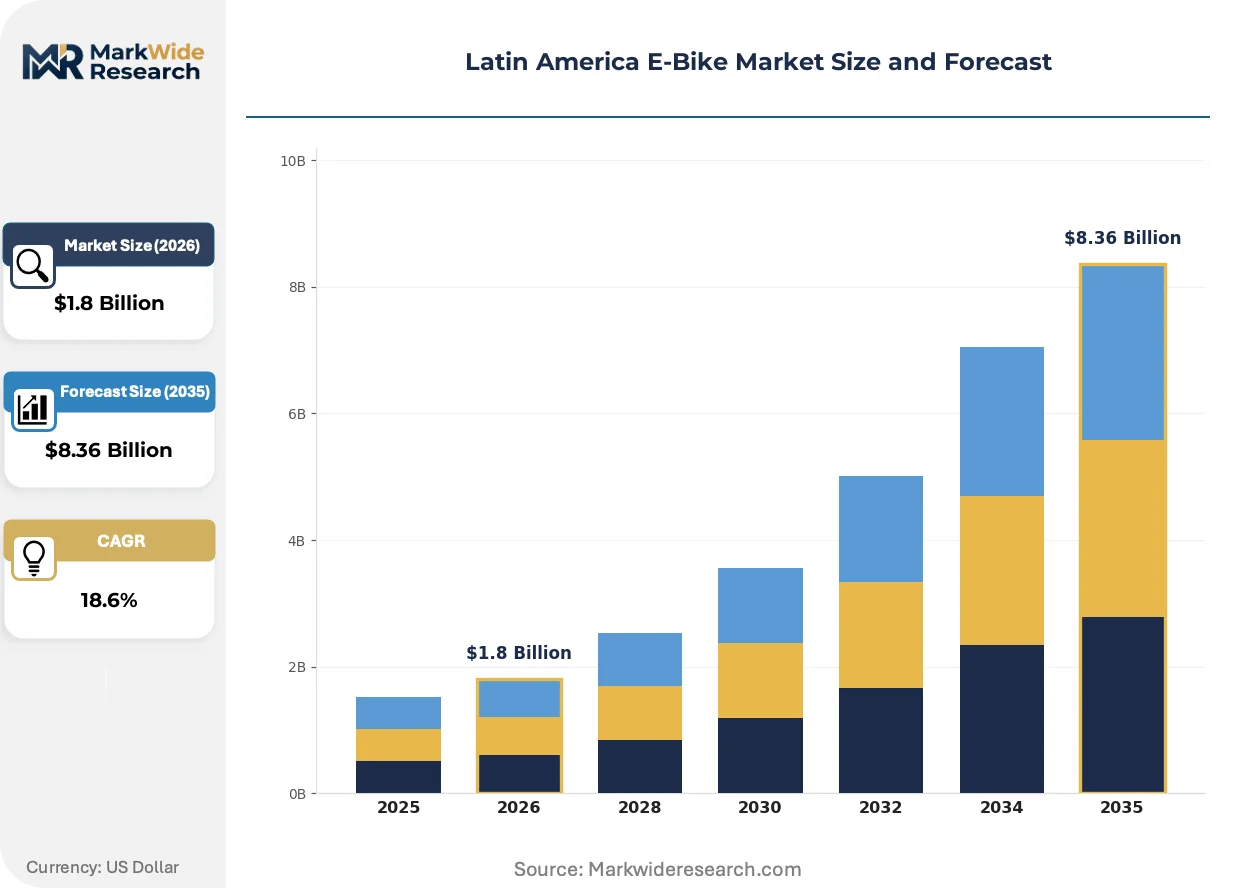
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mountain E-Bikes, City E-Bikes, Folding E-Bikes, Cargo E-Bikes Battery Type: Lithium-ion, Nickel Cadmium, Lead Acid, Lithium Polymer Usage: Recreational, Commuting, Delivery, Sport End User: Businesses, Retailers, Individuals, Tourists |
| Companies Covered | EMOV (Energía en Movimiento), Brazil Electric Bikes, Giant Bicycles Co. Ltd, Caloi, Merida Bikes, Trek Bicycle Corporation, Pedego Electric Bikes, E-Moving, EDG, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America E-Bike Market Shifts & Advancements
Powertrain architecture is compressing toward integrated hub-motor designs that reduce component count, while regulatory clarity is accelerating fleet standardization on specific frame configurations.
Hub-mounted motor systems with internal planetary gearing are miniaturizing previously bulky mid-drive configurations. Cargo fleet operators in São Paulo and Mexico City are adopting these compact units for their reduced maintenance exposure and theft deterrence. The technology is miniaturizing the physical footprint of commercial-grade propulsion, enabling step-through frames with lower center-of-gravity loading.
SEMOV's updated micromobility framework in Mexico City mandates geofenced speed limitation and mandatory insurance coverage for commercial operators. The regulation is forcing platform companies to retrofit existing fleets with connected telematics or retire non-compliant vehicles. Food-delivery aggregators are responding by consolidating procurement around certified models from established distributors.
Direct-to-fleet sales channels are displacing traditional retail intermediaries for commercial buyers. Logistics operators in Brazilian metropolitan zones are negotiating volume contracts with manufacturers that bundle maintenance, battery leasing, and telematics subscriptions. This pattern is most visible among last-mile parcel carriers operating high-utilization routes in Belo Horizonte and Rio de Janeiro.
Latin America E-Bike Market Segmentation
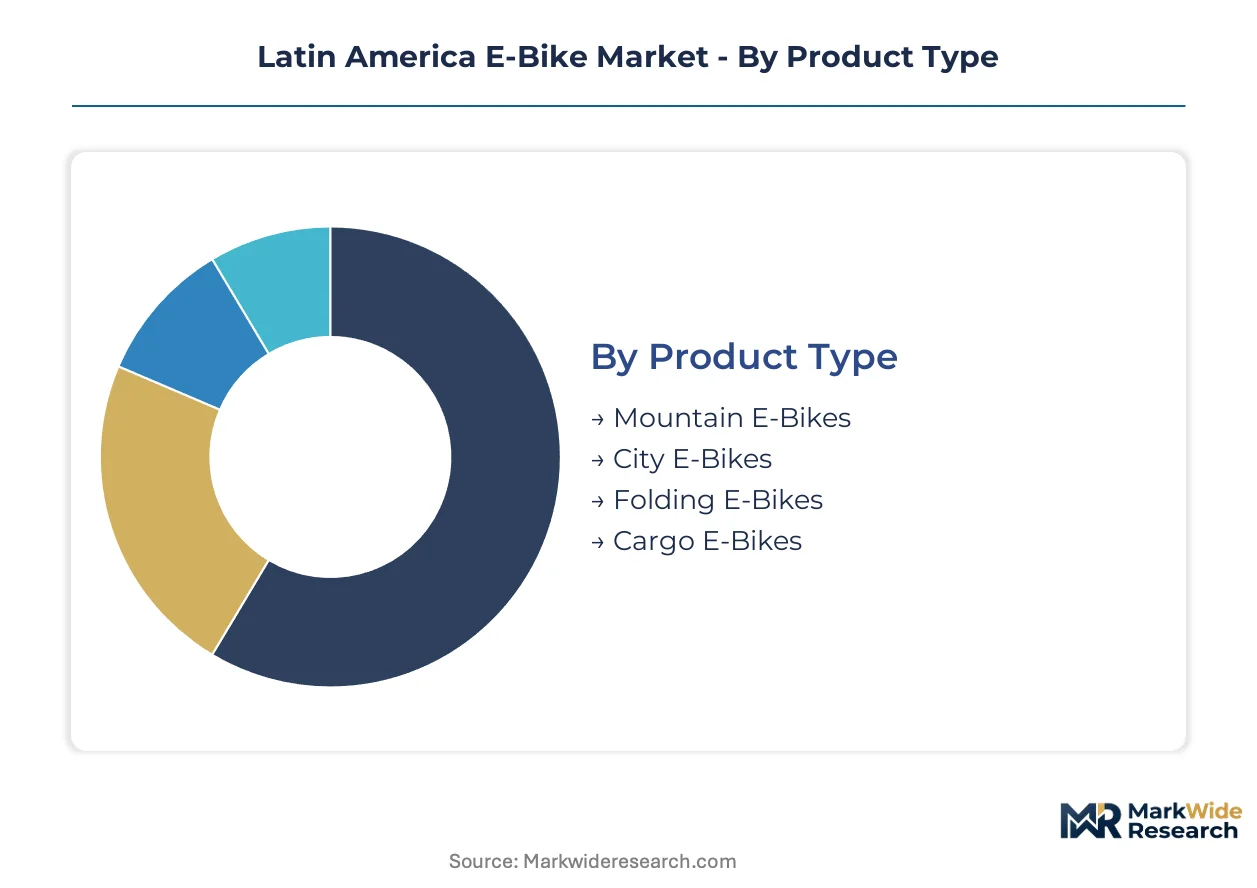
Product specification decisions across Latin America diverge sharply between domestically calibrated models and fully imported platforms. Regulatory fragmentation between Brazil's CONTRAN, Mexico's SEMOV, and Chile's national transport frameworks forces manufacturers to maintain parallel SKUs rather than unified regional offerings.
Product Type:
Brazil and Mexico concentrate domestic assembly capacity for urban-oriented frames, while mountain and cargo variants rely primarily on East Asian import channels.
- City E-Bikes:Step-through frames with integrated racks and hub-mounted motors dominate municipal procurement in São Paulo and Mexico City. Food-delivery platforms standardize on this configuration to comply with geofenced speed limitations and helmet mandates.
- Cargo E-Bikes:Extended wheelbase designs with reinforced loading platforms are displacing combustion vans for last-mile parcel routes in congested metropolitan cores. Fleet operators in Belo Horizonte and Rio de Janeiro negotiate volume contracts bundling maintenance and battery leasing.
- Mountain E-Bikes:Full-suspension and hardtail variants serve Chilean Andean tourism corridors around Santiago and Valparaíso, where rental networks remain underdeveloped relative to European alpine markets.
- Folding E-Bikes:Compact hinge-frame designs with reduced battery capacity address multi-modal commuters in dense urban centers where theft deterrence and indoor storage constraints shape purchasing decisions.
City E-Bikes commands the established base. The steepest expansion runs through Cargo E-Bikes.
Battery Type:
Cost tier stratification separates premium lithium configurations from price-competitive alternatives still prevalent in secondary markets.
- Lithium-ion:Cylindrical and prismatic cell formats deliver superior energy density and cycle life for commercial fleets operating high-utilization routes. Regional pack assembly operations in Brazil and Mexico are reducing import dependency and shortening procurement lead times.
- Lead Acid:Heavier, shorter-cycle configurations persist in price-sensitive consumer segments across secondary Brazilian cities and northern Mexican municipalities where upfront cost sensitivity outweighs total cost-of-ownership considerations.
- Lithium Polymer:Pouch-cell architectures enable frame-integrated battery designs for premium urban models targeting aesthetic-conscious commuters in São Paulo's upscale districts.
- Nickel Cadmium:Legacy chemistry with limited current deployment, constrained by environmental disposal regulations and inferior energy density relative to lithium alternatives.
Lithium-ion anchors fleet procurement. Lead Acid retains volume in retail channels serving budget-constrained purchasers.
Usage:
Application concentration tilts toward commercial mobility as logistics electrification mandates reshape capital allocation patterns.
- Delivery:Platform companies and parcel carriers operate the highest daily utilization rates, driving demand for modular battery-swapping infrastructure and telematics-enabled fleet management systems across Brazilian and Mexican metropolitan zones.
- Commuting:Protected lane expansion by SEMOV in Mexico City and similar municipal programs in Santiago enable modal shift away from private vehicles and public transit for mid-distance urban journeys.
- Recreational:Weekend leisure riders in coastal Brazilian cities and Argentine lake districts prioritize comfort-oriented step-through frames over performance specifications.
- Sport:Competitive and fitness-oriented use cases concentrate in Chile's central valley and Colombian highland regions where elevation profiles justify pedal-assist technology for training regimes.
Delivery applications absorb the largest share of new commercial registrations. Commuting exhibits the strongest policy tailwind from infrastructure investment.
End User:
Customer-type segmentation reveals a structural divide between direct-to-fleet procurement and traditional retail intermediation.
- Businesses:Logistics operators and food-delivery platforms negotiate manufacturer-direct contracts with bundled service agreements, bypassing distributor markups and enabling customized telematics integration for compliance reporting.
- Individuals:Private purchasers rely on established bicycle retail networks in Brazilian and Mexican urban centers, where financing availability and maintenance proximity drive brand selection more than technical specifications.
- Retailers:Independent bike shops and sporting goods chains function as the primary channel for consumer-oriented models, though their margins compress as manufacturers build direct commercial sales capabilities.
- Tourists:Short-term rental demand concentrates in Chilean alpine destinations and Brazilian coastal cities, with seasonal utilization patterns that favor durable, low-maintenance fleet configurations.
Businesses drive volume in commercial-grade segments. Individuals sustain the broader retail infrastructure serving consumer markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands pricing power through domestic assembly scale while Mexican operators absorb premium import costs for specialized cargo configurations. This asymmetry shapes procurement patterns across the region's two largest addressable markets.
Brazil
CONTRAN Resolution 823 eliminated legal ambiguity that previously deterred fleet buyers from electrified two-wheel procurement. The national traffic council's classification framework established helmet standards and roadway access rules that enabled commercial operators to standardize capital allocation. São Paulo's metropolitan congestion charges accelerate replacement cycles for combustion-powered delivery vehicles.
Mexico
SEMOV's micromobility framework mandates geofenced speed limitation and mandatory insurance coverage for commercial operators in Mexico City. The transport secretariat's protected lane expansion enables modal shift for food-delivery platforms operating high-utilization routes. Logistics densification in the capital compresses last-mile costs relative to van-based alternatives.
Chile
The Ministry of Transport maintains distinct motor-power thresholds and testing protocols that fragment product specification requirements against Mercosur standards. Andean tourism corridors around Santiago and Valparaíso present underdeveloped rental network opportunities relative to European alpine markets. Mountain e-bike infrastructure remains concentrated in central valley training regimes.
Argentina
Regulatory harmonization discussions with Mercosur partners threaten to delay type-approval timelines for manufacturers seeking sequential market entry. Buenos Aires metropolitan operators face currency fluctuation exposure on imported power electronics concentrated in East Asian supply chains. Secondary cities sustain price-sensitive demand for heavier lead-acid configurations.
Colombia
Highland elevation profiles justify pedal-assist technology adoption for fitness-oriented commuters in Bogotá's dense urban core. The national transport regulator has not established definitive e-bike classification frameworks comparable to Brazilian or Mexican precedents. Commercial fleet procurement remains nascent relative to Andean neighbors.
Latin America E-Bike Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Latin America e-bike market. Integrated battery producers capture technical margin pools through superior energy density while import-dependent assemblers compete on landed cost in price-sensitive segments. Three strategic archetypes dominate: domestic manufacturers with established distribution infrastructure, regional battery-pack assemblers navigating supply chain volatility, and premium-positioned global brands leveraging urban center penetration. Competitive moves concentrate on direct-to-fleet sales channel development and localized service bundling.
Among regional specialists, EMOV (Energía en Movimiento) exemplifies the battery-pack assembly archetype through localized production that reduces import dependency. Giant Bicycles Co. Ltd represents premium global positioning anchored in established urban distribution networks. Caloi occupies the domestic manufacturing tier with scale-driven cost competitiveness against fully imported alternatives.
| Leading Market Players |
|---|
| EMOV (Energía en Movimiento) |
| Brazil Electric Bikes |
| Giant Bicycles Co. Ltd |
| Caloi |
| Merida Bikes |
| Trek Bicycle Corporation |
| Pedego Electric Bikes |
| E-Moving |
| EDG |
| Others |
Supply & Pricing Matrix
Domestic assembly scale in Brazil anchors regional cost floors while Mexican operators absorb premium import markups for specialized cargo configurations. CONTRAN's regulatory clarity enables São Paulo-based manufacturers to achieve capacity utilization rates that compress unit economics below fully landed import alternatives, concentrating pricing power among integrated producers.
Pricing Analysis
Configured-to-order fleet contracts command 15-25% premiums over standard retail SKUs due to telematics integration and compliance retrofitting. Three-tier pricing structure across premium, standard, and economy levels separates lithium-ion cargo platforms from lead-acid commuter models and hub-motor city bikes. Cost compression in the economy tier intensifies because Brazilian secondary cities sustain price-sensitive demand for heavier lead-acid configurations. Food-delivery platforms exhibit the lowest price sensitivity due to operational cost savings from congestion charge avoidance, while individual commuters in northern Mexican municipalities show highest elasticity.
Supply Chain Analysis
Strait of Malacca transit underwrites lithium cell delivery schedules to regional pack assemblers in São Paulo and Mexico City. East Asian concentration for motor controllers and battery management systems draws from Taiwan, South Korea, and Japan manufacturing clusters. Single-source vulnerability in power electronics exposes assemblers to currency fluctuation and shipping disruption. Distribution runs through manufacturer-direct fleet channels displacing traditional retail intermediaries for commercial buyers, while independent bike shops retain consumer market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-fleet procurement consolidation among Brazilian and Mexican logistics operators has shifted buyer power toward volume-contracting platforms, fragmenting traditional distributor margins.
For Market Incumbents: Consolidate service bundling capabilities around battery leasing and telematics subscription revenue streams. Deepen backward integration into lithium cell procurement to offset East Asian supply concentration exposure. Defend against emerging battery-pack assemblers by securing exclusive distribution rights with SEMOV-certified fleet operators in Mexico City. For New Entrants and Emerging Players: Maintenance network scarcity in secondary Brazilian cities presents white-space entry opportunity. Target Andean tourism corridors around Santiago where rental infrastructure remains underdeveloped relative to European benchmarks. Pursue solar charging depot partnerships as differentiated go-to-market positioning against grid-dependent competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet-focused platform companies with integrated battery leasing operations. Long-term viability favors vertically integrated regional specialists with captive lithium assembly capacity. Monitor CONTRAN-SEMOV harmonization discussions as regulatory alignment signal for scalable procurement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Pack Localization | Regional cell assembly in São Paulo reduces import dependency and shortens fleet procurement lead times. |
| Telematics Platform Integration | Connected motor controllers enable SEMOV-compliant geofencing and insurance verification for commercial operators. |
| Solar Charging Infrastructure | Photovoltaic depot installations pair with battery swapping to reduce grid dependency in unreliable electrical regions. |
| Direct Fleet Sales Channel | Manufacturer bypass of retail intermediaries captures margin pools from high-utilization logistics operators. |
| Protected Lane Partnership | SEMOV infrastructure expansion agreements secure preferential access for certified commercial fleet configurations. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fleet procurement managers, battery pack assembly engineers, and micromobility policy officers; and secondary validation through CONTRAN regulatory filings, SEMOV infrastructure disclosures, customs trade records, and lithium cell import manifests. Bottom-up triangulation across manufacturer shipment data and top-down reconciliation against metropolitan congestion charge revenue enabled cross-verification of commercial fleet penetration estimates.
Across the projection horizon, the analytical framework modeled volume and value outputs across product type, battery chemistry, usage application, and end-user archetype dimensions. CAGRs were derived from regression analysis of historical fleet procurement cycles and policy implementation timelines. Forecast inputs incorporated lithium cell price trajectories and protected lane network expansion schedules from municipal transport authorities.
Underlying assumptions cover sustained regulatory clarity in Brazil and Mexico, with deviation risk concentrated in Mercosur-Pacific Alliance harmonization delays and East Asian supply chain disruption. Practitioners should keep alternative scenarios live as lithium localization timelines and solar charging adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
BEV Electric Drive Unit Market
Electric Vehicles
Electric Unicycle Market
Electric Vehicles
Automotive Battery Thermal Management System Market
Electric Vehicles
Neighbourhood Electric Vehicle Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market
Electric Vehicles
EV Condenser Market
Electric Vehicles
Electric Vehicle Speed Reducer Market
Electric Vehicles
Preassembled Harness Modules for Skateboard EV Platforms Market
Electric Vehicles
EV Taxi Market
Electric Vehicles
Canada Solar E-Bike Market
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
Electric Mobility Market
Electric Vehicles
Hybrid EV Conversion Kit Market
Electric Vehicles
Electric Vehicle Control Unit Market
Electric Vehicles
China NEV Taxi Market
Electric Vehicles
India Electric Car Market