
 Asia Pacific Automotive High Performance Electric Vehicles Market | 2026-2036
Asia Pacific Automotive High Performance Electric Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Automotive High Performance Electric Vehicles Market Outlook
Software-defined performance tuning is rebalancing what buyers pay for in Asia Pacific high performance EVs. Toyota Motor Corporation leverages its solid-state battery R&D pipeline to differentiate future powertrain architectures. BYD Co. Ltd anchors its position through vertical integration across cell production and semiconductor packaging. Hyundai Motor Company competes via dedicated EV platforms that reduce weight and improve thermal management for sustained track performance.
Asia Pacific automotive high performance electric vehicles combine dual-motor or tri-motor architectures delivering sustained output above 300 kW, with battery packs engineered for repeated high-discharge cycles without thermal degradation. These vehicles serve affluent individual buyers and premium fleet operators requiring sub-four-second acceleration alongside daily drivability. Sedans currently occupy the largest revenue pool given their balance of cabin space and aerodynamic efficiency, while solid-state technology represents the fastest-advancing segment as manufacturers race beyond lithium-ion energy density limits. Sports Cars command concentrated margin pools due to limited production volumes and carbon-fiber intensive construction that supports pricing power.
China's MIIT enforces NEV credit mandates that effectively require manufacturers to produce increasing ratios of electrified vehicles, while Japan's METI coordinates industry consortia on solid-state commercialization timelines. South Korea's MFDS-aligned vehicle safety frameworks and KBA-influenced crash standards shape product certification requirements for export-oriented producers. Stakeholders must monitor how battery chemistry regulations and charging infrastructure standardization across these jurisdictions determine which technology bets secure market access.
Market Dynamics
China's MIIT dual carbon mandates are compressing development timelines for domestic manufacturers while Japan's METI solid-state consortia accelerate chemistry transitions. South Korea's KBA-influenced crash standards reshape thermal management architectures across the region.
Growth Catalysts
- MIIT NEV Credit Mandates:China's Ministry of Industry and Information Technology enforces escalating electrified vehicle production ratios that force manufacturers to prioritize high-performance battery architectures.
- Yangtze River Delta Clustering:Battery supply chains and vehicle assembly plants co-locate in this corridor, reducing logistics friction and enabling rapid prototype-to-production cycles.
- Solid-State Chemistry Transition:METI-coordinated industry consortia in Japan accelerate commercialization timelines beyond lithium-ion energy density limits.
Market Restraints
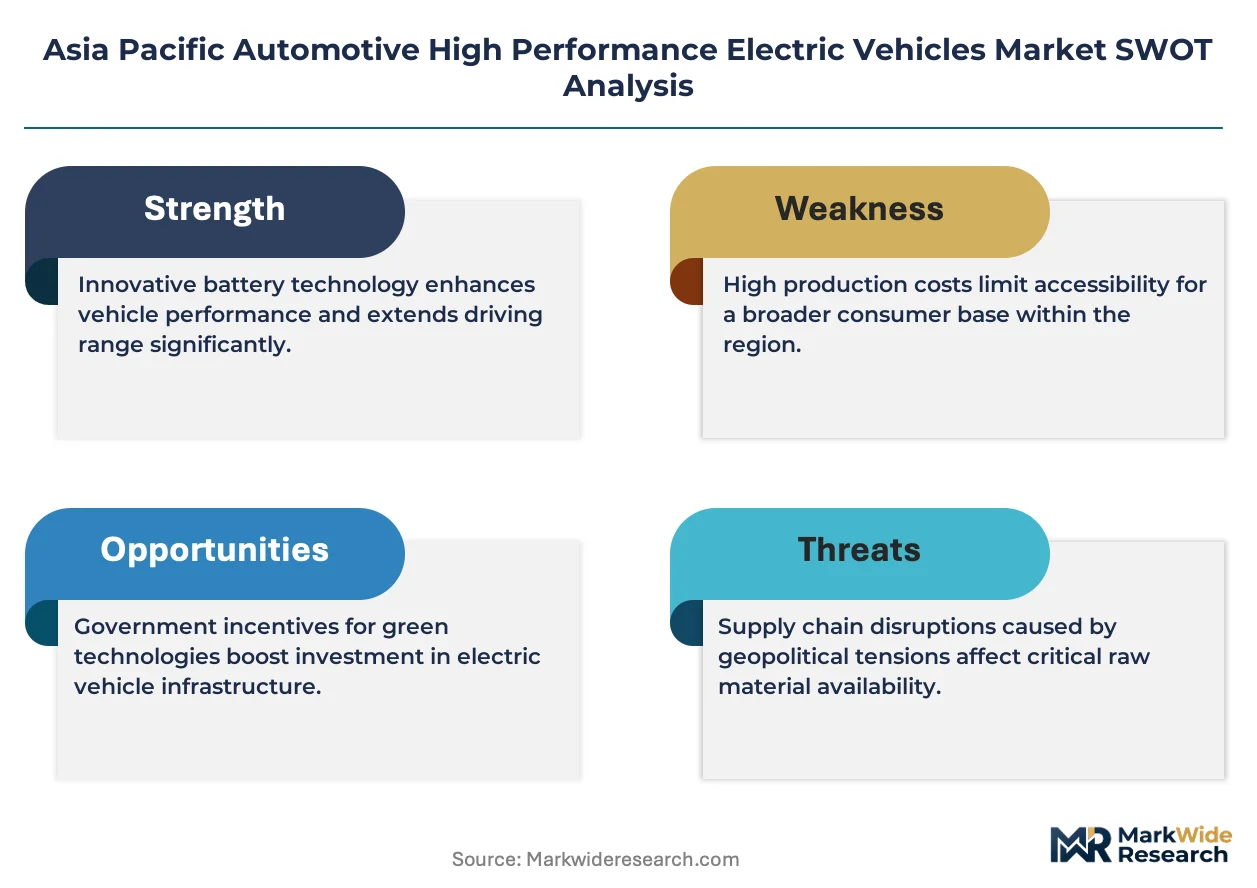
- Lithium Price Volatility:Cathode material cost fluctuations compress margin structures for battery pack producers serving performance-tier vehicles.
- Single-Source Thermal Interface Materials:Concentrated supply of aerospace-grade cooling compounds from Japanese specialty chemical producers creates input vulnerability.
- GB Standard Certification Friction:China's mandatory national standards for high-voltage systems extend homologation timelines for imported powertrain components.
Strategic Opportunities
- India's Nascent Performance EV Segment:Underpenetrated luxury automotive demand in Mumbai and Delhi creates first-mover positioning for tri-motor architectures.
- Fleet Electrification Mandates:Premium mobility operators across Singapore and Hong Kong face tightening emissions rules that favor sustained high-output battery systems.
- Vehicle-to-Grid Convergence:Bidirectional charging integration with stationary storage applications opens ancillary revenue streams for high-capacity pack owners.
Industry Challenges
- Thermal Management Engineering Talent:Scarce specialists in liquid-cooled battery simulation and track-grade heat rejection constrain product development bandwidth.
- MFDS-Aligned Safety Certification:South Korea's Ministry of Food and Drug Safety vehicle safety frameworks require extended validation cycles for new cell chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Automotive High Performance Electric Vehicles Market |
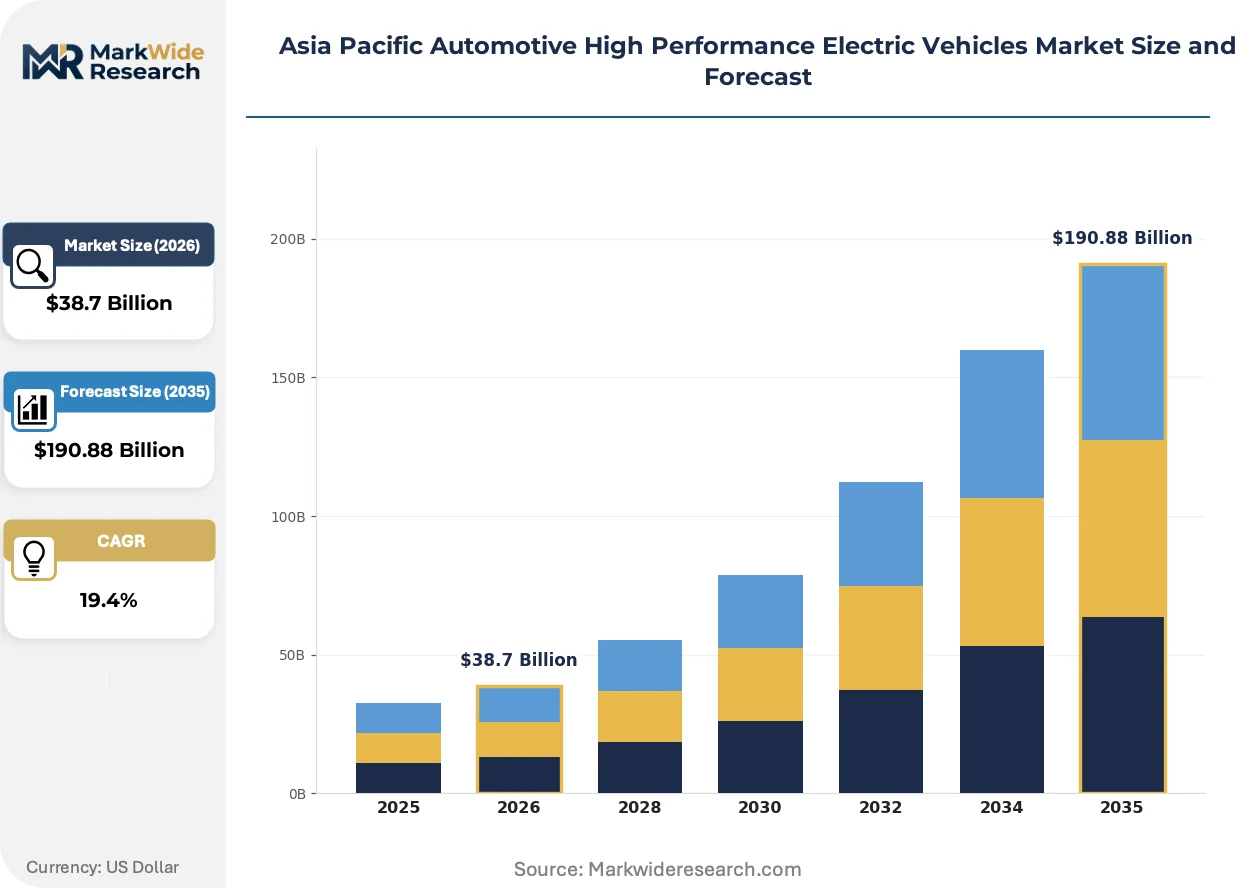
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $190.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sedans, SUVs, Sports Cars, Hatchbacks Technology: Lithium-Ion, Solid-State, Fuel Cell, Hybrid End User: Individual Consumers, Fleet Operators, Government Agencies, Businesses Sales Channel: Online Retail, Dealerships, Direct Sales, Auctions |
| Companies Covered | Toyota Motor Corporation, BYD Co. Ltd, Nissan Motor Co. Ltd, Hyundai Motor Company, BMW AG, Kia Motors Corporation, Honda Motor Co. Ltd, Daimler AG (Mercedes-Benz), General Motors, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Automotive High Performance Electric Vehicles Market Strategic Shifts
Solid-state battery architectures are displacing conventional lithium-ion configurations across Asia Pacific performance EV development pipelines. Software-defined powertrain tuning rebalances buyer willingness-to-pay toward digital upgrade pathways.
Solid-state electrolyte technology is integrating ceramic-oxide separators that eliminate thermal runaway risks while enabling 400+ Wh/kg energy density. Japanese and South Korean cell manufacturers are adopting these architectures for executive fleet prototypes. This chemistry transition is integrating sustained high-discharge capability into daily-drivable vehicle platforms.
China's GB/T charging infrastructure standardization mandates are forcing connector and communication protocol convergence across domestic manufacturers. The MIIT-aligned framework reduces interoperability friction but compresses differentiation space for proprietary fast-charging networks. Premium sedan segments respond by competing on software-layer charging optimization rather than hardware exclusivity.
Affluent individual buyers across China's tier-one cities are compressing replacement cycles as over-the-air performance upgrades extend vehicle relevance. Traditional three-year trade-in patterns shorten to eighteen-month intervals for early-adopter segments. This behavioral shift concentrates margin capture in subscription-based powertrain software tiers rather than discrete hardware sales.
Asia Pacific Automotive High Performance Electric Vehicles Market Segmentation
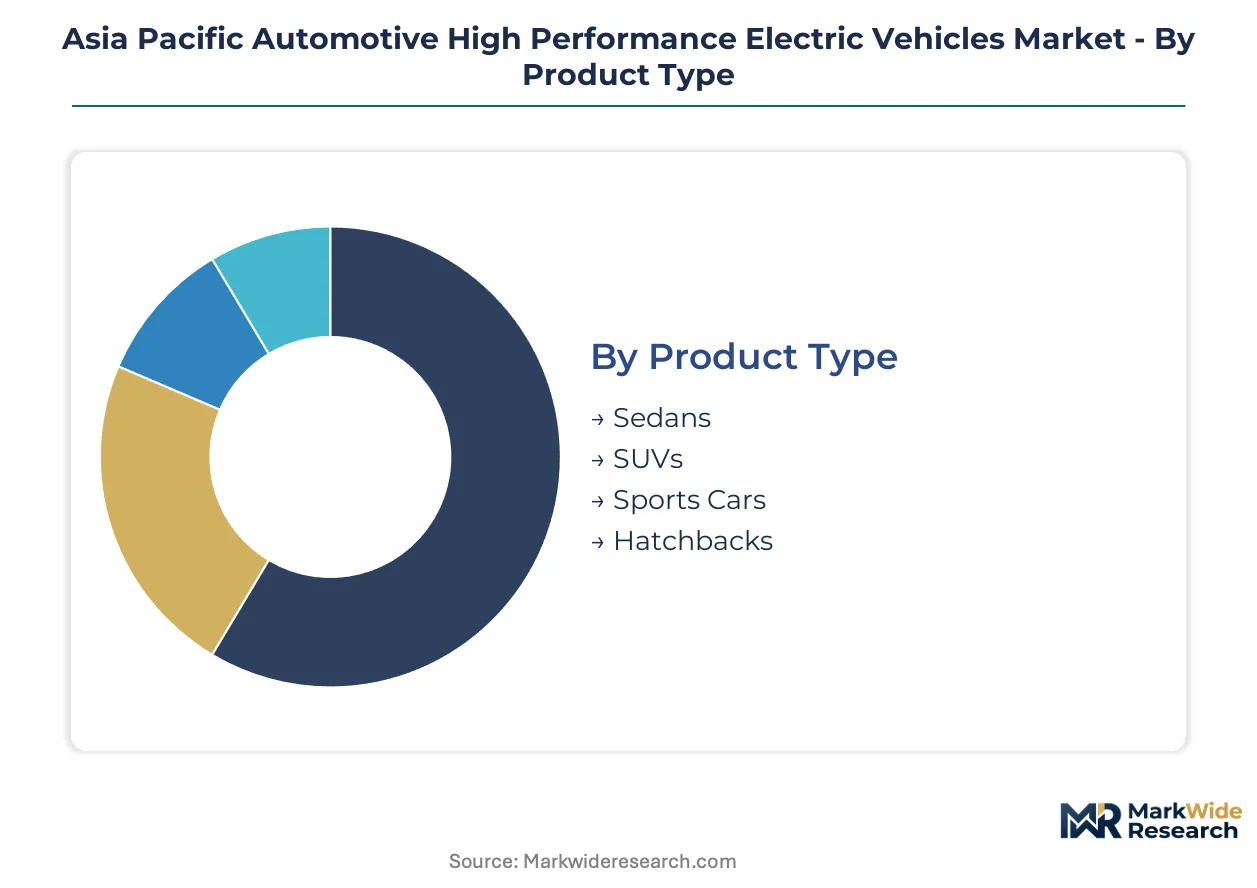
Performance EV buyers across Asia Pacific compress replacement cycles as over-the-air upgrades extend vehicle relevance. Segmentation reveals how software-defined architectures reshape purchasing patterns across product categories, battery chemistries, and procurement channels.
Product Type:
Upgrade cadences vary sharply by body style, with cabin space and aerodynamic efficiency driving divergent replacement timelines.
- Sedans:Dual-motor and tri-motor configurations deliver sustained output above 300 kW within aerodynamic four-door architectures. China's Yangtze River Delta cluster concentrates sedan demand among affluent individual buyers balancing daily drivability with sub-four-second acceleration capability.
- SUVs:Elevated ride height and expanded cabin volume accommodate larger battery packs for repeated high-discharge cycles. Premium fleet operators across South Korea procure performance SUVs for executive mobility services requiring thermal stability during sustained highway operation.
- Sports Cars:Carbon-fiber intensive construction supports concentrated margin pools through limited production volumes. Track-grade heat rejection systems serve enthusiast segments prioritizing sustained circuit performance over daily utility.
- Hatchbacks:Compact footprints with dual-motor layouts target urban buyers in Japan's dense metropolitan corridors. Shorter wheelbases sacrifice battery capacity for maneuverability in constrained parking environments.
Volume placements concentrate in Sedans; the faster expansion belongs to SUVs.
Technology:
Cost tiers separate established lithium-ion deployments from emerging solid-state architectures commanding premium positioning.
- Lithium-Ion:Mature cathode-anode configurations dominate current production with proven thermal management protocols. Domestic Chinese manufacturers leverage Yangtze River Delta supply chain clustering to compress pack costs for mass-market performance tiers.
- Solid-State:Ceramic-oxide separators eliminate thermal runaway risks while enabling 400+ Wh/kg energy density. METI-coordinated Japanese consortia accelerate commercialization timelines for executive fleet prototypes demanding sustained high-discharge capability.
- Fuel Cell:Hydrogen-electric hybrids serve niche applications requiring rapid refueling beyond battery charging infrastructure limits. South Korean producers integrate fuel cell stacks for commercial fleet operators covering extended intercity routes.
- Hybrid:Range-extender architectures combine compact battery packs with combustion generators for markets with charging infrastructure gaps. Australia's vast distances drive hybrid demand among performance buyers prioritizing route flexibility over pure-electric operation.
Cost-sensitive procurement favors Lithium-Ion; technology leadership investments flow to Solid-State.
End User:
Customer type determines specification priorities, with fleet procurement emphasizing thermal durability against individual buyer focus on acceleration metrics.
- Individual Consumers:Affluent buyers across China's tier-one cities compress replacement cycles to eighteen-month intervals. Over-the-air performance upgrades extend vehicle relevance through subscription-based powertrain software tiers.
- Fleet Operators:Premium mobility services across Singapore and Hong Kong face tightening emissions rules favoring sustained high-output battery systems. Procurement specifications prioritize repeated fast-charging tolerance over peak acceleration figures.
- Government Agencies:Official vehicle fleets in Japan and South Korea mandate domestic content ratios influencing supplier selection. MIIT credit mandates in China direct state-affiliated procurement toward qualifying NEV architectures.
- Businesses:Corporate mobility programs across India's Mumbai and Delhi corridors create first-mover positioning for tri-motor architectures. Underpenetrated luxury automotive demand supports premium pricing for sustained track-performance capability.
Procurement volume aggregates with Fleet Operators; steepest expansion trajectory emerges among Businesses.
Sales Channel:
Channel concentration reflects regional retail infrastructure maturity, with direct manufacturer relationships displacing traditional intermediaries in premium tiers.
- Online Retail:Digital configurators enable specification customization with over-the-air upgrade bundling at point of sale. China's MIIT-aligned GB/T standardization reduces interoperability friction for platform-agnostic purchasing.
- Dealerships:Physical showrooms remain essential for test-drive validation of track-grade thermal management claims. South Korea's KBA-influenced crash standards require dealer staff certification for high-voltage system demonstrations.
- Direct Sales:Manufacturer-owned channels capture margin pools previously allocated to independent retailers. Vertical integration into cell production and semiconductor packaging enables BYD and comparable producers to control pricing architecture.
- Auctions:Secondary market liquidity concentrates for limited-production sports cars with carbon-fiber construction. Eighteen-month replacement cycles among early adopters generate supply velocity for certified pre-performance programs.
Transaction volume flows through Dealerships; channel share gains fastest within Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates production capacity while consumption disperses across affluent urban clusters in Japan, South Korea, and Australia. Domestic manufacturers face compressed development timelines under MIIT mandates, yet export-oriented producers must navigate divergent certification regimes.
China
Affluent individual buyers in Shanghai and Shenzhen compress replacement cycles to eighteen-month intervals under over-the-air upgrade models. MIIT dual carbon goals enforce escalating NEV credit ratios that prioritize high-performance battery architectures. The Yangtze River Delta cluster co-locates cell production with vehicle assembly, enabling rapid prototype-to-production cycles for domestic manufacturers.
Japan
Premium fleet operators in Tokyo and Osaka expand procurement of executive mobility vehicles requiring sustained thermal stability. METI coordinates industry consortia on solid-state commercialization timelines beyond lithium-ion energy density limits. Nagoya-based engineering centers concentrate R&D talent for ceramic-oxide separator integration.
South Korea
Busan-Ulsan industrial corridors anchor export-oriented production serving KBA-influenced crash standards across European markets. MFDS-aligned vehicle safety frameworks extend validation cycles for new cell chemistries entering domestic certification. Seoul Capital Area demand concentrates among early adopters prioritizing sub-four-second acceleration metrics.
India
Corporate mobility programs in Mumbai and Delhi corridors create first-mover positioning for tri-motor architectures in underpenetrated luxury segments. Central government PLI schemes for automotive manufacturing attract cell producers establishing localized pack assembly. Karnataka and Tamil Nadu industrial zones concentrate charging infrastructure deployment along premium residential corridors.
Australia
Vast intercity distances drive hybrid demand among performance buyers prioritizing route flexibility over pure-electric operation. State-level fleet electrification mandates in New South Wales and Victoria favor sustained high-output battery systems for government procurement. Melbourne and Sydney metropolitan clusters concentrate affluent individual demand for track-grade thermal management capabilities.
Asia Pacific Automotive High Performance Electric Vehicles Market Competitive Environment
Top-tier vendors anchor premium sedan and SUV segments, while mid-tier specialists compete on platform modularity and thermal engineering differentiation. The vendor base stratifies across three archetypes: integrated cell-to-vehicle producers, dedicated EV platform specialists, and legacy automakers transitioning combustion-era brand equity. Consolidation pressures intensify as MIIT credit mandates force capacity rationalization. Dominant competitive moves include backward integration into semiconductor packaging and strategic partnerships for solid-state chemistry access.
Within the integrated producer archetype, BYD Co. Ltd and Toyota Motor Corporation exemplify contrasting geographic positioning strategies. BYD anchors its competitive stance through captive supply of battery cells and power electronics, while Toyota leverages METI-coordinated consortia for next-generation solid-state commercialization. Hyundai Motor Company occupies a platform-specialist position emphasizing dedicated EV architectures for sustained track performance. These three entities collectively represent the strategic divergence between vertical integration depth and collaborative technology development.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| BYD Co. Ltd |
| Nissan Motor Co. Ltd |
| Hyundai Motor Company |
| BMW AG |
| Kia Motors Corporation |
| Honda Motor Co. Ltd |
| Daimler AG (Mercedes-Benz) |
| General Motors |
| Others |
Value Chain & Pricing Dynamics
Solid-state battery prototyping transitions are compressing cost economics for performance-tier pack producers while concentrating supply leverage among Japanese specialty chemical manufacturers. MIIT credit mandates force domestic Chinese OEMs to absorb near-term margin compression as they scale lithium-ion architectures ahead of chemistry transitions.
Pricing Analysis
Margin tightening in mass-market performance tiers reflects Yangtze River Delta cell oversupply and cathode material cost volatility. Three-tier pricing structure across premium, standard, and economy levels separates track-grade thermal management specifications from daily-drivable configurations. Cost-down pressure on domestic Chinese manufacturers accelerates because GB standard certification extends homologation timelines for imported powertrain components. Fleet operators demonstrate lowest price sensitivity given emissions mandate compliance requirements, while individual consumers in tier-one cities prioritize subscription-based software tiers over upfront hardware costs.
Supply Chain Analysis
Thermal management engineering talent scarcity in Nagoya and Busan-Ulsan corridors constrains prototype-to-production velocity for solid-state architectures. China, South Korea, and Japan anchor geographic supply concentration for battery cell production and semiconductor packaging. Raw material dependencies center on lithium carbonate, nickel-rich cathode precursors, and aerospace-grade thermal interface compounds. Single-source vulnerability from Japanese specialty chemical producers for ceramic-oxide separators creates input concentration risk. Distribution runs through manufacturer-owned direct sales channels and certified dealership networks for high-voltage system demonstrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT dual carbon mandates and NEV credit enforcement are accelerating consolidation as capital-intensive solid-state transitions force sub-scale domestic manufacturers toward joint venture structures or exit.
For Market Incumbents: Deploy backward integration into semiconductor packaging to defend margin pools against BYD-style captive supply architectures. Prioritize METI consortium participation for solid-state chemistry access ahead of lithium-ion energy density limits. Consolidate thermal management engineering talent through targeted acquisition of Nagoya-based simulation specialists. For New Entrants and Emerging Players: Enter via India's underpenetrated corporate mobility corridors in Mumbai and Delhi, where tri-motor architectures face limited incumbent positioning. Target fleet electrification mandates across Singapore and Hong Kong as regulatory-driven procurement creates specification windows. Pursue vehicle-to-grid software partnerships as differentiated go-to-market angle for high-capacity pack owners. For Investors and Strategic Acquirers: Re-rating potential sits with platform-specialist producers given dedicated EV architecture advantages in sustained track performance. Long-term viability over the next decade hinges on solid-state chemistry commercialization timelines and MIIT credit mandate compliance capacity. Monitor KBA-influenced crash standard adoption across European export markets as inflection indicator for thermal management architecture validation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery Supply Agreement | Secures ceramic-oxide separator access from METI-coordinated Japanese consortia ahead of chemistry transitions. |
| Software-Defined Vehicle Investment | Captures recurring revenue from over-the-air performance upgrades compressing replacement cycles to eighteen months. |
| Thermal Management Engineering Acquisition | Addresses scarce liquid-cooled battery simulation talent constraining product development bandwidth. |
| Yangtze River Delta Manufacturing Footprint | Co-locates cell production with vehicle assembly to compress logistics friction and prototype cycles. |
| Charging Infrastructure Partnership | Aligns with China's GB/T standardization mandates reducing interoperability friction for platform-agnostic purchasing. |
Study Parameters
MIIT regulatory filings, vehicle production databases, and customs trade records formed the secondary backbone for market sizing and competitive positioning. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, thermal management R&D directors, and premium fleet operators validated demand assumptions and technology transition timelines. Bottom-up and top-down triangulation reconciled cell production capacity with vehicle assembly forecasts across the analysis window.
Bottom-up modeling segmented volume and value by vehicle class, propulsion architecture, battery chemistry tier, and regional production cluster. Top-down validation cross-checked aggregate forecasts against MIIT NEV credit mandate trajectories and METI solid-state commercialization timelines. CAGRs derived from segment-level growth rate reconciliation with macroeconomic indicators and infrastructure deployment patterns. Industry-specific inputs included GB standard certification timelines and KBA-influenced crash standard adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium price volatility spikes or MFDS-aligned safety certification delays. Forecasts reflect assumptions around solid-state chemistry commercialization schedules and charging infrastructure standardization convergence. Material deviation in MIIT mandate enforcement intensity or METI consortium technology transfer timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
48V Mild Hybrid Electric Vehicle (MHEV) Market
Electric Vehicles
Global Electric Scooters Market
Electric Vehicles
Global Electric Vehicle (EV) Management Solution Market
Electric Vehicles
Electric Two-Wheeler Market
Electric Vehicles
France Automotive High Performance Electric Vehicles Market
Electric Vehicles
France Hybrid Electric Vehicle Battery Market
Electric Vehicles
ASEAN EV Battery Pack Market
Electric Vehicles
Electric Vehicle Operations Management Solutions Market
Electric Vehicles
Electric Vehicle Control Unit Market
Electric Vehicles
Electric Vehicle Sound Generators Market
Electric Vehicles
Global Automotive Inductive Wireless Charging Systems Market
Electric Vehicles
United Kingdom Electric Vehicle (EV) Market
Electric Vehicles
Asia-Pacific Electric Vehicle (EV) Fluids Market
Electric Vehicles
India Electric Rickshaw Market
Electric Vehicles
ASEAN Electric Vehicle Market
Electric Vehicles
Automotive Battery Packs Market