
 Asia Pacific Hybrid Electric Vehicle Battery Market | 2026-2036
Asia Pacific Hybrid Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Hybrid Electric Vehicle Battery Market Insights
Silicon-carbon composite anode chemistry is reshaping energy density benchmarks across the Asia Pacific hybrid battery supply chain. LG Energy Solution leverages its cylindrical cell expertise to anchor premium SUV contracts in South Korea. BYD Company Ltd controls blade battery architecture production through in-house lithium iron phosphate refining. Samsung SDI competes on prismatic module standardization for European-bound export programs from its Tianjin facility.
The Asia Pacific Hybrid Electric Vehicle Battery comprises electrochemical storage systems engineered for partial electrification, typically pairing a 1-5 kWh lithium-ion or nickel-metal hydride pack with an internal combustion engine through regenerative braking integration. Lithium-ion formulations dominate OEM procurement due to superior Wh/kg ratios and cycle stability above 2,000 charge events. Nickel-metal hydride retains structural share in cost-sensitive hatchback segments where thermal tolerance outweighs energy density priorities. Fast charging infrastructure rollouts by fleet operators are redirecting cell procurement toward higher C-rate tolerant cathode formulations.
China's MIIT enforces GB standards for battery safety testing that constrain market access for uncertified imports. Japan's METI and South Korea's MFDS coordinate cell recycling mandates that reshape end-of-life cost structures across the region. India's BIS certification requirements for automotive battery assemblies add compliance layers for entrants targeting fleet electrification programs. Stakeholders must monitor regulatory divergence on solid-state electrolyte classification as chemistry transitions accelerate.
Market Dynamics
Fleet operators across Asia Pacific are accelerating hybrid procurement as fuel cost volatility persists, while China's MIIT dual carbon goals and Japan's METI subsidy frameworks compress cell chemistry transition timelines. Cathode material refining clusters in Jiangsu and Guangdong provinces now sit within tight proximity to OEM assembly plants, creating geographic lock-in effects that reshape competitive positioning.
Growth Catalysts
- MIIT Dual Carbon Mandates:China's GB standards enforcement accelerates lithium iron phosphate adoption across domestic OEM supply chains, forcing cathode formulation upgrades.
- Fleet Electrification Programs:Commercial vehicle operators in South Korea and Japan are scaling hybrid procurement to hedge diesel price exposure, concentrating demand in 1-5 kWh pack segments.
- Silicon-Carbon Composite Anodes:Higher energy density benchmarks from this material system enable smaller pack footprints for compact hybrid architectures without sacrificing cycle stability.
Market Restraints
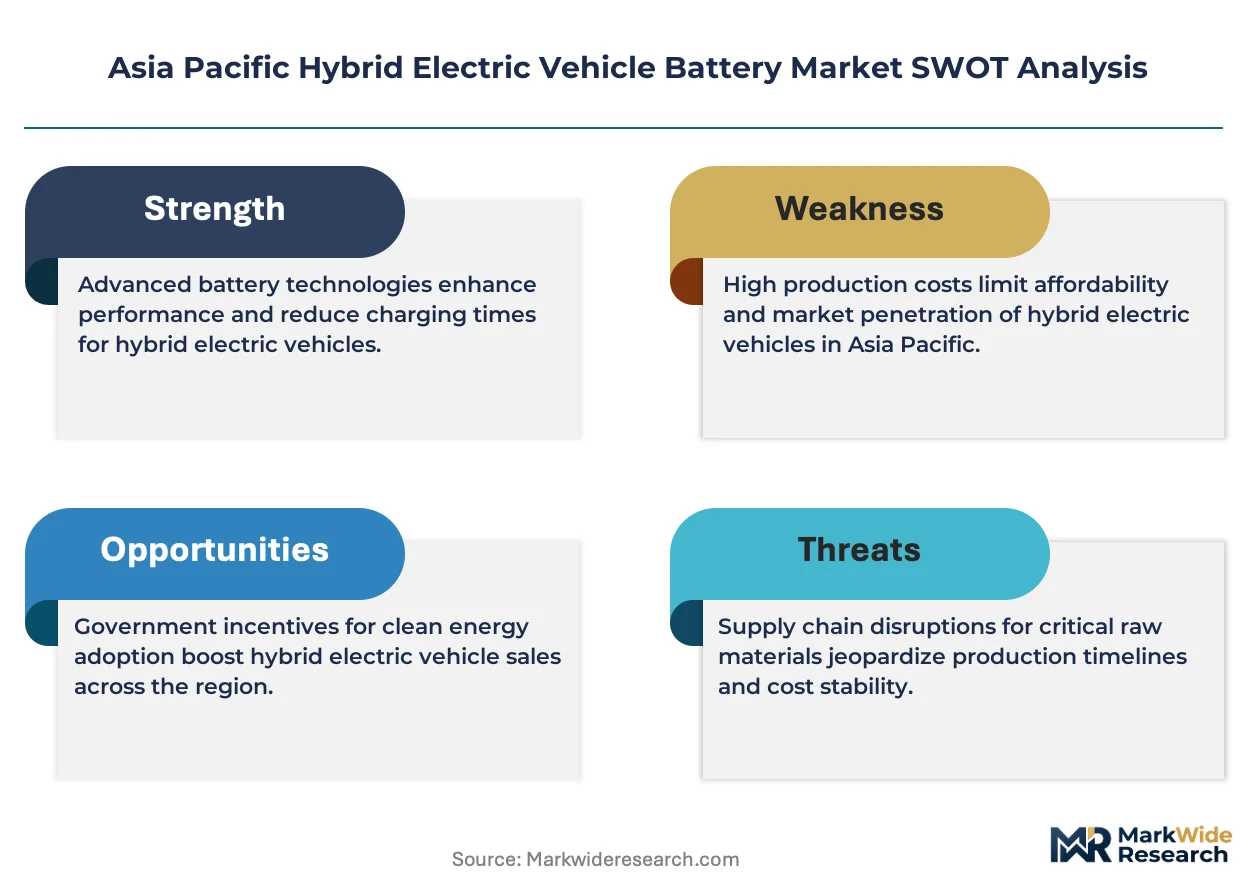
- Lithium Carbonate Volatility:Raw material input costs for cathode production swing unpredictably, compressing margin visibility for cell manufacturers operating on fixed-price OEM contracts.
- Jiangsu-Guangdong Supply Concentration:Over 60% of regional cathode refining capacity clusters in two Chinese provinces, creating geographic vulnerability to localized disruption or policy shifts.
- Nickel-Metal Hydride Lock-In:Cost-sensitive hatchback segments retain this older chemistry due to thermal tolerance requirements, limiting lithium-ion penetration in entry vehicle classes.
Strategic Opportunities
- India BIS Certification Gap:Domestic battery assembly standards remain less stringent than Chinese GB protocols, creating first-mover advantage for certified entrants targeting fleet electrification programs.
- Solid-State Electrolyte Convergence:Hybrid packs below 5 kWh present lower thermal management barriers for solid-state adoption than full-electric architectures, enabling earlier chemistry transition.
- Fast Charging Infrastructure:C-rate tolerant cathode formulations for fleet depots in Japan and South Korea open premium cell procurement channels beyond standard OEM supply agreements.
Industry Challenges
- Recycling Mandate Coordination:Japan's METI and South Korea's MFDS impose divergent end-of-life cost structures, complicating regional product standardization for multi-market suppliers.
- GB Standard Compliance Timelines:China's safety testing protocols for thermal runaway containment extend certification cycles, delaying market access for uncertified import sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Hybrid Electric Vehicle Battery Market |
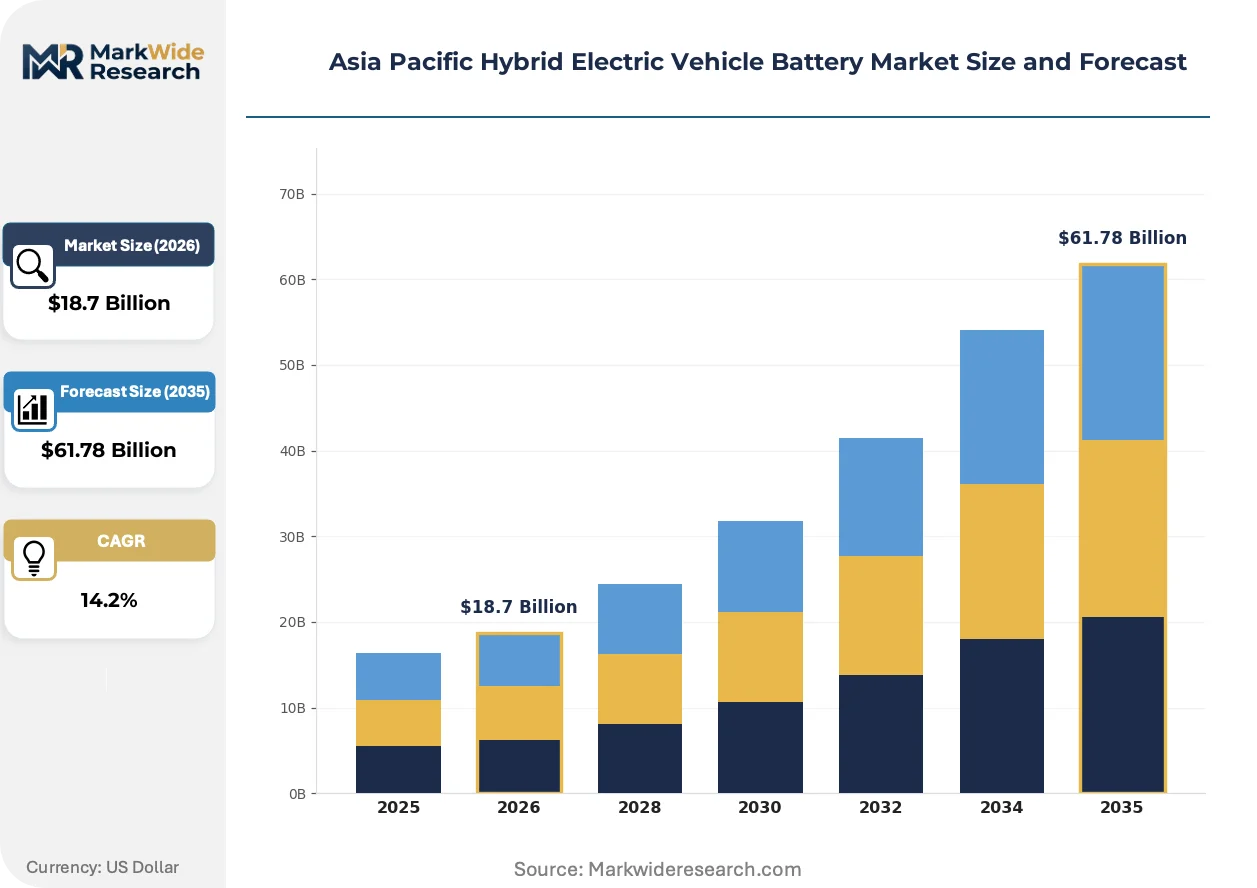
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Solid-State Vehicle Type: SUVs, Sedans, Hatchbacks, Commercial Vehicles End User: Fleet Operators, Individual Users, Ride-Sharing Services, Taxi Services Charging Method: Fast Charging, Standard Charging, Wireless Charging, Battery Swapping |
| Companies Covered | BYD Company Ltd, LG Energy Solution, Panasonic Holdings Corporation, Exide Industries Ltd, EnerSys, Contemporary Amperex Technology Co Ltd, SK Innovation Co Ltd, Samsung SDI, GS Yuasa International Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Hybrid Electric Vehicle Battery Market Trends and Innovations
Silicon-carbon composite anode chemistry is digitizing energy density benchmarks across Asia Pacific hybrid battery supply chains. Cell architecture standardization and solid-state electrolyte development are compressing traditional chemistry transition timelines, while fleet procurement models evolve toward performance-based contracting.
Silicon-carbon composite anodes embed nanostructured silicon particles within carbon matrices to accommodate volume expansion during lithiation. Premium SUV manufacturers in South Korea are adopting cylindrical cells with this chemistry at accelerated pace to reduce pack mass. The technology is digitizing traditional gravimetric density limits, enabling 300+ Wh/kg benchmarks in hybrid-scale packs previously capped at 200 Wh/kg.
China's MIIT enforces escalating GB/T 31485 safety testing protocols for thermal runaway propagation resistance. Cell manufacturers must now demonstrate 5-minute no-fire thresholds under nail penetration and overcharge conditions to access domestic OEM supply chains. South Korean exporters operating Tianjin facilities face accelerated retooling investments to maintain China market eligibility under these tightened standards.
Fleet operators are consolidating procurement authority from decentralized regional managers to centralized technical teams with cell chemistry expertise. Long-term service agreements now embed guaranteed cycle life thresholds rather than simple unit pricing, displacing spot-market purchasing in Japan's commercial vehicle segment. This behavioral shift concentrates demand toward suppliers with validated 2,000+ cycle performance data, compressing qualification timelines for unproven entrants.
Asia Pacific Hybrid Electric Vehicle Battery Market Segmentation
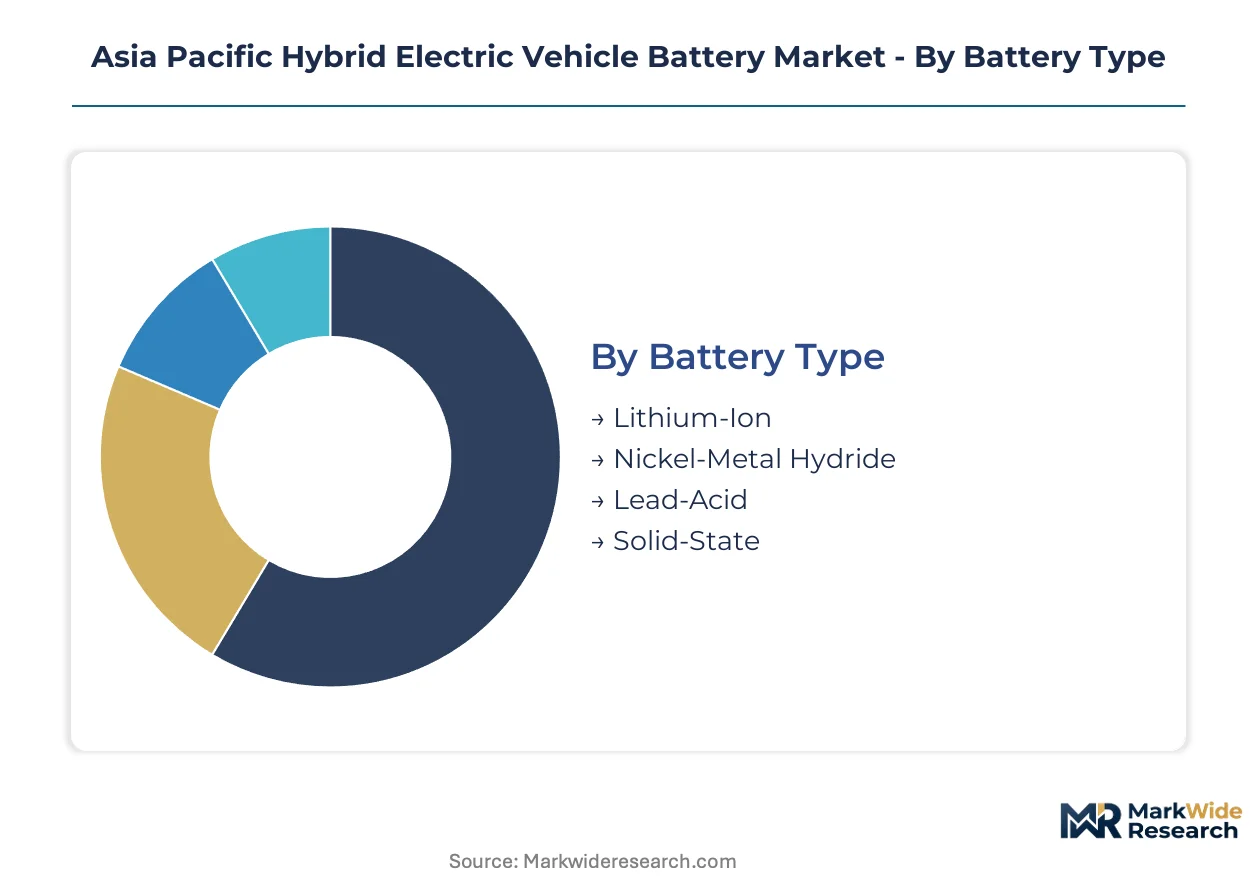
Segmentation in the Asia Pacific hybrid battery market reveals how chemistry choices, vehicle architectures, and procurement models diverge across national regulatory environments. Each dimension carries distinct margin profiles and certification requirements that reshape supplier strategies.
Battery Type:
Mature lithium-ion formulations dominate procurement volumes while emerging solid-state architectures compress transition timelines for next-generation platforms.
- Lithium-Ion:Lithium iron phosphate and nickel-manganese-cobalt cathodes deliver 200-300 Wh/kg densities with 2,000+ cycle stability. Demand concentrates in China's Jiangsu manufacturing corridor where MIIT GB standards enforce thermal runaway containment protocols, forcing cathode formulation upgrades.
- Nickel-Metal Hydride:Nickel-hydrogen chemistry retains cost-sensitive hatchback segments across Japan and South Korea where thermal tolerance outweighs energy density priorities. Toyota's continued procurement of cylindrical NiMH cells for compact hybrid platforms sustains regional production lines despite lithium-ion displacement elsewhere.
- Lead-Acid:Absorbent glass mat variants serve auxiliary power functions in commercial vehicle starter systems across India's BIS-regulated fleet electrification programs.
- Solid-State:Sulfide-based electrolyte prototypes from South Korean R&D clusters target premium SUV contracts with 400+ Wh/kg benchmarks and reduced thermal management overhead.
Lithium-ion handles the majority of throughput; solid-state is expanding most quickly on share as OEMs pre-position for chemistry transitions.
Vehicle Type:
Application scale varies dramatically across passenger and commercial segments, with pack sizing and duty cycles dictating cathode selection and thermal architecture.
- SUVs:Premium platforms in South Korea specify 3-5 kWh packs with silicon-carbon composite anodes to offset mass penalties from larger vehicle footprints. LG Energy Solution anchors cylindrical cell supply for this segment through dedicated production lines.
- Sedans:Mid-size passenger vehicles across China's Guangdong assembly corridor standardize prismatic lithium iron phosphate modules with blade battery architectures for space-efficient floor pan integration.
- Hatchbacks:Compact entry vehicles in cost-sensitive Indian and Southeast Asian markets retain nickel-metal hydride chemistry where BIS certification pathways favor established thermal management profiles.
- Commercial Vehicles:Fleet operators in Japan and South Korea procure 1-3 kWh mild-hybrid packs with high C-rate tolerance for urban delivery duty cycles and regenerative braking intensity.
SUVs command premium pricing per kWh; commercial vehicles are climbing the fastest on procurement volume as fleet electrification accelerates.
End User:
Customer type determines contract structure, with centralized fleet procurement displacing decentralized purchasing across major national markets.
- Fleet Operators:Centralized technical teams in South Korea's commercial vehicle segment now negotiate long-term service agreements embedding guaranteed cycle life thresholds rather than unit pricing, concentrating demand toward suppliers with validated performance data.
- Individual Users:Retail hybrid purchases across Japan's consumer market follow conventional OEM distribution through dealership networks with standardized pack warranties.
- Ride-Sharing Services:High-utilization platforms in India's urban centers prioritize fast-charging tolerant cathode formulations to minimize depot downtime.
- Taxi Services:Metered cab operators across Southeast Asian metropolitan areas favor nickel-metal hydride durability for stop-and-go traffic thermal profiles.
Fleet operators control the dominant procurement channel; ride-sharing services are gaining share fastest as mobility platforms consolidate vehicle assets.
Charging Method:
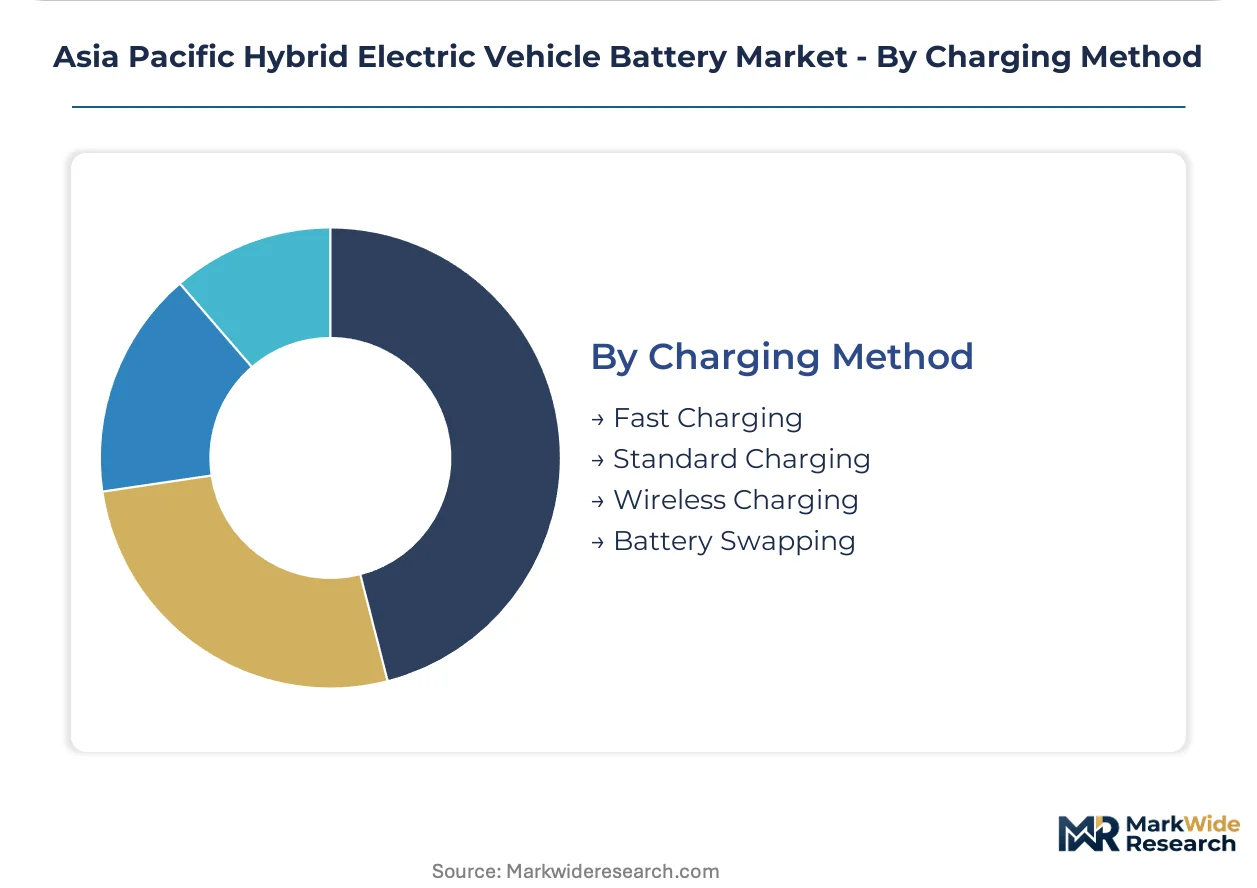
Infrastructure investment patterns across Japan and South Korea are redirecting cell procurement toward electrochemical systems compatible with accelerated energy replenishment.
- Fast Charging:4C-rate capable cathode formulations enable 15-minute depot replenishment for fleet operators in South Korea's commercial vehicle segment, requiring enhanced electrolyte stability and reduced lithium plating susceptibility.
- Standard Charging:Overnight AC charging dominates individual user behavior across residential settings in Japan, sustaining demand for conventional cycle-life optimized cell chemistries without extreme C-rate tolerance.
- Wireless Charging:Inductive pad systems in premium SUV segments across South Korea enable automated parking integration with reduced connector wear.
- Battery Swapping:Station-based exchange networks for taxi services in select Chinese metropolitan areas require standardized pack dimensions and connector protocols.
Fast charging infrastructure absorbs the majority of fleet-directed investment; wireless charging is advancing most quickly on technology readiness for premium applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese cell exports dominate trade flows into South Korean and Japanese OEM supply chains, while domestic absorption within Jiangsu and Guangdong manufacturing corridors absorbs the majority of regional cathode refining output.
China
MIIT dual carbon mandates force lithium iron phosphate adoption across domestic OEM procurement channels. GB/T 31485 safety testing protocols now require 5-minute no-fire thresholds under nail penetration conditions for market access. Cathode material refining clusters in Jiangsu province sit within 50 kilometers of BYD and CATL assembly plants, compressing logistics costs for blade battery architectures.
Japan
Toyota's sustained procurement of nickel-metal hydride cylindrical cells for compact hybrid platforms sustains domestic production lines against lithium-ion displacement. METI battery subsidy frameworks accelerate solid-state electrolyte R&D investments through coordinated public-private funding. Kanto region assembly plants concentrate prismatic module production for European-bound export programs.
South Korea
Premium SUV manufacturers specify silicon-carbon composite anode cylindrical cells to offset vehicle mass penalties. MFDS recycling mandates reshape end-of-life cost structures for multi-market suppliers operating across the region. Seoul Capital Area facilities anchor cylindrical cell expertise for domestic OEM contracts.
India
Fleet electrification programs in urban commercial vehicle segments drive 1-3 kWh mild-hybrid pack procurement from centralized technical teams. BIS certification requirements for automotive battery assemblies remain less stringent than Chinese GB protocols, creating first-mover pathways for certified entrants. Maharashtra and Gujarat manufacturing corridors concentrate domestic assembly capacity for cost-sensitive hatchback applications.
Thailand
Japanese OEM transplant facilities drive localized pack assembly for Southeast Asian export markets. Board of Investment incentive structures attract cathode material precursor investments from Chinese suppliers seeking tariff diversification. Eastern Economic Corridor industrial zones host module integration plants serving regional right-hand-drive vehicle demand.
Asia Pacific Hybrid Electric Vehicle Battery Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base organizes around three archetypes: integrated cathode-to-cell manufacturers, standalone pack assemblers, and technology licensors. Consolidation pressures concentrate around cylindrical and prismatic form factor standardization. Dominant competitive moves include backward integration into lithium carbonate refining and strategic partnerships for solid-state electrolyte development.
Within the integrated manufacturing tier, BYD Company Ltd and Contemporary Amperex Technology Co Ltd exemplify Chinese-origin players with captive cathode production capabilities. LG Energy Solution anchors South Korean cylindrical cell expertise for premium automotive contracts. These three entities occupy positions spanning the full value chain from material refining through module assembly, representing the dominant competitive configuration in regional procurement channels.
| Leading Market Players |
|---|
| BYD Company Ltd |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| Exide Industries Ltd |
| EnerSys |
| Contemporary Amperex Technology Co Ltd |
| SK Innovation Co Ltd |
| Samsung SDI |
| GS Yuasa International Ltd |
| Others |
Pricing and Supply Chain Analysis
Overcapacity signals in Jiangsu province's cathode refining corridor are forcing cell manufacturers to absorb margin compression while defending OEM contract volumes. This utilization dynamic accelerates pricing divergence between premium silicon-carbon formulations and legacy nickel-manganese-cobalt chemistries across Asia Pacific procurement channels.
Pricing Analysis
Technology-generation pricing gaps separate current-generation lithium iron phosphate packs from prior-generation nickel-metal hydride systems and next-generation solid-state prototypes. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under China's GB/T 31485 protocols and volume scale commitments from fleet operators. Cost compression in standard-tier cylindrical cells is intensifying because South Korean exporters face accelerated retooling investments to maintain China market eligibility. Fleet operators demonstrate lowest price sensitivity due to long-term service agreements embedding guaranteed cycle life thresholds, while individual retail purchasers in India's cost-sensitive hatchback segment exhibit highest elasticity.
Supply Chain Analysis
Extended payment terms from OEM procurement teams in South Korea are cascading upstream to cathode precursor suppliers, compressing working capital cycles across tier-two material refiners. Geographic supply concentration centers on China, South Korea, and Japan, with raw material dependencies drawing from Australian lithium spodumene, Chilean lithium carbonate, and Indonesian nickel laterite. Single-source vulnerability in Jiangsu-Guangdong cathode refining clusters creates exposure to localized MIIT policy shifts or environmental enforcement actions. Distribution runs through integrated cell-to-module manufacturers with captive logistics networks serving OEM assembly plants within 50-kilometer radii.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific hybrid battery procurement is fragmenting across chemistry-specific niches as fleet operators displace decentralized purchasing with centralized technical teams, creating entry pathways for specialized suppliers outside integrated manufacturing tiers.
For Market Incumbents: Entrench position through backward integration into lithium carbonate refining and silicon-carbon anode precursor production to defend against emerging Chinese cathode specialists. Prioritize GB standard certification maintenance for thermal runaway containment as MIIT tightens market access protocols, while expanding cylindrical cell capacity in Seoul Capital Area facilities to anchor premium SUV contracts against prismatic module competitors. For New Entrants and Emerging Players: India's BIS certification gap offers first-mover pathways for certified battery assemblers targeting Maharashtra and Gujarat fleet electrification programs with mild-hybrid pack architectures. White-space concentration sits in fast-charging tolerant cathode formulations for commercial vehicle depots, where C-rate performance requirements exceed capabilities of established nickel-metal hydride suppliers. Go-to-market execution should leverage performance-based contracting with guaranteed cycle life thresholds rather than unit pricing competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet operator service agreements with embedded cycle life guarantees and long-term cathode supply offtakes. Long-term viability across the projection horizon favors acquisition targets with validated 2,000+ cycle performance data and established OEM qualification timelines. Signal to monitor: solid-state electrolyte prototype announcements from South Korean R&D clusters indicating chemistry transition inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Carbon Anode Scale-Up | Enables 300+ Wh/kg density benchmarks for premium SUV contracts in South Korea. |
| GB Standard Certification Investment | Secures China market access under MIIT's 5-minute no-fire thermal runaway protocols. |
| Fleet Service Agreement Conversion | Locks in recurring revenue through guaranteed cycle life thresholds versus spot purchasing. |
| Cathode Precursor Backward Integration | Reduces lithium carbonate volatility exposure for cell manufacturers on fixed-price OEM contracts. |
| Solid-State Electrolyte R&D Partnership | Positions for 400+ Wh/kg hybrid pack adoption ahead of full-electric chemistry transitions. |
Research Methodology
A standing panel of cell manufacturing executives, OEM platform engineers, fleet procurement directors, and cathode material specialists provided ongoing calibration across the study period. Primary interview data combined with secondary validation from MIIT GB standard filings, METI subsidy disclosure documents, and BIS certification registries. Bottom-up cell shipment tracking across Jiangsu and Guangdong manufacturing corridors triangulated against top-down OEM production schedules.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling segmentation dimensions including battery chemistry type, vehicle architecture class, end-user procurement model, and charging infrastructure compatibility. CAGRs derived from regression analysis against fleet electrification program announcements and cathode capacity expansion timelines. Forecast inputs incorporated lithium carbonate price volatility bands and solid-state electrolyte technology readiness assessments.
Practitioners should monitor MIIT enforcement actions on thermal runaway containment, METI solid-state subsidy allocation shifts, and lithium carbonate spot price movements for early signals of forecast deviation. Projections reflect assumptions on chemistry transition timelines, fleet procurement consolidation rates, and regional regulatory convergence patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
North America Wireless Electric Vehicle Charging Market
Electric Vehicles
Electric Van Market
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
Central and Eastern Europe E-Bike Market
Electric Vehicles
US Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Electric Loader Rickshaw Market
Electric Vehicles
Europe Electric Scooter Market
Electric Vehicles
Middle East Wireless EV Charging Market
Electric Vehicles
Europe Electric Truck Market
Electric Vehicles
Solar Powered Electric Vehicle Market
Electric Vehicles
Mexico E-Bike Market
Electric Vehicles
Global Automotive Inductive Wireless Charging Systems Market
Electric Vehicles
France Hybrid Electric Vehicle Battery Market
Electric Vehicles
India E-Bike Market
Electric Vehicles
EV Taxi Market
Electric Vehicles
Two-Wheeled Electric Vehicle Battery Market