
 Oman EV Market | 2026-2036
Oman EV Market Size, Share, and Industry Trends Forecast 2026-2036
Oman EV Market Insights
A shift from single-source import dependency toward multi-source supply agreements is restructuring how international automakers establish presence in Oman. Tesla leverages its direct-to-consumer channel control to bypass traditional dealership networks. BMW AG anchors its positioning through premium after-sales infrastructure and localized service partnerships. MG Motor competes aggressively on price-accessible battery electric vehicle configurations tailored to fleet procurement cycles.
An electric vehicle is a road vehicle propelled by one or more electric motors drawing energy from rechargeable battery packs or hydrogen fuel cells, with power outputs typically ranging from 50 kW in compact urban models to over 500 kW in performance configurations, and energy densities in lithium-ion packs reaching 250-300 Wh/kg at the cell level. Battery electric vehicles dominate unit volume as fleet operators prioritize zero-emission compliance and total cost of ownership reduction over plug-in hybrid alternatives. Public charging stations represent the fastest-expanding infrastructure segment, though home charging stations retain margin concentration due to lower installation complexity and recurring hardware service attach rates.
Oman's Ministry of Transport, Communications and Information Technology collaborates with the Authority for Electricity Regulation to mandate building-code readiness for charging infrastructure in new commercial developments. The national utility, Nama Group, shapes demand through time-of-use tariffs that incentivize overnight fleet charging and grid-load balancing. Stakeholders must monitor how rapidly the sultanate's renewable energy procurement targets translate into green electrons available for vehicle charging contracts.
Market Dynamics
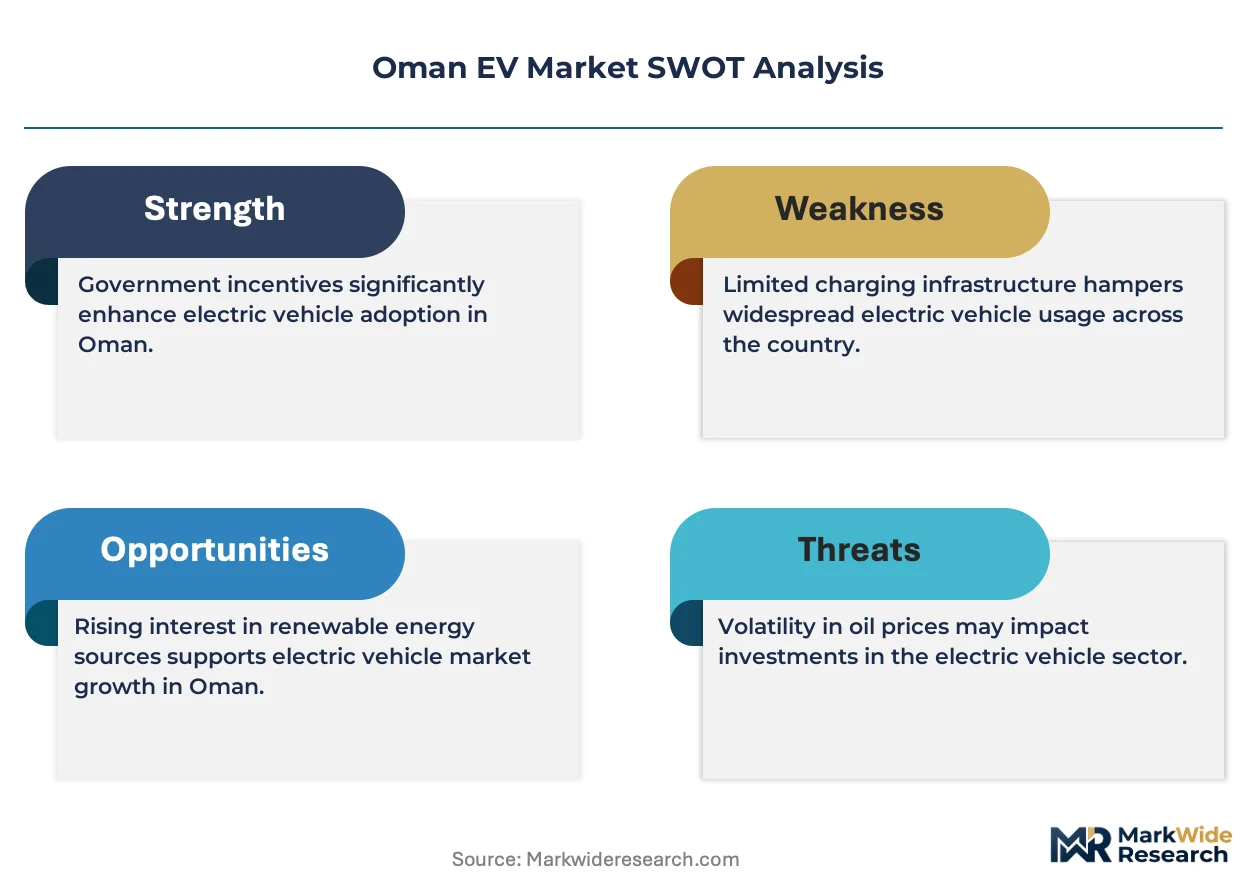
Fleet electrification mandates from Oman's Ministry of Transport are compressing procurement timelines for battery electric vehicles, forcing logistics operators to restructure capital deployment around charging infrastructure co-investment requirements.
Growth Catalysts
- Building-code readiness mandates:The Authority for Electricity Regulation requires new commercial developments to pre-install electrical capacity for charging stations, eliminating retrofit friction for fleet depots.
- Time-of-use tariff structures:Nama Group's overnight pricing incentives are electrifying fleet charging patterns toward grid-load-balancing schedules that reduce per-kilometer energy costs.
- Muscat corridor density:Commercial fleet concentration along the coastal logistics corridor concentrates demand visibility and enables shared infrastructure economics.
Market Restraints
- Lithium supply concentration:Cell-grade lithium hydroxide sourcing remains concentrated among a limited set of international refiners, exposing fleet operators to input cost volatility.
- Grid interconnection queues:Renewable energy project approvals for green electron procurement face procedural delays from the national utility's technical review protocols.
- Plug-in hybrid substitution:Fleet managers in remote interior routes continue specifying range-extended configurations where charging network coverage remains sparse.
Strategic Opportunities
- Sohar Port logistics zone:The industrial free zone adjacent to Oman's primary maritime gateway remains underpenetrated for dedicated fleet charging hubs serving transshipment operators.
- Solar-to-vehicle direct contracting:Utility-scale photovoltaic developers are structuring behind-the-meter supply agreements that bypass grid-tariff exposure for large fleet operators.
- Vehicle-to-grid integration:Bidirectional charging protocols are converging with smart inverter standards to create distributed storage revenue streams for fleet asset owners.
Industry Challenges
- High-voltage technician scarcity:The shortage of certified EV maintenance specialists is extending service turnaround times for commercial operators with uptime-dependent contracts.
- Multi-standard connector fragmentation:Fleet procurement teams face integration complexity when specifying charging hardware compatible with both European and Asian vehicle import portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman EV Market |
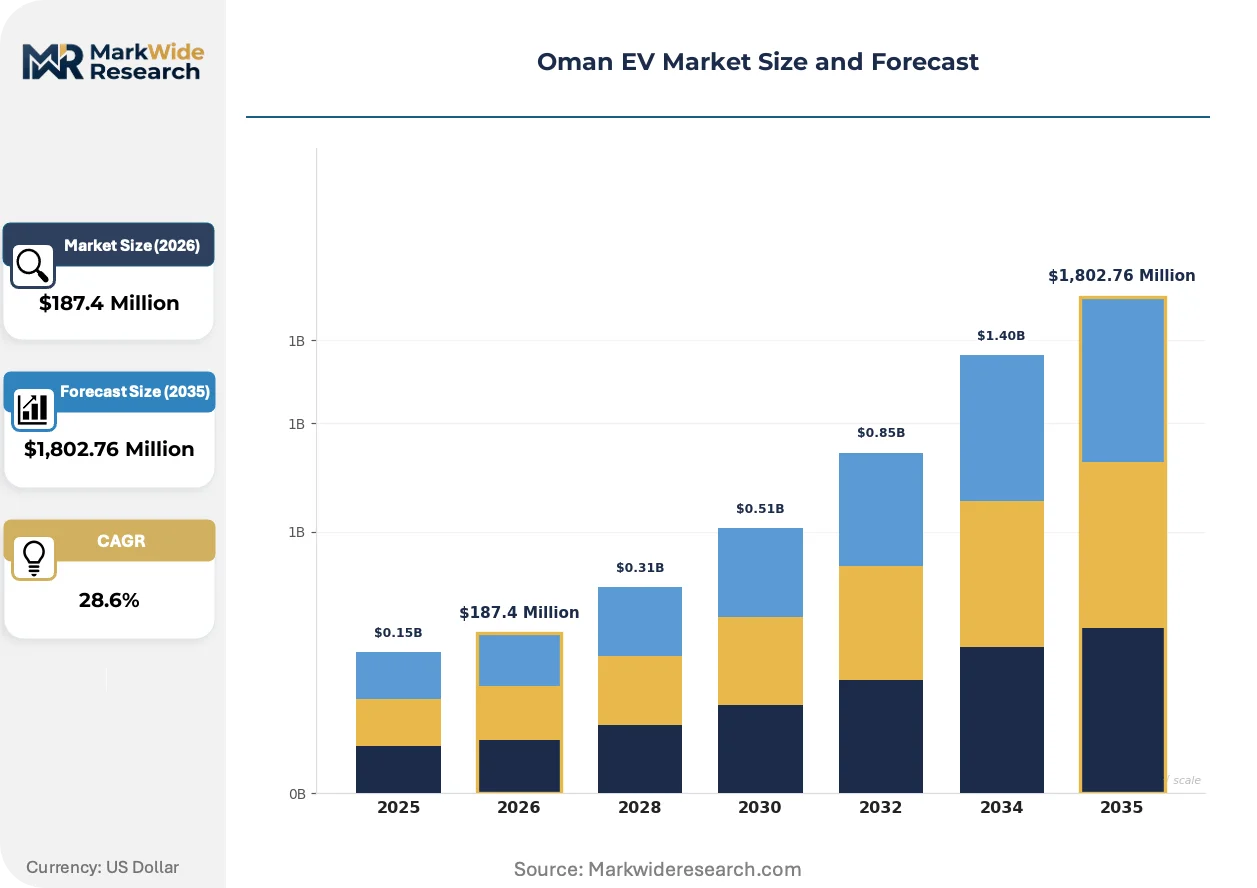
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Electric Vehicles, Plug-in Hybrid Electric Vehicles, Hybrid Electric Vehicles, Fuel Cell Electric Vehicles Charging Infrastructure: Home Charging Stations, Public Charging Stations, Fast Charging Stations, Wireless Charging Solutions End User: Individual Consumers, Fleet Operators, Government Agencies, Corporate Entities Battery Technology: Lithium-ion, Solid-state, Nickel-metal Hydride, Lead-acid |
| Companies Covered | Tesla, BMW AG, Renault Group, Hyundai Motor Company, Nissan Motor Corporation, Audi AG, BYD, MG Motor, Ford Motor Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman EV Market Trends and Innovations
Technology deployment in Oman's EV sector is accelerating around three vectors: battery chemistry evolution, regulatory mandates for infrastructure readiness, and procurement model restructuring among fleet buyers.
Lithium iron phosphate cell chemistry is electrifying commercial vehicle configurations by delivering extended cycle life under high-utilization fleet duty cycles. Logistics operators with daily kilometer thresholds above 300 km are specifying these configurations for their reduced degradation curves. The technology is electrifying total cost of ownership calculations toward battery-electric parity with diesel alternatives across five-year holding periods.
Oman's Authority for Electricity Regulation has issued technical specifications for AC and DC charging equipment interoperability that exceed baseline IEC standards. The mandate requires all public charging station deployments to support open-protocol payment systems and remote monitoring interfaces. Commercial real estate developers in Muscat and Salalah are responding by pre-wiring parking structures to these specifications ahead of tenant occupancy.
Fleet procurement committees are consolidating vendor relationships around full-service mobility contracts that bundle vehicles, charging infrastructure, and energy supply into single-source agreements. Traditional vehicle-only distributors are losing position to integrated providers offering guaranteed cost-per-kilometer structures. The shift is most visible among last-mile delivery operators in the capital region who prioritize operational expenditure predictability over capital ownership.
Oman EV Market Segmentation
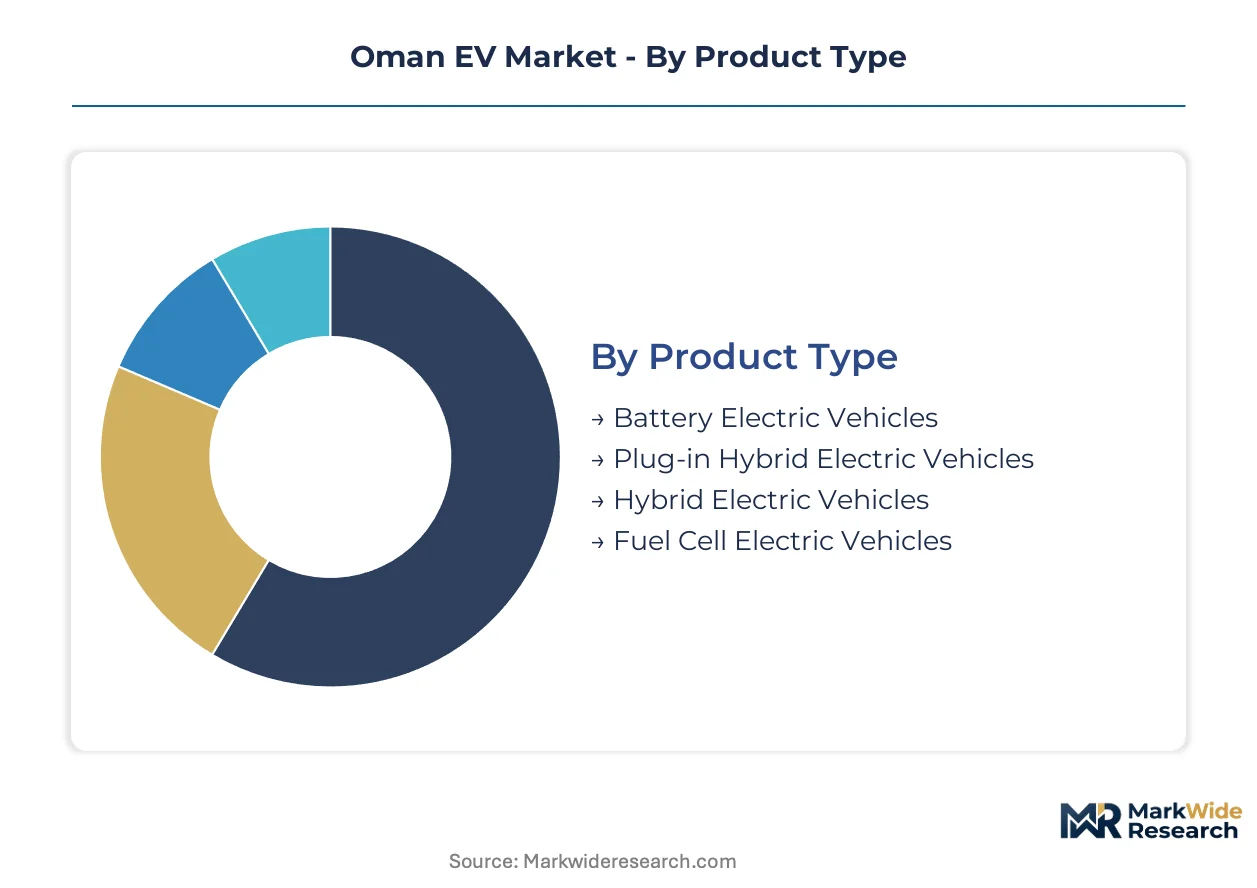
Fleet procurement patterns in Oman favor configurations with predictable total cost of ownership over consumer-oriented premium features. Segmentation reveals how commercial electrification mandates are reshaping demand concentration across vehicle categories, charging modalities, and battery chemistries.
Product Type:
Volume concentrates in battery-dominant configurations, while plug-in alternatives retain niche positioning for range-constrained routes.
- Battery Electric Vehicles:These configurations draw propulsion exclusively from rechargeable lithium-ion packs with power outputs spanning 50 kW to 500 kW. Fleet operators in Muscat's logistics corridor are specifying these for zero-emission compliance and overnight charging economics under Nama Group's time-of-use tariffs.
- Plug-in Hybrid Electric Vehicles:Range-extended architectures combine electric motors with combustion engines for dual-mode operation. Remote interior routes with sparse charging coverage continue driving procurement from operators serving Dhofar and Al Wusta governorates.
- Hybrid Electric Vehicles:Non-plug-in configurations with regenerative braking dominate transitional fleet trials.
- Fuel Cell Electric Vehicles:Hydrogen-fed systems remain pre-commercial in Oman's market.
Mature deployment sits with hybrid configurations serving established routes. Newer deployment is concentrated in battery electric vehicles for depot-based logistics.
Charging Infrastructure:
Installation complexity separates margin-rich home installations from scale-driven public networks.
- Public Charging Stations:Open-access AC and DC equipment governed by Authority for Electricity Regulation interoperability mandates. Muscat and Salalah commercial developers are pre-wiring parking structures to these specifications ahead of tenant fleet occupancy.
- Home Charging Stations:Lower-voltage residential installations with recurring hardware service contracts. Individual consumers in Oman's coastal corridor favor these for overnight replenishment of compact urban vehicles.
- Fast Charging Stations:High-power DC infrastructure for corridor mobility and commercial uptime requirements.
- Wireless Charging Solutions:Inductive pad systems for premium fleet applications.
Margin concentration favors home charging hardware and service attach rates. Scale expansion is accelerating most quickly in public station deployments along the Muscat-Sohar logistics axis.
End User:
Procurement authority separates centralized fleet decisions from distributed consumer purchases.
- Fleet Operators:Logistics and public transport entities with capital deployment structured around charging infrastructure co-investment. Last-mile delivery operators in the capital region are consolidating vendor relationships around full-service mobility contracts with guaranteed cost-per-kilometer structures.
- Government Agencies:Ministry of Transport pilot programs driving standardization through procurement volume. Municipal fleet electrification mandates are compressing tender timelines for battery electric bus and service vehicle configurations.
- Individual Consumers:Private purchasers with charging access through residential or workplace installations.
- Corporate Entities:Employee mobility and executive fleet programs with sustainability reporting requirements.
Procurement sophistication sits with fleet operators managing total cost of ownership calculations. Policy-driven deployment is expanding most rapidly through government agency mandates.
Battery Technology:
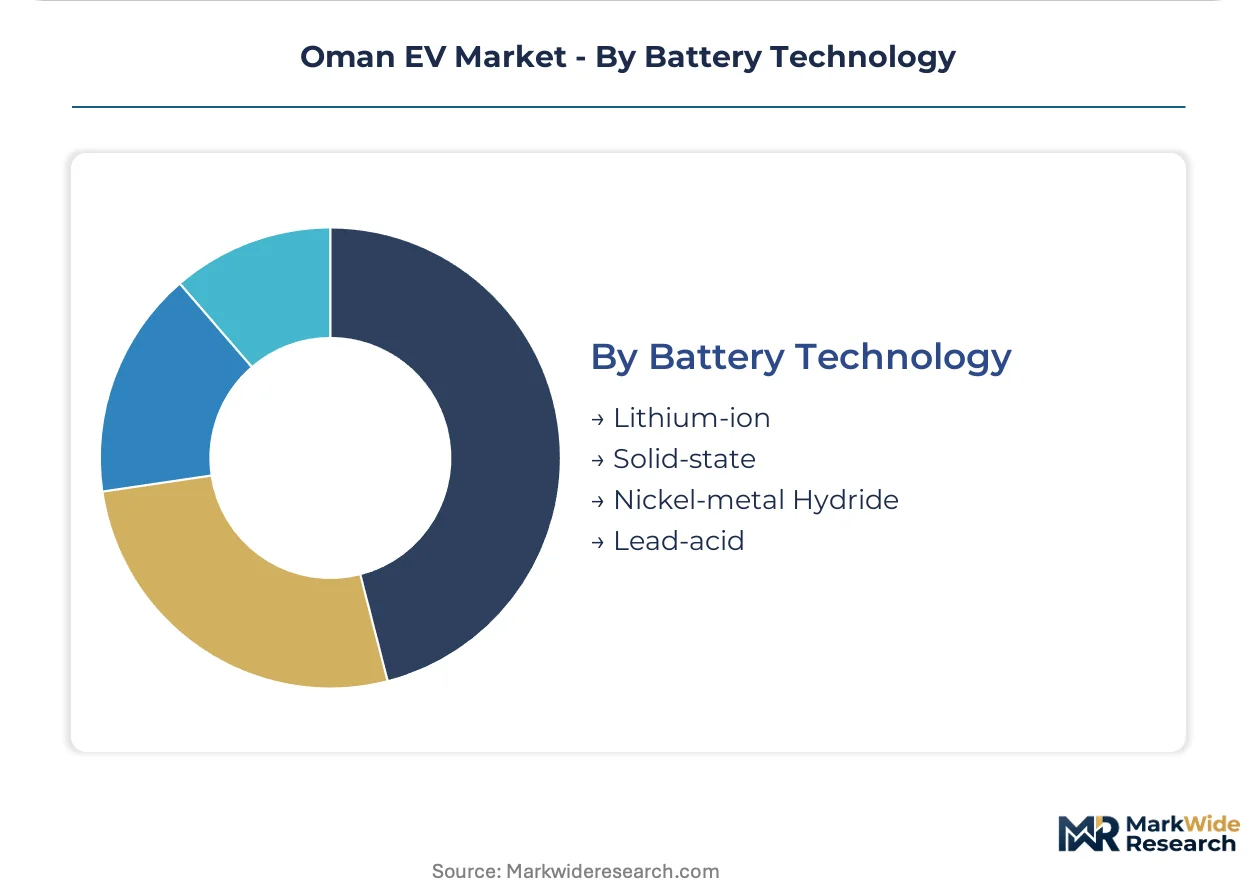
Cell chemistry selection trades cycle life against energy density for Oman's high-utilization commercial duty cycles.
- Lithium-ion:Dominant cell chemistry with energy densities reaching 250-300 Wh/kg at cell level. Fleet operators specifying daily thresholds above 300 km are adopting lithium iron phosphate variants for extended cycle life under depot charging regimens.
- Solid-state:Emerging ceramic-electrolyte configurations with enhanced thermal stability. Pre-commercial trials by Oman's utility-scale fleet operators are evaluating these for vehicle-to-grid integration protocols.
- Nickel-metal Hydride:Mature chemistry retaining position in hybrid vehicle applications.
- Lead-acid:Legacy technology constrained to auxiliary power and low-voltage systems.
Commercial maturity sits with lithium-ion configurations across all product categories. Technology transition is advancing most quickly in solid-state evaluation programs for next-generation fleet procurement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate refineries in the Al Sharqiyah region anchor Oman's emerging battery supply chain integration, with port infrastructure at Sohar and Duqm enabling raw material throughput for regional cell manufacturing.
Muscat Governorate
Commercial fleet density concentrates along the coastal logistics corridor connecting the capital to Sohar Port. The Authority for Electricity Regulation mandates building-code readiness for charging infrastructure in new commercial developments. Last-mile delivery operators in Ruwi and Ghala industrial zones are consolidating vendor relationships around full-service mobility contracts.
Al Batinah North and South
Sohar Port's industrial free zone drives transshipment operator demand for dedicated fleet charging hubs serving maritime logistics chains. Nama Group's time-of-use tariffs incentivize overnight depot charging patterns that reduce per-kilometer energy costs for freight operators. The Sohar-Barka corridor hosts the highest concentration of public DC fast charging deployments outside Muscat.
Dhofar Governorate
Remote interior routes with sparse charging coverage sustain plug-in hybrid procurement from operators serving Salalah's port hinterland. The Ministry of Transport's fleet electrification mandates compress tender timelines for municipal service vehicles in the regional capital. Salalah Free Zone developers are pre-wiring parking structures to Authority for Electricity Regulation interoperability specifications.
Ad Dakhiliyah Governorate
Nizwa's position as a logistics node for interior agricultural and mineral supply chains creates niche demand for range-extended commercial configurations. Grid interconnection queues for renewable energy projects face procedural delays from the national utility's technical review protocols. Local fleet operators prioritize total cost of ownership calculations over zero-emission compliance where charging infrastructure remains underdeveloped.
Al Wusta Governorate
The Duqm Special Economic Zone's industrial scale offers underpenetrated opportunity for solar-to-vehicle direct contracting structures that bypass grid-tariff exposure. Utility-scale photovoltaic developers are structuring behind-the-meter supply agreements for large fleet operators in the zone. Sparse population density limits consumer vehicle demand while concentrating commercial procurement around captive industrial fleets.
Oman EV Market Competitive Landscape
Strategic partnerships dominate the current landscape as international automakers establish localized service networks and energy supply agreements. The vendor base organizes around three tiers: direct-to-consumer specialists with channel control, premium incumbents leveraging after-sales infrastructure, and price-accessible volume players targeting fleet procurement cycles. Two archetypes anchor positioning: integrated mobility providers bundling vehicles with charging and energy contracts, and traditional distributors defending share through vehicle-only transactions. Capacity expansion in charging infrastructure and portfolio diversification into battery chemistry variants represent the dominant competitive vectors.
Within the direct-to-consumer tier, Tesla exemplifies channel control strategies that bypass traditional dealership networks entirely. BMW AG anchors premium positioning through localized after-sales partnerships in Muscat and Salalah. MG Motor occupies the price-accessible fleet tier with configurations tailored to commercial procurement cycles and total cost of ownership calculations. These three entities collectively represent the competitive archetypes reshaping vendor relationships across Oman's electrification transition.
| Leading Market Players |
|---|
| Tesla |
| BMW AG |
| Renault Group |
| Hyundai Motor Company |
| Nissan Motor Corporation |
| Audi AG |
| BYD |
| MG Motor |
| Ford Motor Company |
| Others |
Pricing and Supply Chain Analysis
Warranty-bundling divergence between integrated mobility providers and traditional vehicle distributors separates pricing architectures across Oman's EV procurement landscape. Fleet operators purchasing full-service contracts with guaranteed cost-per-kilometer structures accept premium pricing in exchange for uptime assurance and maintenance coverage, while unbundled vehicle-only transactions from conventional distributors compete on lower capital outlays with service costs transferred to buyer risk.
Pricing Analysis
Warranty and after-sales bundling distinguishes premium positioning from commodity procurement in Oman's fleet-dominated market. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under Authority for Electricity Regulation interoperability mandates and brand heritage premiums for European and Asian OEMs. Pricing pressure stems from MG Motor's aggressive fleet pricing and lithium input cost volatility transmitted through cell-grade hydroxide contracts. Last-mile delivery operators in Muscat exhibit highest price sensitivity due to thin margin structures, while government agencies prioritize compliance over cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with cell-grade lithium hydroxide refining concentrated among Chinese, Australian, and Chilean processors. Battery pack assembly draws from South Korean and Japanese cell manufacturers, with power electronics sourcing anchored in Taiwan and Germany. Tariff exposure on European vehicle imports creates margin compression for BMW AG and Renault Group distributors. Distribution runs through Sohar Port's industrial free zone for fleet depot direct delivery, bypassing traditional dealership inventory holding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oman's EV market operates as a cost-of-compliance arena where Authority for Electricity Regulation building-code mandates and Nama Group tariff structures erect barrier-to-entry moats favoring players with capital for infrastructure co-investment and regulatory certification.
For Market Incumbents: Hedge against lithium iron phosphate substitution by securing multi-year cell supply agreements with Korean and Chinese manufacturers before procurement cycle consolidation locks in vendor relationships. Expand charging infrastructure ownership in Sohar Port's underpenetrated logistics zone to capture transshipment operator demand. Defend margin position by embedding vehicle-to-grid capability into fleet contracts ahead of bidirectional charging standardization.
For New Entrants and Emerging Players: Launch via solar-to-vehicle direct contracting models in Duqm Special Economic Zone, bypassing grid-tariff exposure that constrains incumbent pricing flexibility. Target Al Wusta Governorate's captive industrial fleets with behind-the-meter photovoltaic supply agreements. Exploit high-voltage technician scarcity by building certified service partnerships with Nama Group's training programs.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated mobility providers given fleet procurement consolidation toward full-service contracts. Long-term viability favors archetypes with vertical control over charging infrastructure and energy supply. Monitor solid-state battery trial outcomes by Oman's utility-scale fleet operators as inflection signal for next-generation chemistry transitions.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Multi-year lithium iron phosphate contracts with Korean cell manufacturers secure fleet procurement cycle participation. |
| Charging Infrastructure Partnership | Collaboration with Sohar Free Zone developers captures transshipment operator demand before competitor saturation. |
| Vehicle-to-Grid Integration | Bidirectional charging protocols with Nama Group smart inverter standards create distributed storage revenue streams. |
| Backward Integration into Solar | Behind-the-meter photovoltaic development in Duqm bypasses grid-tariff exposure for large fleet operators. |
| Certification Investment | Authority for Electricity Regulation interoperability compliance exceeds baseline IEC standards for public charging deployment. |
Research Methodology
Independent corroboration across fleet procurement directors, charging infrastructure developers, and utility planning officers underwrites the qualitative findings in this study. Primary interviews with logistics operators in Muscat and Sohar, commercial real estate developers, and Nama Group tariff specialists combined with secondary validation from Authority for Electricity Regulation technical specifications, customs import records, and renewable energy procurement databases. Bottom-up fleet deployment tracking and top-down infrastructure investment analysis triangulate volume estimates.
Rate-of-change decomposition across vehicle class, propulsion architecture, battery chemistry, and charging modality dimensions structures the analytical framework. CAGRs derive from segment-level deployment trajectories weighted by fleet operator procurement timelines and government mandate implementation schedules. Forecast inputs incorporate lithium iron phosphate cycle life assumptions under high-utilization duty cycles and Authority for Electricity Regulation interoperability mandate compliance rates.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook. Forecasts reflect assumptions about grid interconnection queue resolution and renewable energy procurement contract availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
US Automotive High Performance Electric Vehicle Market
Electric Vehicles
Luxury Electric Vehicle Market
Electric Vehicles
Lithium Battery Electric Scooters Market
Electric Vehicles
France E-Bike Market
Electric Vehicles
Electric Light Commercial Vehicle Lithium-Ion Battery Market
Electric Vehicles
Norway Electric Vehicle Market
Electric Vehicles
China Automotive High Performance Electric Vehicle Market
Electric Vehicles
China Electric Bus Market
Electric Vehicles
North America Electric Bus Market
Electric Vehicles
Electric Transporters Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market
Electric Vehicles
EV Thermal Management System Market
Electric Vehicles
Global Electric Vehicles Market
Electric Vehicles
Global Electric Scooters Market
Electric Vehicles
Electric Bicycle Market
Electric Vehicles
Electric Vehicle Control Unit Market