
 Asia-Pacific Electric Vehicle (EV) Fluids Market | 2026-2036
Asia-Pacific Electric Vehicle (EV) Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Electric Vehicle (EV) Fluids Market Analysis
Fleet operator procurement across Southeast Asia is broadening beyond early adopter metros into second-tier logistics hubs. Idemitsu Kosan Co., Ltd. leverages its refinery network to secure feedstock access across Japan and Thailand. Shell plc anchors its position through integrated lubricant-coolant formulations designed for tropical thermal regimes. Sinopec Corp. dominates domestic distribution channels within China's state-linked fleet electrification programs.
Asia-Pacific electric vehicle fluids comprise thermally engineered liquid formulations—typically dielectric coolants with low electrical conductivity below 0.1 μS/cm and synthetic lubricants with tailored viscosity indices—designed to manage heat rejection, reduce friction, and prevent electrical shorting in electrified powertrains. Coolants command the largest product volume pool due to battery thermal management requirements, while brake fluids extract premium pricing from regenerative braking system compatibility demands. Powertrain applications outpace engine cooling in growth velocity as motor-inverter architectures displace conventional thermal loops across OEM assembly lines.
China's MIIT enforces GB standards for battery thermal management fluids, while Japan's METI coordinates JIS lubricant specifications through METI-certified testing protocols. Australia's TGA-aligned state regulators impose chemical disclosure rules affecting coolant import formulations. Stakeholders must track how India's BIS adoption of IEC thermal-fluid benchmarks reshapes supplier qualification timelines across the subcontinent.
Market Dynamics
Battery thermal management requirements are compressing fluid formulation cycles as OEMs migrate from air-cooled to liquid-cooled pack architectures across China's industrial corridor cities.
Growth Catalysts
- MIIT GB Standards:China's mandatory battery thermal management fluid specifications are forcing domestic OEMs to upgrade coolant specifications, creating qualified supplier slots for certified formulators.
- Fleet Electrification Mandates:Southeast Asian logistics operators face binding emissions reduction targets that accelerate EV procurement and attached fluid service contracts.
- Dielectric Coolant Chemistry:Synthetic ester-based formulations with sub-0.1 μS/cm conductivity are penetrating motor-inverter cooling loops previously served by conventional glycols.
Market Restraints
- Feedstock Concentration:Polyalphaolefin base oil supply clusters in Northeast Asian refineries, exposing formulators to regional outage risk and freight cost volatility.
- Technical Limitation:Existing dielectric fluids degrade thermal performance above 150°C, constraining silicon carbide inverter integration in performance EV platforms.
- Regulatory Friction:Australia's TGA-aligned chemical disclosure rules force reformulation of imported coolants, extending qualification timelines by 8-14 months.
Strategic Opportunities
- India BIS Adoption:India's pending alignment with IEC thermal-fluid benchmarks will unlock supplier qualification pathways for formulators with existing European certifications.
- Second-Tier Logistics Hubs:Indonesian and Vietnamese provincial freight terminals are electrifying ahead of metro saturation, opening service-contract whitespace.
- Integrated Lubricant-Coolant Systems:Convergence of motor bearing lubrication and inverter cooling into single-loop architectures favors suppliers with cross-functional formulation expertise.
Industry Challenges
- Electrochemical Compatibility Certification:Validating fluid-copper-aluminum interactions in battery cold plates requires 18-24 month OEM-specific test protocols.
- Thermal Engineer Scarcity:Formulators struggle to recruit specialists fluent in both heat transfer physics and battery cell electrochemistry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Electric Vehicle (EV) Fluids Market |
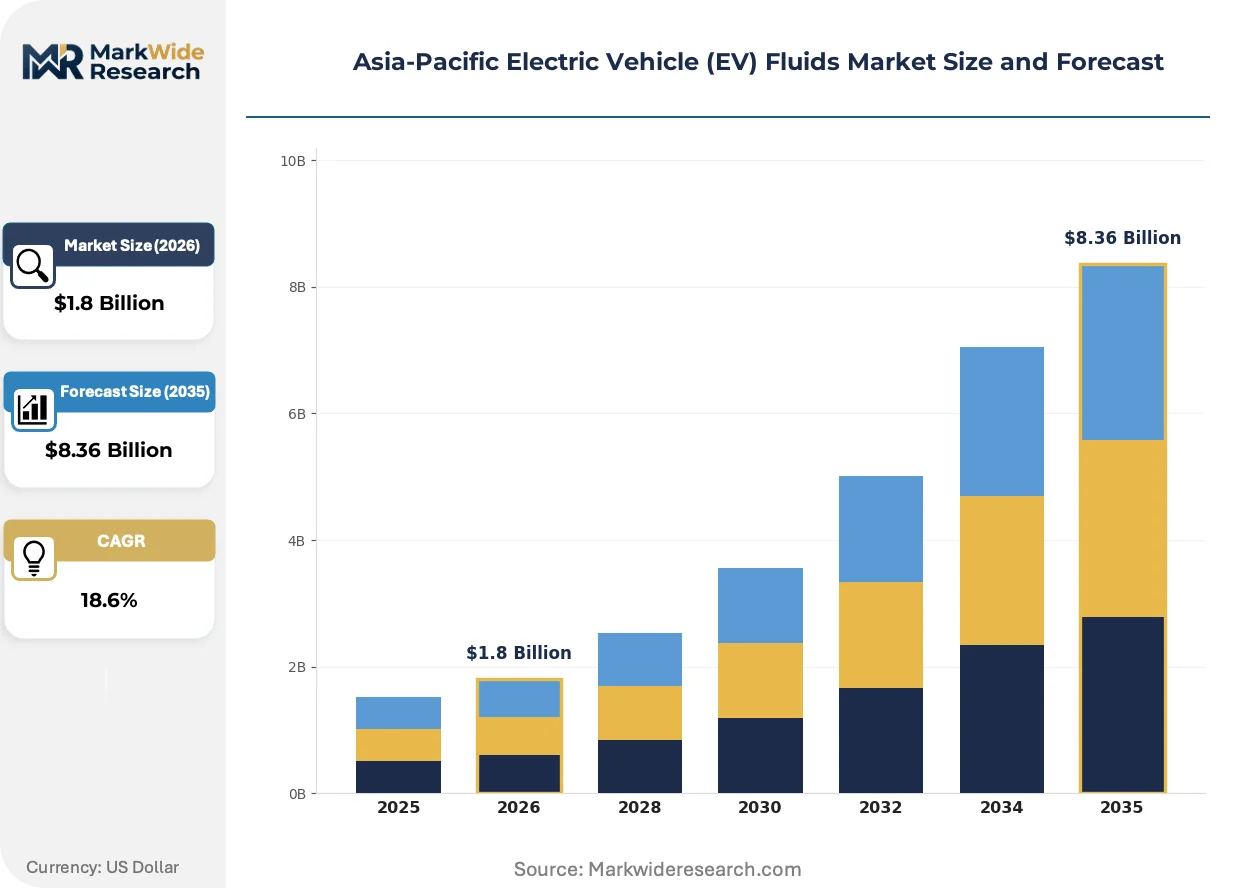
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coolants, Lubricants, Brake Fluids, Transmission Fluids Application: Battery Cooling, Engine Cooling, Brake Systems, Powertrain Delivery Mode: Direct Sales, Online Retail, Distributors, Wholesalers End User: Fleet Operators, OEMs, Aftermarket Services, Individual Owners |
| Companies Covered | FUCHS Petrolub SE, Idemitsu Kosan Co., Ltd., Shell plc, Petronas Lubricants International, Sinopec Corp., ExxonMobil Corporation, ENEOS Corporation, Castrol, TotalEnergies SE, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Electric Vehicle (EV) Fluids Market Emerging Trajectories
Synthetic base stocks and additive packages are evolving faster than specification cycles can codify, creating temporary performance premiums for first movers.
Single-phase dielectric coolants with tailored viscosity-temperature curves are overtaking two-phase vapor chamber systems in volume applications. Chinese battery gigafactories are specifying these fluids for pack-level thermal uniformity. This transition is overtaking incumbent glycol-water formulations in motor cooling loops as OEMs consolidate fluid SKUs.
Japan's METI is tightening JIS lubricant specifications for electrified powertrains through certified testing protocols that mandate 10,000-hour oxidation stability. Domestic formulators must retest entire product lines. Powertrain applications face the steepest compliance burden as motor bearing lubricants fall under expanded scope.
Fleet operators are consolidating fluid procurement under direct OEM service agreements rather than aftermarket distributors. Southeast Asian logistics companies now contract coolant replenishment through vehicle lease providers. Thailand and Vietnam exhibit the fastest migration toward bundled fluid-life-cycle contracts.
Asia-Pacific Electric Vehicle (EV) Fluids Market Segmentation
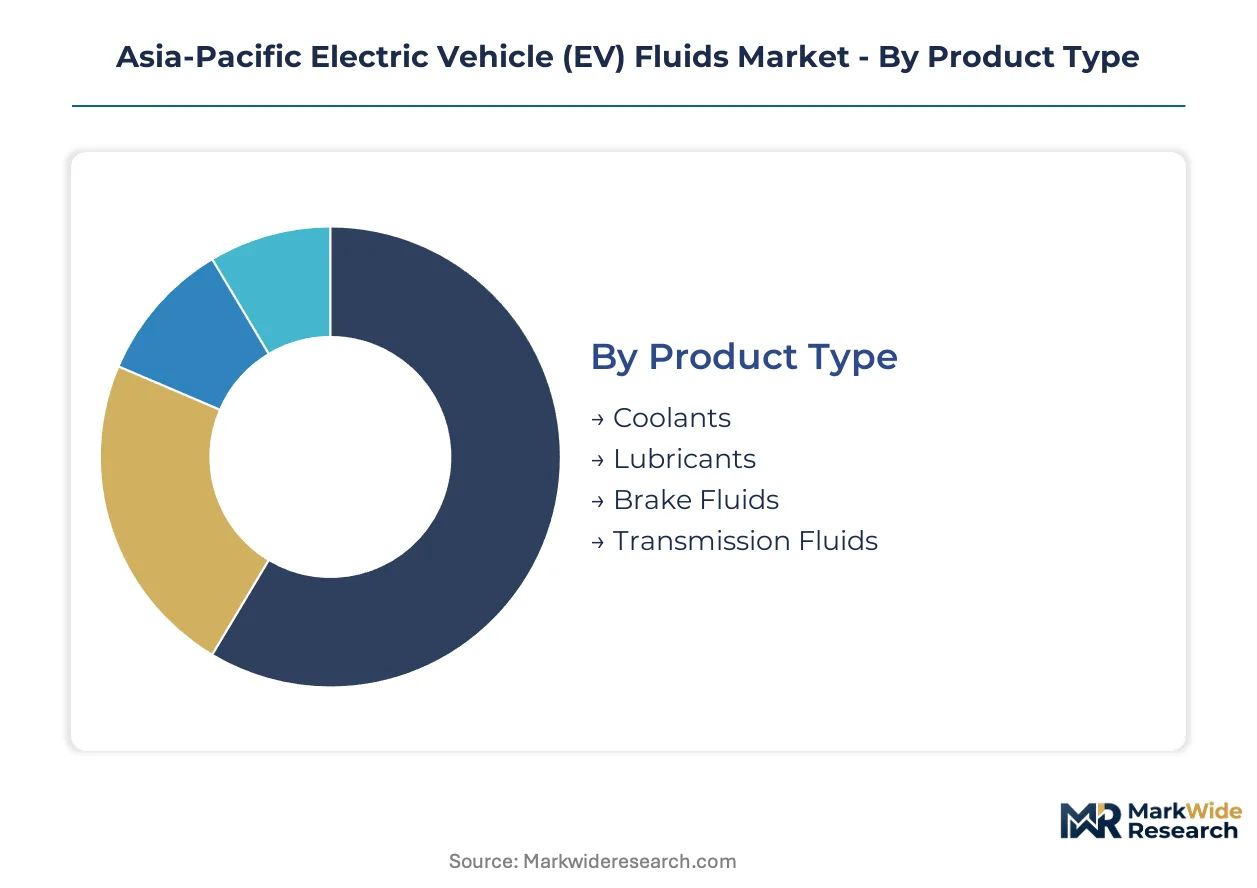
Segmentation in the Asia-Pacific EV fluids market reveals how regulatory certification burdens concentrate in specific product categories while application-driven demand shifts reshape procurement patterns across the region's battery manufacturing corridors.
Product Type:
MIIT GB standards impose tiered certification requirements across product categories, with dielectric coolants facing the most stringent conductivity and thermal stability testing protocols.
- Coolants:Dielectric formulations with sub-0.1 μS/cm conductivity dominate battery thermal management loops. China's industrial corridor cities anchor demand as liquid-cooled pack architectures displace air-cooled systems across domestic OEM assembly lines. MIIT certification timelines stretch 14-18 months for new entrants.
- Lubricants:Synthetic base stocks with tailored viscosity indices serve motor bearing and reduction gear applications. Japan's METI-certified testing protocols mandate 10,000-hour oxidation stability, forcing domestic formulators into full product line retesting. Southeast Asian fleet operators specify these fluids through bundled service contracts.
- Brake Fluids:Low-viscosity synthetic formulations compatible with regenerative braking systems extract premium positioning. Australia's TGA-aligned disclosure rules extend qualification timelines for imported formulations.
- Transmission Fluids:Single-fluid architectures for integrated motor-transmission units reduce SKU complexity. Thai and Vietnamese logistics hubs drive specification convergence as fleet electrification accelerates.
Coolants sit at the top of the volume ranking, with dielectric lubricants climbing the fastest as motor-inverter cooling loops consolidate fluid requirements.
Application:
Application segmentation tracks how thermal management priorities shift from legacy engine architectures toward electrified powertrain components across the region's manufacturing base.
- Battery Cooling:Pack-level thermal uniformity specifications from Chinese battery gigafactories are compressing formulation cycles. Single-phase dielectric fluids with tailored viscosity-temperature curves are overtaking two-phase vapor chamber systems in volume procurement.
- Powertrain:Motor-inverter architectures displace conventional thermal loops across OEM assembly lines. India's pending BIS alignment with IEC thermal-fluid benchmarks will reshape supplier qualification pathways for formulators with existing European certifications.
- Engine Cooling:Declining application as full-electric platforms eliminate internal combustion thermal loops. Remaining demand concentrates in hybrid transition vehicles across Indonesian provincial freight networks.
- Brake Systems:Regenerative braking integration requires fluid compatibility with electronic control modules. Southeast Asian fleet operators specify through direct OEM service agreements rather than aftermarket channels.
Battery cooling commands the steepest expansion trajectory, while powertrain applications gain share fastest as motor bearing lubrication converges with inverter cooling requirements.
Delivery Mode:
Delivery channel segmentation reflects procurement consolidation trends as fleet operators bypass traditional distribution tiers in favor of integrated service agreements.
- Direct Sales:OEM service agreements now dominate fleet procurement across Thailand and Vietnam. Bundled fluid-life-cycle contracts consolidate coolant replenishment under vehicle lease provider relationships.
- Distributors:Regional chemical distributors retain position in aftermarket service networks. Feedstock concentration in Northeast Asian refineries exposes channel partners to regional outage risk and freight cost volatility.
- Online Retail:Limited penetration due to technical specification complexity and certification documentation requirements. Individual owner segments in Australia's TGA-aligned regulatory environment face chemical disclosure barriers.
- Wholesalers:Declining share as procurement shifts toward specification-driven direct relationships. Remaining volume concentrates in second-tier logistics hub service depots.
Direct sales lead channel value capture, with distributor relationships contracting fastest as fleet electrification mandates reshape procurement authority.
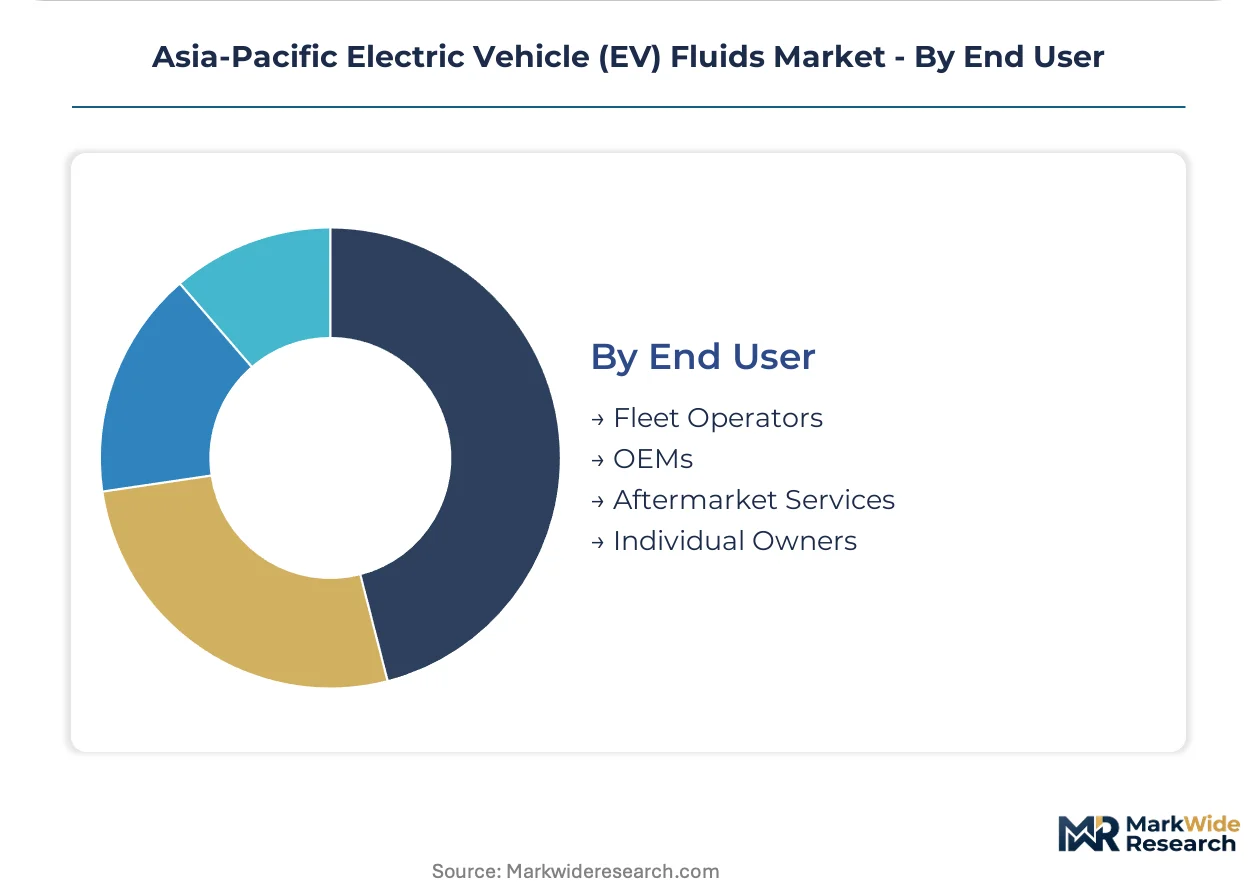
End User:
End user segmentation maps how procurement authority is migrating from vehicle owners toward fleet operators and OEM-linked service providers across the region's electrification corridors.
- Fleet Operators:Binding emissions reduction targets across Southeast Asia are accelerating EV procurement and attached fluid service contracts. Indonesian and Vietnamese provincial freight terminals are electrifying ahead of metro saturation, opening service-contract whitespace.
- OEMs:State-linked fleet electrification programs in China concentrate domestic distribution channel control. Electrochemical compatibility certification for fluid-copper-aluminum interactions in battery cold plates requires 18-24 month OEM-specific test protocols.
- Aftermarket Services:Consolidating under direct OEM service agreements as fleet operators centralize procurement. Technical limitation of existing dielectric fluids above 150°C constrains service portfolio expansion in performance EV platforms.
- Individual Owners:Smallest segment with limited specification influence. Australia's TGA-aligned chemical disclosure rules force reformulation awareness among import-dependent owner segments.
Fleet operators represent the dominant demand concentration, with OEM service agreements expanding most quickly as procurement authority centralizes under electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands battery-grade coolant volume while Japan concentrates premium synthetic lubricant formulation expertise, creating divergent procurement patterns across the region's electrification corridors.
China
MIIT GB standards for battery thermal management fluids enforce 14-18 month certification timelines for new entrants. State-linked fleet electrification programs concentrate procurement authority through domestic distribution channels. Shenzhen and Dongguan anchor demand as liquid-cooled pack architectures displace air-cooled systems across OEM assembly lines.
Japan
METI-certified testing protocols mandate 10,000-hour oxidation stability for electrified powertrain lubricants, forcing domestic formulators into full product line retesting. Nagoya and Osaka industrial zones concentrate motor bearing lubricant demand. Synthetic base stock suppliers face compressed formulation cycles as JIS specifications tighten.
India
BIS adoption of IEC thermal-fluid benchmarks will unlock supplier qualification pathways for formulators with existing European certifications. Delhi-NCR and Maharashtra host emerging battery assembly operations requiring dielectric coolant validation. Provincial freight terminals in Gujarat and Karnataka are electrifying ahead of metro saturation.
Thailand
Fleet electrification mandates from the national transport authority accelerate EV procurement and attached fluid service contracts. Bangkok and Laem Chabang logistics hubs drive bundled fluid-life-cycle contract migration. Japanese and Chinese lubricant suppliers compete for direct OEM service agreements.
Australia
TGA-aligned state regulators impose chemical disclosure rules forcing reformulation of imported coolants and extending qualification timelines by 8-14 months. Melbourne and Sydney concentrate aftermarket service network consolidation. Dielectric fluid imports face documentation barriers affecting individual owner segments.
Asia-Pacific Electric Vehicle (EV) Fluids Market Vendor Landscape
Chinese producers anchor one tier; Japanese specialists hold premium lubricant formulation positions. The market structures around three tiers: state-linked domestic suppliers with distribution control, multinational oil majors with integrated refinery-formulation networks, and regional specialists with tropical climate expertise. Competitive moves concentrate on backward integration into synthetic base stock production and certification-driven portfolio diversification.
Among Japan-based formulators, Idemitsu Kosan Co., Ltd. and ENEOS Corporation exemplify refinery-anchored supply security. Shell plc and FUCHS Petrolub SE occupy positions within the multinational tier, representing integrated lubricant-coolant formulation capabilities. Sinopec Corp. sits within the state-linked domestic tier, anchoring distribution channel control through China's industrial corridor procurement networks.
| Leading Market Players |
|---|
| FUCHS Petrolub SE |
| Idemitsu Kosan Co., Ltd. |
| Shell plc |
| Petronas Lubricants International |
| Sinopec Corp. |
| ExxonMobil Corporation |
| ENEOS Corporation |
| Castrol |
| TotalEnergies SE |
| Others |
Supply Flow & Price Mechanics
China's state-linked fleet electrification programs concentrate procurement authority among domestic OEMs and battery gigafactories, anchoring contract-based long-term offtake as the dominant pricing model across dielectric coolant and synthetic lubricant categories.
Pricing Analysis
Capacity additions in Northeast Asian refineries are reshaping price floors for polyalphaolefin base oils. Three-tier pricing structure across premium, standard, and economy levels separates MIIT-certified formulators from uncertified regional suppliers from commodity glycol blenders. Cost compression in the standard tier is intensifying because Indonesian and Vietnamese fleet operators are consolidating procurement under bundled service contracts. Aftermarket distributors exhibit the highest price sensitivity, while Chinese battery gigafactories prioritize certification grade over unit cost.
Supply Chain Analysis
MIIT certification timelines stretching 14-18 months gate supplier qualification and fragment downstream access. Feedstock supply draws from China, South Korea, and Japan, with polyalphaolefin base oils, synthetic ester stocks, and additive packages forming critical input dependencies. Single-source vulnerability concentrates around Northeast Asian refinery clusters exposed to regional outage risk. Distribution runs through direct OEM service agreements that displace traditional wholesale tiers across Thailand and Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story: Southeast Asian fleet operators are shifting procurement toward dielectric formulations with sub-0.1 μS/cm conductivity and 10,000-hour oxidation stability certification.
For Market Incumbents: Acquire synthetic base stock production capacity to secure feedstock access against Northeast Asian refinery concentration risk. Defensive consolidation should prioritize backward integration into ester chemistry capabilities and certification investment for India's pending BIS-IEC alignment. Emerging regional specialists with tropical climate formulation expertise represent the primary competitive threat to multinational positions. For New Entrants and Emerging Players: India's BIS adoption of IEC thermal-fluid benchmarks opens a window for formulators holding existing European certifications to enter before domestic qualification pathways mature. White-space targets include second-tier logistics hubs in Gujarat and Karnataka, plus integrated lubricant-coolant system architectures for motor-inverter cooling loops. Go-to-market positioning should emphasize bundled fluid-life-cycle contracts rather than aftermarket distribution. For Investors and Strategic Acquirers: National oil companies with refinery-anchored supply security are the most active acquirer in this space. Long-term viability favors targets with cross-functional formulation expertise spanning dielectric coolants and synthetic lubricants. Watch for inflection when silicon carbide inverter platforms exceed 150°C thermal thresholds and force next-generation fluid development cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Base Stocks | Captive supply of polyalphaolefin feedstock insulates formulators from Northeast Asian refinery outage risk. |
| MIIT Certification Investment | GB standard compliance unlocks supplier slots within China's state-linked fleet electrification programs. |
| Integrated Lubricant-Coolant System Development | Single-loop architectures for motor-inverter cooling consolidate SKU requirements and raise switching costs. |
| India BIS Qualification Pathway | Early IEC benchmark alignment positions formulators for supplier approval before domestic certification timelines compress. |
| Bundled Fluid-Life-Cycle Contracts | Direct OEM service agreements in Thailand and Vietnam displace aftermarket distributors and capture recurring revenue. |
Methodological Framework
Multiple input streams — executive interviews with thermal management engineers, procurement leads at Chinese battery gigafactories, and distribution channel partners across Southeast Asia — were reconciled against customs trade data, MIIT certification registries, and SEC filings from listed chemical producers. Bottom-up volume modeling triangulated with top-down market sizing across product type, application, and delivery mode segmentation.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use powertrain architecture, OEM procurement tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year estimates. Industry-specific forecast inputs incorporated liquid-cooled pack architecture migration rates and fleet electrification mandate compliance timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden MIIT specification revisions or silicon carbide inverter thermal threshold breakthroughs. A model refresh is warranted upon material change in India's BIS adoption schedule or Northeast Asian refinery capacity utilization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Luxembourg E-Bike Market
Electric Vehicles
E-Bike Accessories Market
Electric Vehicles
North America Electric Vehicle Battery Market
Electric Vehicles
Lawn Mower Battery Market
Electric Vehicles
Solar Golf Cart Market
Electric Vehicles
Electric Vehicle Liquid-Cooled Charging Connector Market
Electric Vehicles
North America Electric Vehicle Thermal Management System Market
Electric Vehicles
Japan Electric Vehicle Market
Electric Vehicles
India Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Skateboard Chassis Market
Electric Vehicles
Europe Electric Light Commercial Vehicles Market
Electric Vehicles
North America Electric Vehicle (EV) Fluids Market
Electric Vehicles
ASEAN E-Bike Market
Electric Vehicles
North America Electric Truck Market
Electric Vehicles
Japan Electric Car Market
Electric Vehicles
Japan Solar E-Bike Market