
 Europe Electric Scooter Market | 2026-2036
Europe Electric Scooter Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Scooter Market Intelligence
Modular battery-swapping configurations is broadening buyer choice across commuter and commercial segments. Govecs AG anchors its position through dedicated commercial-grade chassis platforms optimized for delivery workflows. BMW Motorrad differentiates via premium engineering heritage transferred into compact urban mobility formats. Silence specializes in removable battery architecture that reduces downtime for fleet operators managing high-utilization schedules.
An electric scooter comprises a lightweight motorized two-wheeler powered by an electric drivetrain, typically integrating a hub motor, lithium-based energy storage, and regenerative braking systems within a frame designed for single-rider urban transit. Its primary commercial purpose centers on reducing last-mile congestion and emissions in dense metropolitan environments. Folding scooters lead volume distribution due to apartment storage constraints and multimodal transit integration across European rail networks. Li-ion battery configurations command the structural margin pool as energy density improvements and the EU Battery Regulation's due diligence requirements elevate technical barriers. Rental services represent the fastest-expanding end user channel, driven by city concession contracts and software-integrated fleet management platforms.
The EU's L-category vehicle-type approval framework and the Battery Regulation establish mandatory safety, traceability, and recycling standards that shape product development timelines and market access conditions. ECHA's REACH restrictions on hazardous substances further constrain material selection for frames and electronic components. National regulators including Germany's KBA and France's ANSM enforce localized compliance protocols that fragment homologation pathways. Stakeholders must monitor evolving subsidy taper schedules and infrastructure allocation decisions as municipalities recalibrate micromobility priorities.
Market Dynamics
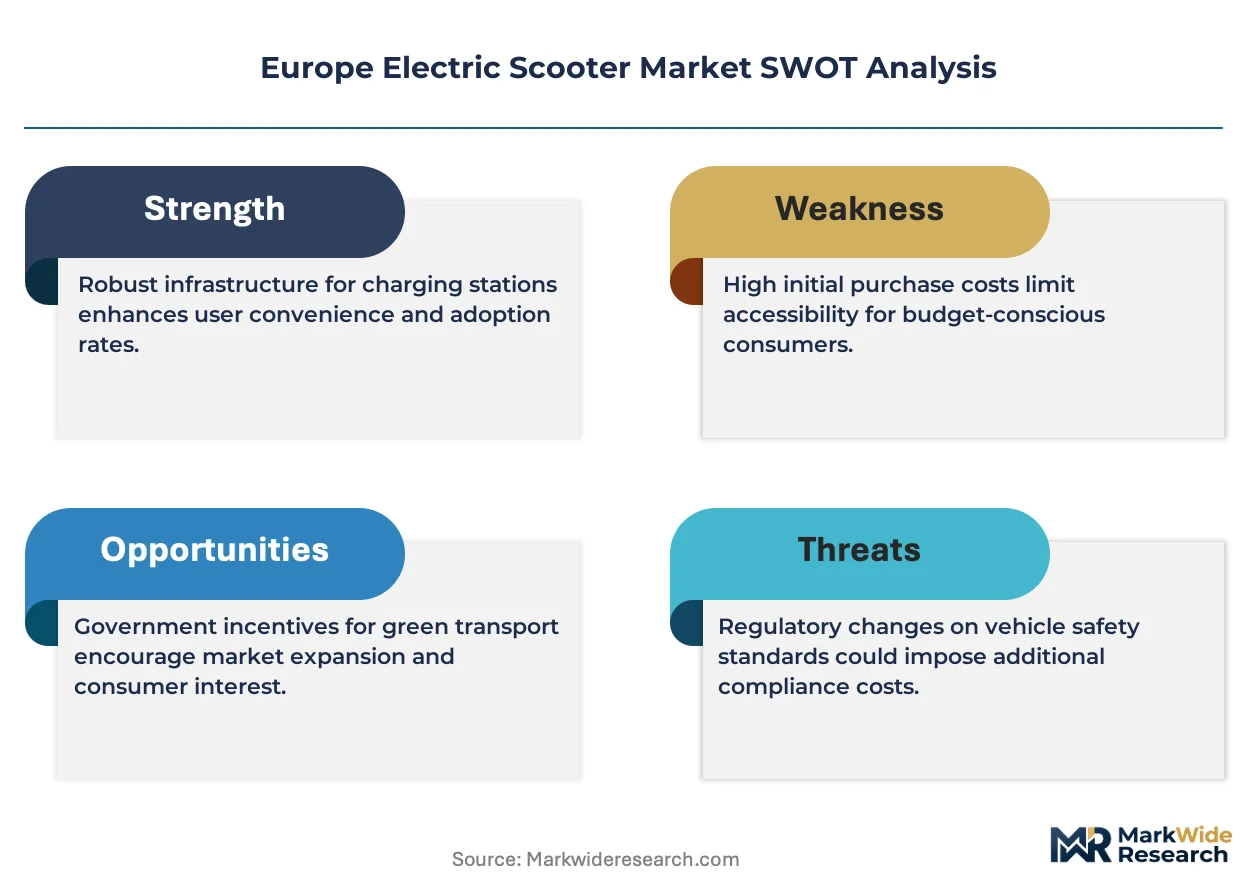
The EU's L-category vehicle-type approval framework and Battery Regulation are compressing product development timelines while elevating compliance costs, forcing manufacturers to redesign chassis architectures and battery management systems ahead of enforcement deadlines.
Growth Catalysts
- Low-Emission Zones:Municipal congestion pricing in Paris, Berlin, and Amsterdam is redirecting commuter traffic toward electric two-wheelers. Fleet operators are expanding shared micromobility contracts to capture displaced car trips.
- REACh Material Standards:ECHA's hazardous substance restrictions are accelerating frame material substitution toward recycled aluminum and bio-composites. Component suppliers are certifying alternative chemistries to maintain market access.
- Rail-First Mile Connectivity:Deutsche Bahn and SNCF infrastructure investments are creating multimodal transfer points where folding scooters integrate with regional transit. Commuter adoption concentrates around stations with secure parking facilities.
Market Restraints
- Lithium Price Volatility:Cathode material cost swings are compressing gross margins on entry-tier models. Manufacturers are hedging through long-term offtake agreements with Portuguese and Finnish refiners.
- Homologation Fragmentation:Germany's KBA and France's ANSM enforce divergent testing protocols for braking performance and lighting visibility. Dual certification requirements extend time-to-market by four to six months.
- Pedestrian Safety Liability:Sidewalk collision incidents are triggering municipal insurance mandates and speed limit reductions. Shared fleet operators face premium escalation and operating zone contraction.
Strategic Opportunities
- Eastern European Expansion:Warsaw and Prague cycling infrastructure investments are creating first-mover advantages before subsidy programs mature. Local assembly partnerships reduce import duty exposure.
- Commercial Delivery Electrification:Last-mile logistics operators in Milan and Barcelona are replacing thermal mopeds with swappable-battery scooters. Silence and Govecs are configuring chassis for thermal box integration.
- EU Battery Passport Integration:The Battery Regulation's traceability mandate is opening software and verification service revenue streams. Third-party auditors are certifying supply chain documentation for OEMs.
Industry Challenges
- Embedded Systems Talent Scarcity:VCU firmware and BMS algorithm development requires automotive-grade engineering expertise. Startups compete with incumbent Tier-1 suppliers for limited Central European talent pools.
- Homologation Backlog:Notified body capacity constraints under the L-category framework are delaying type approvals. Manufacturers are pre-submitting documentation and engaging early technical consultations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Scooter Market |
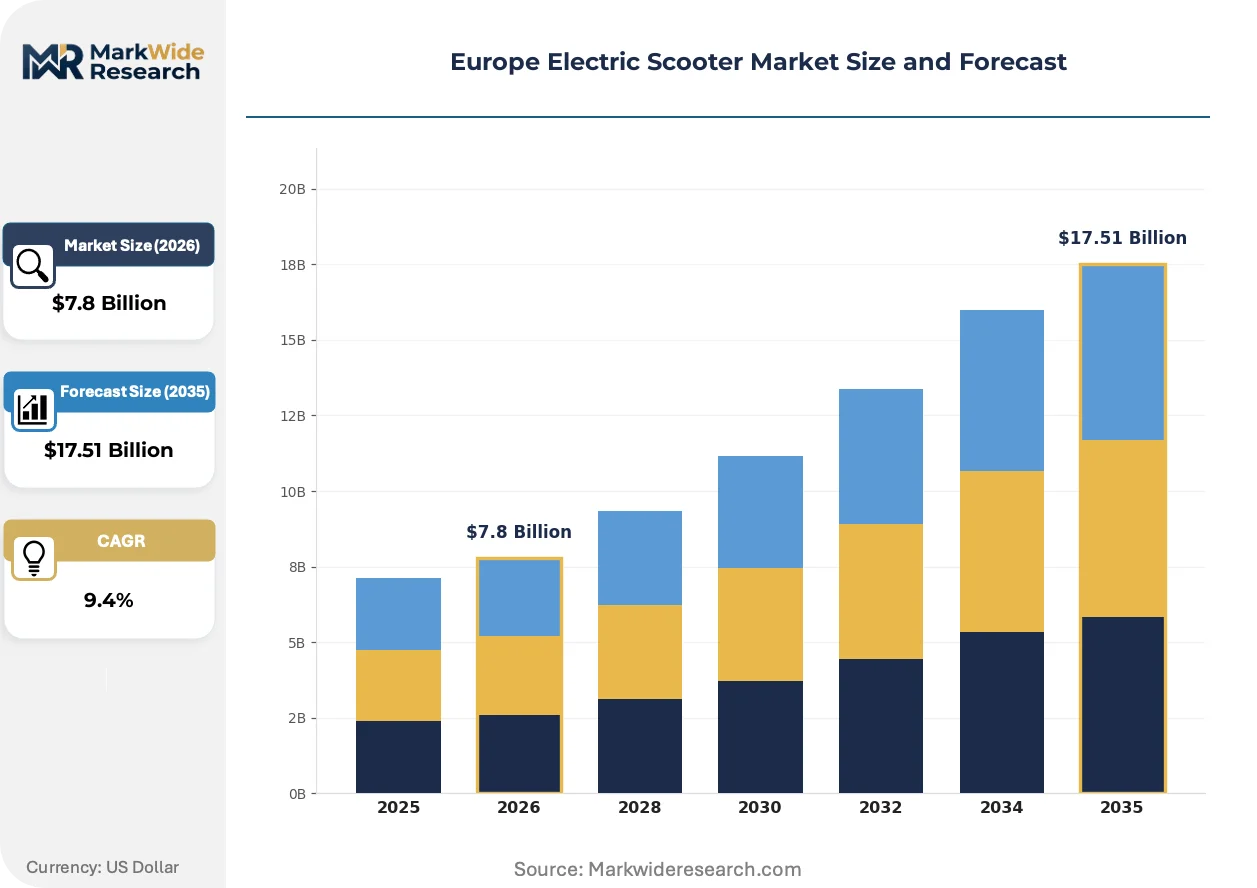
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-up Scooters, Folding Scooters, Self-balancing Scooters, Kick Scooters Battery Type: Li-ion, Lead Acid, NiMH, Others End User: Commuters, Delivery Services, Rental Services, Leisure Users Maximum Speed: 15 km/h, 25 km/h, 30 km/h, 40 km/h |
| Companies Covered | Govecs AG, Energica Motor Company S.p.A., Super Soco, Niu Technologies, BMW Motorrad, Silence, Vespa, Riese & Muller GmbH, myStromer AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Scooter Market Strategic Shifts & Innovations
Product architecture is fragmenting into specialized configurations for distinct use cases, while regulatory traceability requirements and shifting procurement patterns are reconfiguring competitive advantage around software integration and fleet management capabilities.
Battery pack design is modularizing around standardized cell formats and swappable docking mechanisms. Commercial fleet operators in Madrid and Lisbon are specifying hot-swap configurations to eliminate charging downtime. This architecture is modularizing service models away from unit sales toward utilization-based contracts with maintenance bundling.
The EU Battery Regulation's due diligence and recycling quotas are mandating supply chain documentation from raw material extraction through end-of-life collection. OEMs are integrating blockchain verification and partnering with Nordic recyclers to meet recovery rate thresholds. Premium commuter segments are absorbing compliance costs through feature differentiation, while price-sensitive categories face margin compression.
Corporate procurement departments are consolidating micromobility contracts under mobility-as-a-service platforms. Large employers in Munich and Copenhagen are substituting company car allowances with subsidized shared fleet subscriptions. Southern European markets lag this transition due to weaker public transit integration and lower employer benefit standardization.
Europe Electric Scooter Market Segmentation
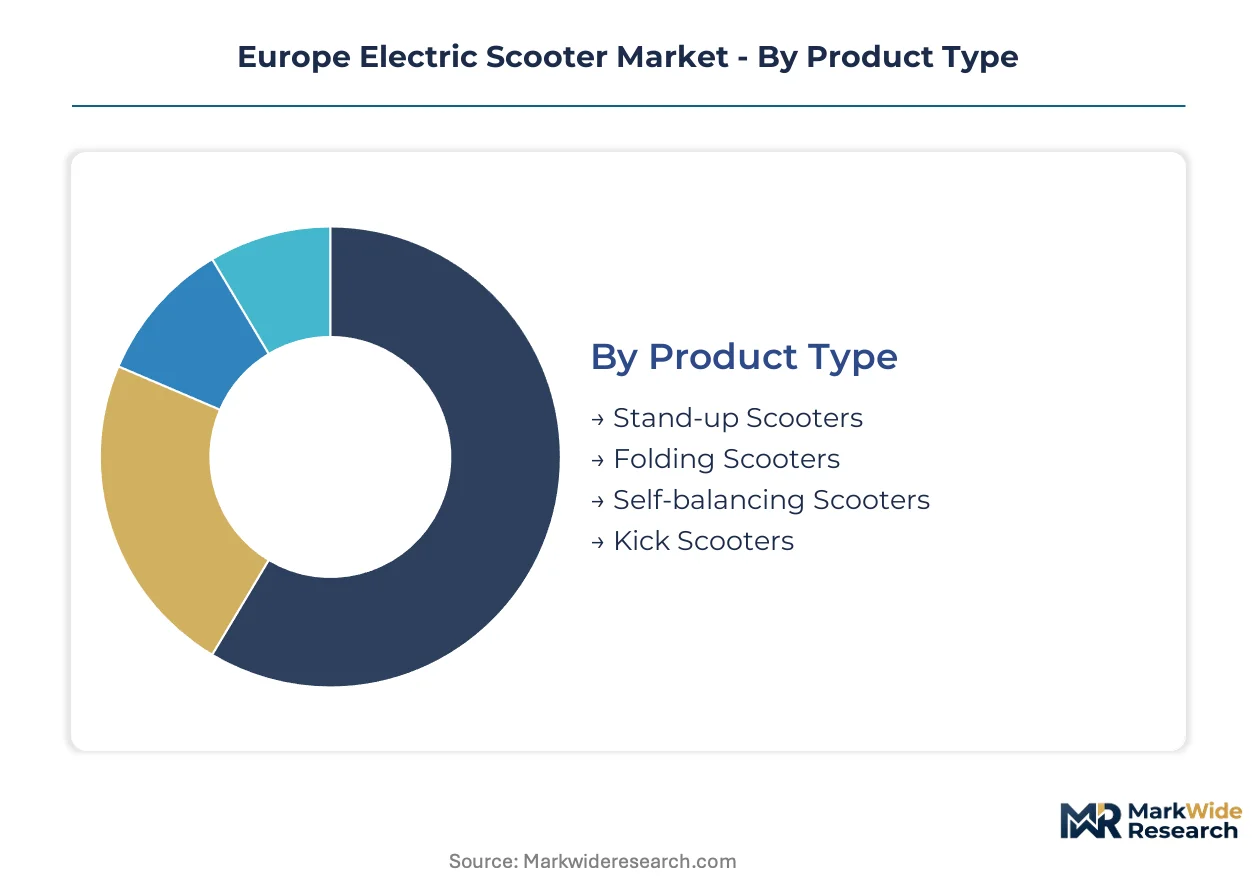
Segmentation in the Europe Electric Scooter Market reveals how regulatory boundaries, infrastructure constraints, and usage intensity create distinct product-positioning zones. Manufacturers configure chassis architectures, battery capacities, and software stacks differently across these divisions to match compliance requirements and customer willingness to pay.
Product Type:
Integration depth varies sharply across this category, with some formats designed for standalone last-mile operation while others embed into multimodal transit chains.
- Folding Scooters:Hinged stem-and-deck mechanisms collapse to briefcase dimensions for apartment storage and train compartment stowage. Demand clusters around Deutsche Bahn and SNCF station catchments in Germany and France where commuters face parking scarcity.
- Stand-up Scooters:Fixed-frame designs prioritize structural rigidity and larger battery enclosures for extended range. Fleet operators in Paris and Amsterdam specify these for all-day commercial utilization where portability is secondary to durability.
- Self-balancing Scooters:Gyroscopic stabilization systems target recreational users and campus environments with controlled speed limits.
- Kick Scooters:Human-powered bases with optional electric assist appeal to price-sensitive entry buyers and youth segments in Southern European markets.
Folding scooters lead volumes today; stand-up configurations are gaining share fastest in commercial fleet procurement.
Battery Type:
Cost tier stratification dominates here, with chemistry choices directly determining vehicle price positioning and operating economics.
- Li-ion:NMC and LFP cell formats deliver energy densities above 250 Wh/kg, enabling 40-60 km ranges within compact pack volumes. Premium commuter and fleet segments in the Netherlands and Denmark absorb the cell cost premium for weight reduction and cycle life.
- Lead Acid:Flooded and AGM configurations persist in price-sensitive Southern European retail channels where purchase price outweighs total cost of ownership considerations.
- NiMH:Intermediate chemistry occupies niche positions in legacy product lines and specific cold-climate applications.
- Others:Solid-state and sodium-ion prototypes are entering validation programs for next-generation platforms.
Li-ion dominates revenue contribution; lead acid retains volume presence in discount retail.
End User:
Application intensity separates this category, from sporadic leisure deployment to continuous commercial utilization.
- Rental Services:Shared micromobility operators deploy swappable-battery fleets under municipal concession agreements in Berlin, Paris, and Barcelona. Software-integrated fleet management and dynamic rebalancing algorithms determine unit economics.
- Delivery Services:Last-mile logistics operators in Milan and Madrid replace thermal mopeds with electric scooters configured for thermal box integration and rapid battery exchange.
- Commuters:Individual purchasers prioritize folding mechanisms and theft-resistant design for daily multimodal trips.
- Leisure Users:Weekend and recreational riders drive seasonal demand spikes with lower utilization rates and price sensitivity.
Rental services lead deployment scale; delivery services are expanding most quickly as logistics electrification accelerates.
Maximum Speed:
Regulatory compliance thresholds structure this category, with national speed limits fragmenting homologation pathways.
- 25 km/h:The EU L-category type-approval ceiling for unlicensed operation creates the largest addressable market. Manufacturers optimize motor controllers and firmware to enforce this limit across Germany, France, and Benelux markets.
- 15 km/h:Pedestrian-zone compatibility specifications in select French and Belgian municipalities drive demand for throttled configurations.
- 30 km/h:Moped-equivalent classifications requiring registration and insurance attract commercial operators seeking throughput efficiency.
- 40 km/h:L3e category approvals target interurban commuters with motorcycle licensing credentials.
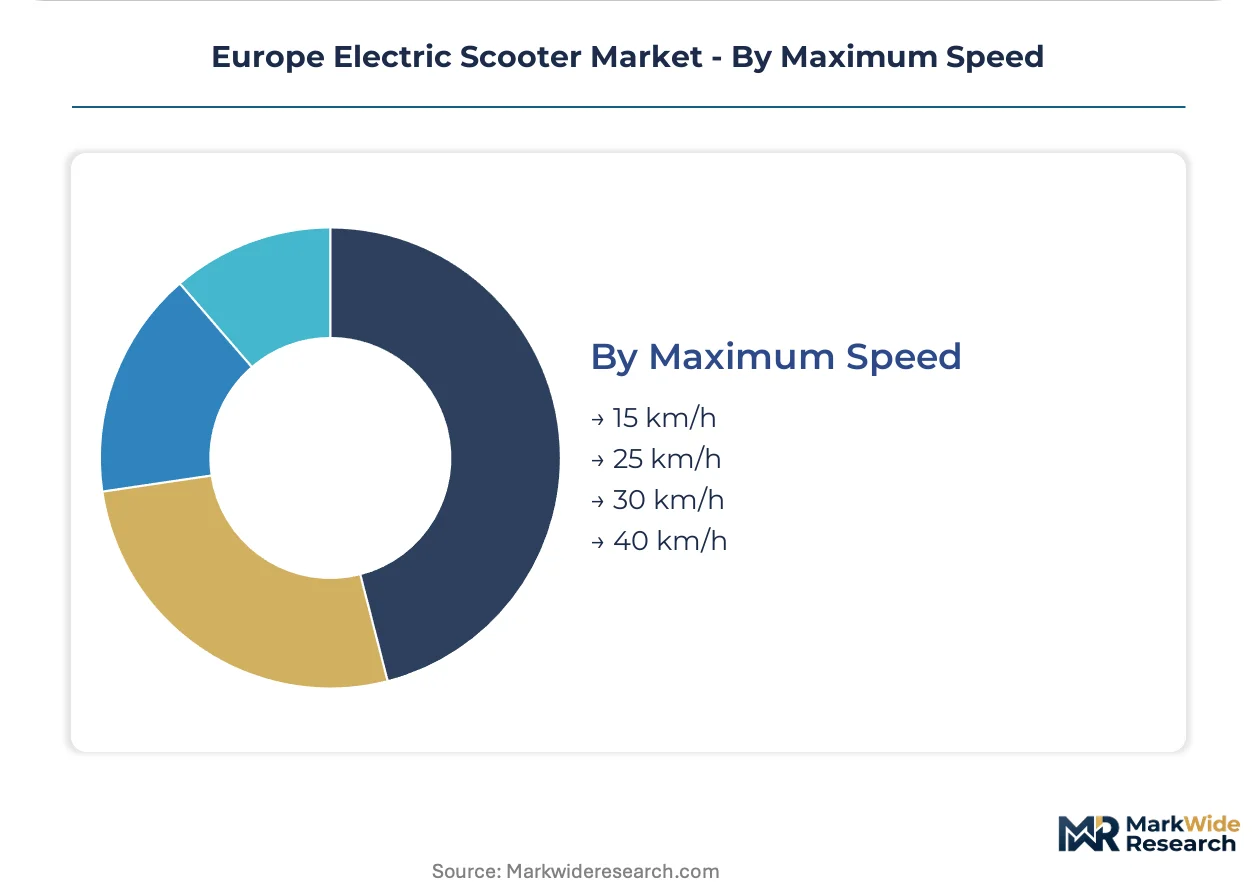
25 km/h configurations lead unit volumes; 30 km/h variants are climbing the fastest in commercial delivery specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric scooter manufacturing first scaled in Germany through automotive supplier networks repurposing precision engineering capabilities. France and the Netherlands followed with cycling infrastructure investments that created early adoption clusters. Today national regulatory frameworks and municipal procurement patterns fragment growth trajectories across the continent.
Germany
Deutsche Bahn's multimodal integration investments drive commuter adoption around regional rail nodes. KBA enforces stringent L-category type-approval protocols that extend homologation timelines. Berlin and Munich concentrate shared fleet deployments where operators negotiate municipal concession agreements.
France
Parisian low-emission zone expansion redirects urban traffic toward electric two-wheelers. ANSM maintains divergent braking performance standards from neighboring jurisdictions. The Île-de-France region anchors commercial delivery electrification as logistics operators replace thermal mopeds.
Netherlands
Cycling path density and intermodal station design create natural scooter integration points. National regulators align with EU Battery Regulation traceability mandates ahead of enforcement deadlines. Randstad municipalities bundle micromobility subsidies with employer benefit programs.
Spain
Barcelona and Madrid fleet operators specify swappable-battery configurations for continuous commercial utilization. Municipal insurance mandates respond to pedestrian safety incidents in dense historic centers. Southern European price sensitivity sustains lead-acid presence in retail channels.
Italy
Milan's last-mile logistics electrification accelerates thermal moped replacement programs. Legacy two-wheeler manufacturing clusters in the north supply component ecosystems. Regional subsidy schedules lag Northern European maturity, delaying individual purchaser adoption.
Europe Electric Scooter Market Key Industry Players
Premium-margin players sit above commodity-margin players across engineering heritage and fleet management software integration. The vendor base concentrates around three strategic tiers: automotive heritage brands transferring manufacturing discipline, pure-play electric specialists optimizing battery architecture, and Asian-scale manufacturers exploiting cell cost advantages. Consolidation pressure intensifies as compliance costs under EU Battery Regulation and L-category frameworks favor entities with dedicated homologation teams. Dominant competitive moves include strategic partnerships with municipal fleet operators and backward integration into battery pack assembly.
Within the commercial-grade chassis tier, Govecs AG and Silence exemplify specialization around delivery workflow optimization. BMW Motorrad occupies a position transferring premium automotive engineering into compact urban formats. These three entities anchor distinct competitive vectors: fleet operator partnerships, removable battery service models, and heritage-brand positioning.
| Leading Market Players |
|---|
| Govecs AG |
| Energica Motor Company S.p.A. |
| Super Soco |
| Niu Technologies |
| BMW Motorrad |
| Silence |
| Vespa |
| Riese & Muller GmbH |
| myStromer AG |
| Others |
Cost & Logistics Intelligence
Captive battery pack assembly in Germany and Poland anchors supply positioning while insulating premium-tier manufacturers from cell cost volatility. This integration choice concentrates pricing power with entities controlling BMS firmware and thermal management IP, forcing commodity assemblers to absorb margin compression from lithium cathode fluctuations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates heritage-brand engineering from fleet-optimized configurations and discount retail imports. Certification grade under EU L-category frameworks and after-sales service bundling drive price differentiation. Cost compression in entry-tier models is intensifying because Portuguese and Finnish refinery offtake agreements face cathode material competition. Fleet operators exhibit lowest price sensitivity due to utilization-based contract economics, while Southern European individual purchasers remain most responsive to purchase price.
Supply Chain Analysis
Freight cost escalation from Asia-to-Europe container routes is accelerating regional cell finishing investments. Cell supply concentrates in China, South Korea, and Japan, while pack assembly and chassis fabrication cluster in Germany, Poland, and Romania. The supply chain rests on NMC cathode powders, aluminum extrusions, and semiconductor motor controllers. Single-source vulnerability in BMS chipsets from Taiwanese foundries threatens production continuity. Distribution runs through OEM direct sales for fleet contracts and specialized micromobility retailers for individual purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Electric Scooter Market reads as a late-cycle quality story where commuter demand shifts toward premium folding configurations with rail-integration features and theft-resistant design.
For Market Incumbents: Acquire swappable-battery service infrastructure to defend against emerging fleet-operator vertical integration. Silence and Govecs have demonstrated that captive battery exchange networks lock in commercial utilization contracts. Incumbents should also secure early technical consultations with Germany's KBA and France's ANSM to compress homologation timelines before notified body capacity constraints worsen. For New Entrants and Emerging Players: The EU Battery Regulation in Europe opens a window for third-party verification and blockchain traceability software vendors. White-space targets include Eastern European municipal concession bidding in Warsaw and Prague before subsidy programs mature, and employer benefit program integration in Copenhagen and Munich where corporate procurement consolidates micromobility contracts. A direct B2B fleet sales motion bypasses retail channel establishment costs. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale fleet operators with municipal concession density because city contracts create predictable utilization revenue and software integration moats. The five-to-ten year viability window favors entities with Battery Passport compliance infrastructure already deployed. The signal to watch is subsidy taper schedules in Randstad municipalities, which will separate subsidy-dependent operators from sustainable unit economics.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Passport Compliance Integration | Blockchain verification partnerships with Nordic recyclers meet EU due diligence mandates ahead of enforcement. |
| Swappable-Battery Service Network Expansion | Hot-swap configurations in Madrid and Lisbon eliminate charging downtime for commercial fleet operators. |
| Municipal Concession Contract Consolidation | Berlin and Paris shared fleet agreements create predictable revenue streams with dynamic rebalancing algorithms. |
| Rail-First Mile Infrastructure Partnership | Deutsche Bahn and SNCF station integration captures commuter adoption around secure parking facilities. |
| Commercial Chassis Thermal Box Integration | Milan and Barcelona last-mile logistics specifications replace thermal mopeds with electric delivery platforms. |
Research Approach
Multiple input streams — primary interviews with fleet operations directors, OEM platform engineers, and municipal procurement officers; secondary validation through EU Battery Regulation filings, KBA type-approval databases, and national subsidy program disclosures — were reconciled through bottom-up unit economics modeling and top-down market sizing across the projection horizon.
Data-stream reconciliation anchored volume and value outputs to segmentation dimensions including product architecture, battery chemistry tier, end-use intensity, and maximum speed classification. CAGRs were derived from modeled adoption curves incorporating rail infrastructure investment schedules and low-emission zone expansion timelines. Forecast inputs included lithium cell cost trajectories and notified body approval capacity constraints.
Revisions become necessary when lithium price volatility exceeds hedging coverage, notified body backlogs extend homologation timelines, or municipal insurance mandates reshape fleet operator unit economics. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Mexico Automotive High Performance Electric Vehicle Market
Electric Vehicles
North America Electric Vehicle Thermal Management System Market
Electric Vehicles
Electric Motorcycles and Scooters Market
Electric Vehicles
Hoverboard Scooter Market
Electric Vehicles
Automotive Battery Packs Market
Electric Vehicles
EV PTC Heaters Market
Electric Vehicles
Electric Vehicle Battery on Demand Market
Electric Vehicles
AC BEV On-Board Charger Market
Electric Vehicles
Asia-Pacific Electric Bus Market
Electric Vehicles
France Electric Vehicle Market
Electric Vehicles
Train Battery Market
Electric Vehicles
Busbar for EV Market
Electric Vehicles
Europe Electric Vehicle Market
Electric Vehicles
Electric Vehicle Liquid Cold Plates Market
Electric Vehicles
Asia Pacific Electric Commercial Vehicles Market
Electric Vehicles
Nordic E-Bike Market