
 Rechargeable Tires Market | 2026-2036
Rechargeable Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Rechargeable Tires Market Analytics
The EU Green Deal is broadening the addressable market for energy-harvesting tire technologies by embedding circular-economy mandates into automotive supply chains. Michelin leverages its R&D footprint in polymer energy storage to sustain technology leadership in self-charging tread compounds. Continental AG anchors European OEM relationships through integrated tire-electric vehicle system development. Bridgestone Corporation competes on manufacturing scale across Asian and North American production networks.
Rechargeable tires integrate piezoelectric or thermoelectric materials within the tire carcass to convert mechanical deformation and thermal gradients into storable electrical energy, typically operating at conversion efficiencies between 5% and 15% depending on material composition and road contact dynamics. Passenger tires command the primary revenue pool due to high unit volumes and OEM integration programs, while wireless charging technology represents the fastest-expanding segment as inductive coupling systems eliminate physical connector wear in fleet applications. Fleet operators constitute the most concentrated end-user margin pool because their total-cost-of-ownership models justify premium pricing for reduced downtime and predictive maintenance capabilities.
The European Commission's ECHA maintains REACH compliance requirements for novel piezoelectric compounds, while the EPA in the United States regulates tire particulate emissions that rechargeable designs aim to reduce through optimized rolling resistance profiles. Japan's METI funds next-generation mobility material research that directly supports domestic tire electrification roadmaps. Stakeholders must monitor how battery storage integration within tire architectures triggers overlapping jurisdiction from transportation safety regulators and electrical equipment certifiers.
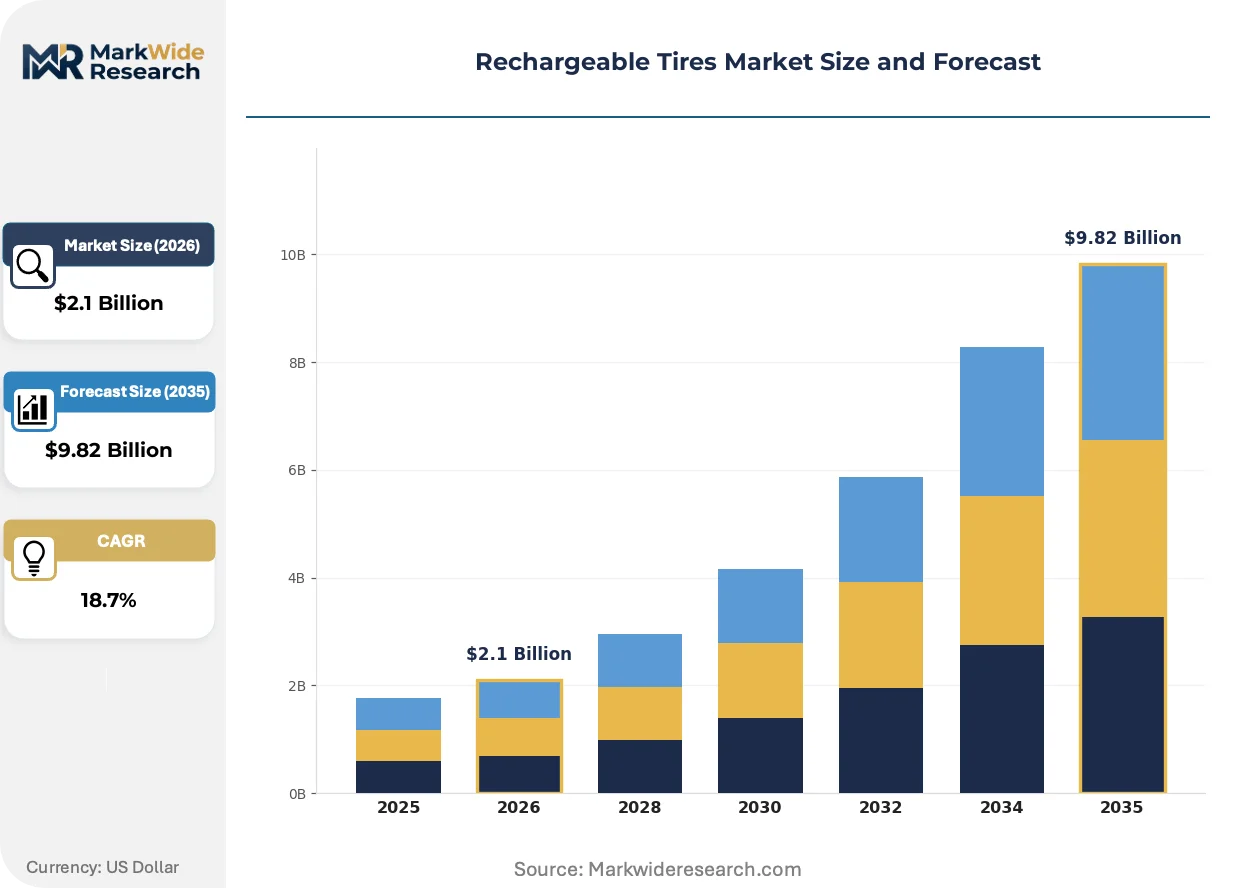
Market Dynamics
Fleet electrification roadmaps and EU emissions mandates are compressing development timelines for energy-harvesting tire architectures. OEM integration programs now require tire-electric vehicle system co-design rather than component-level procurement.
Growth Catalysts
- EU Green Deal:Circular-economy mandates embedded in automotive supply chains expand the addressable market for self-charging tread compounds and regenerative tire systems.
- Fleet operators:Total-cost-of-ownership models justify premium pricing for reduced downtime and predictive maintenance capabilities in electrified tire platforms.
- Piezoelectric materials:Polymer energy storage advances enable conversion efficiencies between five and fifteen percent from mechanical deformation during road contact.
Market Restraints
- Specialized compound costs:Novel piezoelectric materials face input cost volatility from rare earth element supply concentration in China.
- REACH compliance friction:ECHA registration requirements for new tire carcass materials extend commercialization timelines by eighteen to thirty-six months.
- Wireless charging infrastructure:Inductive coupling system deployment lags fleet adoption curves, creating stranded asset risk for early adopters.
Strategic Opportunities
- German automotive OEMs:Next-generation electric vehicle platforms in Stuttgart and Munich offer prototype integration partnerships for rechargeable tire developers.
- Japan METI funding:Next-generation mobility material research programs directly support domestic tire electrification roadmaps and pilot production.
- Thermoelectric-piezoelectric convergence:Dual-mode energy harvesting from thermal gradients and mechanical deformation opens new efficiency frontiers.
Industry Challenges
- Cross-functional talent scarcity:Tire engineering and electrical system integration expertise rarely coexist in single professionals, forcing expensive team assembly.
- Dual certification complexity:Battery storage integration within tire architectures triggers overlapping jurisdiction from NHTSA transportation safety regulators and electrical equipment certifiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rechargeable Tires Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.82 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Tires, Truck Tires, Motorcycle Tires, Off-Road Tires Technology: Wireless Charging, Inductive Charging, Solar Charging, Battery Storage End User: OEMs, Fleet Operators, Individual Consumers, Vehicle Retrofitting Application: Urban Mobility, Commercial Transport, Recreational Vehicles, Delivery Services |
| Companies Covered | Michelin, Goodyear, Bridgestone Corporation, Pirelli, Continental AG, Hankook Tire, Yokohama Rubber Company, Sumitomo Rubber Industries, Toyo Tire, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rechargeable Tires Market Evolving Landscape
Energy-harvesting tire architectures are shifting from laboratory demonstration to production-intent engineering. Material science advances and regulatory pressure are compressing the gap between concept vehicles and serial manufacturing.
Inductive coupling systems are overtaking conductive charging as the dominant wireless power transfer method for fleet applications. Commercial vehicle operators in Germany and the Netherlands are specifying contactless charging to eliminate connector wear and reduce maintenance intervals. This transition is overtaking legacy plug-in architectures and forcing tire manufacturers to embed receiver coils within carcass structures.
REACH authorization requirements for novel piezoelectric compounds are tightening material qualification pathways for European tire manufacturers. The European Chemicals Agency now requires extended toxicity testing for energy-harvesting polymers before automotive integration approval. German and French OEMs are responding by front-loading regulatory engagement eighteen months ahead of platform launch timelines.
Fleet procurement departments are consolidating tire supplier relationships around integrated service contracts rather than unit-based purchasing. Logistics operators in the US and Germany now specify uptime guarantees and predictive maintenance inclusion in tire supply agreements. This restructuring is most visible in long-haul trucking verticals where downtime costs exceed tire acquisition premiums by an order of magnitude.
Rechargeable Tires Market Segmentation
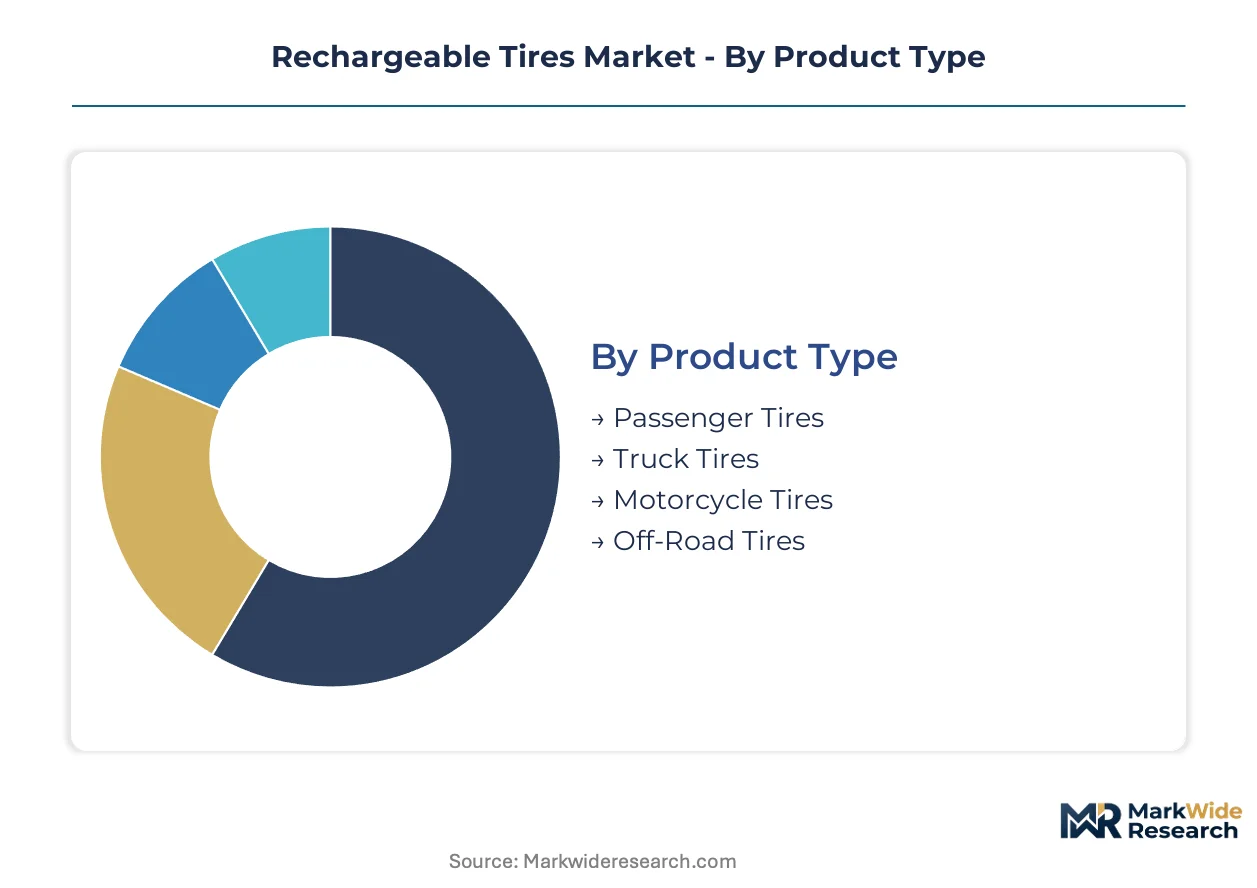
Rechargeable tire architectures diverge sharply across vehicle platforms and energy transfer methods. Product specifications, charging modalities, and procurement channels each impose distinct technical requirements and margin structures on manufacturers.
Product Type:
Volume concentration and unit economics separate passenger applications from commercial-grade alternatives.
- Passenger Tires:Polymer carcass designs integrate piezoelectric tread compounds for electric vehicle platforms. German OEMs in Stuttgart specify these for next-generation urban mobility fleets.
- Truck Tires:Heavy-duty carcass structures accommodate thermoelectric-piezoelectric convergence for long-haul energy harvesting. Fleet operators in the Netherlands demand contactless charging integration to eliminate connector wear.
- Motorcycle Tires:Compact form factors limit battery storage capacity but suit last-mile delivery applications.
- Off-Road Tires:Ruggedized carcass designs prioritize mechanical deformation capture over thermal gradient harvesting for construction and mining vehicles.
Passenger tires lead on scale; truck tires lead on momentum.
Technology:
Energy transfer mechanisms determine infrastructure compatibility and maintenance economics for fleet adopters.
- Wireless Charging:Inductive coupling systems eliminate physical connector degradation. Commercial vehicle operators in Germany specify these for reduced maintenance intervals.
- Inductive Charging:Receiver coil embedding within tire carcass structures enables contactless power transfer. This modality is expanding most quickly across European logistics fleets.
- Solar Charging:Photovoltaic tread surface integration captures ambient light during daytime operation.
- Battery Storage:Integrated cell architectures within tire walls trigger dual certification requirements from NHTSA and electrical equipment regulators.
Wireless charging dominates deployment; inductive charging dominates development pipelines.
End User:
Procurement authority and total-cost-of-ownership modeling determine pricing power and contract structure.
- OEMs:Platform-level integration programs require tire-electric vehicle system co-design rather than component sourcing. German automotive manufacturers in Munich front-load regulatory engagement eighteen months ahead of launch.
- Fleet Operators:Uptime guarantees and predictive maintenance inclusion justify premium acquisition costs. US long-haul trucking verticals specify service contracts over unit purchasing.
- Individual Consumers:Retail channels emphasize rolling resistance reduction and extended range claims for electric vehicle owners.
- Vehicle Retrofitting:Aftermarket installation faces compatibility constraints with legacy wheel well dimensions and suspension geometries.
Fleet operators concentrate margin capture; OEMs concentrate technology validation.
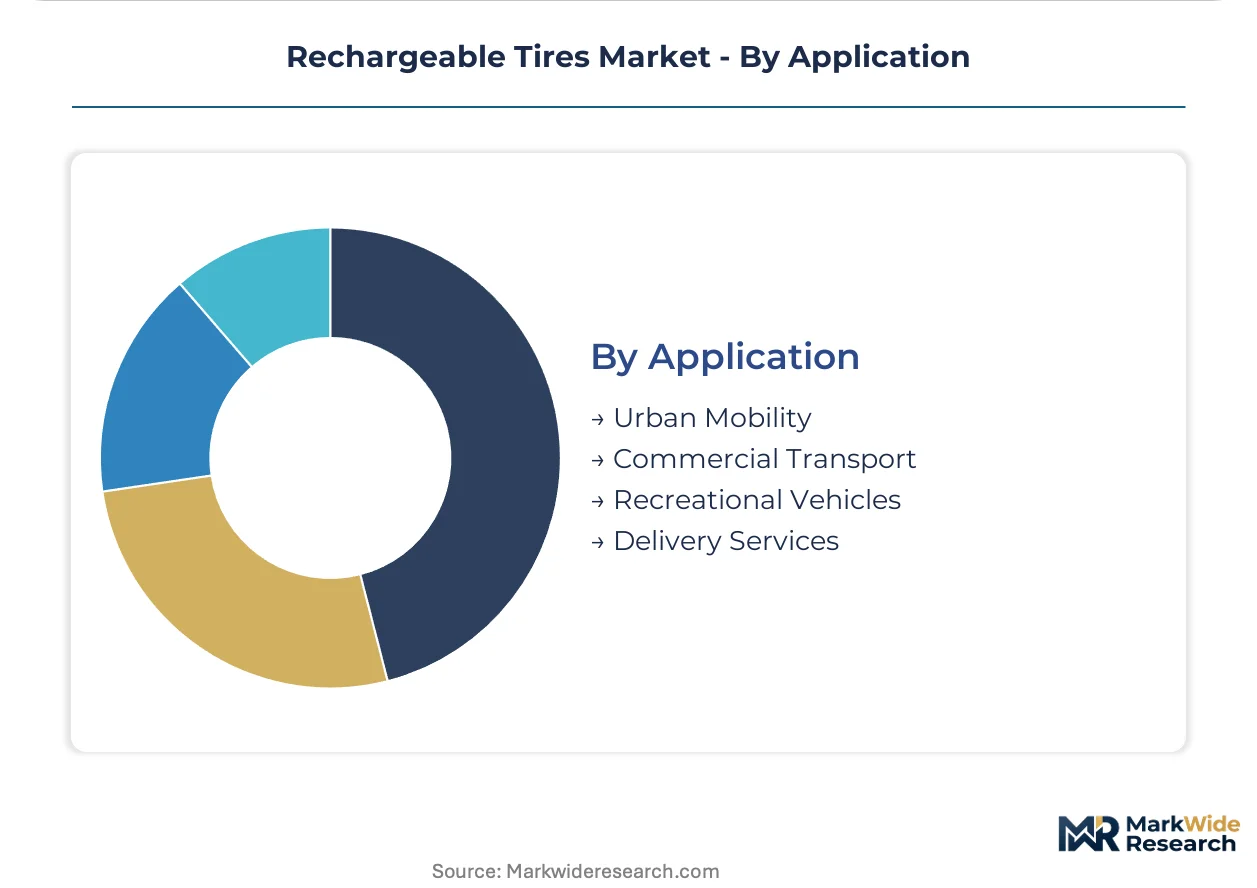
Application:
Operating environment and duty cycle intensity dictate material specifications and energy harvesting priorities.
- Urban Mobility:Stop-start driving patterns maximize piezoelectric output from frequent deformation cycles. Metro transit authorities in the Netherlands pilot these for electric bus fleets.
- Commercial Transport:Sustained highway speeds favor thermoelectric harvesting from thermal gradients. German logistics corridors anchor early deployment.
- Recreational Vehicles:Intermittent usage patterns limit energy storage utilization efficiency.
- Delivery Services:Last-mile density and curb proximity requirements favor compact motorcycle tire formats with wireless charging.
Urban mobility leads on deployment velocity; commercial transport leads on revenue per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The rechargeable tire industry traces its commercial roots to German automotive engineering clusters where piezoelectric material research first merged with tire manufacturing expertise during early electric vehicle platform development.
Germany
Stuttgart and Munich anchor European prototype integration for next-generation electric vehicle platforms. The EU Green Deal's circular-economy mandates accelerate energy-harvesting tire adoption across automotive supply chains. Baden-Württemberg's polymer research institutes collaborate directly with OEMs on self-charging tread compound validation.
United States
Long-haul trucking fleets in the Midwest and Southeast specify uptime guarantees and predictive maintenance inclusion in tire procurement contracts. EPA regulations on tire particulate emissions push manufacturers toward optimized rolling resistance profiles. Detroit-area automotive clusters pilot thermoelectric-piezoelectric convergence for commercial transport applications.
Japan
Domestic tire electrification roadmaps receive direct funding from METI's next-generation mobility material research programs. Osaka and Nagoya house concentrated R&D facilities for piezoelectric polymer development. Kanto-based OEMs integrate receiver coil architectures into production-intent vehicle platforms.
Netherlands
Logistics operators in Rotterdam and Amsterdam demand contactless charging integration to eliminate connector wear in high-frequency fleet rotations. National transit authorities pilot wireless inductive systems for electric bus fleets in urban corridors. Eindhoven's automotive technology cluster advances dual-mode energy harvesting from thermal and mechanical sources.
South Korea
Seoul Capital Area battery manufacturers explore integrated cell architectures within tire wall structures for electric vehicle exports. National industrial policy prioritizes energy-harvesting component development under green mobility initiatives. Busan-Ulsan manufacturing zones test production-scale embedding of receiver coils within tire carcass structures.
Rechargeable Tires Market Competitive Landscape
Capital-heavy tire manufacturers compete with specialized material science firms for control of energy-harvesting architectures. The market structure concentrates around integrated automotive suppliers with captive OEM relationships and polymer research capabilities. Three archetypes dominate: full-stack tire-electronics integrators, compound specialists licensing piezoelectric formulations, and fleet-service operators bundling hardware with predictive maintenance platforms. Competitive dynamics center on strategic partnerships for wireless charging infrastructure deployment and backward integration into rare earth material supply chains.
Within the integrated automotive tier, Michelin and Continental AG exemplify European technology leadership through polymer energy storage R&D footprints. Bridgestone Corporation anchors Asian manufacturing scale across production networks. These three entities represent distinct geographic concentrations while occupying comparable positions as full-system developers rather than component suppliers.
| Leading Market Players |
|---|
| Michelin |
| Goodyear |
| Bridgestone Corporation |
| Pirelli |
| Continental AG |
| Hankook Tire |
| Yokohama Rubber Company |
| Sumitomo Rubber Industries |
| Toyo Tire |
| Others |
Value Network & Pricing Analysis
Piezoelectric polymer chemists in Baden-Württemberg command wage premiums that widen spreads between premium OEM-specified tires and economy-grade fleet alternatives, compressing margin capture for manufacturers lacking captive R&D facilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies rechargeable tires by certification grade and after-sales service bundling. Premium tiers carry OEM validation from Stuttgart-based manufacturers and include predictive maintenance platforms. Cost compression in economy tiers intensifies because fleet operators negotiate uptime guarantees into multi-year service contracts. Individual consumers exhibit highest price sensitivity; fleet procurement departments show lowest sensitivity due to total-cost-of-ownership modeling.
Supply Chain Analysis
Dual-sourcing requirements from German OEMs mandate multi-supplier qualification for piezoelectric compound feedstocks, forcing tire manufacturers to maintain parallel relationships with Japanese and South Korean material specialists. Rare earth element processing concentrates in China; polymer synthesis capabilities center on Germany and Japan. Single-source vulnerability runs through Beijing-controlled terbium and dysprosium supply channels. Distribution runs through integrated tire-electric vehicle system partnerships rather than aftermarket wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rechargeable tire development functions as a geographic-arbitrage play: EU REACH compliance costs in Europe exceed Japan METI subsidy offsets by a margin that favors R&D relocation to Kanto-based production clusters.
For Market Incumbents: To counter emerging compound specialists licensing piezoelectric formulations to Tier 2 manufacturers, backward integration into rare earth material supply chains secures input cost stability. Capacity addition in Osaka polymer research corridors captures METI funding streams. Certification investment in dual NHTSA-electrical equipment standards builds regulatory moats against Asian entrants. For New Entrants and Emerging Players: The 40-60% price-point gap between premium OEM-specified and economy fleet tires opens white-space targeting for mid-tier inductive charging systems. Last-mile delivery motorcycle tire formats in the Netherlands represent the most penetrable segment. Go-to-market through Rotterdam logistics operators as integrated service contractors bypasses established OEM procurement gatekeepers. For Investors and Strategic Acquirers: Full-stack tire-electronics integrators are the most active acquirer in this space, consolidating compound specialists to capture polymer IP. Long-term viability hinges on 5-10 year fleet electrification roadmap execution rather than consumer adoption curves. Watch for ECHA REACH authorization timeline acceleration as the inflection signal indicating European commercialization readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Supply | Captive terbium sourcing from Chinese processors insulates Michelin and Continental from input volatility. |
| Wireless Charging Infrastructure Partnership | Inductive coupling deployment with Rotterdam fleet operators eliminates stranded asset risk for early adopters. |
| Dual-Mode Energy Harvesting R&D | Thermoelectric-piezoelectric convergence programs at Eindhoven automotive cluster open new efficiency frontiers. |
| REACH Pre-Authorization Engagement | Eighteen-month regulatory front-loading by Munich OEMs accelerates platform launch timelines. |
| Fleet Service Contract Consolidation | Integrated uptime guarantees with US long-haul trucking verticals displace unit-based procurement. |
Research Methodology
Coverage spans Germany, Japan, the United States, and the Netherlands, with primary inputs from each market combining executive interviews with tire platform engineers, fleet procurement directors, polymer R&D leads, and ECHA regulatory affairs specialists. Secondary validation draws from EPA emissions filings, METI research program disclosures, EU Green Deal implementation documents, and vehicle production databases. Bottom-up unit economics triangulate against top-down OEM integration program forecasts.
Granularity-level modeling disaggregates volume and value across product type, technology modality, end-user archetype, and application environment, with additional segmentation by regional regulatory cluster. CAGRs derive from fitted growth curves applied to fleet electrification adoption rates and OEM platform launch schedules. Industry-specific inputs include piezoelectric conversion efficiency trajectories and wireless charging infrastructure deployment curves.
The model assumes a particular technology adoption path; alternative pathways for thermoelectric-piezoelectric convergence would alter the outlook if conversion efficiency breakthroughs exceed baseline assumptions. Deviation in ECHA authorization timelines or METI funding continuity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Magnesium Wheel Market
Tires and Wheels
Automotive Alloy Wheels Market
Tires and Wheels
Japan Tyre Market
Tires and Wheels
Global Aircraft Tire Market
Tires and Wheels
Bike Wheels Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
Asia Pacific Two Wheeler Tire Market
Tires and Wheels
Global Automotive Tire Socks Market
Tires and Wheels
Automotive Wheel Market
Tires and Wheels
Automotive Wheel Alignment Service Market
Tires and Wheels
North America 2-Wheeler Replacement Tire Market
Tires and Wheels
Tire Protection Chains Market
Tires and Wheels
Automotive Tubeless Tire Market
Tires and Wheels
Automotive Steel Wheels Market
Tires and Wheels
Bicycle Rim Brake Market
Tires and Wheels
Construction Machinery Tires Market