
 All Weather Tire Market | 2026-2036
All Weather Tire Market Size, Share, and Industry Trends Forecast 2026-2036
All Weather Tire Market Outlook
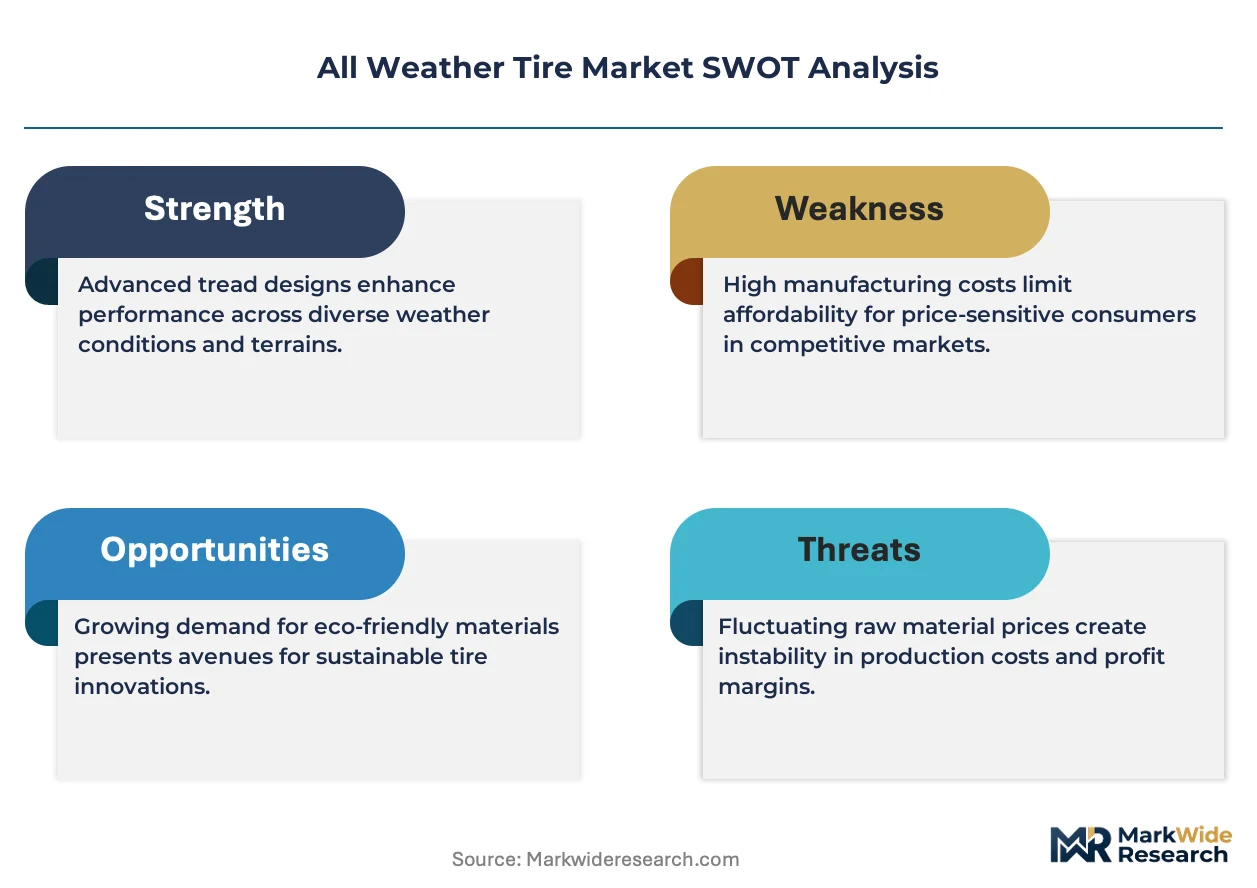
Three-Peak Mountain Snowflake certification is unwinding the commodity-tier structure of the all-weather tire category. Michelin leverages its Nordic testing infrastructure to sustain premium positioning in severe-snow markets. Bridgestone Corporation anchors volume production through its Tennessee manufacturing complex. Continental AG differentiates via ContiSeal self-sealing technology integrated into all-weather platforms.
All-weather tires combine summer and winter performance in a single compound, typically rated for temperatures from -7°C to above 30°C and certified under ASTM F1805 snow traction testing. Their primary purpose is eliminating seasonal tire swaps for consumers and fleet operators in temperate climates with intermittent snow. Passenger cars dominate installed base across symmetrical and asymmetrical tread designs, while directional patterns capture fastest growth in SUV applications where hydroplaning resistance commands price premiums. Distribution through tire shops retains margin concentration due to mounting and balancing service attachment, though online retail is gaining share in replacement cycles.
NHTSA's tire fuel efficiency grading and the EU tire labeling regulation shape product development priorities for rolling resistance and wet grip. Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces winter tire mandates on designated highways, expanding the addressable market for all-weather alternatives. Stakeholders must monitor how ASTM F1805 test protocol revisions and emerging bio-based rubber certifications from USDA BioPreferred reshape qualification thresholds and sourcing requirements.
Market Dynamics
Three-Peak Mountain Snowflake certification requirements are compressing the commodity tier and forcing compound innovation across all-weather tire portfolios. ASTM F1805 snow traction testing now serves as the primary qualification gate for temperate-climate markets seeking single-tire solutions.
Growth Catalysts
- Fleet cost rationalization:Commercial operators in the United States are eliminating seasonal changeover labor and storage expenses through all-weather fitment. Fleet procurement officers now mandate TPC-rated tires for mixed-climate routes.
- EU F-Gas Regulation:Manufacturing process constraints under this framework are accelerating adoption of bio-based rubber compounds. Producers reformulate tread polymers to meet rolling-resistance thresholds without sacrificing cold-weather elasticity.
- Japan highway mandates:MLIT winter tire requirements on designated mountain routes are expanding addressable volume for all-weather alternatives. Consumers substitute dedicated winter sets with certified all-weather products to avoid seasonal swaps.
Market Restraints
- Natural rubber price volatility:Hevea brasiliensis supply concentration in Southeast Asia creates input cost instability. Compounders face margin compression when latex futures spike during monsoon disruptions.
- Technical performance ceiling:Single-compromise formulations cannot match dedicated summer wet-grip or winter ice-traction extremes. Performance-oriented consumers in Germany and Japan retain two-tire strategies despite convenience appeal.
- Steel cord supply concentration:Bead wire and belt production clusters in China create geographic dependency risk. Tire makers face logistics vulnerability when regional port congestion interrupts cord shipments.
Strategic Opportunities
- Underpenetrated SUV segment:Directional tread patterns for sport-utility vehicles command price premiums for hydroplaning resistance. Manufacturers expand asymmetric designs for CUV and SUV fitments in the United States.
- USDA BioPreferred certification:Federal procurement preferences for bio-based content create demand pull. Compounders qualifying soy-oil or guayule-derived rubber gain access to government fleet contracts.
- Online retail channel expansion:Direct-to-consumer platforms with mobile mounting services are capturing replacement cycle share. Digital-native buyers in Germany bypass traditional tire shop intermediaries for standardized fitments.
Industry Challenges
- ASTM F1805 protocol revision timelines:Pending test modifications for snow traction measurement create certification uncertainty. R&D teams must engineer compounds against moving qualification targets.
- Skilled compounder scarcity:Polymer science expertise for temperature-elasticity balancing is concentrated among retiring specialists. Training programs struggle to replicate tacit knowledge of silica dispersion optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | All Weather Tire Market |
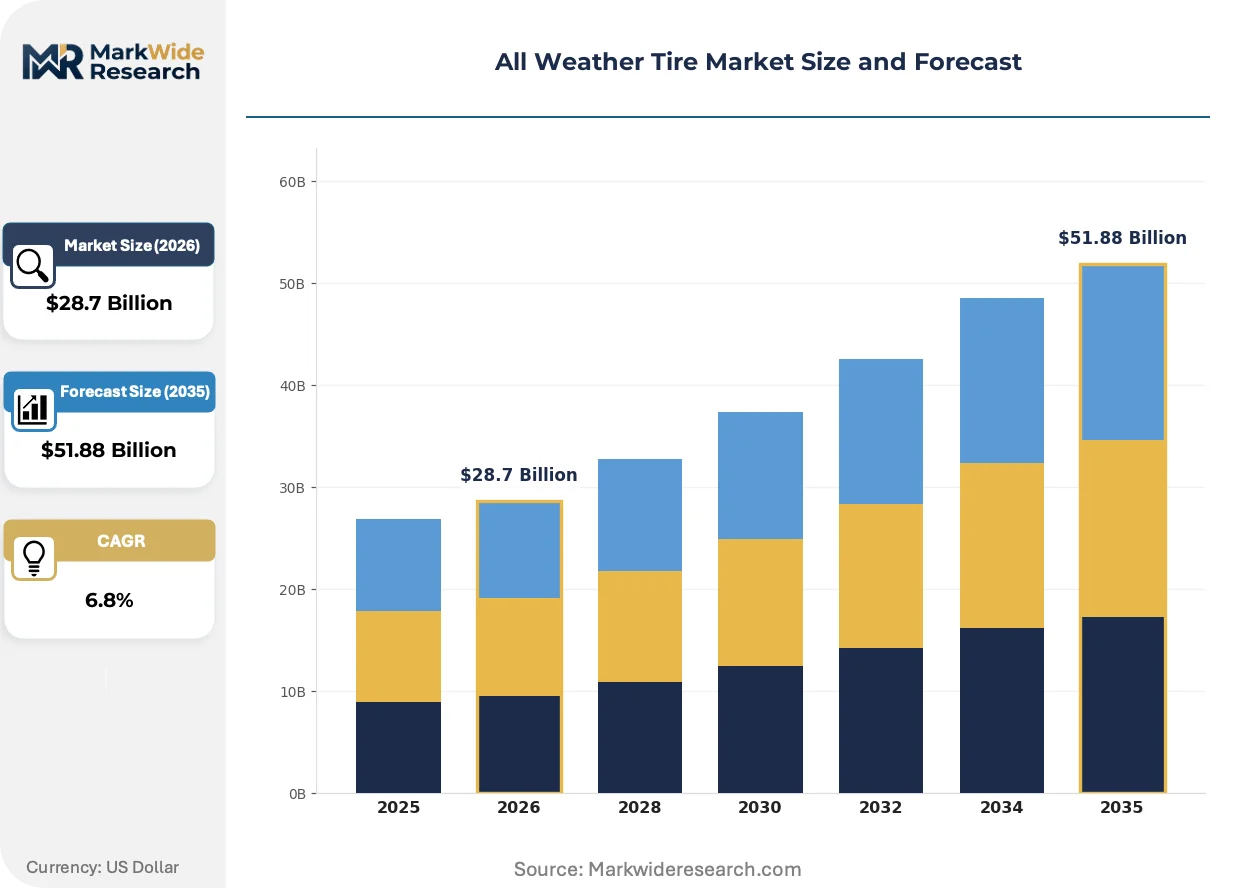
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Cars, SUVs, Light Trucks, Vans Tread Design: Symmetrical, Asymmetrical, Directional, Hybrid Distribution Channel: Online Retail, Dealerships, Tire Shops, Big Box Stores End User: Consumers, Commercial Fleets, Government Agencies, Rental Services |
| Companies Covered | Michelin, Bridgestone Corporation, Continental AG, Goodyear Tire and Rubber Company, Pirelli & C. S.p.A., Hankook Tire and Technology, Nokian Tyres plc, Yokohama Tire Corporation, Sumitomo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
All Weather Tire Market Strategic Shifts
Compound architecture and distribution infrastructure are undergoing parallel transformation as certification standards tighten and buyer procurement patterns digitize. Material science advances now determine competitive position as much as manufacturing scale.
Silica-silane coupling systems are decomposing the traditional carbon-black dominance in tread compounds. Passenger car OEMs in Japan specify high-dispersion silica for factory fitment to achieve EU tire labeling A-grade wet grip. This chemistry is compressing the performance gap between premium and mid-tier all-weather products.
NHTSA's tire fuel efficiency grading program is forcing compound reformulation across US-bound production. Manufacturers reduce hysteresis loss in tread polymers to secure favorable rolling-resistance scores. Light truck and SUV segments face the steepest R&D burden as vehicle weight compounds efficiency challenges.
Subscription-based tire-as-a-service models are emerging among commercial fleet operators seeking to unbundle capital expenditure. Third-party managers in Germany now procure mileage-rated contracts with embedded replacement scheduling. This procurement evolution shifts volume risk from fleet owners to tire suppliers and their financing partners.
All Weather Tire Market Segmentation
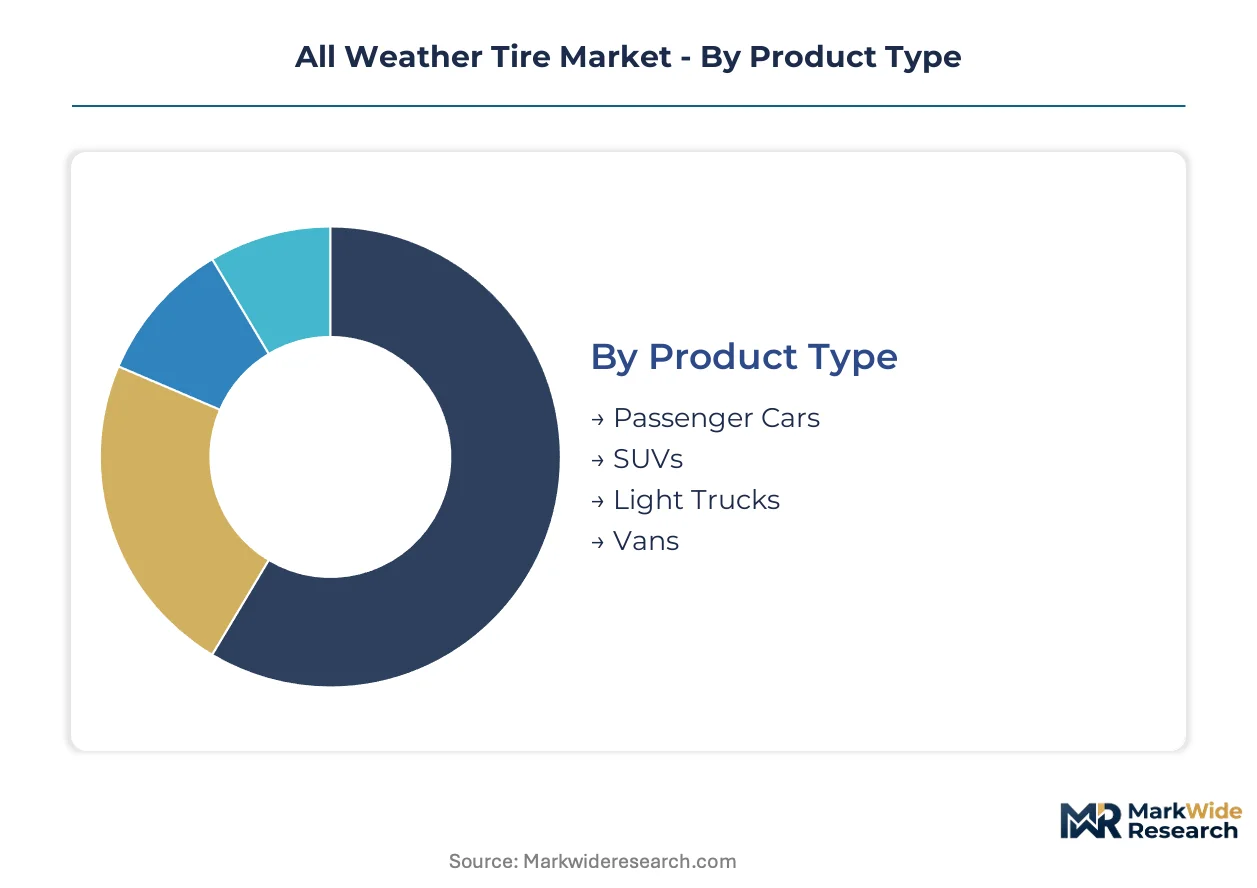
All-weather tire segmentation reveals divergent margin structures across vehicle fitments and procurement channels. Compound architecture and certification tiers fragment profitability within each category, forcing portfolio-specific positioning strategies.
Product Type:
Margin pools concentrate in SUV and light truck fitments where load ratings and speed indices command specification premiums. Passenger car volumes anchor factory fitment economics, while commercial derivatives in vans generate aftermarket replacement density.
- Passenger Cars:Factory fitment concentrates with Japanese and German OEMs specifying high-dispersion silica compounds for EU tire labeling compliance. Symmetrical tread patterns dominate this segment due to lower manufacturing complexity and quieter highway operation. Consumers in Germany and the United States drive replacement demand through shortened ownership cycles.
- SUVs:Directional tread configurations capture price premiums for hydroplaning resistance and aesthetic differentiation. Asymmetric designs are expanding fastest among CUV fitments in the United States where all-wheel-drive penetration supports all-weather positioning. Load range requirements elevate material costs versus passenger car equivalents.
- Light Trucks:Commercial operators specify E-load rated constructions for mixed-service durability. Fleet procurement in the United States mandates Three-Peak Mountain Snowflake certification for route flexibility.
- Vans:Last-mile delivery electrification is reshaping rolling-resistance priorities. European parcel carriers specify low-hysteresis compounds to preserve battery range.
The dominant share belongs to Passenger Cars, while SUVs are closing the gap fastest.
Tread Design:
Manufacturing complexity and mold investment requirements stratify competitive participation across pattern architectures. Directional and hybrid designs filter out commodity producers lacking R&D scale.
- Symmetrical:Lowest mold cost and rotational flexibility support economy-tier positioning. High-volume producers in Asia leverage this architecture for cost-competitive export programs.
- Asymmetrical:Dry grip and wet traction optimization requires dual-purpose mold cavities. Premium brands concentrate fitment here for OEM supply contracts.
- Directional:V-groove geometries excel at water evacuation and snow packing. SUV applications in Germany and the United States absorb capacity from specialized producers.
- Hybrid:Combines asymmetric dry zones with directional wet channels. Patent-protected designs limit competitive replication.
Asymmetrical patterns retain the largest installed base, though Directional configurations are expanding most quickly in premium SUV fitments.
Distribution Channel:
Service attachment rates and inventory carrying costs determine channel viability. Tire shops retain margin concentration through mounting and balancing bundling, while digital platforms compress intermediation.
- Online Retail:Direct-to-consumer platforms with mobile mounting services are capturing replacement share. German consumers bypass traditional intermediaries for standardized fitments.
- Dealerships:OEM-aligned distribution captures warranty-service bundling. New vehicle sales in Japan and the United States drive initial fitment volume.
- Tire Shops:Independent specialists dominate replacement cycles through technical consultation and storage services. United States commercial fleets negotiate volume contracts through regional chains.
- Big Box Stores:Price transparency and convenience positioning attract cost-sensitive consumers. Seasonal promotional cycles concentrate volume in Q4.
Tire Shops command the dominant transaction volume, yet Online Retail is gaining share fastest among digitally native buyer cohorts.
End User:
Procurement sophistication and total-cost-of-ownership calculation depth separate segment profitability. Commercial buyers mandate performance documentation; consumer segments respond to certification visibility.
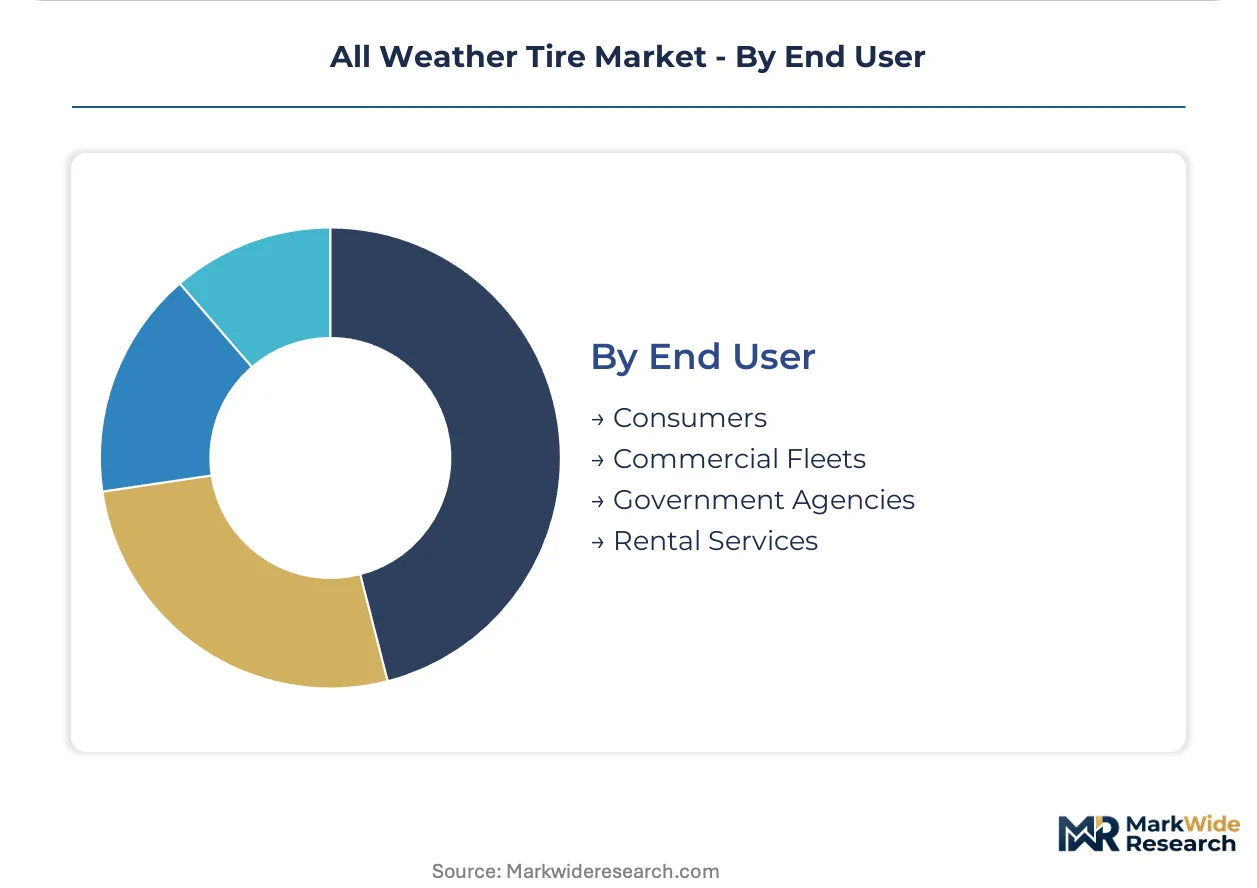
- Consumers:Individual purchasers prioritize Three-Peak Mountain Snowflake visibility and EU tire labeling grades. Convenience positioning in temperate climates supports all-weather substitution for seasonal sets.
- Commercial Fleets:United States logistics operators eliminate changeover labor and storage costs through standardized all-weather fitment. Procurement officers specify TPC-rated tires for mixed-climate route coverage.
- Government Agencies:USDA BioPreferred certification unlocks federal fleet contracts. Soy-oil and guayule-derived rubber content satisfies procurement preferences.
- Rental Services:Turnover velocity and damage liability drive durability specifications. Airport and urban location operators in Germany specify reinforced sidewall constructions.
Consumers represent the largest addressable base, while Commercial Fleets are adopting all-weather solutions most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances tilt toward manufacturing hubs in Asia while temperate-climate consuming markets in North America and Europe absorb finished tire volumes. Logistics corridors linking Southeast Asian rubber sources to East Asian compounding facilities shape regional trade flows. Finished tire shipments from Chinese and South Korean ports supply replacement demand across Pacific and Atlantic basins.
United States
Commercial fleet standardization on all-weather platforms drives replacement volume, with logistics operators eliminating seasonal changeover labor costs. NHTSA's tire fuel efficiency grading shapes compound priorities for domestic-bound production. Tennessee hosts major manufacturing complexes serving both OEM fitment and aftermarket channels.
Germany
OEM specification leadership from premium passenger vehicle manufacturers elevates compound performance thresholds for factory fitment. EU F-Gas Regulation accelerates bio-based rubber adoption in tread formulations. The KBA enforces winter tire mandates on designated mountain routes, expanding certified all-weather alternatives.
Japan
Shortened vehicle ownership cycles compress replacement intervals for passenger car fitments. MLIT winter tire requirements on designated highways expand addressable volume for Three-Peak Mountain Snowflake certified products. Kanto region tire makers supply high-dispersion silica compounds for EU labeling compliance.
China
Domestic vehicle production scale anchors regional compounding capacity expansion. SAMR quality supervision and GB standards alignment shape export-bound product specifications. Shandong Peninsula clusters concentrate mold manufacturing and steel cord processing for integrated supply.
South Korea
OEM supply relationships with domestic automotive groups anchor factory fitment economics. MFDS-equivalent transport ministry standards govern winter performance certification for domestic market entry. Busan-Ulsan industrial corridor hosts integrated tire and petrochemical production.
All Weather Tire Market Competitive Environment
Concentration sits with diversified rubber compounders holding integrated manufacturing footprints across multiple continents. Market structure shows tiered participation with premium compounders commanding OEM specification channels while volume producers serve replacement cycles through distributor networks. Three archetypes dominate: vertically integrated tire-rubber conglomerates, specialized winter-performance houses with Nordic testing heritage, and Asian manufacturing specialists with scale-driven export programs. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as compound architecture becomes the primary differentiation mechanism.
Within the premium compounder tier, Michelin and Continental AG exemplify integrated development approaches spanning tread chemistry through distribution infrastructure. Bridgestone Corporation anchors volume manufacturing capabilities with multi-continental production positioning. These three represent distinct strategic postures: European specification leadership, Japanese-Korean manufacturing scale, and diversified global footprinting respectively.
| Leading Market Players |
|---|
| Michelin |
| Bridgestone Corporation |
| Continental AG |
| Goodyear Tire and Rubber Company |
| Pirelli & C. S.p.A. |
| Hankook Tire and Technology |
| Nokian Tyres plc |
| Yokohama Tire Corporation |
| Sumitomo Corporation |
| Others |
Value Chain & Pricing Dynamics
Ninety-day natural rubber inventory cycles at Southeast Asian processing facilities concentrate pricing power among compounders with backward-integrated sourcing agreements. This lead-time band amplifies margin volatility for manufacturers lacking captive latex supply when monsoon disruptions spike Hevea brasiliensis futures.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Three-Peak Mountain Snowflake certification tier and silica-dispersion grade drive price differentiation between Michelin's premium positioning and volume Asian imports. Cost compression in the commodity tier is intensifying because high-volume producers leverage symmetrical tread molds to undercut asymmetric designs. Fleet procurement officers show lowest price sensitivity due to total-cost-of-ownership calculations, while individual replacement buyers in big-box channels exhibit highest elasticity.
Supply Chain Analysis
Strait of Malacca transit underwrites the majority of natural rubber flows from Thai and Indonesian plantations to East Asian compounding facilities. Manufacturing gravity centers on China, South Korea, and Japan for steel cord processing, mold fabrication, and silica masterbatch production. The supply chain hinges on concentrated Hevea brasiliensis cultivation across Thailand, Indonesia, and Vietnam, with carbon black and steel cord as critical secondary inputs. Single-source vulnerability in Chinese steel cord production creates logistics exposure during regional port congestion. Distribution runs through tire shop networks for service-attached replacement volume, with direct-to-consumer platforms capturing share in standardized fitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation enforcement is accelerating bio-based rubber substitution faster than compounders can qualify alternative feedstocks. This regulatory inflection compresses legacy petroleum-based formulation margins while rewarding early movers with USDA BioPreferred certification.
For Market Incumbents: Consolidate Nordic testing infrastructure and silica-dispersion R&D capabilities to defend against emerging Asian compounders with scale advantages. Secure long-term guayule and soy-oil supply agreements before bio-based feedstock demand outstrips cultivation capacity. Prioritize ContiSeal-type value-added technology integration to escape commodity pricing pressure.
For New Entrants and Emerging Players: Mobile mounting and seasonal storage services represent a service-layer gap where incumbents under-serve digitally native consumers. Target the United States SUV directional-tread segment through direct-to-consumer platforms with embedded installation partnerships. Pursue USDA BioPreferred qualification as the primary go-to-market credential for government fleet procurement.
For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-transition play because regulatory frameworks are hardening against petroleum-based compounds faster than incumbent reformulation cycles. Acquisition targets should display integrated bio-based rubber sourcing or patented silica-silane coupling expertise. Monitor ASTM F1805 protocol revision timing as the critical inflection signal for certification-dependent product pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Compound Certification | USDA BioPreferred qualification unlocks federal fleet procurement preferences under sustainable purchasing mandates. |
| Nordic Testing Infrastructure Expansion | Three-Peak Mountain Snowflake validation capacity in severe-climate facilities defends premium positioning against Asian volume entrants. |
| Silica-Silane Coupling R&D Investment | High-dispersion silica mastery bridges EU tire labeling A-grade wet grip with cold-weather elasticity requirements. |
| Direct-to-Consumer Platform Buildout | Mobile mounting service integration captures replacement share from tire shop intermediaries in standardized fitment segments. |
| Backward Integration into Guayule Cultivation | Domestic bio-based rubber sourcing insulates compound margins from Southeast Asian latex price volatility. |
Study Parameters
Desk research of customs trade filings, tire industry association production databases, and regulatory submission records preceded structured interviews with compound R&D directors, fleet procurement officers, tire shop operators, and OEM platform engineers. Primary fieldwork across Tennessee, Shandong, and Kanto manufacturing clusters validated secondary volume estimates. Bottom-up production capacity modeling and top-down replacement cycle demand triangulation anchored market size calculations.
Variance decomposition across vehicle fitment, tread design architecture, and distribution channel dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from segment-level volume trajectories and value-per-unit trends across passenger car, SUV, light truck, and van categories. Silica compound adoption curves, EU tire labeling grade distributions, and fleet standardization rates served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU F-Gas implementation and NHTSA fuel efficiency grading regimes; material policy shifts would require re-modeling. Natural rubber supply disruptions, ASTM F1805 protocol modifications, or bio-based feedstock cost spikes could revise trajectory assumptions. Practitioners should keep alternative scenarios live as certification standards and procurement preferences evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive Wheel Alignment System Market
Tires and Wheels
Asia Pacific Two Wheeler Tire Market
Tires and Wheels
Automotive 3D Printed Tires Market
Tires and Wheels
Europe Aircraft Tires Market
Tires and Wheels
Tire Retreading Market
Tires and Wheels
Green Tires Market
Tires and Wheels
Global Automotive Tires Market
Tires and Wheels
Automotive Smart Tire Market
Tires and Wheels
Tire Protection Chains Market
Tires and Wheels
Russia OTR Tire Market
Tires and Wheels
Automotive Green Tires Market
Tires and Wheels
Wheel Spacers and Adapters Market
Tires and Wheels
North Commercial Vehicle Tire Pressure Monitoring Systems Market
Tires and Wheels
Southeast Asian Tire Market
Tires and Wheels
Automotive Airless Tire Market
Tires and Wheels
Automotive Alloy Wheels Market