
 Global Tires Market | 2026-2036
Global Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tires Market Intelligence
The consolidation of purchasing power among large fleet operators and automotive OEMs is restructuring the supply dynamics for tire producers. Michelin Group leverages its extensive research and development in advanced materials to meet the specific performance demands of these large buyers. Goodyear Tire & Rubber Company competes on the basis of its vast distribution network and brand recognition in the aftermarket, while Continental AG differentiates through its integrated offerings combining tires with vehicle electronics.
Tires are composite structures, typically comprising layers of rubber, fabric, and steel, designed to be mounted on a wheel. Their primary function is to provide a frictional contact patch for traction, support the vehicle load, and absorb road surface irregularities. Radial tires continue to dominate the product landscape due to superior handling and fuel efficiency. While passenger cars represent the largest volume application, the commercial trucks segment often commands higher per-unit margins for specialized, durable designs.
Regulatory mandates significantly influence tire design and material composition. For instance, the US EPA's fuel economy standards and the EU's comprehensive tire labeling regulations compel manufacturers to innovate for lower rolling resistance. China's GB standards enforce strict safety and performance criteria for market access. Navigating the trade-off between investing in sustainable materials and managing cost pressures from powerful OEM and fleet buyers will define future market leadership.
Market Dynamics
The global tire market's structure is defined by the fundamental trade-off between performance engineering and regulatory compliance. Intense pressure from automotive OEMs and large fleet operators for cost reduction clashes with government mandates for improved fuel efficiency and safety, forcing material science innovation.
Growth Catalysts
- Electric Vehicle Adoption:Demand from EV manufacturers for tires with low rolling resistance to maximize battery range, reduced noise for cabin comfort, and high load capacity for heavy battery packs is a primary catalyst.
- Regulatory Mandates:The EU's tire labeling regulations and the US EPA's fuel economy standards compel manufacturers to develop more efficient products, stimulating replacement cycles and R&D investment.
- Emerging Market Automotive Growth:Expansion of the vehicle parc in countries like India and throughout Southeast Asia creates sustained, high-volume demand for both OEM and aftermarket tires across passenger and commercial segments.
Market Restraints
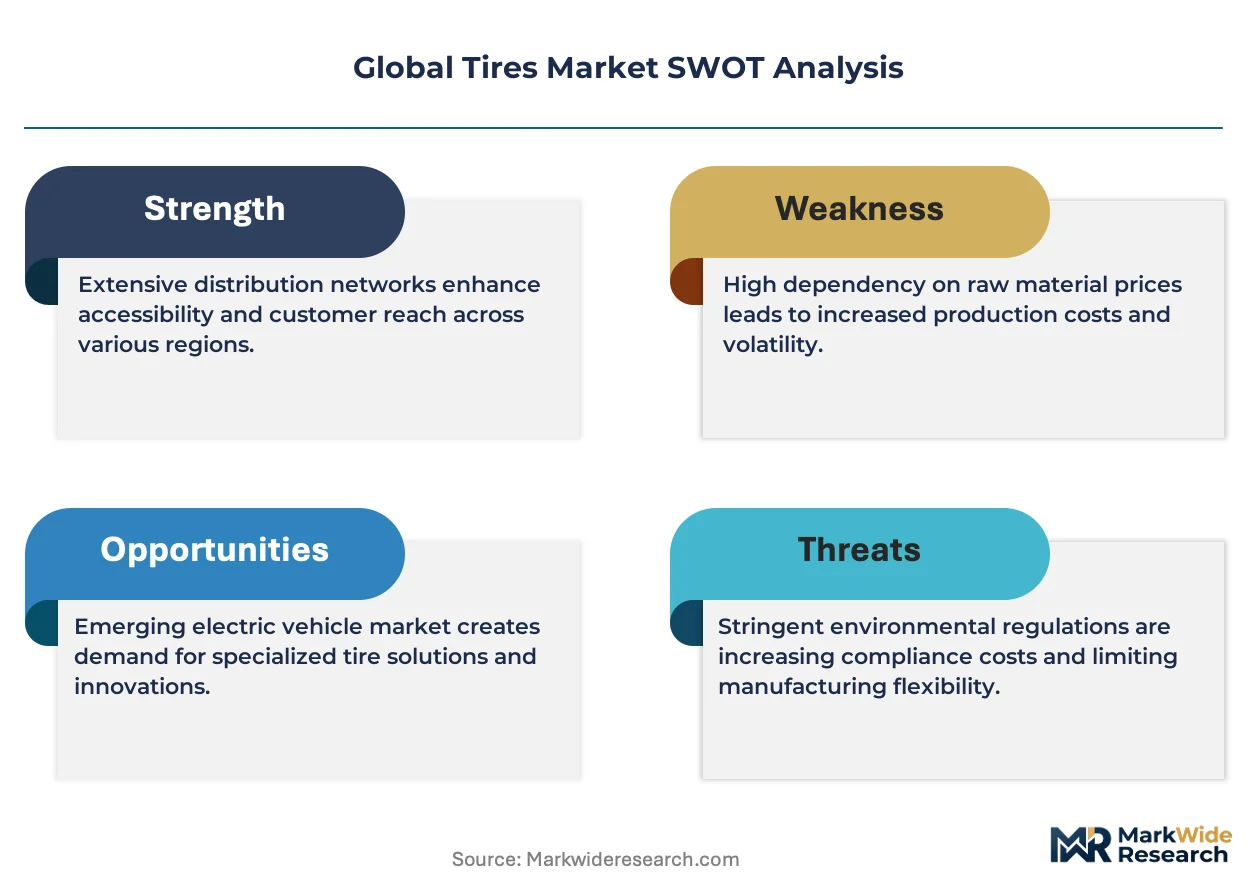
- Raw Material Volatility:Price fluctuations in natural rubber, primarily sourced from Southeast Asia, and petroleum-derived synthetic rubber create significant cost uncertainty and margin pressure for manufacturers.
- Inherent Design Trade-offs:The laws of physics impose a difficult compromise in tire design, where improving one characteristic, such as rolling resistance, often degrades another, like wet grip or wear life.
- Capital Intensity:Tire manufacturing requires massive, specialized production facilities with high upfront capital costs, creating a significant barrier to entry for new players and slowing down retooling for existing ones.
Strategic Opportunities
- Sustainable Materials:Commercializing alternative raw materials, such as guayule, Russian dandelion, and recycled plastics, offers a path to reduce dependence on traditional rubber sources and appeal to environmentally conscious consumers.
- Non-Pneumatic Tire Technology:Airless tire designs present an opportunity to eliminate punctures and reduce maintenance for specific applications, including autonomous shuttles, off-road vehicles, and industrial equipment.
- Integrated Fleet Solutions:Developing service models that bundle tires with sensor data, predictive maintenance analytics, and on-site servicing can create new, recurring revenue streams from commercial fleet operators.
Industry Challenges
- End-of-Life Management:Managing the environmental impact of scrap tires remains a persistent challenge, requiring significant investment in recycling infrastructure and the development of circular economy business models.
- Complex Compliance Landscape:Manufacturers must navigate a fragmented and evolving set of global regulations, including the EU's REACH chemical standards, China's GB standards, and various national safety certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tires Market |
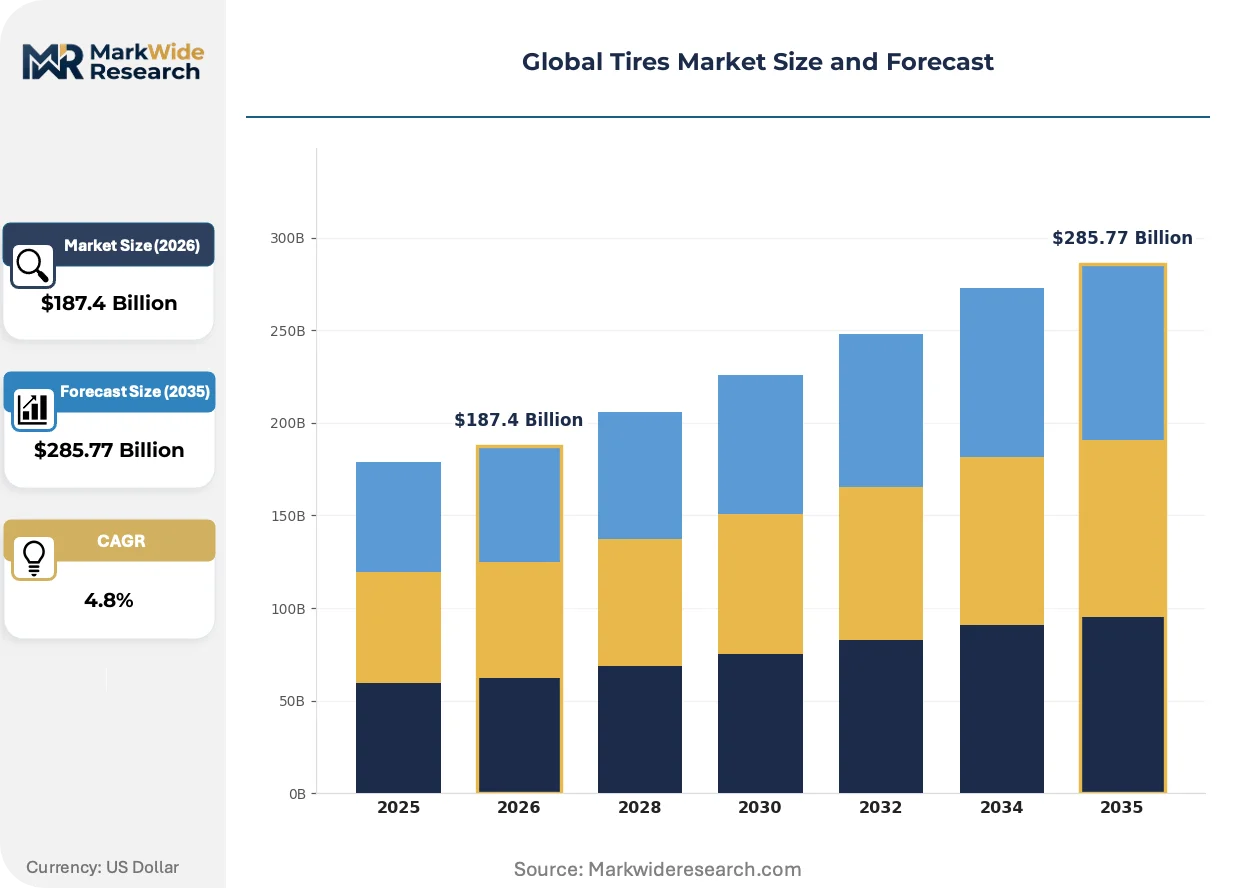
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Tires, Bias Tires, Run-Flat Tires, Tubeless Tires, Tube-Type Tires Application: Passenger Cars, Commercial Trucks, Two-Wheelers, Agriculture Vehicles, Construction Machines End User: OEMs, Tire Dealers, Fleet Operators, Aftermarket Service Providers Distribution Channel: Offline Retail, Online Platforms, Wholesale Distributors, Direct Sales |
| Companies Covered | Bridgestone Corporation, Michelin Group, Goodyear Tire & Rubber Company, Continental AG, Pirelli & C. S.p.A., Sumitomo Rubber Industries Ltd., Hankook Tire & Technology Co. Ltd., Yokohama Rubber Co. Ltd., ZC Rubber, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tires Market Strategic Shifts & Innovations
Material science is converging with digital technology to redefine tire performance and lifecycle management. This intersection creates products that are not just passive components but active contributors to vehicle efficiency, safety, and data generation, reshaping the industry's value proposition.
Embedded sensor technology is a key area of product evolution. These smart tires incorporate internal sensors that go beyond basic pressure monitoring to track temperature, load, and tread wear in real time. Commercial fleets and premium automotive brands are the primary adopters, seeking to optimize performance and safety. This technology is unifying tire maintenance, driver feedback, and vehicle dynamics into integrated, data-driven platforms for predictive management.
The EU's Corporate Sustainability Reporting Directive (CSRD) is forcing a profound shift in operational transparency. This regulation requires large companies to disclose detailed information on environmental and social impacts throughout their value chain. For tire makers, this means providing auditable proof of sustainable sourcing for materials like natural rubber and managing the carbon footprint of production, directly affecting supplier selection and global logistics strategies.
A shift from transactional sales to performance-based contracts is altering procurement patterns for large-scale users. Instead of purchasing tires outright, some commercial fleet operators now pay on a per-kilometer or per-hour basis, with the manufacturer retaining ownership and responsibility for maintenance. This model is gaining traction in the European heavy-duty trucking and mining sectors, where uptime and predictable costs are paramount.
Global Tires Market Segmentation
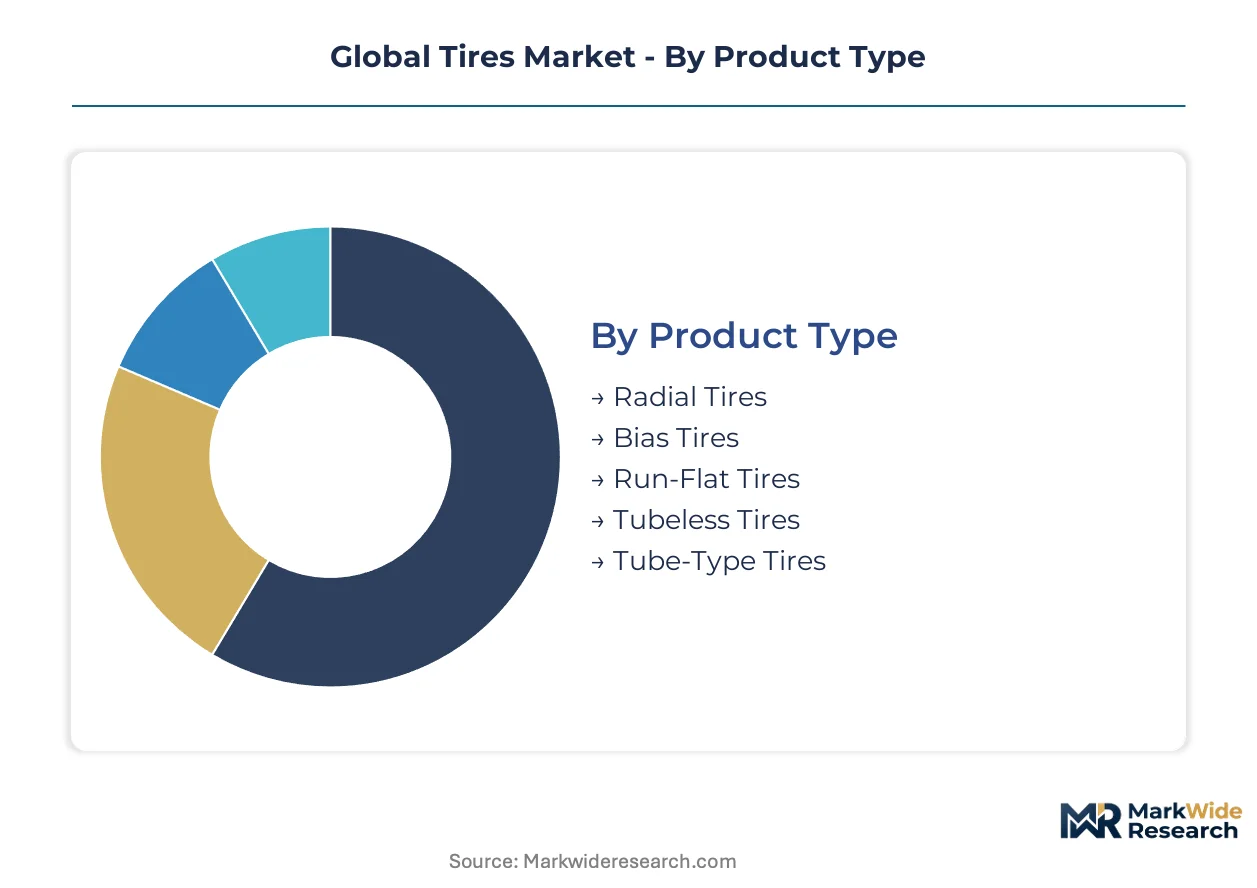
Understanding the Global Tires Market through segmentation reveals how diverse product engineering and distribution strategies address varied end-user requirements. This granular view highlights the specialized production capabilities required for distinct tire types and their applications across global vehicle fleets.
Product Type:
The capital intensity of tire manufacturing facilities often dictates which product types receive the most investment for retooling and expansion.
- Radial Tires:These tires feature body ply cords oriented at 90 degrees to the direction of travel, with steel belts under the tread, offering superior handling, fuel efficiency, and longer tread life. Demand from passenger cars and commercial trucks across Europe and North America drives continuous innovation for lower rolling resistance.
- Run-Flat Tires:Engineered with reinforced sidewalls or internal support rings, these tires allow a vehicle to be driven for a limited distance after a puncture, eliminating the need for an immediate spare tire change. Premium automotive brands in Germany and Japan integrate run-flat technology to enhance safety and vehicle design flexibility.
- Bias Tires:Characterized by body ply cords laid diagonally from bead to bead, bias tires are generally more resistant to sidewall damage.
- Tubeless Tires:These tires rely on a tight seal between the tire and the wheel rim to hold air, reducing weight and improving safety by preventing sudden air loss.
- Tube-Type Tires:Requiring an inner tube to maintain air pressure, these tires are commonly found in two-wheelers and some older vehicle models.
Radial Tires absorbs the bulk of installed capacity; Run-Flat Tires is expanding most quickly.
Application:
Volume considerations heavily influence manufacturing scale and material procurement strategies across different vehicle applications.
- Passenger Cars:Tires for passenger vehicles prioritize a balance of handling, comfort, and fuel efficiency, designed for a wide range of driving conditions. The vast global vehicle parc, especially in China and India, generates consistent demand for both original equipment and aftermarket replacements.
- Commercial Trucks:These tires are built for durability, heavy load support, and extended mileage, often featuring specialized tread patterns for various terrains and hauling needs. Fleet operators in North America and Europe require robust, long-lasting tires to minimize downtime and operational costs.
- Two-Wheelers:Tires for motorcycles and scooters focus on grip, maneuverability, and stability, tailored to diverse road surfaces and riding styles.
- Agriculture Vehicles:Designed for traction on soft or uneven terrain, these tires feature deep lugs and robust construction to support heavy machinery in farming operations.
- Construction Machines:Heavy-duty tires for equipment like excavators and loaders require extreme resistance to punctures and cuts, alongside high load-carrying capacity.
The Passenger Cars segment sees significant investment due to its sheer scale; Commercial Trucks commands premium pricing for specialized durability.
End User:
Customer type defines the sales approach and the specific performance and cost criteria that tire manufacturers must meet.
- OEMs:Original Equipment Manufacturers procure tires directly from manufacturers for installation on new vehicles at the factory. Electric vehicle manufacturers demand tires with specific low rolling resistance and noise reduction properties.
- Fleet Operators:Companies managing large vehicle fleets, such as logistics firms or rental agencies, purchase tires in bulk, often seeking long-term performance contracts and integrated maintenance solutions. Commercial fleet operators prioritize uptime and predictable costs for their extensive vehicle networks.
- Tire Dealers:These retail outlets sell tires directly to consumers and provide installation and maintenance services.
- Aftermarket Service Providers:Garages and service centers offer tire replacement and repair services to vehicle owners, sourcing tires from distributors or directly from manufacturers.
OEMs exert considerable influence on product specifications; Fleet Operators are increasingly adopting performance-based procurement models.
Distribution Channel:
The maturity of distribution channels impacts market access and customer reach for tire products globally.
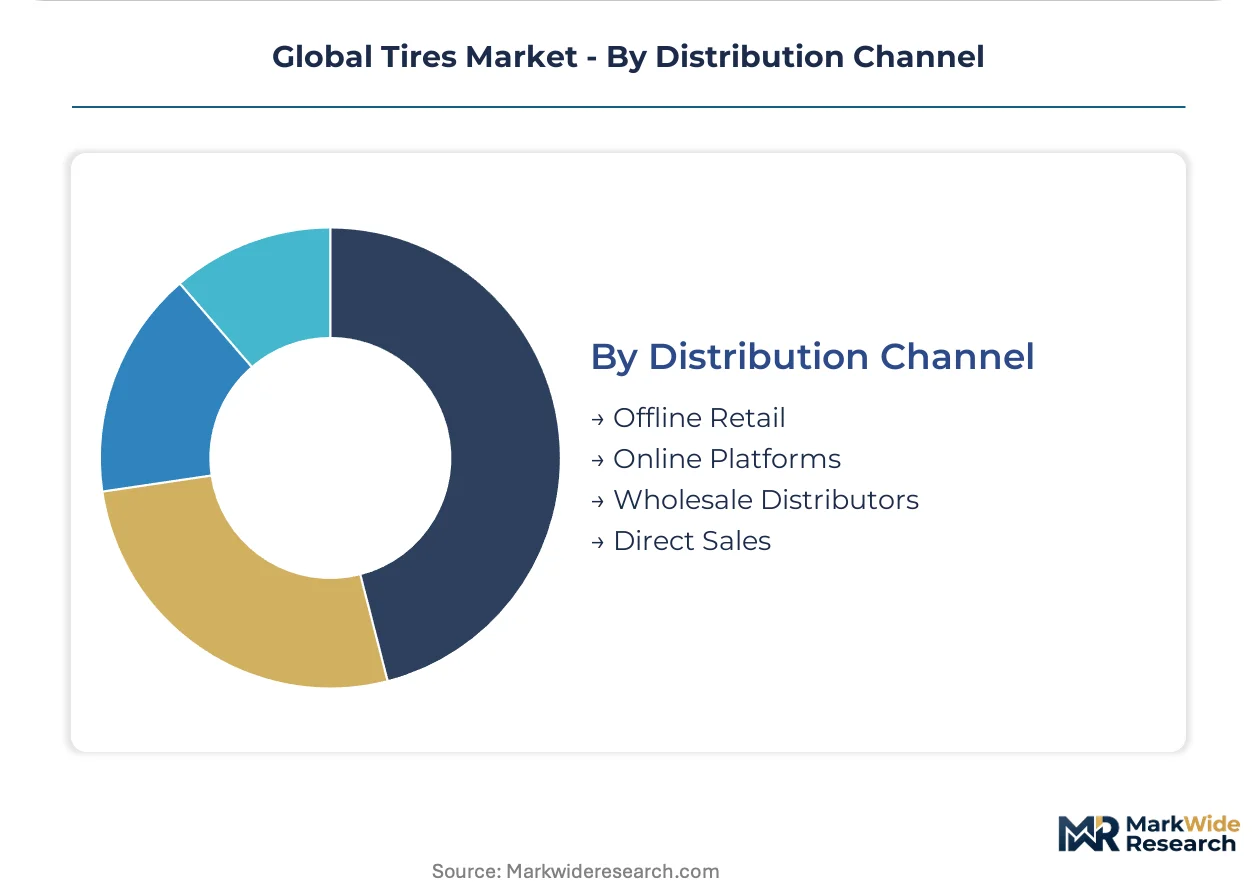
- Offline Retail:Traditional brick-and-mortar stores, including independent tire shops and automotive service centers, offer personalized service, physical inspection, and immediate installation. Local consumers in emerging markets like India often prefer the direct interaction and service provided by offline retail channels.
- Online Platforms:E-commerce websites and digital marketplaces allow consumers to compare prices, read reviews, and purchase tires for delivery or installation at a partner location. Convenience-seeking buyers in developed economies like the United States increasingly utilize online platforms for tire purchases.
- Wholesale Distributors:These intermediaries purchase tires in large volumes from manufacturers and supply them to a network of retailers and service providers.
- Direct Sales:Some manufacturers sell tires directly to large fleet operators or OEMs, bypassing traditional retail channels to manage specialized contracts.
Offline Retail remains the dominant channel for immediate replacement; Online Platforms exhibit the steepest expansion trajectory for consumer purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for advanced tires concentrates heavily in major automotive manufacturing hubs and large consumer markets. Electric vehicle adoption and stringent environmental regulations drive innovation across these key geographies. This dynamic environment shapes regional investment and supply chain strategies for tire producers.
China
Demand for passenger car and commercial truck tires remains substantial, driven by vehicle parc expansion. China's GB standards enforce strict safety and performance criteria for market entry. Manufacturing hubs in the Yangtze River Delta focus on high-volume production for both domestic and export markets.
United States
The US market generates strong demand for aftermarket replacement tires and specialized commercial vehicle applications. The US EPA's fuel economy standards compel manufacturers to develop more efficient products. Automotive clusters around Detroit actively integrate new tire technologies into OEM vehicle designs.
Germany
Germany's premium automotive sector requires high-performance tires with advanced handling and safety features. EU tire labeling regulations encourage manufacturers to innovate for lower rolling resistance. Research and development centers in cities like Hanover drive material science advancements for next-generation tires.
India
India's expanding two-wheeler and passenger car segments create sustained, high-volume demand for affordable and durable tires. India's BIS standards ensure product quality and safety within the domestic market. Production facilities in Chennai actively scale up to meet both OEM and aftermarket requirements.
Japan
Japan's automotive industry emphasizes precision engineering and run-flat tire technology for enhanced safety. JIS standards govern the quality and performance of tires manufactured and sold in the country. Advanced material research in Yokohama focuses on developing quieter and more fuel-efficient tire compounds.
Global Tires Market Key Industry Players
European producers anchor one tier of the Global Tires Market, emphasizing advanced technology and integrated solutions; Asian manufacturers hold significant market share through high-volume production and cost efficiency. The market structure is moderately concentrated among a few global players, with numerous regional specialists competing on price and local relevance. Major strategic archetypes include innovation leaders, aftermarket powerhouses, and integrated mobility solution providers. Companies frequently engage in strategic partnerships to expand geographic reach and diversify product portfolios. Capacity expansion in emerging markets also remains a critical competitive move for scale-focused manufacturers.
Among the established global players, Michelin Group exemplifies innovation leadership through extensive research and development in advanced materials. Goodyear Tire & Rubber Company represents a strong aftermarket powerhouse, leveraging its vast distribution network and brand recognition. Continental AG occupies a position as an integrated solutions provider, combining tires with vehicle electronics for enhanced performance. These entities collectively anchor the premium and high-performance segments of the global tire industry.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Michelin Group |
| Goodyear Tire & Rubber Company |
| Continental AG |
| Pirelli & C. S.p.A. |
| Sumitomo Rubber Industries Ltd. |
| Hankook Tire & Technology Co. Ltd. |
| Yokohama Rubber Co. Ltd. |
| ZC Rubber |
Cost & Logistics Intelligence
Electric vehicle manufacturers' demand for low rolling resistance tires impacts how tire producers structure their supply chains, influencing pricing power. This dynamic forces material science innovation and strategic sourcing decisions across the industry.
Pricing Analysis
Volume sales in the passenger car segment generate lower per-unit margins, while specialized commercial truck tires command premium pricing. The dominant pricing model is per-unit transactional, with contract-based long-term offtake agreements common for OEMs and large fleet operators. Price differentiation stems from performance characteristics like fuel efficiency and wet grip, alongside brand premium. Cost compression intensifies due to the consolidated purchasing power of large fleet operators and automotive OEMs. Passenger car aftermarket consumers are generally more price-sensitive, whereas commercial truck fleet operators prioritize total cost of ownership and durability.
Supply Chain Analysis
Dual-sourcing requirements from major automotive OEMs and fleet operators necessitate diversified supplier bases for tire manufacturers. Natural rubber supply concentrates primarily in Southeast Asia, while synthetic rubber production centers in China and the United States. The industry relies heavily on raw materials such as natural rubber, synthetic rubber, carbon black, and steel cord. Commodity price volatility for both natural and synthetic rubber creates a significant supply chain risk. Distribution primarily occurs through wholesale distributors and direct sales channels to OEMs and large fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global tires market is engaged in a vertical-integration race, as manufacturers seek to control critical raw material sourcing to mitigate volatility and secure supply.
For Market Incumbents:
Deepen research and development in sustainable materials like guayule to reduce reliance on volatile natural rubber sources. Consolidate market share through strategic acquisitions in emerging markets, countering the threat from regional specialists. Invest in advanced manufacturing facilities in China or India to leverage scale and meet evolving GB or BIS standards for market access. Control over advanced material formulations is crucial for meeting stringent regulatory demands.
For New Entrants and Emerging Players:
Online platforms offer a direct-to-consumer go-to-market angle, bypassing traditional distribution networks. Target niche applications like autonomous shuttles or off-road vehicles with non-pneumatic tire technology, where maintenance-free operation provides a clear value proposition. Focus on specific regional markets with less stringent regulatory hurdles to establish a foothold. Performance-based contracts for specialized fleets present an opportunity for market penetration.
For Investors and Strategic Acquirers:
The window for entry favors strategic acquirers seeking technology-driven specialists in smart tires or sustainable material science over the next five to ten years. Focus on companies with patented low rolling resistance compounds or integrated fleet solution capabilities. A signal to watch for inflection is the widespread adoption of performance-based contracts in the commercial trucking sector. Targets offering data analytics for tire lifecycle management are particularly attractive.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Emerging Markets | Secures high-volume production to meet demand from rapidly expanding vehicle fleets in India and Southeast Asia. |
| Sustainable Material R&D | Reduces dependence on volatile natural rubber prices and addresses environmental compliance mandates like the EU's CSRD. |
| Integrated Fleet Solutions | Creates new recurring revenue streams by bundling tires with predictive maintenance and sensor data for commercial operators. |
| Non-Pneumatic Tire Development | Opens new market segments in industrial and autonomous vehicles by eliminating puncture risks and maintenance needs. |
| Digital Distribution Channel Expansion | Improves market reach and customer convenience, particularly for aftermarket consumers in developed economies. |
Research Approach
Document review covered regulatory filings, industry association reports, and trade publications, complemented by interviews with tire R&D directors, OEM procurement managers, fleet operators, and aftermarket distributors. This approach combined primary insights with secondary validation. Bottom-up and top-down triangulation ensured data consistency across the market.
The quantitative model produced detailed volume and value forecasts segmented by product type, application, end-user, distribution channel, and key geographies. Compound annual growth rates were derived from historical trends and projected market dynamics over the analysis window. Key forecast inputs included electric vehicle adoption rates and evolving regional fuel efficiency standards.
The model holds under current macroeconomic stability and predictable regulatory frameworks; deviation in global trade policies or raw material supply shocks would shift the outlook materially. Forecasts reflect documented assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Off-The-Road (OTR) Tire Market
Tires and Wheels
E-Bike Tire Market
Tires and Wheels
Commercial Vehicle Forged Aluminum Alloy Wheels Market
Tires and Wheels
Tire Retreading Market
Tires and Wheels
Global Electric Vehicle Tire Market
Tires and Wheels
Wheel Market
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
Zeropressure Tires Market
Tires and Wheels
Global Pneumatic Tires Market
Tires and Wheels
Bike Wheels Market
Tires and Wheels
Carbon Wheels Market
Tires and Wheels
United States Tire Market
Tires and Wheels
Global Tire Curing Press Machine Market
Tires and Wheels
Truck and Bus Radial (TBR) Tire Market
Tires and Wheels
Automotive Intelligent Tires Market
Tires and Wheels
Automotive Green Tires Market