
 Global Winter Tires Market | 2026-2036
Global Winter Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Global Winter Tires Market Foresight
Silica-infused tread compounds is reshaping winter tire construction by replacing carbon-black-dominant formulations with materials that retain elasticity below minus thirty degrees Celsius. Bridgestone Corporation leverages its proprietary NanoPro-Tech polymer architecture to sustain grip performance across freeze-thaw cycles. Nokian Tyres plc anchors its competitive position through captive testing facilities north of the Arctic Circle. Continental AG differentiates via integrated sensor-ready tire platforms that feed vehicle stability systems in real time.
Winter tires are specialized pneumatic structures engineered with dedicated tread patterns, flexible rubber compounds, and siping geometries designed to maintain traction on snow, ice, and sub-zero pavement surfaces. Their primary commercial purpose is to reduce braking distances and lateral skid incidence when ambient temperatures fall below seven degrees Celsius, a threshold where all-season compounds harden and lose road contact. Studless tires now command the largest volume share within product type categories, driven by noise restrictions and road surface preservation mandates across Central European jurisdictions. SUVs represent the fastest-expanding vehicle type segment as consumer preference shifts toward higher-weight platforms that impose greater shear loads on winter-optimized contact patches.
The US Department of Transportation through NHTSA maintains minimum performance benchmarks for severe snow traction, while Transport Canada enforces mandatory winter tire requirements on designated mountain highways and Quebec provincial roads. ECE Regulation 117 from the United Nations Economic Commission for Europe governs rolling resistance and wet-grip labeling, directly influencing OEM fitment decisions and aftermarket replacement cycles. Stakeholders must monitor evolving polymer feedstock costs and regional traction-labeling harmonization to calibrate inventory positioning across hemispheric selling seasons.
Market Dynamics
Silica-infused tread compounds are compressing replacement cycles as fleet operators in Nordic logistics corridors accelerate seasonal tire replacement programs to meet tightening EU F-Gas Regulation and REACH compliance frameworks.
Growth Catalysts
- REACH material mandates:The EU F-Gas Regulation drives reformulation of rubber compounds toward low-global-warming-potential alternatives, forcing manufacturers to innovate cold-weather elasticity solutions.
- Fleet electrification:Electric vehicle weight distribution and torque profiles demand specialized winter tire constructions, pulling OEM fitment specifications toward heavier-load-rated designs.
- German Motor Vehicle Safety Standard:Mandatory winter tire fitment during specific months creates predictable replacement demand spikes across Central European distribution channels.
Market Restraints
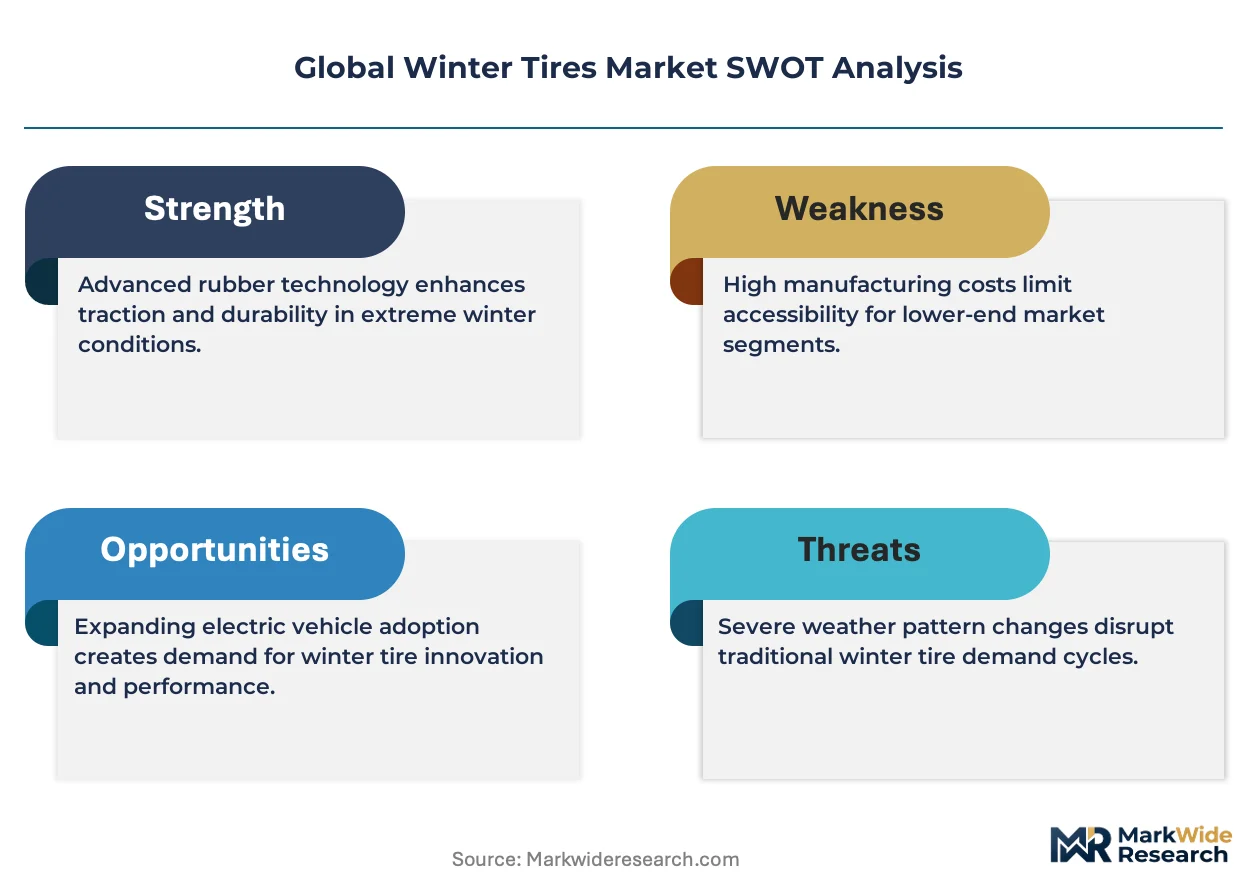
- Petrochemical feedstock volatility:Synthetic rubber and carbon black input costs fluctuate with crude oil benchmarks, compressing margin stability for compound-dependent manufacturers.
- Arctic testing infrastructure concentration:Captive proving grounds north of the Arctic Circle limit independent validation capacity, constraining new market entrants.
- Stud prohibition ordinances:Urban noise restrictions across Austrian, Swiss, and German municipalities eliminate studded tire options for metropolitan fleet operators.
Strategic Opportunities
- Sensor-integrated tire platforms:Real-time pressure and temperature telemetry convergence with vehicle stability systems opens subscription-based fleet monitoring revenue streams.
- Romanian and Polish aftermarket penetration:Underdeveloped winter tire fitment rates in Eastern European passenger vehicle segments present white-space expansion potential.
- ECE Regulation 117 label optimization:Rolling resistance and wet-grip grading alignment with OEM procurement scorecards creates premium positioning leverage for A-grade performers.
Industry Challenges
- Polymer chemistry specialization shortage:Formulation scientists capable of balancing silica dispersion, tear strength, and glass transition temperature are concentrated among incumbent manufacturers.
- Homologation timeline compression:ECE Regulation 117 certification cycles must synchronize with annual vehicle platform launches, squeezing development windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Winter Tires Market |
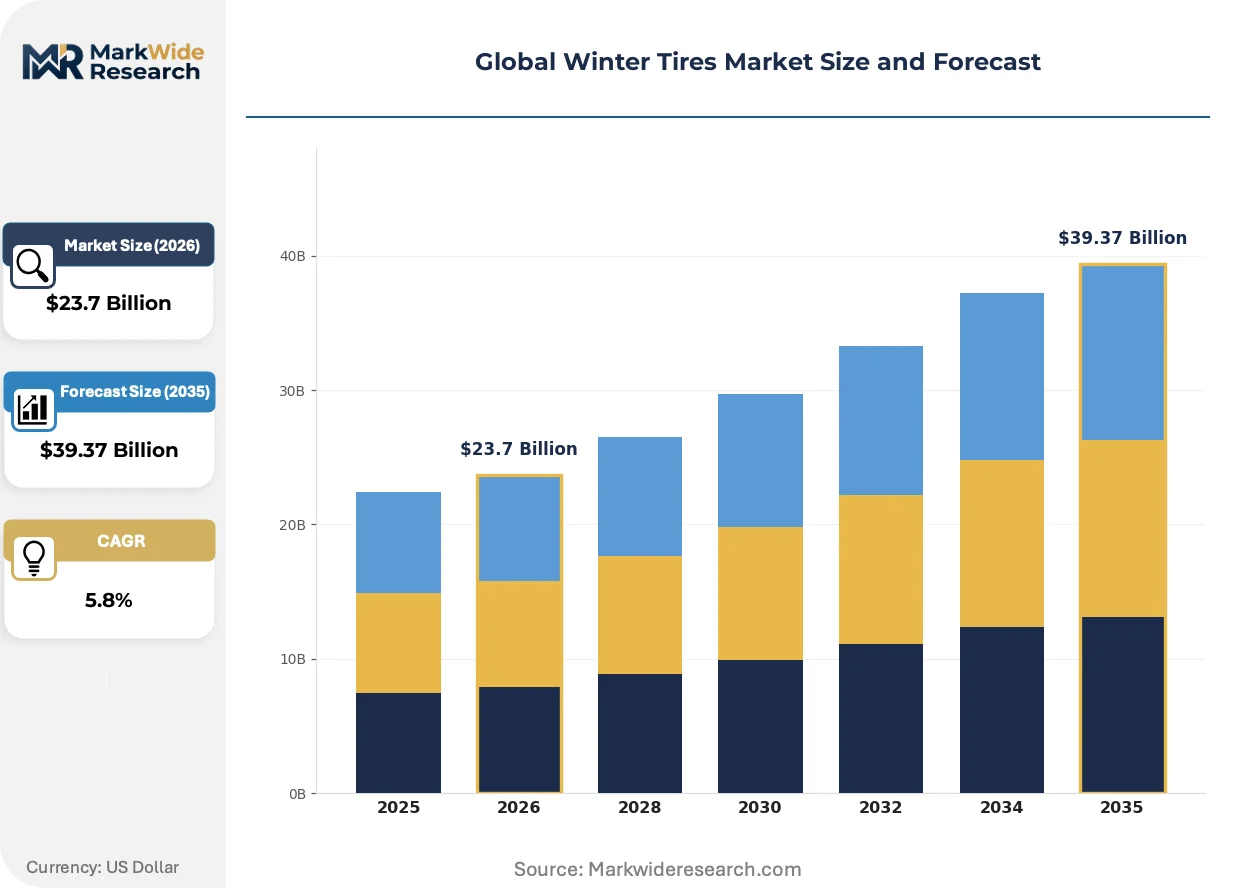
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $39.37 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Studded Tires, Studless Tires, Performance Tires, Run-Flat Tires Vehicle Type: Passenger Cars, Light Commercial Vehicles, SUVs, Heavy Trucks Technology: Silica Compounds, Microporous Rubber, Multi-Layer Construction, Enhanced Grip Tread Distribution Channel: Specialized Dealers, Online Retail, Automotive Service Centers, Wholesale Suppliers |
| Companies Covered | Bridgestone Corporation, Michelin, Continental AG, The Goodyear Tire & Rubber Company, Nokian Tyres plc, Pirelli & C. S.p.A., Hankook Tire & Technology, Sumitomo Rubber Industries, Yokohama Rubber Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Winter Tires Market Shifts & Advancements
Winter tire construction is migrating from mechanical grip enhancement toward material science solutions that maintain compound elasticity across freeze-thaw thermal cycling. Three interconnected developments are compressing traditional design paradigms.
Multi-cellular rubber foam technology is migrating from aerospace insulation applications into tire cavity liners, where trapped air pockets reduce heat transfer and maintain inflation pressure stability across temperature differentials exceeding fifty degrees Celsius. Premium SUV fitment programs at German OEMs are adopting this technology fastest, compressing the performance gap between studless and studded constructions.
REACH authorization procedures for novel chemical substances are extending material qualification timelines from eighteen to thirty-six months, forcing compound laboratories to accelerate pre-registration dossier preparation. Tire manufacturers with captive chemical synthesis capabilities are internalizing regulatory affairs functions that previously relied on external consultants, compressing time-to-market for next-generation tread formulations.
Fleet procurement departments are consolidating seasonal tire contracts under multi-year total-cost-of-ownership frameworks that weight fuel efficiency, retreadability, and warranty claims frequency above unit purchase price. Nordic logistics operators are piloting this model most aggressively, displacing spot-market purchasing through integrated tire lifecycle management agreements that bundle mounting, storage, and disposal services.
Global Winter Tires Market Segmentation
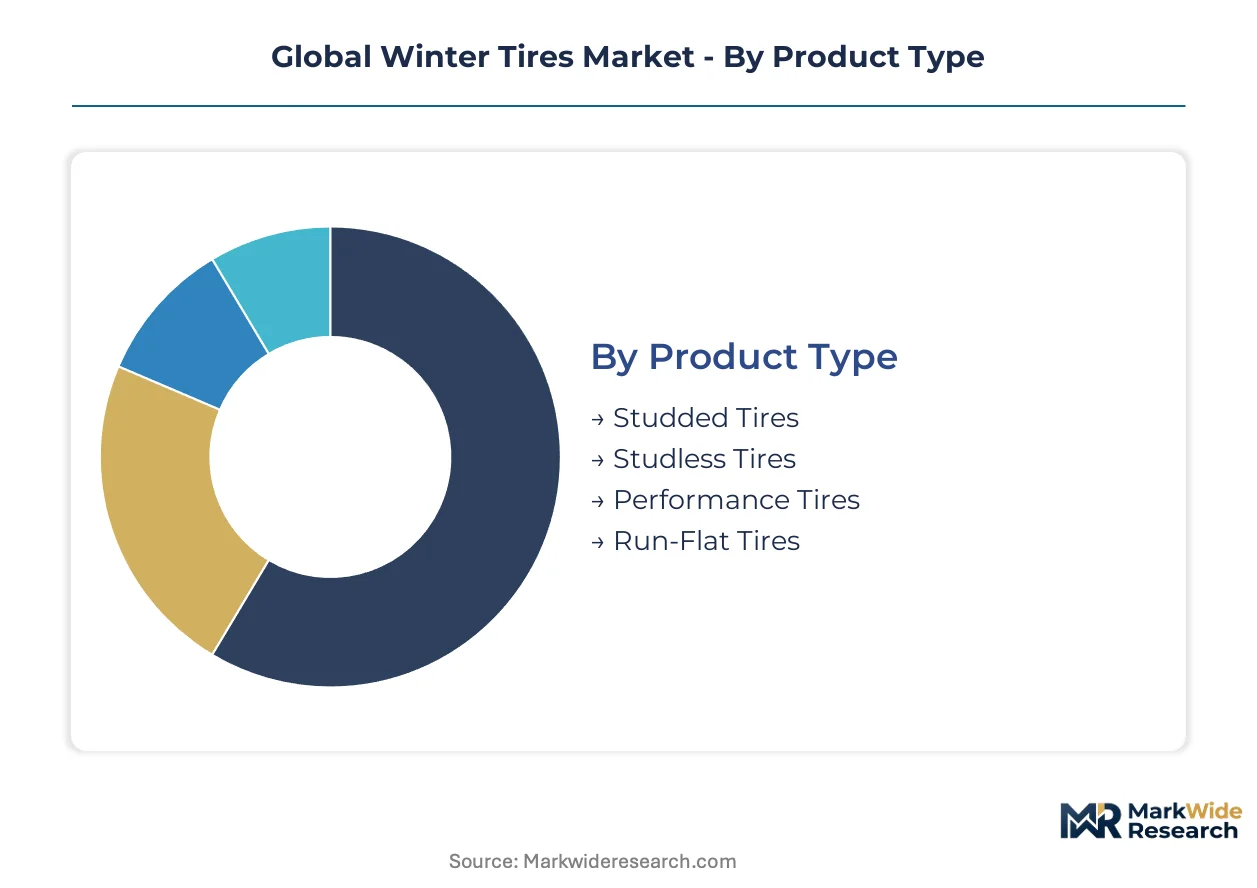
Winter tire segmentation reflects divergent technical requirements across vehicle platforms and climatic severity zones. Product architecture, compound chemistry, and distribution logistics each create distinct competitive battlegrounds with specialized margin profiles.
Product Type:
Mature studded designs coexist with emerging studless formulations as noise ordinances reshape regulatory acceptance across European municipalities.
- Studded Tires:Metal pin inserts bite into ice through pre-drilled tread blocks, delivering maximum traction on bare frozen surfaces. Finnish and Swedish rural fleets sustain demand despite urban prohibition spreads, anchored by Transport Canada mandates on designated mountain highways.
- Studless Tires:Advanced siping geometries and silica-rich compounds generate mechanical grip without road surface damage, now commanding the dominant volume position. German Motor Vehicle Safety Standard compliance drives replacement spikes across Central European distribution channels where noise restrictions eliminate studded alternatives.
- Performance Tires:Speed-rated constructions maintain handling precision on cold dry pavement for premium passenger applications.
- Run-Flat Tires:Reinforced sidewalls permit limited mobility after pressure loss, appealing to safety-focused urban drivers.
Studless tires handle the majority of throughput; performance tires are expanding most quickly on share as OEM fitment specifications tighten.
Vehicle Type:
Cost tier stratification separates mass-market passenger applications from premium SUV and commercial segments with divergent load rating requirements.
- SUVs:Higher curb weights and elevated center-of-gravity dynamics demand reinforced bead constructions and broader contact patches. German premium OEM fitment programs accelerate specialized SKU proliferation as consumer preference shifts toward heavier platforms.
- Heavy Trucks:Drive-axle bias ply configurations and aggressive lug patterns withstand extreme torque loads across Nordic logistics corridors. Fleet electrification pulls specifications toward heavier-load-rated designs as battery weight redistributes axle loading.
- Passenger Cars:Compact dimensions and standardized fitments dominate replacement volume in mature European markets.
- Light Commercial Vehicles:Mixed-use duty cycles balance cargo capacity with cold-weather mobility for contractor and delivery applications.
Passenger cars anchor absolute volume; SUVs are climbing the fastest as platform mix shifts toward higher-weight segments.
Technology:
Supply concentration around proprietary compound architectures differentiates incumbent manufacturers from commodity suppliers.
- Silica Compounds:Precipitated silica dispersion replaces carbon-black-dominant formulations, maintaining elasticity below minus thirty degrees Celsius. REACH authorization timelines extending to thirty-six months favor manufacturers with captive chemical synthesis capabilities.
- Multi-Layer Construction:Hard base compounds support soft tread cap layers, optimizing rolling resistance and snow traction simultaneously. ECE Regulation 117 label optimization creates premium positioning leverage for A-grade performers.
- Microporous Rubber:Trapped air cellular structures reduce heat transfer across extreme temperature differentials.
- Enhanced Grip Tread:Directional groove patterns and 3D siping interlock for slush evacuation and ice bite.
Silica compounds carry the deepest R&D investment; multi-layer construction is gaining share fastest as fuel efficiency regulations tighten.
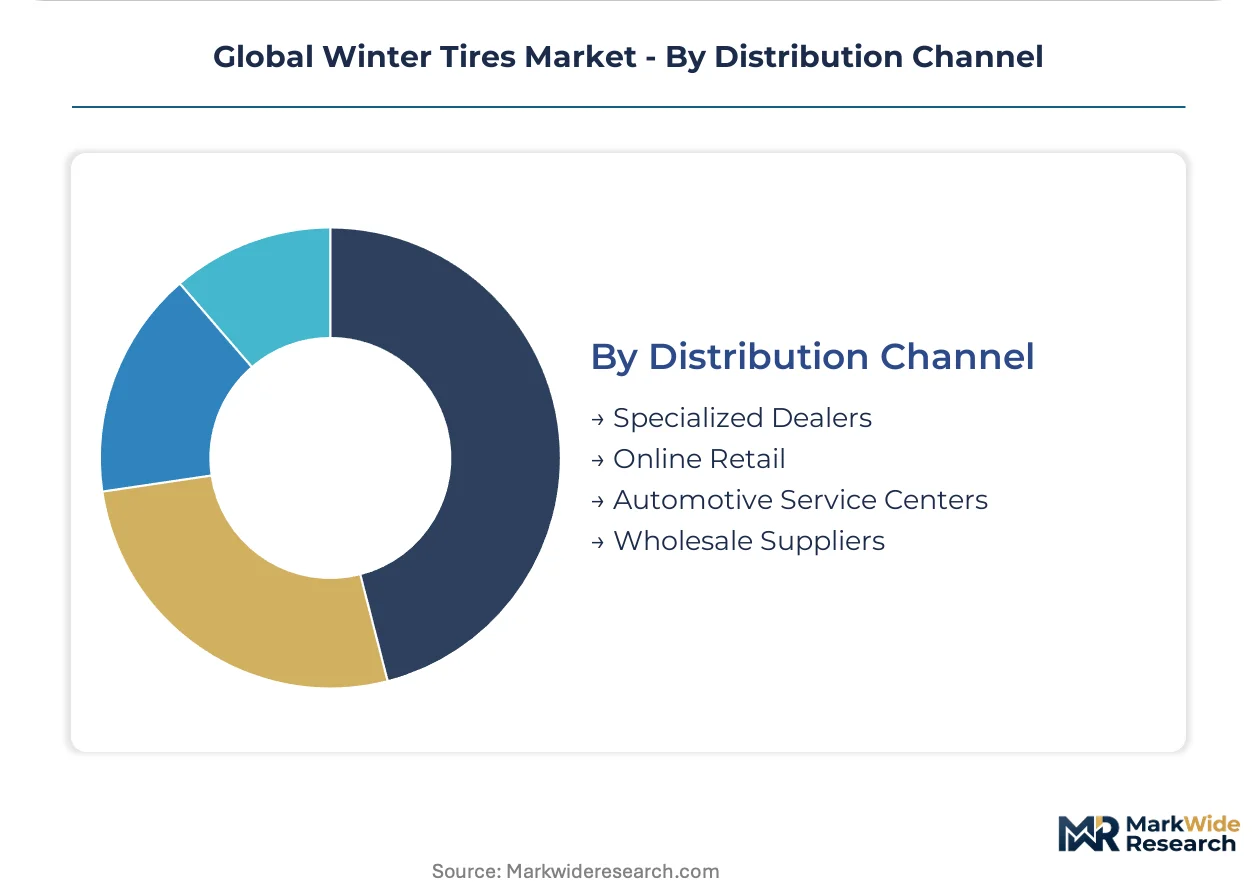
Distribution Channel:
Customer type fragmentation splits between price-sensitive independent installers and integrated fleet procurement departments.
- Specialized Dealers:Technical consultation and seasonal storage services command margin premiums in affluent suburban markets. Nordic logistics operators are consolidating contracts under multi-year total-cost-of-ownership frameworks that bundle mounting, storage, and disposal.
- Automotive Service Centers:Rapid installation capacity and alignment equipment capture emergency replacement demand during first frost events. German distribution channels experience predictable demand spikes as mandatory fitment windows open.
- Online Retail:Price transparency and home delivery convenience attract informed replacement buyers.
- Wholesale Suppliers:Volume aggregation serves independent garages and regional tire chains.
Specialized dealers retain the highest margin pool; automotive service centers are expanding fastest as convenience preferences harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement departments and OEM fitment programs concentrate demand across four distinct national markets where winter tire mandates, logistics corridor density, and premium vehicle production intersect.
Germany
The KBA enforces Motor Vehicle Safety Standard mandates requiring winter tire fitment during specific months, generating predictable replacement demand spikes across Bavarian and North Rhine-Westphalian distribution channels. Premium SUV fitment programs at Stuttgart and Munich-headquartered OEMs accelerate specialized SKU proliferation as platform mix shifts toward heavier-weight segments.
United States
NHTSA maintains minimum performance benchmarks for severe snow traction while state-level mandates in mountainous corridors drive fleet seasonal replacement cycles. The Upper Midwest and Northeast industrial clusters concentrate aftermarket installation capacity, with Minnesota and Michigan distributors capturing emergency replacement demand during first frost events.
Canada
Transport Canada enforces mandatory winter tire requirements on designated mountain highways and Quebec provincial roads, creating regulatory pull-through for heavy-load-rated constructions. Nordic logistics operators across Ontario and Quebec are consolidating contracts under multi-year total-cost-of-ownership frameworks that bundle mounting, storage, and disposal services.
Japan
METI industrial standards and northern prefecture snow belt requirements sustain demand for advanced siping geometries and silica-rich compounds. Nagoya and Tokyo metropolitan manufacturing clusters supply both domestic OEM fitment programs and export markets across East Asian winter climates.
Sweden
Rural fleet operators sustain studded tire demand despite urban prohibition spreads, anchored by Transport Canada-equivalent mandates on designated arterial routes. Arctic Circle proving grounds north of Umeå concentrate captive testing infrastructure that limits independent validation capacity for new market entrants.
Global Winter Tires Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered distribution networks where OEM fitment decisions and aftermarket replacement cycles create divergent margin pools. The market structure consolidates around compound-chemistry leaders with captive Arctic testing infrastructure, mid-scale regional fabricators serving fleet procurement departments, and technology licensors supplying sensor-integrated platforms. Strategic moves concentrate on backward integration into polymer synthesis capabilities and multi-year fleet lifecycle management agreements that displace spot-market purchasing.
Within the premium compound-architecture tier, Bridgestone Corporation and Continental AG exemplify integrated manufacturers with proprietary NanoPro-Tech and sensor-ready tire platforms respectively. Nokian Tyres plc occupies a position representing Arctic-testing-anchored specialists serving Nordic logistics corridors. These three entities sit within distinct competitive archetypes: Japanese-integrated conglomerate, German automotive-systems supplier, and Finnish climate-specialist respectively.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Michelin |
| Continental AG |
| The Goodyear Tire & Rubber Company |
| Nokian Tyres plc |
| Pirelli & C. S.p.A. |
| Hankook Tire & Technology |
| Sumitomo Rubber Industries |
| Yokohama Rubber Company |
| Others |
Supply & Pricing Matrix
Nordic logistics corridors spanning Oslo to Helsinki transmit freight cost volatility directly into winter tire procurement economics, where supply concentration around German and Japanese polymer synthesis hubs amplifies price differentiation between fleet contract tiers and spot-market purchasers.
Pricing Analysis
Cost-plus contracts indexed to Brent crude benchmarks govern long-term fleet supply agreements, while spot purchasers absorb petrochemical feedstock swings immediately. Pricing stratifies across premium certified, standard fitment, and economy replacement tiers, with ECE Regulation 117 A-grade labeling commanding measurable premiums. Cost compression in economy segments is intensifying because carbon black and synthetic rubber input costs track oil volatility. Fleet procurement departments exhibit lowest price sensitivity due to total-cost-of-ownership frameworks, whereas independent installers face highest sensitivity during emergency replacement spikes.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Japanese trading houses sustain working capital for tire manufacturers amid raw material prepayment requirements. Manufacturing concentrates in Germany, Japan, and South Korea, with compounding operations drawing from Malaysian natural rubber, Russian carbon black, and Chinese precipitated silica. Single-source vulnerability around Arctic Circle proving grounds limits independent validation capacity for new formulations. Distribution runs through specialized dealers in affluent suburbs and automotive service centers capturing emergency demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global winter tire penetration remains in early-cycle expansion as Eastern European fitment rates lag Nordic benchmarks, creating runway for volume growth before saturation dynamics emerge.
For Market Incumbents: Insulate compound-architecture advantages through captive chemical synthesis capabilities that compress REACH authorization timelines from thirty-six months. Defend against Nordic logistics fleet consolidation by locking multi-year lifecycle management agreements bundling mounting, storage, and disposal before procurement departments centralize contracts. For New Entrants and Emerging Players: Build out aftermarket presence in Romanian and Polish passenger segments where winter tire fitment rates trail German benchmarks by substantial margins. Target automotive service centers with rapid installation capacity and alignment equipment, leveraging convenience positioning against specialized dealer technical consultation. For Investors and Strategic Acquirers: Sensor-integrated tire platform specialists with real-time telemetry capabilities represent the most attractive acquisition archetype as vehicle stability system convergence accelerates. Monitor ECE Regulation 117 label optimization progress as the inflection signal indicating which compound laboratories will capture OEM procurement scorecard premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Synthesis | Captive chemical capabilities compress REACH authorization timelines and protect formulation secrecy. |
| Multi-Year Fleet Lifecycle Agreements | Nordic logistics operators displace spot purchasing through bundled mounting, storage, and disposal services. |
| Arctic Testing Infrastructure Expansion | Proving grounds north of the Arctic Circle validate cold-weather elasticity below minus thirty degrees Celsius. |
| Sensor-Ready Tire Platform Development | Real-time pressure and temperature telemetry feeds Continental AG and similar vehicle stability systems. |
| ECE Regulation 117 Label Optimization | A-grade rolling resistance and wet-grip performers capture German OEM procurement scorecard premiums. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, ECE Regulation 117 certification databases, and OEM procurement disclosures. Primary interviews engaged tire compound laboratory directors, fleet procurement managers at Nordic logistics operators, automotive service center owners, and polymer feedstock procurement leads. Secondary validation drew from KBA registration statistics, Transport Canada highway mandate documentation, and SEC filings of publicly traded tire manufacturers. Bottom-up volume modeling triangulated against top-down market sizing across product type, vehicle platform, and regional clusters.
Forecast inputs incorporate vehicle production schedules, fleet electrification penetration curves, and REACH authorization timeline extensions across the analysis window. Segmentation dimensions modeled include studded versus studless product architecture, SUV versus passenger car platform mix, silica compound versus multi-layer construction technology, and specialized dealer versus automotive service center channel dynamics. CAGRs were derived from regression analysis of historical replacement cycles against regulatory mandate expansion. Industry-specific inputs encompass ECE Regulation 117 label adoption rates and EU F-Gas Regulation compliance cost trajectories.
Stress conditions across petrochemical feedstock volatility, REACH authorization delays, and fleet electrification acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and OEM platform launch timing. Macroeconomic contraction, abrupt regulatory relaxation, or breakthrough all-season compound technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
North America 2-Wheeler Replacement Tire Market
Tires and Wheels
Global Tires Market
Tires and Wheels
Off-The-Road (OTR) Tire Market
Tires and Wheels
Saudi Arabia Tire Market
Tires and Wheels
Automotive 3D Printed Tires Market
Tires and Wheels
North America Alloy Wheels Market
Tires and Wheels
Intelligent Tire Market
Tires and Wheels
Solid Tire Market
Tires and Wheels
Automotive Carbon Wheels Market
Tires and Wheels
Tire & Wheel Cleaners Market
Tires and Wheels
Forestry Equipment Tire Market
Tires and Wheels
Bicycle Rim Brake Market
Tires and Wheels
South Korea Automotive Carbon Wheels Market
Tires and Wheels
Global OTR Tires Market
Tires and Wheels
Global Advanced Tires Market
Tires and Wheels
Ground Support Equipment Tires Market