
 Rail Road Wheels Market | 2026-2036
Rail Road Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Road Wheels Market Analytics
The divergence between premium forged wheels and commodity cast products is repositioning procurement strategies across rail networks. Amsted Rail Company leverages vertical integration from steelmaking to finishing to sustain margin control in North American freight. Nippon Steel Corporation anchors supply to Japanese Shinkansen operators through metallurgical precision in high-carbon grades. Lucchini RS specializes in forged monobloc designs that dominate European passenger corridors requiring thermal fatigue resistance.
Rail road wheels are steel or alloy discs mounted on axles to support rail vehicle weight, transmit traction, and brake forces, typically manufactured through casting or forging with subsequent heat treatment to achieve hardness between 321-388 BHN for tread surfaces. Their primary purpose is ensuring safe, durable rolling contact with rails under cyclic mechanical and thermal stress. Steel wheels occupy the largest installed base across freight and legacy passenger fleets where replacement volume sustains aftermarket revenue pools. Composite wheels are gaining traction in high-speed rail applications where unsprung mass reduction directly improves ride quality and energy efficiency. Alloy wheels command premium positioning in industrial mining segments where axle loads exceed 35 tonnes and thermal cracking resistance determines wheel life.
The Federal Railroad Administration enforces minimum tread wear limits and thermal damage protocols that compel Class I railroads into predictive replacement schedules rather than run-to-failure models. In Europe, the EU Agency for Railways coordinates EN 13262 interoperability standards that shape wheelset design certification and cross-border market access. China's National Railway Administration imposes domestic GB standards that CRRC Corporation and Taiyuan Heavy Industry must satisfy for state procurement eligibility. Stakeholders must monitor how diverging carbon-accounting rules across jurisdictions reshape material sourcing and energy-intensive heat treatment processes.
Market Dynamics
Freight railroads face accelerating wheel replacement cycles as FRA axle load mandates tighten and thermal damage protocols force predictive maintenance over run-to-failure models. This regulatory compression is restructuring procurement toward certified forged products and fragmenting supplier relationships across North American and European networks.
Growth Catalysts
- Heavy-haul mining corridors:Australian and Brazilian bulk commodity routes operate under extreme duty cycles that compress replacement intervals and sustain aftermarket volume.
- EN 13262 interoperability standards:The EU Agency for Railways coordinates certification requirements that shape wheelset design and unlock cross-border procurement pools.
- Composite wheel adoption:High-speed rail operators deploy carbon-fiber reinforced designs to reduce unsprung mass and improve energy efficiency on passenger corridors.
Market Restraints
- Scrap steel price volatility:Electric arc furnace feedstock costs fluctuate with construction sector demand, squeezing margin on commodity cast wheel production.
- Supplier concentration in forged monobloc:European production clusters around northern Italy and Germany create geographic vulnerability for premium passenger wheel supply.
- Technical ceiling on cast products:Microstructural porosity limits in sand-cast wheels prevent certification for axle loads above 25 tonnes on heavy-haul routes.
Strategic Opportunities
- Indian freight electrification:Dedicated freight corridors under Ministry of Railways expansion create demand for wheels rated to 32.5-tonne axle loads on new broad-gauge networks.
- EU Green Deal carbon accounting:Embedded emissions disclosure requirements favor domestic European producers with renewable-powered heat treatment facilities.
- Digital twin integration:Convergence of ultrasonic testing data with predictive analytics enables condition-based replacement contracts with Class I railroads.
Industry Challenges
- Metallurgical technician shortage:Heat treatment expertise for high-carbon grade certification is retiring faster than apprenticeship pipelines replenish in North America.
- Multi-standard compliance timelines:Simultaneous FRA, ERA, and GB standard testing extends product qualification to 18-24 months for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Road Wheels Market |
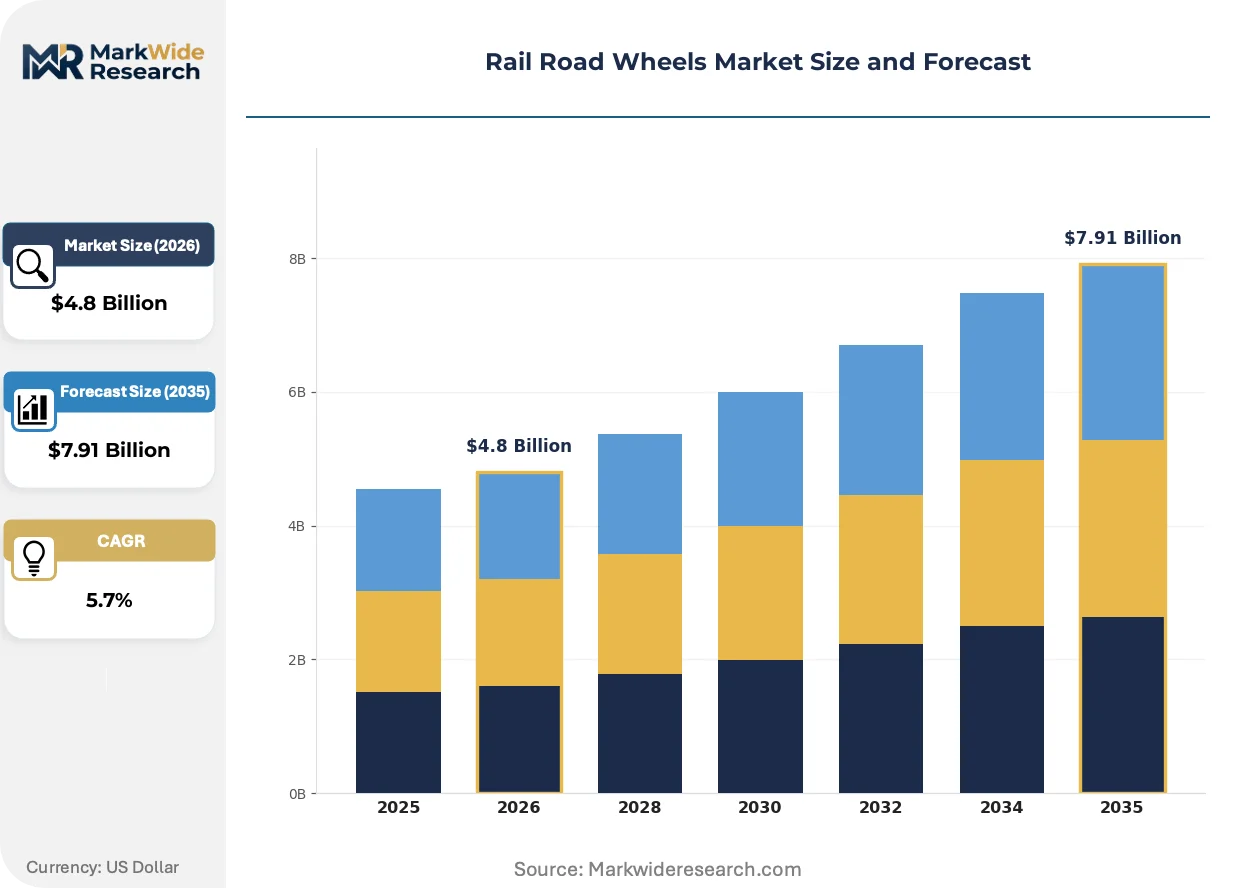
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Wheels, Steel Wheels, Alloy Wheels, Cast Iron Wheels Application: Freight Transport, Passenger Transport, Industrial Use, High-Speed Rail End User: Rail Operators, Railway Maintenance Companies, OEMs, Freight Forwarders Manufacturing Stage: Raw Material Processing, Wheel Casting, Heat Treatment, Quality Testing |
| Companies Covered | Amsted Rail Company, Inc., Nippon Steel Corporation, Lucchini RS S.p.A., GHH-BONATRANS Group, Bharat Forge Limited, ArcelorMittal SA, CRRC Corporation Limited, Interpipe Group, Taiyuan Heavy Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Road Wheels Market Evolving Landscape
Wheel manufacturing is pivoting from commodity casting toward precision-forged designs as thermal fatigue resistance becomes the decisive specification. Digital inspection protocols and alternative material architectures are compressing traditional supply relationships.
Additive manufacturing is decentralizing repair and remanufacturing operations for worn wheel profiles. Deposition welding systems using wire-arc technology rebuild tread surfaces at railyard maintenance facilities rather than central foundries. Union Pacific and BNSF are piloting mobile units that restore 15,000-mile wear profiles without wheelset removal, collapsing logistics costs for intermediate overhauls.
The Federal Railroad Administration updated thermal damage detection protocols in 2024, mandating infrared monitoring systems on all Class I mainlines carrying hazardous materials. Railroads must now install wayside sensors at 40-mile intervals, triggering immediate wheelset inspection for temperature excursions above 400°F. This enforcement shift is accelerating sensor hardware procurement and predictive analytics software deployment across the US freight network.
Asset-light service contracts are displacing unit-price wheel procurement among European passenger operators. Deutsche Bahn and SNCF now contract full wheelset lifecycle management to suppliers, transferring inventory risk and inspection liability in exchange for per-kilometer fees. This restructuring concentrates volume with forged specialists capable of metallurgical traceability and rapid turnaround at maintenance depots.
Rail Road Wheels Market Segmentation
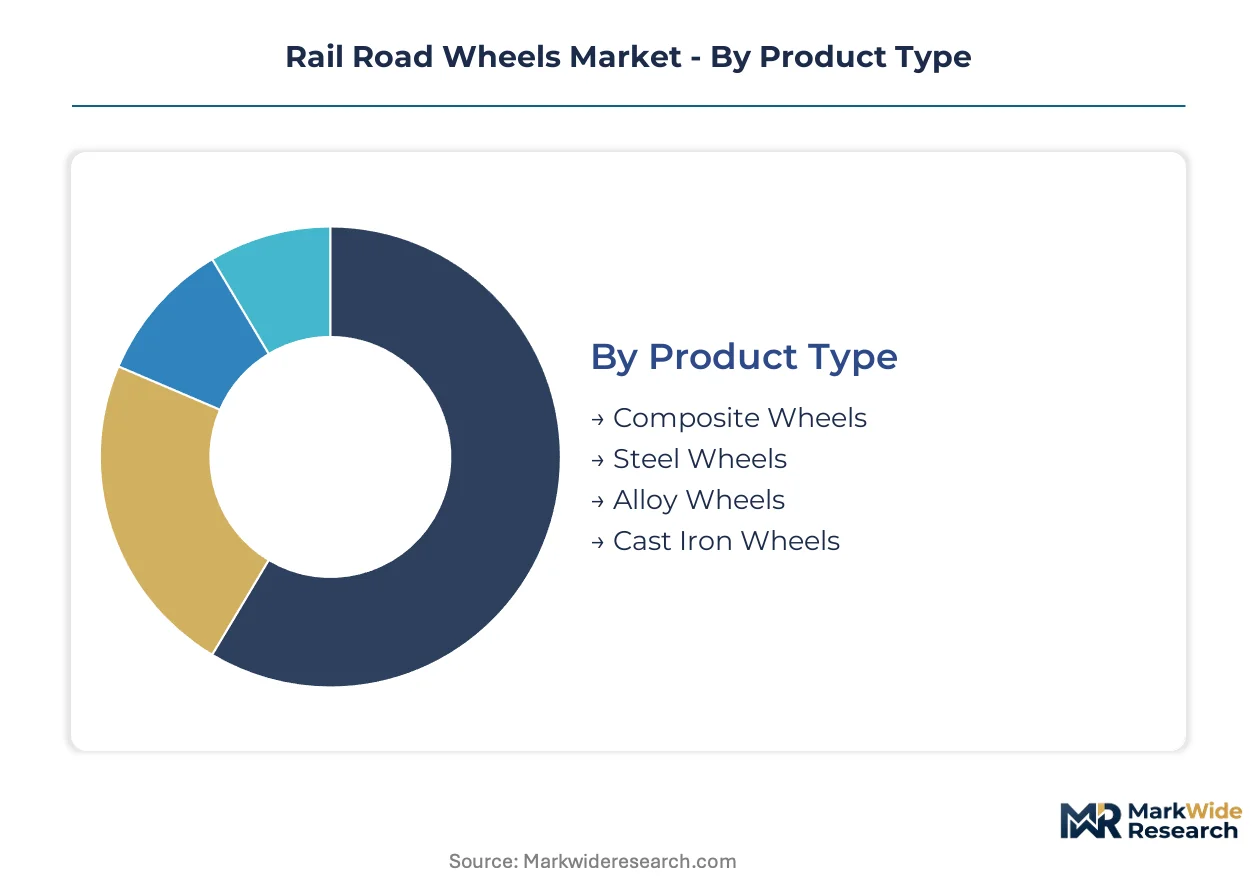
Rail road wheels segment across material grades, duty cycles, and procurement relationships that reshape supplier economics. Procurement patterns diverge sharply between heavy-haul freight operators replacing wheels on predictive schedules and passenger rail contracting full lifecycle management.
Product Type:
Buyers in this category separate by axle load requirements and thermal fatigue tolerance rather than upfront unit cost.
- Steel Wheels:Forged or cast carbon steel discs with tread hardness of 321-388 BHN dominate installed base across North American Class I freight fleets. Replacement volume concentrates in coal and intermodal corridors where FRA axle load mandates compress service intervals.
- Alloy Wheels:High-carbon grades with enhanced thermal cracking resistance command premium positioning in Australian and Brazilian mining routes exceeding 35-tonne axle loads. Metallurgical precision requirements limit certified suppliers to forged specialists with captive steelmaking.
- Composite Wheels:Carbon-fiber reinforced designs reduce unsprung mass for high-speed rail energy efficiency gains.
- Cast Iron Wheels:Lower-cost sand-cast products serve legacy passenger fleets and industrial switching yards with moderate duty cycles.
Volume sits with Steel Wheels; growth tilts toward Alloy Wheels.
Application:
Duty cycle intensity and regulatory exposure determine wheel specification and replacement economics across transport modes.
- Freight Transport:Heavy-haul bulk commodity routes in Australia, Brazil, and Russia operate under extreme cyclic loading that compresses wheel life to 18-24 months. Thermal damage protocols and axle load enforcement sustain aftermarket demand pools.
- High-Speed Rail:Passenger corridors exceeding 250 km/h require forged monobloc designs with ultrasonic-grade material integrity. European networks under EN 13262 certification drive specification toward thermal fatigue-resistant grades.
- Passenger Transport:Regional and commuter rail operators balance acquisition cost against depot turnaround constraints.
- Industrial Use:Mining and steel mill internal railways subject wheels to abrasive environments and uncontrolled loading.
Freight Transport commands installed base volume; High-Speed Rail offers the steepest expansion trajectory as corridor construction accelerates.
End User:
Procurement authority and technical capability determine whether buyers purchase unit wheels or delegate full lifecycle risk.
- Rail Operators:Class I railroads and state railways with in-house maintenance infrastructure purchase wheels directly from forged specialists. Union Pacific and BNSF negotiate volume contracts tied to predictive replacement schedules.
- Railway Maintenance Companies:Third-party service providers aggregate demand across smaller operators and manage depot-level inventory.
- OEMs:Rolling stock manufacturers specify wheelsets for new-build locomotives and passenger coaches.
- Freight Forwarders:Asset-light logistics firms typically defer wheel procurement to contracted rail operators.
Direct procurement concentrates with Rail Operators; outsourcing momentum favors Railway Maintenance Companies.
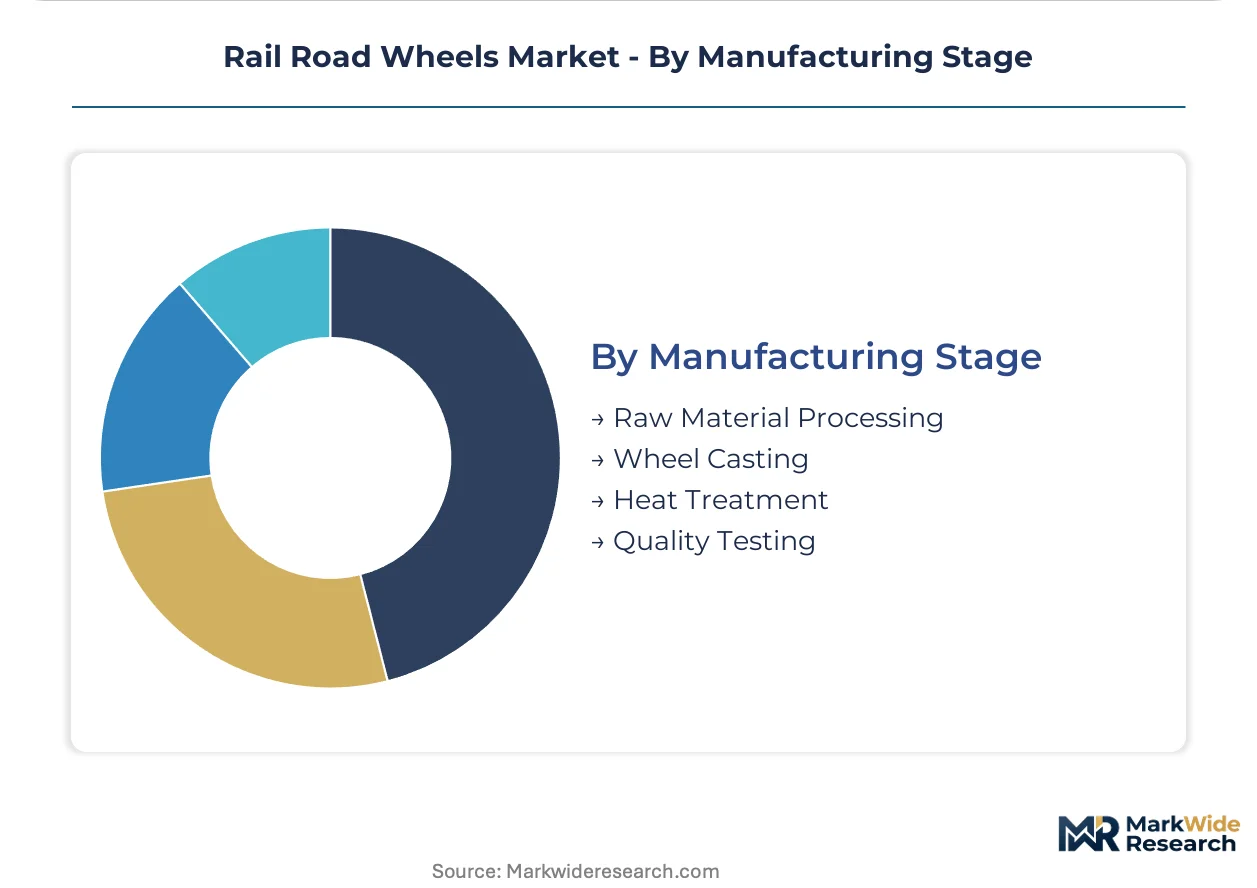
Manufacturing Stage:
Process control and certification requirements fragment value capture across production stages.
- Heat Treatment:Controlled quenching and tempering cycles achieve hardness specifications that determine wheel service life. Expertise scarcity in high-carbon grade certification creates supplier stickiness in North America.
- Quality Testing:Ultrasonic and magnetic particle inspection protocols gate EN 13262 and FRA certification. Testing data integration with predictive analytics enables condition-based service contracts.
- Raw Material Processing:Scrap steel selection and electric arc furnace operation influence microstructural consistency.
- Wheel Casting:Sand casting for commodity grades versus precision forging for premium applications.
Process value concentrates in Heat Treatment; digital integration is expanding fastest in Quality Testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American rail manufacturing concentration, with the Calumet Region hosting heat treatment facilities serving Union Pacific and BNSF fleet renewal programs. The FRA's 2024 thermal damage protocols are accelerating sensor deployment and predictive replacement cycles across heavy-haul corridors.
United States
Class I railroads operate 140,000 route-miles where axle load limits tightened under FRA safety mandates. The Federal Railroad Administration enforces infrared monitoring at 40-mile intervals on hazardous material corridors. Calumet Region foundries in Illinois and Indiana concentrate forged wheel supply for coal and intermodal routes.
Germany
Deutsche Bahn contracts full lifecycle wheelset management to suppliers under per-kilometer fee structures. The EU Agency for Railways coordinates EN 13262 certification requirements that gate cross-border procurement. Ruhr Valley production clusters around Essen and Dortmund supply thermal fatigue-resistant grades to European passenger networks.
China
CRRC Corporation and Taiyuan Heavy Industry satisfy state procurement under GB standards administered by the National Railway Administration. The Shanxi Province steel corridor around Taiyuan integrates electric arc furnace feedstock with precision forging capacity. Dedicated freight corridors under Ministry of Railways expansion demand 32.5-tonne axle load ratings.
Australia
Pilbara mining routes compress wheel replacement intervals to 18-24 months under extreme cyclic loading above 35 tonnes. The country's national rail safety regulator enforces predictive maintenance protocols on heavy-haul bulk commodity corridors. Perth-based maintenance depots coordinate aftermarket volume for iron ore export networks.
Brazil
Vale operates Carajás heavy-haul railway where thermal cracking resistance determines wheel specification in tropical duty cycles. ANVISA coordinates equipment certification parallel to infrastructure safety mandates. São Paulo state foundries supply forged products to southeastern mining and agricultural export corridors.
Rail Road Wheels Market Competitive Landscape
Premium-margin players sit above commodity-margin players across metallurgical precision and certification depth. The vendor base separates into captive steelmaking specialists, regional forging houses, and state-affiliated rolling stock integrators. Three archetypes dominate: vertically integrated producers with in-house heat treatment, technology licensors leveraging metallurgical IP, and scale-driven commodity casters serving replacement volume. Competitive moves concentrate on capacity expansion in high-carbon grade certification and strategic partnerships for digital twin integration.
Among North American integrated producers, Amsted Rail Company exemplifies the captive steelmaking archetype with margin control from raw material through finishing. Nippon Steel Corporation occupies a position representing precision metallurgy for high-speed passenger applications. Lucchini RS sits within the European forging specialist tier, anchoring thermal fatigue-resistant supply to certified corridors. These three illustrate how geographic clustering around regulatory hubs shapes competitive positioning.
| Leading Market Players |
|---|
| Amsted Rail Company, Inc. |
| Nippon Steel Corporation |
| Lucchini RS S.p.A. |
| GHH-BONATRANS Group |
| Bharat Forge Limited |
| ArcelorMittal SA |
| CRRC Corporation Limited |
| Interpipe Group |
| Taiyuan Heavy Industry Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Heat treatment expertise concentration in the Calumet Region and northern Italy widens labor-cost differentials between premium forged wheels and commodity cast products. Pricing stratifies across certification-grade tiers as FRA and EN 13262 compliance costs embed into supplier quotes.
Pricing Analysis
Per-kilometer lifecycle contracts now anchor value-based pricing for European passenger operators transferring inventory risk to suppliers. Price differentiation hinges on metallurgical certification depth and thermal fatigue resistance ratings. Cost compression in sand-cast commodity grades intensifies as scrap steel volatility squeezes electric arc furnace margins. Class I freight railroads exhibit lowest price sensitivity given predictive replacement mandates; regional switching yards show highest sensitivity to unit acquisition costs.
Supply Chain Analysis
Scrap steel supply rests on construction sector demand cycles in the United States, Germany, and China. High-carbon alloy feedstock draws from captive steelmaking operations at Amsted Rail and Nippon Steel. Single-source vulnerability concentrates in forged monobloc supply from northern Italian and German production clusters. Distribution runs through direct procurement contracts with Class I railroads and per-kilometer service agreements with European passenger operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players pursue captive steelmaking control to secure high-carbon grade certification and margin defense against scrap volatility.
For Market Incumbents: Anticipate regulatory compression on thermal damage protocols by securing EN 13262 and FRA certification capacity ahead of compliance deadlines. Deepen backward integration into electric arc furnace feedstock selection to control microstructural consistency. Counter composite wheel substitution threats by demonstrating total-cost-of-ownership superiority in heavy-haul duty cycles. For New Entrants and Emerging Players: Digital twin integration for predictive analytics offers a channel route to bypass incumbent service relationships with Union Pacific and BNSF. Target Australian Pilbara mining corridors where 18-24 month replacement cycles sustain aftermarket volume independent of OEM ties. Pursue condition-based replacement contracts leveraging ultrasonic testing data convergence. For Investors and Strategic Acquirers: Re-rating potential sits with forged specialists possessing captive heat treatment expertise given FRA thermal protocol acceleration. Long-term viability favors producers with renewable-powered facilities positioned for EU Green Deal carbon accounting compliance. Watch Indian freight corridor electrification as inflection indicator for 32.5-tonne axle load demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Steel Sourcing | Captive feedstock selection at Amsted Rail insulates margin from construction sector demand swings. |
| EN 13262 Certification Expansion | Lucchini RS leverages thermal fatigue-resistant grades to lock cross-border procurement pools under EU Agency for Railways coordination. |
| Digital Twin Platform Deployment | Ultrasonic testing data convergence enables condition-based contracts displacing unit-price procurement at Deutsche Bahn. |
| Renewable-Powered Heat Treatment | Domestic European producers with green energy facilities capture embedded emissions disclosure advantages under EU Green Deal rules. |
| Mobile Deposition Welding Units | Union Pacific pilots wire-arc tread rebuilding at railyard facilities collapsing logistics costs for intermediate overhauls. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this rail road wheels analysis. Primary interviews with heat treatment specialists, Class I railroad procurement directors, and EN 13262 certification auditors combined with FRA enforcement documentation and EU Agency for Railways interoperability standards. Secondary sources included Association of American Railroads fleet statistics, ERA technical specifications, and steel trade flow databases. Bottom-up volume modeling triangulated against top-down market sizing across material grade and application segments.
Segment-level granularity modeled steel, alloy, composite, and cast iron product types against freight transport, high-speed rail, passenger transport, and industrial use applications. Geographic clustering captured United States, Germany, China, Australia, and Brazil production and demand centers. CAGRs derived from replacement cycle compression rates under tightening axle load mandates and thermal damage protocol enforcement. Forecast inputs incorporated FRA infrared monitoring deployment timelines and Indian Ministry of Railways electrification corridor expansion.
The model holds under stable regulatory enforcement trajectories; deviation in scrap steel price volatility or metallurgical technician shortage severity would shift supplier margin and capacity expansion timelines. Forecasts reflect assumptions on EN 13262 certification continuity and FRA thermal protocol adherence rates. A small set of triggers—EU carbon accounting implementation pace, Indian axle load standard adoption, and composite wheel certification thresholds—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Connected Tire Market
Tires and Wheels
Truck and Bus Tires Market
Tires and Wheels
Wheel and Tire Service Equipment Market
Tires and Wheels
Europe 2-Wheeler Replacement Tire Market
Tires and Wheels
Continuous Track Wheels Market
Tires and Wheels
Ground Support Equipment Tires Market
Tires and Wheels
Global Tire Curing Press Machine Market
Tires and Wheels
Carbon Wheels Market
Tires and Wheels
EV Tire Market
Tires and Wheels
Asia-Pacific Automotive Tire Pressure Management System Market
Tires and Wheels
Automotive Carbon Wheels Market
Tires and Wheels
Specialty Tire Market
Tires and Wheels
Run Flat Tire Inserts Market
Tires and Wheels
Automotive Racing Slicks Tire Market
Tires and Wheels
Tire Retreading Market
Tires and Wheels
Kuwait Tyres Market