
 North America 2-Wheeler Replacement Tire Market | 2026-2036
North America 2-Wheeler Replacement Tire Market Size, Share, and Industry Trends Forecast 2026-2036
North America 2-Wheeler Replacement Tire Market Analytics
Multi-source procurement among aftermarket distributors is realigning supply relationships across the replacement tire channel. Michelin leverages its premium manufacturing scale to sustain pricing power in touring-grade motorcycle tires. Dunlop anchors its position through deep OEM partnerships that extend into replacement demand. Cooper Tires competes on value-tier positioning for commuter scooters and urban delivery fleets.
The North America 2-wheeler replacement tire comprises circumferential tread structures molded from natural and synthetic rubber compounds with nylon or Kevlar belt reinforcement, engineered to restore grip, load capacity, and speed rating on motorcycles, scooters, mopeds, and electric bicycles after original-equipment wear. Motorcycle tires command the largest volume share given the installed base of internal-combustion bikes, while electric bike tires represent the fastest-expanding product type as lithium-powered commuter adoption climbs. City riding applications dominate replacement frequency due to stop-start abrasion patterns, though off-roading segments carry higher per-unit margins through specialized tread compounds.
NHTSA's Uniform Tire Quality Grading standards and EPA emissions rules for rubber manufacturing shape product compliance costs and factory location decisions across the United States. Health Canada and Mexico's national standards body add cross-border certification layers that filter which suppliers access the full North American aftermarket. Stakeholders must monitor how California's advancing low-carbon material mandates and evolving electric-bike weight classifications recalibrate compound formulations and labeling requirements.
Market Dynamics
Urban food-delivery fleet expansion across Toronto and Chicago is compressing replacement cycles for scooter tires while NHTSA tire-grading standards and EPA rubber-processing rules simultaneously tighten performance benchmarks and manufacturing compliance costs.
Growth Catalysts
- Year-round riding in US Sun Belt states:Arizona, Florida, and Texas sustain above-average wear rates that outpace seasonal northern markets. Delivery density in these states accelerates tire turnover.
- EPA emissions rules for rubber manufacturing:Compliance investments are filtering smaller suppliers and consolidating procurement toward certified producers with verified low-carbon compound capabilities.
- Lithium-powered commuter adoption:Electric bicycle tires represent the fastest-expanding product type as battery-powered urban mobility displaces short car trips.
Market Restraints
- Natural and synthetic rubber input volatility:Petrochemical feedstock price swings and plantation supply disruptions in Southeast Asia compress margin predictability for North American molders.
- Cross-border certification friction:Health Canada and Mexico's national standards body impose non-harmonized testing protocols that fragment supplier access across the trilateral market.
- Off-road tire substitution by retread solutions:Specialized tread compounds for adventure motorcycles face price competition from premium retread services in cost-sensitive rider segments.
Strategic Opportunities
- California low-carbon material mandates:Advanced bio-based rubber formulations can capture preferential procurement from state fleet operators and municipal bike-share programs.
- Multi-source procurement realignment:Aftermarket distributors are consolidating supplier panels, creating entry points for mid-tier manufacturers with certified nylon belt reinforcement capabilities.
- Convergence of Kevlar reinforcement with smart tire sensors:Integrated pressure-monitoring tread structures can command premium positioning in touring-grade replacement channels.
Industry Challenges
- Compound formulation talent scarcity:Formulators with expertise in dual-rubber blends for electric-bike weight classifications are concentrated among legacy OEM suppliers.
- NHTSA Uniform Tire Quality Grading recertification timelines:Updated traction and temperature rating protocols require 18-24 month validation cycles that delay new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America 2-Wheeler Replacement Tire Market |
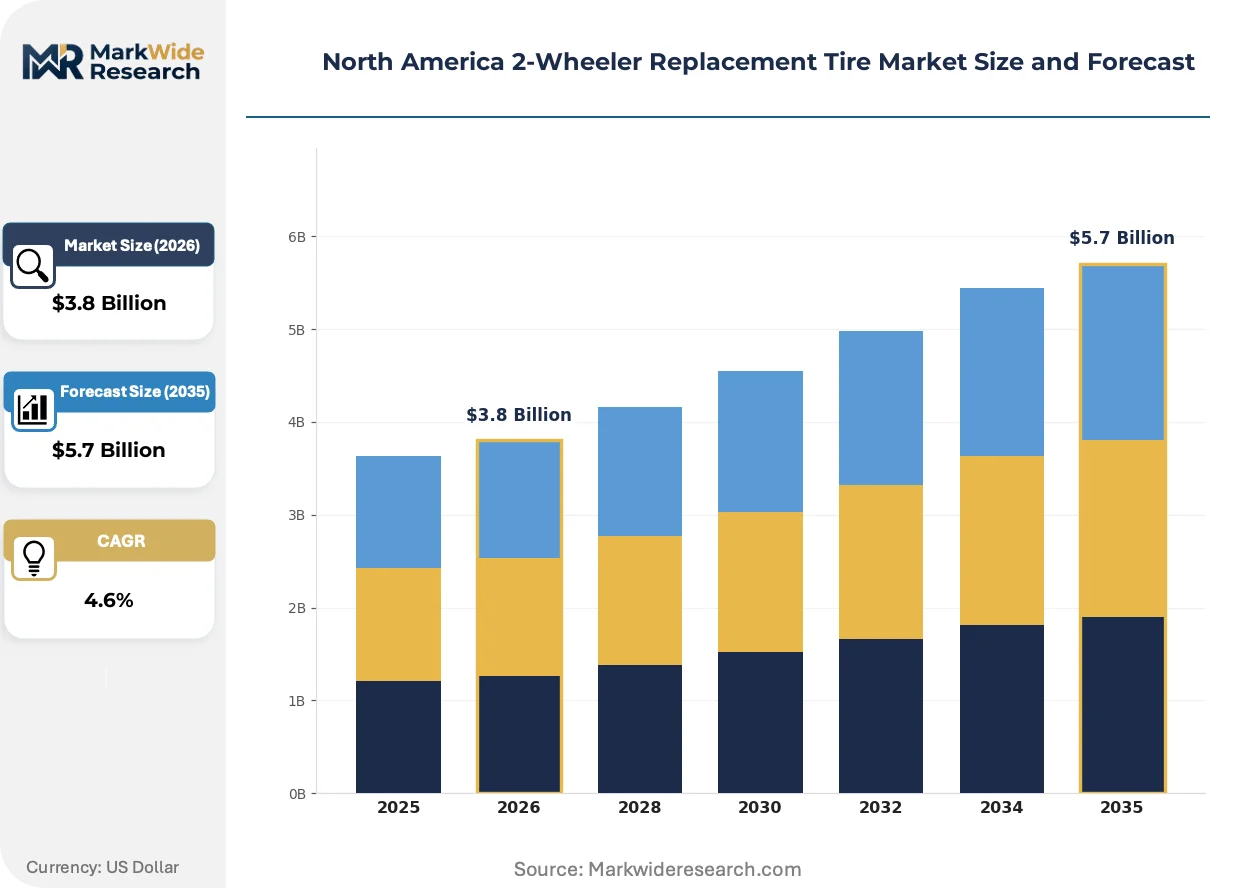
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motorcycle Tires, Scooter Tires, Moped Tires, Electric Bike Tires Application: City Riding, Off-Roading, Touring, Racing Material Type: Rubber, Nylon, Kevlar, Composite Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesalers |
| Companies Covered | Apollo Tyres, BFGoodrich, Cooper Tires, Coker Tire, Dunlop Tires, Michelin, Goodyear, Firestone, Yokohama, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America 2-Wheeler Replacement Tire Market Evolving Landscape
Active reshaping of the North America 2-wheeler replacement tire market centers on automation of manufacturing quality control, tightening emissions compliance for rubber processing, and channel consolidation among fleet procurement officers.
Machine vision tread inspection is automating defect detection in nylon and Kevlar belt layup operations. Tier-one molders in Ohio and South Carolina have deployed these systems across touring-grade motorcycle tire lines. Quality variance is compressing warranty claim rates and reducing manual inspection labor.
California's advancing low-carbon material mandates are recalibrating compound formulation investments across US manufacturing plants. Suppliers must document bio-based content percentages and lifecycle emissions for state procurement eligibility. Electric-bike tire categories face the steepest compliance ramps given their volume growth trajectory.
Fleet procurement officers at urban delivery operators are consolidating supplier relationships into single-source agreements with volume-tier pricing. Multi-brand distributors in Chicago and Toronto are losing share to direct manufacturer contracts. This concentration is most visible in scooter tire categories where replacement frequency justifies inventory holding costs.
North America 2-Wheeler Replacement Tire Market Segmentation
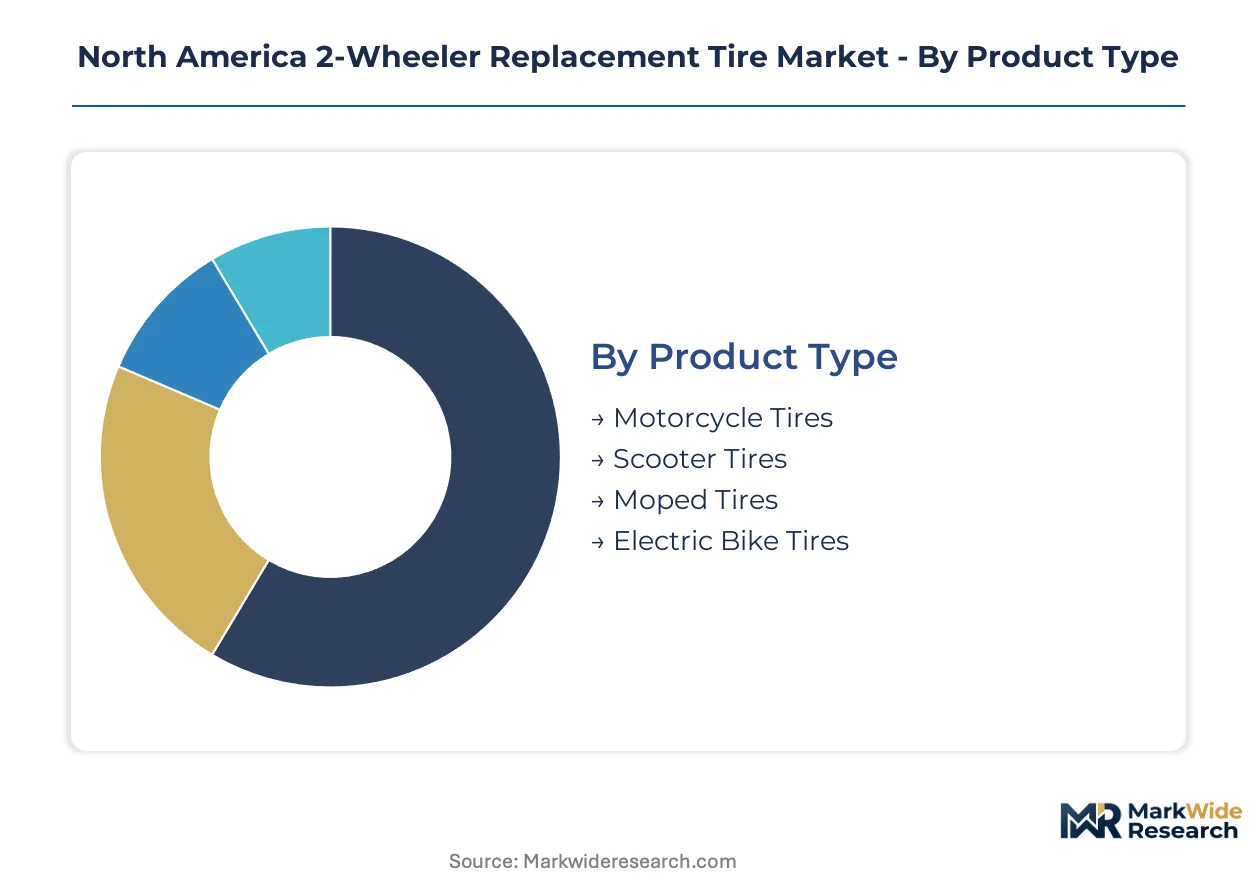
Replacement tire procurement in North America stratifies sharply across vehicle electrification curves, riding intensity patterns, and channel consolidation trends. Segmentation reveals where NHTSA grading burdens, EPA rubber-processing compliance costs, and fleet procurement scale reshape competitive access.
Product Type:
NHTSA Uniform Tire Quality Grading applies universally, yet certification intensity varies: motorcycle and scooter tires face full traction-temperature-treadwear protocols, while emerging electric bike categories navigate evolving weight-classification standards.
- Motorcycle Tires:Circumferential tread structures with nylon or Kevlar belt reinforcement dominate this segment, engineered for internal-combustion touring and cruiser platforms. Demand concentrates in US Sun Belt states where Arizona, Florida, and Texas sustain year-round replacement cycles above seasonal northern markets.
- Electric Bike Tires:Dual-rubber compounds calibrated for lithium-powered commuter weight loads and higher torque profiles define this fastest-climbing category. Toronto and Chicago food-delivery fleets are compressing replacement cycles as urban battery-powered mobility displaces short car trips.
- Scooter Tires:Value-tier positioning serves urban delivery density with frequent stop-start abrasion patterns.
- Moped Tires:Narrower rim-fit specifications address legacy two-stroke and small-displacement four-stroke platforms with declining installed base.
Leading the category by volume: Motorcycle Tires. Expanding most quickly: Electric Bike Tires.
Application:
Margin structure inverts across use cases: city riding generates volume through abrasion-intensive replacement, while off-roading and touring command premium positioning through specialized compound requirements.
- City Riding:Stop-start traffic patterns in dense urban corridors accelerate tread wear and compress replacement intervals. Chicago and Toronto delivery fleet procurement officers are consolidating supplier relationships into direct manufacturer contracts with volume-tier pricing.
- Touring:Extended highway mileage and sustained load conditions demand reinforced belt structures with verified speed ratings. Premium manufacturing scale sustains pricing power for suppliers with certified low-carbon compound capabilities under advancing California mandates.
- Off-Roading:Specialized tread compounds for adventure motorcycles face price competition from retread solutions.
- Racing:Track-day and competition specifications prioritize grip over durability with limited replacement volume.
Highest volume concentration: City Riding. Steepest margin profile: Touring.
Material Type:
Reinforcement selection determines factory capital intensity and compliance documentation burdens under EPA rubber-processing rules and California low-carbon material mandates.
- Rubber:Natural and synthetic compound formulations remain the foundational matrix, with petrochemical feedstock price volatility compressing margin predictability for North American molders. Bio-based content percentages now determine state procurement eligibility.
- Kevlar:Aramid belt reinforcement enables reduced weight and enhanced puncture resistance for premium touring-grade applications. Integration with smart tire sensors is emerging as a premium positioning pathway.
- Nylon:Standard belt reinforcement for mid-tier manufacturing with established machine vision quality control deployment.
- Composite:Multi-material layering approaches balance cost and performance for electric bike weight classifications.
Dominant by installed base: Rubber. Fastest technology migration: Kevlar.
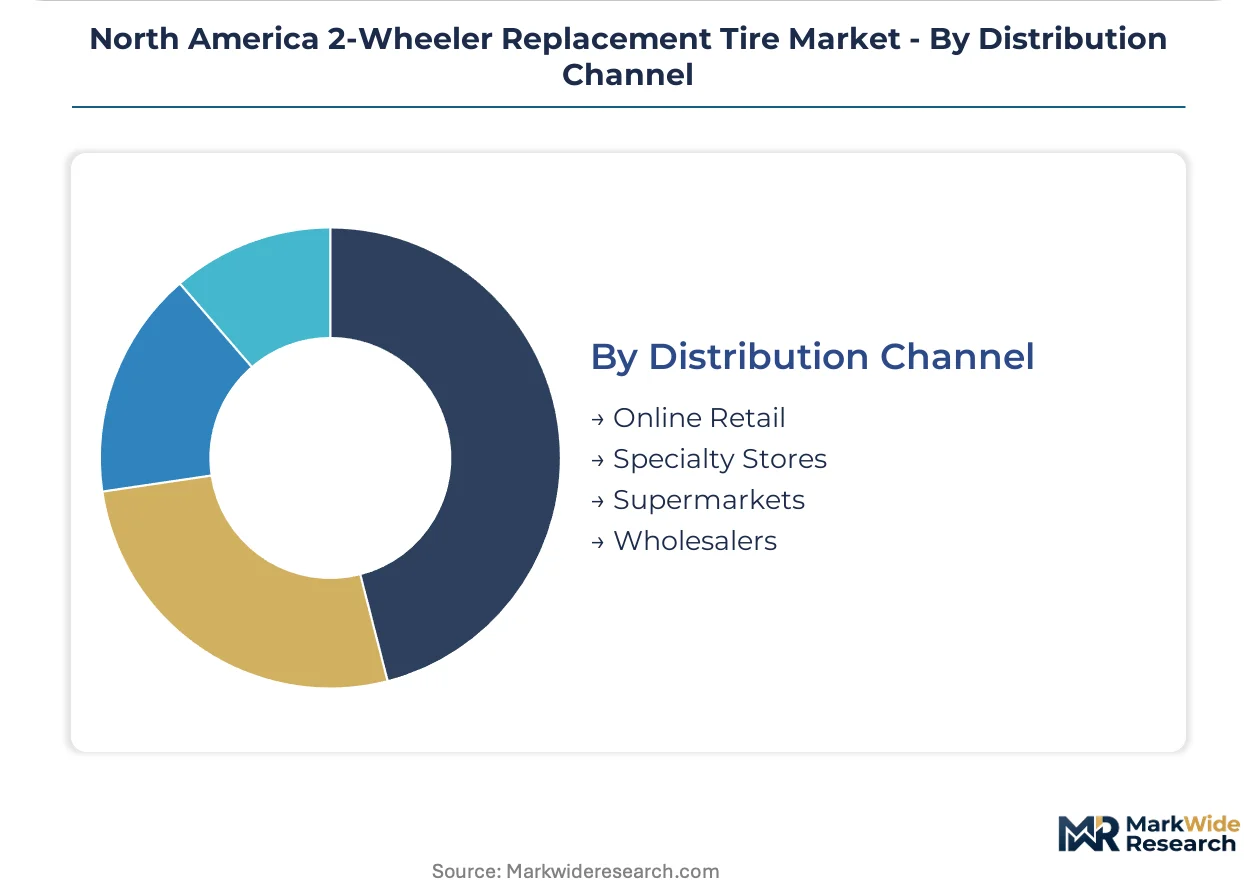
Distribution Channel:
Channel power is concentrating toward direct manufacturer relationships as fleet procurement scale justifies inventory holding costs and bypasses traditional distributor markups.
- Specialty Stores:Technical consultation and installation services sustain relevance for touring-grade and off-roading segments where fitment expertise reduces warranty claims. Ohio and South Carolina tier-one molder proximity supports rapid inventory replenishment.
- Wholesalers:Multi-source procurement consolidation among aftermarket distributors is realigning supply relationships, with certified producers capturing expanded panel positions.
- Online Retail:Price transparency and convenience serve cost-sensitive commuter replacement with compressed delivery timelines.
- Supermarkets:Limited SKU depth restricts presence to basic scooter and moped specifications.
Retaining procurement share: Specialty Stores. Losing ground fastest: Supermarkets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Replacement tire demand concentrates in the US Sun Belt states where year-round riding sustains above-average wear rates, while cross-border certification friction fragments supplier access across the trilateral market.
United States
Arizona, Florida, and Texas sustain replacement cycles that outpace seasonal northern markets through year-round riding intensity. NHTSA Uniform Tire Quality Grading standards impose 18-24 month recertification timelines that delay new product launches. Tier-one molders in Ohio and South Carolina have deployed machine vision tread inspection across touring-grade motorcycle tire lines.
Canada
Toronto food-delivery fleets are compressing replacement cycles for scooter tires as urban battery-powered mobility expands. Health Canada adds cross-border certification layers that filter which suppliers access the full North American aftermarket. Montreal and Vancouver procurement officers are consolidating supplier relationships into direct manufacturer contracts.
Mexico
Mexico's national standards body imposes non-harmonized testing protocols that fragment supplier access across the trilateral market. The country's growing urban delivery density accelerates tire turnover in Mexico City Metro and Guadalajara. Cross-border manufacturing proximity supports rapid inventory replenishment for US distributors.
California
California's advancing low-carbon material mandates recalibrate compound formulation investments across US manufacturing plants. State fleet operators and municipal bike-share programs now require documented bio-based content percentages. Los Angeles and San Francisco electric-bike tire categories face the steepest compliance ramps given their volume growth trajectory.
North America 2-Wheeler Replacement Tire Market Competitive Landscape
Capacity expansion dominates the current landscape as tier-one molders scale machine vision quality control deployment across touring-grade lines. The vendor base stratifies across three tiers: premium manufacturers with certified low-carbon compound capabilities, mid-tier specialists with nylon belt reinforcement expertise, and value-tier competitors serving urban delivery density. Strategic archetypes include OEM-anchored incumbents extending into replacement demand, certified producers capturing distributor panel consolidation, and regional specialists competing on cross-border logistics. M&A activity and vertical integration into Kevlar belt sourcing represent the dominant competitive moves.
Within the premium-tier vector, Michelin and Goodyear exemplify scale-driven positioning, while Dunlop occupies a position as an OEM-anchored incumbent. Cooper Tires represents the value-tier archetype serving commuter scooters and urban delivery fleets. These three companies illustrate how manufacturing scale, OEM relationships, and pricing differentiation segment competitive access across replacement channels.
| Leading Market Players |
|---|
| Apollo Tyres |
| BFGoodrich |
| Cooper Tires |
| Coker Tire |
| Dunlop Tires |
| Michelin |
| Goodyear |
| Firestone |
| Yokohama |
| Others |
Value Network & Pricing Analysis
Fleet procurement consolidation in Chicago and Toronto is forcing molders to absorb inventory holding costs and offer volume-tier contracts, compressing margins for distributors while rewarding certified producers with NHTSA recertification capabilities. This buyer-side concentration is reshaping how supply must configure to retain access.
Pricing Analysis
Volume concentration in city-riding scooter tires runs on thinner margins than touring-grade motorcycle replacements where Kevlar reinforcement and verified speed ratings sustain premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates Michelin's certified low-carbon compounds from Cooper's value-tier commuter lines and mid-tier nylon-belt alternatives. Cost compression in the scooter segment is intensifying because fleet procurement officers are bypassing traditional distributor markups for direct manufacturer contracts. Urban delivery fleets exhibit the sharpest price sensitivity, while touring riders prioritize performance verification over per-unit cost.
Supply Chain Analysis
Dual-sourcing requirements among aftermarket distributors are fragmenting procurement panels and forcing molders to maintain redundant certification across NHTSA, Health Canada, and Mexico's national standards body. Natural rubber plantations in Thailand and Indonesia, synthetic rubber feedstocks from South Korean petrochemical complexes, and Kevlar aramid fiber from domestic DuPont facilities anchor North American compound formulation. Single-source vulnerability in Southeast Asian natural rubber exposes molders to plantation supply disruptions and currency volatility. Distribution runs through specialty stores in Ohio and South Carolina tier-one molder proximity, consolidated wholesaler panels, and direct fleet contracts in urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NHTSA's 18-24 month Uniform Tire Quality Grading recertification timelines erect a compliance moat that filters smaller suppliers and consolidates procurement toward certified producers with verified low-carbon compound capabilities.
For Market Incumbents: To counter distributor panel consolidation and direct manufacturer contract erosion, deepen backward integration into Kevlar belt sourcing and expand machine vision quality control deployment across touring-grade lines. Anchor replacement demand through OEM partnership extensions that lock in certified supply agreements. For New Entrants and Emerging Players: Capture white-space in electric bike tire categories where dual-rubber compound expertise is scarce and California low-carbon material mandates create procurement eligibility barriers for legacy suppliers. Target municipal bike-share programs with documented bio-based content percentages as the most penetrable institutional segment. For Investors and Strategic Acquirers: The window for entry favors mid-tier manufacturers with certified nylon belt reinforcement capabilities and established Health Canada cross-border access. Watch for inflection when EPA rubber-processing rules filter additional smaller suppliers and consolidate procurement toward verified low-carbon compound producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aramid Sourcing | Captive Kevlar supply secures puncture-resistant touring-grade positioning against petrochemical volatility. |
| Machine Vision Quality Control Deployment | Ohio and South Carolina tier-one molders compress warranty claims and manual inspection labor. |
| California Low-Carbon Compound Certification | Bio-based content documentation unlocks state fleet and municipal bike-share procurement eligibility. |
| Fleet Direct Contract Consolidation | Volume-tier pricing with Chicago and Toronto delivery operators bypasses distributor markups. |
| Cross-Border Certification Harmonization | Unified NHTSA-Health Canada-Mexico standards access fragments competitor reach across trilateral markets. |
Research Methodology
Document review covered SEC 10-K filings from tire manufacturers, NHTSA Uniform Tire Quality Grading databases, EPA rubber-processing compliance records, and customs trade data, complemented by interviews with aftermarket distributor procurement officers, fleet operations managers at Toronto and Chicago food-delivery companies, tier-one molder plant managers in Ohio and South Carolina, and regulatory affairs leads navigating Health Canada certification. Bottom-up triangulation across replacement cycle data and top-down validation against vehicle registration stocks anchored volume estimates.
Historical shipment data cross-referenced against panel input from procurement officers and distributor inventory managers shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle electrification curve, riding intensity pattern, reinforcement material type, and channel consolidation tier. CAGRs derived from replacement cycle compression rates in urban delivery fleets and Sun Belt year-round riding intensity, with electric bike weight classification evolution and California mandate compliance ramps as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to natural rubber plantation supply disruptions in Southeast Asia and NHTSA grading protocol revisions. Deviation in EPA enforcement intensity or California low-carbon mandate acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Wheel Market
Tires and Wheels
Forestry Equipment Tire Market
Tires and Wheels
Bias Tire Market
Tires and Wheels
E-Bike Tire Market
Tires and Wheels
Global Tire Curing Press Machine Market
Tires and Wheels
Specialty Tire Market
Tires and Wheels
Rechargeable Tires Market
Tires and Wheels
Automotive Green Tires Market
Tires and Wheels
Automotive Tire Chains Market
Tires and Wheels
Europe Aircraft Tires Market
Tires and Wheels
Truck and Bus Radial (TBR) Tire Market
Tires and Wheels
Automotive Wheel Cap Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Automotive Winter Tire Market
Tires and Wheels
Tire Bead Wire Market
Tires and Wheels
Airless Tires Market