
 Airless Tires Market | 2026-2036
Airless Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Airless Tires Market Analysis
A shift from outsourced prototyping to in-house advanced manufacturing is restructuring how tire makers control airless tire development cycles. Bridgestone Corporation leverages captive polymer research facilities in Japan to refine spoke-structure geometries. Michelin Group anchors European testing programs through dedicated proving grounds. Continental AG competes via integrated simulation-to-road validation pipelines that compress design iterations.
Airless tires are non-pneumatic wheel assemblies that replace pressurized air chambers with engineered support structures—typically thermoplastic resin spokes or honeycomb lattice cores—rated for specific load-bearing thresholds and rolling-resistance coefficients. Their primary purpose is to eliminate puncture failures while reducing maintenance intervals in high-utilization vehicle fleets. Composite Materials command premium positioning due to strength-to-weight optimization demands in military and off-road segments. Passenger Vehicles represent the volume frontier where OEM specification negotiations determine adoption timelines. Rubber formulations retain cost-sensitive aftermarket relevance despite performance trade-offs.
The U.S. Department of Transportation sets Federal Motor Vehicle Safety Standards that govern rolling resistance and noise emissions for road-legal airless tire deployment. Japan's Ministry of Economy, Trade and Industry (METI) channels industrial technology grants toward next-generation mobility materials including non-pneumatic structures. Stakeholders must track how OEM qualification timelines intersect with evolving load-rating protocols before committing production scale.
Market Dynamics
Military logistics fleets are accelerating airless tire trials to eliminate battlefield puncture failures, while the U.S. Department of Transportation shapes certification timelines through Federal Motor Vehicle Safety Standards that govern rolling resistance and noise emissions.
Growth Catalysts
- Defense procurement mandates:Military vehicle operators in the United States prioritize puncture-proof mobility for tactical advantage in contested supply zones. Pentagon maintenance budgets favor zero-maintenance wheel systems for forward-deployed assets.
- METI industrial technology grants:Japan's Ministry of Economy, Trade and Industry channels funding toward next-generation mobility materials including non-pneumatic structures. Japanese tire manufacturers leverage these subsidies to accelerate spoke-structure prototyping.
- High-density urban fleet utilization:Last-mile delivery operators in Japan demand reduced downtime from tire-related service interruptions. Commercial vehicle uptime metrics now include airless tire compatibility in OEM specification sheets.
Market Restraints
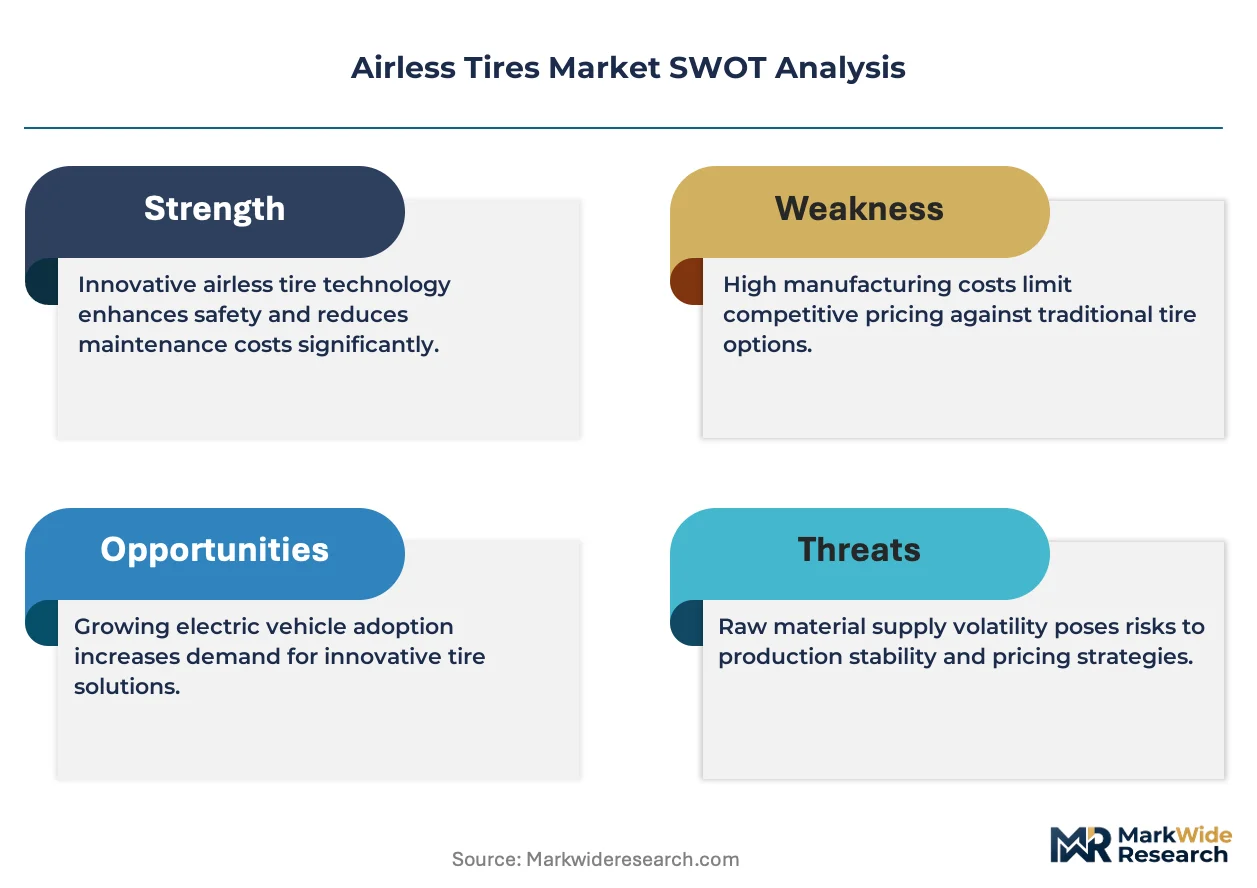
- Thermoplastic resin cost volatility:Engineered polymer feedstock prices fluctuate with petrochemical supply chain disruptions. Composite material formulations require specialized resin grades with limited supplier alternatives.
- Load-rating protocol uncertainty:Federal Motor Vehicle Safety Standards lack finalized test procedures for non-pneumatic structures above light-truck weight classes. Certification delays extend product qualification timelines beyond traditional pneumatic tire cycles.
- Manufacturing equipment concentration:Advanced injection molding systems for lattice-core production concentrate among Japanese and German machinery suppliers. Equipment lead times exceed eighteen months for new market entrants.
Strategic Opportunities
- Off-road construction equipment:Mining and quarry operators in Australia face puncture losses from sharp aggregate surfaces. Airless tire architectures eliminate pressure-loss downtime in remote extraction sites without service infrastructure.
- Shared micromobility expansion:Electric scooter and bike-share operators in France require vandal-resistant wheel systems for public deployment. Municipal procurement specifications increasingly mandate puncture-proof designs for fleet durability.
- EU Green Deal material circularity:The European Union's sustainable mobility framework incentivizes recyclable tire constructions. Thermoplastic resin spokes enable end-of-life material recovery compared to conventional rubber-tire incineration.
Industry Challenges
- Simulation-to-validation talent scarcity:Finite element analysis specialists capable of modeling spoke-structure fatigue under combined loading conditions command premium compensation. Tire makers compete with aerospace and automotive sectors for computational mechanics expertise.
- OEM integration complexity:Suspension tuning for airless tire compliance characteristics requires recalibration of vehicle dynamics control systems. Automakers resist absorbing additional development costs without volume commitment guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airless Tires Market |
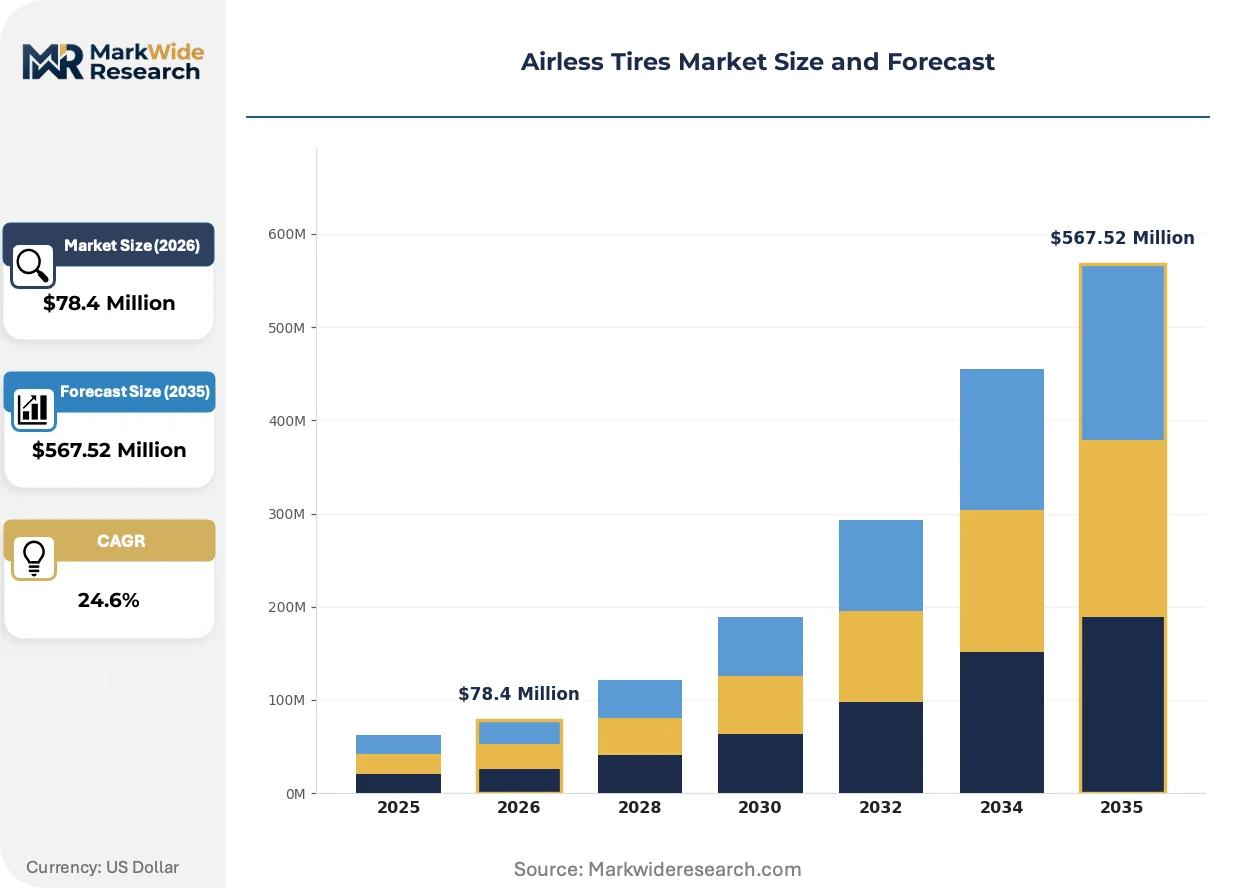
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $567.52 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Vehicles, Commercial Vehicles, Industrial Equipment, Off-Road Vehicles Material: Rubber, Plastic, Composite Materials, Metal Use Case: Urban Transportation, Agriculture, Military, Recreational Vehicles End User: OEMs, Aftermarket Providers, Fleets, Consumers |
| Companies Covered | Continental AG, Sumitomo Rubber Industries, Bridgestone Corporation, Pirelli Tyre, Toyo Tire Corporation, Michelin Group, Hankook Tire & Technology, Amerityre Corporation, The Goodyear Tire & Rubber Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airless Tires Market Emerging Trajectories
Development cycles are compressing as tire manufacturers internalize advanced manufacturing capabilities previously outsourced to specialty prototyping firms. Three converging developments are restructuring competitive positioning.
Thermoplastic resin spoke geometries are consolidating around honeycomb lattice architectures optimized for vertical load distribution and lateral stability. Military vehicle procurement offices in the United States specify these structures for armored personnel carrier retrofits. The technology is consolidating supplier relationships toward integrated material-formulation-to-testing pipelines.
REACH chemical substance restrictions in Europe are forcing reformulation of rubber-compound bonding agents used in hybrid airless-pneumatic transitional designs. Tire makers serving EU markets must substitute legacy adhesion promoters with compliant alternatives by registration deadlines. Passenger vehicle OEMs in Germany are accelerating validation schedules to lock specifications before regulatory transition periods.
Fleet procurement departments are unbundling tire supply from vehicle purchase agreements to negotiate direct airless tire service contracts. Logistics operators in Japan now contract separately with Bridgestone Corporation for wheel-as-a-service arrangements covering maintenance and replacement cycles. This disintermediation shifts margin capture from vehicle OEMs toward specialized tire suppliers with captive servicing networks.
Airless Tires Market Segmentation
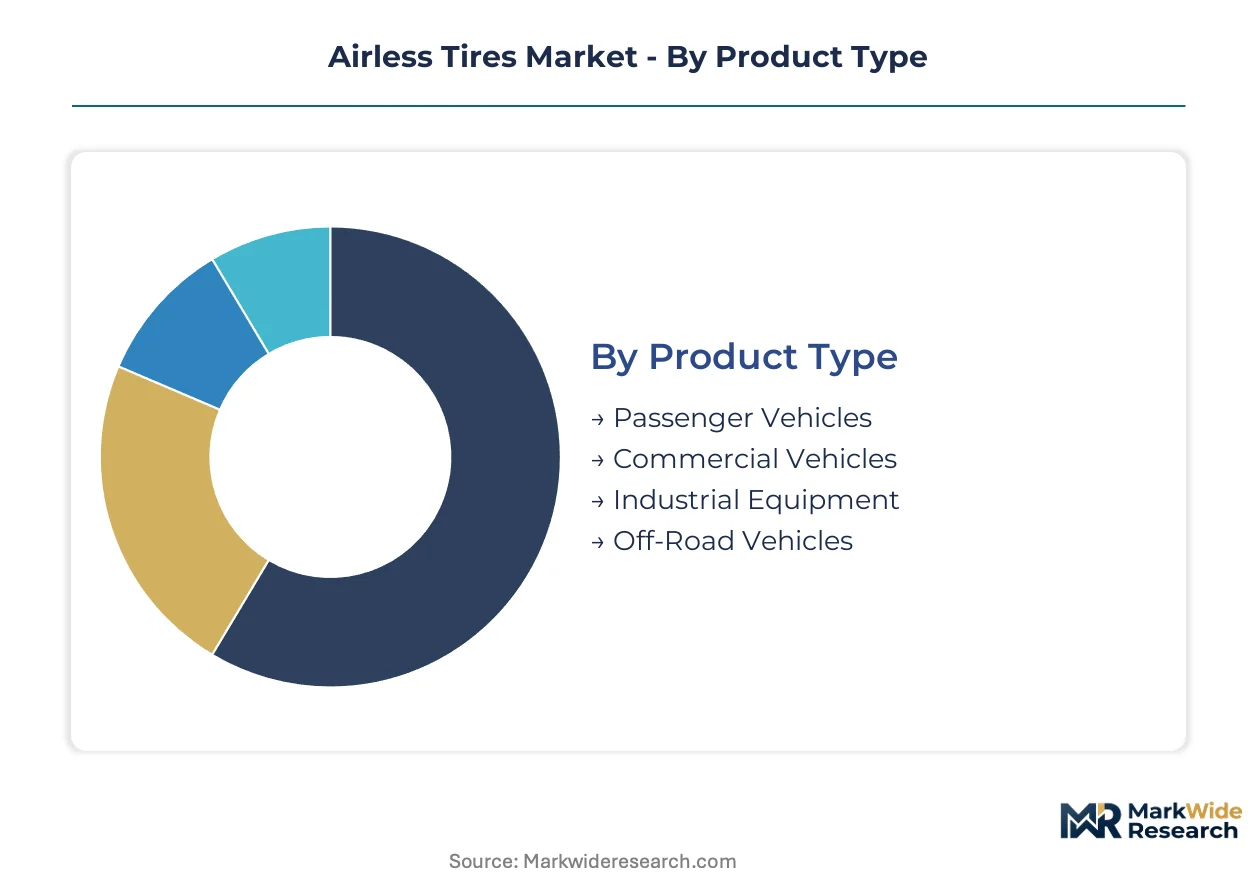
Airless tire architectures vary dramatically in load-bearing requirements and spoke-structure complexity across vehicle classes. Material selection and end-user procurement patterns further fragment the competitive landscape into distinct qualification pathways.
Product Type:
Standalone wheel assemblies dominate heavy-duty applications, while embedded integration with vehicle suspension systems shapes passenger vehicle development cycles.
- Passenger Vehicles:Honeycomb lattice spoke structures rated for highway speeds require NHTSA rolling resistance certification. Japanese OEMs negotiate multi-year supply agreements with Bridgestone and Michelin for next-generation electric vehicle platforms, though load-rating protocol uncertainty delays final specifications.
- Commercial Vehicles:Thermoplastic resin formulations optimized for repeated stop-start duty cycles target last-mile delivery density. Fleet operators in France and Japan now unbundle tire procurement from vehicle purchase agreements to secure wheel-as-a-service contracts with direct maintenance coverage.
- Industrial Equipment:Mining excavators and quarry loaders in Australia deploy solid rubber-core variants for puncture immunity on aggregate surfaces.
- Off-Road Vehicles:Military armored personnel carriers in the United States specify military-grade composite spoke geometries for contested supply zone mobility.
Volume placements concentrate in Commercial Vehicles; the faster expansion belongs to Off-Road Vehicles.
Material:
Cost tiers separate commodity formulations from engineered polymers with specialized fatigue resistance.
- Composite Materials:Carbon-fiber reinforced thermoplastic spokes deliver strength-to-weight ratios essential for military weight-class compliance. Pentagon procurement mandates specify these structures for forward-deployed tactical vehicles, though resin cost volatility constrains civilian adoption timelines.
- Rubber:Conventional vulcanized compounds retain aftermarket price sensitivity despite higher rolling resistance coefficients. EU Green Deal circularity requirements are forcing reformulation of bonding agents ahead of REACH registration deadlines.
- Plastic:Injection-molded lattice cores from German and Japanese machinery suppliers serve micromobility and light industrial segments.
- Metal:Spring-steel spoke arrays persist in heavy construction equipment where deflection tolerance exceeds ride comfort priorities.
Margin capture favors Composite Materials; Plastic formulations are climbing the fastest as shared mobility fleets scale.
Use Case:
Application maturity ranges from field-proven military deployments to emerging micromobility specifications.
- Military:Battlefield puncture elimination drives Pentagon maintenance budget allocations toward zero-maintenance wheel systems. United States Marine Corps logistics trials are accelerating qualification timelines for armored vehicle retrofits.
- Urban Transportation:Electric scooter and bike-share operators in France require vandal-resistant designs for public deployment. Municipal procurement specifications now mandate puncture-proof wheel systems as fleet durability standards.
- Agriculture:Tractor and harvester applications in the United States Midwest face soil compaction trade-offs against puncture immunity on stubble fields.
- Recreational Vehicles:All-terrain vehicle enthusiasts in Australia accept ride stiffness penalties for trail-side reliability in remote terrain.
Procurement scale centers on Military applications; Urban Transportation is gaining share fastest through municipal fleet mandates.
End User:
Customer type determines whether specifications flow through OEM integration or direct fleet negotiation.
- Fleets:High-utilization operators in Japan and France bypass vehicle OEMs to contract directly with tire manufacturers for lifecycle service coverage. Bridgestone's wheel-as-a-service model captures recurring revenue streams through captive maintenance networks.
- OEMs:German and Japanese automakers resist absorbing suspension recalibration costs without volume commitment guarantees from airless tire suppliers.
- Aftermarket Providers:Independent distributors in the United States stock rubber-based transitional designs for cost-sensitive replacement cycles.
- Consumers:Individual purchasers remain limited to specialty off-road and recreational applications pending highway-legal certification expansion.
Contract value aggregates with Fleets; the steepest expansion trajectory belongs to OEMs as platform integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan concentrates airless tire demand through intensive manufacturer R&D programs and METI-funded mobility material initiatives. Military procurement in the United States and fleet unbundling trends in France reshape regional adoption timelines.
United States
Pentagon maintenance budgets prioritize zero-maintenance wheel systems for forward-deployed tactical vehicles. NHTSA Federal Motor Vehicle Safety Standards govern rolling resistance certification for highway-legal deployment. Michigan-based automotive clusters coordinate suspension recalibration programs with emerging airless tire specifications.
Japan
Last-mile delivery operators demand reduced downtime from tire-related service interruptions in high-density urban corridors. METI channels industrial technology grants toward next-generation mobility materials including non-pneumatic spoke structures. Tokyo-Osaka industrial corridors host captive polymer research facilities refining honeycomb lattice geometries.
Germany
REACH chemical substance restrictions force reformulation of rubber-compound bonding agents in hybrid transitional designs. EU Green Deal material circularity frameworks incentivize recyclable thermoplastic resin constructions. Bavarian and Baden-Württemberg automotive clusters accelerate validation schedules ahead of regulatory transition periods.
France
Electric scooter and bike-share operators require vandal-resistant wheel systems for public micromobility deployment. Municipal procurement specifications increasingly mandate puncture-proof designs as fleet durability standards. Paris and Lyon metropolitan authorities lead service contract unbundling from vehicle purchase agreements.
Australia
Mining and quarry operators face puncture losses from sharp aggregate surfaces in remote extraction sites. National heavy vehicle safety regulators evaluate load-rating protocols for off-road construction equipment. Western Australia mining clusters test solid-core variants without service infrastructure dependencies.
Airless Tires Market Vendor Landscape
Capacity expansion dominates the current landscape as tire manufacturers internalize advanced molding capabilities previously outsourced to specialty prototyping firms. The vendor base concentrates around integrated material-formulation-to-testing pipelines rather than fragmented component suppliers. Three archetypes define positioning: captive polymer researchers with in-house simulation infrastructure, proving-ground operators with dedicated validation assets, and machinery-integrated producers controlling injection-to-road pipelines. Geographic expansion and strategic partnerships constitute the dominant competitive moves as firms seek qualification timeline advantages across regulatory jurisdictions.
Within the integrated research tier, Bridgestone Corporation and Michelin Group exemplify divergent regional anchoring strategies. Bridgestone occupies a position shaped by Japanese METI grant access and Tokyo-based polymer facilities. Michelin represents European proving-ground validation approaches with French regulatory coordination capabilities. Continental AG sits within the machinery-integrated archetype, reflecting German injection molding supply chain proximity.
| Leading Market Players |
|---|
| Continental AG |
| Sumitomo Rubber Industries |
| Bridgestone Corporation |
| Pirelli Tyre |
| Toyo Tire Corporation |
| Michelin Group |
| Hankook Tire & Technology |
| Amerityre Corporation |
| The Goodyear Tire & Rubber Company |
| Others |
Supply Flow & Price Mechanics
Computational mechanics specialists concentrated in Germany and Japan command premium compensation that compresses margin spreads between premium composite spoke systems and standard rubber-core alternatives. Labor-cost differentials between captive polymer research facilities and outsourced prototyping operations directly shape three-tier pricing structures across military-grade, commercial fleet, and aftermarket replacement segments.
Pricing Analysis
Warranty and lifecycle service bundling separates fleet wheel-as-a-service contracts from unbundled per-unit tire transactions in aftermarket channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under NHTSA Federal Motor Vehicle Safety Standards and volume scale commitments from high-utilization logistics operators. Pricing pressure stems from thermoplastic resin cost volatility in petrochemical supply chains. Aftermarket providers exhibit highest price sensitivity; military procurement offices demonstrate lowest sensitivity due to zero-maintenance operational requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Japanese and German automakers, while fleet service contracts flow through captive maintenance networks operated by integrated tire manufacturers. Manufacturing equipment concentrates in Japan and Germany, with advanced injection molding systems for lattice-core production drawing from specialized machinery suppliers. Raw material dependencies center on engineered thermoplastic resins, carbon-fiber reinforcement fibers, and vulcanized rubber compounds. Single-source vulnerability in injection molding equipment creates supply chain risk. Distribution runs through dual-track structures: OEM specification pathways and direct fleet negotiation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. NHTSA Federal Motor Vehicle Safety Standards create a barrier-to-entry moat for players with proven rolling resistance certification, locking out undercapitalized entrants lacking dedicated proving-ground validation assets.
For Market Incumbents: Deepen captive polymer research infrastructure to compress simulation-to-road validation cycles before emerging machinery-integrated competitors achieve qualification timeline parity. Add proving-ground capacity in Michigan and Baden-Württemberg automotive clusters to defend against Continental AG's injection-to-road pipeline advantages. Prioritize METI grant capture to maintain Japanese R&D positioning against Sumitomo Rubber Industries. For New Entrants and Emerging Players: Australian mining operators represent an underserved buyer archetype with puncture-loss tolerance for solid-core variants lacking highway-legal certification. Target Western Australia extraction sites with rubber-core airless architectures that bypass NHTSA load-rating protocol uncertainty. Pursue equipment-leasing partnerships with German and Japanese machinery suppliers to circumvent eighteen-month equipment lead times. For Investors and Strategic Acquirers: Re-rating potential sits with integrated material-formulation-to-testing pipelines given METI industrial technology grant acceleration and Pentagon procurement mandate expansion. Long-term viability favors tire manufacturers with captive servicing networks capturing recurring wheel-as-a-service revenue streams. Monitor NHTSA finalization of non-pneumatic load-rating protocols above light-truck weight classes as inflection indicator for commercial vehicle segment unlock.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Polymer Research Facility Expansion | Bridgestone's Tokyo-Osaka facilities compress spoke-structure prototyping cycles ahead of outsourced competitors. |
| Proving-Ground Validation Asset Acquisition | Michelin's European testing programs lock NHTSA certification timelines for highway-legal deployment. |
| Wheel-as-a-Service Contract Scaling | Fleet unbundling in Japan shifts margin capture from vehicle OEMs toward tire manufacturers with maintenance networks. |
| Injection Molding Equipment Integration | Continental AG's German supply chain proximity enables simulation-to-road pipeline control. |
| METI Grant Portfolio Optimization | Japanese manufacturers leverage industrial technology funding to accelerate non-pneumatic structure development. |
Methodological Framework
Trade association filings, customs and import-export databases, and SEC 10-K disclosures formed the secondary backbone of this analysis. Primary interviews with tire manufacturer R&D directors, OEM platform engineering leads, fleet procurement managers, and NHTSA regulatory affairs specialists were combined with secondary validation. Bottom-up segment sizing and top-down macroeconomic triangulation were applied across product type, material formulation, use case, and end-user dimensions.
Historical trendline analysis of military procurement cycles, METI grant disbursement patterns, and fleet unbundling adoption curves informed the projection framework. Segmentation modeling covered vehicle class, spoke-structure architecture, material grade tier, and regional regulatory cluster across the analysis window. CAGRs were derived from elasticity-adjusted demand curves incorporating thermoplastic resin price indices and equipment lead time trajectories.
Revisions become necessary when NHTSA finalizes non-pneumatic load-rating protocols, Pentagon maintenance budgets shift procurement priorities, or thermoplastic resin supply chains experience sustained disruption. Forecasts reflect assumptions about regulatory timeline adherence and material cost stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Global Tires Market
Tires and Wheels
Automotive Automatic Tire Inflation System (ATIS) Market
Tires and Wheels
Europe 2-Wheeler Replacement Tire Market
Tires and Wheels
Automotive All-Season Tire Market
Tires and Wheels
United States Tire Market
Tires and Wheels
Europe Aircraft Tires Market
Tires and Wheels
Asia-Pacific Alloy Wheels Market
Tires and Wheels
Automotive Intelligent Tires Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Automotive Wheel Market
Tires and Wheels
Agricultural Tires Market
Tires and Wheels
Global Automotive Tire Inflator Market
Tires and Wheels
Solid Tire Market
Tires and Wheels
Self-Healing Tire Market
Tires and Wheels
Rail Road Wheels Market
Tires and Wheels
Bias Tire Market