
 Asia-Pacific Heat Shrink Tubing for Automotive Market | 2026-2036
Asia-Pacific Heat Shrink Tubing for Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Heat Shrink Tubing for Automotive Market Outlook
Buyer concentration across Asia-Pacific automotive harness procurement is shifting as Chinese EV OEMs consolidate supplier pools around vertically integrated tier-1s. Sumitomo Electric Industries leverages its polymer compounding expertise to sustain captive supply advantages for Japanese transplants operating in Thailand and Vietnam. Dasheng Group anchors domestic procurement networks through backward integration into polyolefin resin processing, while Shenzhen Woer Heat-Shrinkable Material competes on automated installation compatibility for high-volume EV platforms.
Asia-Pacific heat shrink tubing for automotive comprises cross-linked polymeric sleeves that recover diametrically when heated, typically formulated with halogen-free flame retardants and operating temperature ratings from minus 40 degrees Celsius to 135 degrees Celsius to protect wire harnesses against abrasion, moisture ingress, and short-circuit propagation. Polyolefin formulations dominate volume production for standard under-hood applications, while fluoropolymer grades command premium positioning in battery thermal management zones where chemical resistance requirements exceed conventional specifications. Installation method segmentation reveals automated heat-shrinking lines gaining share among OEMs, though repair shops and aftermarket distributors still rely heavily on heat gun deployment for localized harness servicing.
China's MIIT enforces GB standards for automotive wire insulation that increasingly align with RoHS substance restrictions, while Japan's METI coordinates JIS certification pathways that govern material acceptance by Toyota, Honda, and Nissan procurement systems. India's BIS has introduced phased mandatory testing for automotive cable protection materials under its automotive mission plan, creating compliance complexity for suppliers serving multiple national approval frameworks. Stakeholders must monitor divergence between Chinese GB standards and Japanese JIS specifications as both jurisdictions accelerate EV-specific material testing protocols that could fragment cross-border product qualification requirements.
Market Dynamics
Chinese OEM platform-sharing strategies are compressing heat shrink tubing specifications across shared EV architectures, forcing tier-1 harness suppliers to consolidate polymer procurement around fewer qualified resin grades that satisfy multiple simultaneous certification pathways.
Growth Catalysts
- MIIT dual carbon mandates:China's tightened automotive material specifications under GB standards are accelerating halogen-free flame-retardant formulation upgrades across wire harness insulation supply chains.
- Thai manufacturing clusters:Japanese transplant OEMs operating in Thailand's Eastern Economic Corridor are localizing polymer compounding operations to reduce cross-border qualification delays for EV platform launches.
- Battery thermal management zones:Fluoropolymer-grade tubing demand is expanding as high-voltage battery architectures require chemical resistance beyond standard polyolefin capabilities.
Market Restraints
- Polyolefin resin price volatility:Feedstock cost swings for ethylene and propylene derivatives are compressing margin buffers for standard-grade tubing producers serving high-volume harness contracts.
- Supplier concentration in Yangtze River Delta:Overreliance on Shanghai-Ningbo polymer processing hubs creates geographic vulnerability to regional logistics disruptions or environmental compliance shutdowns.
- Cross-certification friction:Divergence between Chinese GB standards and Japanese JIS specifications forces dual testing protocols that extend product qualification timelines by 8-14 months.
Strategic Opportunities
- Vietnamese manufacturing expansion:Underpenetrated automotive wiring capacity in northern Vietnam offers first-mover positioning for suppliers establishing halogen-free compounding operations ahead of regional EV supply chain migration.
- Automated installation systems:Robotic heat-shrinking line integration at Chinese tier-1 harness facilities is creating demand for tubing with tighter diameter tolerances and optimized shrink ratios.
- India BIS phased mandates:The country's automotive mission plan is introducing mandatory cable protection testing that will require new certification investments from incumbent suppliers.
Industry Challenges
- Polymer formulation expertise scarcity:Cross-linking chemistry and flame-retardant additive blending capabilities are concentrated among aging technical workforces in Japan and select Chinese state-owned material institutes.
- Multi-jurisdiction certification complexity:Simultaneous pursuit of GB, JIS, and emerging BIS approvals demands dedicated regulatory affairs infrastructure that mid-cap suppliers struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Heat Shrink Tubing for Automotive Market |
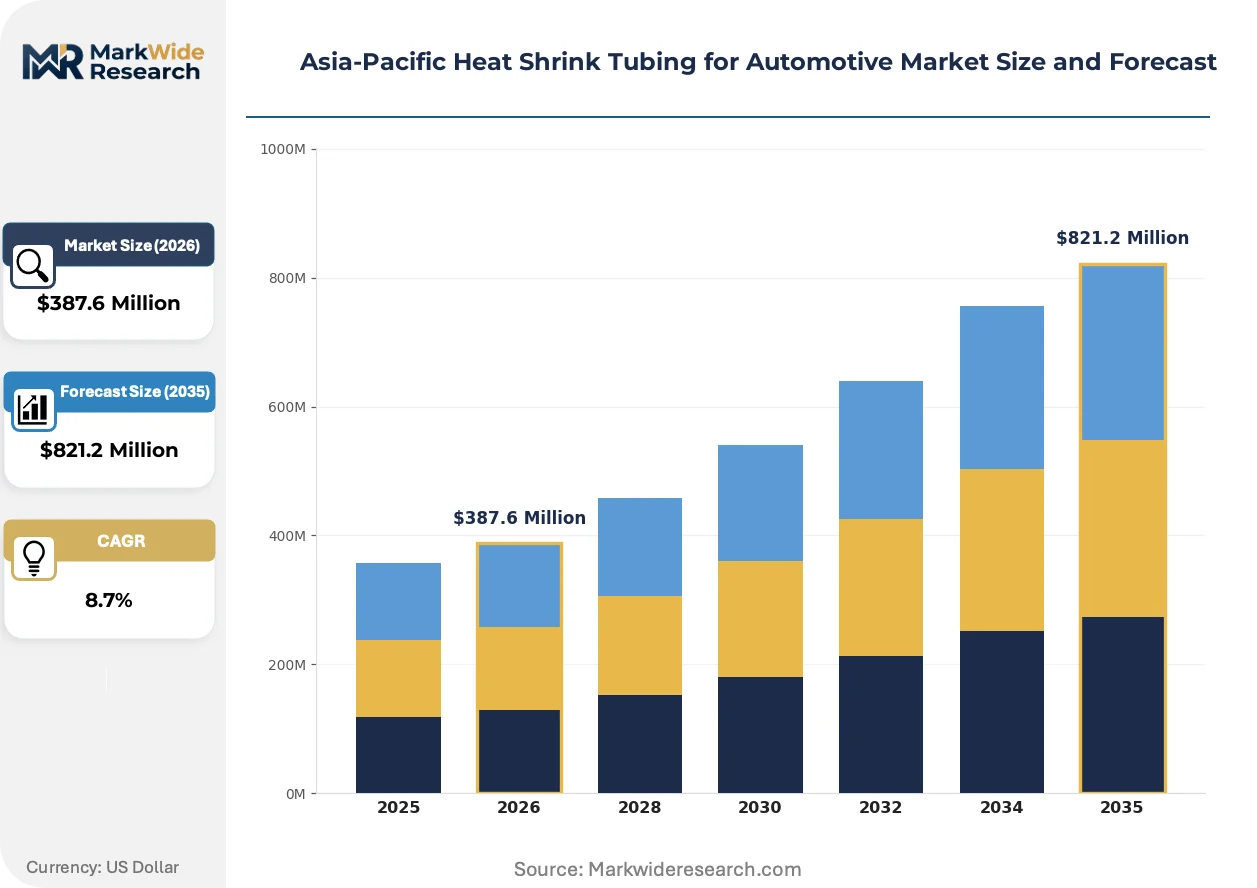
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyolefin, PVC, Fluoropolymer, Elastomer Installation Method: Manual, Automated, Semi-automated, Heat Gun End User: OEMs, Aftermarket, Repair Shops, Distributors Certification: UL, CSA, RoHS, ISO |
| Companies Covered | Sumitomo Electric Industries, Ltd., Dasheng Group, Shenzhen Woer Heat-Shrinkable Material Co., Ltd., Huizhou Guanghai Electronic Insulation Materials Co., Ltd., TE Connectivity, ABB, 3M Co., Changchun Heat Shrinkable Materials, Alpha Wire Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Heat Shrink Tubing for Automotive Market Strategic Shifts
Material science advances and installation automation are converging to redefine performance benchmarks and procurement criteria across Asia-Pacific automotive harness protection markets.
Halogen-free polyolefin compounds with enhanced thermal cycling resistance are modularizing platform-grade tubing specifications. Chinese EV OEMs adopting shared battery and powertrain architectures are consolidating procurement around these formulations. This standardization is modularizing supplier qualification pools and compressing pricing differentiation between mid-tier and premium-grade products.
METI-coordinated JIS certification updates are tightening smoke density and toxicity requirements for passenger compartment wire insulation. Japanese OEM procurement systems are rejecting legacy formulations that lack updated test documentation. Thai and Indonesian harness suppliers serving Toyota and Honda networks are accelerating laboratory investment to secure revised material acceptance.
Direct contracting between Chinese EV OEMs and resin compounders is displacing traditional distributor-mediated procurement for high-volume platform programs. Tier-2 tubing processors in Jiangsu and Zhejiang provinces are losing margin to vertically integrated tier-1 harness manufacturers with captive polymer operations. This channel compression is most visible in Yangtze River Delta automotive clusters where BYD and NIO supply chains dominate.
Asia-Pacific Heat Shrink Tubing for Automotive Market Segmentation
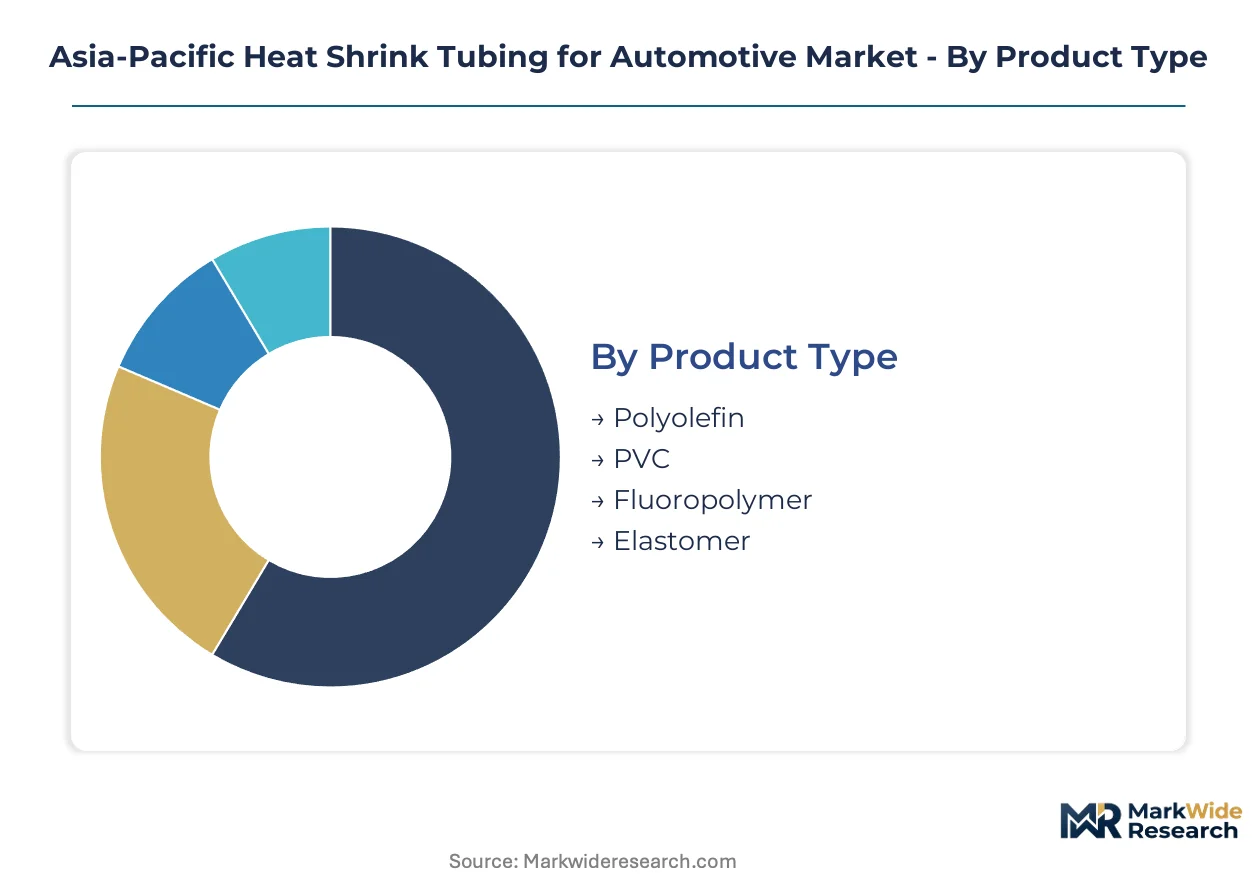
Heat shrink tubing procurement across Asia-Pacific automotive harness supply chains fragments across four decisive axes. Product chemistry determines thermal performance ceilings for battery zone applications. Installation method selection separates high-volume EV platform contracts from aftermarket service economics. Certification pathways gate access to Japanese OEM procurement systems versus Chinese domestic qualification.
Product Type:
Material selection hinges on operating temperature exposure and chemical resistance requirements across under-hood, passenger compartment, and battery thermal management zones.
- Polyolefin:Cross-linked polyethylene and polypropylene formulations dominate standard under-hood wire harness protection with operating ranges from minus 40 degrees Celsius to 135 degrees Celsius. Procurement concentrates in China's Yangtze River Delta automotive cluster where tier-1 harness suppliers scale polymer procurement for platform-shared EV architectures. MIIT GB standards enforcement is accelerating halogen-free flame-retardant formulation upgrades across this grade.
- Fluoropolymer:PTFE, FEP, and PVDF grades deliver chemical resistance beyond polyolefin capabilities for high-voltage battery thermal management zones. Demand is expanding fastest among Chinese EV OEMs adopting 800-volt architectures where electrolyte exposure risks exceed conventional specifications. Japanese OEM procurement systems through METI-coordinated JIS pathways command premium positioning for these grades.
- PVC:Legacy vinyl formulations retain cost-positioned share in aftermarket repair applications and commercial vehicle segments with less stringent smoke toxicity requirements. BIS phased mandates in India are compressing PVC acceptance for new platform certifications.
- Elastomer:Silicone and EPDM-based tubing serves flexible harness routing in door jambs and suspension zones requiring abrasion resistance combined with elastic recovery. Thai manufacturing clusters serving Japanese transplant OEMs localize limited compounding for this niche.
Volume sits with polyolefin; growth tilts toward fluoropolymer.
Installation Method:
Deployment economics separate OEM platform contracts from fragmented aftermarket demand patterns.
- Automated:Robotic heat-shrinking line integration at Chinese tier-1 harness facilities demands tubing with tighter diameter tolerances and optimized shrink ratios. BYD and NIO supply chains in the Yangtze River Delta are driving fastest adoption for high-volume EV platform production.
- Manual:Hand-fed installation persists in prototype shops, low-volume specialty vehicle builds, and emerging market harness facilities with limited capital equipment. Labor cost arbitrage in Vietnamese manufacturing expansion zones sustains this method for initial production ramps.
- Semi-automated:Batch processing stations bridge manual and fully automated lines at mid-tier harness suppliers scaling toward OEM qualification. Zhejiang province processors deploy this configuration during production volume ramps.
- Heat Gun:Portable deployment dominates repair shops and aftermarket distributors servicing localized harness damage. Inventory concentration at Shanghai-Ningbo logistics hubs feeds regional distribution networks.
Platform-scale contracts favor automated; repair economics anchor heat gun.
End User:
Customer type determines specification stringency, volume predictability, and margin structure across the value chain.
- OEMs:Direct contracting with Chinese EV OEMs is displacing traditional distributor-mediated procurement for high-volume platform programs. Tier-1 harness manufacturers with captive polymer operations capture margin from tier-2 tubing processors in Jiangsu province.
- Aftermarket:Distributor networks serving independent repair facilities stock standard polyolefin grades with broad vehicle compatibility. Price compression from generic imports challenges branded positioning.
- Repair Shops:Localized harness servicing relies on heat gun deployment with immediate availability requirements. Geographic concentration in Yangtze River Delta automotive clusters creates inventory proximity advantages.
- Distributors:Channel intermediaries face margin pressure from direct OEM-resin compounder relationships. Value-add services including cut-to-length and kit assembly differentiate surviving intermediaries.
Revenue concentrates with OEMs; aftermarket retains volume breadth.
Certification:
Approval framework selection gates market access and determines testing investment requirements.
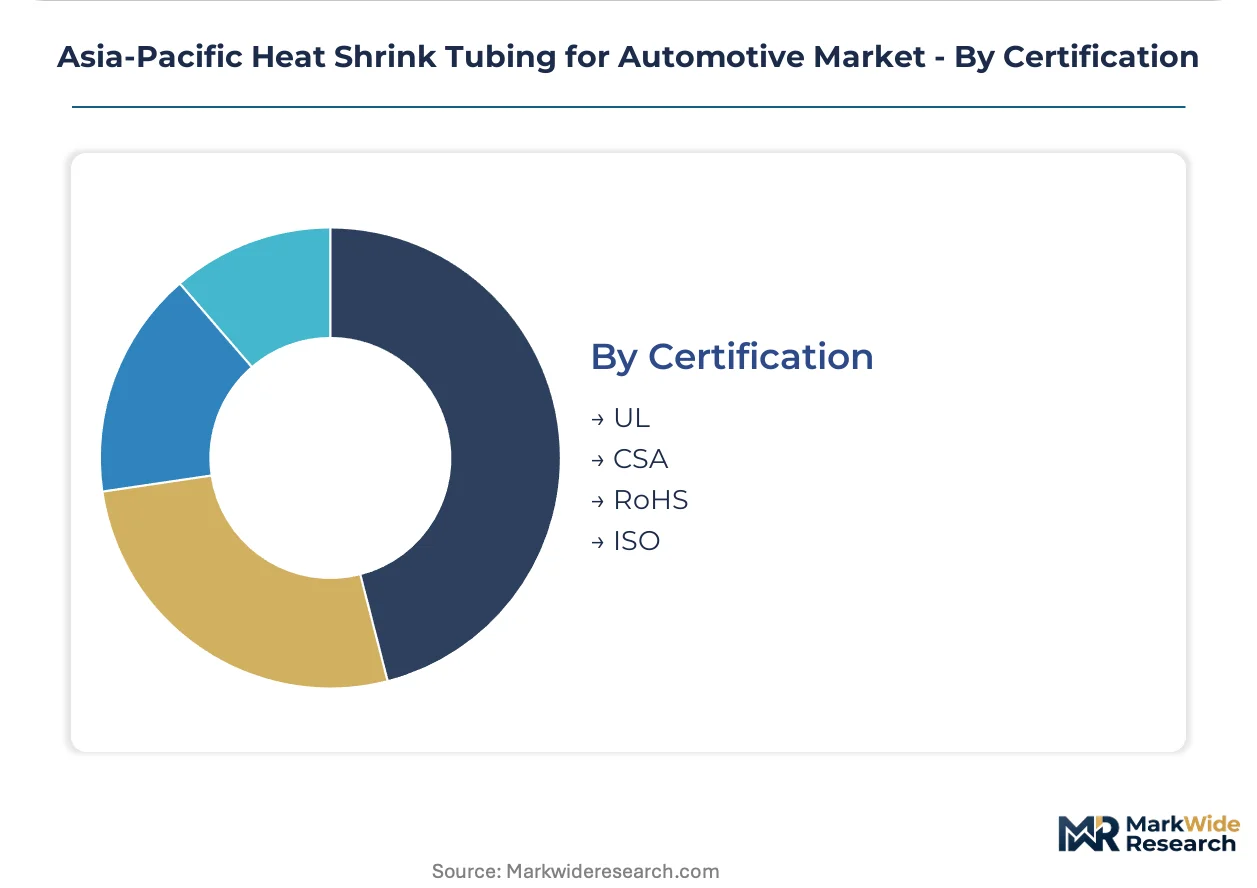
- RoHS:Substance restriction compliance underpins Chinese MIIT dual carbon mandates and Japanese METI environmental coordination. GB standards alignment with RoHS restrictions is fragmenting cross-border product qualification requirements.
- JIS/UL:Toyota, Honda, and Nissan procurement systems demand updated test documentation under METI-coordinated certification updates. Thai and Indonesian harness suppliers accelerate laboratory investment to secure revised material acceptance.
- CSA:Canadian-origin standards retain limited relevance for Asia-Pacific-focused supply chains. Exporters serving North American vehicle production maintain dual certification.
- ISO:Quality management system certification provides baseline supplier qualification without product-specific performance claims. Mid-cap suppliers leverage ISO as entry credential toward jurisdiction-specific approvals.
Compliance investment concentrates on RoHS; JIS updates drive fastest specification change.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese EV OEM procurement concentrates platform-grade tubing demand in the Yangtze River Delta, while Japanese OEM networks anchor premium fluoropolymer requirements through METI-coordinated supply chains. Regulatory divergence between MIIT GB standards and JIS specifications fragments cross-border product qualification timelines.
China
BYD and NIO platform-sharing strategies compress tubing specifications across shared EV architectures. MIIT dual carbon mandates enforce halogen-free flame-retardant upgrades under evolving GB standards. Tier-1 harness suppliers in Shanghai-Ningbo polymer processing hubs consolidate procurement around fewer qualified resin grades.
Japan
Toyota, Honda, and Nissan procurement systems demand updated JIS test documentation for passenger compartment wire insulation. METI coordinates certification pathway updates tightening smoke density and toxicity requirements. Technical workforces at state-owned material institutes concentrate cross-linking chemistry expertise.
Thailand
Japanese transplant OEMs operating in the Eastern Economic Corridor localize polymer compounding operations to reduce cross-border qualification delays. Thai manufacturing clusters serve as regional hubs for harness suppliers scaling toward OEM qualification. Limited elastomer compounding capacity addresses niche flexible harness routing demand.
India
BIS phased mandatory testing for automotive cable protection materials introduces compliance complexity under the automotive mission plan. Domestic harness facilities with limited capital equipment sustain manual installation methods during initial production ramps. Emerging platform certifications compress PVC acceptance for new vehicle programs.
Vietnam
Underpenetrated automotive wiring capacity in northern Vietnam offers positioning for suppliers establishing halogen-free compounding operations. Labor cost arbitrage sustains manual installation methods at emerging harness facilities. Regional EV supply chain migration patterns favor first-mover manufacturing expansion.
Asia-Pacific Heat Shrink Tubing for Automotive Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue automated installation compatibility and fluoropolymer specialization. The vendor base stratifies across three tiers: integrated harness manufacturers with captive polymer operations, independent tubing processors serving aftermarket channels, and resin compounders engaging in direct OEM contracting. Two competitive moves dominate: backward integration into polyolefin resin processing to capture margin from tier-2 processors, and laboratory investment to secure multi-jurisdiction certification acceptance.
Among Japan-based industrial conglomerates, Sumitomo Electric Industries anchors premium-tier positioning through polymer compounding expertise. Chinese specialists including Dasheng Group and Shenzhen Woer Heat-Shrinkable Material occupy distinct archetypes: the former exemplifies backward integration into resin processing, while the latter represents automated installation compatibility focus for high-volume EV platforms. These three entities illustrate the geographic and capability segmentation defining competitive positioning.
| Leading Market Players |
|---|
| Sumitomo Electric Industries, Ltd. |
| Dasheng Group |
| Shenzhen Woer Heat-Shrinkable Material Co., Ltd. |
| Huizhou Guanghai Electronic Insulation Materials Co., Ltd. |
| TE Connectivity |
| ABB |
| 3M Co. |
| Changchun Heat Shrinkable Materials |
| Alpha Wire Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive polymer operations at tier-1 harness manufacturers anchor both supply security and margin capture across Asia-Pacific automotive tubing procurement. BYD and NIO platform-sharing strategies in China's Yangtze River Delta consolidate procurement around vertically integrated suppliers, compressing pricing leverage for independent tier-2 processors.
Pricing Analysis
High-volume polyolefin contracts trade margin for scale, while fluoropolymer grades retain premium positioning through JIS certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates METI-coordinated Japanese OEM supply chains from Chinese domestic qualification pathways. Cost compression in standard-grade tubing intensifies because ethylene and propylene derivative volatility erodes producer buffers. Aftermarket distributors exhibit highest price sensitivity; OEM direct contracting shows lowest.
Supply Chain Analysis
Freight cost exposure concentrates around Shanghai-Ningbo polymer processing hubs serving Yangtze River Delta automotive clusters. Supply concentrates in China, Japan, and Thailand, with raw material dependencies on ethylene, propylene, and fluoropolymer resin feeds. Single-source vulnerability sits with cross-linking chemistry expertise concentrated among aging technical workforces. Distribution runs through tier-1 harness manufacturers with captive compounding, bypassing traditional distributor channels for platform-scale EV programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream control over polyolefin resin processing determines margin retention against platform-scale procurement consolidation.
For Market Incumbents: Cement captive supply advantages by deepening backward integration into halogen-free flame-retardant compounding ahead of MIIT specification tightening. Sumitomo Electric Industries' polymer expertise in Thai manufacturing clusters exemplifies defensive positioning against emerging Chinese entrants. Prioritize laboratory investment for simultaneous GB-JIS-BIS qualification to compress 8-14 month testing timelines.
For New Entrants and Emerging Players: Enter via underpenetrated northern Vietnam automotive wiring capacity before regional EV supply chain migration accelerates. Target manual installation segments at emerging harness facilities with limited capital equipment. Pursue automated heat-shrinking line compatibility as the go-to-market angle for tier-1 qualification.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by tier-1 harness manufacturers seeking captive polymer operations. Long-term viability favors compounders with multi-jurisdiction certification infrastructure spanning Chinese, Japanese, and Indian approval frameworks. Watch for divergence between GB standards and JIS specifications as the inflection signal for qualification complexity premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Processing | Captive polyolefin supply secures margin against platform-scale procurement consolidation. |
| Multi-Jurisdiction Certification Investment | Simultaneous GB-JIS-BIS qualification compresses testing timelines for cross-border contracts. |
| Automated Installation Line Integration | Robotic heat-shrinking compatibility unlocks BYD and NIO high-volume EV platform supply. |
| Halogen-Free Formulation Upgrade | MIIT dual carbon mandates accelerate flame-retardant specification shifts across wire harness insulation. |
| Vietnamese Manufacturing Footprint | First-mover positioning in northern Vietnam captures regional EV supply chain migration. |
Study Parameters
Multi-period observation of platform-sharing adoption, certification pathway divergence, and polymer procurement consolidation anchored the trend analysis, supplemented by interviews with tier-1 harness procurement managers, OEM platform engineers, resin compounder technical directors, and aftermarket distribution heads. Secondary validation drew from MIIT GB standard filings, METI JIS certification updates, BIS automotive mission plan documentation, vehicle production databases, and customs trade records. Bottom-up tubing volume estimates triangulated against top-down EV platform content assumptions.
Segment-weighting across product chemistry, installation method, end-user type, and certification pathway structured the analytical framework across the projection horizon. CAGRs derived from regression against EV penetration curves and wire harness content per vehicle trajectories. Modeled inputs included 800-volt architecture adoption rates and automated heat-shrinking line deployment at Chinese tier-1 facilities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under polyolefin resin price volatility or accelerated regulatory divergence between Chinese and Japanese standards. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Active Suspension Damper Actuator Systems Market
Automotive Components
France Automotive Electric Actuators Market
Automotive Components
Automobile Accessories Market
Automotive Components
Automotive Stamped Component Market
Automotive Components
Automotive Sheet Metal Components Market
Automotive Components
Advanced Automotive Materials Market
Automotive Components
Automotive Connecting Rod Bearing Market
Automotive Components
Automotive Brake Pads Market
Automotive Components
Automotive Axle Market
Automotive Components
Africa and Middle East Automotive Actuators Market
Automotive Components
Automotive Engine Connecting Rods Market
Automotive Components
Automotive Active Suspension System Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Automotive Subframe Market
Automotive Components
Saudi Arabia Automotive Actuators Market
Automotive Components
Automotive Catalytic Converter Market