
 Automotive Horn Systems Market | 2026-2036
Automotive Horn Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Horn Systems Market Analysis
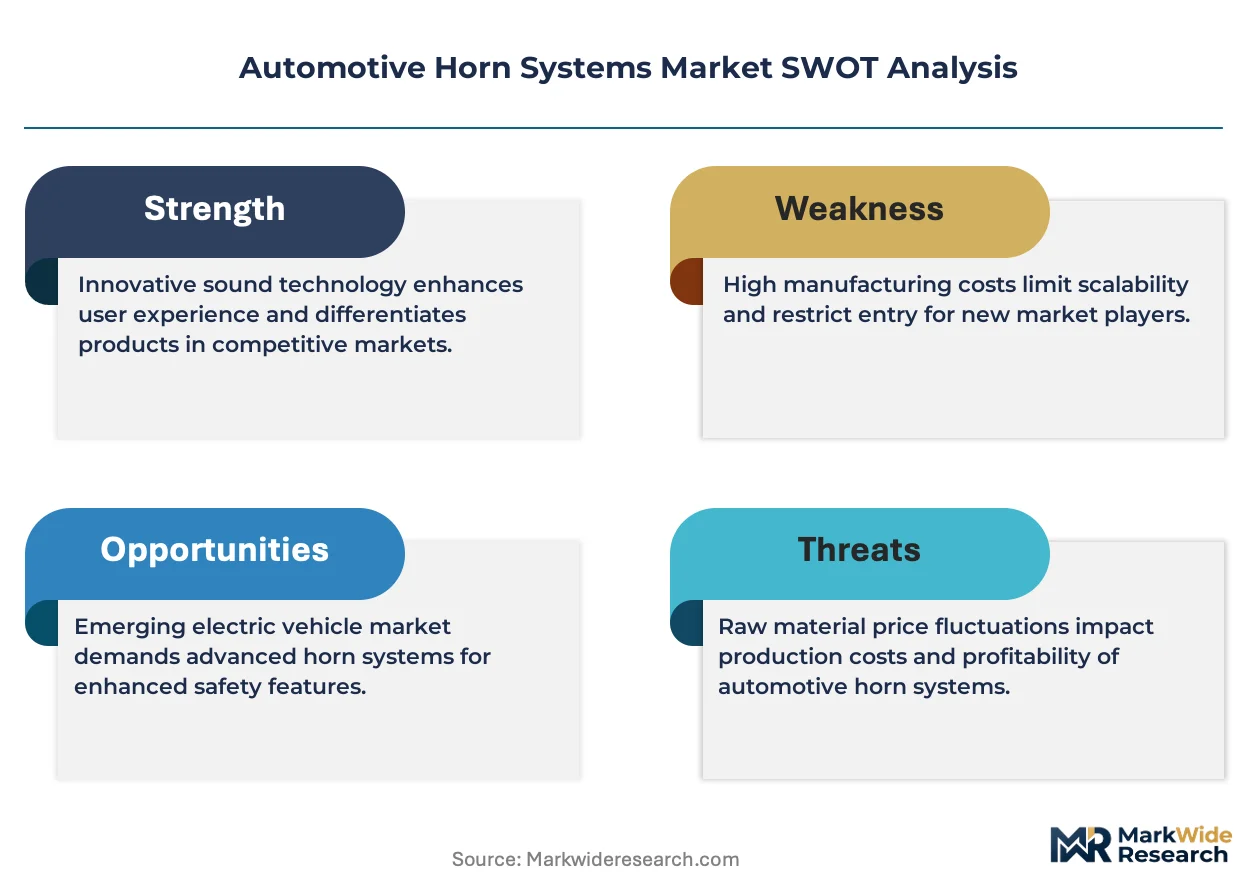
Electric vehicle manufacturers are pivoting toward low-power, high-decibel horn designs that preserve battery range without compromising pedestrian safety. Denso Corporation leverages its tier-1 supplier relationships with Japanese OEMs to dominate electromagnetic horn production. Robert Bosch sustains technology leadership through integrated acoustic sensor platforms. Mitsuba Corporation anchors aftermarket channels across Southeast Asia with cost-optimized disc horn portfolios.
Automotive horn systems are electromechanical or pneumatic acoustic warning devices typically generating 90–115 dB at two meters, engineered to alert pedestrians and nearby vehicles through controlled diaphragm vibration or compressed air discharge. Electromagnetic horns occupy the largest installed base due to compact packaging and minimal power draw, while air horns command premium positioning in heavy commercial vehicles where regulatory minimums exceed 100 dB. Musical horns represent a niche but growing segment in aftermarket customization, particularly across two-wheeler applications in India and Southeast Asia where brand differentiation drives replacement cycles.
India's Ministry of Road Transport enforces CMVR noise limits through ARAI certification, compressing demand toward compliant 93 dB electromagnetic units. China's MIIT integrates horn specifications into GB vehicle type-approval standards, restricting aftermarket modifications. The EU's UNECE R28 framework mandates directional sound testing, forcing redesigns for European-market exports. Stakeholders must monitor divergence between emerging-market permissiveness and developed-market acoustic strictness when allocating R&D budgets across product architectures.
Market Dynamics
Electric vehicle platform consolidation is compressing horn system architectures toward unified 12V/48V electrical domains, forcing suppliers to redesign electromagnetic drivers for compatibility with next-generation battery management topologies.
Growth Catalysts
- CMVR Decibel Mandates:India's Central Motor Vehicle Rules mandate specific 93 dB maximum thresholds, redirecting aftermarket demand toward ARAI-certified electromagnetic units and eliminating non-compliant imports.
- Commercial Fleet Retrofit Cycles:Asia-Pacific logistics operators are upgrading heavy truck warning systems to meet stricter road safety codes, expanding replacement demand for dual-tone air horn configurations.
- EV Acoustic Optimization:Low-current horn designs preserve battery range in electric passenger vehicles, aligning with OEM targets for auxiliary load reduction.
Market Restraints
- Copper Diaphragm Volatility:Electromagnetic horn manufacturing depends on copper alloy pricing, with sheet metal cost swings compressing margin stability for tier-2 component suppliers.
- Aftermarket Modification Bans:China's MIIT integrates horn specifications into GB type-approval standards, criminalizing non-factory acoustic alterations and shrinking the customization segment.
- Acoustic Substitution Pressure:External sound synthesis systems for pedestrian warning in EVs reduce reliance on traditional horn functions in low-speed urban environments.
Strategic Opportunities
- Musical Horn Aftermarket:Two-wheeler riders in India and Vietnam seek brand-differentiating melodic signatures, creating replacement-cycle revenue beyond functional compliance.
- UNECE R28 Export Alignment:Directional sound testing requirements for European-market homologation reward suppliers investing in anechoic chamber certification capabilities.
- Integrated Sensor Platforms:Convergence of horn actuation with ADAS acoustic sensors enables tier-1 suppliers to bundle warning hardware into larger driver assistance contracts.
Industry Challenges
- Electromagnetic Compatibility Testing:OEM qualification timelines stretch 18-24 months for horn systems requiring validation against 48V electrical arc interference.
- Legacy Pneumatic Integration:Heavy commercial vehicle manufacturers face friction retrofitting electronic horn controllers into existing compressed air architectures without full cab redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Horn Systems Market |
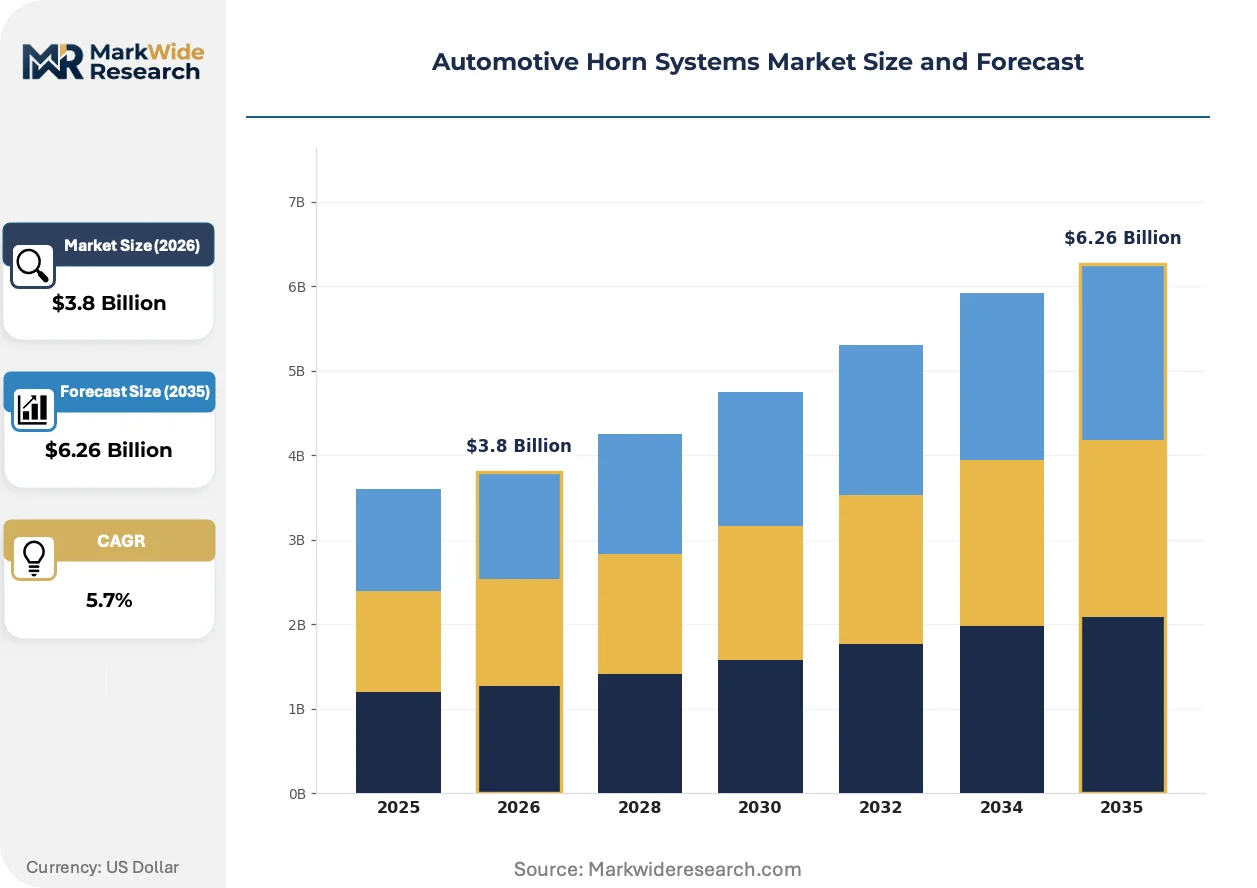
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic Horns, Air Horns, Disc Horns, Musical Horns Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Electric Vehicles Material: Plastic, Metal, Composite, Rubber Installation Type: OEM, Aftermarket, Custom Fit, Universal Fit |
| Companies Covered | Denso Corporation, Mitsuba Corporation, Robert Bosch, Wolo Manufacturing, Imasen Electric Industrial, HELLA, Fiamm, SORL Auto Parts, Uno Minda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Horn Systems Market Emerging Trajectories
Component miniaturization and acoustic engineering advances are collapsing the traditional trade-off between horn output power and packaging volume, enabling placement in constrained EV front modules previously reserved for passive crash structures.
Smart horn controllers with programmable amplitude curves are modularizing across premium electric vehicle lineups. NIO and Li Auto integrate these units to vary pedestrian alert intensity based on proximity sensor inputs. This architecture is compressing demand for fixed-output electromagnetic designs by enabling software-defined acoustic profiles.
UNECE R28 directional sound testing is forcing redesigns of dual-horn mounting geometries for European-market exports. Suppliers must now validate left-right amplitude balance across ±15 degree azimuth angles, adding anechoic chamber capacity requirements. Japanese OEMs serving EU markets have accelerated supplier audits to pre-qualify compliant acoustic packages ahead of 2026 model-year deadlines.
Fleet procurement managers now bundle horn replacement into scheduled maintenance contracts rather than ad-hoc aftermarket purchases. This consolidation favors direct supplier relationships over distributor intermediaries in North American commercial vehicle channels. Large logistics operators including Schneider and J.B. Hunt negotiate multi-year acoustic component supply agreements with tier-1 manufacturers.
Automotive Horn Systems Market Segmentation
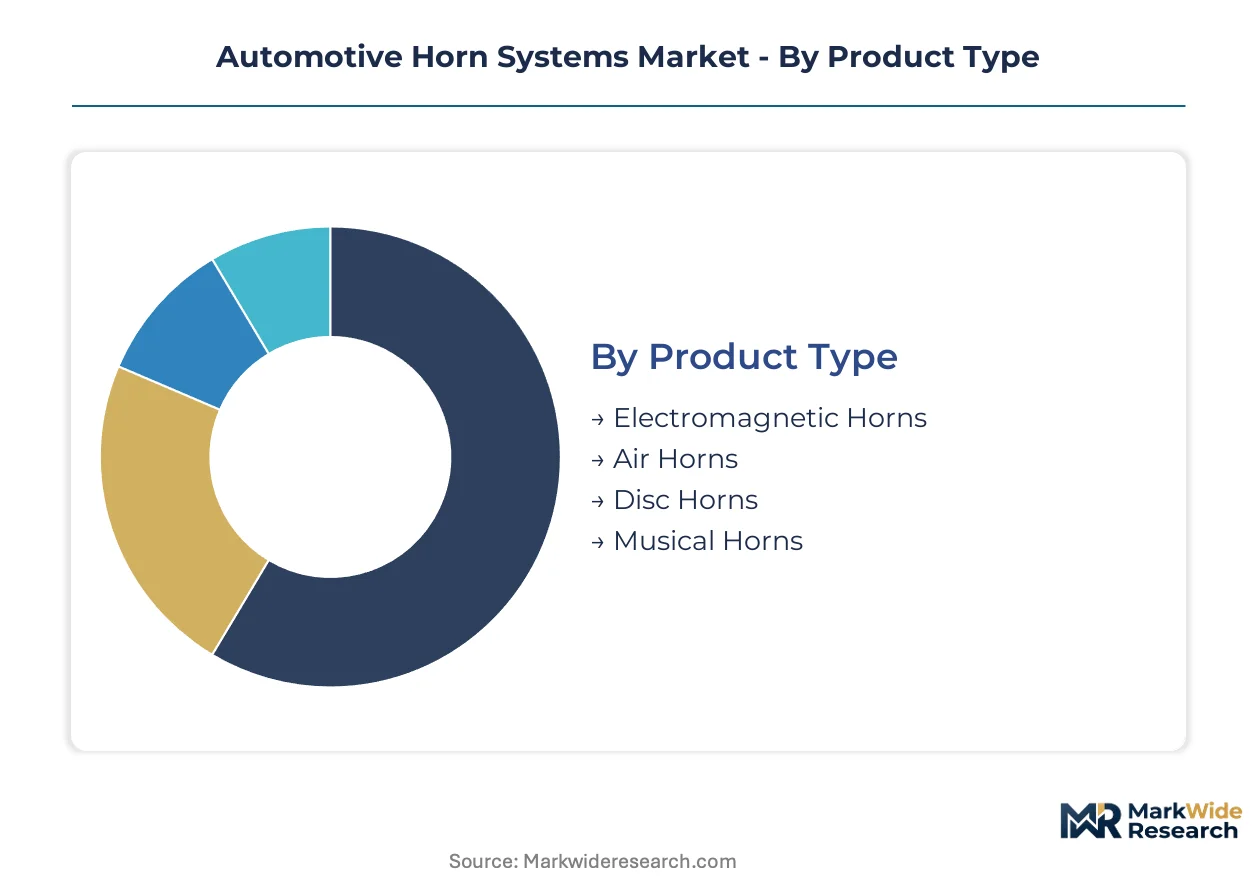
Automotive horn system segmentation reveals divergent certification burdens across product architectures. Material selection and installation channel determine which regulatory frameworks—ARAI, MIIT, UNECE R28—suppliers must satisfy for market access.
Product Type:
Electromagnetic variants face ARAI decibel certification under India's CMVR, while air horn configurations trigger UNECE R28 directional testing for European export eligibility.
- Electromagnetic Horns:Compact diaphragm assemblies utilizing copper coil actuation generate 90-115 dB outputs with minimal current draw. Passenger vehicle OEMs in China and South Korea specify these units for electric vehicle platforms where auxiliary load preservation matters. CMVR 93 dB maximums compress demand toward compliant single-tone designs.
- Air Horns:Compressed-air discharge systems produce sustained outputs exceeding 100 dB through dual-trumpet configurations. Heavy commercial vehicle fleets across India and Southeast Asia retrofit these units to satisfy escalating road safety code enforcement. Pneumatic integration complexity limits adoption in electric vehicle architectures lacking compressed air infrastructure.
- Disc Horns:Flat-profile electromagnetic alternatives optimized for packaging-constrained engine compartments.
- Musical Horns:Programmable melodic output devices serving aftermarket customization demand among two-wheeler riders.
Leading the category by volume: Electromagnetic Horns. Growing fastest: Musical Horns.
Application:
End-use segmentation tracks divergent power architecture requirements across propulsion technologies, with 48V domain compatibility becoming a gatekeeping specification.
- Passenger Vehicles:Integrated 12V/48V electrical domain compatibility dominates supplier qualification timelines. Smart horn controllers with proximity-variable amplitude now penetrate premium electric vehicle lineups from NIO and Li Auto.
- Commercial Vehicles:Fleet procurement consolidation favors direct tier-1 supply agreements over distributor channels. Schneider and J.B. Hunt negotiate multi-year acoustic component contracts bundling horn replacement into scheduled maintenance.
- Two-Wheelers:Aftermarket replacement cycles concentrate in India and Vietnam where brand-differentiating melodic signatures drive musical horn demand.
- Electric Vehicles:Low-current electromagnetic designs preserve battery range while satisfying pedestrian warning mandates. External sound synthesis systems at low speeds reduce traditional horn dependency in urban environments.
Volume concentration: Passenger Vehicles. Steepest expansion trajectory: Electric Vehicles.
Material:
Raw material selection determines acoustic damping characteristics and corrosion resistance for underhood placement.
- Metal:Copper alloy diaphragms and steel housings dominate electromagnetic horn manufacturing. Copper price volatility compresses margin stability for tier-2 component suppliers.
- Plastic:Glass-filled polyamide enclosures enable weight reduction in electric vehicle front modules.
- Composite:Hybrid material stacks balancing acoustic resonance with packaging miniaturization.
- Rubber:Vibration isolation grommets and sealing elements for environmental protection.
Primary volume: Metal. Fastest material transition: Plastic.
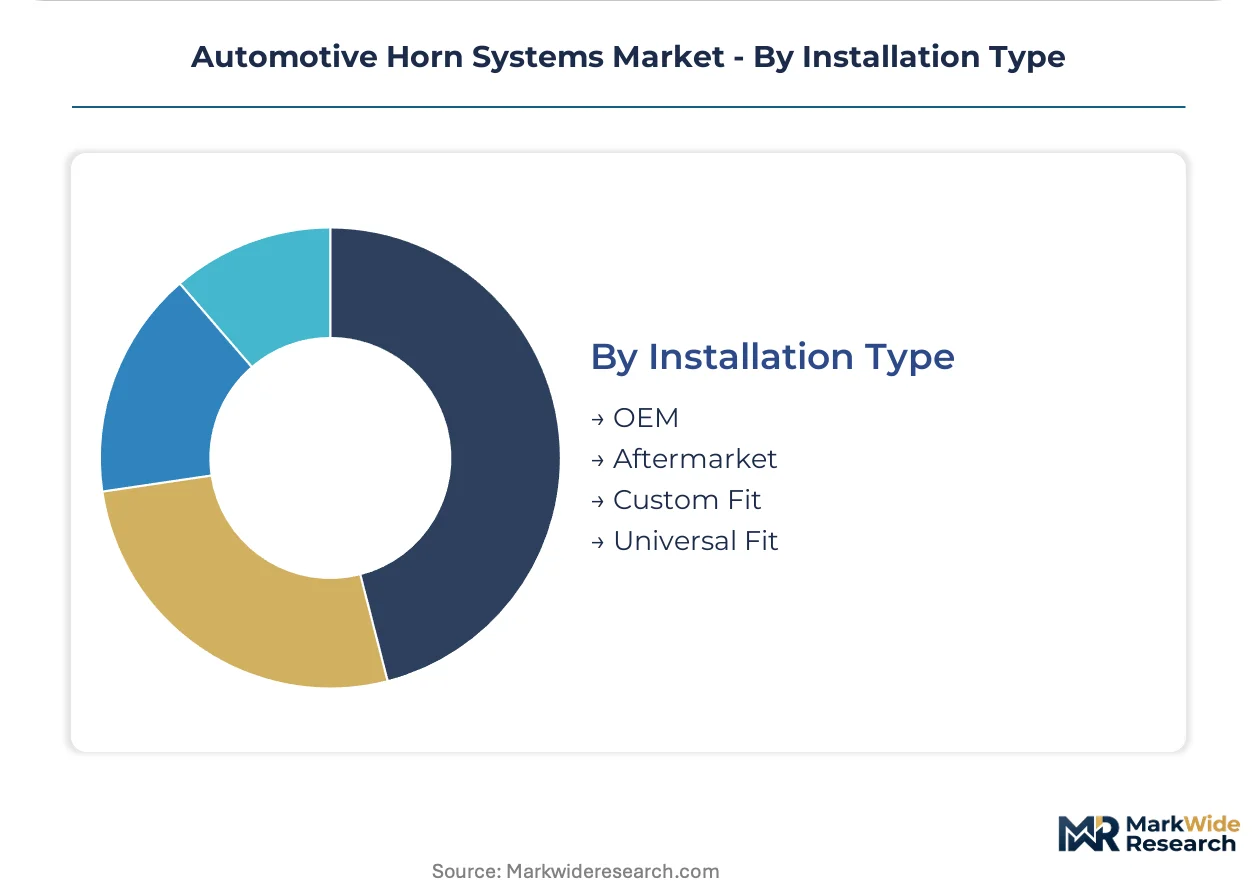
Installation Type:
Channel structure determines regulatory exposure, with factory-fit units carrying type-approval burden versus aftermarket freedom.
- OEM:Factory-installed units must satisfy GB type-approval in China and UNECE R28 in Europe. Denso Corporation and Robert Bosch leverage tier-1 relationships to embed horn systems within larger driver assistance contracts.
- Aftermarket:India's ARAI certification redirects demand toward compliant electromagnetic units while China's MIIT criminalizes non-factory acoustic alterations. Mitsuba Corporation anchors Southeast Asian aftermarket channels with cost-optimized disc horn portfolios.
- Custom Fit:Vehicle-specific mounting hardware and wiring harnesses for direct replacement.
- Universal Fit:Adaptable mounting brackets serving heterogeneous fleet maintenance operations.
Revenue concentration: OEM. Channel expansion: Aftermarket.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures electromagnetic horn systems for domestic electric vehicle platforms while India consumes the largest aftermarket volume for two-wheeler acoustic customization. Germany and Japan export precision-engineered units to European and Asian OEMs respectively. The United States concentrates air horn demand within heavy commercial fleet retrofits.
China
Domestic electric vehicle manufacturers specify low-current electromagnetic horns compatible with 48V electrical domains. MIIT integrates horn specifications into GB vehicle type-approval standards, criminalizing non-factory acoustic modifications. Shanghai and Shenzhen house tier-1 supplier engineering centers serving BYD and NIO proximity-variable horn controller programs.
India
Two-wheeler riders drive aftermarket replacement cycles for brand-differentiating musical horns. The Central Motor Vehicle Rules enforce ARAI-certified 93 dB maximum thresholds, eliminating non-compliant imports. Pune and Chennai cluster electromagnetic horn manufacturing for Maruti Suzuki and Bajaj Auto factory-fit programs.
Germany
Heavy commercial vehicle OEMs source dual-trumpet air horn configurations for export markets requiring UNECE R28 directional sound compliance. KBA enforces left-right amplitude balance validation across ±15 degree azimuth angles. Stuttgart and Munich anchor acoustic engineering R&D for European-market homologation.
Japan
Tier-1 suppliers leverage OEM relationships to embed horn systems within integrated driver assistance contracts. METI coordinates standards alignment with UNECE R28 for export-bound vehicle platforms. Nagoya and Yokohama concentrate electromagnetic horn production for Toyota and Honda global supply chains.
United States
Commercial fleet operators negotiate multi-year acoustic component supply agreements bundling horn replacement into scheduled maintenance. NHTSA maintains Federal Motor Vehicle Safety Standards for horn audibility without prescribing specific decibel ceilings. Michigan and Ohio house heavy truck manufacturing corridors driving air horn retrofit demand.
Automotive Horn Systems Market Vendor Landscape
Top-tier vendors anchor OEM supply chains through tier-1 automotive relationships, while mid-scale fabricators serve aftermarket channels with cost-optimized disc horn portfolios. The vendor base stratifies across electromagnetic specialists, air horn manufacturers, and musical horn customization providers. Three archetypes dominate: integrated acoustic platform suppliers, regional aftermarket distributors, and niche melodic signature developers. Competitive positioning depends on anechoic chamber certification capacity and 48V electrical domain compatibility timelines.
Within the integrated platform tier, Denso Corporation and Robert Bosch exemplify tier-1 supplier architectures. Denso leverages Japanese OEM relationships to dominate electromagnetic horn production for factory-fit programs. Bosch sustains technology positioning through acoustic sensor platform convergence with ADAS hardware. Mitsuba Corporation occupies a distinct aftermarket-focused position, anchoring Southeast Asian distribution channels with cost-optimized portfolios.
| Leading Market Players |
|---|
| Denso Corporation |
| Mitsuba Corporation |
| Robert Bosch |
| Wolo Manufacturing |
| Imasen Electric Industrial |
| HELLA |
| Fiamm |
| SORL Auto Parts |
| Uno Minda |
| Others |
Supply Flow & Price Mechanics
India's CMVR 93 dB decibel mandate gates qualified supply for electromagnetic horn certification while compressing aftermarket pricing tiers toward ARAI-compliant units, forcing premium-tier pricing access to hinge on anechoic chamber validation capacity rather than raw acoustic output alone.
Pricing Analysis
Margin tightening in tier-2 electromagnetic horn manufacturing reflects copper alloy sheet metal cost swings and compressed OEM qualification timelines stretching 18-24 months. Pricing stratifies across premium, standard, and economy tiers based on UNECE R28 directional testing certification and 48V electrical domain compatibility. Cost-down pressure on standard-tier units accelerates because Chinese MIIT integration of horn specifications into GB type-approval standards criminalizes non-factory modifications, shrinking customization revenue. Fleet procurement managers at Schneider and J.B. Hunt exhibit lowest price sensitivity through multi-year supply agreements, while two-wheeler aftermarket riders in Vietnam demonstrate highest sensitivity to unit cost differentials.
Supply Chain Analysis
Single-source vulnerability sits with copper alloy diaphragm suppliers in China and electromagnetic coil winding operations concentrated in South Korea and Japan. Raw material dependencies include copper sheet metal, glass-filled polyamide enclosures, and neodymium magnet assemblies. Supply chain risk centers on tariff exposure for Chinese-manufactured components entering European UNECE R28 certification pipelines. Distribution runs through tier-1 supplier direct relationships with OEM platform engineers and aftermarket distributor networks anchored by Mitsuba Corporation across Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive horn systems market sits in a technology-transition phase where smart horn controllers with proximity-variable amplitude curves displace fixed-output electromagnetic designs across premium electric vehicle lineups.
For Market Incumbents: Anchor defensive positioning through backward integration into copper alloy diaphragm production to offset raw material volatility, while accelerating anechoic chamber certification investments to pre-qualify UNECE R28-compliant acoustic packages ahead of European model-year deadlines. Denso Corporation and Robert Bosch should leverage existing tier-1 OEM relationships to bundle horn actuation hardware into integrated ADAS sensor platform contracts, displacing standalone component suppliers. For New Entrants and Emerging Players: Direct-to-distributor e-commerce channels offer the lowest-friction entry path for musical horn customization targeting two-wheeler riders in India and Vietnam, where brand-differentiating melodic signatures drive replacement cycles beyond functional compliance. White-space concentration sits with cost-optimized disc horn portfolios for Southeast Asian aftermarket channels and programmable amplitude controller modules for Chinese EV manufacturers lacking in-house acoustic engineering. For Investors and Strategic Acquirers: Tier-1 supplier acquisition of anechoic chamber certification facilities is the leading indicator that UNECE R28 directional testing capacity will consolidate pricing power among integrated acoustic platform providers over the mid-term horizon. Target vertically integrated specialists combining electromagnetic driver manufacturing with smart controller firmware development, as external sound synthesis systems for EV pedestrian warning signal long-term displacement risk for traditional horn functions.| Strategic Initiative | Industry Significance |
|---|---|
| UNECE R28 Anechoic Chamber Certification | Directional sound testing capacity gates European-market homologation for dual-horn mounting geometries. |
| 48V Electrical Domain Compatibility Investment | Redesigned electromagnetic drivers align with NIO and Li Auto battery management topologies. |
| Integrated ADAS Sensor Platform Convergence | Bosch bundles horn actuation hardware into larger driver assistance contracts with Japanese OEMs. |
| Musical Horn Aftermarket Channel Expansion | Brand-differentiating melodic signatures capture replacement-cycle revenue in India and Vietnam. |
| Copper Alloy Backward Integration | Captive diaphragm production insulates margin stability against sheet metal cost volatility. |
Methodological Framework
Multi-period observation of vehicle production databases, IHS Markit registration data, and OEM platform engineering disclosures anchored the trend analysis, supplemented by interviews with tier-1 supplier procurement leads, aftermarket distributor operations heads, and ARAI certification engineers. Secondary validation drew from MIIT GB type-approval filings, UNECE R28 test protocols, and customs records tracking copper alloy trade flows. Bottom-up triangulation across electromagnetic horn unit shipments and top-down reconciliation against electric vehicle platform consolidation timelines ensured cross-verified demand estimates.
Segment-weighting applied product type splits across electromagnetic, air, disc, and musical horn configurations, application differentiation across passenger vehicle, commercial fleet, two-wheeler, and electric vehicle architectures, and installation channel bifurcation between OEM factory-fit and aftermarket replacement. CAGRs were derived from regression analysis of auxiliary load reduction targets and pedestrian safety mandate implementation schedules. Forecast inputs included 48V electrical domain adoption curves and fleet procurement contract consolidation patterns.
Inputs from tier-1 supplier engineering centers and ARAI certification laboratories were available through the study window; gaps in real-time copper alloy pricing transparency and unannounced OEM platform redesigns introduce uncertainty bands around electromagnetic horn demand projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive Integrated Control Panel Market
Automotive Circuit Systems
South Korea Automotive Relay Market
Automotive Circuit Systems
Automotive Touch Screen Control Systems Market
Automotive Circuit Systems
Automotive Oil Pressure Control Valve Market
Automotive Circuit Systems
Global Automotive Display System Market
Automotive Circuit Systems
Global Automotive Power Distribution Modules Market
Automotive Circuit Systems
Automotive Steer-by-Wire Actuator Market
Automotive Circuit Systems
Automotive V2X Antenna Market
Automotive Circuit Systems
Dual Circuit Brakes System Market
Automotive Circuit Systems
Global Automotive Engine Management System Market
Automotive Circuit Systems
Steering Thermal Systems Market
Automotive Circuit Systems
Automotive Advanced Shifter System Market
Automotive Circuit Systems
Japan Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Automotive Ethernet Switches Market
Automotive Circuit Systems
Traction Control System Market
Automotive Circuit Systems
Automotive Grade Inductors Market