
 Briquetting Machine Market | 2026-2036
Briquetting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Briquetting Machine Market Outlook
Aftermarket service revenue is reconfiguring margin capture across the competitive landscape. WEIMA Maschinenbau GmbH leverages its German engineering base to dominate high-throughput industrial installations across Europe. RUF US, Inc. anchors North American demand through extensive spare parts logistics and field technician networks. Ecostan India Pvt. Ltd. competes aggressively on localized fabrication costs while extending service reach into Southeast Asian markets.
A briquetting machine compresses loose biomass, metal swarf, or industrial waste into dense, uniformly shaped blocks using applied pressure and often controlled temperature. Mechanical press systems typically deliver output densities between 1,000 and 1,400 kg per cubic meter, making them suitable for coal substitution in cement kilns and thermal power stations. Hydraulic press configurations command premium pricing due to their ability to process harder materials such as cast iron borings and stainless steel turnings with consistent briquette integrity. Screw press technology dominates agricultural residue applications across South Asia where feedstock moisture variability demands continuous extrusion rather than batch compression.
The EPA's industrial waste regulations in the United States restrict landfill disposal of metalworking sludge, directly stimulating demand for briquetting systems that extract cutting fluids and densify solids. India's BIS certification requirements for biomass briquette fuel standards create compliance barriers for uncertified equipment imports while favoring domestic manufacturers with established testing protocols. China's MEE enforcement of dual carbon goals pushes steel producers toward coke-briquette blends that reduce per-ton emissions intensity. Stakeholders must monitor how tightening particulate emissions standards across multiple jurisdictions reshape acceptable binder chemistries and machine exhaust configurations.
Market Dynamics
Carbon border adjustment mechanisms and industrial waste directives are forcing steel mills and foundries across Turkey, India, and Brazil to densify process residues into standardized briquette feedstock rather than incur landfill penalties or import tariffs on carbon-intensive alternatives.
Growth Catalysts
- EU Waste Framework Directive:The revised directive pressures industrial operators in Germany, Italy, and Poland to convert metalworking sludge and biomass residues into certified fuel briquettes, eliminating landfill disposal routes.
- Blast furnace feedstock substitution:Steel producers in Turkey and Brazil are expanding briquette consumption to reduce coke dependency and lower per-ton emissions intensity in primary steelmaking.
- Agricultural residue clustering:Rice husk and straw briquetting operations in India's Punjab-Haryana belt serve proximate thermal power plants and brick kilns with reliable biomass fuel supply.
Market Restraints
- Scrap metal price volatility:Fluctuations in ferrous scrap and steel turnings pricing compress briquette producer margins and deter long-term equipment investment cycles.
- Hydraulic component supply concentration:High-pressure hydraulic pumps and precision cylinders for industrial briquetting presses concentrate among German and Japanese suppliers, creating lead time vulnerability.
- Moisture content technical limitation:Mechanical press systems require feedstock below 15% moisture for optimal density, restricting direct processing of fresh agricultural residues without pre-drying infrastructure.
Strategic Opportunities
- Indonesian palm oil residue valorization:Empty fruit bunches and palm kernel shells from Sumatra and Kalimantan processing mills represent underexploited feedstock for industrial-scale briquetting serving regional cement kilns.
- Carbon credit monetization:Verified emissions reduction frameworks in voluntary carbon markets enable briquette producers to capture incremental revenue from coal displacement in thermal applications.
- Remote monitoring convergence:Integration of IoT sensors with hydraulic press systems enables predictive maintenance and throughput optimization for distributed agricultural residue processing networks.
Industry Challenges
- Skilled technician scarcity:Hydraulic system diagnostics and die maintenance expertise remains concentrated among aging workforces in European equipment manufacturing hubs, constraining service response times in emerging markets.
- BIS certification timeline:India's biomass briquette fuel standards require extended testing protocols for imported equipment, delaying market entry for non-domestic manufacturers lacking established laboratory relationships.
- Legacy control system integration:Foundries and steel mills operating decades-old furnace automation face complex retrofit requirements to accommodate briquette feedstock handling and combustion monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Briquetting Machine Market |
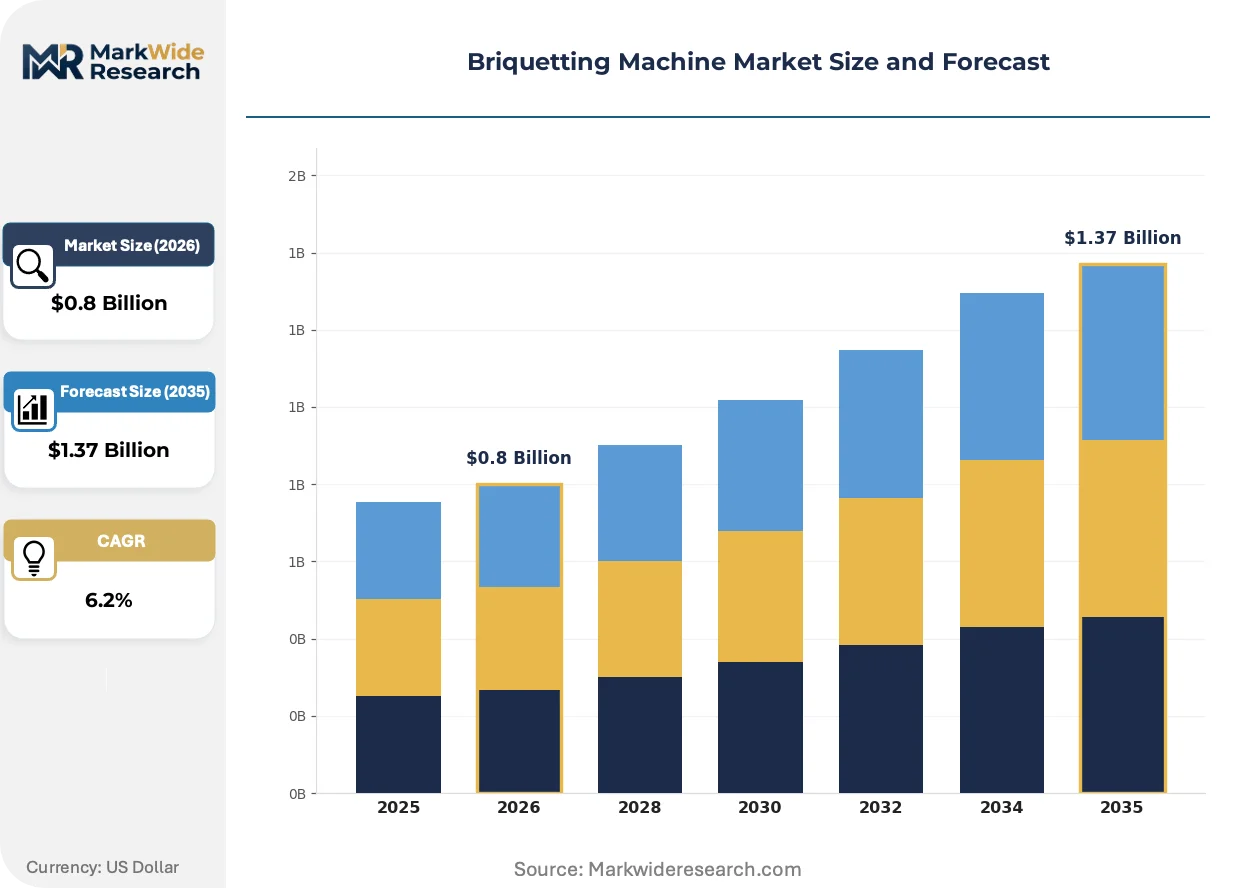
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.37 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Press, Hydraulic Press, Screw Press, Punching Press Material Type: Wood Waste, Agricultural Residues, Industrial Waste, Biomass End User: Energy Sector, Manufacturing, Waste Management, Agriculture Sales Channel: Direct Sales, Distributors, Online Retailers, Others |
| Companies Covered | RUF US, Inc., C.F. Nielsen, WEIMA Maschinenbau GmbH, Anyang Gemco Energy Machinery Co., Ltd., K.R. Komarek Inc., Ruf Maschinenbau GmbH, Ecostan India Pvt. Ltd., Lehra Fuel Tech, Top Briquetting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Briquetting Machine Market Strategic Shifts
Digital twin architectures and predictive maintenance platforms are compressing equipment downtime and reshaping how operators optimize press configuration for variable feedstock quality across distributed processing networks.
Digital twin software is virtualizing press performance simulation before physical die changes, allowing operators to model density outcomes across moisture gradients and particle size distributions. Steel mills in South Korea and Brazil are deploying these systems to minimize trial batches when switching between cast iron borings and stainless steel turnings. The technology is virtualizing traditional equipment commissioning timelines and reducing raw material waste during process parameter optimization.
China's MEE enforcement of dual carbon goals is mandating coke-briquette blend ratios in blast furnace operations, compelling equipment suppliers to certify emission reduction metrics alongside mechanical performance. Steel producers in Hebei and Shandong provinces are retrofitting existing presses with real-time carbon intensity tracking to demonstrate compliance. This regulatory pressure is accelerating replacement cycles for pre-2020 hydraulic installations lacking integrated emissions monitoring capabilities.
After-sales service unbundling is fragmenting traditional equipment procurement models as operators separate capital acquisition from maintenance contracting and consumables supply. Large agricultural cooperatives in India's Uttar Pradesh are sourcing screw presses from domestic fabricators while contracting specialized firms for die refurbishment and remote troubleshooting. This behavioral shift is compressing manufacturer margins on initial equipment sales while expanding recurring revenue pools for technical service providers with established field networks.
Briquetting Machine Market Segmentation
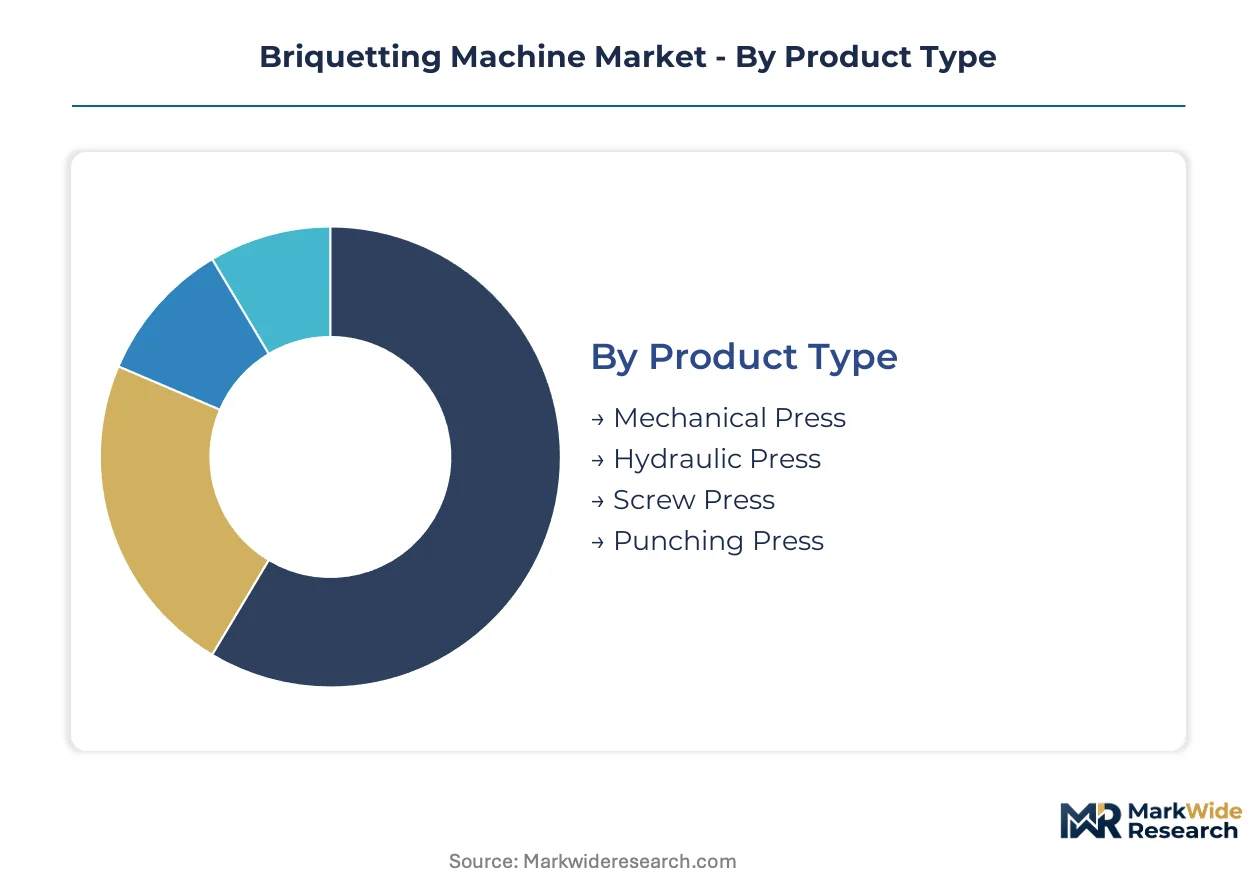
Segmentation in briquetting machines reveals divergent equipment lifecycles and replacement patterns across press technologies and material applications. Understanding these cycles helps suppliers align inventory, service contracts, and R&D investments with actual demand velocity.
Product Type:
Replacement cycles stretch from three years for entry-level screw presses to twelve-plus years for heavy-duty hydraulic installations, creating distinct aftermarket revenue windows.
- Mechanical Press:These systems deploy eccentric drives and flywheel mechanisms to deliver compression forces between 1,000 and 1,400 kg per cubic meter output density. Demand concentrates in India's Punjab-Haryana belt where rice husk processors supply proximate thermal power plants and brick kilns with standardized biomass fuel, constrained by feedstock moisture requirements below 15%.
- Hydraulic Press:High-pressure hydraulic pumps and precision cylinders generate sufficient force to densify cast iron borings and stainless steel turnings into furnace-ready briquettes with consistent structural integrity. Steel mills in Turkey and Brazil are expanding these installations to reduce blast furnace coke dependency while complying with tightening carbon border adjustment mechanisms.
- Screw Press:Continuous extrusion designs dominate South Asian agricultural residue processing where feedstock moisture variability demands adaptive throughput rather than batch compression cycles.
- Punching Press:Ram-driven compression systems serve niche metal swarf applications requiring discrete briquette geometries for specialized foundry feedstock handling.
Mechanical press installations anchor the volume base while hydraulic press configurations gain share at the steepest rate.
Material Type:
Processing economics vary sharply by feedstock energy density, ash content, and preprocessing requirements, with biomass commanding premium equipment specifications.
- Wood Waste:Sawdust and chip residues from sawmills and furniture manufacturing require moderate compression forces and standard die configurations. European pulp and paper integrated operations deploy these systems to convert process residues into on-site boiler fuel, driven by EU Waste Framework Directive landfill diversion mandates.
- Agricultural Residues:Rice husk, wheat straw, and cotton stalk processing demands screw press technology with hardened extrusion barrels to manage silica abrasion and variable particle sizes. India's BIS certification requirements for biomass briquette fuel standards favor domestic equipment manufacturers with established testing laboratory relationships.
- Industrial Waste:Metal swarf, grinding sludge, and machining turnings require fluid extraction systems integrated with briquetting presses to recover cutting oils and densify solids for furnace feedstock.
- Biomass:Dedicated energy crops and purpose-grown feedstocks command the highest processing specifications due to controlled moisture content and calorific value requirements for utility-scale cofiring.
Agricultural residue processing dominates installed base volume while biomass-to-energy applications are climbing the fastest.
End User:
Customer technical sophistication and procurement authority structures diverge significantly between industrial operators and decentralized agricultural processors.
- Energy Sector:Utility and independent power producers specify briquette fuel for cofiring with coal in thermal generation assets. Cement kilns in Indonesia's Sumatra and Kalimantan regions source palm kernel shell briquettes as alternative fuel under emerging dual carbon compliance frameworks.
- Manufacturing:Steel mills and foundries densify process residues for blast furnace feedstock substitution, with China's MEE enforcement mandating coke-briquette blend ratios in Hebei and Shandong provinces.
- Waste Management:Specialized contractors operate centralized briquetting facilities for municipal and industrial waste stream diversion from landfill disposal routes.
- Agriculture:Cooperative-owned processing clusters in India's Uttar Pradesh source equipment through domestic fabricators while contracting specialized firms for die refurbishment and remote troubleshooting services.
Manufacturing sector demand anchors current revenue while energy sector procurement is expanding most quickly.
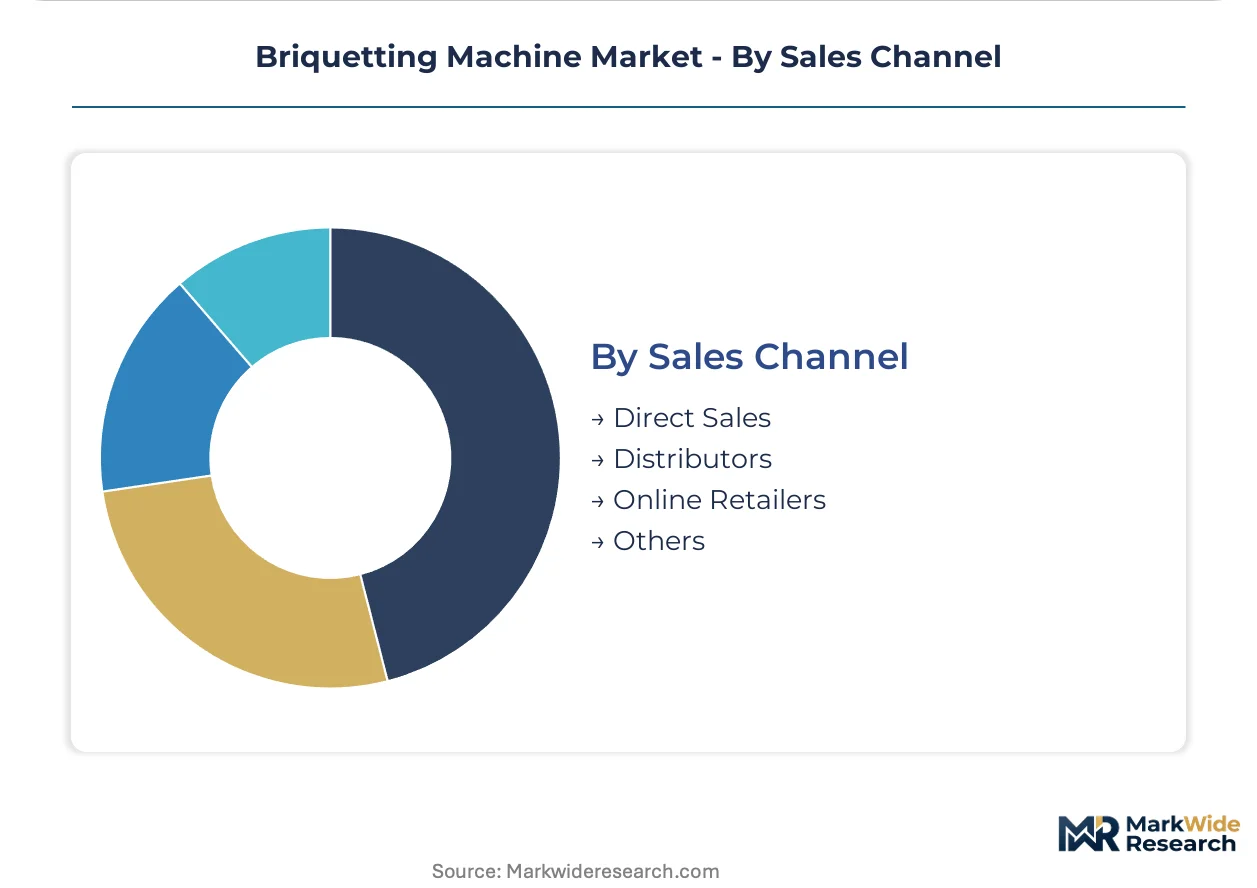
Sales Channel:
Channel selection reflects equipment complexity, service dependency, and buyer procurement maturity across end-user segments.
- Direct Sales:Large-capacity hydraulic press installations for steel mills and cement producers require factory-direct specification, commissioning, and long-term service contracting. WEIMA Maschinenbau GmbH leverages its German engineering base to dominate these high-throughput European installations.
- Distributors:Regional equipment dealers stock mechanical and screw press units for agricultural residue processors with faster replacement cycles and standardized specifications. RUF US, Inc. anchors North American demand through extensive spare parts logistics and field technician networks.
- Online Retailers:Entry-level equipment and replacement consumables reach small-scale operators through digital procurement platforms with limited technical support integration.
- Others:Equipment leasing and performance-based contracting models emerge for carbon credit monetization projects where verified emissions reduction frameworks enable incremental revenue capture.
Distributor networks capture the broadest volume base while direct sales channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese engineering houses concentrate hydraulic component supply for high-pressure briquetting systems, creating lead time dependencies that reshape procurement geography for steel mills and agricultural processors worldwide.
Germany
WEIMA Maschinenbau GmbH anchors European high-throughput industrial installations with factory-direct specification and commissioning services. The EU Waste Framework Directive pressures German operators to convert metalworking sludge into certified fuel briquettes rather than landfill disposal. Industrial clusters in North Rhine-Westphalia and Baden-Württemberg densify automotive and machinery sector residues for on-site boiler fuel substitution.
India
Screw press technology dominates agricultural residue processing across the Punjab-Haryana belt where rice husk and straw briquetting clusters serve proximate thermal power plants and brick kilns. India's BIS certification requirements for biomass briquette fuel standards create compliance barriers for uncertified equipment imports while favoring domestic manufacturers with established testing protocols. Uttar Pradesh cooperatives source equipment through domestic fabricators while contracting specialized firms for die refurbishment and remote troubleshooting.
China
Steel producers in Hebei and Shandong provinces retrofit existing presses with real-time carbon intensity tracking to demonstrate compliance with MEE enforcement of dual carbon goals. The regulatory mandate for coke-briquette blend ratios in blast furnace operations accelerates replacement cycles for pre-2020 hydraulic installations lacking integrated emissions monitoring. Yangtze River Delta equipment fabricators supply mid-capacity mechanical presses for wood waste and agricultural residue applications across Southeast Asian markets.
Brazil
Steel mills expand briquette consumption for blast furnace feedstock substitution to reduce coke dependency and lower per-ton emissions intensity in primary steelmaking. Carbon border adjustment mechanisms pressure industrial operators to densify process residues into standardized briquette feedstock rather than incur import tariffs on carbon-intensive alternatives. Foundry clusters in Minas Gerais and São Paulo states deploy hydraulic press configurations to process cast iron borings and stainless steel turnings with consistent structural integrity.
United States
RUF US, Inc. anchors North American demand through extensive spare parts logistics and field technician networks serving metalworking and biomass processing operators. EPA industrial waste regulations restrict landfill disposal of metalworking sludge, directly stimulating demand for briquetting systems that extract cutting fluids and densify solids. Midwest manufacturing corridors in Illinois, Michigan, and Ohio concentrate automotive and machinery sector residue processing for furnace feedstock recovery.
Briquetting Machine Market Competitive Environment
Precision-engineering specialists and cost-optimized fabricators split the market between premium hydraulic installations and standardized mechanical systems. German and Japanese engineering houses dominate high-pressure component supply while Indian and Chinese manufacturers compete on localized fabrication economics. Three archetypes define competitive positioning: European precision-engineering houses with factory-direct service models, Asian cost-optimized fabricators with distributor-heavy reach, and regional specialists with embedded agricultural residue expertise. Capacity expansion in Southeast Asian markets and strategic partnerships for carbon credit monetization frameworks represent the dominant competitive moves reshaping vendor relationships.
Among European precision-engineering houses, WEIMA Maschinenbau GmbH and Ruf Maschinenbau GmbH occupy positions defined by German engineering heritage and high-throughput industrial focus. Ecostan India Pvt. Ltd. exemplifies the cost-optimized fabricator archetype with localized production economics and service reach into Southeast Asian markets. These three anchors illustrate how geographic origin and organizational structure map to distinct competitive vectors without overlapping positioning.
| Leading Market Players |
|---|
| RUF US, Inc. |
| C.F. Nielsen |
| WEIMA Maschinenbau GmbH |
| Anyang Gemco Energy Machinery Co., Ltd. |
| K.R. Komarek Inc. |
| Ruf Maschinenbau GmbH |
| Ecostan India Pvt. Ltd. |
| Lehra Fuel Tech |
| Top Briquetting |
| Others |
Value Chain & Pricing Dynamics
The Hamburg-Mumbai maritime corridor shapes cost dynamics for hydraulic component shipments, concentrating pricing power among German and Japanese engineering houses while forcing tiered equipment economics across downstream buyer segments.
Pricing Analysis
After-sales revenue tiers spanning spare parts logistics, field technician networks, and extended service contracts drive lifetime value capture more than initial equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates hydraulic press configurations with integrated emissions monitoring from mechanical systems for agricultural residue processing. Cost compression in standard-tier mechanical presses is intensifying because Indian and Chinese fabricators compete aggressively on localized production economics. Agricultural cooperatives in Uttar Pradesh exhibit the highest price sensitivity, while steel mills in Turkey and Brazil demonstrate lowest sensitivity due to carbon border compliance mandates.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk planning for high-pressure hydraulic pumps and precision cylinders. Component manufacturing concentrates in Germany, Japan, and China, with raw material dependencies spanning specialty steel alloys, precision-machined hydraulic valves, and hardened extrusion barrels for screw press applications. Single-source vulnerability persists for sub-15% moisture feedstock preprocessing systems. Distribution runs through factory-direct channels for steel mill installations and regional distributor networks for agricultural residue processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a substitution defense against direct reduced iron and pelletized feedstock alternatives that threaten briquette demand in blast furnace operations.
For Market Incumbents: Build switching-cost moats through integrated IoT-enabled predictive maintenance platforms that lock steel mills into proprietary service ecosystems. Anchor capacity in Brazil and India where carbon border adjustment mechanisms are tightening fastest. Defend against Chinese mid-cap fabricators by securing BIS certification laboratory relationships that delay competitor market entry.
For New Entrants and Emerging Players: Build out remote monitoring and die refurbishment service capabilities for India's cooperative-owned agricultural residue processing clusters, the most penetrable segment given unbundled procurement behavior. Target Indonesian palm oil residue valorization in Sumatra and Kalimantan where feedstock supply exceeds localized processing capacity. Pursue carbon credit monetization frameworks as the primary go-to-market angle for utility-sector cofiring applications.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial equipment parents seeking to divest non-core briquetting divisions amid energy transition portfolio rebalancing. Long-term viability hinges on regulatory durability of landfill diversion mandates and carbon border mechanisms rather than commodity fuel pricing cycles. Monitor MEE enforcement intensity in Hebei and Shandong provinces as the signal for replacement cycle acceleration in pre-2020 hydraulic installations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydraulic Component Supply | German engineering houses reduce lead time vulnerability for high-pressure pump sourcing. |
| Carbon Credit Monetization Partnership | Verified emissions reduction frameworks enable incremental revenue capture from coal displacement. |
| Digital Twin Platform Deployment | South Korean steel mills minimize trial batches when switching between cast iron and stainless feedstock. |
| BIS Certification Laboratory Investment | Domestic Indian manufacturers accelerate market entry timelines versus uncertified imports. |
| Remote Monitoring Service Unbundling | Uttar Pradesh cooperatives separate capital acquisition from specialized maintenance contracting. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with maintenance directors at steel mills, plant engineers in agricultural residue processing clusters, OEM procurement teams specifying hydraulic press configurations, and aftermarket service heads managing die refurbishment networks. Secondary validation drew from EPA industrial waste filings, EU Waste Framework Directive implementation reports, India's BIS certification registries, and China's MEE dual carbon compliance disclosures. Bottom-up equipment installation tracking and top-down fuel substitution demand modeling were triangulated to anchor volume estimates.
Calibration against historical replacement cycles and regulatory implementation timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include press technology type, feedstock material category, end-user sector, and regional regulatory cluster. CAGRs were derived from installed base growth rates, equipment replacement velocity, and feedstock availability projections. Industry-specific forecast inputs encompassed steel mill coke-briquette blend ratio mandates and agricultural residue moisture content variability patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese mid-cap fabricators or accelerated EU carbon border phase-in would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Canada Metal Fabrication Equipment Market
Construction Equipment and Machinery
Australia Construction Machinery Market
Construction Equipment and Machinery
Wire Mesh Welding Machines Market
Construction Equipment and Machinery
Die Casting Machinery Market
Construction Equipment and Machinery
Milling Machine Market
Construction Equipment and Machinery
GCC Construction Machinery Rental Market
Construction Equipment and Machinery
Brick Making Machines Market
Construction Equipment and Machinery
Aluminum Die Casting Machinery Market
Construction Equipment and Machinery
Metal Fabrication Equipment Market
Construction Equipment and Machinery
Crane Motors Market
Construction Equipment and Machinery
Industrial Machinery Market
Construction Equipment and Machinery
Cold Forging Machines Market
Construction Equipment and Machinery
Spraying and Plastering Machine Market
Construction Equipment and Machinery
Universal Milling Machine Market
Construction Equipment and Machinery
Hydraulic Shop Crane Market
Construction Equipment and Machinery
Industrial Dryers Market