
 Chip Conveyors Market | 2026-2036
Chip Conveyors Market Size, Share, and Industry Trends Forecast 2026-2036
Chip Conveyors Market Insights
Preventive maintenance contracts and remote monitoring subscriptions is expanding the revenue model beyond unit sales. Mayfran International leverages its global service network to lock in multi-year aftermarket agreements. Hennig Inc. sustains dominance in North American machine tool integrations through captive repair infrastructure. LNS America Inc. specializes in compact conveyor systems for Swiss-type lathes, occupying a defensible niche in high-mix, low-volume shops.
Chip conveyors are material handling systems engineered to evacuate metal chips, swarf, and cutting debris from machine tools, typically employing steel hinge belts, magnetic drums, or auger screws rated for continuous loads exceeding 500 kg per hour. These systems integrate with coolant filtration loops to preserve thermal stability and surface finish in precision machining operations. Magnetic chip conveyors lead product type demand where ferrous materials dominate, while belt conveyors capture the broadest cross-material applicability across titanium and aluminum alloys. Electric drive technology is displacing hydraulic alternatives in new installations, driven by energy efficiency mandates and simplified maintenance protocols.
OSHA enforces machine guarding standards that directly shape conveyor enclosure and interlock specifications, while EPA regulations on metalworking fluid management force chip-handling systems to incorporate sealed coolant recovery. ISO 9001 quality management and CE marking under EU machinery directives create divergent compliance pathways for suppliers serving multiple geographies. Stakeholders must weigh regional certification burdens against the margin compression of standardized global platforms.
Market Dynamics
Automotive OEMs are consolidating machining operations into lights-out facilities, forcing chip conveyor suppliers to engineer systems capable of 168-hour continuous operation without manual intervention.
Growth Catalysts
- OSHA Machine Guarding Standards:U.S. workplace safety mandates require enclosed chip handling with interlocked access panels, compelling shops to replace open trough conveyors with sealed systems.
- Titanium Aerospace Machining:Defense contractors and commercial airframers are expanding five-axis titanium work, generating high-volume chip loads that demand heavy-duty steel hinge belt configurations rated above 750 kg per hour.
- Germany's Precision Corridor:Stuttgart-to-Dresden manufacturing density creates concentrated demand for coolant-integrated chip evacuation systems in high-mix, low-volume toolrooms.
Market Restraints
- Neodymium Magnet Supply Concentration:Chinese rare earth processing dominance exposes magnetic conveyor manufacturers to input cost volatility and export restriction risk.
- CE Marking Compliance Burden:EU Machinery Directive conformity assessment adds 8-14 week certification timelines, compressing margins for standardized platform strategies.
- Compact CNC Footprint Constraints:Swiss-type lathe and micro-machining center designs limit available floor space, restricting auger conveyor diameter and chip storage capacity.
Strategic Opportunities
- Indian Defense Production:Indigenization mandates under the Make in India initiative are localizing aerospace machining, creating virgin demand for coolant-compatible chip handling in Bangalore and Hyderabad clusters.
- Predictive Maintenance Convergence:Vibration sensors and motor current signature analysis are converging with cloud-based fleet management to enable condition-based service scheduling.
- EPA Metalworking Fluid Rules:Stricter disposal regulations are creating aftermarket pull for sealed coolant recovery modules retrofittable to legacy conveyor installations.
Industry Challenges
- Mechatronics Technician Scarcity:Integration of servo drives, PLCs, and filtration loops demands cross-functional maintenance skills that vocational pipelines are not producing at replacement rates.
- Legacy CNC Communication Protocols:Proprietary machine tool interfaces complicate chip conveyor automation integration, requiring custom gateway development for each OEM platform.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chip Conveyors Market |
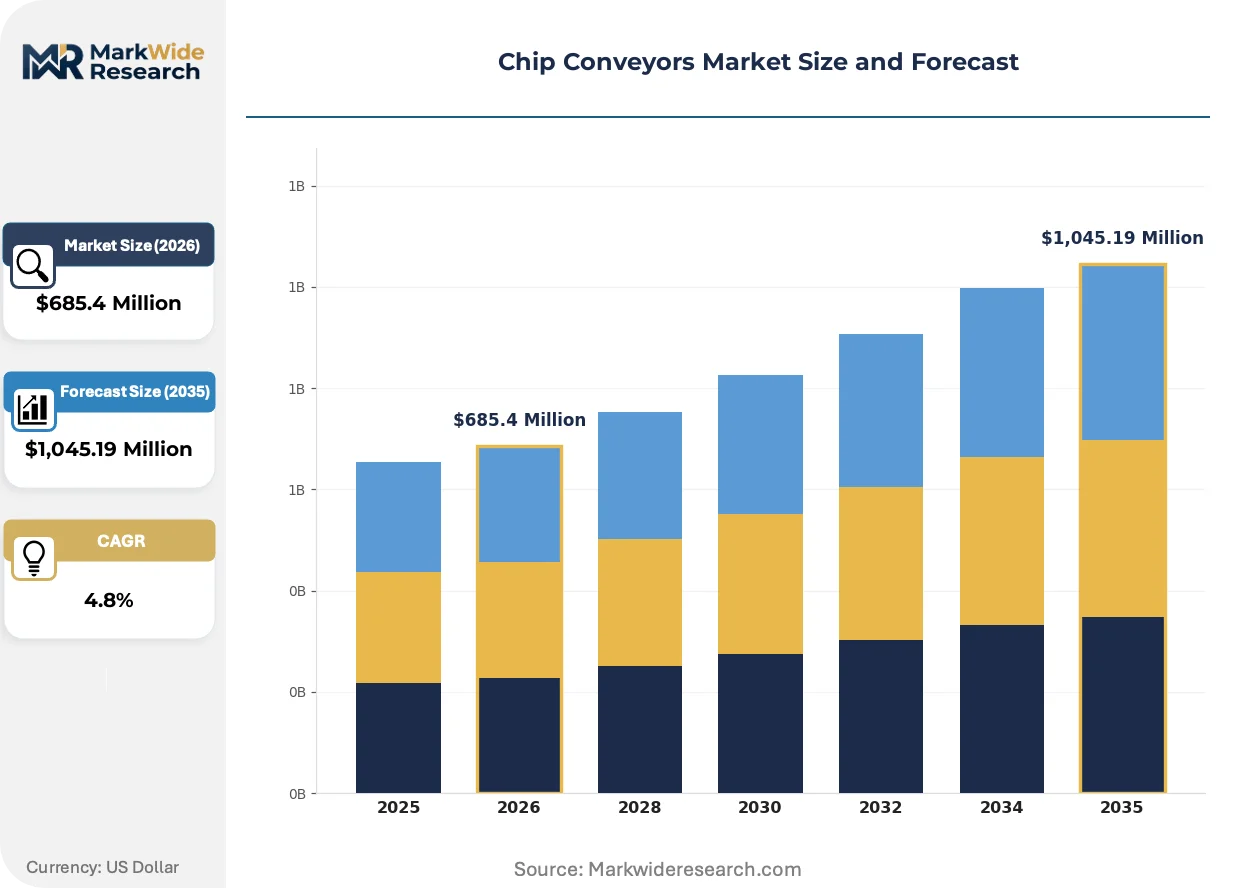
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Chip Conveyor, Roller Conveyor, Belt Conveyor, Screw Conveyor Application: Machining Centers, Lathes, Grinding Machines, Tooling End User: Aerospace, Automotive, Manufacturing, Metalworking Technology: Hydraulic, Pneumatic, Electric, Mechanical |
| Companies Covered | Mayfran International, Hennig Inc., LNS America Inc., Jorgensen Conveyors, Inc., PRAB Inc., Haas Automation, Inc., Eriez Manufacturing Co., Miven Mayfran Conveyors Pvt. Ltd., Nederman Holding AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chip Conveyors Market Trends and Innovations
Electrification and digital thread integration are restructuring how chip evacuation systems are specified, procured, and maintained across precision manufacturing sectors.
Permanent magnet synchronous motors are overtaking hydraulic power units in new installations. These electric drives eliminate fluid leak paths and reduce energy draw by 30-40 percent in continuous-duty cycles. Tier-one automotive stampers and powertrain machinists are specifying all-electric chip handling as standard for greenfield plants, compressing the installed base of legacy hydraulic systems toward obsolescence.
EPA effluent guidelines for metalworking fluids are tightening discharge limits on tramp oil and suspended solids. Machine shops in Michigan and Ohio are responding by specifying chip conveyors with integrated coolant coalescers and centrifugal separators. The regulatory pressure is most acute in high-volume aluminum automotive component manufacturing, where coolant turnover rates directly affect compliance costs.
Service contracting is displacing transactional spare parts purchasing in aftermarket relationships. German machine tool builders are bundling five-year chip conveyor maintenance into turnkey project financing, unbundling the traditional capital equipment sale from operational support. This shift is most visible in the Stuttgart automotive supplier ecosystem, where total cost of ownership metrics dominate procurement committee evaluations.
Chip Conveyors Market Segmentation
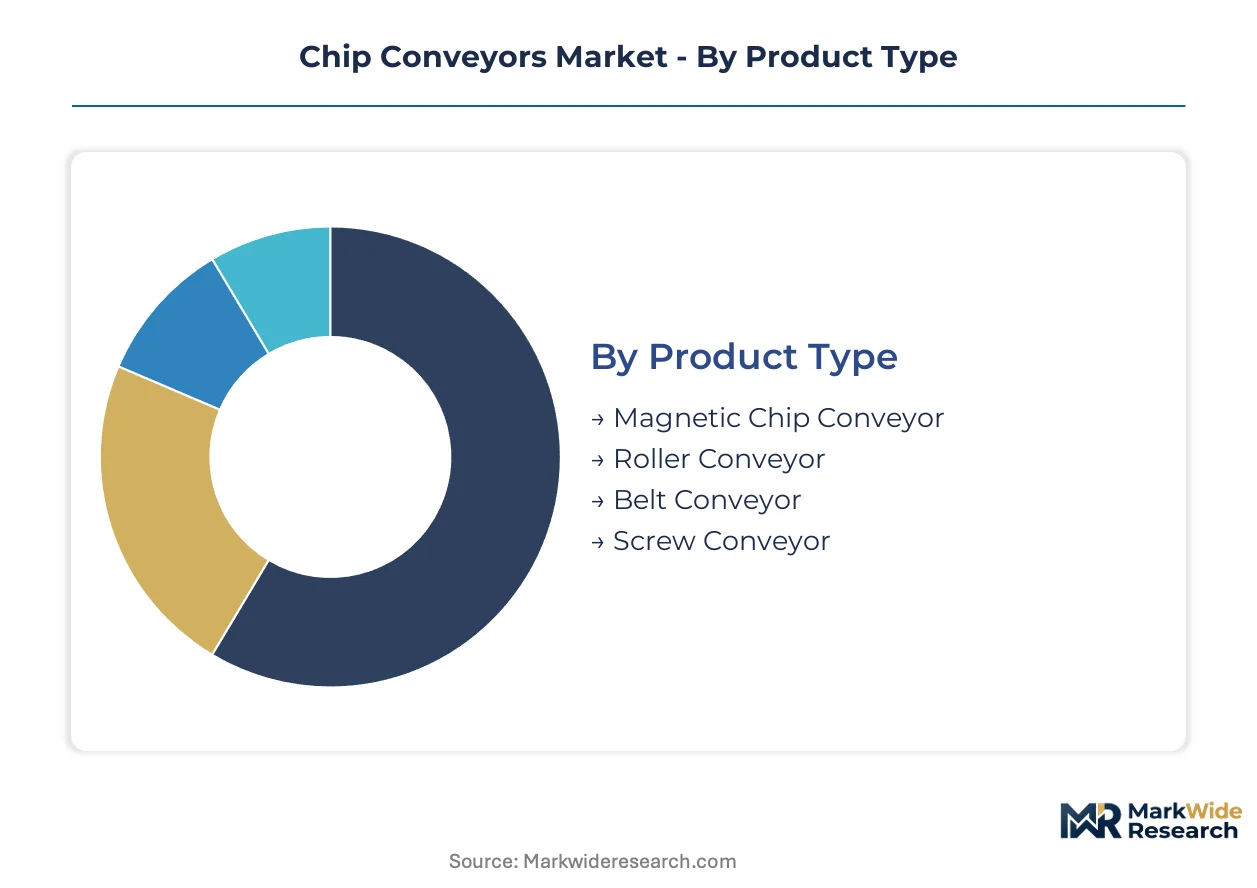
Chip conveyor procurement patterns diverge sharply across machine tool configurations and operational environments. Upgrade cycles and replacement demand vary by segment, creating distinct revenue windows for suppliers targeting specific installation bases.
Product Type:
Replacement cycles accelerate where coolant compatibility and magnetic efficiency determine operational uptime.
- Magnetic Chip Conveyor:Permanent magnet drums extract ferrous swarf from cutting zones without mechanical contact, eliminating belt wear in cast iron and steel machining. Stuttgart automotive suppliers specify these for uninterrupted lights-out production. Demand concentrates in Germany's precision corridor where five-axis titanium work generates high ferrous chip loads.
- Belt Conveyor:Steel hinge belts rated above 750 kg per hour handle aluminum and titanium alloys across mixed-material shops. U.S. automotive OEMs in Michigan and Ohio deploy these for coolant-integrated chip evacuation under EPA metalworking fluid rules. Belt configurations capture broadest cross-material applicability.
- Roller Conveyor:Heavy-duty roller chains transport bulky cast iron chips from roughing operations.
- Screw Conveyor:Auger screws fit compact Swiss-type lathe footprints where floor space constraints restrict diameter and chip storage capacity.
Belt Conveyor sits at the top of the volume ranking, with Magnetic Chip Conveyor climbing the fastest.
Application:
Cost tier separation emerges between high-volume production environments and precision toolroom installations.
- Machining Centers:Vertical and horizontal machining centers demand continuous chip evacuation systems rated for 168-hour operation. Tier-one automotive stampers bundle five-year maintenance contracts into turnkey project financing. These installations represent the premium tier of conveyor specification.
- Lathes:CNC turning centers generate stringy chip formations requiring specialized conveyor geometries. Compact Swiss-type designs in Bangalore and Hyderabad defense clusters drive demand for space-constrained auger configurations. Lathe integrations span mid-market to economy pricing tiers.
- Grinding Machines:Fine abrasive sludge demands filtration-integrated chip handling.
- Tooling:High-mix, low-volume toolrooms prioritize flexibility over throughput specifications.
Machining Centers command the highest average contract value, with Lathe applications expanding most quickly in emerging defense production clusters.
End User:
Customer type determines service intensity and aftermarket attachment rates.
- Automotive:OEM consolidation into lights-out facilities forces 168-hour continuous operation specifications. Greenfield plants in Michigan and Ohio specify all-electric chip handling as standard, eliminating hydraulic alternatives. Predictive maintenance subscriptions lock in multi-year aftermarket revenue.
- Aerospace:Defense contractors and commercial airframers expand five-axis titanium work, generating chip loads above 750 kg per hour. Indian indigenization mandates under Make in India localize machining demand in Bangalore and Hyderabad. Sealed coolant recovery modules address EPA disposal regulations.
- Metalworking:Job shops and contract manufacturers span fragmented demand across equipment vintages.
- Manufacturing:General industrial applications follow capital equipment replacement cycles.
Automotive end users generate the highest service contract attachment rates, while Aerospace shows the steepest expansion trajectory in emerging production clusters.
Technology:
Supply concentration in drive systems creates divergent margin profiles across installation bases.
- Electric:Permanent magnet synchronous motors displace hydraulic power units in new installations, reducing energy draw by 30-40 percent in continuous-duty cycles. Tier-one automotive stampers specify all-electric systems exclusively for greenfield plants. Simplified maintenance protocols accelerate replacement of legacy hydraulic bases.
- Hydraulic:Installed base obsolescence accelerates as energy efficiency mandates tighten. Fluid leak paths and maintenance complexity drive upgrade decisions. Remaining demand concentrates in retrofit-averse legacy facilities.
- Pneumatic:Compressed air systems occupy niche applications in explosive environments.
- Mechanical:Direct-drive configurations persist in cost-sensitive installations.
Electric technology dominates new specification, with Hydraulic retaining residual share in replacement-averse legacy infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates precision machining demand while the United States drives regulatory compliance upgrades, creating divergent specification patterns across major installation bases.
United States
Automotive OEMs in Michigan and Ohio consolidate machining into lights-out facilities requiring 168-hour continuous operation. EPA metalworking fluid discharge rules tighten coolant recovery specifications. Detroit-area stamping plants specify all-electric chip handling exclusively for greenfield installations.
Germany
Stuttgart-to-Dresden manufacturing density generates concentrated demand for coolant-integrated systems in high-mix toolrooms. CE marking under EU Machinery Directive adds certification timelines for standardized platforms. Bavarian automotive suppliers bundle five-year maintenance contracts into turnkey project financing.
China
Rare earth processing dominance exposes magnetic conveyor manufacturers to input cost volatility and export restriction risk. National dual carbon goals accelerate electric drive adoption in new installations. Yangtze River Delta machining clusters face pressure to upgrade sealed coolant recovery systems.
India
Defense indigenization mandates under Make in India localize aerospace machining demand. BIS quality standards create compliance pathways for imported equipment. Bangalore and Hyderabad production clusters drive virgin demand for compact auger configurations in Swiss-type lathe integrations.
Japan
METI energy efficiency guidelines displace hydraulic power units in precision machining facilities. JIS standards govern conveyor safety specifications for domestic machine tool builders. Nagoya-area automotive component manufacturers specify permanent magnet synchronous motors for continuous-duty cycles.
Chip Conveyors Market Competitive Landscape
Top-tier vendors anchor premium-tier service contracting, while mid-market fabricators compete on equipment specification flexibility. The vendor base spans multi-national service networks, regional machine tool integrators, and specialized compact system designers. Strategic archetypes include full-service aftermarket providers, captive repair infrastructure operators, and niche Swiss-type specialists. Competitive moves center on multi-year maintenance agreement expansion and predictive maintenance technology licensing.
Within the global service network tier, Mayfran International and Hennig Inc. exemplify contrasting geographic anchoring strategies. Mayfran International leverages international footprint breadth to lock in aftermarket agreements across dispersed installation bases. Hennig Inc. sustains North American market presence through integrated repair infrastructure. LNS America Inc. occupies a defensible position among compact conveyor specialists serving high-mix, low-volume machining environments.
| Leading Market Players |
|---|
| Mayfran International |
| Hennig Inc. |
| LNS America Inc. |
| Jorgensen Conveyors, Inc. |
| PRAB Inc. |
| Haas Automation, Inc. |
| Eriez Manufacturing Co. |
| Miven Mayfran Conveyors Pvt. Ltd. |
| Nederman Holding AB |
| Others |
Pricing and Supply Chain Analysis
Neodymium magnet feedstock from Chinese rare earth processors flows through three pricing tiers: premium-grade sealed systems for Stuttgart automotive suppliers, mid-tier belt configurations for Michigan toolrooms, and economy auger units for Bangalore defense clusters. Steel hinge belt specifications and permanent magnet synchronous motor assemblies determine final equipment positioning across these tiers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta machining clusters are reshaping price floors for magnetic conveyor subassemblies. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked German OEM integrations from EPA-compliant U.S. automotive stampers and BIS-certified Indian defense installations. Cost compression in standard-tier belt systems intensifies because electric drive component sourcing faces rare earth volatility. Job shops and contract manufacturers exhibit highest price sensitivity, while tier-one automotive OEMs prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Detroit-area stamping plants and Stuttgart automotive suppliers, while regional distributors serve fragmented metalworking job shops. Manufacturing concentrates in Germany, China, and the United States for precision-machined conveyor housings and drive assemblies. Supply chains draw from neodymium magnet processing, cold-rolled steel production, and permanent magnet motor fabrication. Single-source vulnerability in Chinese rare earth processing exposes magnetic conveyor manufacturers to export restriction risk. Distribution runs through machine tool OEM bundling agreements and independent aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EPA metalworking fluid compliance costs in Michigan and Ohio create pricing premiums that Indian defense clusters avoid through BIS certification pathways, enabling margin capture for suppliers with dual-qualification capability.
For Market Incumbents: Cement multi-year aftermarket lock-in through predictive maintenance subscriptions and captive repair infrastructure. Defend against compact Swiss-type specialists by acquiring regional service networks in Bangalore and Hyderabad. Invest in CE marking pre-certification to compress EU market entry timelines for standardized platforms. For New Entrants and Emerging Players: Launch via direct OEM bundling partnerships targeting Indian defense production clusters under Make in India localization mandates. Exploit white-space in coolant-integrated retrofit modules for legacy hydraulic installations. Prioritize compact auger configurations for space-constrained Swiss-type lathe integrations where Hennig and LNS America hold limited presence. For Investors and Strategic Acquirers: Consolidation pressure builds where mechatronics technician scarcity fragments aftermarket service quality and drives acquisition of captive repair infrastructure. Long-term viability centers on electric drive technology displacement of hydraulic bases and predictive maintenance platform licensing. Target regional machine tool integrators with established CE marking pathways and Indian BIS certification. Monitor neodymium export license issuance patterns from Chinese regulators as inflection indicator for magnetic conveyor input cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Aftermarket Service Network Expansion | Multi-year maintenance contracts with Stuttgart automotive suppliers lock in recurring revenue streams. |
| Electric Drive Technology Transition | Permanent magnet synchronous motor adoption reduces energy draw for Michigan greenfield installations. |
| Indian Defense Cluster Localization | Bangalore and Hyderabad production mandates under Make in India create virgin demand capture. |
| Coolant Recovery Module Retrofitting | EPA metalworking fluid rules pull sealed system upgrades across legacy Ohio installations. |
| Predictive Maintenance Platform Licensing | Vibration sensor and motor current signature analysis enable condition-based service scheduling. |
Research Methodology
Multiple input streams — primary interviews with maintenance directors and plant engineers, secondary validation through customs records and machine tool OEM procurement disclosures, and technical specification analysis — were reconciled to construct segment-level demand estimates. Stakeholder roles included aftermarket service heads at multi-national conveyor suppliers, OEM procurement teams for tier-one automotive stampers, and facility managers at precision machining job shops. Secondary sources encompassed EPA enforcement action databases, EU Machinery Directive conformity assessment registries, and BIS certification filings. Bottom-up equipment installation counts were triangulated against top-down metalworking fluid management expenditure flows.
Historical shipment patterns were cross-referenced against panel input from machine tool builders and defense production coordinators to anchor projection assumptions. Segmentation dimensions modeled include product type, application environment, end-user industry, and technology architecture across the projection horizon. CAGRs were derived from equipment replacement cycle analysis and regulatory compliance upgrade timelines. Industry-specific forecast inputs incorporated OSHA machine guarding standard enforcement intensity and Indian defense indigenization mandate implementation pace.
Forecast precision tightens around the base case; tail outcomes carry wider variance under neodymium export restriction scenarios and CE marking timeline delays. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Chip Mounter Market
Semiconductor Equipment
Plasma Etching Equipment Market
Semiconductor Equipment
Laser Micro Perforation Equipment Market
Semiconductor Equipment
Semiconductor Wafer Cleaning Equipment Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
Vacuum & Low Pressure Diffusion Furnace Market
Semiconductor Equipment
Global Wafer Processing and Assembly Equipment Market
Semiconductor Equipment
Electrostatic Chucks Market
Semiconductor Equipment
Remote Plasma Source Market
Semiconductor Equipment
Ion Milling System Market
Semiconductor Equipment
Plasma Etch System Market
Semiconductor Equipment
Global Semiconductor Wafer Polishing and Grinding Equipment Market
Semiconductor Equipment
Global Semiconductor Stepper Systems Market
Semiconductor Equipment
Lithographic Photomasks Market
Semiconductor Equipment
Die Bonder Equipment Market
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market