
 Tea Processing Machine Market | 2026-2036
Tea Processing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Tea Processing Machine Market Analytics
EU Green Deal compliance is decoupling energy efficiency from optional premium positioning and making it a baseline cost-of-entry requirement for equipment sold into European tea importing nations. Bühler Group leverages its thermal engineering heritage to anchor retrofit demand across South Asian estates. GEA Group competes on dairy-crossover technology adapted for oxidation control in large-scale fermentation lines. Marshall Fowler Engineers sustains regional dominance across East African markets through localized fabrication networks.
Tea processing machines mechanically transform fresh Camellia sinensis leaves through controlled withering, rolling, oxidation, and drying sequences, with drum rotation speeds typically ranging from 25 to 55 RPM and drying air temperatures maintained between 90°C and 120°C to preserve polyphenol integrity and achieve moisture content below 5%. Withering machines retain the largest installed base across mature tea-growing regions, while fully automated continuous processing lines capture the fastest expansion as labor costs rise in India and Vietnam. Drying machines concentrate the deepest margin pools due to burner efficiency regulations and fuel-switching requirements.
India's BIS energy labeling standards, China's GB machinery safety codes, and Kenya's Tea Board quality certification protocols collectively reshape equipment procurement criteria, forcing manufacturers to certify thermal efficiency and traceability systems before market access. ISO food safety management standards further filter supplier qualification for exporter-facing estates. Stakeholders must weigh automation capex against regulatory compliance timelines and fuel transition risks when planning replacement cycles.
Market Dynamics
Estate consolidation across Kenya's Rift Valley and Vietnam's Central Highlands is compressing replacement cycles for continuous processing systems while simultaneously raising minimum efficiency thresholds for new equipment procurement.
Growth Catalysts
- India's PLI scheme:Capital subsidies for food processing machinery reduce upgrade barriers for mid-sized estates in Assam and West Bengal, accelerating automated line adoption.
- EU Green Deal thermal standards:Importing nations now mandate burner efficiency certifications, creating retrofit demand for existing South Asian and East African installations.
- Specialty tea export protocols:Japanese and South Korean premium brands require traceability-integrated processing lines, pulling advanced oxidation control systems into commercial production.
Market Restraints
- Natural gas price volatility:Drying machine operating costs fluctuate with LNG spot markets, squeezing margin pools for fuel-dependent estates in Sri Lanka and Indonesia.
- Fabrication network concentration:Localized spare parts production clusters in Kenya and India create supply vulnerability when currency instability disrupts component import flows.
- Skilled technician scarcity:Automated line maintenance requires mechatronics competencies that training institutes in Vietnam and Bangladesh have not yet scaled to meet replacement demand.
Strategic Opportunities
- Rwanda's emerging specialty sector:Smallholder cooperative consolidation creates first-mover positioning for compact continuous systems serving orthodox tea export channels.
- Biomass burner convergence:Tea waste gasification technology paired with IoT combustion control opens fuel-switching revenue streams for estates facing carbon border adjustment exposure.
- Remote diagnostics channels:Predictive maintenance platforms unbundle service contracts from equipment sales, capturing recurring revenue from dispersed African and South Asian estate networks.
Industry Challenges
- Multi-standard certification timelines:India's BIS energy labeling, China's GB machinery safety codes, and Kenya's Tea Board quality protocols require parallel compliance tracks that extend pre-market validation periods.
- Legacy drum dryer integration:New oxidation control modules must interface with 1980s-era mechanical systems common across older Assam estates, complicating automation retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tea Processing Machine Market |
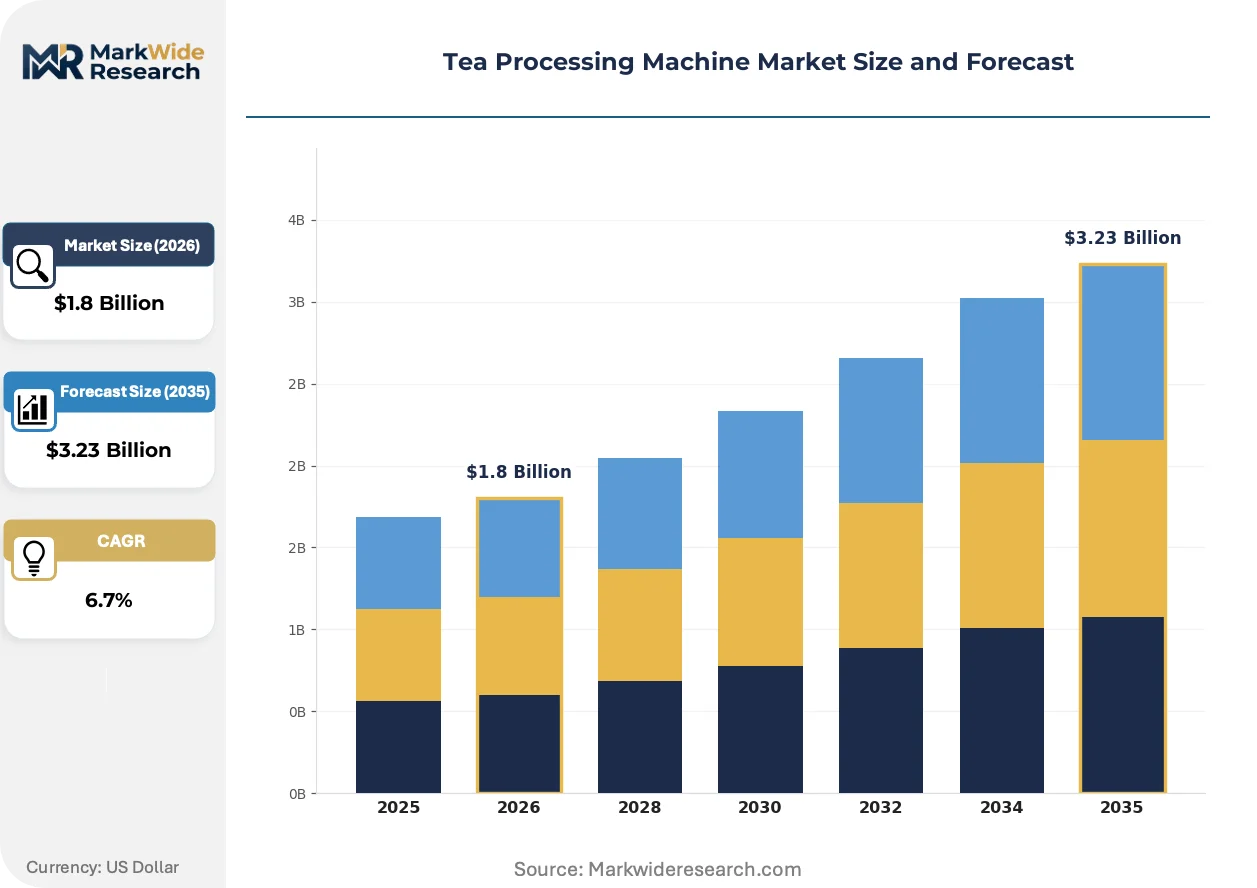
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Withering Machines, Rolling Machines, Fermentation Equipment, Drying Machines End User: Tea Estates, Large Scale Producers, Small Scale Producers, Exporters Technology: Conventional, Semi-Automatic, Fully Automated, Continuous Processing Capacity: Small Scale, Medium Scale, Large Scale, High Volume |
| Companies Covered | Bühler Group, GEA Group, Kawasaki Kiko, Steelsworth, Marshall Fowler Engineers, T & I Global Ltd., G.G. Dandekar Machine Works Ltd, Quanzhou Deli Agroforestrial Machinery Co., Ltd., Hunan Jinfeng Tea Machinery Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tea Processing Machine Market Evolving Landscape
Digital thread integration across withering-through-packaging sequences is displacing siloed machine-level control, while thermal engineering advances and procurement model evolution reshape competitive positioning.
Continuous processing line architecture is modularizing around standardized oxidation drum units that estates configure to capacity. Large plantation groups in Kenya and Vietnam now specify plug-and-expand layouts that defer capital commitment until yield forecasts firm. This flexibility is compressing the traditional distinction between estate-scale and factory-scale equipment tiers.
EU F-Gas Regulation phase-down schedules are forcing refrigerant-dependent withering systems toward CO2 heat pump alternatives. Equipment suppliers serving European import markets must now certify thermal efficiency under updated Ecodesign requirements. South Asian manufacturers are responding by partnering with Italian compressor specialists to fast-track compliant system validation.
After-sales service unbundling is accelerating as estate procurement teams separate maintenance contracts from initial equipment financing. Third-party technical service networks in Tamil Nadu and Kerala now compete directly with original manufacturers for multi-year oxidation line support agreements. This shift is most visible among Indian mid-cap estates seeking to reduce total cost of ownership across 15-year equipment lifecycles.
Tea Processing Machine Market Segmentation
Equipment procurement patterns across tea-growing regions diverge sharply based on estate scale, fuel access, and export certification requirements. Capital deployment decisions hinge on matching processing technology to leaf throughput volumes and labor cost structures.
Product Type:
Capital intensity varies dramatically across processing stages, with thermal equipment demanding the heaviest upfront investment while mechanical systems offer lower entry thresholds.
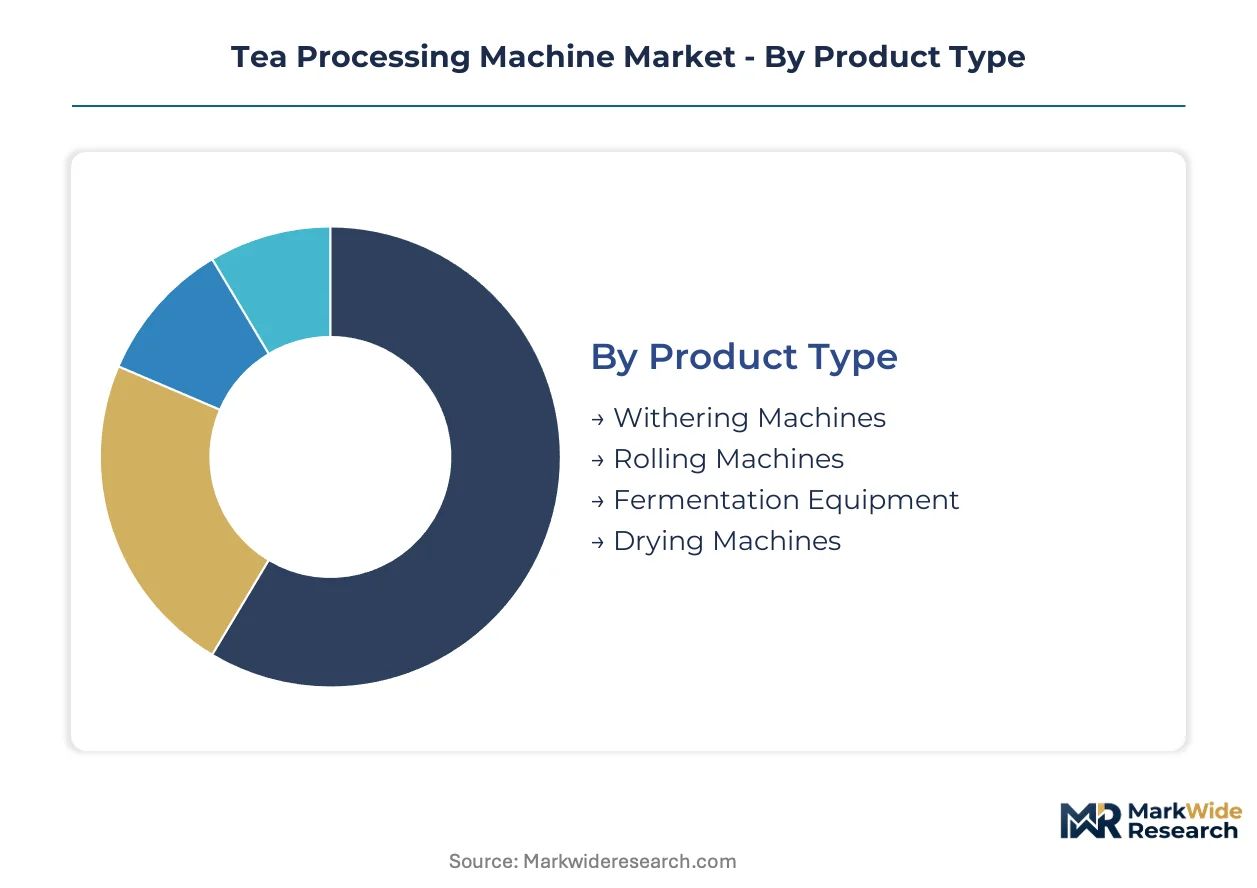
- Withering Machines:These units reduce leaf moisture content from 75% to 55-70% through controlled air circulation across perforated troughs or drum systems. Demand concentrates most visibly across Assam and West Bengal estates upgrading from open-air withering to enclosed climate-controlled systems that meet ISO food safety standards for export certification. India's BIS energy labeling standards now mandate thermal efficiency disclosures for new installations.
- Drying Machines:Fired systems utilizing gas, biomass, or electric heat sources reduce finished tea moisture below 5% while preserving polyphenol integrity through precise temperature control between 90°C and 120°C. Kenyan Rift Valley estate consolidation is driving replacement cycles for high-volume continuous dryers as consolidated operations seek burner efficiency certifications required under EU Green Deal thermal standards for importing nations.
- Rolling Machines:Rotating drums at 25-55 RPM rupture leaf cells to release enzymes for oxidation, with pressure-adjustable rollers accommodating orthodox and CTC processing requirements.
- Fermentation Equipment:Humidity-controlled chambers or conveyor systems manage enzymatic oxidation duration, with advanced units integrating IoT sensors for real-time polyphenol monitoring.
Withering machines absorb the bulk of installed capacity across mature tea-growing regions; drying machines are expanding most quickly as fuel-switching regulations and carbon border adjustment exposure accelerate equipment replacement.
End User:
Customer scale determines automation depth, with large plantation groups specifying integrated continuous lines while smallholder cooperatives prioritize modular, expandable configurations.
- Tea Estates:Vertically integrated operations from cultivation through packaging require comprehensive processing lines with traceability-integrated oxidation control systems. Japanese and South Korean specialty tea brands are expanding automated processing lines within estate-owned facilities to meet premium export protocols demanding batch-level documentation.
- Large Scale Producers:Multi-estate processing companies serving commodity export markets prioritize high-volume continuous systems with standardized maintenance protocols to minimize technician downtime.
- Small Scale Producers:Cooperative-owned micro-factories in Rwanda's emerging specialty sector favor compact continuous systems with plug-and-expand layouts that defer capital commitment until yield forecasts firm.
- Exporters:Third-party processors serving international traders require flexible equipment configurations accommodating multiple tea grades and origin certifications.
Tea estates command the deepest equipment investment per hectare; small scale producers are climbing the fastest as cooperative consolidation creates first-mover positioning for compact system suppliers.
Technology:
Automation sophistication correlates directly with labor cost trajectories and regulatory compliance burdens across origin markets.
- Fully Automated:Integrated withering-through-packaging sequences with digital thread architecture and predictive maintenance platforms capture recurring revenue from dispersed estate networks. India's PLI scheme for food processing machinery is lowering capital barriers for mid-sized estates in Assam and West Bengal accelerating automated line adoption.
- Continuous Processing:Modular architecture around standardized oxidation drum units allows estates to configure capacity with plug-and-expand layouts. Vietnam's Central Highlands plantation groups now specify these systems to compress replacement cycles while raising minimum efficiency thresholds.
- Semi-Automatic:Hybrid configurations retaining manual loading and quality inspection points with automated temperature and humidity control reduce technician competency requirements.
- Conventional:Standalone mechanical systems with manual process intervention persist across older Sri Lankan and Indonesian estates facing natural gas price volatility squeezing margin pools for fuel-dependent operations.
Continuous processing systems dominate new capacity additions; fully automated lines are gaining share fastest as mechatronics training institutes in Vietnam and Bangladesh struggle to scale technician output to meet replacement demand.
Capacity:
Throughput specifications align with estate consolidation patterns and regional leaf availability concentration.
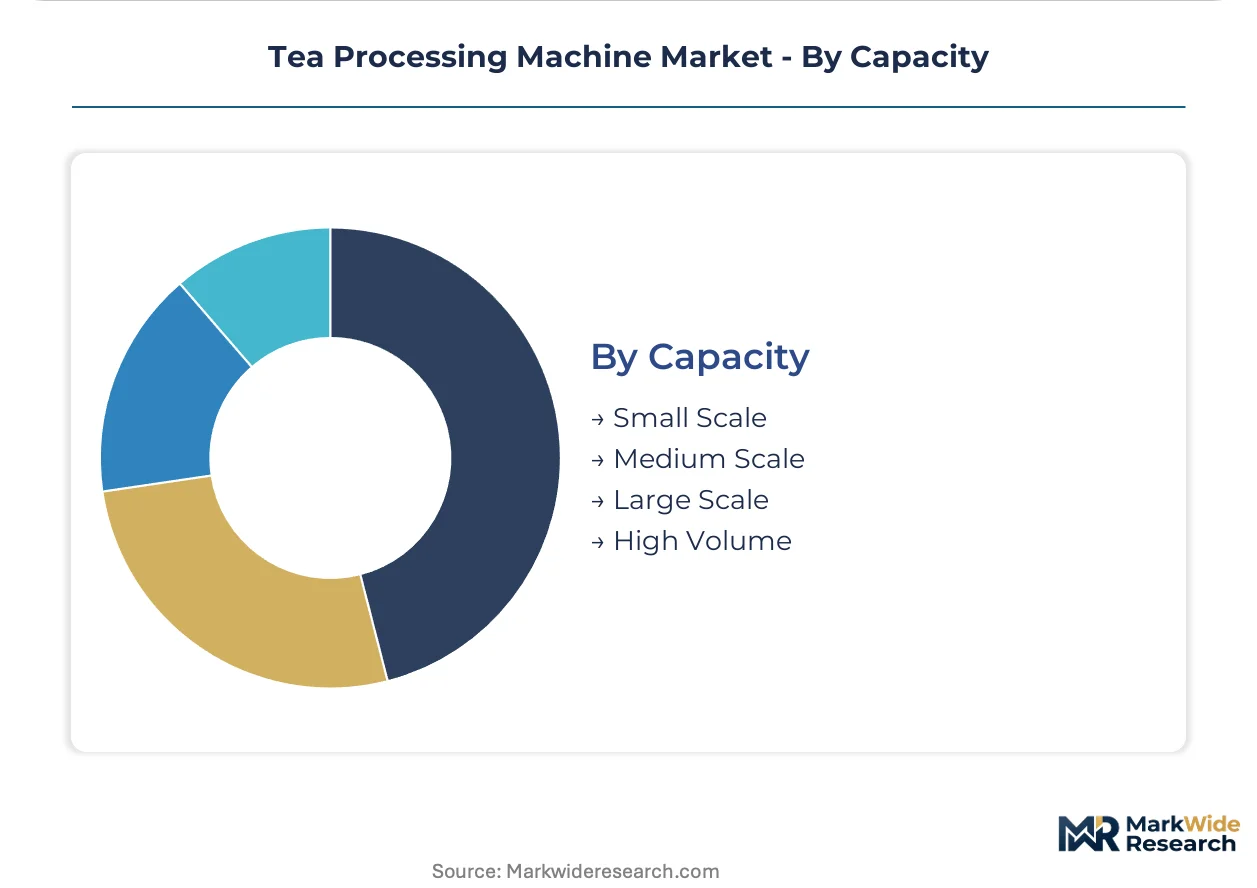
- High Volume:Systems processing over 10,000 kg of fresh leaf per hour serve consolidated Kenyan Rift Valley operations and Vietnamese plantation groups. EU F-Gas Regulation phase-down schedules are forcing refrigerant-dependent withering components toward CO2 heat pump alternatives in these large installations.
- Large Scale:Equipment handling 5,000-10,000 kg hourly matches mid-tier Indian estates upgrading through PLI scheme subsidies while navigating multi-standard certification timelines across BIS, GB, and Tea Board protocols.
- Medium Scale:Configurations for 1,000-5,000 kg hourly throughput address cooperative consolidation in Rwanda and emerging specialty sectors elsewhere in East Africa.
- Small Scale:Units below 1,000 kg hourly serve individual smallholders and village-level processing clusters with localized fabrication network dependence creating supply vulnerability when currency instability disrupts component import flows.
High volume systems anchor replacement demand from estate consolidation; medium scale equipment is expanding most quickly as cooperative structures proliferate across underpenetrated origin markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates most visibly in Kenya's Rift Valley, where estate consolidation drives replacement cycles for high-volume continuous processing systems. India's PLI scheme accelerates automated line adoption across Assam and West Bengal. Specialty tea brands in Japan and South Korea expand automated processing lines to meet premium export standards.
India
Mid-sized estates in Assam and West Bengal accelerate automated line adoption through PLI scheme capital subsidies. BIS energy labeling standards now mandate thermal efficiency disclosures for new withering machine installations. Kolkata-based fabrication networks supply oxidation control modules to estates navigating multi-standard certification timelines.
Kenya
Rift Valley estate consolidation compresses replacement cycles for continuous processing systems while raising minimum efficiency thresholds. Kenya's Tea Board quality certification protocols reshape procurement criteria for thermal equipment. Kericho and Nandi Hills clusters drive demand for burner efficiency certifications required under EU Green Deal standards.
China
GB machinery safety codes and dual carbon goals force equipment validation for export-facing tea processors. Fujian and Zhejiang province manufacturers partner with Italian compressor specialists to fast-track CO2 heat pump compliance for withering systems. Hangzhou and Anhui clusters specialize in compact oxidation control units for orthodox tea production.
Japan
Specialty tea brands expand automated processing lines within estate-owned facilities to meet premium export protocols. METI efficiency standards and JIS certification requirements filter supplier qualification for traceability-integrated systems. Shizuoka and Kagoshima prefectures anchor demand for batch-level documentation capabilities.
South Korea
Premium tea exporters specify advanced oxidation control systems with real-time polyphenol monitoring for specialty grade certification. MFDS food safety management standards and traceability mandates shape equipment procurement for export-facing estates. Boseong and Hadong regions concentrate demand for climate-controlled fermentation chambers.
Tea Processing Machine Market Competitive Landscape
Swiss and German producers anchor the premium engineering tier; Indian and Chinese fabricators hold cost-optimized positions across emerging markets. The vendor base splits between thermal engineering heritage specialists and localized fabrication networks serving regional spare parts demand. Three archetypes dominate: multinational industrial conglomerates with dairy-crossover technology, regional champions with estate-consolidation relationships, and compact system specialists targeting cooperative structures. Competitive moves center on strategic partnerships with compressor specialists for F-Gas compliance and unbundled service contracts capturing recurring revenue from dispersed estate networks.
Within the multinational tier, Bühler Group and GEA Group occupy positions anchored by thermal engineering heritage and dairy-crossover technology adaptation respectively. Among regional fabricators, Marshall Fowler Engineers exemplifies localized production network strategies across East African markets. Chinese specialists including Hunan Jinfeng Tea Machinery Co., Ltd. and Quanzhou Deli Agroforestrial Machinery Co., Ltd. represent the compact system archetype targeting cooperative consolidation in underpenetrated origin markets.
| Leading Market Players |
|---|
| Bühler Group |
| GEA Group |
| Kawasaki Kiko |
| Steelsworth |
| Marshall Fowler Engineers |
| T & I Global Ltd. |
| G.G. Dandekar Machine Works Ltd |
| Quanzhou Deli Agroforestrial Machinery Co., Ltd. |
| Hunan Jinfeng Tea Machinery Co., Ltd. |
| Others |
Value Network & Pricing Analysis
LNG spot price volatility cascades through tea processing equipment supply chains, compressing margins for fuel-dependent drying machine operators in Sri Lanka and Indonesia while elevating thermal efficiency specifications to premium-tier pricing differentiators. Fabrication network concentration in Kenya and India amplifies currency-driven component cost swings, forcing procurement teams to weight localized spare parts availability against import-dependent technology upgrades.
Pricing Analysis
Volume-heavy commodity dryers in Kenya's Rift Valley operate on thinner per-unit margins than traceability-integrated oxidation control systems serving Japanese specialty brands. Three-tier pricing structure across premium, standard, and economy levels separates EU Green Deal-certified thermal equipment from BIS-compliant Indian mid-market configurations and conventional mechanical systems. Cost compression in Sri Lankan fuel-dependent estates is intensifying because natural gas price instability squeezes operating budgets. Cooperative-owned micro-factories in Rwanda exhibit highest price sensitivity; vertically integrated Kenyan plantation groups prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Skilled welder and mechatronics technician scarcity in Tamil Nadu and Gujarat constrains oxidation drum fabrication throughput for Indian domestic demand and East African export orders. Component sourcing draws from Italian compressor specialists for CO2 heat pump compliance, Chinese steel foundries for drum housings, and German burner manufacturers for EU-certified thermal systems. Single-source vulnerability concentrates in precision fermentation sensors supplied through limited South Korean distributors. Distribution runs through Kolkata-based equipment dealers serving Assam estates, Nairobi fabrication hubs supplying Rift Valley clusters, and direct manufacturer relationships for large plantation groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation phase-down schedules and multi-standard certification burdens are consolidating vendor tiers, eliminating fabricators unable to parallel-track BIS, GB, and Tea Board compliance timelines.
For Market Incumbents: Deploy unbundled predictive maintenance platforms to capture recurring revenue from dispersed African and South Asian estate networks. Accelerate partnerships with Italian compressor specialists to fast-track CO2 heat pump validation ahead of refrigerant-dependent withering system obsolescence. Counter Chinese compact system specialists by embedding traceability-integrated oxidation control modules into estate-owned facilities serving Japanese premium export protocols. For New Entrants and Emerging Players: The 40-60% price-point gap between premium Swiss thermal engineering and economy-tier Indian fabrication creates entry space for mid-market modular continuous systems. Rwanda's emerging specialty sector and Vietnamese Central Highlands cooperative consolidation represent the most penetrable geographies for compact plug-and-expand configurations. Lead with biomass burner convergence offerings that pair tea waste gasification with IoT combustion control to estates facing carbon border adjustment exposure. For Investors and Strategic Acquirers: Distressed-cycle entries favor distressed Indian mid-cap fabricators with established BIS certification pipelines and Kolkata distribution networks. Long-term viability hinges on automation capex cycles extending across the next decade of estate consolidation in Kenya and Vietnam. Watch EU carbon border adjustment implementation timelines as the critical inflection signal for biomass burner retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biomass Burner Technology Licensing | Tea waste gasification paired with IoT combustion control unlocks fuel-switching revenue for estates facing EU carbon border adjustments. |
| CO2 Heat Pump Partnership | Italian compressor specialist alliances fast-track F-Gas Regulation compliance for withering system manufacturers serving European import markets. |
| Predictive Maintenance Platform Launch | Remote diagnostics unbundle service contracts from equipment sales, capturing recurring revenue from dispersed Kenyan and Indian estate networks. |
| Compact System Geographic Expansion | Plug-and-expand modular architecture targets Rwanda cooperative consolidation and Vietnamese Central Highlands smallholder aggregation. |
| Multi-Standard Certification Investment | Parallel BIS, GB, and Kenya Tea Board validation eliminates pre-market timeline disadvantages against established Swiss and German competitors. |
Research Methodology
Multi-period observation of estate consolidation patterns, PLI scheme disbursement trajectories, and EU Green Deal thermal standard adoption rates anchored the trend analysis, supplemented by interviews with maintenance directors at Kenyan Rift Valley plantations, oxidation line procurement leads in Assam, and aftermarket service heads at Indian fabrication networks. Secondary validation drew from Kenya Tea Board certification registries, BIS energy labeling disclosures, Indian customs machinery import records, and F-Gas Regulation implementation schedules. Bottom-up equipment shipment tracking across withering, drying, rolling, and fermentation categories triangulated against top-down estate capacity surveys.
Input-output matrices modeled fresh leaf throughput volumes against automation depth, fuel source transitions, and certification tier requirements across the projection horizon. Segmentation dimensions spanned processing stage, estate scale, technology sophistication, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle compression rates and cooperative consolidation trajectories. Forecast inputs incorporated natural gas price volatility bands and mechatronics technician training pipeline scaling assumptions.
Inputs from Kenya Tea Board certification databases and Indian PLI scheme administrative records were available through the study window; gaps in real-time smallholder cooperative financial disclosures introduce uncertainty bands around Rwanda and Vietnam emerging sector projections. Forecasts reflect documented assumptions regarding EU carbon border adjustment implementation sequencing and biomass gasification technology maturation curves. A small set of triggers—F-Gas Regulation enforcement timing, LNG price regime shifts, and mechatronics training institute output scaling—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Cold Storage Equipment Market
Food Processing Equipment
Global Food and Beverage Processing Equipment Market
Food Processing Equipment
Clean in Place Market
Food Processing Equipment
Oceania Commercial Ice Machine Market
Food Processing Equipment
Milk Sterilizer Machine Market
Food Processing Equipment
Dehydrators Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Water Cooled Cube Ice Machines Market
Food Processing Equipment
Residential Food Waste Disposer Market
Food Processing Equipment
Sandwich Preparation Refrigerators Market
Food Processing Equipment
Tube Ice Machine Market
Food Processing Equipment
North America Cold Storage Market
Food Processing Equipment
Blast Chillers Market
Food Processing Equipment
Coconut Crushers Market
Food Processing Equipment
Salmon Fish Scaling Machine Market
Food Processing Equipment
Food Sorting Machines Market