
 Deep Fryer Machine Market | 2026-2036
Deep Fryer Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Deep Fryer Machine Market Outlook
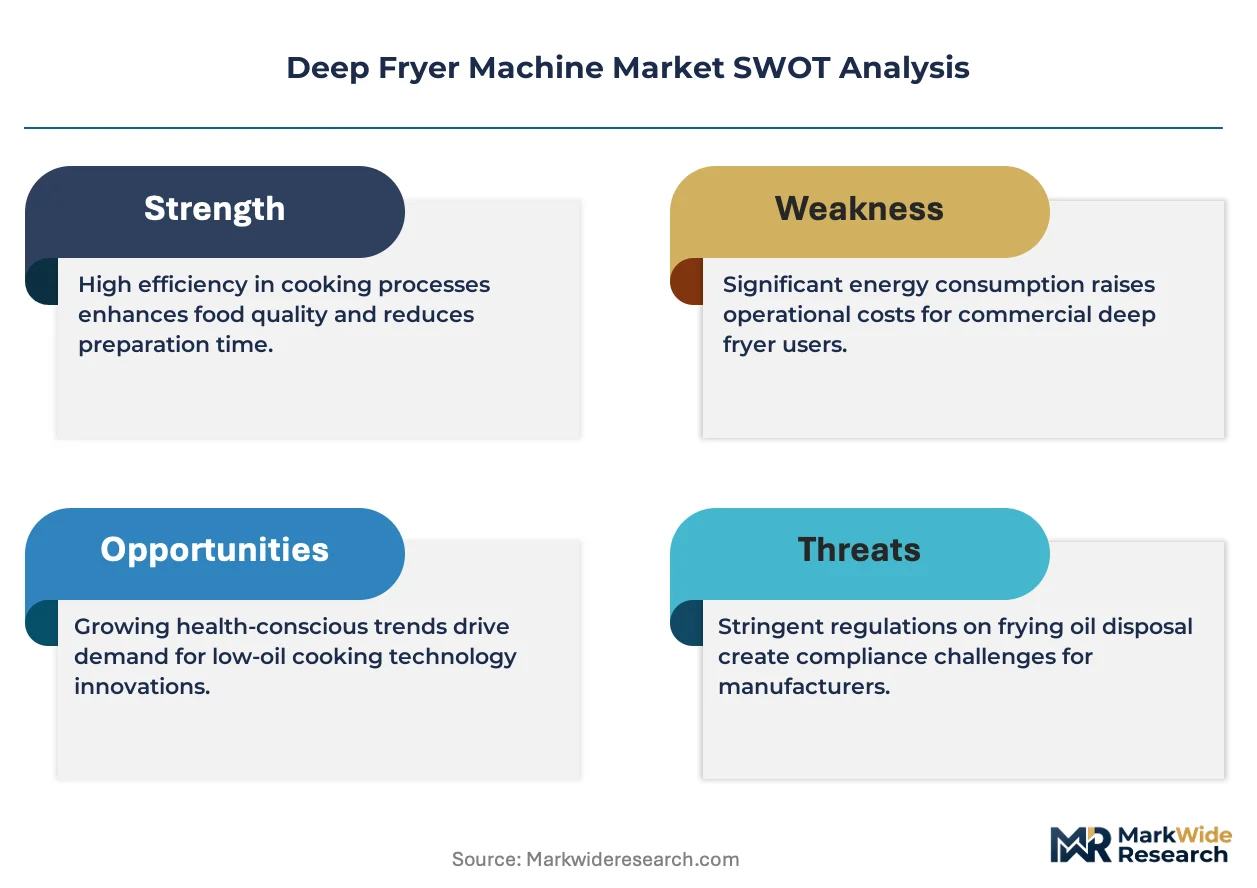
Equipment leasing and managed-service financing is fragmenting the competitive landscape for deep fryer procurement. Frymaster leverages its vertical integration into burner and control system manufacturing to sustain margin capture across premium commercial installations. Middleby Corporation anchors its position through broad foodservice equipment portfolios that compete across multiple kitchen categories. Henny Penny differentiates via pressure-frying technology leadership in high-volume quick-service chains.
A deep fryer machine is a thermostatically controlled cooking appliance that heats oil to temperatures between 325°F and 375°F for submerging and cooking food products, employing either immersion heating elements or atmospheric gas burners as thermal sources. The device serves commercial kitchens by delivering consistent throughput, standardized cook times, and repeatable product quality under continuous operational loads. Electric countertop units dominate small-format food trucks and cafes where space constraints and ventilation limitations restrict gas infrastructure deployment. Industrial floor-mounted gas fryers lead margin pools in high-throughput quick-service restaurant chains where energy cost differentials and recovery speed determine total operating economics. Multi-functional configurations integrating filtration and oil management represent the fastest-growing technology segment as labor cost pressures intensify.
The US FDA enforces Food Code standards governing cooking oil quality management and filtration protocols that directly shape fryer design requirements for food safety compliance. The EPA regulates commercial kitchen emissions through National Emission Standards for Hazardous Air Pollutants, forcing manufacturers to engineer lower-VOC burner systems and advanced ventilation integration. Stakeholders must monitor evolving energy efficiency benchmarks and oil lifecycle regulations to calibrate R&D priorities and regional product portfolios against compliance-driven replacement cycles.
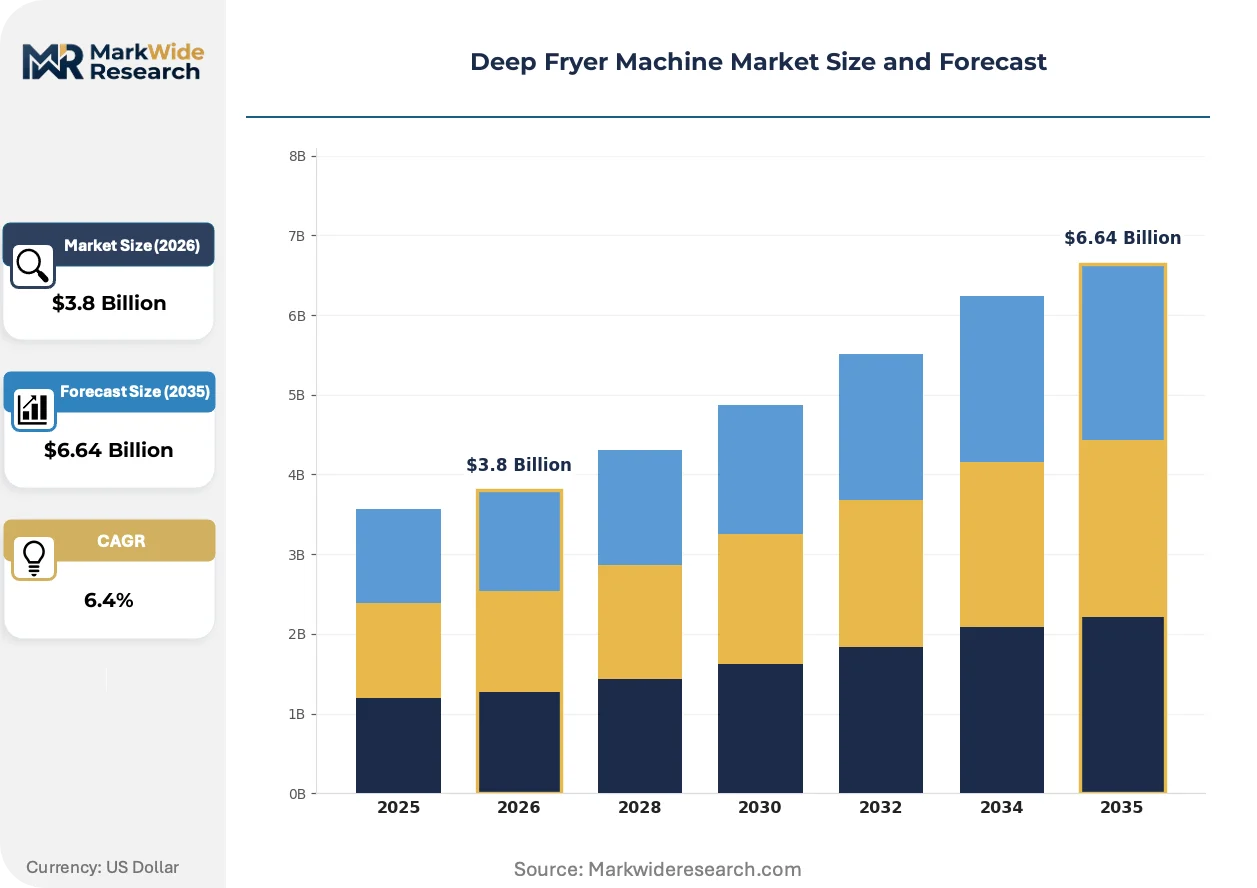
Market Dynamics
Equipment leasing and managed-service financing is fragmenting the competitive landscape for deep fryer procurement. This structural shift is compressing capital expenditure cycles and forcing manufacturers to compete on total cost of ownership rather than unit price alone.
Growth Catalysts
- EPA National Emission Standards:Hazardous air pollutant regulations are accelerating replacement of legacy gas burners with lower-VOC systems in US commercial kitchens.
- Quick-service restaurant expansion:Southeast Asian chains are driving replacement cycles through franchise standardization and volume growth.
- Automated oil filtration:Multi-functional fryer configurations integrating real-time quality monitoring are reducing labor dependency in high-throughput operations.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 sheet metal price swings compress margin stability for equipment fabricators.
- Ventilation infrastructure lock-in:Existing hood and ductwork configurations limit retrofit adoption of advanced emissions-control fryer systems.
- Induction cooking substitution:Oil-free and reduced-oil alternatives are capturing share in health-positioned foodservice segments.
Strategic Opportunities
- Vietnam manufacturing incentives:Industrial zone tax holidays and import duty exemptions are attracting assembly capacity for gas-powered commercial units.
- Cloud-connected kitchen ecosystems:Convergence of fryer telemetry with enterprise resource planning platforms is opening subscription revenue streams.
- EU F-Gas Regulation phase-down:Refrigerant restrictions are creating demand for alternative heat-pump based oil temperature management systems.
Industry Challenges
- Certified technician scarcity:Commercial gas burner commissioning and EPA compliance verification require specialized HVAC-R credentials that remain concentrated in metropolitan labor markets.
- Legacy control system incompatibility:Analog thermostat fryer fleets resist integration with modern kitchen display systems without expensive controller retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deep Fryer Machine Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Commercial, Industrial, Multi-functional Technology: Electric, Gas, Conduction, Induction End User: Restaurants, Cafes, Food Trucks, Residential Users Installation: Standalone, Built-in, Portable, Floor-mounted |
| Companies Covered | Frymaster, Vulcan, Middleby Corporation, Welbilt, Avantco Equipment, Henny Penny, Pitco, Standex International Corporation, Electrolux Professional, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deep Fryer Machine Market Strategic Shifts
Sensor-enabled fryer management systems are compressing operational decision cycles from shift-based to real-time. This technological inflection is redistributing value capture toward data-analytics providers and away from pure hardware manufacturers.
IoT-enabled oil monitoring is digitizing quality assurance protocols across quick-service restaurant chains. Operators in Indonesia and Vietnam are deploying connected probes that transmit temperature degradation and particulate counts to centralized kitchen management platforms. This visibility is digitizing maintenance scheduling and reducing unplanned downtime in franchise networks.
REACH chemical restrictions in Europe are forcing reformulation of non-stick fryer pot coatings and heat-resistant gasket materials. Manufacturers serving EU markets are qualifying ceramic-based and silicone-alternative compounds to maintain CE marking compliance. This regulatory pressure is extending product development timelines and elevating R&D spend for brands targeting European foodservice.
Food trucks and micro-format cafes are bypassing traditional equipment distributors through direct manufacturer e-commerce channels. Small-format operators in US urban clusters are configuring electric countertop units online with specification tools previously reserved for enterprise procurement teams. This channel disintermediation is compressing price transparency and forcing distributor margin recalibration.
Deep Fryer Machine Market Segmentation
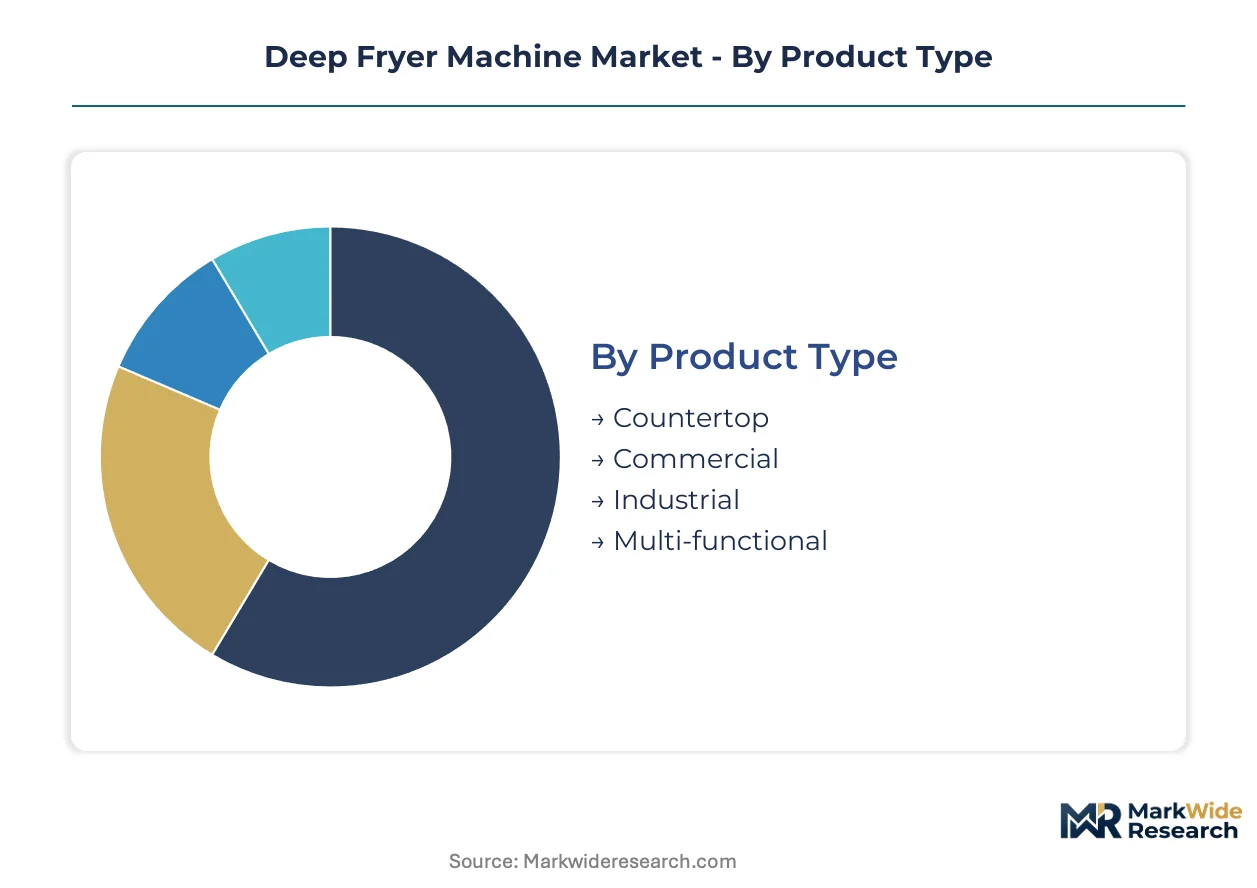
Deep fryer machine procurement cycles vary dramatically across segment boundaries. Equipment replacement timelines stretch from eighteen months for portable electric units in food trucks to eight-plus years for industrial floor-mounted installations in quick-service chains.
Product Type:
Countertop units turn inventory fastest through micro-format foodservice churn, while industrial configurations anchor longest depreciation schedules.
- Countertop:Compact electric units with immersion heating elements rated for 15-20 amp circuits. Food trucks in US urban clusters and Southeast Asian night markets drive replacement through vibration damage and mobility wear.
- Commercial:Mid-capacity floor or countertop designs with 30-50 lb oil capacity and programmable thermostatic controls. Quick-service franchise standardization in Indonesia and Vietnam concentrates demand for gas-powered variants with rapid recovery times.
- Industrial:High-throughput systems with 100+ lb capacity, automated filtration, and multi-vat configurations. Heavy stainless steel construction extends service life beyond a decade in centralized commissary kitchens.
- Multi-functional:Integrated oil management, filtration, and telemetry systems reducing labor touchpoints. Cloud connectivity and real-time quality monitoring are gaining traction fastest among enterprise operators.
Commercial configurations dominate installed base. Multi-functional systems are where expansion concentrates.
Technology:
Energy infrastructure availability and operating cost differentials partition demand across thermal source categories.
- Electric:Resistance-element heating with precise digital thermostats and minimal ventilation requirements. US food trucks and European cafes favor these where gas hookups are impractical or emissions regulations are strictest.
- Gas:Atmospheric or power burner systems delivering faster recovery and lower per-BTU operating costs. Southeast Asian quick-service chains and US high-volume independents standardize on these for throughput economics.
- Conduction:Direct-contact heating surfaces eliminating oil immersion for reduced-fat applications. Health-positioned fast-casual concepts in California and New York test these for menu differentiation.
- Induction:Electromagnetic coil systems with instant temperature response and energy efficiency gains. Premium European installations and demonstration kitchens adopt these despite capital cost premiums.
Gas technology anchors high-throughput commercial installations. Electric systems are climbing fastest in constrained-footprint segments.
End User:
Volume scale and operational intensity create divergent equipment durability requirements across customer types.
- Restaurants:Full-service and quick-service operators with continuous production demands. US EPA emissions compliance and oil filtration mandates shape specification requirements for exhaust-integrated systems.
- Cafes:Limited-menu operators with intermittent frying needs and space constraints. Electric countertop units with minimal ventilation footprints predominate in urban retail corridors.
- Food Trucks:Mobile operators prioritizing compact dimensions, electrical compatibility, and rapid setup. Direct manufacturer e-commerce channels are displacing traditional distribution for this segment.
- Residential Users:Consumer-grade countertop appliances with 2-4 liter capacity and mechanical thermostats. Replacement cycles track small appliance turnover patterns rather than commercial depreciation schedules.
Restaurant end users dominate revenue concentration. Food trucks are gaining share fastest through mobile foodservice expansion.
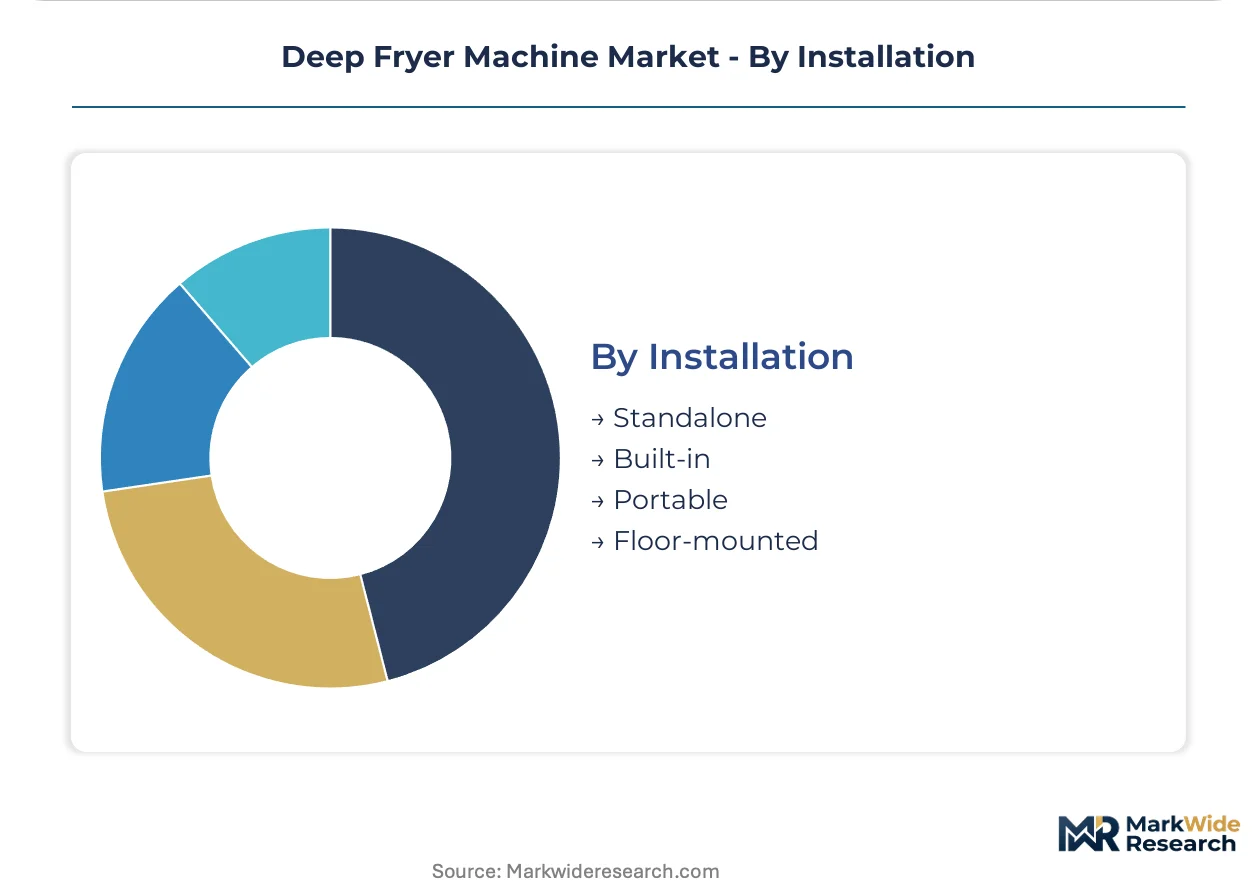
Installation:
Structural integration requirements determine retrofit feasibility and replacement pathway complexity.
- Standalone:Self-contained units with independent support frames and utility connections. Commissary kitchens and catering operations favor these for layout flexibility.
- Built-in:Custom-integrated systems requiring dedicated cabinetry and ventilation ductwork. Casino and hotel kitchen renovations specify these for aesthetic cohesion with surrounding equipment lines.
- Portable:Castor-mounted designs with quick-disconnect utilities for repositioning. Event catering and ghost kitchen operators deploy these for production line reconfiguration.
- Floor-mounted:Heavy-duty frames with seismic anchoring and integrated filtration modules. Quick-service chain prototypes in Vietnam and Indonesia standardize on these for franchise replication.
Floor-mounted systems anchor enterprise chain deployments. Portable configurations are expanding most quickly through flexible kitchen formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment leasing incentives and managed-service financing are accelerating procurement cycles across divergent regulatory environments. Southeast Asian governments are subsidizing commercial kitchen infrastructure to capture quick-service restaurant expansion. US EPA emission standards and EU chemical restrictions are forcing differentiated product portfolios by geography.
United States
Quick-service franchise standardization and food truck fleet expansion drive countertop and floor-mounted unit demand. The EPA enforces National Emission Standards for Hazardous Air Pollutants on commercial gas burners, compelling lower-VOC system redesigns. Texas and Florida concentrate gas-powered industrial fryer deployment through independent restaurant clusters.
Germany
Precision-engineered commercial kitchen equipment exports and premium foodservice concepts anchor demand for induction and electric systems. ECHA administers REACH chemical restrictions on non-stick coatings and heat-resistant gasket materials. Bavaria hosts specialized fabricators qualifying ceramic-based coating alternatives for CE marking compliance.
Indonesia
Franchise network proliferation and night market vendor formalization create sustained replacement demand for gas-powered commercial units. The national industrial ministry extends tax holidays for kitchen equipment assembly in designated zones. Jakarta and Surabaya concentrate floor-mounted system procurement for quick-service chain replication.
Vietnam
Foreign direct investment in food processing and quick-service franchise licensing accelerate commercial fryer adoption. Industrial zone authorities offer import duty exemptions for gas burner component sourcing. Ho Chi Minh City and Hanoi anchor manufacturing incentives attracting assembly capacity for Southeast Asian distribution.
China
Centralized commissary kitchen construction and cloud kitchen platform expansion drive multi-functional system demand. SAMR enforces GB standards on commercial appliance energy efficiency and electrical safety certification. Yangtze River Delta industrial clusters concentrate stainless steel fabrication for domestic and export equipment supply.
Deep Fryer Machine Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement pathways. Equipment leasing companies and managed-service providers are compressing traditional distributor margins while opening enterprise-scale contracts. Three archetypes dominate: vertically integrated burner manufacturers, broad foodservice equipment conglomerates, and pressure-frying technology specialists. Competitive moves center on backward integration into control system production and portfolio diversification across adjacent kitchen categories.
Among US-based manufacturers, Frymaster and Middleby Corporation exemplify contrasting strategic positions. Frymaster represents the vertically integrated archetype through captive supply of burner and control components. Middleby Corporation anchors the diversified conglomerate model with broad foodservice equipment portfolios spanning multiple kitchen categories. Henny Penny occupies a specialist position exemplifying pressure-frying technology leadership in high-volume quick-service applications.
| Leading Market Players |
|---|
| Frymaster |
| Vulcan |
| Middleby Corporation |
| Welbilt |
| Avantco Equipment |
| Henny Penny |
| Pitco |
| Standex International Corporation |
| Electrolux Professional |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Long Beach transpacific corridor cost dynamics compress margin buffers for stainless steel-dependent fabricators while amplifying price differentiation between EPA-certified and non-certified equipment tiers. Supply concentration in Yangtze River Delta metalworking clusters intersects with buyer procurement power to stratify commercial fryer pricing across certification-grade boundaries.
Pricing Analysis
Certification level (EPA-compliant/FDA-grade/CE-marked) creates the primary spread between premium and standard equipment tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with ISO-certified industrial units commanding substantial premiums over uncertified countertop alternatives. Cost compression in economy electric segments is intensifying because direct manufacturer e-commerce channels bypass traditional distributor markups. Food truck operators exhibit highest price sensitivity, while quick-service franchise procurement teams prioritize total cost of ownership over unit price.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for stainless steel component sourcing. Manufacturing gravity centers on China, Vietnam, and Indonesia, with Grade 304 and 316 sheet metal drawing from Yangtze River Delta foundries. Single-source vulnerability in specialized burner control modules threatens production continuity for gas-powered configurations. Distribution runs through foodservice equipment distributors, though direct manufacturer channels are displacing traditional intermediaries in small-format segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified HVAC-R technician scarcity constrains field service capacity for gas burner commissioning, creating a bottleneck that shapes competitive positioning across installation and aftermarket revenue streams. This capability gap rewards players who can internalize service delivery or automate compliance verification.
For Market Incumbents: Build captive service networks as the defensive moat against emerging equipment-leasing competitors. Acquire Vietnamese assembly capacity to capture industrial zone tax incentives before competitor footprint consolidation. Internalize burner control system production to defend margin capture against component suppliers. EPA compliance verification automation represents the critical R&D priority for reducing field technician dependency. For New Entrants and Emerging Players: Mid-market commercial kitchens in Indonesian secondary cities represent the most penetrable entry point given franchise network proliferation and limited incumbent service coverage. Cloud-connected oil management subscriptions offer a recurring revenue wedge against capital-intensive hardware incumbents. Direct e-commerce configuration tools for electric countertop units provide immediate channel access without distributor relationship investment. For Investors and Strategic Acquirers: Pressure-frying technology specialists with quick-service chain relationships command premium multiples due to switching cost entrenchment. Long-term viability hinges on R&D spend ratios relative to connectivity and automation feature development. Watch for EPA enforcement intensity acceleration as the inflection signal for compliance-driven replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Burner Manufacturing | Frymaster's captive control system production sustains margin capture against component suppliers. |
| Vietnam Assembly Capacity Expansion | Industrial zone tax holidays in Ho Chi Minh City reduce landed cost for Southeast Asian distribution. |
| Cloud-Connected Kitchen Ecosystem Development | Telemetry integration with ERP platforms opens subscription revenue streams beyond hardware sales. |
| Ceramic-Based Coating Qualification | REACH-compliant alternatives preserve EU market access amid chemical restriction tightening. |
| Direct E-Commerce Channel Investment | Food truck procurement bypasses distributor markups and compresses price transparency. |
Study Parameters
A standing panel of quick-service franchise procurement directors, commercial kitchen maintenance managers, foodservice equipment distributors, and EPA compliance officers provided ongoing calibration for demand assumptions. Primary interviews with these stakeholders combined with secondary validation from SAMR GB standard filings, US EPA NESHAP enforcement records, and ASEAN trade customs data. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction across product type, technology, and end-user dimensions.
Scenario-bracketing around stainless steel price volatility and regulatory enforcement intensity bounded the projection range. Segmentation modeling incorporated product type, thermal source technology, installation configuration, and regional regulatory cluster across the analysis window. CAGRs derived from fitted growth curves anchored to replacement cycle data and franchise expansion timelines. Oil filtration automation adoption curves and connectivity penetration rates served as industry-specific forecast inputs.
Stress conditions across commodity input costs, tariff rate adjustments, and technician labor availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding replacement cycle timing and regulatory compliance phase-in. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Wine Crusher Market
Food Processing Equipment
Brewing Boiler Market
Food Processing Equipment
Beer Brewing Equipment Market
Food Processing Equipment
Global Nutating Mixers Market
Food Processing Equipment
Brewery Equipment Market
Food Processing Equipment
Freezers Market
Food Processing Equipment
Food Waste Composting Machine Market
Food Processing Equipment
Global Food Processing Market
Food Processing Equipment
Craft Beer Saccharification Equipment Market
Food Processing Equipment
Food Extrusion Market
Food Processing Equipment
North America Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Europe Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Global Non Thermal Processing Market
Food Processing Equipment
Food Sterilization Equipment Market
Food Processing Equipment
Freeze-Drying Market
Food Processing Equipment
Commercial Beverage Blender Market