
 Filleting Machines Market | 2026-2036
Filleting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Filleting Machines Market Analytics
Multi-source equipment procurement is realigning how mid-sized seafood processors secure filleting lines. Baader Global leverages its integrated service network across Northern European ports to sustain long-term customer relationships. Marel anchors premium positioning through advanced vision-guided cutting systems. Zhang Jiang Hongwu Machinery Co competes on manufacturing scale for entry-level electric units shipped to emerging processing hubs.
Filleting machines are automated or semi-automated devices designed to remove bones and slice fish flesh into standardized portions using reciprocating blade assemblies, conveyor feeds, and programmable cutting heads operating at throughputs from 20 to 400 fish per minute. These systems serve commercial fisheries and seafood processing plants seeking yield optimization, labor reduction, and compliance with HACCP traceability requirements. Automatic filleting systems command the dominant share of capital expenditure among seafood processors, while semi-automatic configurations represent the fastest-growing installation category as mid-scale operators balance throughput needs against floor space constraints. Electric drive technology leads new equipment sales, displacing pneumatic and hydraulic alternatives where energy efficiency and precise blade control determine yield rates.
EU hygiene regulation under EFSA and the Machinery Directive (MDR) mandates stainless steel construction, clean-in-place capability, and operator safety interlocks for all filleting equipment sold within member states. FDA seafood HACCP requirements in the United States impose parallel pathogen control standards that shape export-oriented processor purchasing decisions. Stakeholders must monitor divergence between EU and North American certification requirements when planning platform standardization across multinational processing footprints.
Market Dynamics
Electric drive systems are displacing hydraulic and pneumatic alternatives across Nordic seafood processing corridors, compressing energy consumption by 40-60% while enabling precision blade control that directly lifts yield rates on high-value whitefish species.
Growth Catalysts
- EFSA Hygiene Mandates:EU regulations under the Machinery Directive require stainless steel construction and clean-in-place capability, forcing processor upgrades toward automated filleting lines that eliminate manual handling contamination risks.
- Whitefish Yield Optimization:North Sea cod and haddock processors deploy vision-guided cutting heads to maximize flesh recovery from irregular carcass shapes, converting previously discarded trim into premium loin portions.
- Electric Drive Adoption:Medium-scale Danish and Dutch plants retrofit hydraulic lines with servo-electric blade assemblies to reduce maintenance downtime and achieve programmable cut thickness for retail-ready portioning.
Market Restraints
- Stainless Steel Input Volatility:Grade 316L stainless steel price swings directly compress equipment margins, forcing manufacturers to absorb cost spikes or pass through to capital-constrained mid-scale processors.
- Specialized Technician Scarcity:Vision system calibration and servo-drive maintenance require electro-mechanical skills rare in traditional fishing communities, extending commissioning timelines and elevating service contract premiums.
- Hydraulic System Stranded Assets:Existing pneumatic infrastructure in older Icelandic and Norwegian plants creates sunk-cost resistance, slowing replacement cycles despite proven electric efficiency gains.
Strategic Opportunities
- Polish and Baltic Processing Hubs:Emerging seafood clusters in Gdansk and Klaipėda seek entry-level electric units, presenting manufacturing-scale suppliers with volume deployment potential outside saturated Nordic markets.
- CE-MDR Certification Arbitrage:Machinery Directive compliance expertise becomes a differentiable asset, enabling pre-certified equipment bundles that accelerate EU market entry for non-European manufacturers.
- Converged Sensor-Analytics Platforms:Blade-wear monitoring fused with cloud-based throughput analytics enables predictive maintenance contracts, shifting revenue from equipment sales to recurring service streams.
Industry Challenges
- Multi-Standard Certification Burden:Processors serving both EU and North American markets must reconcile EFSA cleanability requirements with FDA HACCP documentation protocols, doubling compliance engineering overhead.
- Legacy Conveyor Integration:Retrofitting automated cutting heads onto existing grading and weighing lines demands custom mechanical interfaces, extending project timelines and elevating total installed cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Filleting Machines Market |
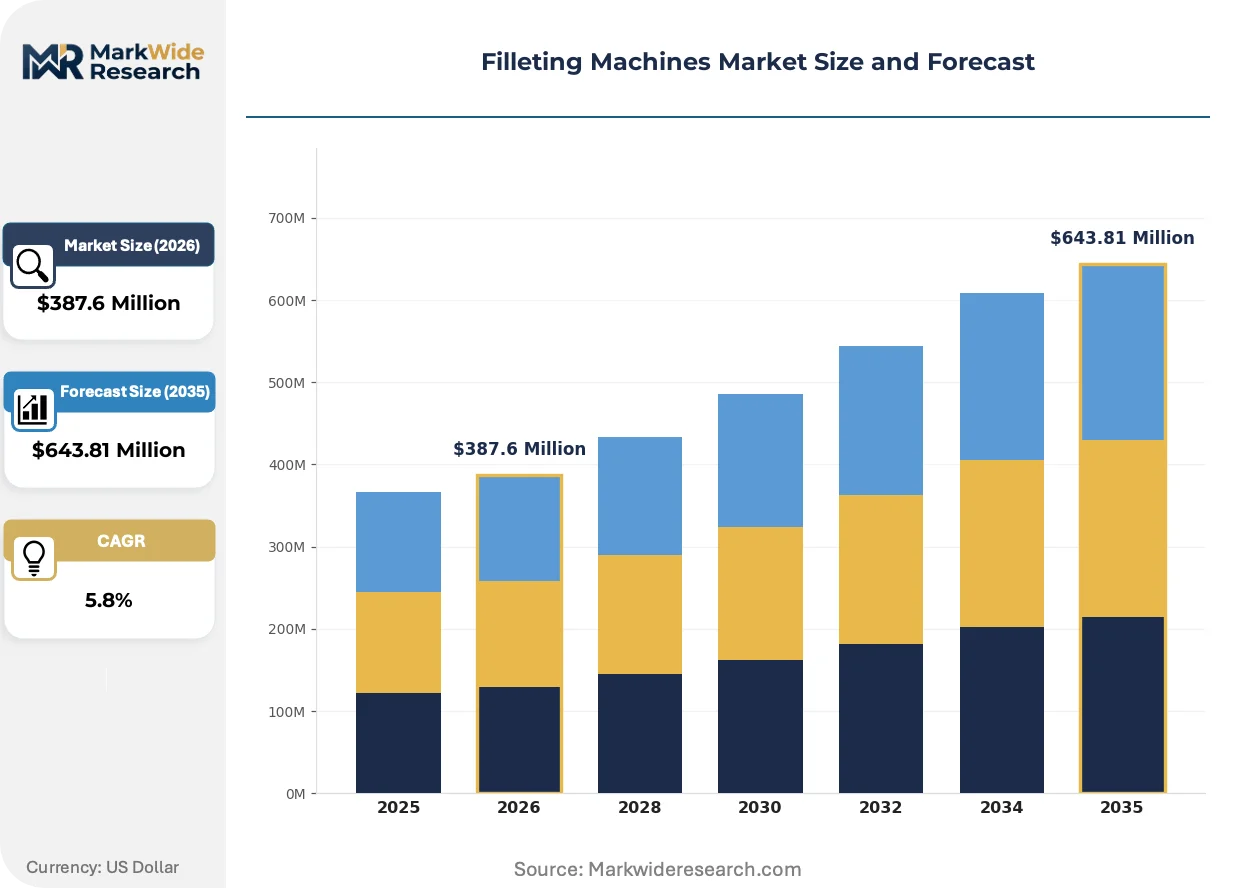
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Custom End User: Commercial Fisheries, Seafood Processing Plants, Restaurants, Retail Outlets Technology: Hydraulic, Pneumatic, Electric, Mechanical Size: Small, Medium, Large, Industrial |
| Companies Covered | Marel, Baader Global, Zhang Jiang Hongwu Machinery Co, Carnitec, PERUZA, Norbech A/S, Kroma, YUKE, Pisces Fish Machinery Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Filleting Machines Market Evolving Landscape
Automation architectures are fragmenting into modular, upgradeable configurations that let processors stage capital deployment. This shift responds to yield pressure on whitefish margins and the need for operational flexibility across seasonal catch volumes.
Machine vision systems paired with AI-driven cut-path optimization are converging with traditional mechanical blade assemblies. Premium North Sea processors deploy these hybrid platforms to adapt cutting patterns to individual fish morphology in real time. The technology compresses skilled labor dependency while standardizing portion weights for retail contract compliance.
EU Machinery Directive enforcement through national market surveillance authorities is tightening documentation requirements for safety interlocks and emergency stop functionality. German and Dutch regulators now demand third-party notified body certification for filleting line integrations, elevating compliance costs but creating barriers against uncertified import competition. Medium-scale processors respond by consolidating vendor relationships with integrated service providers.
Buyer consolidation among European retail seafood chains is compressing equipment procurement cycles. Large-volume processors now demand outcome-based performance guarantees linking payment to achieved yield rates and uptime thresholds, displacing traditional capital purchase models. This shift concentrates contract awards with vendors capable of field service density across the North Sea corridor.
Filleting Machines Market Segmentation
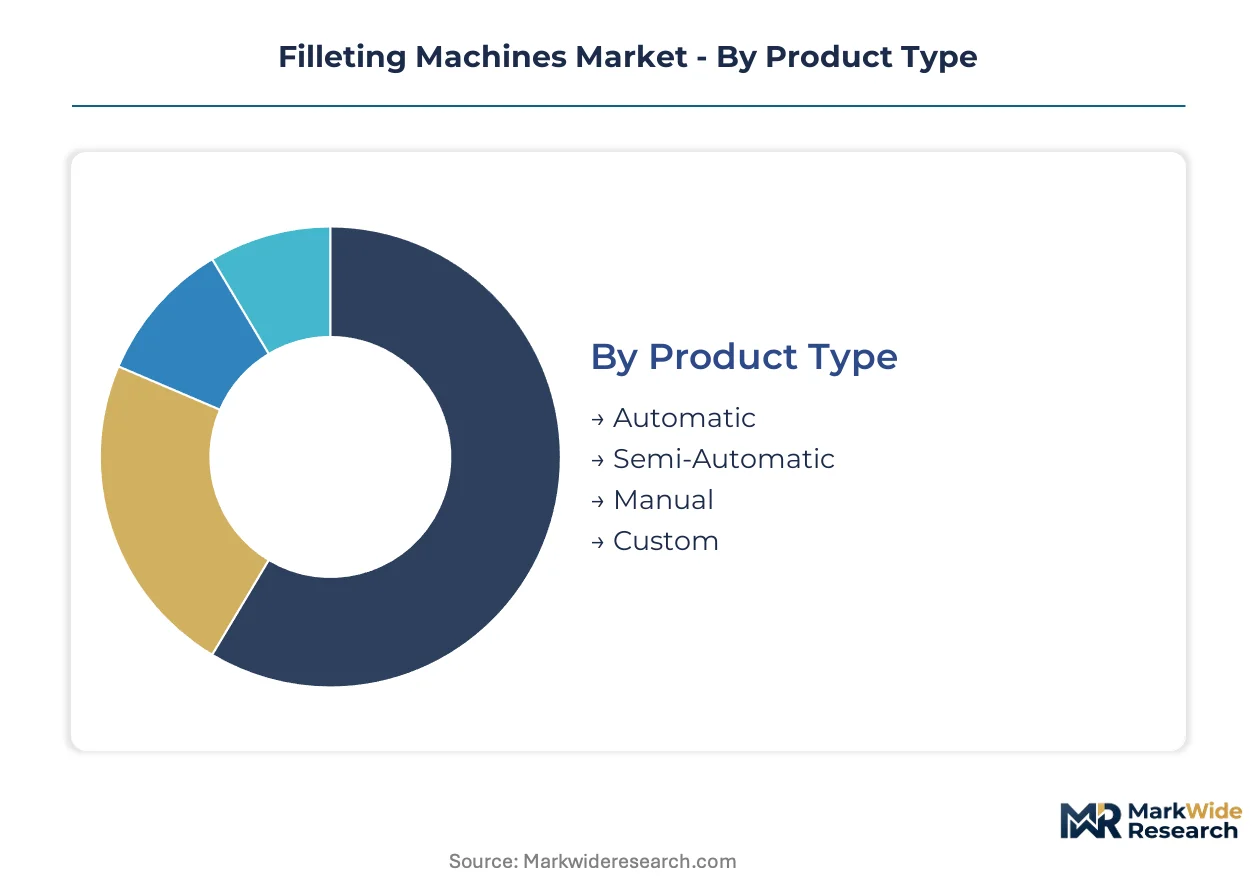
Filleting machine procurement varies sharply by operational scale and regulatory exposure. Equipment specifications diverge across automated processing lines versus artisanal installations, while technology choices reflect energy infrastructure and maintenance capabilities at specific sites.
Product Type:
Replacement cycles concentrate in automated lines as EU hygiene mandates force upgrades from manual handling systems. Norwegian and Icelandic processors prioritize stainless steel construction with clean-in-place capability to satisfy EFSA requirements.
- Automatic:Vision-guided cutting heads with servo-electric blade assemblies achieve throughputs exceeding 200 fish per minute. North Sea cod processors in Denmark and Germany deploy these systems to maximize flesh recovery from irregular carcass shapes for retail contract compliance.
- Semi-Automatic:Hybrid configurations blend mechanical blade assemblies with operator-assisted feeding stations. Dutch mid-scale operators favor this category to balance throughput needs against floor space constraints in aging port-side facilities.
- Manual:Hand-fed cutting stations serve artisanal smokehouses and small-batch processors in peripheral fishing communities.
- Custom:Purpose-built configurations accommodate non-standard species dimensions or specialized portioning requirements.
Automatic sits at the top of the volume ranking, with Semi-Automatic climbing the fastest.
End User:
Capital deployment intensity tracks processing volume and export orientation. Facilities serving EU retail chains face stricter equipment certification requirements than domestic-market operators.
- Commercial Fisheries:Onboard filleting systems demand corrosion-resistant construction and compact footprints for vessel stability. Icelandic trawler fleets retrofit electric drive units to reduce hydraulic fluid contamination risks in North Atlantic conditions.
- Seafood Processing Plants:Land-based facilities integrate filleting lines with grading, weighing, and packaging automation. German processors along the North Sea corridor deploy vision-guided systems to standardize portion weights for supermarket contract specifications.
- Restaurants:Compact benchtop units serve high-volume catering operations and institutional kitchens.
- Retail Outlets:In-store fish counters require low-throughput systems with prominent hygiene visibility for consumer assurance.
Seafood Processing Plants dominates capital expenditure, with Commercial Fisheries expanding most quickly.
Technology:
Energy efficiency and precision control are redrawing equipment specifications across Nordic installations. Danish and Dutch retrofit projects favor electric alternatives where grid reliability supports servo-drive performance.
- Electric:Servo-motor blade assemblies deliver programmable cut thickness with 40-60% energy reduction versus hydraulic alternatives. Medium-scale Norwegian plants adopt these systems to achieve yield optimization on high-value whitefish species while minimizing maintenance downtime.
- Hydraulic:Legacy pneumatic infrastructure in older Icelandic facilities creates sunk-cost resistance despite proven efficiency disadvantages.
- Pneumatic:Compressed-air systems persist in budget-constrained installations where precision requirements remain modest.
- Mechanical:Direct-drive linkages serve basic cutting functions in minimal-automation environments.
Electric commands new equipment sales, with Hydraulic retaining substantial installed base.
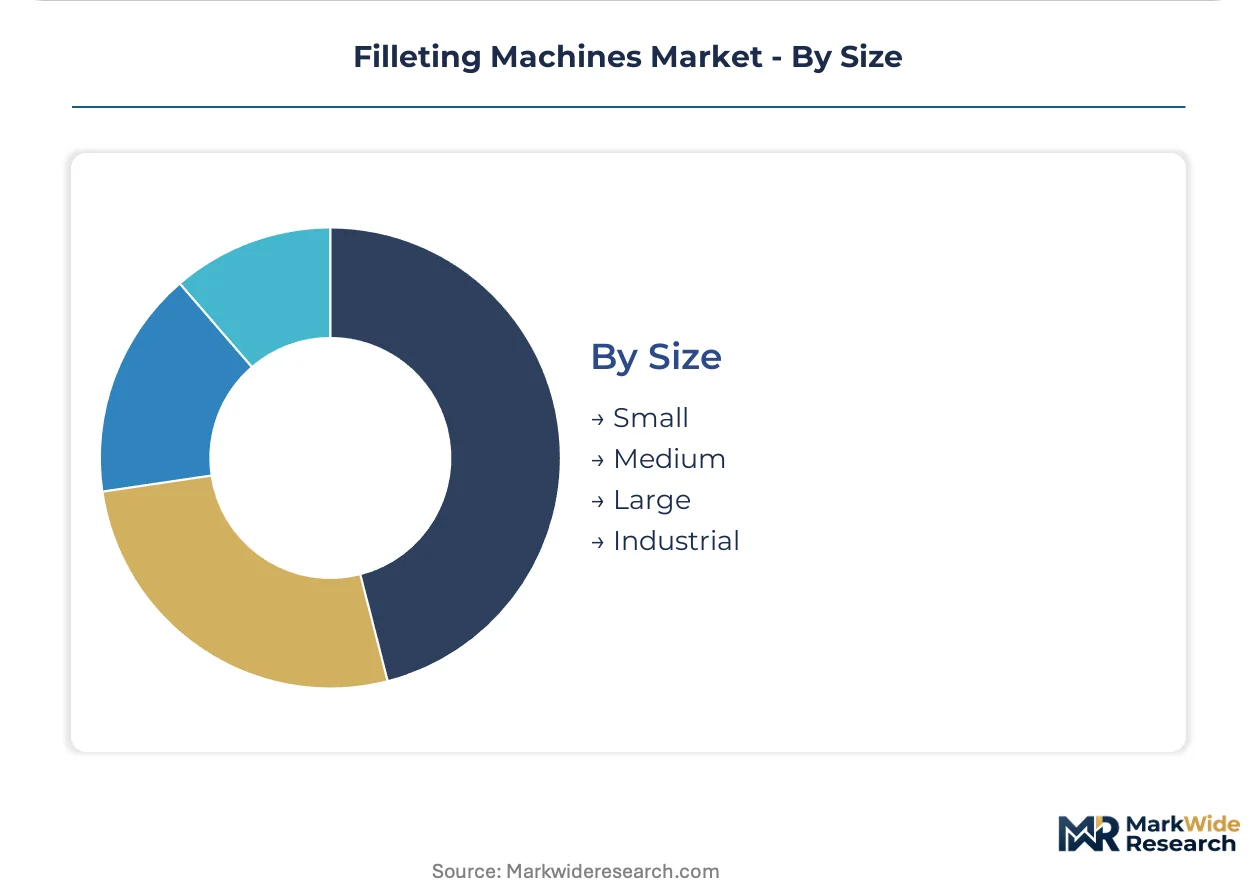
Size:
Facility footprint constraints and seasonal catch variability shape capacity decisions. Polish and Baltic emerging hubs favor scalable configurations that accommodate volume fluctuations.
- Industrial:Continuous-feed systems process 300-400 fish per minute across integrated lines. Major North Sea processors deploy these platforms to meet consolidated retail chain procurement volumes.
- Large:Standalone units serve dedicated species lines within multi-product facilities.
- Medium:Modular configurations allow staged capital deployment for expanding operations in Gdansk and Klaipėda clusters.
- Small:Benchtop and floor-standing units address space-constrained installations and specialty product niches.
Industrial leads absolute unit value, with Medium gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea fishing corridor anchors equipment deployment, with Norwegian and Icelandic processors driving automation upgrades to satisfy tightening EU hygiene mandates under EFSA frameworks.
Norway
Trawler fleets and land-based plants demand corrosion-resistant electric drive systems for North Atlantic conditions. EFSA hygiene regulations under the Machinery Directive mandate stainless steel construction and clean-in-place capability. Bergen and Ålesund processing clusters retrofit hydraulic lines with servo-electric blade assemblies to reduce maintenance downtime.
Iceland
Whitefish processors prioritize yield optimization technology for cod and haddock recovery. The country's national food safety authority enforces parallel pathogen control standards to EU EFSA benchmarks. Reykjanesbær and Akureyri facilities balance sunk-cost resistance in legacy pneumatic infrastructure against proven electric efficiency gains.
Germany
North Sea corridor processors deploy vision-guided cutting heads to standardize portion weights for retail contract specifications. German regulators under the Machinery Directive now demand third-party notified body certification for filleting line integrations. Cuxhaven and Bremerhaven plants consolidate vendor relationships with integrated service providers capable of field service density.
Denmark
Medium-scale operators favor modular semi-automatic configurations to balance throughput against floor space constraints in aging port-side facilities. EU MDR enforcement elevates compliance costs but creates barriers against uncertified import competition. Hanstholm and Hirtshals clusters stage capital deployment through upgradeable automation architectures.
Poland
Emerging seafood processing hubs in Gdansk seek entry-level electric units for volume deployment outside saturated Nordic markets. CE-MDR certification arbitrage presents manufacturing-scale suppliers with accelerated EU market entry pathways. Baltic clusters accommodate seasonal catch variability through scalable medium-capacity configurations.
Filleting Machines Market Competitive Landscape
Global majors compete with regional champions across integrated service networks and manufacturing scale. The vendor base stratifies into three tiers: premium vision-system providers, mid-market electric-drive specialists, and entry-level fabricators serving emerging hubs. Consolidation pressures concentrate contract awards with vendors capable of outcome-based performance guarantees linking payment to yield rates and uptime thresholds. Dominant competitive moves include geographic expansion into Baltic processing clusters and technology licensing for CE-MDR pre-certification bundles.
Among Nordic integrated service providers, Baader Global occupies a position exemplifying long-term customer relationship sustainment across Northern European ports. Marel anchors the premium-tier vector through advanced vision-guided cutting system representation. Zhang Jiang Hongwu Machinery Co exemplifies manufacturing-scale competition for entry-level electric units shipped to emerging processing hubs in Poland and the Baltic states.
| Leading Market Players |
|---|
| Marel |
| Baader Global |
| Zhang Jiang Hongwu Machinery Co |
| Carnitec |
| PERUZA |
| Norbech A/S |
| Kroma |
| YUKE |
| Pisces Fish Machinery Inc. |
| Others |
Value Network & Pricing Analysis
Electro-mechanical technician concentrations in Denmark and the Netherlands compress service-contract premiums for vision-system calibration, widening pricing-tier spreads between premium CE-MDR certified bundles and entry-level electric units sourced from manufacturing-scale competitors.
Pricing Analysis
Grade 316L stainless steel input-cost pass-through dominates equipment margin compression, forcing manufacturers to absorb spikes or shift burden to capital-constrained mid-scale processors. Pricing stratifies across CE-MDR pre-certified premium tiers, standard electric-drive configurations, and economy hydraulic retrofits. Pricing pressure intensifies in the standard tier as Polish and Baltic emerging hubs demand entry-level electric units at volume scale. Seafood processing plants serving consolidated retail chains exhibit lowest price sensitivity due to outcome-based performance guarantees, while artisanal smokehouses and small-batch operators in peripheral fishing communities face acute budget constraints.
Supply Chain Analysis
North Sea freight corridors from Norwegian port clusters to German processing hubs elevate landed costs for stainless steel components and servo-motor blade assemblies. Manufacturing concentrates in Denmark, Germany, and China, with component sourcing drawing from Taiwanese servo-drive suppliers and Swedish stainless steel mills. Single-source vulnerability in vision-system sensor modules creates chokepoint exposure for premium-tier equipment bundles. Distribution runs through integrated service providers capable of field-service density across the North Sea corridor, displacing direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on electric-drive technology displacement compressing energy consumption and maintenance downtime, while premium-tier vision-guided systems capture yield-optimization premiums from whitefish processors.
For Market Incumbents: Deploy CE-MDR certification arbitrage as a differentiable asset against uncertified import competition. Consolidate vendor relationships with medium-scale Danish and Dutch operators seeking integrated service networks. Deepen backward integration into stainless steel component fabrication to buffer Grade 316L price volatility. Anchor long-term contracts through predictive maintenance subscriptions that shift revenue from equipment sales to recurring service streams. For New Entrants and Emerging Players: Polish mid-scale processors represent the most penetrable buyer archetype, seeking entry-level electric units outside saturated Nordic markets. Baltic emerging hubs in Klaipėda accommodate seasonal catch variability through scalable medium-capacity configurations. CE-MDR pre-certified equipment bundles accelerate EU market entry against documentation-burdened competitors. Target outcome-based performance guarantee capabilities to displace traditional capital purchase models among consolidated retail chain suppliers. For Investors and Strategic Acquirers: Integrated seafood processing equipment conglomerates are the most active acquirer in this space, consolidating field-service density across the North Sea corridor. Long-term viability centers on vendors capable of linking payment to achieved yield rates and uptime thresholds. Acquisition targets should demonstrate CE-MDR compliance expertise and cloud-based blade-wear monitoring platforms. Watch for inflection in Baltic processing hub capital deployment as signal of volume-shift away from Nordic saturation.| Strategic Initiative | Industry Significance |
|---|---|
| CE-MDR Pre-Certification Bundles | Accelerates EU market entry for non-European manufacturers against documentation barriers. |
| Predictive Maintenance Platform Development | Shifts revenue from equipment sales to recurring service streams with blade-wear monitoring. |
| Baltic Hub Geographic Expansion | Captures volume deployment potential in Gdansk and Klaipėda outside saturated Nordic markets. |
| Vision-Guided Cutting System Integration | Standardizes portion weights for German retail contract specifications through AI-driven optimization. |
| Electric Drive Retrofit Service Lines | Converts hydraulic stranded assets in Icelandic and Norwegian plants to servo-electric efficiency. |
Research Methodology
Bottom-up seafood processing plant deployment modeling reconciled against top-down equipment manufacturer shipment tracking forms the analytical core. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads across Norway, Iceland, Germany, Denmark, and Poland combined with secondary validation from EFSA guidance documents, EU Machinery Directive enforcement records, customs trade data, and SEC filings from publicly traded processing equipment vendors. Triangulation between stakeholder-reported installation timelines and manufacturer production schedules resolved data conflicts.
Input-output matrices mapped electric-drive adoption rates against stainless steel price indices and EFSA compliance enforcement intensity across the projection horizon. Segmentation dimensions modeled include automation level, end-user facility type, drive technology, and equipment capacity tier, with regional regulatory cluster as an industry-specific overlay. CAGRs derived from logistic diffusion curves fitted to technology substitution patterns in Nordic retrofit markets. Forecast inputs incorporated whitefish yield optimization pressure and retail chain buyer consolidation dynamics.
Inputs from EFSA enforcement records and notified body certification databases were available through the study window; gaps in real-time Baltic hub capital deployment tracking introduce uncertainty bands around emerging market penetration assumptions. Forecasts reflect documented assumptions regarding electric-drive displacement velocity and Grade 316L price stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Mooncake Production Line Market
Food Processing Equipment
Food Processor Market
Food Processing Equipment
UHT Systems Market
Food Processing Equipment
Commercial Food Processors Market
Food Processing Equipment
US Cold Storage Market
Food Processing Equipment
Contact and Convective Dryers Market
Food Processing Equipment
Non-Thermal Food Processing Market
Food Processing Equipment
Wine Crusher Market
Food Processing Equipment
Canning Equipment Market
Food Processing Equipment
Reflow Oven Market
Food Processing Equipment
Cold Storage Equipment Market
Food Processing Equipment
Spray Dryer Market
Food Processing Equipment
Butcher Equipment Market
Food Processing Equipment
Reach-In Freezers Market
Food Processing Equipment
Corn Puff Making Machine Market
Food Processing Equipment
Shrimp Peeling Machine Market