
 Tomato Processing Machine Market | 2026-2036
Tomato Processing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Tomato Processing Machine Market Analytics
Premium aseptic processing lines and commodity batch systems is decoupling across the tomato processing machine landscape. Morning Star Company leverages vertical integration from field to paste to control equipment specification cycles. Ingomar Packing anchors its position through R&D intensity in low-temperature evaporation technology. COFCO Tunhe dominates volume-scale deployment across Xinjiang's tomato belt, competing on throughput metrics rather than flexibility.
Tomato processing machines encompass mechanical, thermal, ultrasonic, and vacuum-based equipment designed to transform raw tomatoes into shelf-stable products through washing, sorting, peeling, crushing, heating, concentrating, and aseptic filling operations; critical specifications include stainless steel 316L construction, CIP/SIP compatibility, and pasteurization temperatures between 85°C and 95°C for microbial stabilization. Peelers and concentrators command the deepest margin pools due to energy intensity and precision requirements, while ultrasonic technology segments attract capital as water and enzyme usage regulations tighten. Mechanical systems still occupy the largest installed base across sauces and puree applications, though thermal concentrators lead replacement cycles in European and North American retrofit markets.
The FDA's Food Safety Modernization Act mandates preventive controls for human food, directly elevating demand for traceable, hygienically designed processing equipment with validated kill-step documentation. EFSA and EU MDR frameworks impose parallel constraints on materials contact surfaces and electromagnetic compatibility for automated sorting systems. Stakeholders must weigh capital allocation between incremental mechanical upgrades and full ultrasonic or vacuum technology transitions as energy pricing and water scarcity thresholds shift operating economics.
Market Dynamics
The tomato processing machine sector faces intensifying pressure from the FDA's Food Safety Modernization Act, which mandates preventive controls and validated kill-step documentation across all human food equipment. This regulatory compression is accelerating capital redeployment toward traceable, hygienically designed systems with stainless steel 316L construction and CIP/SIP compatibility as baseline specifications.
Growth Catalysts
- FSMA compliance mandates:The FDA's preventive controls rule elevates demand for equipment with documented microbial stabilization capabilities between 85°C and 95°C pasteurization thresholds.
- Ultrasonic peeling systems:Water and enzyme usage restrictions in California's Central Valley are redirecting capital toward mechanical and ultrasonic alternatives that reduce chemical dependency.
- Xinjiang volume expansion:COFCO Tunhe's throughput-focused deployment across China's tomato belt validates demand for high-capacity concentrators in water-scarce processing corridors.
Market Restraints
- Stainless steel 316L cost volatility:Nickel and molybdenum price swings directly compress margins on hygienic equipment construction, particularly for batch system manufacturers without long-term supply agreements.
- European energy pricing:Natural gas and electricity cost structures in Italy and Spain are extending replacement cycles for thermal concentrators, delaying retrofit decisions by 18-36 months in Mediterranean processing zones.
- Technical limitation in low-temperature evaporation:Ingomar Packing's R&D intensity notwithstanding, energy recovery rates below 70% in vacuum-based systems constrain adoption in cost-sensitive commodity paste operations.
Strategic Opportunities
- Underpenetrated Brazilian paste sector:ANVISA's evolving food contact material standards create first-mover advantage for equipment suppliers offering pre-validated stainless steel documentation.
- EU Green Deal capital access:The EU's decarbonization funding mechanisms favor thermal efficiency upgrades in Italian and Portuguese tomato processing cooperatives, subsidizing concentrator replacement cycles.
- Ultrasonic-vacuum convergence:Hybrid systems combining mechanical peeling with vacuum concentration are opening specification windows in premium aseptic sauce applications where water recovery rates exceed 85%.
Industry Challenges
- Certification timeline compression:EFSA's evolving electromagnetic compatibility requirements for automated sorting systems are extending validation periods by 6-9 months, delaying revenue recognition on European deployments.
- Integration complexity with legacy batch infrastructure:Food processing plants with 15-20 year old mechanical systems face control architecture mismatches when retrofitting CIP/SIP modules, requiring parallel SCADA upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tomato Processing Machine Market |
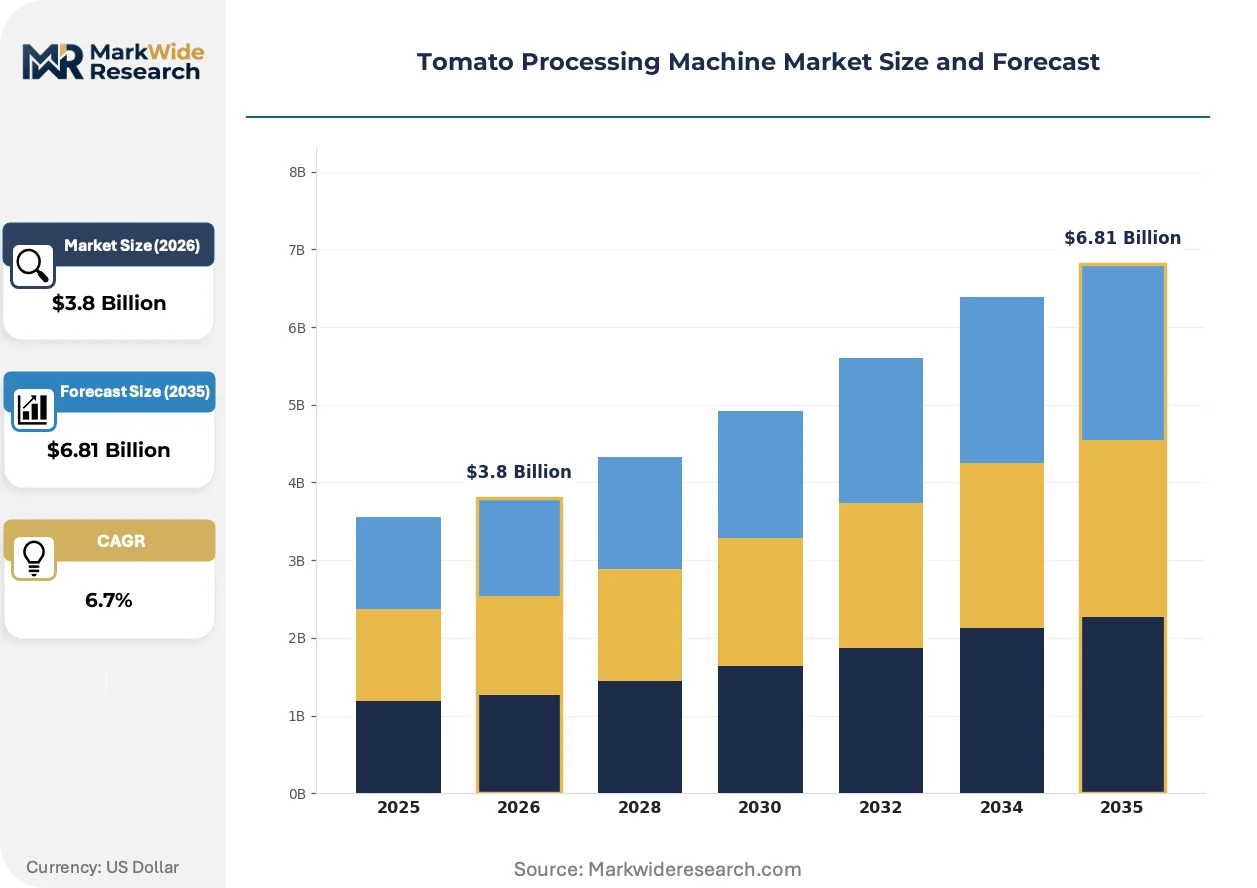
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peelers, Cutters, Juicers, Concentrators Technology: Mechanical, Thermal, Ultrasonic, Vacuum Application: Sauces, Soups, Pulp, Puree End User: Food Processing Plants, Restaurants, Catering Services, Household |
| Companies Covered | Morning Star Company, Ingomar Packing, Neil Jones Food Company, Conesa Group, Toul, Sugal Group, J.G. Boswell, Los Gatos Tomato Products, COFCO Tunhe Tomato, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tomato Processing Machine Market Evolving Landscape
Equipment specification cycles in tomato processing are compressing as regulatory validation requirements and energy efficiency mandates converge. Three distinct vectors are restructuring competitive positioning across mechanical, thermal, and emerging ultrasonic system categories.
Hybrid ultrasonic-mechanical peeling systems are unifying water reduction and yield preservation in a single processing stage. Mid-scale sauce manufacturers in Portugal and Chile are adopting these configurations at replacement-cycle velocity. The technology is unifying previously separate enzyme bath and abrasive peeling operations into continuous-flow architectures that cut water consumption by 40-60% while maintaining peel removal rates above 98%.
REACH's restrictions on chromium VI in surface treatments are forcing revisions to passivation protocols on stainless steel contact surfaces. Equipment fabricators serving EU markets must now document alternative citric acid-based passivation with equivalent corrosion resistance. Automated sorting systems with electromagnetic sensors face the steepest compliance burden, as EFSA's MDR framework adds parallel biocompatibility testing for food-contact electronics housings.
After-sales service unbundling is fragmenting traditional full-service contracts into componentized offerings. Italian and Spanish processing cooperatives now procure CIP chemical supply, spare parts logistics, and remote diagnostics through separate vendors rather than OEM-integrated packages. This disintermediation is most visible in California's Central Valley, where Morning Star Company's vertical control over field-to-paste operations has normalized multi-vendor maintenance strategies that prioritize uptime guarantees over brand loyalty.
Tomato Processing Machine Market Segmentation
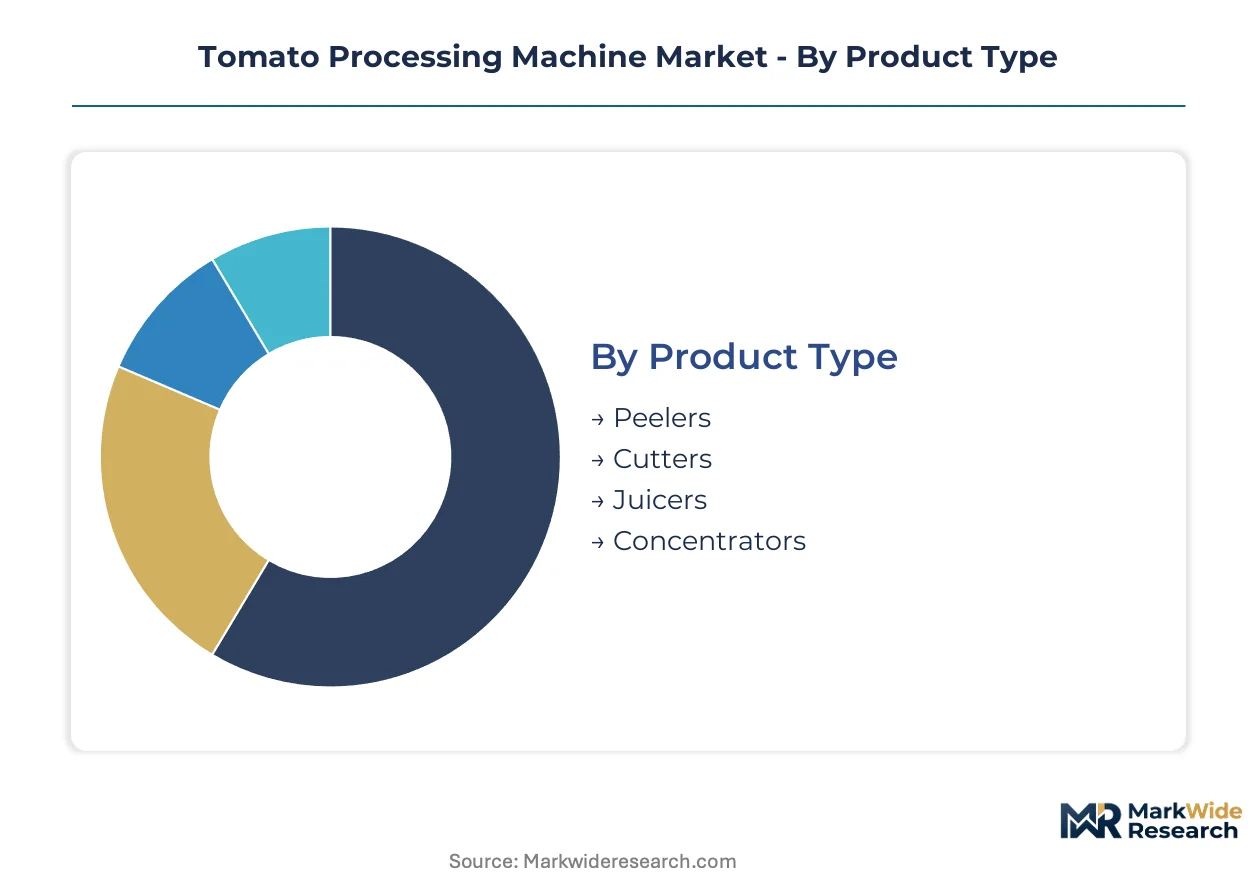
Equipment specification cycles in tomato processing diverge sharply across product categories and end-use applications. Replacement decisions track regulatory pressure, energy pricing, and water scarcity thresholds rather than uniform depreciation schedules.
Product Type:
Upgrade cycles for peeling and concentration equipment are compressing as California's Central Valley processors face water restrictions and pasteurization documentation mandates.
- Peelers:Mechanical abrasive and enzymatic systems dominate installed base, though ultrasonic alternatives are gaining specification share where water recovery exceeds 85%. California processors facing Central Valley Water Board restrictions are redirecting capital toward mechanical and ultrasonic configurations that eliminate chemical dependency.
- Concentrators:Vacuum-based low-temperature evaporation systems command deepest margin pools due to energy intensity and precision requirements. European energy pricing volatility in Italy and Spain extends replacement cycles for thermal concentrators by 18-36 months.
- Cutters:Stainless steel 316L rotary and dicing systems serve sauce and diced-tomato applications with CIP/SIP compatibility as baseline specification.
- Juicers:Cold-press and hot-break extraction equipment occupies niche position in premium aseptic juice segments.
Peelers sit at the top of the volume ranking, with concentrators climbing the fastest.
Technology:
Cost tier separation between established mechanical infrastructure and emerging ultrasonic-vacuum hybrids is restructuring procurement patterns across processing corridors.
- Mechanical:Abrasive peeling, rotary cutting, and batch thermal systems retain largest installed base across commodity paste operations. Legacy mechanical infrastructure in plants with 15-20 year depreciation cycles faces SCADA integration barriers when retrofitting CIP/SIP modules.
- Thermal:Pasteurization and evaporation equipment operating between 85°C and 95°C microbial stabilization thresholds. Natural gas pricing in Mediterranean processing zones compresses operating margins and delays replacement decisions.
- Ultrasonic:High-frequency cavitation peeling reduces water consumption 40-60% while maintaining 98%+ peel removal rates. Portugal and Chile mid-scale sauce manufacturers are adopting these configurations at replacement-cycle velocity.
- Vacuum:Low-temperature concentration preserves volatile flavor compounds in premium applications. Energy recovery rates below 70% constrain adoption in cost-sensitive commodity paste operations.
Mechanical systems retain the largest installed base, with ultrasonic configurations expanding most quickly.
Application:
Volume concentration in commodity paste versus premium aseptic sauce segments creates divergent equipment specification requirements.
- Sauces:Aseptic filling lines with validated kill-step documentation dominate premium segments. Hybrid ultrasonic-mechanical peeling systems are unifying water reduction and yield preservation in continuous-flow architectures for sauce manufacturers.
- Puree:High-Brix concentration equipment serves industrial ingredient channels. Xinjiang's tomato belt validates demand for high-capacity concentrators competing on throughput metrics.
- Soups:Ready-to-eat and condensed soup operations require particulate handling capabilities beyond homogeneous paste systems.
- Pulp:Diced and crushed tomato applications for foodservice and ingredient channels.
Sauces command the largest equipment installed base, with puree applications gaining share fastest in water-scarce processing corridors.
End User:
Customer type determines scale economies, maintenance strategy, and regulatory compliance burden intensity.
- Food Processing Plants:Industrial-scale operations with automated handling capacity and preventive controls documentation under FDA FSMA mandates. Multi-vendor maintenance strategies prioritize uptime guarantees over brand loyalty.
- Restaurants:Commercial kitchen equipment for fresh sauce and prep applications with lower pasteurization requirements.
- Catering Services:Batch-scale systems for event and institutional food production.
- Household:Consumer-grade appliances for home preservation and small-batch processing.
Food processing plants anchor equipment demand volume, with catering services representing the steepest expansion trajectory among smaller-scale segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing engineers and equipment technicians concentrate in California's Central Valley, Italy's Po Valley, and China's Xinjiang corridor, anchoring three distinct operational models for tomato handling infrastructure.
United States
California's Central Valley processing corridor drives equipment specification cycles through water scarcity mandates and FSMA preventive controls documentation. The FDA's Food Safety Modernization Act pressures processors toward validated kill-step equipment with traceable microbial stabilization. Fresno and Modesto clusters concentrate aseptic filling line deployments where Morning Star Company exercises vertical control from field operations through paste production.
China
Xinjiang's tomato belt validates demand for high-capacity concentrators competing on throughput metrics rather than flexibility. The country's dual carbon goals and water conservation directives redirect capital toward vacuum-based low-temperature evaporation with energy recovery targets. COFCO Tunhe anchors volume-scale deployment across processing zones near Ürümqi and Changji, standardizing equipment procurement around metric-ton-per-hour benchmarks.
Italy
Natural gas pricing volatility in Mediterranean processing zones extends thermal concentrator replacement cycles by 18-36 months. The EU Green Deal's decarbonization funding mechanisms subsidize efficiency upgrades in Emilia-Romagna and Campania cooperatives. Parma and Foggia clusters concentrate hybrid ultrasonic-mechanical peeling adoption where water recovery rates exceed 85%.
Spain
Andalusian and Extremadura processing cooperatives face compressed margins from electricity cost structures delaying thermal equipment retrofits. EFSA's electromagnetic compatibility requirements for automated sorting systems extend validation periods by 6-9 months. Badajoz and Almería clusters concentrate mid-scale sauce manufacturers adopting continuous-flow peeling architectures to cut water consumption 40-60%.
Brazil
ANVISA's evolving food contact material standards create specification windows for equipment suppliers offering pre-validated stainless steel documentation. São Paulo and Minas Gerais processing corridors concentrate paste production capacity with limited aseptic infrastructure penetration. Campinas and Uberaba clusters represent underpenetrated retrofit opportunities as regulatory frameworks align with EU and US hygiene benchmarks.
Tomato Processing Machine Market Competitive Landscape
Top-tier vendors anchor premium aseptic processing lines, while mid-scale fabricators compete on batch system cost efficiency across commodity paste operations. Equipment specification authority concentrates among vertically integrated processors who internalize equipment design cycles rather than deferring to OEM standards. Three archetypes structure competition: field-to-paste integrators controlling upstream specification, regional cooperatives pooling procurement leverage, and volume-scale state enterprises optimizing throughput metrics. Consolidation pressure manifests through backward integration into equipment design and geographic expansion into water-scarce processing corridors.
Among US-based processors, Morning Star Company and Ingomar Packing occupy distinct positions within the integrator archetype, while COFCO Tunhe represents the state-enterprise volume model in Chinese deployment. Morning Star exemplifies vertical control over specification cycles from agricultural operations through finished paste production. Ingomar Packing anchors R&D intensity positioning in low-temperature evaporation technology despite energy recovery constraints. COFCO Tunhe validates throughput-focused procurement patterns across Xinjiang's processing belt, competing on metric scale rather than equipment flexibility.
| Leading Market Players |
|---|
| Morning Star Company |
| Ingomar Packing |
| Neil Jones Food Company |
| Conesa Group |
| Toul |
| Sugal Group |
| J.G. Boswell |
| Los Gatos Tomato Products |
| COFCO Tunhe Tomato |
| Others |
Value Network & Pricing Analysis
Backward integration into equipment specification cycles anchors both supply security and pricing power for field-to-paste processors controlling upstream tomato sourcing through finished paste production. Morning Star Company's captive control over California Central Valley growing operations insulates its procurement from spot-market volatility in stainless steel 316L components while compressing vendor margins through direct equipment design authority.
Pricing Analysis
After-sales service unbundling splits traditional full-service contracts into componentized offerings across Italian and Spanish cooperatives. Three-tier pricing structure across premium aseptic, standard batch, and economy mechanical levels separates validated kill-step documentation tiers from commodity paste systems. Cost compression in standard batch equipment intensifies because nickel and molybdenum price swings directly squeeze stainless steel 316L fabrication margins. Food processing plants with multi-vendor maintenance strategies demonstrate lowest price sensitivity, while mid-scale sauce manufacturers in Portugal and Chile face acute pressure on capital deployment timelines.
Supply Chain Analysis
Equipment qualification gating through FDA FSMA preventive controls documentation and EFSA electromagnetic compatibility requirements restricts vendor participation to fabricators with validated CIP/SIP protocols. Stainless steel 316L supply concentrates in Germany, Italy, and China, with specialty alloy mills anchoring hygienic equipment construction. Component sourcing draws from precision machining clusters in Northern Italy, electrical automation suppliers in Germany, and nickel alloy producers in China. Single-source vulnerability in specialty alloy supply creates exposure to commodity price volatility. Distribution runs through OEM-direct channels for premium aseptic lines and regional fabricator networks for batch system retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in ultrasonic-vacuum hybrid configurations where water recovery premiums command pricing power above commodity mechanical tiers, with energy efficiency gains in low-temperature evaporation anchoring cost-down trajectories for early movers.
For Market Incumbents: Anchor defensive positioning through R&D intensity in hybrid ultrasonic-mechanical peeling systems that unify water reduction with yield preservation, while extending backward integration into stainless steel 316L supply agreements to neutralize nickel-molybdenum cost volatility. Certification investment in FDA FSMA kill-step documentation and EFSA electromagnetic compatibility protocols creates switching-cost barriers against emerging Asian fabricators competing on throughput metrics alone. For New Entrants and Emerging Players: ANVISA's evolving food contact material standards in Brazil open a window for equipment suppliers offering pre-validated stainless steel documentation to capture first-mover advantage in underpenetrated paste production corridors. Target mid-scale sauce manufacturers in Portugal and Chile adopting continuous-flow peeling architectures at replacement-cycle velocity, with a go-to-market angle anchored on water consumption reduction metrics that satisfy tightening Central Valley Water Board restrictions. For Investors and Strategic Acquirers: Roll-up economics work for regional batch-system fabricators because specification authority is fragmenting across multi-vendor maintenance strategies that prioritize uptime guarantees over OEM brand loyalty. Platform consolidation targets should emphasize service network density in California's Central Valley and Italy's Po Valley processing clusters. The inflection signal to monitor is EU Green Deal decarbonization funding velocity subsidizing thermal efficiency upgrades in Mediterranean cooperatives.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic-Vacuum Hybrid Development | Combines mechanical peeling with vacuum concentration for premium aseptic sauce applications where water recovery exceeds 85%. |
| Backward Integration into Alloy Supply | Captive stainless steel 316L sourcing from German and Italian mills neutralizes nickel-molybdenum price volatility compressing batch system margins. |
| FSMA Pre-Validation Documentation | FDA preventive controls compliance accelerates specification cycles for equipment with documented microbial stabilization between 85°C and 95°C. |
| EU Green Deal Efficiency Subsidies | Decarbonization funding mechanisms in Italy and Portugal subsidize thermal concentrator replacement cycles delayed by natural gas pricing volatility. |
| Multi-Vendor Service Unbundling | Fragmentation of CIP chemical supply, spare parts logistics, and remote diagnostics creates componentized revenue streams beyond OEM-integrated packages. |
Research Methodology
Multiple input streams — primary interviews with plant engineers and maintenance directors, regulatory filing analysis, and equipment procurement database review — were reconciled to construct segment-level demand estimates. Processing plant managers, OEM procurement teams at Morning Star Company and Ingomar Packing, aftermarket service heads, and Central Valley Water Board compliance officers provided operational validation. Secondary sources included FDA FSMA guidance documents, EFSA MDR framework updates, EU Green Deal funding disclosures, and customs data on stainless steel 316L alloy imports. Bottom-up equipment deployment counts were triangulated against top-down paste production volume estimates across California, Xinjiang, and Mediterranean processing corridors.
Historical replacement cycle patterns were cross-referenced against panel input from equipment fabricators and processing cooperatives to model deployment trajectories across the projection horizon. Segmentation dimensions included product type (peelers, concentrators, cutters, juicers), technology tier (mechanical, thermal, ultrasonic, vacuum), application (sauces, puree, soups, pulp), and end-user scale (industrial plants, catering services, restaurants, household). CAGRs were derived from installed base turnover rates and regulatory compliance-driven compression of specification cycles. Industry-specific forecast inputs incorporated water scarcity thresholds in California's Central Valley and energy recovery rate assumptions for vacuum-based low-temperature evaporation systems.
Revisions become necessary when FDA enforcement intensity on preventive controls documentation, EU energy pricing volatility, or nickel-molybdenum alloy cost swings materialize beyond modeled ranges. Forecasts reflect assumptions about regulatory timeline compression and hybrid technology adoption velocity in premium sauce segments. A model refresh is warranted upon material change in EU Green Deal capital access conditions or ANVISA regulatory alignment velocity in Brazilian processing corridors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Bottled Water Processing Equipment Market
Food Processing Equipment
Pasty Products Filling Machine Market
Food Processing Equipment
Optical Sorter Market
Food Processing Equipment
Craft Brewery Equipment Market
Food Processing Equipment
Multi Ovens Market
Food Processing Equipment
Automatic Canning Machine Market
Food Processing Equipment
Commercial Beverage Blender Market
Food Processing Equipment
Canning Equipment Market
Food Processing Equipment
Insect Protein Processing Equipment Market
Food Processing Equipment
Spray Drying Market
Food Processing Equipment
Pet Food Extrusion Market
Food Processing Equipment
Plastic Processing Equipment Market
Food Processing Equipment
Ice Cream Machine Market
Food Processing Equipment
De-Agglomerating Equipment Market
Food Processing Equipment
Butcher Equipment Market
Food Processing Equipment
Alternative Protein Processing Equipment Market