
 Loss-In-Weight Feeder Market | 2026-2036
Loss-In-Weight Feeder Market Size, Share, and Industry Trends Forecast 2026-2036
Loss-In-Weight Feeder Market Analytics
Direct distribution through OEM-integrator partnerships is reshaping how loss-in-weight feeder systems reach end-users in plastics and chemical processing. Coperion K-Tron leverages its captive extrusion systems business to bundle gravimetric feeders with compounding lines. Schenck Process anchors its position through deep vertical integration into weighing electronics and control software. Gericke differentiates via specialization in hygienic designs for food and pharmaceutical applications.
A loss-in-weight feeder is a gravimetric dispensing device that continuously measures mass flow by weighing the contents of a hopper on load cells and adjusting discharge speed to maintain setpoint accuracy, typically achieving precision within ±0.25% to ±1.0% of feed rate. The instrument serves critical process control functions in continuous manufacturing where material consistency directly determines product quality and batch uniformity. Screw feeders occupy the largest installed base across bulk material handling applications due to mechanical simplicity and broad material compatibility. Digital technology represents the fastest-expanding segment as processors replace analog controllers with IoT-enabled platforms supporting real-time recipe adjustment and remote diagnostics. Electromechanical systems retain margin concentration in pharmaceutical additive manufacturing where servo-driven accuracy commands premium positioning.
FDA cGMP guidelines and EMA Annex 15 validation requirements shape pharmaceutical feeder specifications by mandating containment integrity, cleaning verification, and electronic batch records. REACH chemical safety obligations and EU Machinery Directive CE marking compel European manufacturers to certify materials of construction and operator safety interlocks for chemical industry deployments. Stakeholders must monitor evolving MDR traceability mandates and FDA guidance on continuous manufacturing to anticipate certification burdens that will determine competitive access across regulated verticals.
Market Dynamics
Electromechanical digital architectures are systematically displacing pneumatic control systems across European compounders, forcing incumbent suppliers to reengineer core product platforms while pharmaceutical traceability mandates from EMA and MDR tighten specification requirements.
Growth Catalysts
- EMA Annex 15 Validation:Pharmaceutical manufacturers in Germany and Switzerland are expanding gravimetric feeder deployments to satisfy electronic batch record requirements and containment integrity standards for continuous manufacturing lines.
- Servo-Driven Accuracy:Electromechanical systems command premium positioning in pharmaceutical additive manufacturing where precision dosing directly determines product uniformity and regulatory compliance.
- Germany's Chemical Corridor:Bulk polymer processors along the Rhine-Ruhr industrial belt are replacing volumetric feeders with loss-in-weight systems to reduce material waste and improve recipe consistency.
Market Restraints
- Load Cell Input Volatility:Strain gauge and force sensor component costs fluctuate with semiconductor foundry capacity constraints, compressing margins for mid-tier feeder manufacturers.
- Control Software Concentration:Proprietary weighing electronics and recipe management platforms remain concentrated among German and Swiss engineering houses, creating supplier lock-in risks for processors.
- Technical Limitation:Loss-in-weight systems struggle with cohesive, adhesive, or floodable powders below 50 microns, restricting penetration in certain specialty chemical and food additive segments.
Strategic Opportunities
- Continuous Manufacturing Transition:FDA guidance on integrated continuous bioprocessing creates demand for gravimetric feeders with real-time release testing capabilities in US pharmaceutical facilities.
- Battery Materials Processing:Lithium-ion cathode and anode slurry production requires precision additive feeding for conductive agents and binders, opening new verticals outside traditional plastics and chemicals.
- Remote Diagnostics Convergence:IoT-enabled platforms combining edge computing with cloud-based recipe optimization enable predictive maintenance contracts and recurring revenue streams.
Industry Challenges
- Calibration Technician Scarcity:Gravimetric system commissioning requires specialized expertise in load cell verification, signal conditioning, and control loop tuning that outpaces vocational training pipeline output.
- Legacy DCS Integration:Brownfield chemical plants running 1990s-era distributed control systems face protocol conversion complexity when connecting modern digital feeders to existing automation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loss-In-Weight Feeder Market |
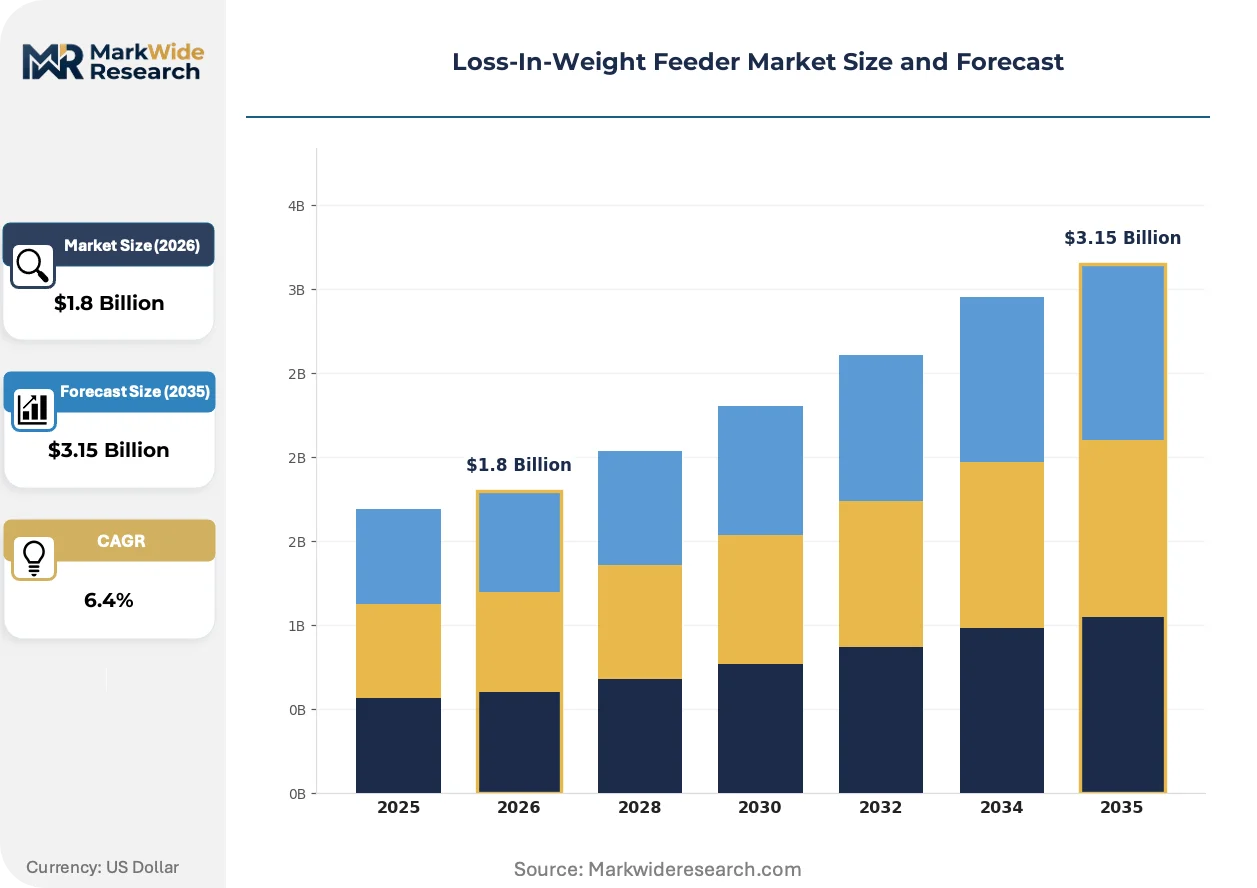
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
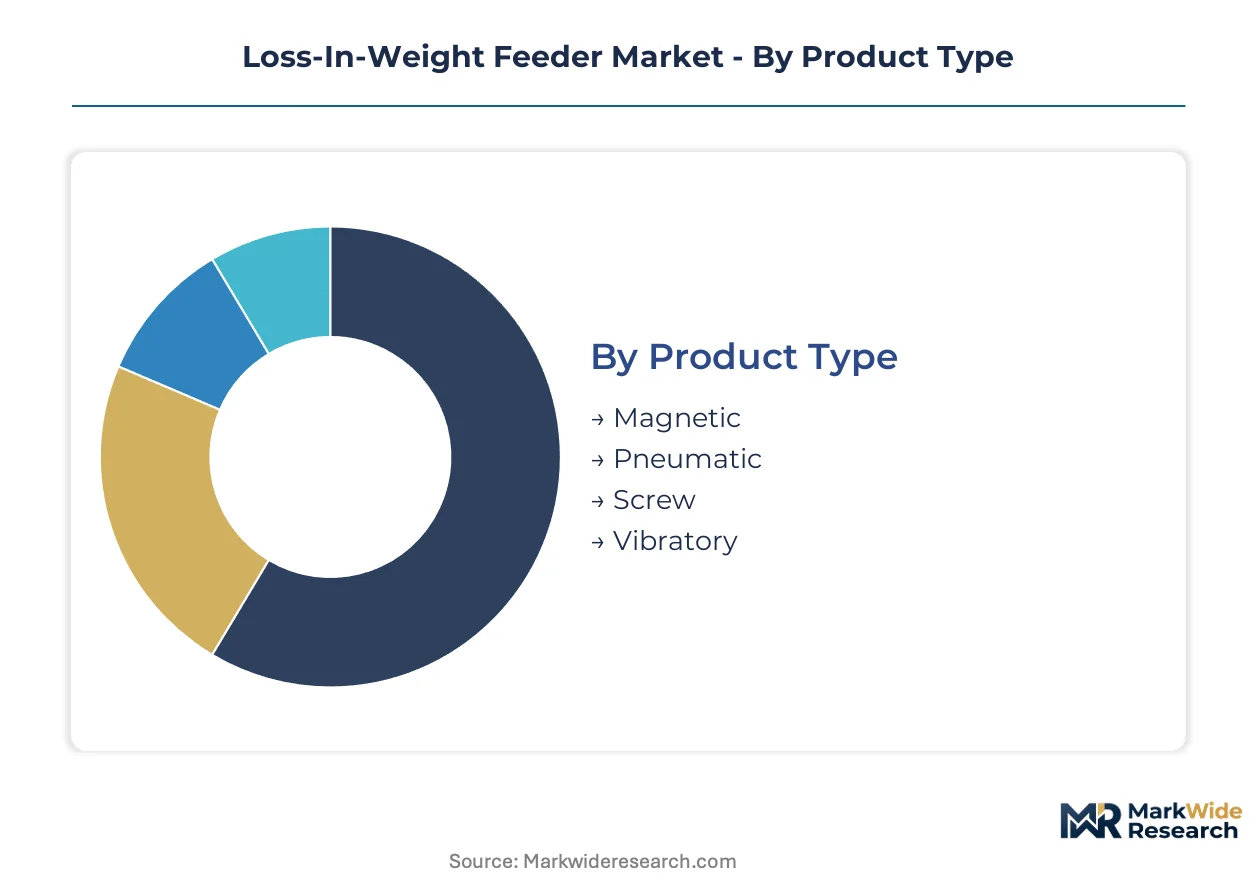
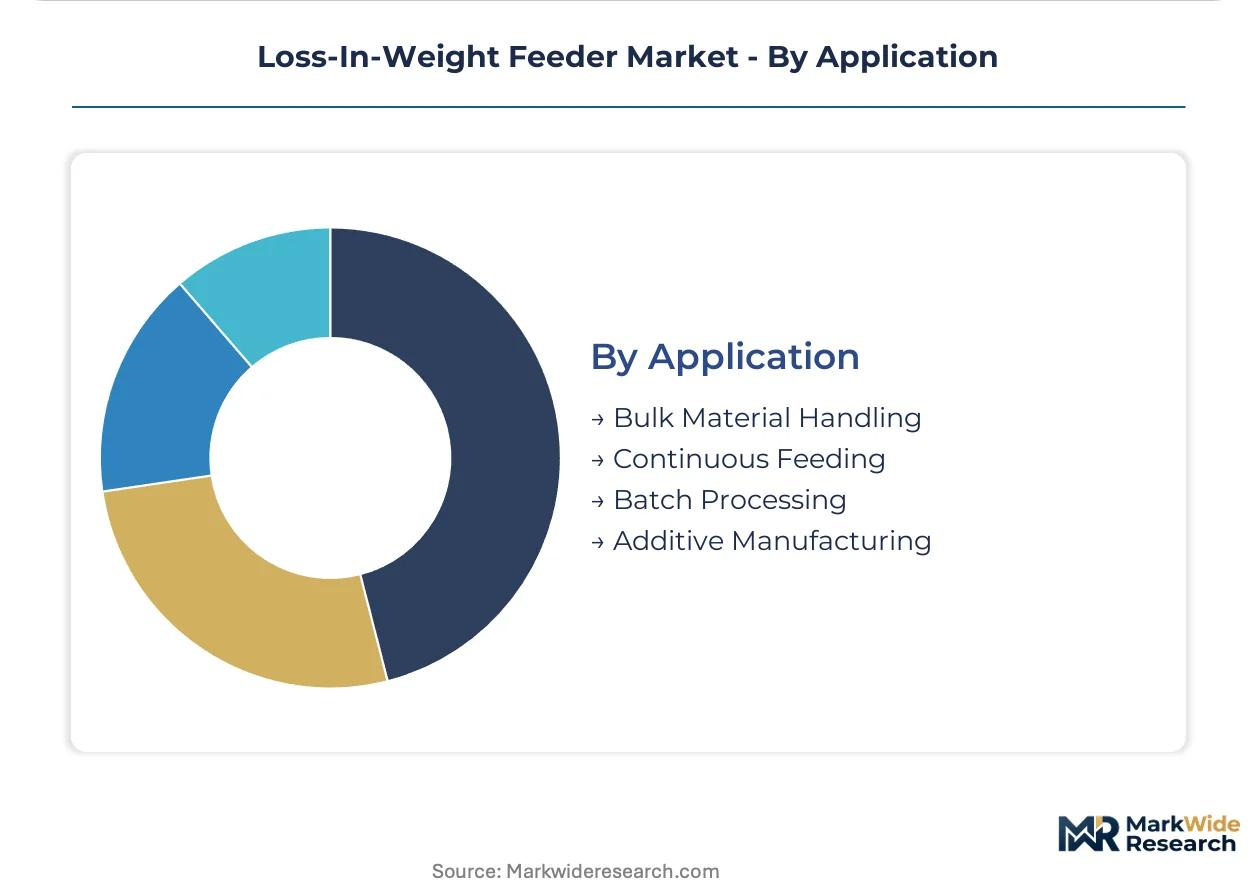
| Segmentation | Product Type: Magnetic, Pneumatic, Screw, Vibratory Industry Vertical: Food Processing, Chemical, Pharmaceutical, Plastics Technology: Electromechanical, Valve-Based, Hydraulic, Digital Application: Bulk Material Handling, Continuous Feeding, Batch Processing, Additive Manufacturing |
| Companies Covered | Merrick Industries Inc., Gericke, Hapman, Acrison, Schenck Process, Novatec, GIMAT, Coperion K-Tron, FLSmidth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loss-In-Weight Feeder Market Evolving Landscape
Digital transformation is rewriting competitive rules across feeder system architecture, control methodology, and commercial engagement models. Three distinct vectors are compressing product lifecycles and reshaping supplier-customer relationships.
Servo-driven screw feeder technology is migrating from niche pharmaceutical applications into mainstream chemical processing. These systems replace variable-frequency motor drives with closed-loop position control, enabling stroke-by-stroke dosing resolution below 0.1% deviation. European compounders in Switzerland's precision equipment cluster are adopting this architecture fastest, compressing the performance gap between premium and standard feeder tiers.
EMA's Medical Device Regulation traceability mandates are forcing design changes across pharmaceutical feeder portfolios. The regulation requires unique device identification and electronic history records for production equipment touching drug products. German manufacturers are responding with stainless-steel construction upgrades, sealed cable routing, and embedded RFID tags for component-level tracking.
Equipment-as-a-service contracting is displacing capital purchase models among mid-sized European plastics processors. Under these arrangements, OEMs retain ownership while charging per-kilogram throughput fees bundled with predictive maintenance and recipe optimization. This shift concentrates most visibly in Germany's automotive supply chain, where Tier 2 compounders face working capital constraints from volatile polymer feedstock pricing.
Loss-In-Weight Feeder Market Segmentation
Loss-in-weight feeder procurement decisions pivot on material rheology, regulatory exposure, and integration complexity. Segment boundaries blur as electromechanical platforms migrate from pharmaceutical niche into chemical mainstream, while digital architectures reshape competitive positioning across all verticals.
Product Type:
Cost tier differentiation separates mechanically simple designs from servo-driven precision platforms commanding premium positioning.
- Screw:Helical auger mechanisms handle free-flowing pellets and granules across broad bulk density ranges. Germany's chemical corridor deploys these systems most intensively for polymer compounding, where material waste reduction drives replacement of volumetric alternatives.
- Vibratory:Electromagnetic or electromechanical excitation enables gentle handling of friable materials without screw shear. Swiss pharmaceutical additive manufacturers specify these for active pharmaceutical ingredient dosing where particle integrity determines dissolution profiles.
- Magnetic:Rare-earth actuator arrays suit ferrous or magnetically susceptible feedstocks in specialty metal powder processing.
- Pneumatic:Compressed-air conveying integration persists in legacy installations though electromechanical displacement accelerates across European compounders.
Screw feeders hold installed capacity. Vibratory designs are rotating up the share rankings.
Industry Vertical:
Application context determines specification stringency, with regulatory burden and contamination risk creating tiered demand profiles.
- Pharmaceutical:EMA Annex 15 validation and FDA cGMP compliance mandate containment integrity, cleaning verification protocols, and electronic batch record integration. Servo-driven electromechanical systems capture this vertical due to stroke-by-stroke dosing resolution below 0.1% deviation.
- Chemical:REACH obligations and EU Machinery Directive CE marking compel materials certification and safety interlock validation. Rhine-Ruhr polymer processors are converting volumetric lines to gravimetric control for recipe consistency improvements.
- Plastics:Continuous compounding and masterbatch production favor robust screw architectures with moderate precision requirements.
- Food Processing:Hygienic design standards including EHEDG and 3-A Sanitary specifications govern stainless-steel construction and clean-in-place capability.
Chemical vertical holds installed capacity. Pharmaceutical applications are rotating up the share rankings.
Technology:
Maturity gradients separate established electromechanical platforms from emerging digital architectures reshaping control methodology.
- Digital:IoT-enabled platforms with edge computing and cloud-based recipe optimization support real-time adjustment and predictive maintenance contracting. European OEMs are bundling these capabilities into throughput-based service models for capital-constrained processors.
- Electromechanical:Closed-loop servo positioning delivers premium accuracy for pharmaceutical additive manufacturing where dosing precision determines batch uniformity. Switzerland's precision equipment cluster concentrates adoption of these architectures.
- Valve-Based:Pneumatic or solenoid actuation suits intermittent discharge applications in batch processing contexts.
- Hydraulic:High-torque drive systems persist in heavy-duty bulk material handling where mechanical load demands exceed electromechanical ratings.
Electromechanical technology holds installed capacity. Digital platforms are rotating up the share rankings.
Application:
Volume throughput and control precision requirements segment demand between continuous manufacturing and batch-oriented deployment patterns.
- Continuous Feeding:Real-time mass flow control maintains setpoint accuracy within ±0.25% to ±1.0% for extrusion and compounding lines. FDA guidance on integrated continuous bioprocessing expands pharmaceutical demand for gravimetric feeders with real-time release testing capabilities.
- Additive Manufacturing:Precision powder dosing for metal and polymer 3D printing requires contained transfer and layer-by-layer mass control. Battery materials processing for lithium-ion cathode slurry production opens new vertical demand for conductive agent and binder feeding.
- Bulk Material Handling:High-throughput polymer and mineral processing prioritizes mechanical reliability over dosing resolution.
- Batch Processing:Intermittent discharge cycles with recipe-based setpoint changes suit formulation and blending operations.
Bulk material handling holds installed capacity. Continuous feeding applications are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's chemical corridor and Switzerland's precision equipment cluster anchor European gravimetric feeder demand, with EMA traceability mandates and MDR compliance requirements accelerating technology refresh cycles across pharmaceutical and chemical processing installations.
Germany
Rhine-Ruhr polymer processors and Bavarian pharmaceutical compounders drive replacement of volumetric systems with loss-in-weight architectures to reduce material waste and satisfy electronic batch record requirements. REACH chemical safety obligations and EU Machinery Directive CE marking compel materials certification and operator safety interlock validation for chemical industry deployments. Stuttgart's precision engineering cluster concentrates servo-driven electromechanical system adoption for additive manufacturing applications.
Switzerland
Swiss pharmaceutical additive manufacturers specify vibratory feeder designs for active pharmaceutical ingredient dosing where particle integrity determines dissolution profiles. Swissmedic medical device regulations and EMA Annex 15 validation standards mandate containment integrity and cleaning verification protocols for continuous manufacturing equipment. Basel's life sciences corridor concentrates gravimetric system procurement for bioprocessing and precision dosing operations.
United States
FDA guidance on integrated continuous bioprocessing expands pharmaceutical demand for feeders with real-time release testing capabilities across New Jersey and Massachusetts biotech corridors. EPA environmental compliance and OSHA process safety management requirements shape chemical industry specifications for bulk material handling systems. Houston's petrochemical complex and Boston's biotech cluster represent contrasting demand profiles for standard versus precision gravimetric architectures.
China
Battery materials processing for lithium-ion cathode and anode slurry production creates precision additive feeding demand for conductive agents and binders outside traditional plastics and chemicals. NMPA pharmaceutical regulations and GB standards for industrial equipment safety influence specification requirements for domestic and export-oriented manufacturers. Yangtze River Delta chemical processors and Pearl River Delta electronics material compounders concentrate electromechanical system adoption.
India
CDSCO pharmaceutical manufacturing requirements and FSSAI food safety standards drive gravimetric feeder specification for domestic formulation and export-oriented generic drug production. Maharashtra's pharmaceutical belt and Gujarat's chemical corridor concentrate procurement of screw and vibratory architectures for continuous manufacturing and bulk material handling applications. Government PLI scheme incentives for specialty chemicals and active pharmaceutical ingredients accelerate technology modernization timelines.
Loss-In-Weight Feeder Market Competitive Landscape
On the supply side, the industry is structured around vertically integrated engineering houses with captive weighing electronics capabilities, mid-tier specialists in hygienic designs, and regional fabricators serving cost-sensitive bulk processing applications. Three strategic archetypes dominate: precision equipment specialists commanding premium positioning in pharmaceutical traceability applications, integrated systems providers bundling feeders with extrusion and compounding lines, and component-focused suppliers emphasizing load cell and control module standardization. Competitive moves concentrate on backward integration into weighing electronics manufacturing and technology licensing partnerships for IoT-enabled predictive maintenance platforms.
Among Germany and Switzerland-based integrated engineering houses, Coperion K-Tron, Schenck Process, and Gericke exemplify contrasting strategic positions. Coperion K-Tron occupies a position representing captive extrusion systems bundling, while Schenck Process exemplifies upstream control over weighing electronics and control software. Gericke represents specialization in hygienic design architectures for food and pharmaceutical regulatory environments. Merrick Industries Inc. and Acrison anchor North American competitive dynamics as regional precision equipment specialists.
| Leading Market Players |
|---|
| Merrick Industries Inc. |
| Gericke |
| Hapman |
| Acrison |
| Schenck Process |
| Novatec |
| GIMAT |
| Coperion K-Tron |
| FLSmidth |
| Others |
Value Network & Pricing Analysis
Stuttgart's precision engineering cluster channels servo-driven electromechanical system capacity toward pharmaceutical additive manufacturing, concentrating pricing power among German and Swiss OEMs with captive weighing electronics production. Load cell input volatility and semiconductor foundry constraints feed downstream into margin compression for mid-tier manufacturers lacking backward integration into sensor fabrication.
Pricing Analysis
Certification level creates the primary spread between FDA-grade pharmaceutical systems and standard chemical-processing architectures. Three-tier pricing structure across premium, standard, and economy levels segments by servo precision, hygienic design complexity, and after-sales service bundling. Cost compression in mid-tier electromechanical platforms is intensifying because load cell component shortages force margin sacrifice to maintain volume. Tier 2 compounders in Germany's automotive supply chain exhibit highest price sensitivity, while Swiss pharmaceutical additive manufacturers accept premium positioning for containment integrity.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from German engineering houses anchor working capital structures for downstream plastics processors. Component manufacturing concentrates in Germany, Switzerland, and China, with load cells and servo drives drawing from semiconductor foundries in Taiwan and South Korea. Single-source vulnerability in strain gauge sensor supply creates exposure to foundry capacity allocation decisions. Distribution runs through OEM-integrator partnerships with captive extrusion systems bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Loss-in-weight feeder adoption sits in early-cycle expansion across continuous manufacturing transitions, with FDA guidance on integrated bioprocessing and EMA traceability mandates accelerating replacement of volumetric systems.
For Market Incumbents: Build switching-cost moats through embedded RFID tracking and predictive maintenance platform lock-in. Deepen backward integration into weighing electronics manufacturing to defend against load cell cost volatility. Capture channel control by expanding equipment-as-a-service contracting for capital-constrained processors. For New Entrants and Emerging Players: Establish a beachhead in battery materials processing for lithium-ion cathode slurry production, where precision additive feeding demand outpaces established supplier coverage. Target conductive agent and binder feeding applications in China's Yangtze River Delta chemical processors. Lead with IoT-enabled remote diagnostics bundled into throughput-based pricing to bypass incumbent installed-base advantages. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors engineering houses with captive control software and hygienic design specialization. Long-term viability hinges on regulatory certification depth rather than commodity hardware scale. Acquisition targets should display vertical integration into weighing electronics or pharmaceutical containment expertise. Watch FDA guidance expansion on real-time release testing as inflection indicator for pharmaceutical gravimetric system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Weighing Electronics | Captive load cell production insulates margins from semiconductor foundry volatility. |
| IoT-Enabled Predictive Maintenance Platform | Edge computing convergence enables recurring revenue through throughput-based contracting. |
| Pharmaceutical Containment Certification Investment | EMA MDR traceability mandates require stainless-steel construction and sealed cable routing upgrades. |
| Battery Materials Processing Specialization | Lithium-ion cathode slurry production opens vertical demand outside traditional plastics. |
| Equipment-as-a-Service Model Expansion | Per-kilogram throughput fees address working capital constraints in Germany's automotive supply chain. |
Research Methodology
A standing panel of plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors provided ongoing calibration against operational deployment realities. Primary fieldwork combined structured interviews with secondary validation through customs data, SEC filings from listed engineering houses, and EMA regulatory guidance documents. Bottom-up triangulation across installation base estimates and top-down cross-check against capital expenditure disclosures anchored volume and value outputs.
Scenario-bracketing framed analytical approach across the projection horizon, with segmentation modeling across product type, industry vertical, technology architecture, and regional regulatory cluster. CAGRs derived from curve-fitting against historical replacement cycles and technology refresh patterns. Forecast inputs incorporated load cell component cost trajectories and pharmaceutical continuous manufacturing adoption curves.
Sensitivities concentrate around semiconductor foundry capacity allocation, EMA MDR enforcement timelines, and FDA guidance finalization on real-time release testing. Forecasts reflect documented assumptions on technology displacement rates and regional regulatory harmonization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Freshwater Flake Ice Machine Market
Food Processing Equipment
Brewing Boiler Market
Food Processing Equipment
Convection Ovens Market
Food Processing Equipment
UHT Systems Market
Food Processing Equipment
Alternative Protein Processing Equipment Market
Food Processing Equipment
French Fries Cutter Market
Food Processing Equipment
Commercial Winery Equipment Market
Food Processing Equipment
Chewing Gum Machine Market
Food Processing Equipment
Aseptic Processing Equipment Market
Food Processing Equipment
Commercial Panini Machine Market
Food Processing Equipment
Tunnel Oven Market
Food Processing Equipment
Global Conveyor Oven Market
Food Processing Equipment
Global Non-Thermal Pasteurization Market
Food Processing Equipment
Yogurt Makers Market
Food Processing Equipment
Hot Food Processing Equipment Market
Food Processing Equipment
Nut Processing Machine Market