
 Dispensing Systems and Equipment Market | 2026-2036
Dispensing Systems and Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Dispensing Systems and Equipment Market Analysis
Precision-grade dispensing specifications is rotating demand toward equipment capable of micro-liter accuracy and contamination-free operation. Nordson Corporation leverages its fluid management portfolio to sustain technology leadership in adhesive dispensing for electronics assembly. Graco Inc. anchors industrial-scale pump systems across manufacturing facilities, while Henkel AG & Co KGaA competes through integrated material-dispensing combinations that bind equipment with consumables.
Dispensing systems and equipment encompass machinery engineered to deliver controlled volumes of liquids, pastes, or gels through pneumatic, electronic, or mechanical actuation mechanisms, typically achieving tolerances within one percent for critical pharmaceutical and chemical applications. These systems serve primary industrial purposes spanning sterile drug filling, automated coating, and precise adhesive bonding in regulated production environments. Automated dispensers lead product-type configurations where throughput and repeatability command premium positioning, while pharmaceutical applications concentrate margin pools due to FDA validation requirements and batch integrity standards. Electronic technology segments are gaining fastest as servo-driven systems displace pneumatic alternatives in cleanroom-compatible installations.
FDA cGMP guidelines and EMA Annex 1 standards shape equipment design by mandating isolator-based filling and single-use fluid path components for sterile operations. EPA chemical handling regulations and OSHA workplace exposure limits further constrain material compatibility and ventilation specifications for industrial dispensing installations. Stakeholders must monitor evolving ESG disclosure requirements and carbon border adjustments that will reshape supplier qualification criteria and equipment sourcing decisions across regulated end-use sectors.
Market Dynamics
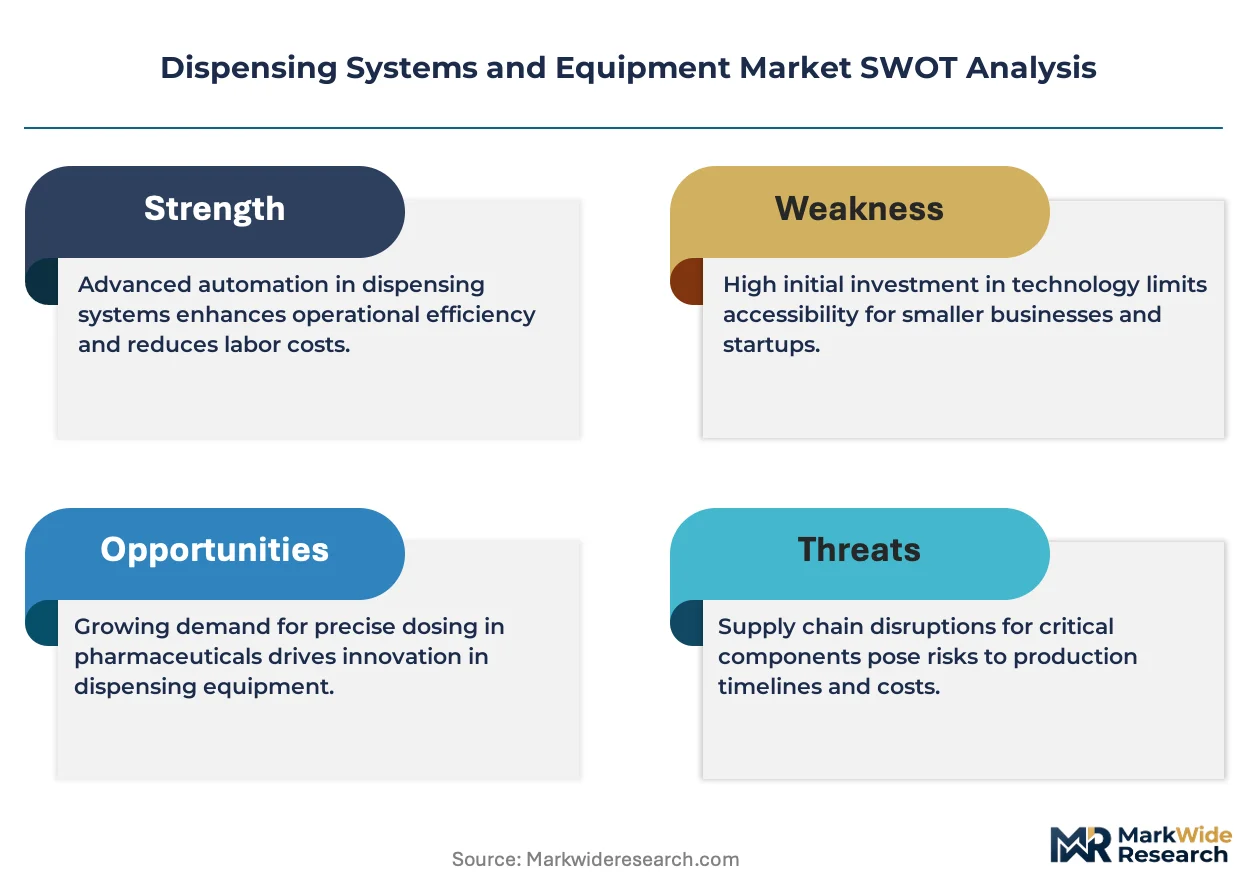
Servo-driven electronic dispensing systems are supplanting pneumatic alternatives across pharmaceutical cleanrooms, forcing capital retooling cycles and compressing margins for legacy equipment portfolios.
Growth Catalysts
- FDA cGMP Annex 1:The 2022 revision mandates isolator-based filling and single-use fluid paths, compelling sterile drug manufacturers to upgrade dispensing infrastructure.
- Biologics manufacturing:Cell and gene therapy production lines require micro-liter precision dosing that only advanced electronic dispensers can deliver.
- Germany's medical device cluster:Concentrated automation demand around Stuttgart and Munich sustains specialized equipment procurement for catheter and implant assembly.
Market Restraints
- Stainless steel supply concentration:Pharmaceutical-grade 316L sourcing depends on a narrow supplier base in Northern Europe, exposing equipment fabricators to alloy price volatility.
- EMA validation timelines:Extended qualification periods for aseptic filling equipment delay revenue recognition and strain working capital.
- Manual dispensing persistence:Low-volume generic drug facilities continue using operator-controlled systems, capping automation penetration in cost-sensitive segments.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for active pharmaceutical ingredient manufacturing are triggering greenfield facility investments requiring compliant dispensing systems.
- Continuous processing:Perfusion bioreactor adoption creates demand for real-time dosing integration that batch systems cannot support.
- Direct equipment leasing:Asset-light procurement models are emerging in mid-tier contract manufacturing organizations seeking to avoid capital commitment.
Industry Challenges
- Cross-functional talent scarcity:Engineers combining fluid dynamics expertise with FDA validation knowledge command premium compensation and extended search timelines.
- Legacy SCADA integration:New electronic dispensers must interface with decades-old plant control architectures, complicating commissioning and qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dispensing Systems and Equipment Market |
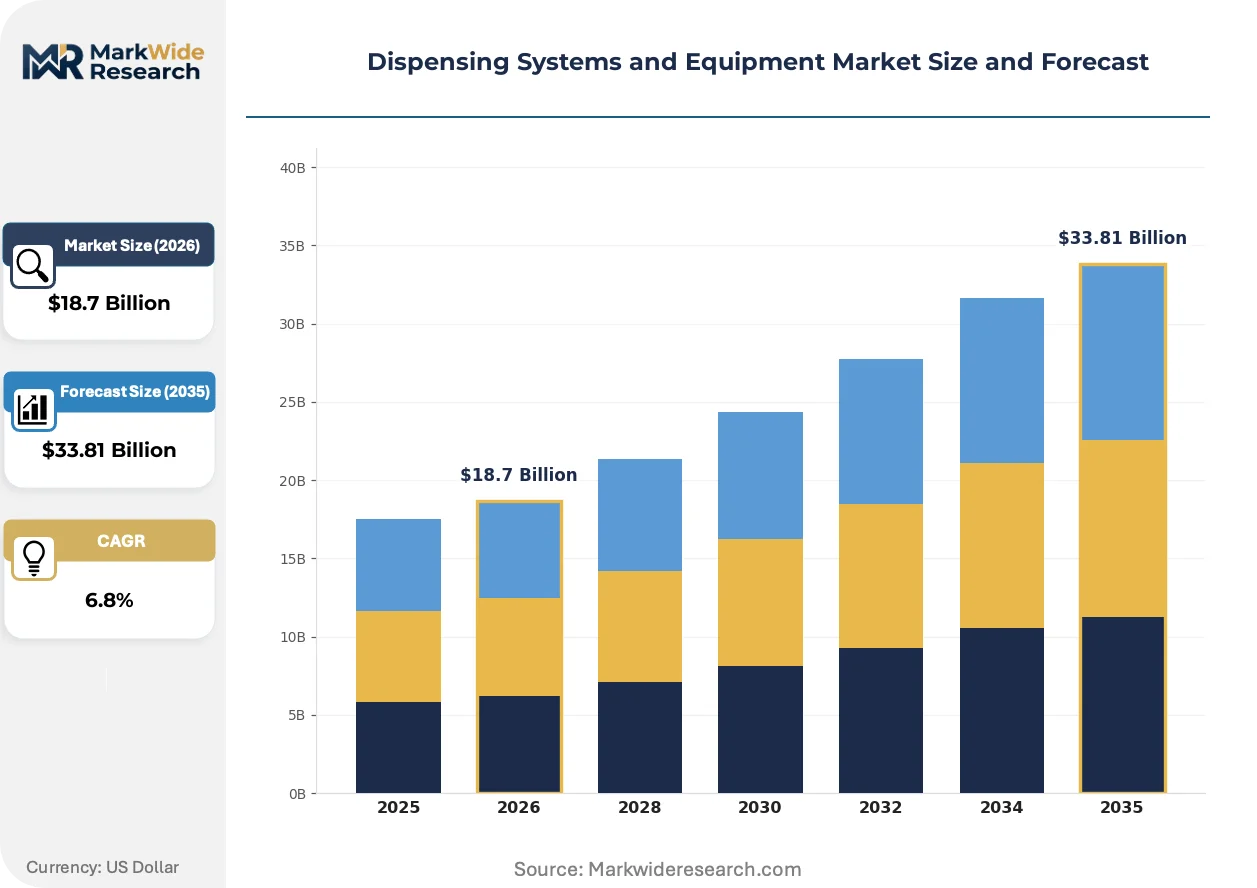
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Dispensers, Manual Dispensers, Dispensing Pumps, Vials Application: Pharmaceuticals, Food & Beverage, Chemicals, Cosmetics End User: Hospitals, Laboratories, Manufacturing Facilities, Retail Outlets Technology: Electronic, Mechanical, Pneumatic, Gravity-fed |
| Companies Covered | Techcon Systems, Sulzer Ltd., Nordson Corporation, ViscoTec Pumpen- und Dosiertechnik GmbH, Henkel AG & Co KGaA, Graco Inc., Dymax Corporation, Musashi Engineering, Inc., Fisnar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dispensing Systems and Equipment Market Emerging Trajectories
Precision requirements and contamination control standards are accelerating equipment architecture shifts. Three developments are restructuring competitive positioning and procurement patterns.
Single-use fluid path assemblies are supplanting fixed stainless steel manifolds in multi-product biologics facilities. Contract manufacturers facing frequent product changeovers adopt disposable contact surfaces to eliminate cleaning validation burdens. This shift compresses equipment lifecycle revenue while expanding recurring consumable streams.
REACH restrictions on perfluorinated compounds are constraining seal and gasket material options for chemical dispensing pumps. Equipment fabricators must qualify alternative elastomers without compromising chemical resistance profiles. European pharmaceutical and agrochemical end-users now require material composition disclosure as a standard procurement condition.
Service unbundling is fragmenting traditional equipment supply relationships. End-users are separating hardware acquisition from validation support and maintenance contracts, sourcing each element from specialized providers. This pattern is most pronounced in North American biotechnology clusters where venture-backed facilities prioritize operational flexibility over single-source accountability.
Dispensing Systems and Equipment Market Segmentation
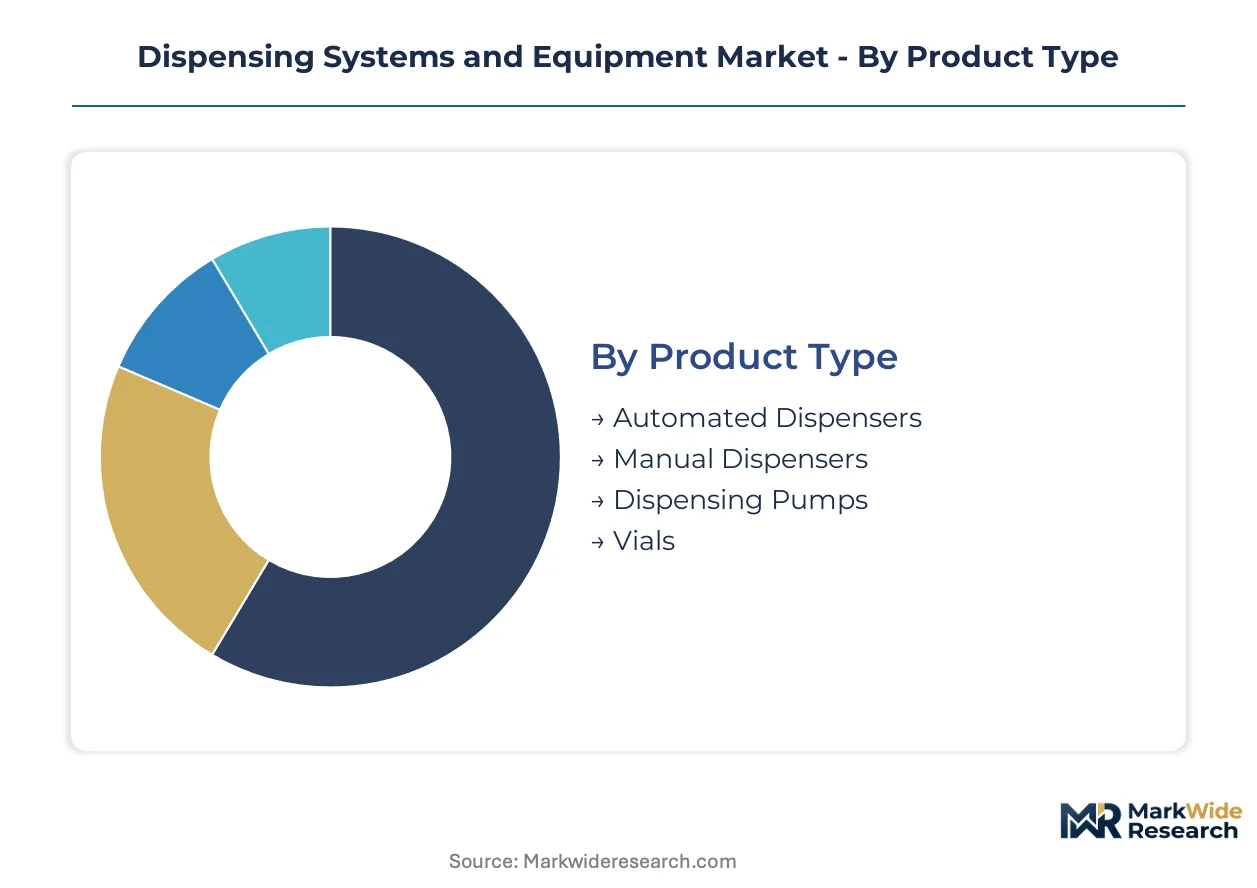
Dispensing equipment procurement patterns diverge sharply across product architectures and operational environments. Pharmaceutical manufacturers prioritize validated precision systems, while chemical processors balance throughput against material compatibility constraints.
Product Type:
Automated dispensers face intensifying substitution pressure from modular robotic platforms that integrate dispensing with upstream material handling.
- Automated Dispensers:Servo-driven systems achieve sub-microliter repeatability through closed-loop feedback control. Demand concentrates in German medical device clusters around Stuttgart, where catheter assembly lines require FDA-validated precision for adhesive bonding operations.
- Manual Dispensers:Operator-controlled systems persist in low-volume generic drug facilities and emerging market contract manufacturers. Indian API producers under the PLI scheme initially deploy manual systems before graduating to automated infrastructure, constraining near-term automation penetration.
- Dispensing Pumps:Peristaltic and piston pump architectures dominate sterile fluid transfer applications.
- Vials:Pre-sterilized container systems integrate dispensing closure mechanisms for point-of-use drug reconstitution.
Automated dispensers retain volume leadership; electronic pump systems hold the steepest expansion curve.
Application:
Margin concentration follows regulatory burden intensity, with aseptic pharmaceutical operations commanding premium equipment specifications.
- Pharmaceuticals:Sterile filling operations under FDA cGMP Annex 1 mandate isolator-based dispensing with single-use fluid paths. Biologics manufacturing in Massachusetts and North Carolina biotech corridors drives demand for micro-liter precision dosing that batch systems cannot support.
- Chemicals:Corrosive material handling requires specialized pump seals and ventilation integration. REACH restrictions on perfluorinated compounds force equipment fabricators to qualify alternative elastomers for European agrochemical processors.
- Food & Beverage:Volumetric filling systems achieve sanitary compliance through 3A-standard stainless steel construction.
- Cosmetics:Precision dosing for high-viscosity creams emphasizes repeatability over absolute accuracy.
Pharmaceutical applications capture the dominant margin pool; chemical processing expands most quickly in Asian manufacturing hubs.
End User:
Capital intensity and validation requirements create distinct procurement patterns across facility types.
- Manufacturing Facilities:Large-scale production environments integrate dispensing systems with SCADA architectures and MES platforms. Continuous processing adoption in perfusion bioreactor installations creates demand for real-time dosing integration that standalone batch dispensers cannot fulfill.
- Laboratories:Research and development environments prioritize flexibility over throughput. Contract research organizations in Boston and San Diego biotech clusters favor modular dispensing platforms that accommodate rapid protocol changes.
- Hospitals:Compounding pharmacies require USP-compliant sterile preparation systems.
- Retail Outlets:Point-of-sale dispensing emphasizes operator simplicity and maintenance minimization.
Manufacturing facilities dominate equipment procurement volume; laboratories generate the fastest technology refresh cycles.
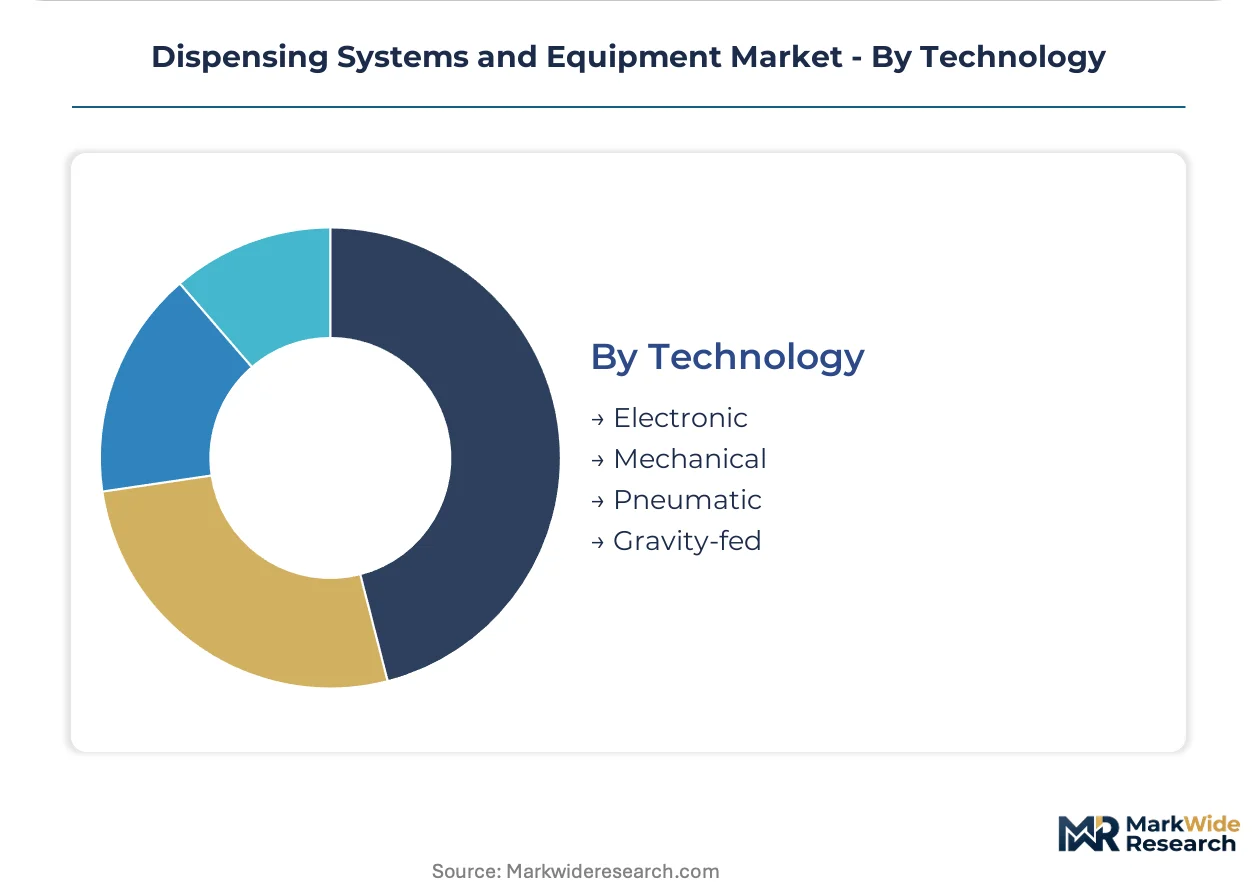
Technology:
Actuation mechanism selection determines cleanroom compatibility, precision ceiling, and total cost of ownership.
- Electronic:Servo-motor actuation delivers programmable stroke profiles and real-time force feedback. Pharmaceutical cleanrooms across Germany and Switzerland are displacing pneumatic alternatives with electronic systems to eliminate compressed air contamination risks.
- Pneumatic:Compressed air actuation persists in cost-sensitive industrial coating applications. Legacy installations in Midwest US automotive adhesive lines face retooling pressure as maintenance costs escalate.
- Mechanical:Cam-driven and screw-based systems offer simplicity for fixed-volume applications.
- Gravity-fed:Passive dispensing relies on head pressure and flow restriction for low-precision requirements.
Electronic technology commands the premium tier; pneumatic systems retain installed base dominance in industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment fabricators export precision dispensing systems to North American biotech clusters, while Indian pharmaceutical manufacturers import automated filling infrastructure under production-linked incentive schemes.
United States
Massachusetts and North Carolina biotech corridors drive demand for micro-liter precision dosing in cell and gene therapy manufacturing. FDA cGMP Annex 1 compliance mandates isolator-based sterile filling upgrades across existing facilities. Greater Boston contract research organizations favor modular dispensing platforms that accommodate rapid protocol changes.
Germany
Stuttgart and Munich medical device clusters sustain specialized procurement for catheter and implant assembly automation. EMA Annex 1 standards tighten material and process specifications for aseptic filling equipment validation. Baden-Württemberg anchors automated dispensing system production serving European pharmaceutical manufacturers.
India
Active pharmaceutical ingredient manufacturing expansion under the PLI scheme triggers greenfield facility investments requiring compliant dispensing infrastructure. CDSCO regulatory alignment with international standards pressures domestic equipment upgrading timelines. Gujarat and Maharashtra pharmaceutical clusters initially deploy manual systems before graduating to automated infrastructure.
China
Biologics manufacturing scale-up in Yangtze River Delta cities drives demand for contamination-free electronic dispensing systems. NMPA tightening of sterile drug filling standards accelerates replacement of pneumatic alternatives in cleanroom installations. Shanghai and Suzhou pharmaceutical parks concentrate precision equipment procurement for monoclonal antibody production.
Switzerland
Basel pharmaceutical headquarters operations command premium equipment specifications for high-value biologic filling. Swissmedic validation requirements for aseptic processing exceed baseline European standards, filtering supplier qualification. Zug and Basel-Land cantons concentrate precision dosing equipment demand for injectable drug manufacturing.
Dispensing Systems and Equipment Market Vendor Landscape
Listed leaders compete with private specialists across technology sophistication tiers, producing a bifurcated structure where public companies dominate capital-intensive scale segments and private fabricators capture niche precision applications. The vendor base stratifies into three archetypes: diversified industrial conglomerates with fluid management portfolios, dedicated dispensing technology specialists, and integrated material-equipment combination providers. M&A activity concentrates on acquiring electronic control capabilities, while geographic expansion targets Indian and Chinese pharmaceutical manufacturing corridors.
Among Germany-based precision specialists, ViscoTec Pumpen- und Dosiertechnik GmbH and Sulzer Ltd. exemplify the dedicated technology archetype, occupying positions in medical device automation clusters. Nordson Corporation represents the diversified industrial model with cross-sector fluid management capabilities. These three entities anchor distinct competitive vectors: precision dosing specialization, pump system integration, and multi-industry application breadth.
| Leading Market Players |
|---|
| Techcon Systems |
| Sulzer Ltd. |
| Nordson Corporation |
| ViscoTec Pumpen- und Dosiertechnik GmbH |
| Henkel AG & Co KGaA |
| Graco Inc. |
| Dymax Corporation |
| Musashi Engineering, Inc. |
| Fisnar Inc. |
| Others |
Supply Flow & Price Mechanics
FDA cGMP Annex 1 validation requirements gate both supplier qualification and price differentiation simultaneously, forcing equipment fabricators to absorb compliance costs while pharmaceutical buyers segment procurement across certified and uncertified tiers. Stainless steel 316L sourcing concentration in Northern Europe and servo-drive component dependence on German and Japanese suppliers create asymmetric pricing power that equipment manufacturers struggle to pass downstream.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on FDA validation tier and after-sales service bundling, with validated isolator-based systems commanding substantial premiums over unvalidated alternatives. Cost compression in the economy tier is intensifying because Indian API producers under the PLI scheme prioritize capital efficiency over precision specifications. Contract manufacturing organizations exhibit the highest price sensitivity, while Basel-headquartered biopharma operations demonstrate minimal elasticity for contamination-free guarantee.
Supply Chain Analysis
Germany and Switzerland anchor precision servo-drive and motion-control component fabrication for electronic dispensing systems. Equipment assembly draws from stainless steel 316L feedstock concentrated in Northern European foundries, elastomer seal suppliers constrained by REACH perfluorinated compound restrictions, and single-use fluid path consumables manufactured in cleanroom facilities across Massachusetts and North Carolina. Single-source vulnerability in pharmaceutical-grade alloy supply exposes fabricators to commodity price volatility. Distribution runs through authorized equipment integrators serving regional pharmaceutical clusters, with direct OEM relationships dominating high-value biologics installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dispensing equipment procurement is shifting toward platform-based interoperability, with Massachusetts and North Carolina biotech corridors demanding modular architectures that integrate with perfusion bioreactor control systems and manufacturing execution platforms.
For Market Incumbents: Consolidate electronic control capabilities through targeted acquisition of servo-drive specialists, as pneumatic legacy portfolios face accelerated displacement. Deepen backward integration into single-use fluid path consumables to capture recurring revenue streams that hardware commoditization threatens. Prioritize certification investment for isolator-based systems ahead of EMA Annex 1 enforcement timelines. For New Entrants and Emerging Players: Lead with continuous processing integration capabilities targeting mid-tier contract manufacturing organizations seeking asset-light procurement models. India's PLI scheme-triggered greenfield API facilities represent the most penetrable geography, with manual-to-automated graduation cycles creating equipment replacement windows. Pursue direct equipment leasing arrangements as the primary go-to-market mechanism, bypassing capital-intensive ownership barriers. For Investors and Strategic Acquirers: FDA cGMP Annex 1 compliance deadlines reshape the acquisition landscape toward validated precision specialists with established pharmaceutical customer relationships. Long-term viability centers on recurring consumable revenue attachment rates rather than standalone equipment margins. Target acquisition candidates with demonstrated servo-electronic portfolios and single-use fluid path integration. Monitor EMA validation timeline extensions as the critical inflection signal for working capital stress among equipment fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Single-Use Consumables | Captures recurring revenue streams from biologics facilities in Basel and Boston clusters. |
| Servo-Electronic Platform Standardization | Displaces pneumatic alternatives in German and Swiss pharmaceutical cleanrooms. |
| Direct Equipment Leasing Models | Addresses capital constraints among venture-backed CMOs in North American biotechnology corridors. |
| Continuous Processing Integration | Aligns with perfusion bioreactor adoption in cell and gene therapy manufacturing. |
| EMA Validation Pre-Certification Programs | Accelerates revenue recognition timelines for aseptic filling equipment deployments. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with pharmaceutical manufacturing executives, biomedical engineers, equipment procurement managers at contract manufacturing organizations, and aftermarket service directors. Secondary validation drew from FDA 483 observation databases, EMA inspection findings, CDSCO facility approval records, and SEC filings of listed industrial conglomerates with fluid management portfolios. Bottom-up equipment shipment data triangulated against top-down pharmaceutical capital expenditure surveys.
Across the analysis window, volume and value outputs reflect modeled segmentation across product architecture, actuation technology, application regulatory intensity, and end-user facility scale. CAGRs were derived from installed base replacement cycles, greenfield facility investment pipelines, and technology displacement curves. Forecast inputs incorporated servo-drive adoption rates in cleanroom installations and single-use fluid path penetration in multi-product biologics facilities.
Forecasts assume regulatory continuity in FDA cGMP Annex 1, EMA Annex 1, and NMPA sterile drug filling standards; material policy shifts would require re-modeling. Specific risk factors include REACH expansion to additional polymer classes, carbon border adjustment implementation affecting stainless steel sourcing economics, and biologics pipeline failures altering capital commitment timelines. Recalibration cycles align with material shifts in regulatory enforcement intensity and alloy commodity pricing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Reflow Oven Market
Food Processing Equipment
Ultrasonic Homogenizer Machines Market
Food Processing Equipment
Smart Bread Machine Market
Food Processing Equipment
Smart Bread Maker Market
Food Processing Equipment
North America Commercial Sous Vide Machine Market
Food Processing Equipment
Brewing Boiler Market
Food Processing Equipment
Cook Processor Market
Food Processing Equipment
North America Ginger Processing Market
Food Processing Equipment
Pizza Scissors Market
Food Processing Equipment
Food Ingredients Sterilization Market
Food Processing Equipment
Spiral Cooler Market
Food Processing Equipment
Bread Processing Equipment Market
Food Processing Equipment
Contact and Convective Dryers Market
Food Processing Equipment
Brewing Thermometer Market
Food Processing Equipment
Food Processing Blades Market
Food Processing Equipment
Commercial Oven for Bakery Market