
 Bottling Machinery Market | 2026-2036
Bottling Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Bottling Machinery Market Analytics
Asset-light leasing and pay-per-output contracting is tilting competitive dynamics toward vendors with strong balance sheets and service networks. Krones AG leverages its integrated digital platform to lock in long-term service revenue alongside equipment placement. Syntegon Technology GmbH sustains R&D intensity in aseptic and containment systems for pharmaceutical-grade applications. GEA Group Aktiengesellschaft anchors its position through backward integration into hygienic component manufacturing.
Bottling machinery comprises integrated systems designed to fill, cap, label, and package liquid, viscous, or powdered products into rigid or flexible containers at speeds ranging from 1,000 to 120,000 units per hour depending on configuration. These systems serve as critical production nodes in continuous-flow manufacturing environments where sterility, fill accuracy, and throughput directly determine operational economics. Rotary systems dominate high-volume beverage installations where speed and footprint efficiency determine total cost of ownership. Aseptic technology commands premium positioning as dairy and pharmaceutical end users eliminate preservatives and extend shelf life. Automatic fillers represent the mature revenue base, while labeling machines face margin pressure from modular retrofit upgrades rather than greenfield demand.
FDA cGMP guidelines and EU MDR standards shape equipment validation protocols for pharmaceutical bottling lines, extending sales cycles but creating switching-cost barriers for incumbent suppliers. EPA effluent regulations and OSHA noise exposure limits influence stainless-steel finishing specifications and enclosure designs across US installations. Buyers must weigh total lifecycle service commitments against upfront capital outlays as financing structures fragment vendor risk profiles.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant choices for cold-fill bottling lines, forcing simultaneous retooling of compressor systems and line controls while aseptic technology expands into shelf-stable dairy and plant-based beverages.
Growth Catalysts
- Aseptic filling systems:Beverage manufacturers are eliminating preservatives from dairy and plant-based drinks, requiring sterile barrier technology that extends shelf life without refrigeration. This drives replacement cycles across North American and European dairy operations.
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is mandating low-global-warming-potential alternatives in cold-fill installations, creating equipment refresh demand as existing lines face compliance deadlines.
- German machinery cluster:Dense supplier concentration around Munich and Hamburg accelerates component sourcing, technical service response times, and specialized labor pools that shorten project delivery schedules.
Market Restraints
- Stainless steel input volatility:Grade 316L and 304 price swings compress margin predictability for hygienic component fabricators, particularly affecting rotary filler and capper manufacturers with fixed-price contract exposure.
- Precision component supply concentration:High-speed servo motors, magnetic flow meters, and HMI controllers concentrate among Japanese and German suppliers, creating single-source vulnerability for throughput-critical subsystems.
- Pharmaceutical validation friction:FDA cGMP and EU MDR compliance documentation extends sales cycles 6-18 months for aseptic pharmaceutical lines, delaying revenue recognition and inflating pre-sale engineering costs.
Strategic Opportunities
- India packaged beverage expansion:FSSAI enforcement of stricter hygiene standards and rising PET bottling demand in Maharashtra and Gujarat create greenfield opportunities for aseptic and hot-fill line suppliers.
- Digital twin convergence:Integration of real-time line simulation with predictive maintenance platforms is enabling remote commissioning and virtual FAT protocols that reduce travel-dependent service costs.
- US IRA clean manufacturing credits:Energy-efficient blower-filler-capper integration qualifies for Section 48C tax credits, improving project ROI calculations for domestic beverage capital expenditure committees.
Industry Challenges
- Mechatronics skill scarcity:Servo programming, hygienic welding certification, and sterile barrier validation expertise concentrate among aging technicians in Germany and Switzerland, constraining service network expansion.
- Legacy SCADA integration friction:Brownfield installations require protocol translation between proprietary filler controls and plant-level MES systems, inflating commissioning timelines and acceptance testing complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottling Machinery Market |
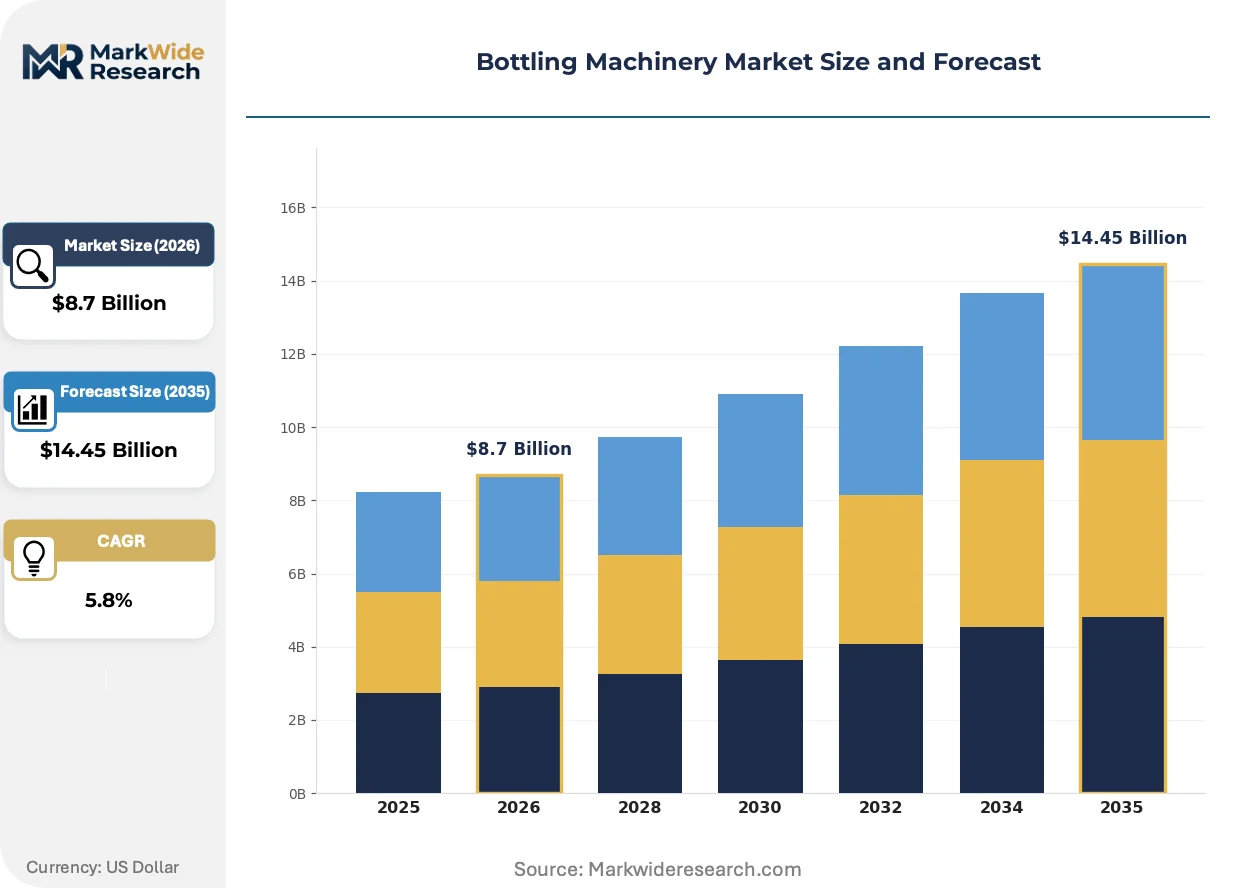
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Fillers, Semi-Automatic Fillers, Labeling Machines, Capping Machines End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Technology: Rotary Systems, Linear Systems, Vacuum Systems, Aseptic Technology Application: Liquid Bottling, Powder Filling, Viscous Product Filling, Alcoholic Beverages |
| Companies Covered | Krones AG, Tetra Laval Group, Syntegon Technology GmbH, KHS Group, Coesia Group, ProMach, Barry-Wehmiller Group, GEA Group Aktiengesellschaft, Sacmi Imola, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottling Machinery Market Evolving Landscape
Electrification of mechanical functions, regulatory compression of refrigerant options, and servitization of vendor-buyer relationships are restructuring how bottling capacity is procured, operated, and upgraded across beverage and pharmaceutical end uses.
Electromagnetic flow metering is hybridizing with Coriolis mass flow technology in high-viscosity applications. Pharmaceutical and nutraceutical bottlers operating shear-sensitive products are adopting hybrid measurement systems that combine non-contact electromagnetic sensors with direct mass verification. This dual-technology approach is hybridizing equipment specifications, enabling single fillers to handle both aqueous and viscous formulations without mechanical changeover.
EU F-Gas Regulation mandates are accelerating heat pump and CO2 transcritical system adoption in cold-fill lines. The phasedown schedule forces beverage producers to abandon R-404A and R-507A before 2030, triggering parallel upgrades to compressor packages and line controls. German and Dutch dairy bottlers are most affected, with retrofit demand concentrating in facilities built during the 2010-2015 capacity expansion wave.
After-sales service unbundling is fragmenting traditional vendor lock-in. Beverage producers in Brazil and Mexico are separating spare parts procurement, technical training, and emergency response into discrete contracts, enabling third-party service providers to capture maintenance revenue previously captured by OEMs. This disaggregation pressures machinery suppliers to defend position through proprietary digital platforms and encrypted component authentication rather than geographic service density alone.
Bottling Machinery Market Segmentation
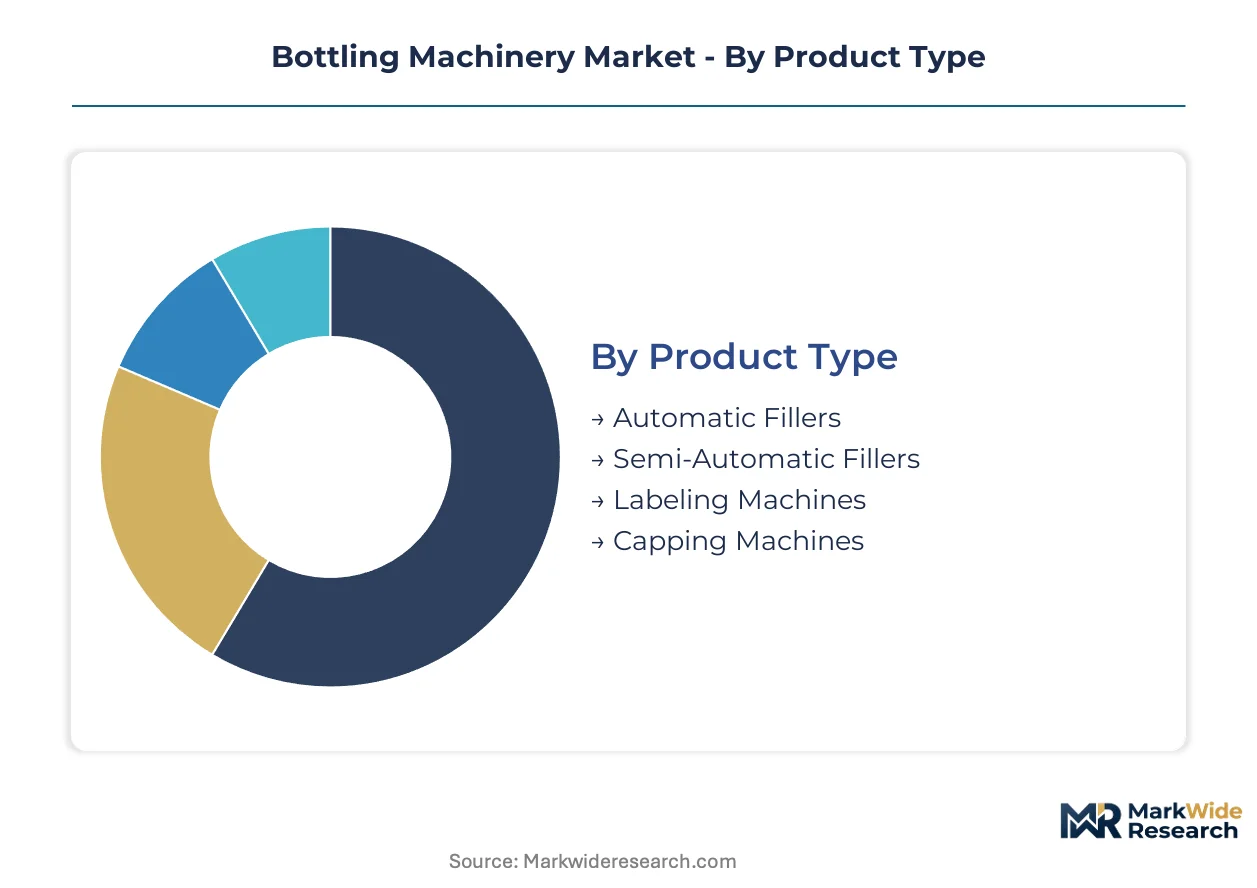
Bottling machinery segmentation reveals distinct equipment economics across product categories. Technology choices determine capital intensity and service revenue potential. End-use specialization creates divergent regulatory compliance burdens and margin profiles.
Product Type:
Equipment automation levels span from operator-dependent semi-automatic stations to fully integrated rotary fillers serving 100,000+ units per hour.
- Automatic Fillers:High-speed rotary and linear configurations integrate servo-driven valve clusters with electromagnetic flow metering for precision dosing. Beverage bottlers in Germany and the Netherlands deploy these for carbonated soft drinks and mineral water where throughput determines line economics.
- Labeling Machines:Pressure-sensitive, sleeve, and hot-melt adhesive systems apply primary and secondary decoration at speeds matching filler output. Demand concentrates in retrofit upgrades rather than greenfield installations as beverage producers extend existing line life through modular control replacements.
- Semi-Automatic Fillers:Piston and gravity-fed benchtop units serve craft distilleries and regional dairy processors with batch volumes below 5,000 units per shift.
- Capping Machines:Chuck, snap, and ROPP closure systems complete the sterile barrier or carbonation seal depending on product specification.
Established volume favors Automatic Fillers; emerging adoption favors Labeling Machines through retrofit demand.
End User:
Regulatory stringency and sterility requirements fragment customer economics across application categories.
- Food & Beverage:Dairy, soft drink, and brewing operations drive the largest installed base with aseptic and hot-fill lines dominating capital expenditure. EU F-Gas Regulation compliance deadlines in Germany and the Netherlands accelerate cold-fill line refurbishment for shelf-stable products.
- Pharmaceuticals:Injectable, oral solid dose, and ophthalmic bottling demand isolator technology and continuous particle monitoring. FDA cGMP and EU MDR validation protocols extend sales cycles but create substantial switching costs for incumbent suppliers.
- Cosmetics:Viscous creams, serums, and fragrance filling requires piston and peristaltic pump configurations with quick-clean protocols for batch changeovers.
- Chemicals:Corrosive, flammable, and agrochemical formulations mandate explosion-proof enclosures and specialty alloy construction for safety compliance.
Food & Beverage captures the dominant equipment volume; Pharmaceuticals delivers the steepest expansion trajectory through aseptic technology upgrades.
Technology:
Mechanical architecture determines footprint efficiency, changeover flexibility, and sterile barrier capability.
- Aseptic Technology:Hydrogen peroxide vapor, UV, and e-beam sterilization integrated with laminar flow isolators enables preservative-free packaging. Dairy and plant-based beverage producers in Germany and India deploy these systems to extend shelf life without cold chain dependency.
- Rotary Systems:Circular turret configurations with 40-120 stations maximize output per square meter for high-volume carbonated and still water bottling. The German machinery cluster around Munich supplies precision cam-driven turrets with sub-50-millisecond fill cycle consistency.
- Linear Systems:Straight-line indexing accommodates irregular container geometries and frequent size changes for contract packagers serving multiple brands.
- Vacuum Systems:Negative pressure filling handles foam-prone products and precise level control for high-value spirits and fragrances.
Rotary Systems anchor current revenue concentration; Aseptic Technology is climbing the fastest as dairy and pharmaceutical end users eliminate preservatives.
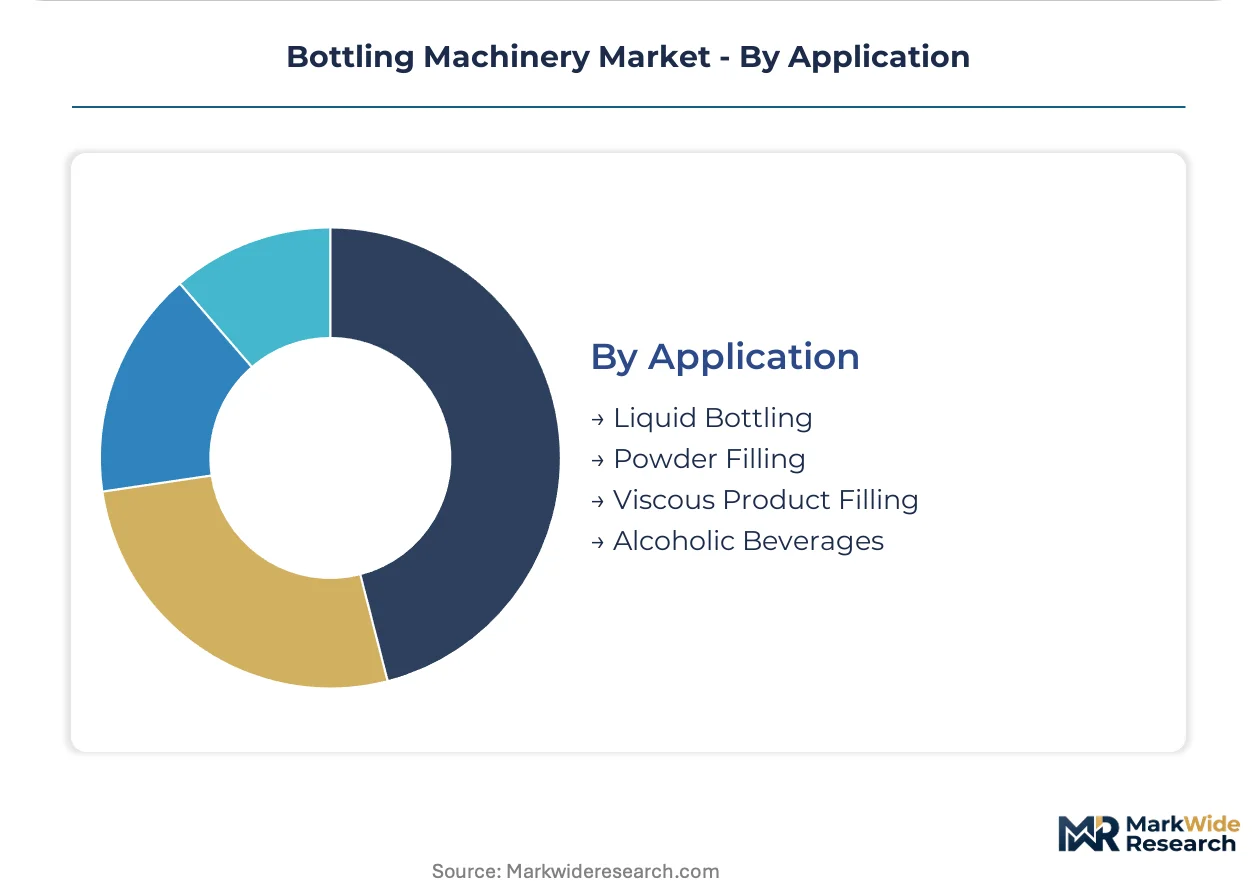
Application:
Product physical state and shelf-stability requirements dictate filler specification and downstream packaging integration.
- Liquid Bottling:Water, juices, and dairy flow through gravity, pressure, or vacuum fillers with volumetric or mass-based measurement. Demand concentrates in aseptic configurations for ambient distribution in India and extended-shelf-life dairy in Germany.
- Viscous Product Filling:Sauces, condiments, and personal care emulsions require positive-displacement pumps with heated product paths to maintain flow characteristics. Coriolis mass flow hybridization with electromagnetic metering enables single-platform flexibility for contract manufacturers.
- Alcoholic Beverages:Wine, spirits, and beer bottling combines inert gas pre-purge with level-based or volumetric fill control to minimize oxidation and ensure tax-compliant fill tolerances.
- Powder Filling:Auger and cup systems dose free-flowing and non-free-flowing solids into rigid containers with dust containment and checkweigh feedback.
Liquid Bottling maintains the largest equipment base; Viscous Product Filling gains share fastest through hybrid metering technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clean manufacturing incentives and refrigerant phaseout mandates are redirecting capital expenditure toward compliant bottling infrastructure across major production economies.
Germany
Aseptic dairy line upgrades and plant-based beverage capacity expansion drive equipment procurement in Bavaria and Hamburg. The EU F-Gas Regulation compels cold-fill line retooling by 2030 deadlines. Munich anchors a dense machinery cluster where Krones AG and KHS Group coordinate component sourcing and specialized technician training.
United States
Energy-efficient blower-filler-capper integration attracts IRA Section 48C tax credit claims from beverage capital committees. FDA cGMP validation protocols extend pharmaceutical line sales cycles. Wisconsin and California host concentrated dairy and craft beverage bottling operations retrofitting for extended shelf-life production.
India
FSSAI enforcement of stricter hygiene standards accelerates PET bottling demand in Maharashtra and Gujarat. The PLI scheme for food processing machinery reduces import dependency for aseptic line components. Ahmedabad and Mumbai emerge as greenfield installation hubs for ambient distribution dairy and juice operations.
China
Dual carbon goals and provincial energy efficiency mandates reshape cold-fill line specifications in Yangtze River Delta beverage plants. NMPA pharmaceutical packaging regulations elevate isolator technology requirements. Shanghai and Guangzhou concentrate dairy and nutraceutical bottling capacity requiring sterile barrier upgrades.
Brazil
After-sales service unbundling fragments traditional vendor lock-in across São Paulo and Minas Gerais beverage operations. ANVISA pharmaceutical packaging standards extend equipment validation timelines. Contract packagers in Campinas separate spare parts procurement and technical training into discrete supplier agreements.
Bottling Machinery Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a consolidated vendor base where integrated digital platforms determine long-term service revenue capture. The market structures around three archetypes: full-line system integrators with captive component manufacturing, aseptic technology specialists serving pharmaceutical validation requirements, and regional fabricators competing on delivery speed and customization flexibility. M&A activity concentrates on digital twin and predictive maintenance capabilities, while strategic partnerships lock in refrigerant transition engineering for EU F-Gas compliance.
Within the full-line system integrator tier, Krones AG exemplifies channel control through integrated digital platforms that capture service revenue alongside equipment placement. Syntegon Technology GmbH occupies a position among aseptic specialists, anchoring pharmaceutical-grade containment system development. KHS Group represents the machinery cluster concentration that shortens component sourcing and technical response times for European beverage producers.
| Leading Market Players |
|---|
| Krones AG |
| Tetra Laval Group |
| Syntegon Technology GmbH |
| KHS Group |
| Coesia Group |
| ProMach |
| Barry-Wehmiller Group |
| GEA Group Aktiengesellschaft |
| Sacmi Imola |
| Others |
Value Network & Pricing Analysis
Stainless steel input volatility in Grade 316L and 304 determines both pricing tier spreads and supply chain shape for bottling machinery manufacturers, compressing margin predictability for hygienic component fabricators while forcing procurement hedging strategies across German and Japanese supplier networks.
Pricing Analysis
Certification level (FDA-grade, EU MDR-compliant, ISO-standard) creates the primary spread between premium aseptic lines and standard carbonated beverage fillers. Three-tier pricing structure across premium, standard, and economy levels reflects validation documentation intensity, with pharmaceutical-grade systems commanding substantial premiums over dairy applications. Cost compression in mid-tier rotary fillers is intensifying because Brazilian and Mexican buyers unbundle after-sales service contracts. Craft distilleries and regional dairy processors exhibit highest price sensitivity, while multinational beverage conglomerates prioritize lifecycle service commitments over upfront capital outlays.
Supply Chain Analysis
Extended payment terms from 90 to 180 days now dominate capital equipment procurement, with supply-chain finance facilities increasingly intermediating transactions between German machinery clusters and Indian greenfield buyers. Component sourcing concentrates in Germany, Japan, and Switzerland for high-speed servo motors, magnetic flow meters, and HMI controllers. Stainless steel Grade 316L, precision cam assemblies, and hydrogen peroxide vapor sterilization modules constitute critical input dependencies. Single-source vulnerability for throughput-critical subsystems creates structural risk. Distribution runs through direct OEM sales teams for pharmaceutical lines and regional distributor networks for beverage applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin and predictive maintenance service layers are expanding faster than hardware placements, creating recurring-revenue multiples that justify platform investments ahead of pure equipment sales.
For Market Incumbents: Harden proprietary digital platforms against third-party service disaggregation by encrypting component authentication and locking spare parts compatibility. Backward integration into hygienic component manufacturing defends margin position against stainless steel price swings. Prioritize certification investment in FDA-grade and EU MDR validation capabilities to extend switching-cost barriers. For New Entrants and Emerging Players: India's Maharashtra and Gujarat bottling corridors present underpenetrated greenfield demand for aseptic PET lines as FSSAI enforcement tightens. Target contract packagers requiring linear system flexibility for frequent size changes across multiple brands. Pursue pay-per-output financing partnerships to bypass capital expenditure committee resistance. For Investors and Strategic Acquirers: EU F-Gas Regulation phasedown deadlines reshape the acquisition landscape toward refrigerant transition engineering capabilities and heat pump integration expertise. Long-term viability centers on vendors with installed base density sufficient to capture digital service revenue. Monitor cold-fill line refurbishment order backlogs in Germany and the Netherlands as inflection indicators for equipment refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Virtual FAT protocols reduce commissioning costs for remote pharmaceutical line installations. |
| Refrigerant Transition Engineering | EU F-Gas compliance deadlines force parallel compressor and control upgrades in German dairy plants. |
| Aseptic Containment Certification | FDA cGMP validation creates switching-cost barriers for incumbent pharmaceutical suppliers. |
| Pay-per-Output Contracting | Asset-light financing structures favor vendors with strong balance sheets and dense service networks. |
| Hybrid Metering Technology Development | Coriolis-electromagnetic fusion enables single-filler flexibility for contract manufacturers. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers, aftermarket service heads, OEM procurement teams, and beverage operations directors, and refined through secondary validation across SEC filings, VDMA machinery statistics, customs trade data, and EU regulatory implementation notices. Bottom-up equipment shipment tracking and top-down capital expenditure analysis were triangulated to reconcile volume estimates.
Demand-supply balance modeling across the analysis window incorporated technology type (aseptic, rotary, linear, vacuum), end-use vertical (food and beverage, pharmaceutical, cosmetics, chemicals), and automation tier. CAGRs were derived from installed base replacement cycles and greenfield capacity announcements. Forecast inputs included EU F-Gas compliance deadlines, FSSAI enforcement timelines, and IRA Section 48C credit uptake rates.
Macroeconomic conditions sit as an overlay; deviation in stainless steel commodity indices, interest rate environments affecting equipment financing, or regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about replacement cycle timing and greenfield investment appetite. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Brining Systems Market
Food Processing Equipment
Commercial Food Processors Market
Food Processing Equipment
Global Industrial Food Blanchers Market
Food Processing Equipment
Portioning Machines Market
Food Processing Equipment
Food Industry Pulsed Electric Field (PEF) Systems Market
Food Processing Equipment
De-Agglomerating Equipment Market
Food Processing Equipment
Countertop Food Blenders Market
Food Processing Equipment
Spray Drying Equipment Market
Food Processing Equipment
Europe Household Food Waste Composting Machine Market
Food Processing Equipment
Destemmer Market
Food Processing Equipment
Pasta Machine Market
Food Processing Equipment
Industrial Steam Peeler Market
Food Processing Equipment
Food Ingredients Sterilization Market
Food Processing Equipment
India Household Flour Milling Machines Market
Food Processing Equipment
Flakes Making Machine Market
Food Processing Equipment
North America Commercial Sous Vide Machine Market