
 Bovine Tuberculosis Diagnosis Market | 2026-2036
Bovine Tuberculosis Diagnosis Market Size, Share, and Industry Trends Forecast 2026-2036
Bovine Tuberculosis Diagnosis Market Intelligence
Multi-source procurement of diagnostic reagents is realigning supply relationships across the bovine tuberculosis testing value chain. IDEXX Laboratories leverages its channel density in North American veterinary networks to sustain kit availability. Zoetis anchors its position through backward integration into antigen production, reducing batch-to-batch variability.
Bovine tuberculosis diagnosis encompasses laboratory and field-based detection methods for Mycobacterium bovis infection in cattle, employing skin tuberculin reactions, serological assays with purified protein derivative antigens, and nucleic acid amplification targeting IS6110 insertion sequences to enable herd-level disease surveillance and international trade certification. The interferon gamma test segment occupies premium positioning in confirmatory protocols for high-value breeding stock, while PCR-based molecular assays are displacing culture methods in reference laboratories due to turnaround time advantages. Point-of-care delivery modes compete on labor cost reduction in remote pastoral regions where laboratory infrastructure remains sparse.
The OIE Terrestrial Animal Health Code shapes cross-border movement standards for tuberculosis-free herd certification, while national regulators including the USDA and EFSA enforce slaughterhouse surveillance mandates that sustain baseline testing volumes. Stakeholders must monitor divergence between WHO-endorsed tuberculosis elimination timelines and national eradication program funding commitments that dictate diagnostic procurement cycles.
Market Dynamics
The European Union's F-Gas Regulation and MDR frameworks are forcing diagnostic equipment manufacturers to redesign cooling systems and recertify assay platforms, compressing product development cycles while elevating compliance costs across the bovine tuberculosis testing supply chain.
Growth Catalysts
- USDA slaughterhouse surveillance mandates:Federal inspection protocols sustain baseline testing volumes at federally inspected facilities, creating recurring demand for tuberculin reagents and interferon gamma assay kits.
- Brazil's southern cattle states:Paraná and Rio Grande do Sul are expanding herd certification programs for export eligibility to China and the European Union, driving field-deployable diagnostic procurement.
- IS6110-targeted PCR assays:Nucleic acid amplification technology is compressing turnaround times from weeks to hours in reference laboratories, enabling same-day quarantine decisions for suspect animals.
Market Restraints
- Purified protein derivative antigen supply concentration:Batch-to-batch variability in tuberculin production creates diagnostic inconsistency, with only three qualified suppliers serving international markets.
- CE-IVDR transition costs:The European Union's In Vitro Diagnostic Regulation reclassification of bovine tuberculosis assays as Class C devices imposes clinical evidence requirements that smaller manufacturers cannot absorb.
- Culture-based confirmatory testing:Mycobacterium bovis isolation remains the OIE gold standard despite six-to-eight-week incubation periods, limiting throughput in high-volume screening programs.
Strategic Opportunities
- India's Uttar Pradesh dairy belt:The country's largest milk-producing state lacks centralized laboratory infrastructure, creating demand for point-of-care platforms that operate without cold chain dependency.
- Interferon gamma-ELISA convergence:Combining cellular immunity detection with enzyme-linked serological readouts offers multiplexing potential for concurrent pathogen screening.
- EU Green Deal agricultural transition incentives:Carbon-neutral farm certification programs are bundling disease-free herd status with sustainability premiums, expanding voluntary testing beyond regulatory minimums.
Industry Challenges
- Veterinary diagnostic technician shortages:Rural laboratories in Australia's Northern Territory and Canada's Prairie Provinces struggle to staff bovine tuberculosis screening programs, delaying test result reporting.
- Cross-reactivity with environmental mycobacteria:Nontuberculous mycobacterial exposure in tropical pastures generates false-positive skin test reactions, complicating herd clearance decisions in Brazil's Pantanal region.
- Legacy data system integration:National animal identification databases in Argentina and New Zealand use incompatible formats, obstructing traceability for international trade certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bovine Tuberculosis Diagnosis Market |
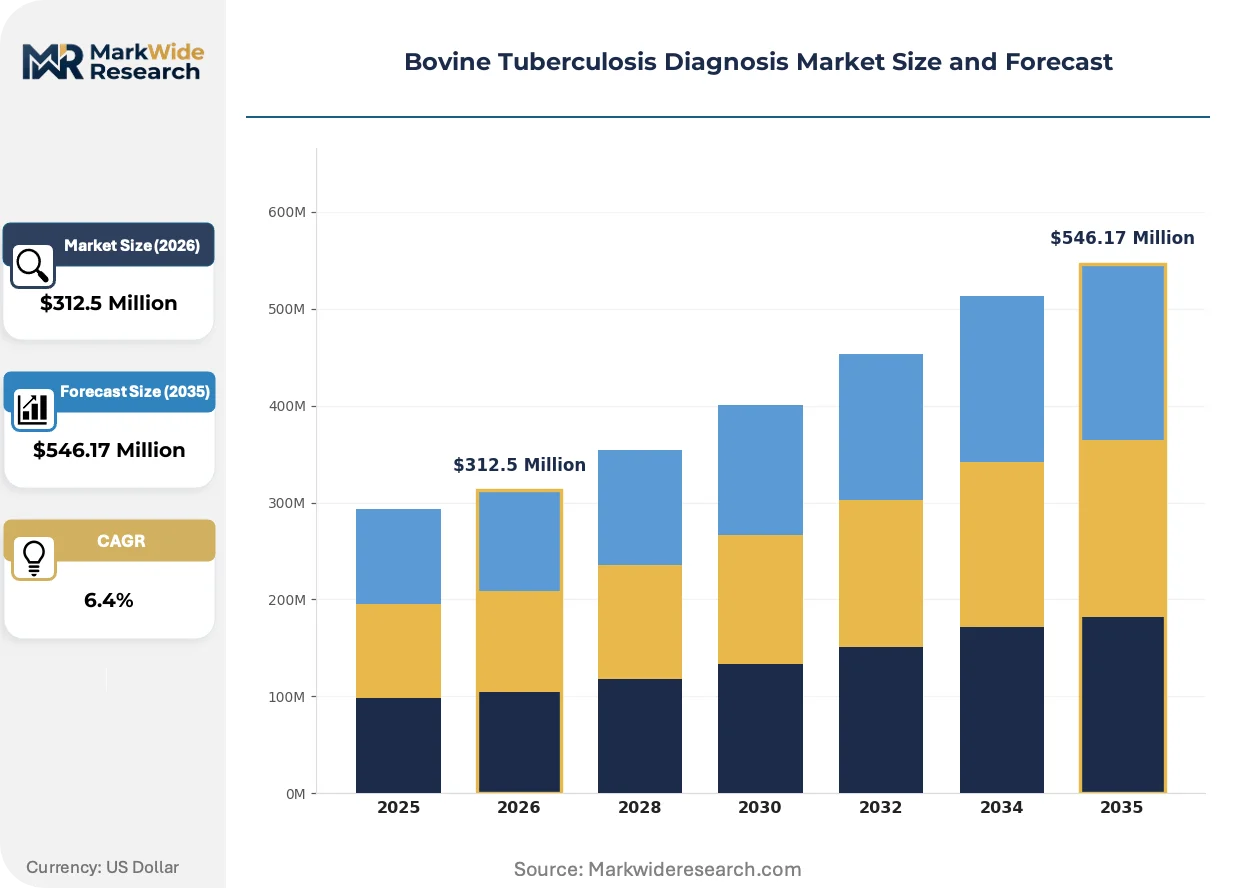
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Skin Test, Blood Test, Interferon Gamma Test, PCR Test End User: Veterinary Clinics, Research Laboratories, Livestock Farms, Diagnostic Centers Technology: ELISA, LAMP, Culture Method, Molecular Assays Delivery Mode: Point-of-Care, Laboratory Testing, Home Testing, Mobile Testing Units |
| Companies Covered | IDEXX Laboratories, Zoetis, Thermo Fisher Scientific, PBD Biotech, Innovative Diagnostics, Bio-Rad Laboratories, Enfer Group, IDvet, Neogen Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bovine Tuberculosis Diagnosis Market Strategic Shifts & Innovations
Laboratory infrastructure constraints in pastoral regions are accelerating adoption of portable molecular platforms, while regulatory convergence around OIE standards is harmonizing test interpretation protocols across major beef and dairy exporting nations.
Loop-mediated isothermal amplification (LAMP) technology targets IS6110 and MPB70 gene sequences without thermal cycling equipment, enabling nucleic acid detection in field stations lacking real-time PCR capacity. Veterinary services in Ethiopia's Borana pastoral zone and Mongolia's Khövsgöl province are deploying battery-powered LAMP devices for remote herd screening. This platform is decentralizing confirmatory testing authority from centralized reference laboratories to district-level veterinary officers, compressing response times for quarantine implementation.
REACH restrictions on perfluorinated compounds are compelling manufacturers to reformulate diagnostic reagent stabilizers and replace fluorinated cold chain packaging, with compliance deadlines cascading through 2026. The European Chemicals Agency's authorization requirements are elevating substitution costs for assay kit producers serving EU member states. High-throughput laboratories in Germany's Bavaria and France's Brittany regions are prioritizing suppliers with verified fluorine-free formulations to preempt supply disruption.
Dairy cooperatives in the Netherlands and Ireland are consolidating diagnostic procurement through centralized tendering platforms, aggregating testing volumes across member farms to negotiate volume-based pricing. This aggregation is displacing individual farm-level kit purchasing through veterinary clinics, compressing distributor margins while elevating manufacturer direct engagement requirements. The procurement consolidation is most visible in Ireland's Dairygold and Netherlands' FrieslandCampina supply bases, where cooperative-managed testing now exceeds fifty percent of regional volume.
Bovine Tuberculosis Diagnosis Market Segmentation
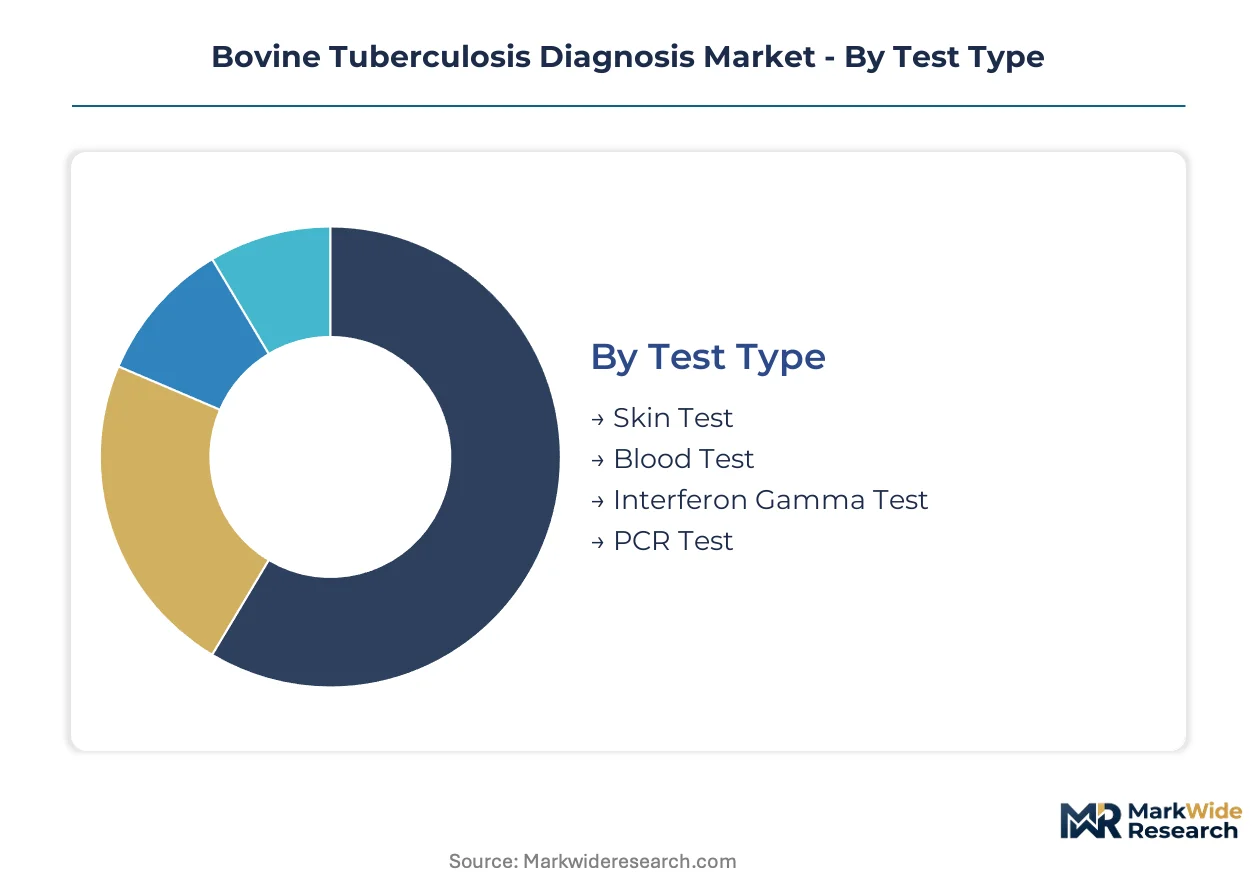
Diagnostic procurement patterns in bovine tuberculosis testing diverge sharply between centralized reference laboratories and decentralized field operations. Test type selection hinges on turnaround requirements, equipment availability, and regulatory acceptance for trade certification. Understanding these segment boundaries clarifies where manufacturers must configure product portfolios versus where standardization prevails.
Test Type:
Standardization dominates skin-based protocols, while molecular platforms permit customization through primer design and amplification targets.
- Skin Test:Intradermal tuberculin injection measuring delayed hypersensitivity reactions at 72 hours. Demand concentrates in Brazil's Paraná and Rio Grande do Sul states where field veterinarians require equipment-free screening for export herd certification under China's sanitary protocols.
- Blood Test:Serological detection of antibodies against MPB70 and MPB83 antigens. Adoption is accelerating in India's Uttar Pradesh dairy belt where cold chain-independent sample collection suits cooperative-managed surveillance programs lacking laboratory infrastructure.
- Interferon Gamma Test:Whole blood cytokine release assay for cellular immunity detection.
- PCR Test:IS6110-targeted nucleic acid amplification for confirmatory diagnosis.
Most installed capacity flows through Skin Test. Expansion is steepest in Blood Test.
End User:
Customer concentration varies from fragmented farm-level purchasing to consolidated tendering by cooperative networks.
- Veterinary Clinics:Primary access point for individual producers requiring regulatory compliance testing. Procurement in Ireland's Dairygold and Netherlands' FrieslandCampina supply bases is shifting toward cooperative-managed aggregation, compressing clinic-level kit volumes.
- Research Laboratories:Validation studies and assay development for new antigen targets. Activity clusters at Germany's Friedrich-Loeffler-Institut and France's ANSES Maisons-Alfort for OIE reference reagent standardization.
- Livestock Farms:On-site testing for high-value breeding stock in closed herds.
- Diagnostic Centers:High-throughput regional screening facilities processing slaughterhouse surveillance samples.
Veterinary Clinics retain the largest installed base. Research Laboratories are gaining share fastest through regulatory validation contracts.
Technology:
Method selection trades capital intensity against throughput and biosafety containment requirements.
- ELISA:Enzyme-linked immunosorbent assay for antibody detection in serum samples. Demand is concentrating in Australia's Northern Territory where centralized laboratories process remote pastoral zone samples with semi-automated plate readers.
- LAMP:Loop-mediated isothermal amplification eliminating thermal cycling equipment. Ethiopia's Borana pastoral zone and Mongolia's Khövsgöl province are deploying battery-powered devices for district-level confirmatory authority.
- Culture Method:Mycobacterium bovis isolation on selective media retaining OIE gold standard status.
- Molecular Assays:Broad category encompassing real-time PCR and gene probe technologies.
Culture Method anchors regulatory compliance. LAMP is climbing the fastest as pastoral regions bypass PCR infrastructure gaps.
Delivery Mode:
Physical distribution of testing capacity responds to laboratory density and sample transport economics.
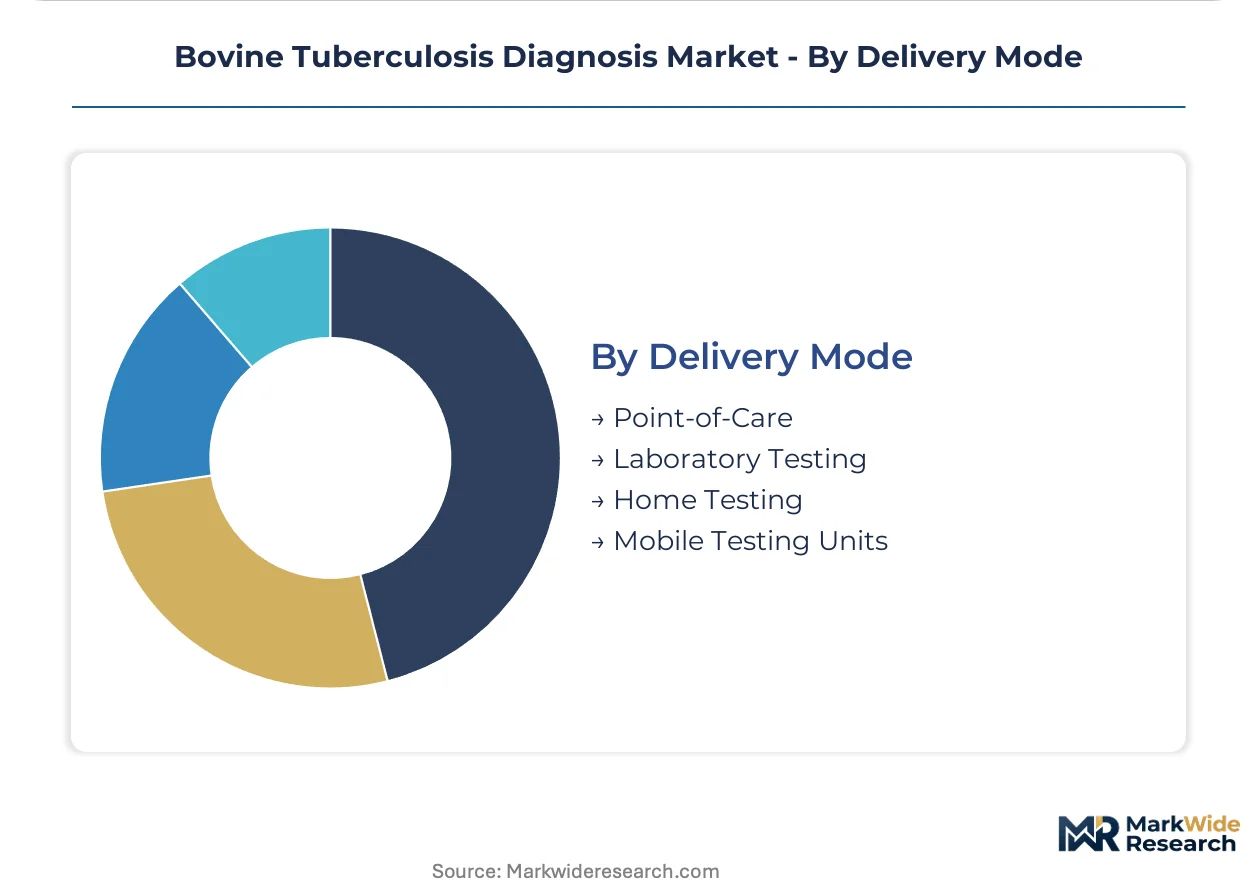
- Point-of-Care:Field-deployable platforms operating without permanent infrastructure. Canada's Prairie Provinces are prioritizing these formats to offset veterinary technician shortages delaying result reporting in remote areas.
- Laboratory Testing:Centralized processing with biosafety level containment. Germany's Bavaria and France's Brittany regions maintain high-throughput facilities prioritizing fluorine-free reagent suppliers under REACH restrictions.
- Home Testing:Producer-collected sample submission for remote diagnosis.
- Mobile Testing Units:Vehicle-mounted laboratory capacity for seasonal herd movements.
Laboratory Testing commands the largest throughput volume. Point-of-Care is expanding most quickly where infrastructure investment lags herd surveillance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's southern cattle states anchor diagnostic procurement intensity, with Paraná and Rio Grande do Sul expanding herd certification programs for export eligibility to China and the European Union.
Brazil
Paraná and Rio Grande do Sul states drive field-deployable diagnostic demand through export herd certification programs targeting China and EU markets. ANVISA enforces sanitary protocols that mandate pre-shipment tuberculosis screening. Field veterinarians in these southern states prioritize equipment-free skin testing formats for remote ranch operations.
United States
USDA slaughterhouse surveillance mandates sustain baseline testing volumes at federally inspected facilities across the Midwest and Great Plains. The Department of Agriculture's Animal and Plant Health Inspection Service enforces interstate movement regulations requiring tuberculosis-free herd certification. High-throughput diagnostic centers in Nebraska and Kansas process cattle samples from feedlot consolidation zones.
India
Uttar Pradesh's dairy belt generates point-of-care platform demand where cooperative-managed surveillance programs lack centralized laboratory infrastructure. The Food Safety and Standards Authority of India coordinates with state veterinary departments on zoonotic disease control frameworks. Dairy cooperatives in the state's western districts aggregate testing volumes through centralized procurement platforms.
Germany
Bavaria maintains high-throughput reference laboratories prioritizing fluorine-free reagent suppliers under REACH restrictions from the European Chemicals Agency. The Friedrich-Loeffler-Institut serves as the OIE reference laboratory for bovine tuberculosis reagent standardization. Regional diagnostic networks in southern Germany process slaughterhouse surveillance samples from dense dairy farming clusters.
Ethiopia
Borana pastoral zone deploys battery-powered LAMP devices for district-level confirmatory authority without thermal cycling infrastructure. The country's national veterinary regulator aligns field protocols with OIE Terrestrial Animal Health Code standards for cross-border livestock trade. Mobile veterinary units operating from Yabelo town compress response times for quarantine implementation in remote rangelands.
Bovine Tuberculosis Diagnosis Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue point-of-care decentralization and molecular assay miniaturization. The vendor base stratifies across three archetypes: multinational veterinary pharmaceutical conglomerates with channel density advantages, specialized molecular diagnostics firms with isothermal amplification expertise, and regional reagent suppliers serving national eradication programs. Competitive positioning depends on backward integration into antigen production and regulatory certification speed under evolving CE-IVDR frameworks.
Among North American veterinary diagnostic conglomerates, IDEXX Laboratories and Zoetis exemplify contrasting supply chain architectures. IDEXX leverages established channel density in veterinary networks to sustain kit availability across fragmented clinic purchasing. Zoetis anchors its position through captive supply of antigen production, reducing batch-to-batch variability in tuberculin reagents. Thermo Fisher Scientific represents the diversified life sciences conglomerate archetype, occupying a position spanning research-use and clinical diagnostic applications. These three entities collectively illustrate how scale, integration depth, and portfolio breadth define competitive differentiation in regulatory-intensive veterinary diagnostics.
| Leading Market Players |
|---|
| IDEXX Laboratories |
| Zoetis |
| Thermo Fisher Scientific |
| PBD Biotech |
| Innovative Diagnostics |
| Bio-Rad Laboratories |
| Enfer Group |
| IDvet |
| Neogen Corporation |
| Others |
Cost & Logistics Intelligence
IS6110-targeted PCR assay miniaturization simultaneously compresses per-test reagent costs and concentrates manufacturing capability among suppliers with thermal cycling platform expertise. This dual effect reshapes procurement economics as reference laboratories negotiate volume contracts while field-deployable formats command portability premiums.
Pricing Analysis
Input-cost pass-through from purified protein derivative antigen production runs through tuberculin reagent pricing, with batch-to-batch variability penalties absorbed by manufacturers serving OIE reference standards. Three-tier pricing structure across premium interferon gamma kits, standard ELISA panels, and economy skin test formats differentiates based on certification tier and cold chain dependency. Pricing pressure stems from REACH-mandated fluorine-free reformulation costs elevating reagent stabilizer expenses. Dairy cooperatives in Ireland and the Netherlands exhibit highest price sensitivity through centralized tendering, while high-value breeding stock operations in Germany's Bavaria region prioritize assay accuracy over unit cost.
Supply Chain Analysis
Purified protein derivative antigen supply rests on qualified production facilities in Germany, the United Kingdom, and the Netherlands serving international tuberculin markets. Bovine tuberculin production draws from bovine source herds, specialized fermentation equipment, and cold chain logistics infrastructure. Single-source vulnerability concentrates in antigen master seed stocks held by OIE reference laboratories. Distribution runs through veterinary pharmaceutical distributors to clinic networks, with direct manufacturer engagement rising as cooperative procurement platforms aggregate demand in dairy-intensive regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bovine tuberculosis diagnosis market functions as a geographic-arbitrage play where CE-IVDR compliance costs in Europe diverge from India's infrastructure-constrained demand for cold chain-independent formats.
For Market Incumbents: Hedge antigen supply exposure through captive production investments or dual-source qualification programs given OIE reference reagent concentration risk. Accelerate fluorine-free formulation validation to preempt REACH authorization deadlines. Defend channel position by embedding field service capabilities with cooperative procurement platforms displacing traditional distributor relationships.
For New Entrants and Emerging Players: Battery-powered LAMP platforms targeting Ethiopia's Borana pastoral zone and India's Uttar Pradesh dairy belt exploit infrastructure gaps that PCR incumbents cannot address. White-space concentration sits in point-of-care multiplexing for concurrent pathogen screening. Partner with mobile veterinary units to bypass centralized laboratory gatekeepers.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional reagent suppliers with national eradication program contracts but lacking CE-IVDR transition capital. Long-term viability favors manufacturers with backward integration into antigen production and isothermal amplification IP. Watch OIE Terrestrial Animal Health Code revision timelines as trade certification standard shifts trigger procurement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Antigen Production Backward Integration | Captive PPD supply reduces batch variability penalties under OIE reference standards. |
| Fluorine-Free Reagent Reformulation | REACH compliance secures continued EU market access for Bavaria and Brittany laboratories. |
| Point-of-Care LAMP Platform Launch | Battery-powered devices unlock Uttar Pradesh and Borana pastoral zones lacking PCR infrastructure. |
| Cooperative Procurement Partnership | Direct engagement with Dairygold and FrieslandCampina bypasses distributor margin compression. |
| Interferon Gamma-ELISA Convergence R&D | Multiplexing capability addresses EU Green Deal bundling of disease-free status with carbon premiums. |
Research Approach
Multiple input streams — regulatory filing analysis, veterinary diagnostic procurement records, and OIE reference laboratory technical documentation — were reconciled against primary interviews with veterinary service directors, diagnostic kit procurement managers at dairy cooperatives, reference laboratory technical officers, and field veterinarians in Brazil's Paraná state. Secondary validation incorporated ANVISA sanitary protocol publications, USDA APHIS surveillance reports, EFSA scientific opinions, and CE-IVDR technical documentation from notified bodies. Bottom-up test volume estimates from national eradication programs were triangulated against top-down diagnostic reagent trade flows.
Historical testing volume trajectories were cross-referenced against expert panel assessments of regulatory enforcement intensity and export certification demand. The forecast framework modeled segmentation across test type, end user, technology platform, and delivery mode dimensions. CAGRs were derived from infection prevalence projections, slaughterhouse surveillance mandate expansion schedules, and laboratory infrastructure investment pipelines. Industry-specific inputs included OIE disease freedom timeline commitments and F-Gas Regulation equipment redesign cost curves.
The model holds under stable regulatory enforcement and continued export market access conditions; deviation in national eradication program funding or trade certification reciprocity agreements would shift procurement cycle timing. Forecasts reflect documented assumptions regarding technology adoption rates and antigen supply stability. Regulatory divergence between WHO elimination targets and national budget commitments, alongside REACH authorization timeline slippage, warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Hydroponics Nutrients Market
Bio-Agriculture
Biochar Machine Market
Bio-Agriculture
Europe Feed Phytogenics Market
Bio-Agriculture
Asia-Pacific Bio-Ethanol Market
Bio-Agriculture
Canada Biofertilizers Market
Bio-Agriculture
Biofuel Enzymes Market
Bio-Agriculture
Europe Biofertilizer Market
Bio-Agriculture
Bioethanol Yeast Market
Bio-Agriculture
Transgenic Animals Market
Bio-Agriculture
Africa Biofertilizer Market
Bio-Agriculture
Asia-Pacific Biopesticides Market
Bio-Agriculture
India Feed Probiotics Market
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
Middle East and Africa Biopesticides Market
Bio-Agriculture
India Biocontrol Agents Market
Bio-Agriculture
Red Algae Market