
 Arachnoiditis Treatment Market | 2026-2036
Arachnoiditis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Arachnoiditis Treatment Market Outlook
Multi-sourced pharmaceutical supply for chronic pain therapies is recalibrating how hospital formularies secure arachnoiditis medications. Pfizer Inc. leverages its manufacturing scale to maintain broad distribution across institutional channels. Novartis AG anchors its position through specialized neuroscience portfolios that address refractory pain states. Johnson & Johnson competes via its diversified medical device and pharmaceutical footprint in spinal care.
Arachnoiditis denotes inflammatory fibrosis of the arachnoid membrane surrounding the spinal cord, typically triggered by trauma, infection, or iatrogenic insult following spinal surgery or myelography, producing chronic adhesive changes that compress nerve roots and disrupt cerebrospinal fluid dynamics. The condition demands multimodal management combining pharmacologic neuromodulation, targeted drug delivery, and interventional pain procedures. Neurostimulation devices command premium positioning due to their implantable complexity and long-term therapy value, while intrathecal delivery modes concentrate margin pools through specialized pump-and-catheter systems requiring surgical placement and refill protocols. Oral analgesics retain volume leadership across outpatient and home care settings where invasive access remains clinically inappropriate.
The FDA governs premarket approval for implantable neurostimulation systems and intrathecal pumps under stringent device classification pathways, while the DEA regulates controlled-substance analgesics through scheduling and distribution quotas that directly constrain formulary composition. State-level Medicaid programs and Medicare coverage determinations further filter patient access to surgical intervention and device implantation. Stakeholders must monitor evolving reimbursement thresholds for neurostimulation trials and permanent implants, as coverage expansion or contraction will directly shift treatment approach economics across hospital and ambulatory settings.
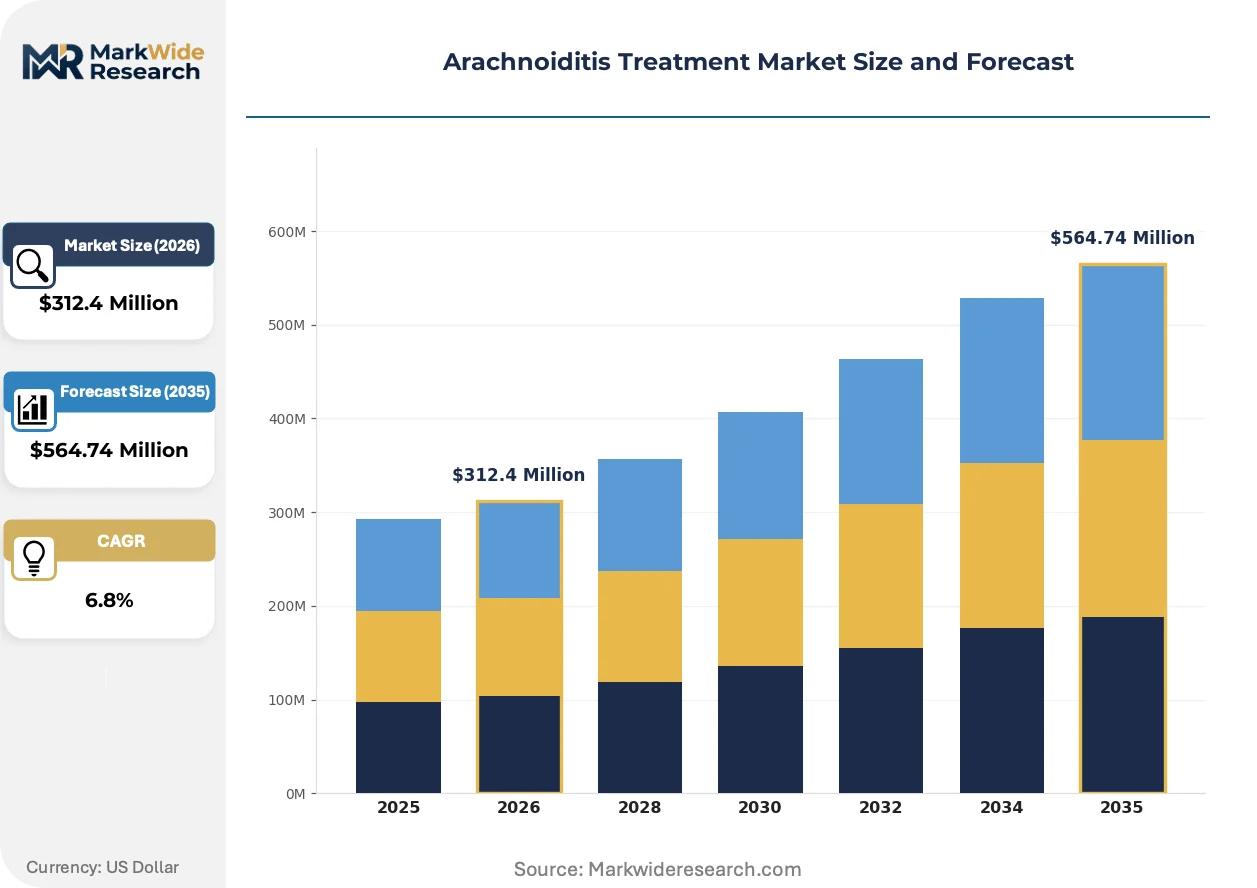
Market Dynamics
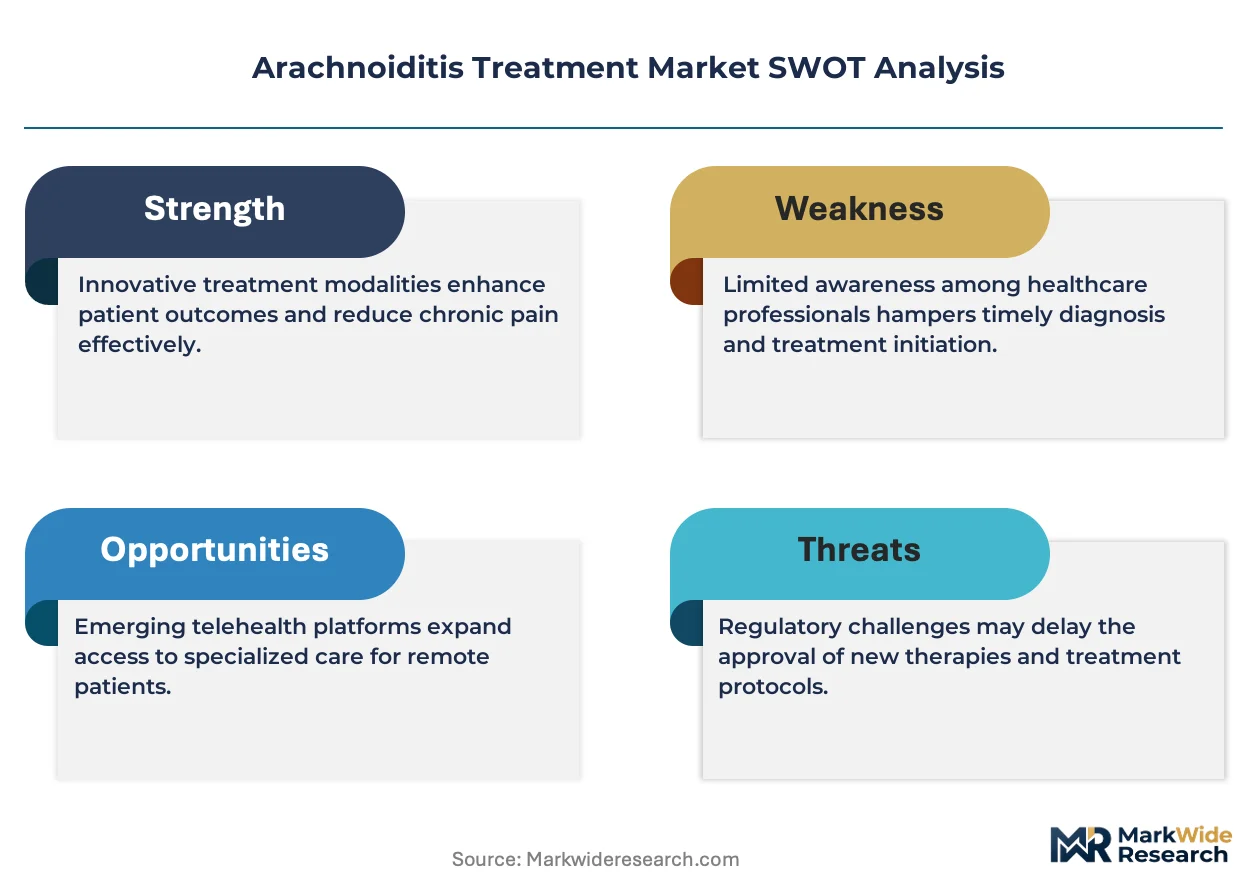
The FDA's evolving guidance on intrathecal drug delivery systems is compressing device qualification timelines while simultaneously raising clinical evidence thresholds, forcing manufacturers to recalibrate their regulatory strategies and hospital formularies to reconsider their neurostimulation procurement protocols.
Growth Catalysts
- Neurostimulation service line expansion:Hospital-based pain management programs are broadening their implantable device portfolios to capture complex chronic pain referrals. Tertiary centers in major US metropolitan corridors are clustering specialized surgical expertise.
- Medicaid coverage expansion:State-level Medicaid programs are progressively authorizing neurostimulation trials and permanent implants for refractory arachnoiditis cases. This policy shift is unlocking patient access previously blocked by reimbursement barriers.
- Intrathecal pump protocol refinement:Specialized refill and surgical placement protocols are extending therapy duration and reducing complication rates. Pain management clinics are building dedicated pump management infrastructure.
Market Restraints
- DEA controlled-substance quotas:Federal scheduling and distribution limits constrain formulary composition for oral analgesics. Hydrocodone and oxycodone availability fluctuates with enforcement cycles.
- Implantable device cost concentration:Neurostimulation systems and pump-and-catheter hardware command premium pricing that limits adoption in capitated reimbursement environments. Medicare coverage determinations filter patient access.
- Surgical placement dependency:Intrathecal delivery requires invasive access and specialized interventional pain physicians. Rural and underserved regions face procedural capacity shortages.
Strategic Opportunities
- Home-based oral analgesic optimization:Outpatient and home care settings remain underpenetrated for multimodal pharmacologic management. Patient education and adherence monitoring tools can extend therapy effectiveness.
- Device-pump convergence:Integration of neurostimulation with closed-loop intrathecal delivery represents emerging white space. Hybrid systems could reduce polypharmacy burden in refractory cases.
- IRA drug pricing provisions:Medicare negotiation authority is reshaping pharmaceutical economics for chronic pain therapies. Manufacturers must adapt pricing strategies for institutional channels.
Industry Challenges
- Interventional pain physician scarcity:The specialized skill set for pump implantation and neurostimulation lead placement is concentrated in academic medical centers. Training pipeline expansion lags demand growth.
- Premarket approval timeline compression:FDA device classification pathways require extensive clinical evidence. Manufacturers face capital intensity for pivotal trials while reimbursement codes remain unsettled.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arachnoiditis Treatment Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Neurostimulation Devices, Anti-Inflammatory Drugs, Corticosteroids Delivery Mode: Intrathecal, Oral, Injectable, Topical End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Treatment Approach: Medication Management, Surgical Intervention, Physical Therapy, Patient Education |
| Companies Covered | Pfizer Inc., Novartis AG, Johnson & Johnson, AstraZeneca, Teva Pharmaceutical Industries Ltd., F. Hoffmann-La Roche Ltd., Baxter, B. Braun Melsungen AG, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arachnoiditis Treatment Market Strategic Shifts
Neurostimulation hardware and intrathecal delivery architectures are undergoing simultaneous miniaturization and algorithmic sophistication, reshaping competitive positioning across implantable pain management devices.
Closed-loop spinal cord stimulation is electrifying therapeutic response by enabling real-time patient-specific parameter adjustment. Academic medical centers in Boston and Baltimore are piloting these adaptive systems for adhesive arachnoiditis with radiculopathy. The technology is compressing the gap between trial and permanent implant success rates.
MDR certification requirements in Europe are extending technical documentation and post-market surveillance obligations for implantable neuromodulation devices. Manufacturers serving EU markets must maintain clinical follow-up registries that exceed FDA post-approval study demands. The German and French hospital procurement consortia are now requiring MDR compliance documentation in competitive tenders.
Consolidated purchasing by US hospital systems is displacing traditional distributor relationships in the neurostimulation segment. Integrated delivery networks in Texas and California are negotiating direct manufacturer contracts for pump-and-catheter systems. This channel compression is most visible in metropolitan corridors where tertiary referral centers command volume leverage.
Arachnoiditis Treatment Market Segmentation
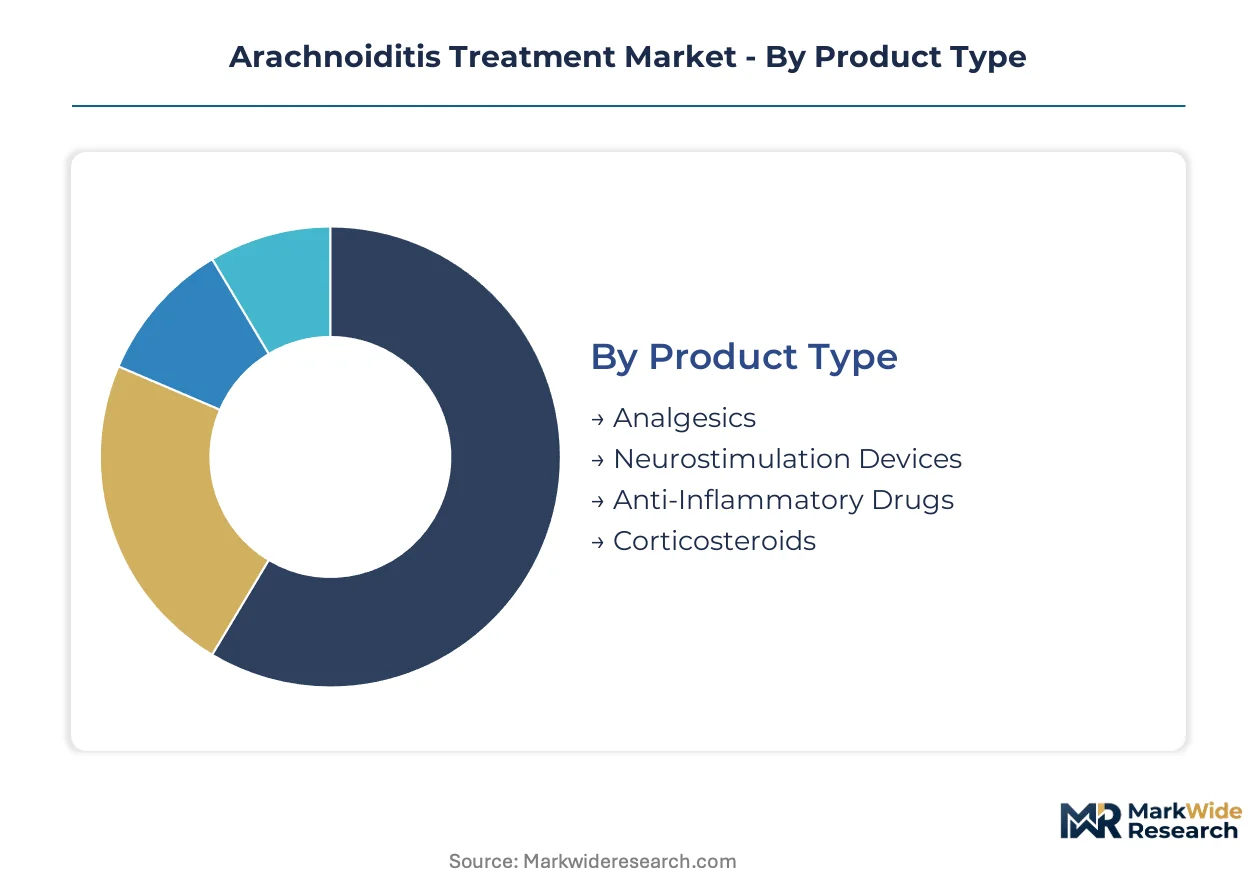
Arachnoiditis treatment modalities span a wide capital-intensity spectrum, from commodity oral formulations to implantable neurostimulation systems requiring surgical infrastructure and specialized interventional expertise. Segmentation reveals where margin pools concentrate versus where volume leadership resides across the care continuum.
Product Type:
Capital requirements vary dramatically across this category, with implantable hardware demanding manufacturing scale and clinical evidence investment that oral pharmaceuticals cannot match.
- Neurostimulation Devices:Implantable pulse generators and lead arrays deliver electrical modulation to the spinal cord or targeted nerve roots. Tertiary referral centers in Boston, Baltimore, and Houston cluster the surgical expertise for permanent implantation, with FDA premarket approval pathways compressing manufacturer timelines while raising evidence thresholds.
- Analgesics:Oral and parenteral formulations including opioids, NSAIDs, and adjuvant agents constitute the pharmacologic backbone of outpatient management. Home care settings and primary care clinics across the United States dispense these therapies under DEA scheduling constraints that directly constrain formulary composition.
- Anti-Inflammatory Drugs:Systemic and targeted immunomodulatory agents address the underlying inflammatory fibrosis driving arachnoiditis progression.
- Corticosteroids:Epidural and systemic steroid protocols remain standard-of-care for acute inflammatory flares despite limited long-term efficacy data.
Neurostimulation Devices absorb the bulk of installed capacity; Analgesics is expanding most quickly through Medicaid coverage expansion for refractory cases.
Delivery Mode:
Route of administration determines reimbursement complexity, patient compliance burden, and the clinical settings where therapy initiation occurs.
- Intrathecal:Pump-and-catheter systems deliver medication directly to the cerebrospinal fluid, bypassing blood-brain barrier limitations. Medicare coverage determinations and state Medicaid programs filter patient access, with specialized refill protocols extending therapy duration in academic medical centers.
- Oral:Tablets, capsules, and liquid formulations enable patient self-administration in ambulatory and home settings. Rural and underserved regions rely heavily on this mode due to procedural capacity shortages for invasive alternatives.
- Injectable:Parenteral delivery in clinical settings supports acute pain control and bridging therapy during device trials.
- Topical:Transdermal patches and localized formulations address peripheral symptom clusters with minimal systemic exposure.
Oral delivery commands the widest patient reach; Intrathecal modes capture the steepest expansion trajectory as pump management infrastructure proliferates.
End User:
Site-of-care economics reshape competitive dynamics, with integrated delivery networks consolidating purchasing power and displacing traditional distributor relationships.
- Hospitals:Inpatient and outpatient surgical suites host device implantation, pump placement, and complex medication management. Texas and California health systems negotiate direct manufacturer contracts for neurostimulation hardware, compressing channel margins.
- Clinics:Ambulatory pain management practices manage oral analgesic titration, pump refills, and neurostimulation parameter adjustments. These settings bridge acute intervention and longitudinal chronic care.
- Rehabilitation Centers:Post-acute facilities coordinate physical therapy and functional restoration alongside pharmacologic support.
- Home Care:Patient-directed oral therapy and remote monitoring tools extend treatment access beyond institutional walls.
Hospitals anchor device revenue concentration; Home Care is climbing the fastest as telehealth infrastructure and patient education tools mature.
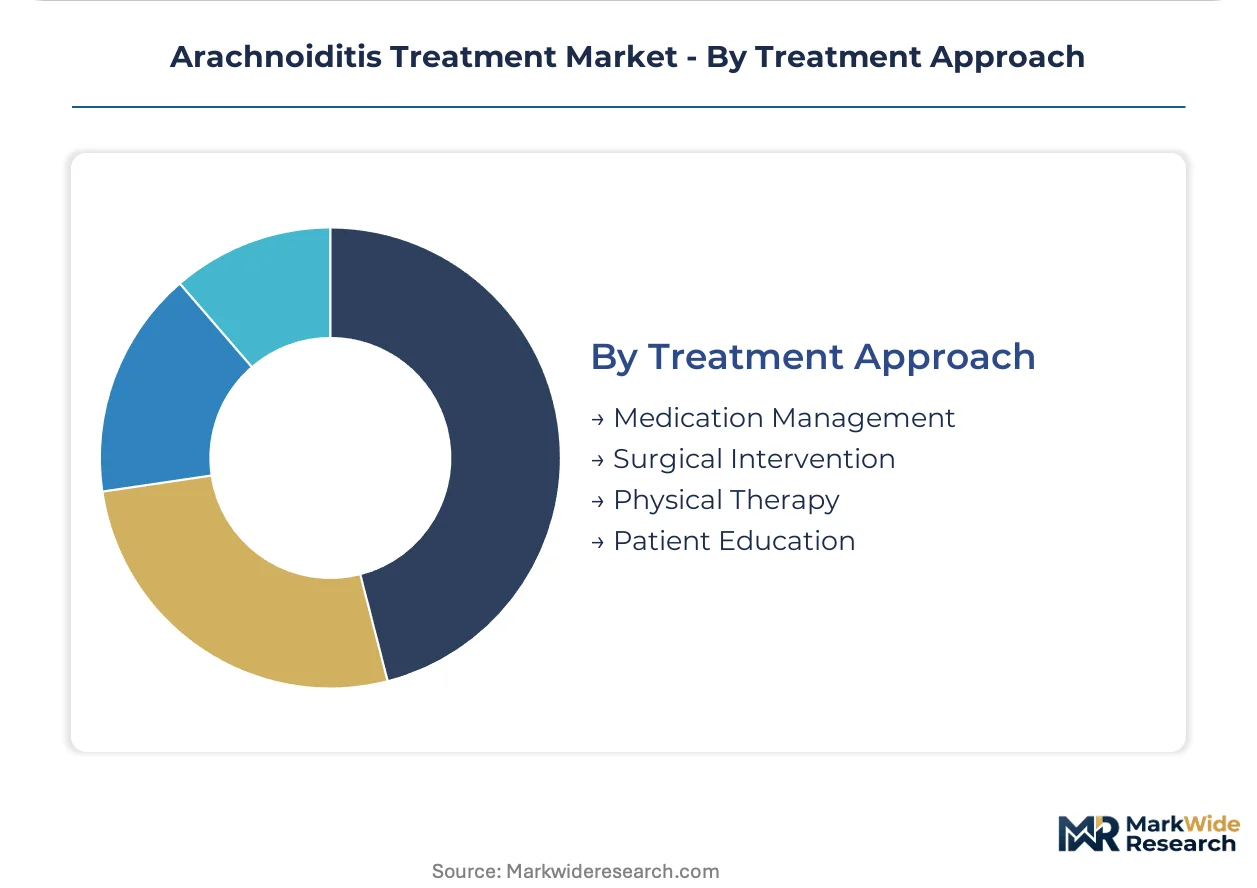
Treatment Approach:
Multimodal care protocols integrate pharmacologic, interventional, and rehabilitative elements based on disease stage and patient functional status.
- Medication Management:Systematic analgesic titration, polypharmacy optimization, and adverse event monitoring form the foundation of conservative care. The IRA's Medicare negotiation authority is reshaping pharmaceutical economics for chronic pain therapies in institutional channels.
- Surgical Intervention:Neurostimulation lead placement, pump implantation, and lysis of adhesions address refractory cases. FDA device classification pathways govern premarket approval, with clinical evidence requirements raising manufacturer capital intensity.
- Physical Therapy:Structured rehabilitation protocols preserve functional capacity and reduce pharmacologic dependency.
- Patient Education:Adherence monitoring, expectation management, and self-advocacy training improve long-term outcomes across all settings.
Medication Management retains the largest patient volume; Surgical Intervention is gaining share fastest as tertiary referral capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for arachnoiditis treatment concentrates in the United States, where tertiary referral centers cluster in major metropolitan corridors and Medicaid coverage expansion is unlocking patient access previously blocked by reimbursement barriers.
United States
Boston and Baltimore academic medical centers pilot closed-loop spinal cord stimulation systems for adhesive arachnoiditis with radiculopathy. The FDA governs premarket approval for implantable neurostimulation under stringent device classification pathways. Texas and California health systems negotiate direct manufacturer contracts for pump-and-catheter hardware, compressing traditional distributor margins.
Germany
German hospital procurement consortia now require MDR compliance documentation in competitive tenders for implantable neuromodulation devices. The MDR extends technical documentation and post-market surveillance obligations beyond FDA requirements. Frankfurt and Munich tertiary centers maintain clinical follow-up registries that exceed post-approval study demands, anchoring European evidence generation.
France
Parisian referral networks specialize in intrathecal pump management infrastructure for refractory pain states. ANSM oversight aligns with EMA pharmaceutical regulations for controlled-substance analgesics distributed through institutional channels. Lyon and Marseille pain clinics are building dedicated refill protocol capabilities to extend therapy duration.
United Kingdom
London's National Health Service trusts cluster interventional pain physicians for complex arachnoiditis surgical intervention. MHRA device regulations mirror FDA evidence thresholds for neurostimulation trials and permanent implants. Manchester and Birmingham rehabilitation centers coordinate physical therapy with pharmacologic support for post-acute functional restoration.
Japan
Tokyo metropolitan hospitals anchor demand for miniaturized neurostimulation hardware with algorithmic sophistication. PMDA governs premarket approval for implantable devices with clinical evidence requirements comparable to FDA pathways. Osaka and Nagoya medical centers are expanding neurostimulation service lines to capture complex chronic pain referrals from surrounding prefectures.
Arachnoiditis Treatment Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers recalibrate regulatory strategies amid evolving FDA guidance on intrathecal drug delivery systems. The vendor base spans multinational pharmaceutical conglomerates with manufacturing scale, specialized neuroscience portfolios, and diversified medical device footprints. Three archetypes define competitive positioning: scale-driven institutional channel suppliers, refractory pain specialists with targeted portfolios, and integrated spinal care device-pharmaceutical hybrids. M&A activity and capacity expansion in pump-and-catheter manufacturing represent the dominant competitive moves as hospital formularies reconsider procurement protocols.
Among diversified medical device and pharmaceutical conglomerates, Johnson & Johnson occupies a position exemplifying the integrated spinal care archetype through its footprint across implantable hardware and pharmacologic neuromodulation. Pfizer Inc. represents the scale-driven institutional supplier, leveraging manufacturing breadth for distribution across hospital channels. Novartis AG anchors the specialized neuroscience tier, with its portfolio addressing refractory pain states that demand multimodal management combining targeted drug delivery and interventional procedures.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Johnson & Johnson |
| AstraZeneca |
| Teva Pharmaceutical Industries Ltd. |
| F. Hoffmann-La Roche Ltd. |
| Baxter |
| B. Braun Melsungen AG |
| Sanofi |
| Others |
Value Chain & Pricing Dynamics
Active pharmaceutical ingredient spot indices for opioid analgesics and specialized polymers for implantable device housings cascade through hospital procurement tiers, concentrating margin capture among manufacturers with captive raw material sourcing while forcing price concessions from distributors lacking backward integration into component production.
Pricing Analysis
Volume leadership in oral analgesics trades at thin margins against premium capture in neurostimulation hardware and pump-and-catheter systems. Three-tier pricing structure across premium, standard, and economy levels separates FDA-breakthrough-designation devices from CE-marked alternatives and unbranded commodity pumps. Cost compression in standard-tier oral formulations is intensifying because Medicaid rebate obligations and IRA Medicare negotiation authority are reshaping institutional channel economics. Safety-net hospitals and rural clinics exhibit the highest price sensitivity, while tertiary academic medical centers prioritize clinical evidence and device reliability over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from Texas and California integrated delivery networks require pump-and-catheter manufacturers to qualify secondary component suppliers for lead arrays and biocompatible tubing. Component production concentrates in the United States, Germany, and Switzerland for precision-machined hardware, while active pharmaceutical ingredients for intrathecal formulations draw from India and Italy. Supply chain risk centers on single-source vulnerability for specialized implant-grade polymers subject to FDA device master file restrictions. Distribution runs through direct manufacturer contracts with hospital systems, displacing traditional medical device distributors in metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The arachnoiditis treatment market is becoming a vertical-integration race, with manufacturers pursuing captive control over implantable device component production to defend margin pools against consolidated hospital purchasing power.
For Market Incumbents: Deepen backward integration into biocompatible polymer production and precision-machined pump components to offset distributor displacement by Texas and California health systems. Defend against emerging closed-loop neurostimulation entrants by accelerating FDA breakthrough device designation pathways for adaptive algorithm platforms. Priority investment in pump refill protocol automation will extend therapy duration and lock in recurring revenue streams. For New Entrants and Emerging Players: Launch via direct-to-clinic distribution models targeting ambulatory pain management practices in underserved rural corridors where procedural capacity shortages limit incumbent device penetration. White-space opportunities concentrate in home-based oral analgesic adherence monitoring tools and telehealth-integrated pump management platforms. The most penetrable segment is Medicaid-expansion states where reimbursement barriers previously blocked device access. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap device manufacturers with FDA premarket approval infrastructure but strained capital reserves for pivotal trials in the United States. Long-term viability over the next decade hinges on convergence capabilities across neurostimulation and intrathecal delivery architectures. The signal to watch is Medicare coverage determination expansion for closed-loop spinal cord stimulation trials as an inflection indicator for premium device adoption.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates premarket approval timelines for closed-loop neurostimulation systems targeting adhesive arachnoiditis. |
| Backward Integration into Polymer Production | Captures margin pools from specialized implant-grade materials subject to FDA device master file restrictions. |
| Hospital System Direct Contracting | Bypasses distributor markups in Texas and California metropolitan corridors where tertiary centers command volume leverage. |
| Pump Refill Protocol Automation | Extends therapy duration and reduces complication rates in academic medical center pain management clinics. |
| Telehealth-Integrated Pump Management | Extends treatment access to rural and underserved regions facing interventional pain physician scarcity. |
Study Parameters
FDA 510(k) and PMA filings, CMS Medicare coverage determinations, and ClinicalTrials.gov registries formed the secondary backbone, cross-referenced with primary interviews with interventional pain physicians, hospital procurement directors, and biomedical engineers specializing in implantable neuromodulation. Bottom-up and top-down triangulation validated patient volume estimates against manufacturer shipment data and institutional formulary composition records.
Bottom-up modeling aggregated procedure volumes for neurostimulation trials and permanent implants, intrathecal pump placements, and oral analgesic prescriptions across hospital, clinic, and home care settings. Top-down analysis calibrated aggregate market value against pharmaceutical manufacturer revenue disclosures and medical device segment reporting. Segmentation dimensions included product type, delivery mode, end user, and treatment approach, with CAGRs derived from trend extrapolation of Medicaid coverage expansion patterns and FDA device approval velocity across the analysis window.
Regulatory approval delays, Medicaid reimbursement contraction, and DEA controlled-substance quota reductions are the dominant revision risks to procedure volume and pricing assumptions. Deviation in FDA guidance timelines for intrathecal drug delivery systems would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Neurological Biomarkers Market
Neurology
Sweden Neurology Devices Market
Neurology
US Optic Neuritis Market
Neurology
South America Neurology Monitoring Market
Neurology
United States Neurology Devices Market
Neurology
Spasticity Treatment Market
Neurology
Idiopathic Intracranial Hypertension Therapeutics Market
Neurology
Tourette Syndrome Market
Neurology
Amnestic Disorders Therapeutics Market
Neurology
Chordoma Disease Market
Neurology
Bell Palsy Treatment Market
Neurology
Movement Disorder Market
Neurology
Italy Neurology Devices Market
Neurology
CNS Lymphoma Market
Neurology
Transverse Myelitis Treatment Market
Neurology
CNS Treatment and Therapy Market