
 Chiari Malformation Treatment Market | 2026-2036
Chiari Malformation Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chiari Malformation Treatment Market Outlook
Project finance for dedicated neurosurgical centers is reshaping competitive access to the Chiari treatment landscape. Medtronic leverages its deep portfolio of cranial fixation and CSF management systems to anchor high-complexity surgical workflows. Integra LifeSciences specializes in dural repair and regenerative tissue technologies that differentiate its position in decompression procedures. Stryker competes through integrated operating room ecosystems that control surgical navigation and instrument sterilization chains.
Chiari malformation treatment encompasses surgical decompression, pharmaceutical management, and rehabilitative care addressing cerebellar tonsillar herniation and associated CSF flow obstruction. The standard surgical approach involves suboccipital craniectomy with or without duraplasty, typically requiring titanium plate fixation and synthetic dural grafts to restore normal intracranial pressure dynamics. Surgical interventions dominate value capture given the high cost of inpatient neurosurgical episodes and device-intensive procedures, while pain management medication represents a mature, high-volume segment with compressed margins. Neurological rehabilitation is expanding fastest as payers and specialty care centers push for standardized post-operative functional recovery protocols that reduce readmission exposure.
The FDA's neurological device premarket approval pathway and the EU MDR's heightened clinical evidence requirements for implantable cranial systems are extending development timelines and consolidating manufacturer capabilities. Japan's PMDA maintains distinct reimbursement thresholds for novel CSF shunt technologies that filter market entry to firms with robust Japanese clinical data. Stakeholders must monitor evolving HTA body assessments of minimally invasive versus open decompression outcomes as these determinations will reset procedural reimbursement and device substitution patterns.
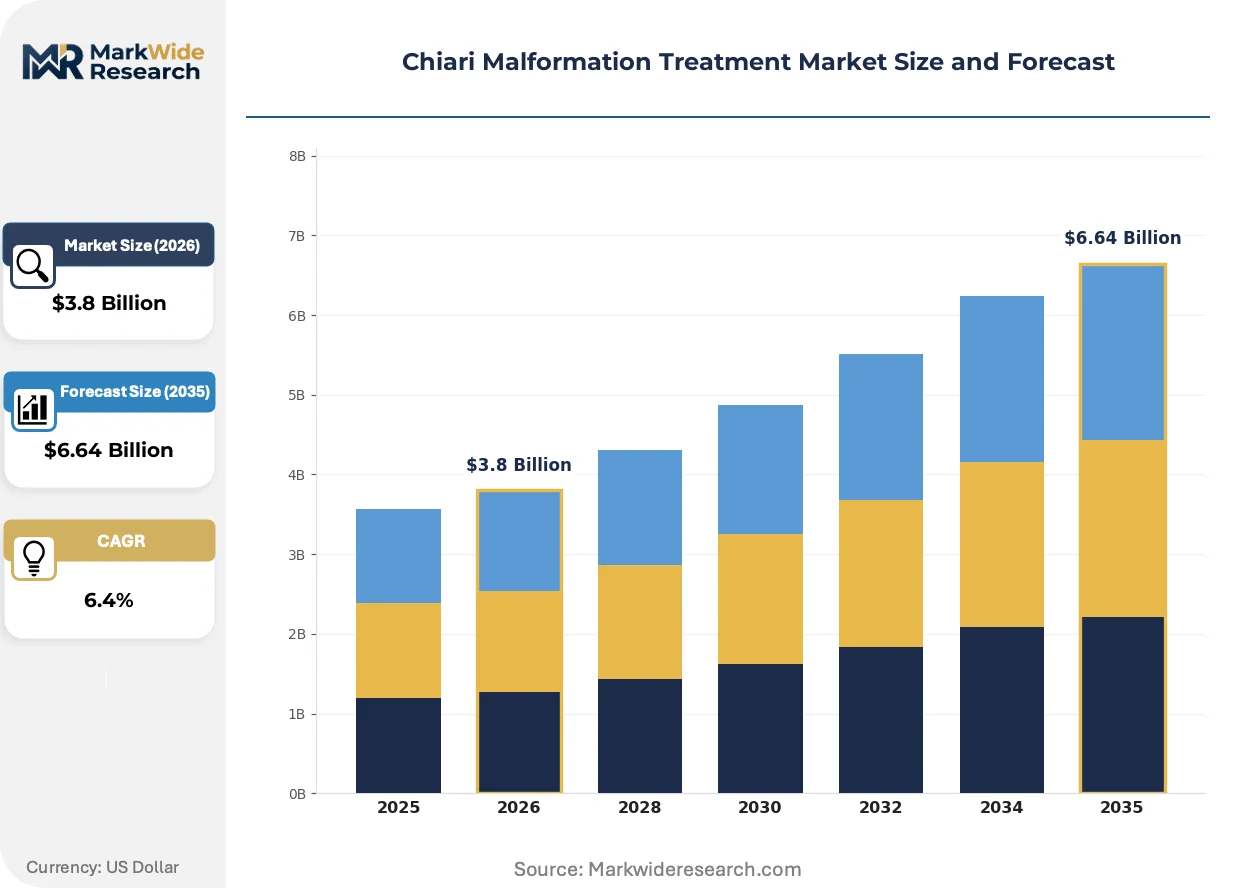
Market Dynamics
Specialized pediatric neurosurgical centers are consolidating treatment capacity as FDA and EMA neurological device approval standards tighten, forcing smaller hospitals to exit high-complexity Chiari procedures and redirecting patient flows toward integrated academic medical centers with full craniovertebral junction surgery programs.
Growth Catalysts
- EU MDR clinical evidence mandates:Heightened requirements for implantable cranial systems are filtering out marginal device manufacturers and concentrating procurement among suppliers with robust European clinical data portfolios.
- Pediatric neurosurgical center expansion:Dedicated children's hospitals in the United States and Germany are building craniovertebral junction surgery programs that attract international patient referrals.
- CSF flow dynamics modeling:Computational fluid dynamics simulation is enabling patient-specific surgical planning that reduces revision rates and shortens inpatient episodes.
Market Restraints
- Titanium plate and screw cost volatility:Cranial fixation hardware input costs fluctuate with aerospace alloy demand, compressing margins on standard decompression procedures.
- Synthetic dural graft supply concentration:Manufacturing of collagen matrix and synthetic dural substitutes concentrates among a limited supplier base in Switzerland and the United States.
- Extended FDA premarket approval timelines:Neurological device pathway requirements for novel CSF shunt technologies delay commercialization by 18-36 months versus historical benchmarks.
Strategic Opportunities
- Post-operative neurological rehabilitation standardization:Payers are mandating functional recovery protocols that create service revenue streams beyond the surgical episode.
- Japan PMDA reimbursement thresholds:Novel CSF diversion technologies with Japanese clinical data access premium reimbursement tiers unavailable to imported devices.
- Minimally invasive endoscopic decompression:Convergence of surgical navigation systems with micro-instrumentation enables outpatient procedure migration for select Type I presentations.
Industry Challenges
- Pediatric neurosurgical workforce scarcity:Fellowship-trained craniovertebral junction specialists are concentrated at academic centers, limiting procedure volume expansion at community hospitals.
- Operating room ecosystem integration complexity:Stryker, Medtronic, and Brainlab navigation platforms require dedicated capital expenditure and staff training that fragments purchasing decisions.
- HTA body outcome measurement standardization:Germany's IQWiG and England's NICE are developing divergent quality-of-life endpoints for decompression versus conservative management that complicate multi-market evidence generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chiari Malformation Treatment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Interventions, Medication, Physical Therapy, Lifestyle Modifications End User: Neurosurgeons, General Practitioners, Rehabilitation Specialists, Patients Care Setting: Hospitals, Outpatient Clinics, Specialty Care Centers, Home Care Therapy Area: Cerebrospinal Fluid Disorders, Pain Management, Neurological Rehabilitation, Surgical Recovery |
| Companies Covered | Medtronic, Integra LifeSciences, Stryker, B. Braun, Pfizer Inc., F. Hoffmann-La Roche Ltd, Novartis AG, Teva Pharmaceutical Industries Ltd., Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chiari Malformation Treatment Market Strategic Shifts
Digital surgical planning and intraoperative navigation are compressing the technical variance between high-volume academic centers and lower-volume community practice, while regulatory evidence requirements reshape which device manufacturers can sustain market participation.
Intraoperative MRI and augmented reality surgical navigation is virtualizing the spatial reasoning traditionally concentrated among fellowship-trained neurosurgeons. Community hospitals with limited Chiari case volume are adopting these platforms to maintain procedural competence. The technology is virtualizing expertise geography and enabling case retention that would otherwise migrate to academic referral centers.
The EU MDR's heightened clinical evidence requirements for Class III implantable cranial systems are extending development timelines and consolidating manufacturer capabilities. Small and mid-cap device firms without existing European notified body relationships are exiting the neurological implant category. Germany's BfArM and France's ANSM are coordinating post-market surveillance requirements that favor manufacturers with established European quality management infrastructure.
Hospital purchasing committees are unbundling after-sales service from device procurement and negotiating direct technical support contracts. Academic medical centers in the United States and Japan are leading this shift, demanding transparent service pricing separate from hardware margins. The unbundling is most visible at pediatric neurosurgical centers with dedicated biomedical engineering departments capable of first-line device troubleshooting.
Chiari Malformation Treatment Market Segmentation
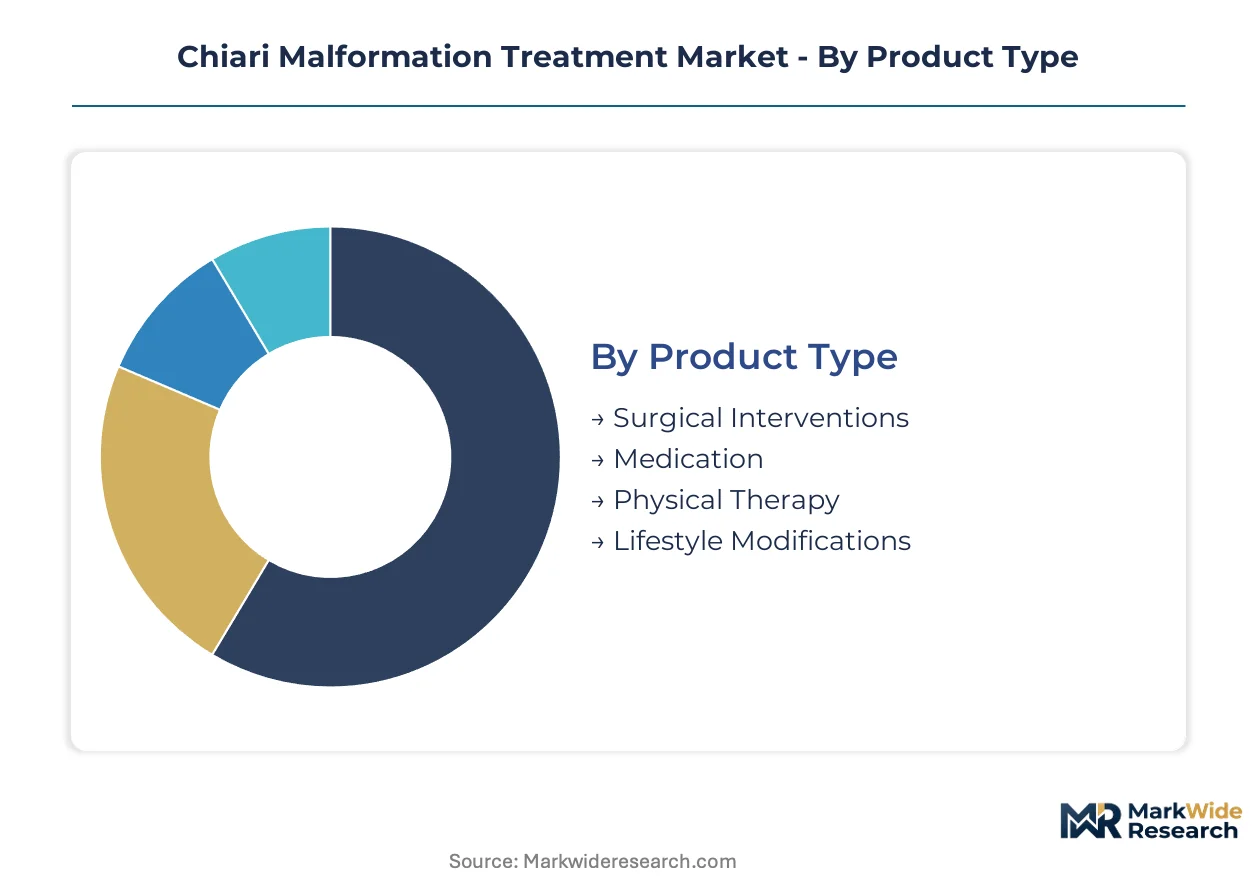
Chiari malformation treatment spans surgical, pharmaceutical, and rehabilitative modalities with distinct procurement pathways and reimbursement structures. Understanding segment boundaries clarifies where device manufacturers, service providers, and pharmaceutical firms compete for margin capture.
Product Type:
Cost tier differentiation separates high-acuity surgical episodes from maintenance pharmacotherapy and supportive rehabilitation services.
- Surgical Interventions:Suboccipital craniectomy with duraplasty, titanium plate fixation, and synthetic dural graft placement commands premium inpatient reimbursement. Academic medical centers in the United States and Germany concentrate demand for complex craniovertebral junction procedures requiring fellowship-trained neurosurgical teams.
- Medication:Analgesics, muscle relaxants, and neuropathic pain agents address symptom management without altering anatomical pathology. Pain management protocols at outpatient clinics in Japan emphasize conservative pharmacological approaches before surgical referral.
- Physical Therapy:Vestibular rehabilitation and cervical stabilization exercises target postural control deficits associated with cerebellar tonsillar herniation. Rehabilitation specialists in specialty care centers coordinate with neurosurgeons on post-operative functional recovery timelines.
- Lifestyle Modifications:Activity restriction, sleep positioning, and symptom monitoring strategies support patients awaiting surgical candidacy or declining operative intervention.
Surgical Interventions holds installed capacity. Medication is rotating up the share rankings.
End User:
Specialist concentration versus generalist distribution shapes referral patterns and treatment intensity across patient populations.
- Neurosurgeons:Fellowship-trained craniovertebral junction specialists perform decompression procedures and manage CSF diversion hardware complications. Pediatric neurosurgical centers in the United States attract international referrals for complex Chiari Type II presentations with associated myelomeningocele.
- General Practitioners:Primary care physicians coordinate initial symptom evaluation and specialist referral decisions. Community practice networks in Germany gatekeep access to academic neurosurgical centers through structured referral pathways.
- Rehabilitation Specialists:Physical medicine and neurological rehabilitation physicians design post-operative functional recovery protocols. Outpatient clinics in Japan deploy standardized assessment tools mandated by payer quality frameworks.
- Patients:Self-directed symptom management and care navigation decisions influence treatment adherence and surgical timing, particularly in markets with limited specialist density.
Neurosurgeons holds installed capacity. Rehabilitation Specialists is climbing the fastest as payers mandate functional outcome documentation.
Care Setting:
Volume distribution across inpatient, ambulatory, and community-based venues reflects reimbursement incentives and technology portability.
- Hospitals:Inpatient neurosurgical units with intraoperative MRI and navigation systems manage high-complexity decompression procedures. Academic medical centers in the United States consolidate craniovertebral junction surgery programs as FDA device approval standards tighten.
- Outpatient Clinics:Ambulatory surgical centers with specialized neurosurgical capabilities are piloting select endoscopic decompression procedures for Type I presentations. Germany's outpatient reimbursement framework limits expansion of invasive neurological procedures outside hospital settings.
- Specialty Care Centers:Dedicated pediatric neurosurgical facilities and craniofacial centers concentrate multidisciplinary expertise. Children's hospitals in Japan leverage PMDA reimbursement thresholds for novel CSF shunt technologies to attract device innovation trials.
- Home Care:Remote patient monitoring and telehealth rehabilitation extend post-operative surveillance beyond traditional facility boundaries.
Hospitals holds installed capacity. Specialty Care Centers is gaining share fastest through pediatric program consolidation.
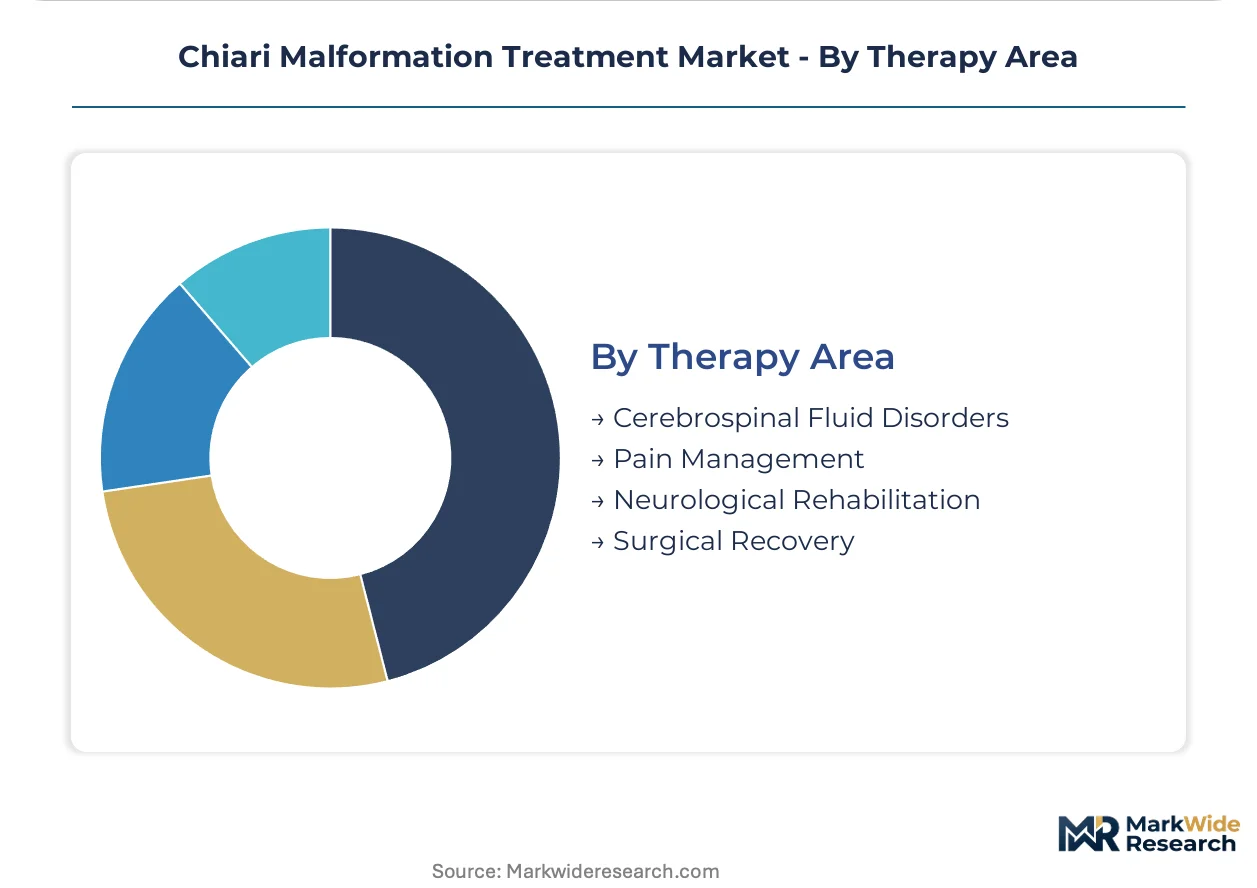
Therapy Area:
Maturity gradients separate established symptomatic management from emerging protocol standardization in functional recovery.
- Cerebrospinal Fluid Disorders:CSF flow obstruction management via shunting, diversion, or decompression addresses the core pathophysiology of Chiari malformation. Computational fluid dynamics modeling at select United States academic centers enables patient-specific surgical planning.
- Pain Management:Neuropathic pain and headache control through pharmacological and interventional approaches represents a mature, high-volume segment with compressed margins. Germany's IQWiG evaluates comparative effectiveness of conservative versus surgical pain outcomes.
- Neurological Rehabilitation:Standardized functional recovery protocols targeting gait, coordination, and cognitive sequelae are expanding fastest as payers link reimbursement to outcome metrics. Japan's specialty care centers deploy robotic-assisted rehabilitation technologies for post-operative motor recovery.
- Surgical Recovery:Post-operative monitoring, complication management, and revision planning occupy neurosurgical capacity at high-volume centers.
Cerebrospinal Fluid Disorders holds installed capacity. Neurological Rehabilitation is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for titanium cranial fixation hardware and synthetic dural grafts shapes procurement strategies across major neurosurgical markets, with specialized pediatric centers driving demand concentration in countries with established reimbursement frameworks for complex craniovertebral junction procedures.
United States
Pediatric neurosurgical centers in Boston and Philadelphia attract international referrals for complex Chiari Type II presentations, with the FDA's neurological device premarket approval pathway filtering market entry to manufacturers with robust clinical data portfolios. The IRA's hospital price transparency mandates are pressuring device procurement negotiations at academic medical centers. Philadelphia's craniovertebral junction surgery programs are expanding intraoperative MRI capacity to capture complex revision cases.
Germany
IQWiG assessments of decompression versus conservative management outcomes are resetting procedural reimbursement thresholds, concentrating high-complexity cases at university hospitals in Munich and Heidelberg. The EU MDR's clinical evidence mandates for Class III implantable cranial systems are extending development timelines for novel CSF diversion technologies. Heidelberg's pediatric neurosurgical center is coordinating post-market surveillance requirements with France's ANSM under BfArM guidance.
Japan
PMDA reimbursement thresholds for novel CSF shunt technologies filter market entry to firms with Japanese clinical data, creating premium tiers unavailable to imported devices. METI's medical device innovation programs are funding computational fluid dynamics modeling capabilities at Tokyo academic centers. Osaka's specialty care centers are deploying robotic-assisted rehabilitation technologies for post-operative motor recovery.
Switzerland
Manufacturing concentration for collagen matrix and synthetic dural substitutes creates supply vulnerability for European neurosurgical supply chains, with Swissmedic maintaining distinct quality management infrastructure requirements. The country's precision manufacturing base anchors production of high-grade titanium cranial fixation hardware. Zurich's pediatric neurosurgical programs are piloting patient-specific surgical planning protocols using computational fluid dynamics simulation.
United Kingdom
NICE quality-of-life endpoint development for decompression outcomes is diverging from German IQWiG methodologies, complicating multi-market evidence generation for device manufacturers. NHS England's specialized commissioning frameworks are consolidating Chiari procedures at designated neuroscience centers in London and Manchester. Manchester's academic medical center is building craniovertebral junction surgery capacity to reduce referral leakage to European centers.
Chiari Malformation Treatment Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers: diversified medical technology conglomerates with full operating room ecosystem control, specialized neurosurgical device manufacturers with concentrated cranial portfolios, and pharmaceutical firms addressing symptomatic management. Competitive positioning depends on regulatory evidence generation capabilities, European notified body relationships, and Japanese PMDA clinical data access. M&A activity targets pediatric neurosurgical center access and computational surgical planning technologies.
Among diversified medical technology conglomerates, Medtronic, Stryker, and Johnson & Johnson occupy positions spanning cranial fixation hardware, CSF management systems, and integrated surgical navigation platforms. These firms exemplify the scale-driven archetype where operating room ecosystem control and service unbundling negotiations anchor procurement relationships at academic medical centers. Integra LifeSciences represents the specialized neurosurgical device tier with concentrated expertise in dural repair and regenerative tissue technologies. B. Braun and Teva Pharmaceutical Industries Ltd. sit within the European-origin pharmaceutical and device manufacturing segment, with the former occupying a position in surgical instrumentation and the latter exemplifying the symptomatic management pharmaceutical archetype.
| Leading Market Players |
|---|
| Medtronic |
| Integra LifeSciences |
| Stryker |
| B. Braun |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Johnson & Johnson |
| Others |
Value Chain & Pricing Dynamics
Synthetic dural graft manufacturing concentrates in Switzerland and the United States, anchoring margin capture downstream at academic medical centers negotiating unbundled service contracts. Titanium cranial fixation hardware draws from aerospace alloy supply chains, transmitting commodity volatility into neurosurgical device procurement.
Pricing Analysis
Academic medical center purchasing committees anchor three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FDA premarket approval tier, Japanese PMDA clinical data access, and after-sales service bundling. Cost compression in standard decompression hardware intensifies because aerospace alloy demand fluctuates. Community hospitals exhibit highest price sensitivity; pediatric neurosurgical centers with dedicated biomedical engineering departments demonstrate lowest sensitivity due to in-house troubleshooting capabilities.
Supply Chain Analysis
Export-control restrictions on computational fluid dynamics software and intraoperative navigation platforms limit technology flows into non-allied markets. Manufacturing of collagen matrix dural substitutes and synthetic grafts concentrates in Switzerland and the United States. Raw material dependencies include medical-grade titanium alloys, bovine collagen sources, and biocompatible polymers. Single-source vulnerability runs through Swissmedic-certified production facilities for high-grade fixation hardware. Distribution feeds from manufacturer direct sales teams into hospital purchasing committees and GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device manufacturer consolidation and regulatory evidence requirements fragment competitive access, creating niches for specialized dural repair technologies and computational surgical planning platforms. Payer-mandated functional outcome documentation accelerates demand-side specialization.
For Market Incumbents: Entrench ecosystem control by deepening backward integration into titanium alloy supply chains and securing European notified body relationships ahead of EU MDR enforcement waves. Anchor procurement relationships at pediatric neurosurgical centers through transparent service pricing separate from hardware margins. Counter emerging entrant pressure in minimally invasive endoscopic instrumentation by accelerating Japanese PMDA clinical data generation.
For New Entrants and Emerging Players: Build out white-space positions in patient-specific surgical planning software and robotic-assisted rehabilitation technologies. Japan's specialty care centers offer the most penetrable entry point due to PMDA reimbursement thresholds that reward local clinical data. Pursue hospital system partnerships that bundle post-operative neurological rehabilitation protocols with device placement.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed neurosurgical device specialists concentrated in dural repair and regenerative tissue platforms. The five-to-ten year viability window favors manufacturers with established European quality management infrastructure and Japanese clinical data access. Watch IQWiG and NICE quality-of-life endpoint divergence as the signal indicating reimbursement reset timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Japanese PMDA Clinical Trial Investment | Unlocks premium reimbursement tiers unavailable to imported CSF diversion devices. |
| European Notified Body Relationship Expansion | Accelerates EU MDR compliance timelines for Class III implantable cranial systems. |
| Computational Fluid Dynamics Platform Acquisition | Enables patient-specific surgical planning that reduces revision rates at academic centers. |
| Post-Operative Rehabilitation Service Unbundling | Captures recurring revenue streams beyond surgical episode at pediatric neurosurgical centers. |
| Titanium Alloy Supply Agreement Restructuring | Hedges aerospace commodity volatility compressing margins on standard decompression hardware. |
Study Parameters
A spread of perspectives from pediatric neurosurgeons, hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and regulatory affairs leads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EMA premarket approval databases, Japanese PMDA reimbursement bulletins, and hospital procurement records. Bottom-up segmentation modeling triangulated against top-down macro indicators across the analysis window.
Demand-supply balance dynamics anchored the forecast framework throughout the projection horizon. Segmentation dimensions modeled include surgical intervention type, care setting tier, end-user specialist concentration, and regional regulatory cluster. CAGRs derived from procedure volume trajectories, device replacement cycles, and reimbursement rate evolution. Industry-specific inputs encompassed EU MDR transition timelines, Japanese METI innovation funding flows, and pediatric neurosurgical fellowship pipeline constraints.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified medical technology conglomerates would shift outcomes. Material shifts in FDA neurological device premarket approval timelines or PMDA reimbursement threshold recalibration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Brain Ischemia Market
Neurology
Cluster Headache Syndrome Market
Neurology
Japan Neurology Devices Market
Neurology
Middle-East and Africa Neurology Monitoring Market
Neurology
Canada Neurology Devices Market
Neurology
Olivopontocerebellar Atrophy Treatment Market
Neurology
United States Neurology Devices Market
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market
Neurology
Arachnoiditis Market
Neurology
Mild Cognitive Impairment Market
Neurology
CNS Therapeutics Market
Neurology
Movement Disorder Market
Neurology
Transverse Myelitis Treatment Market
Neurology
Occipital Nerve Block Treatment Market
Neurology
Labyrinthitis Market
Neurology
Spinal Cord Trauma Treatment Market