
 Australia Life and Non-Life Insurance Market | 2026-2036
Australia Life and Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Life and Non-Life Insurance Market Outlook
A capital-intensity divergence between established incumbents and digital challengers is reorganizing competitive dynamics across Australian insurance. QBE Insurance Group leverages its global underwriting footprint to sustain pricing power in commercial lines. Suncorp Group anchors its position through integrated banking and insurance distribution across Queensland and Victoria. Insurance Australia Group dominates personal lines via scale advantages in motor and home coverage.
Australia life and non-life insurance encompasses risk-pooling contracts where insurers collect premiums to fund mortality, morbidity, property, and liability claims, governed by prudential capital reserves and risk-based pricing models. The sector operates on long-duration liability matching for life products and annual renewable structures for property and casualty lines, serving both wealth protection and risk transfer purposes. Term life products lead premium flows among life segments due to straightforward structures and lower acquisition costs, while health insurance within coverage type captures expanding margin pools as an aging population elevates claims frequency. Online platforms within distribution channel represent the fastest-growing access point, though brokers retain control over complex commercial placements.
APRA enforces risk-based capital standards that determine minimum capital holdings and dictate product design constraints across the sector. ASIC oversees disclosure requirements and consumer protection frameworks that shape policy documentation and sales conduct standards. The Australian Competition and Consumer Commission monitors distribution practices and premium transparency. Stakeholders must monitor how climate scenario testing requirements will reshape property underwriting appetite and regional coverage availability.
Market Dynamics
APRA's climate scenario testing mandate is forcing insurers to reprice property exposure across flood-prone catchments, compressing risk appetite in regional Queensland and northern New South Wales while redirecting capital toward metropolitan portfolios.
Growth Catalysts
- Embedded insurance APIs:Non-insurance platforms in automotive retail and property settlement are integrating point-of-sale coverage activation, lowering acquisition friction for motor and home policies.
- APRA CPS 230 operational risk standards:The prudential framework mandates enhanced resilience investment, creating compliance-driven demand for cyber and business interruption coverage among mid-market enterprises.
- Queensland cyclone pool mechanics:State-backed reinsurance facilities reduce insurer capital strain for catastrophe-exposed lines, sustaining underwriting capacity where private markets would otherwise contract.
Market Restraints
- Reinsurance cost pass-through:Hard market conditions in international retrocession are elevating property treaty pricing, compressing domestic insurer margins without commensurate premium recovery.
- Concentrated broker control:Steadfast and Aon dominate commercial placement flows, constraining direct channel penetration and elevating distribution economics for mid-tier carriers.
- Legacy core system debt:Policy administration platforms built on 1990s architectures impose integration costs that deter product innovation velocity relative to digital-native entrants.
Strategic Opportunities
- Tasmanian commercial lines underpenetration:Lower incumbent density relative to premium growth in Hobart's professional services cluster creates white space for specialized liability and D&O offerings.
- ASIC sustainable finance disclosure alignment:Mandatory climate risk reporting for ASX-listed entities is generating advisory and assurance demand that insurers can capture through integrated risk services.
- Parametric trigger convergence with IoT sensors:Index-based crop and weather products paired with remote monitoring hardware enable automated claims settlement for agricultural portfolios.
Industry Challenges
- Actuarial climate modeling capability gaps:Shortage of catastrophe modelers with regional flood and bushfire calibration experience delays product repricing cycles.
- Multi-channel data architecture fragmentation:Inconsistent customer records across direct, broker, and embedded platforms impede lifetime value analytics and cross-sell execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Life and Non-Life Insurance Market |
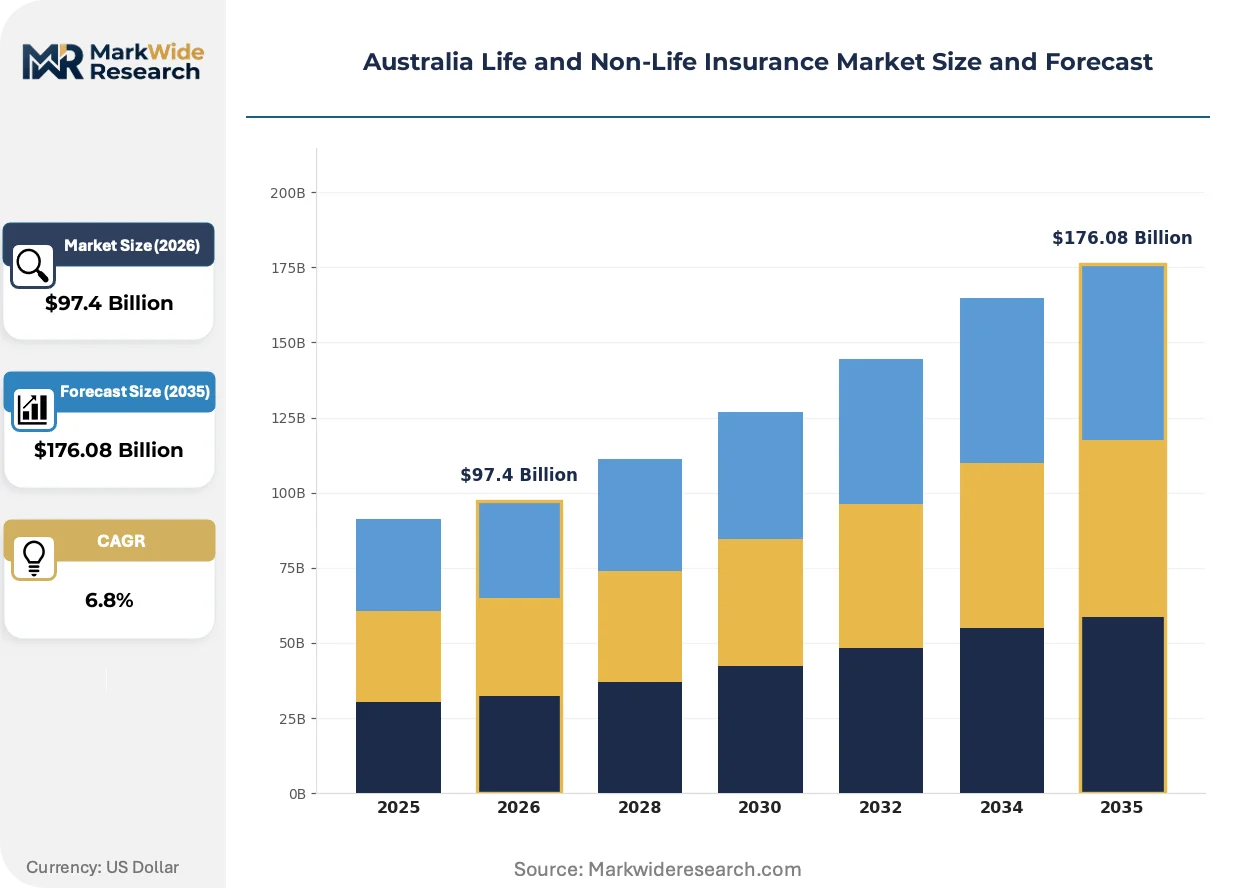
| Market Size in 2026 | $97.4 Billion |
| Market Size in 2035 | $176.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Term Life, Whole Life, Endowment, Universal Life Coverage Type: Health Insurance, Property Insurance, Vehicle Insurance, Travel Insurance Distribution Channel: Brokers, Direct Sales, Online Platforms, Agents Customer Type: Individuals, Corporates, SMEs, Institutions |
| Companies Covered | QBE Insurance Group, Suncorp Group, TAL Life Limited, Acenda, Allianz Australia, AIA Australia Limited, Insurance Australia Group (IAG), Resolution Life Australasia Limited, Zurich Australia Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Life and Non-Life Insurance Market Strategic Shifts
Digital distribution infrastructure is compressing policy origination costs while regulatory disclosure mandates are elevating data transparency requirements across the value chain.
Telematics-enabled usage-based motor coverage is supplanting traditional annual rating factors in personal auto lines. Younger policyholders in Victoria and New South Wales are migrating to pay-per-kilometer structures at accelerating velocity. This shift is compressing risk pooling efficiency for conventional annual policies while enabling granular pricing that rewards low-mileage behavior.
ASIC's design and distribution obligations under the Financial Services Reform Act are reshaping product governance workflows. Insurers must now document target market determinations before launch, elevating compliance overhead. SME packaged products face the steepest adaptation burden as historical broad-market positioning conflicts with narrowed eligibility criteria.
Broker disintermediation in simple personal lines is accelerating as direct digital platforms capture comparison-shopping behavior. Price-sensitive home and motor buyers in metropolitan markets are migrating to aggregator-enabled purchase journeys. This pattern concentrates broker value in complex commercial placements where coverage tailoring and claims advocacy retain pricing power.
Australia Life and Non-Life Insurance Market Segmentation
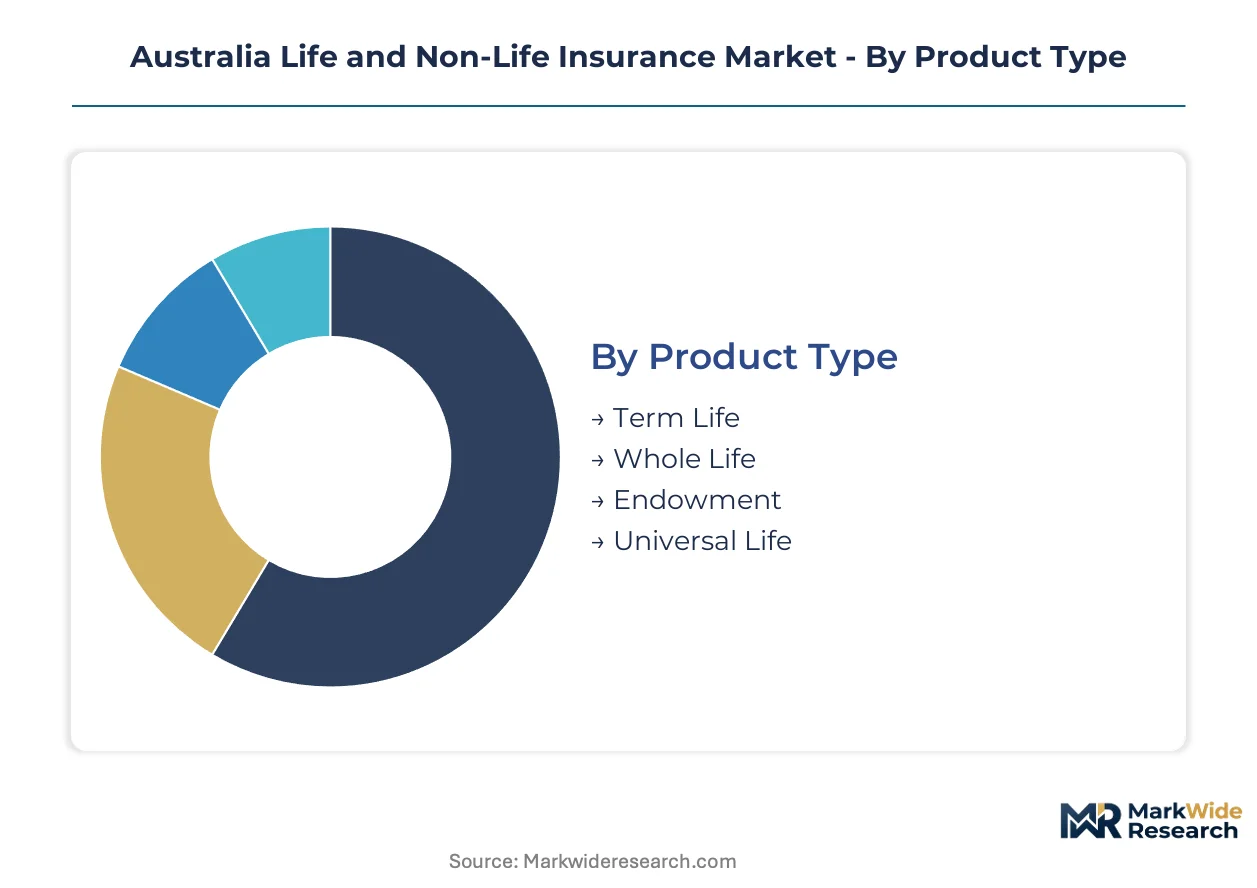
Segmentation reveals where capital flows concentrate across Australia's insurance landscape. Product design constraints from APRA's prudential framework and shifting distribution economics reshape profitability pools by category.
Product Type:
Margin pools concentrate in products with lower acquisition costs and simpler liability matching requirements.
- Term Life:Fixed-duration mortality coverage with no cash value accumulation. Premium flows dominate in New South Wales and Victoria where professional services employment elevates income protection demand alongside basic death benefits. APRA's capital standards favor the straightforward liability structure.
- Whole Life:Permanent coverage bundling mortality protection with investment-linked cash value. Queensland's aging demographic concentrates demand for estate planning vehicles with tax-advantaged accumulation. Legacy system constraints slow product innovation velocity relative to term structures.
- Endowment:Savings-linked life contracts maturing at specified dates. Corporate trustee demand in Melbourne's financial sector sustains placement volumes.
- Universal Life:Flexible premium and adjustable death benefit structures. Policy administration complexity limits distributor appetite outside specialized advisory channels.
Term Life holds installed capacity. Universal Life is rotating up the share rankings.
Coverage Type:
Claims frequency patterns and regulatory disclosure burdens split profitability across protection categories.
- Health Insurance:Medical expense reimbursement and hospital coverage. Australia's aging population in Adelaide and Perth elevates claims frequency while community rating rules compress risk selection flexibility. ASIC's design obligations impose elevated product governance overhead.
- Property Insurance:Physical asset protection against fire, flood, and catastrophe perils. APRA's climate scenario testing mandate forces repricing across northern New South Wales floodplains, redirecting capital toward metropolitan Melbourne and Sydney portfolios.
- Vehicle Insurance:Motor damage and third-party liability coverage. Telematics-enabled usage-based products gain traction among younger policyholders in Victoria's urban corridors.
- Travel Insurance:Trip cancellation and medical evacuation protection. Post-pandemic recovery concentrates demand in outbound tourism from Sydney and Brisbane.
Property Insurance anchors premium volume. Health Insurance is climbing the fastest as margin pools expand.
Distribution Channel:
Customer acquisition economics diverge sharply between intermediated and direct pathways.
- Brokers:Independent intermediaries placing complex commercial and high-net-worth coverage. Steadfast and Aon control placement flows in Sydney's commercial lines market, constraining direct channel penetration.
- Direct Sales:Insurer-employed channels bypassing external intermediation. Suncorp's integrated banking footprint in Queensland sustains proprietary distribution economics.
- Online Platforms:Digital comparison and purchase journeys for standardized personal lines. Melbourne and Sydney price-sensitive motor buyers migrate to aggregator-enabled purchase paths at accelerating velocity.
- Agents:Tied representatives with exclusive carrier relationships. Regional Victoria and Tasmania retain higher agent dependency for face-to-face consultation.
Brokers hold installed capacity. Online Platforms are rotating up the share rankings.
Customer Type:
Risk sophistication and purchasing power determine service model economics across buyer segments.
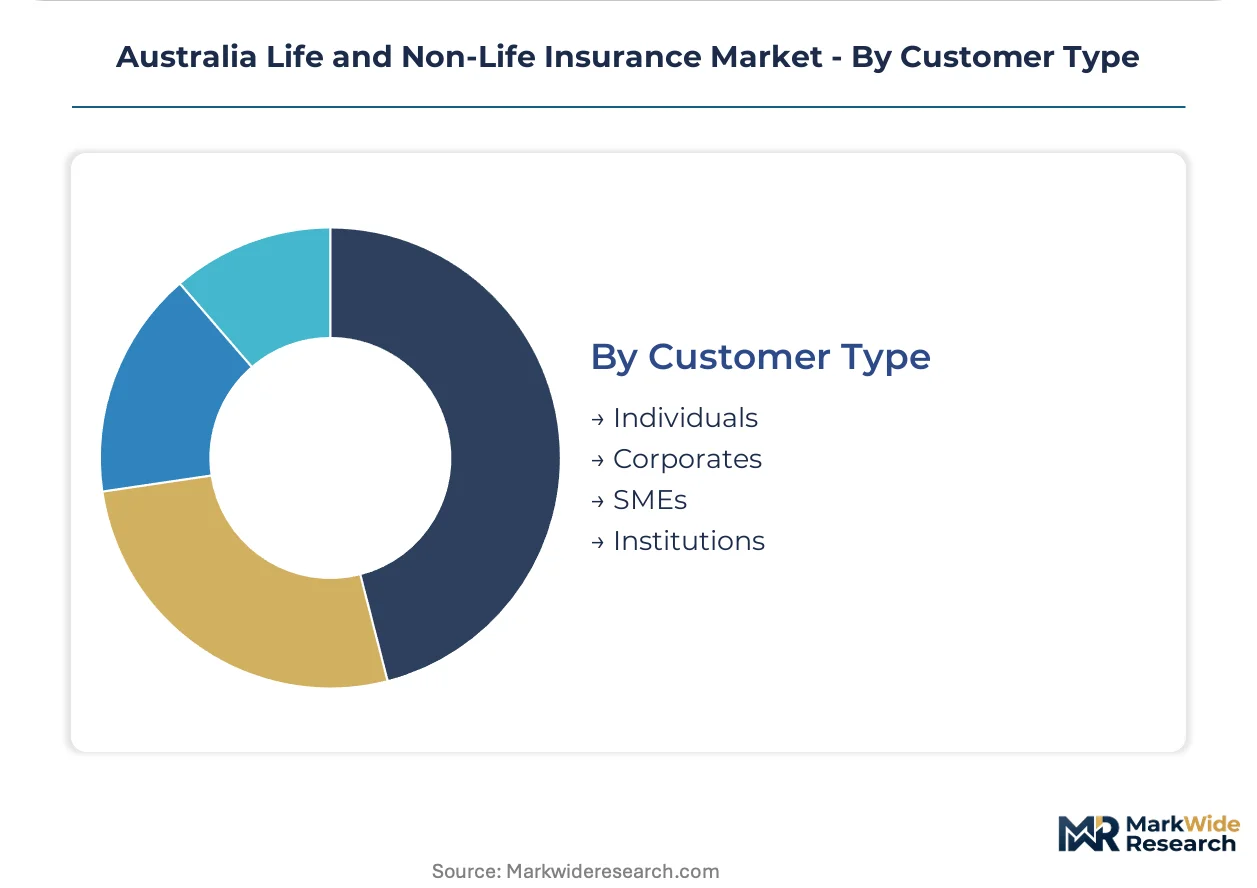
- Individuals:Personal purchasers of life, health, and property protection. New South Wales household formation rates sustain premium growth in core motor and home lines.
- Corporates:Large enterprises procuring group life, D&O, and commercial property programs. ASX-listed entities in Sydney's CBD generate advisory demand through mandatory climate risk reporting.
- SMEs:Small and medium enterprises with packaged coverage needs. Digital distribution lowers barriers to tailored coverage in Hobart's professional services cluster.
- Institutions:Superannuation funds and government entities with captive or pooled arrangements. APRA CPS 230 operational risk standards drive cyber and business interruption procurement.
Individuals hold installed capacity. SMEs are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New South Wales commands premium pricing power through Sydney's concentrated commercial activity and elevated property values, while Queensland's cyclone exposure compresses underwriting margins and redirects capital toward metropolitan portfolios.
New South Wales
Sydney's CBD generates concentrated demand for D&O and professional indemnity coverage as ASX-listed entities expand procurement. APRA's climate scenario testing mandates reshape capital allocation across flood-prone catchments. The professional services cluster in North Sydney drives group life and income protection volumes.
Victoria
Melbourne's financial sector sustains endowment and corporate trustee placement volumes alongside SME packaged coverage growth. ASIC's design and distribution obligations elevate compliance overhead for product governance workflows. The city's telematics adoption rates lead national migration toward usage-based motor structures.
Queensland
Brisbane's outbound tourism recovery concentrates travel insurance demand while state-backed cyclone reinsurance facilities sustain catastrophe capacity. The state's aging demographic elevates whole life demand for estate planning vehicles. Gold Coast property development elevates construction and liability coverage procurement.
Western Australia
Perth's mining and resources sector drives specialized commercial lines and group life programs for fly-in-fly-out workforces. The state's superannuation fund concentration elevates captive and pooled arrangement complexity. Fremantle's port activity sustains marine and cargo insurance flows.
South Australia
Adelaide's aging population elevates health insurance claims frequency while community rating rules compress risk selection flexibility. The city's emerging professional services cluster creates white space for tailored SME liability offerings. APRA CPS 230 standards drive cyber coverage procurement among mid-market enterprises.
Australia Life and Non-Life Insurance Market Competitive Environment
Concentration sits with integrated banking-insurance conglomerates and global underwriting specialists. Three domestic groups control placement flows across personal lines and Queensland regional markets. The sector organizes around scale-driven incumbents, global commercial specialists, and digital distribution challengers. Competitive moves center on embedded insurance API partnerships and legacy core system modernization programs.
Among the scale-driven domestic tier, Insurance Australia Group and Suncorp Group exemplify integrated distribution models, while QBE Insurance Group occupies a position as the global commercial specialist with Australian roots. These three anchors represent divergent capital intensity strategies across personal lines, regional banking integration, and international underwriting footprint expansion.
| Leading Market Players |
|---|
| QBE Insurance Group |
| Suncorp Group |
| TAL Life Limited |
| Acenda |
| Allianz Australia |
| AIA Australia Limited |
| Insurance Australia Group (IAG) |
| Resolution Life Australasia Limited |
| Zurich Australia Limited |
| Others |
Value Chain & Pricing Dynamics
Annual renewable contract structures lock in premium visibility for property and casualty lines while exposing insurers to catastrophe repricing cycles. This mechanism binds capital adequacy planning to reinsurance treaty renewal timing across the Australian market.
Pricing Analysis
The customization-premium spread separates tailored commercial placements from standardized personal lines products. Broker-intermediated commercial coverage commands substantial pricing power through coverage tailoring and claims advocacy services, while direct-channel motor and home policies face compression from aggregator-enabled comparison shopping. Price differentiation hinges on risk selection granularity and distribution channel control, with metropolitan portfolios in Sydney and Melbourne capturing rate adequacy advantages over regional flood-exposed catchments. SME buyers exhibit highest price sensitivity due to packaged coverage bundling, whereas ASX-listed corporates prioritize coverage breadth over premium minimization.
Supply Chain Analysis
Just-in-time capital deployment through offshore reinsurance markets dominates Australian insurer risk transfer strategies. Risk capital flows from Bermuda, London, and Singapore retrocession markets, with treaty pricing volatility in international hubs transmitting directly to domestic underwriting margins. The supply chain rests on catastrophe modeling services from US and UK vendors, actuarial talent pools concentrated in Sydney and Melbourne, and regulatory technology providers supporting APRA compliance workflows. Single-source vulnerability sits with international reinsurer capacity contraction during hard market conditions. Distribution runs through broker-controlled placement flows for commercial lines and direct digital platforms for personal lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Steadfast and Aon in commercial placement flows, fragmenting pricing leverage for mid-tier carriers and elevating distribution economics as a strategic battleground.
For Market Incumbents: Shield core personal lines profitability through telematics-enabled usage-based product migration in Victoria and New South Wales. Accelerate legacy core system modernization to match digital-native entrant velocity on embedded insurance API partnerships. Vertical integration into banking distribution, exemplified by Suncorp's Queensland footprint, retains channel control advantages against broker concentration.
For New Entrants and Emerging Players: Anchor in Tasmanian commercial lines underpenetration where lower incumbent density relative to Hobart's professional services growth creates white space for specialized liability and D&O offerings. Target SME packaged coverage through digital distribution platforms that lower acquisition friction relative to broker-dependent mid-tier carriers. Parametric trigger products paired with IoT sensor networks offer automated claims settlement differentiation for agricultural portfolios.
For Investors and Strategic Acquirers: Capital is best deployed toward digital distribution challengers with embedded insurance API capabilities and clean data architectures unburdened by legacy system debt. Long-term viability favors platforms demonstrating customer lifetime value analytics across multi-channel touchpoints. The signal to watch is APRA climate scenario testing mandate compliance velocity as a proxy for underwriting discipline and capital allocation quality.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Insurance API Integration | Automotive retail and property settlement platforms in Melbourne activate point-of-sale coverage, reducing acquisition friction. |
| Legacy Core System Modernization | Policy administration platform replacement enables product innovation velocity matching digital-native competitor cycles. |
| Telematics-Enabled Product Launch | Pay-per-kilometer motor coverage captures younger policyholder migration in Victoria's urban corridors. |
| Parametric Trigger Convergence | Index-based crop products paired with remote monitoring hardware automate agricultural claims settlement. |
| Climate Risk Advisory Service Buildout | ASIC sustainable finance disclosure alignment generates integrated risk services demand from ASX-listed entities. |
Study Parameters
Cross-validation between APRA prudential filings and ASIC disclosure registrations anchors the qualitative findings on regulatory capital requirements and product governance workflows. Primary interviews with chief risk officers, actuarial directors, broker placement specialists, and superannuation fund investment committees combined with secondary analysis of APRA quarterly statistics, ASIC enforcement reports, and reinsurance treaty market commentary. Bottom-up premium flow modeling triangulates against top-down macroeconomic scenario testing.
Sensitivity analysis across climate scenario severity grades, reinsurance pricing cycles, and embedded insurance adoption curves shapes the projection framework. Segmentation dimensions span product type, coverage category, distribution channel, and customer archetype across the modeling period. CAGRs derive from fitted growth curves calibrated to historical premium volume trajectories and demographic demand drivers. Forecast inputs incorporate floodplain exposure repricing timelines and CPS 230 operational risk compliance investment schedules.
Material uncertainties — catastrophic event frequency, international reinsurance market hardening duration, and climate litigation liability emergence — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory stability and demographic trend continuity. Revision becomes warranted when APRA capital adequacy requirement adjustments or ASIC design obligation enforcement intensity crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
North America Business Income Insurance Market
Life and Non Life Insurance
Iran Property and Casualty Insurance Market
Life and Non Life Insurance
Asia-Pacific Life and Annuity Insurance Market
Life and Non Life Insurance
Ireland Life and Non-Life Insurance Market
Life and Non Life Insurance
Sweden Life and Non-Life Insurance Market
Life and Non Life Insurance
Austria Life and Non-Life Insurance Market
Life and Non Life Insurance
Asia Pacific Life & Non-Life Insurance Market
Life and Non Life Insurance
South Korea Life & Non-Life Insurance Market
Life and Non Life Insurance
Life Reinsurance Market
Life and Non Life Insurance
Malaysia Life Insurance Market
Life and Non Life Insurance
Asia Life and Non-Life Insurance Market
Life and Non Life Insurance
Teenager Life Insurance Market
Life and Non Life Insurance
USA Life and Non-Life Insurance Market
Life and Non Life Insurance
Israel Life and Non-Life Insurance Market
Life and Non Life Insurance
Children Life Insurance Market
Life and Non Life Insurance
Peru Life and Non-Life Insurance Market