
 Asia Life and Non-Life Insurance Market | 2026-2036
Asia Life and Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Life and Non-Life Insurance Market Outlook
China's digital infrastructure build-out is reshaping distribution economics across the Asia Life and Non-Life Insurance Market. Ping An Insurance leverages its technology stack to integrate health services with underwriting, cutting acquisition costs. China Life Insurance anchors the state-backed pension segment through exclusive bancassurance partnerships with major lenders. Nippon Life Insurance sustains dominance in Japan's yen-denominated whole-life category through proprietary actuarial models.
Asia life and non-life insurance encompasses risk-pooling contracts where insurers collect premiums to fund mortality, morbidity, or property-liability contingencies, with solvency ratios and claim-reserve adequacy serving as core operational parameters. The primary purpose centers on household financial protection and corporate risk transfer against catastrophic loss events. Term life products lead volume in emerging Southeast Asian markets where disposable income limits premium capacity. Health insurance within the non-life category is expanding fastest as public hospital systems across the region face capacity constraints. Online platforms are capturing margin pools previously held by agent networks, particularly for standardized auto and term products.
China's NMPA and India's IRDAI enforce capital adequacy and product-approval frameworks that determine market entry feasibility. Japan's FSA maintains strict reserve-valuation standards that shape product design in yen-denominated lines. Stakeholders must monitor regulatory divergence on digital sales licensing, as sandbox approvals in Singapore and Hong Kong create asymmetric channel advantages.
Market Dynamics
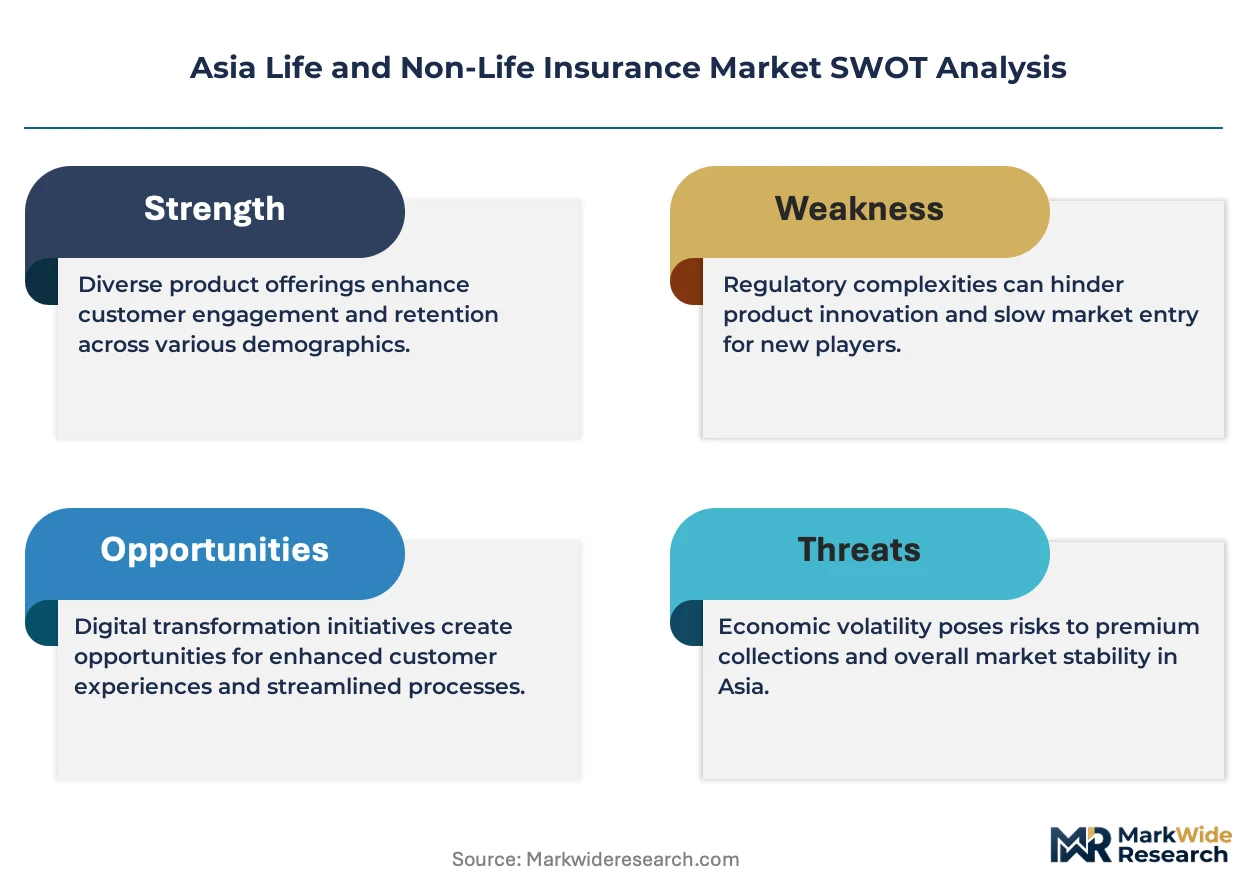
Digital distribution infrastructure is compressing agent commissions and rewiring customer acquisition economics across Asia's insurance sector. InsurTech platforms in Singapore and Hong Kong are capturing premium flows that previously required physical branch networks, forcing incumbents to rebuild their cost structures around API-driven onboarding.
Growth Catalysts
- IRDAI Foreign Ownership Liberalization:India's regulatory easing permits wholly-owned subsidiaries, accelerating capital deployment from European and Japanese insurers into underpenetrated rural districts.
- Health Service Integration:Wearable biometric data streams enable dynamic underwriting models that price mortality risk in real time, expanding addressable markets among younger demographics.
- Tier-One City Affluence Concentration:Shanghai, Beijing, and Shenzhen households are stacking investment-linked policies atop base protection, lifting average premium per policyholder.
Market Restraints
- Reserve Valuation Stringency:Japan's FSA mandates conservative discount rates for yen-denominated whole-life reserves, compressing product margins and limiting competitive pricing flexibility.
- Agent Network Fixed Costs:Southeast Asian markets retain high-touch distribution dependencies, with commission loads consuming 35-50% of first-year premiums and resisting digitization.
- Public Hospital Capacity Constraints:Health insurance claim ratios spike where government healthcare infrastructure fails, exposing non-life carriers to adverse selection in outpatient coverage lines.
Strategic Opportunities
- MSME Commercial Expansion:Vietnam, Indonesia, and Philippines micro-enterprises lack standardized property-liability coverage, creating whitespace for parametric weather and cyber products.
- Sandbox Licensing Asymmetry:Hong Kong's Insurance Authority and Singapore's MAS digital-only licenses enable pure-play InsurTechs to bypass capital requirements imposed on traditional balance sheets.
- Pension System Gaps:China's third-pillar voluntary pension framework remains underdeveloped, opening channels for annuity products targeting aging urban populations.
Industry Challenges
- Actuarial Talent Scarcity:Predictive modeling and machine learning deployment outpaces supply of credentialed professionals who bridge statistical rigor with regulatory compliance.
- Core System Modernization:Legacy policy administration platforms across mid-tier Japanese and Korean carriers impede real-time data integration with health service partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Life and Non-Life Insurance Market |
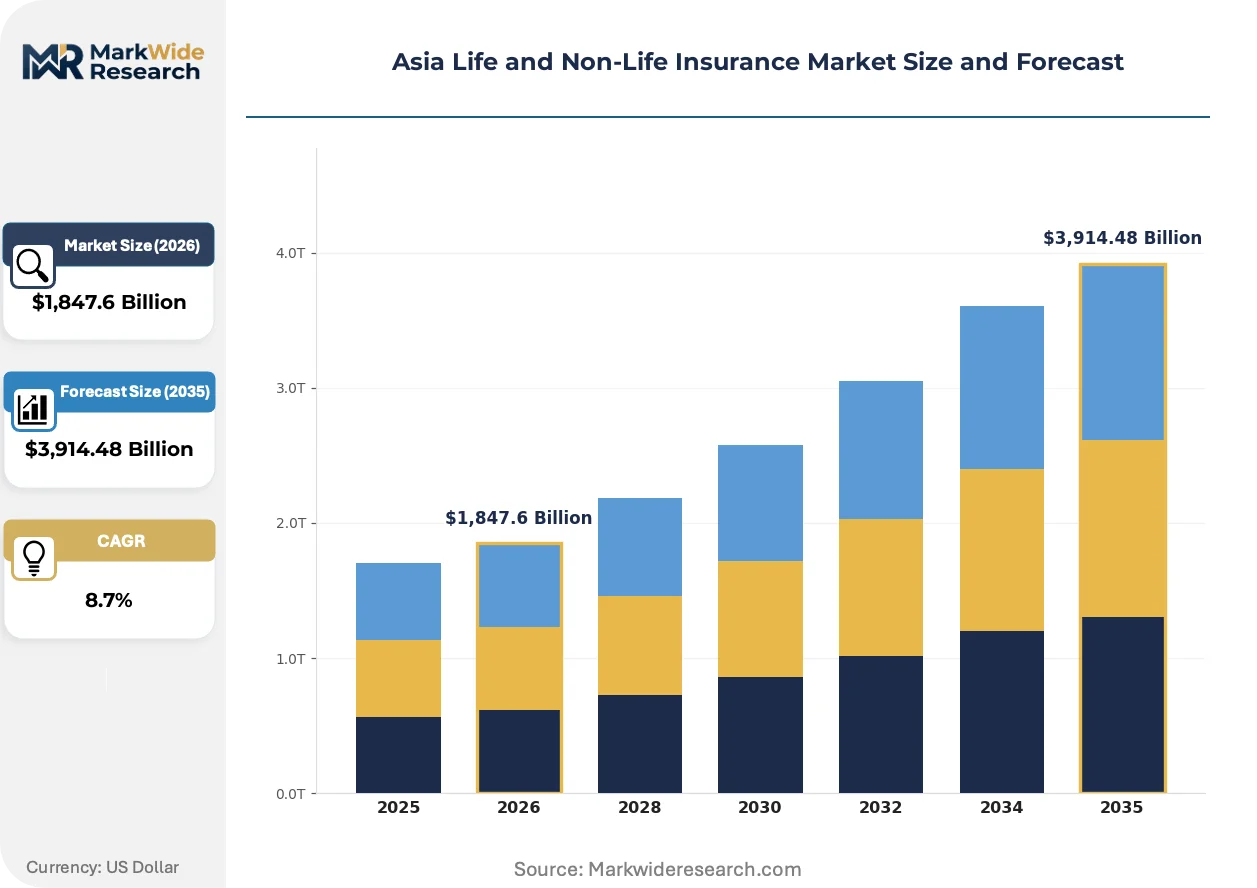
| Market Size in 2026 | $1,847.6 Billion |
| Market Size in 2035 | $3,914.48 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Term Life, Whole Life, Endowment, Universal Life Inception Year: Pre-2000, 2000-2010, 2011-2020, Post-2020 Insurance Type: Health, Auto, Property, Liability Distribution Channel: Brokers, Direct Sales, Online Platforms, Agents |
| Companies Covered | DBS Bank, QBE Insurance Group, China Life Insurance, SBI Life Insurance, Bank of the Philippine Islands, Ping An Insurance, Commonwealth Bank, Nippon Life Insurance, AIA Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Life and Non-Life Insurance Market Strategic Shifts
Embedded insurance distribution is dissolving traditional boundaries between risk transfer and transactional platforms. Carriers now compete to insert coverage into e-commerce checkouts, ride-hailing apps, and supply chain finance workflows.
Telematics-enabled usage-based auto coverage is virtualizing risk assessment from annual policy reviews to continuous driving behavior monitoring. Chinese and South Korean fleet operators are adopting these models fastest, with premium adjustments flowing weekly rather than yearly. This compression of pricing cycles is virtualizing the traditional annual renewal relationship into an ongoing data exchange.
China's NMPA and India's IRDAI are tightening algorithmic governance standards for automated underwriting decisions. Insurers must now document model training data and bias testing protocols before deploying AI-driven pricing engines. Health and motor lines face the steepest compliance burdens, with several carriers pausing rollout of fully automated quote systems pending regulatory clarity.
Direct-to-consumer platforms are capturing term life and standardized health volumes that agents previously controlled. Younger buyers in Jakarta, Bangkok, and Manila complete purchases via mobile apps without intermediary consultation. This channel migration is most pronounced among digitally native demographics purchasing simple, non-participating products with transparent benefit structures.
Asia Life and Non-Life Insurance Market Segmentation
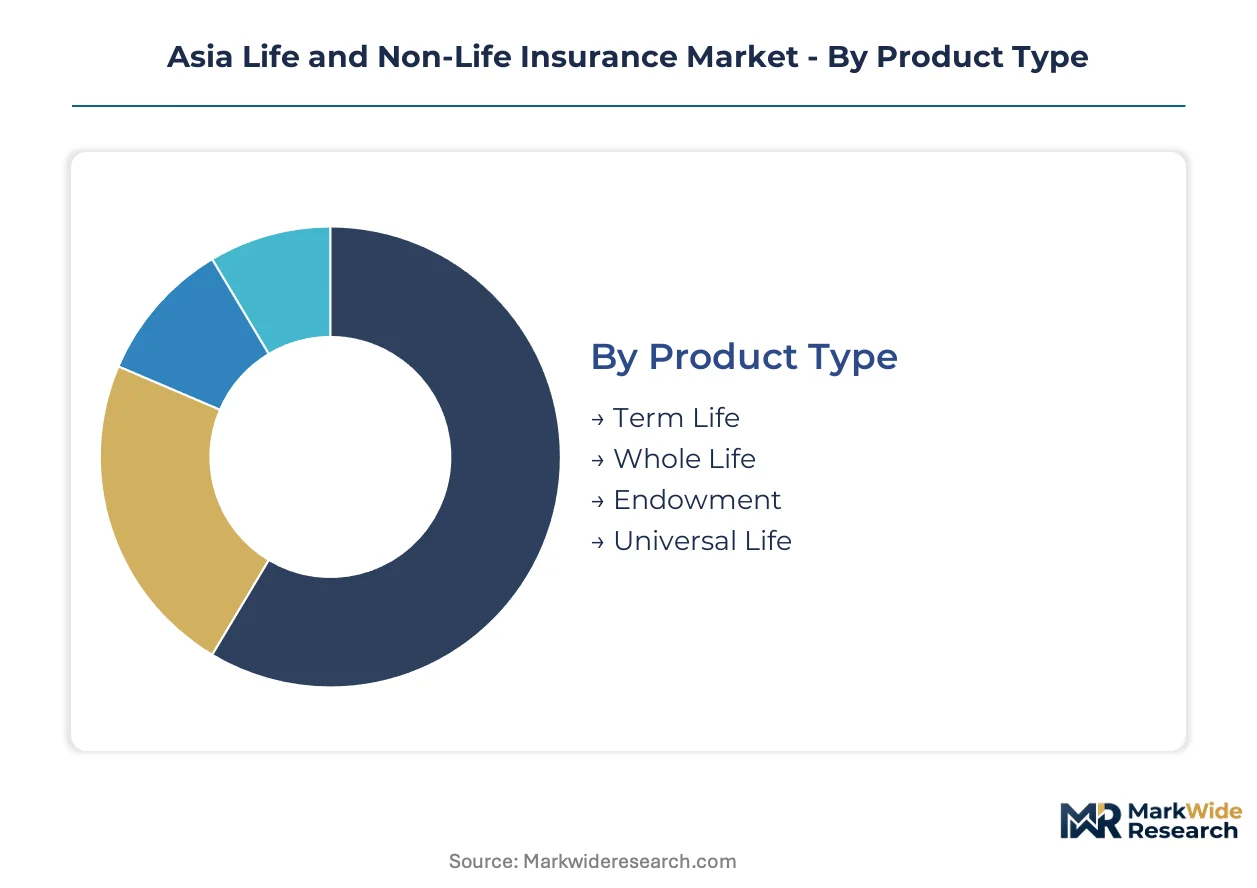
Segmentation reveals how premium flows concentrate across product architectures, distribution economics, and regulatory vintage in Asia's insurance landscape. Disparities in commission structures, solvency requirements, and customer acquisition costs create divergent margin profiles by category.
Product Type:
Cost tier differentiation separates mass-market accessibility from affluent wealth accumulation strategies across life insurance lines.
- Term Life:Pure mortality coverage with no cash value component, priced on age-banded risk curves. Demand concentrates in Indonesia, Vietnam, and Philippines where household disposable income caps premium capacity; digital direct-to-consumer platforms are compressing acquisition costs below traditional agent-loaded structures.
- Whole Life:Permanent coverage bundling guaranteed death benefit with conservative cash value accumulation. Japan's FSA reserve-valuation stringency shapes product economics, with Nippon Life and domestic incumbents dominating yen-denominated issuance through proprietary mortality tables.
- Endowment:Savings-linked contracts maturing at fixed intervals with survival benefits. China's tier-one cities anchor demand as affluent households layer forced-savings mechanisms atop base protection.
- Universal Life:Flexible premium and adjustable death benefit structures tied to declared crediting rates. Singapore's dollar-denominated issuance attracts regional HNWI flows seeking currency diversification.
Term Life commands the established base across emerging Southeast Asia. The steepest expansion runs through Universal Life as wealth management integration deepens.
Inception Year:
Regulatory vintage captures how solvency regimes, commission caps, and product-approval frameworks have evolved across successive regulatory eras.
- Pre-2000:Legacy books issued under permissive commission structures and loose reserve standards. Japan's FSA and China's former CIRC imposed retrospective solvency requirements that forced recapitalizations.
- 2000-2010:Products shaped by post-Asian financial crisis prudential tightening. India's IRDAI establishment and China's insurance law revisions introduced risk-based capital frameworks.
- 2011-2020:Digital distribution emergence and bancassurance channel expansion characterized this era. China's NMPA and India's IRDAI tightened product-approval timelines while expanding foreign participation caps.
- Post-2020:Algorithmic governance and embedded distribution define current issuance. Singapore's MAS and Hong Kong's Insurance Authority sandbox approvals enable InsurTech-native product architectures.
Pre-2000 books command the established base through embedded value release. The steepest expansion runs through Post-2020 issuance as API-driven distribution scales.
Insurance Type:
Application-specific risk pools separate mortality-driven life contracts from property-liability contingencies in non-life lines.
- Health:Medical expense reimbursement and critical illness lump-sum coverage. Public hospital capacity constraints across Thailand, Indonesia, and Philippines drive claim ratio volatility; outpatient coverage lines face adverse selection where government infrastructure fails.
- Auto:Motor third-party liability and own-damage coverage. Chinese and South Korean fleet operators are adopting telematics-enabled usage-based models fastest, with premium adjustments flowing weekly rather than annually.
- Property:Fire, engineering, and natural catastrophe coverage for commercial and residential assets. Vietnam, Indonesia, and Philippines micro-enterprises lack standardized coverage, creating whitespace for parametric weather products.
- Liability:Professional indemnity, product liability, and directors-and-officers coverage. Cyber liability is expanding fastest as MSME digitalization exposes new risk vectors.
Auto commands the established base through mandatory coverage requirements. The steepest expansion runs through Health as public system capacity constraints deepen.
Distribution Channel:
Customer type and channel economics determine acquisition cost structures and persistency rates across the policy lifecycle.
- Brokers:Independent intermediaries placing commercial risks across multiple carriers. Southeast Asian commercial lines retain broker dependency due to complex risk customization requirements.
- Direct Sales:Carrier-employed forces targeting corporate group policies and affinity schemes. China's state-owned insurers anchor pension segment through exclusive bancassurance partnerships with major lenders.
- Online Platforms:API-driven onboarding with automated underwriting and instant policy issuance. Younger buyers in Jakarta, Bangkok, and Manila complete purchases via mobile apps without intermediary consultation.
- Agents:Tied representatives earning commission-loaded compensation. Commission loads consume 35-50% of first-year premiums in Southeast Asian markets, resisting digitization.
Agents command the established base through relationship-driven persistency. The steepest expansion runs through Online Platforms as standardized product digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital deployment concentrates in regulatory jurisdictions with foreign ownership liberalization and digital distribution sandbox approvals. India's IRDAI reforms and Singapore's MAS licensing frameworks attract disproportionate investment flows relative to legacy reserve-stringent markets.
China
Affluent households in Shanghai, Beijing, and Shenzhen are layering investment-linked products over base protection coverage. The NMPA enforces algorithmic governance standards for automated underwriting decisions, requiring documented model training data and bias testing protocols. Ping An Insurance anchors the technology-integrated health segment through proprietary platforms that merge underwriting with health services.
India
IRDAI's foreign ownership liberalization permits wholly-owned subsidiaries, accelerating European and Japanese capital into underpenetrated rural districts. The regulator's risk-based capital frameworks shape product-approval timelines and solvency requirements. SBI Life Insurance represents the state-backed distribution tier through extensive bancassurance networks with public sector lenders.
Japan
The FSA mandates conservative discount rates for yen-denominated whole-life reserves, compressing product margins and limiting competitive pricing flexibility. Nippon Life Insurance sustains dominance in the yen-denominated whole-life category through proprietary actuarial models and established mortality tables. Tokyo anchors the regional headquarters functions for multinational reinsurance operations.
Singapore
The MAS digital-only licensing framework enables pure-play InsurTechs to bypass capital requirements imposed on traditional balance sheets. DBS Bank leverages its banking infrastructure to distribute embedded insurance products through transactional platforms. The city-state's regulatory sandbox attracts regional InsurTech platform development targeting Southeast Asian markets.
Australia
QBE Insurance Group occupies a position in the commercial property-liability segment with regional underwriting expertise. The prudential regulator enforces capital adequacy standards that shape reinsurance purchasing patterns. Sydney and Melbourne concentrate actuarial talent pools serving Asia-Pacific risk modeling requirements.
Asia Life and Non-Life Insurance Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in niche risk segments. The market structure tiers between state-backed incumbents with exclusive distribution partnerships and technology-enabled challengers compressing acquisition costs. Two strategic archetypes dominate: bancassurance-anchored conglomerates leveraging captive customer bases, and API-native distributors bypassing agent networks. Competitive moves center on health service integration partnerships and regulatory sandbox licensing applications.
Within the state-backed tier, China Life Insurance and Ping An Insurance exemplify platform-scale operations with integrated technology stacks. AIA Group represents the regional multinational archetype spanning multiple regulatory jurisdictions. Nippon Life Insurance anchors the conservative reserve-management segment with yen-denominated specialization. These three occupy positions reflecting distinct strategic bets on distribution economics versus product margin preservation.
| Leading Market Players |
|---|
| DBS Bank |
| QBE Insurance Group |
| China Life Insurance |
| SBI Life Insurance |
| Bank of the Philippine Islands |
| Ping An Insurance |
| Commonwealth Bank |
| Nippon Life Insurance |
| AIA Group |
| Others |
Value Chain & Pricing Dynamics
Shanghai's concentration of actuarial talent and technology infrastructure anchors pricing power for Asia's digitally integrated carriers, compressing acquisition costs for competitors forced to source equivalent capabilities from dispersed markets. Tier-one city insurers leverage this hub effect to underprice regional rivals on standardized products while extracting premiums on bespoke wealth-management-linked contracts.
Pricing Analysis
Japan's FSA reserve-valuation stringency dictates the pricing tier structure for yen-denominated whole-life products, forcing conservative discount rates that compress margins. Pricing stratifies across proprietary mortality-table tiers, with domestic incumbents commanding premium positioning against foreign entrants lacking historical data depth. Cost compression in the mass-market term segment is intensifying because digital platforms are eliminating agent commission loads. Younger demographics purchasing via mobile apps in Jakarta and Manila exhibit highest price sensitivity, while HNWI segments in Singapore accept currency-diversified universal life premiums with minimal elasticity.
Supply Chain Analysis
Cross-border data localization requirements and algorithmic governance standards restrict technology flows between regulatory jurisdictions, fragmenting underwriting platform deployment. Actuarial modeling capabilities concentrate in Japan, Singapore, and Australia, while health service integration partnerships draw from India's hospital networks and China's biometric wearable ecosystems. Single-source vulnerability runs through proprietary mortality tables held by Nippon Life and domestic Japanese carriers. Distribution runs through API-driven platforms for standardized products, with broker networks retaining dominance in complex commercial lines across Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-moat story where switching costs lock policyholders into legacy books through surrender-charge structures and exclusive bancassurance distribution. Network effects compound as health service integration deepens data advantages for early platform builders.
For Market Incumbents: Insulate core profitability by accelerating vertical integration into health service partnerships before regulatory sandboxes enable challenger bypass of capital requirements. Lock in exclusive bancassurance renewal terms with state-backed lenders in India and China. Defend against InsurTech margin compression by embedding coverage into transactional platforms where switching friction exceeds price sensitivity. For New Entrants and Emerging Players: Pursue sandbox licensing in Singapore and Hong Kong to circumvent traditional solvency burdens while building API-native distribution infrastructure. Vietnam, Indonesia, and Philippines MSME commercial lines offer the most penetrable whitespace, with parametric weather products addressing unmet property coverage gaps. Lead with cyber liability and embedded supply-chain finance coverage where incumbent agent networks lack technical expertise. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory divergence creates asymmetric returns for multi-jurisdictional platform operators capable of arbitraging capital requirements across sandbox and traditional licensing regimes. Target acquisition archetypes include InsurTechs with proven API onboarding technology and established health service data partnerships. Watch for IRDAI further liberalization on foreign ownership as the signal indicating accelerated capital deployment windows into India's rural districts.| Strategic Initiative | Industry Significance |
|---|---|
| Health Service Integration Partnership | Ping An's proprietary platforms merge underwriting with care delivery, cutting acquisition costs below traditional agent models. |
| Regulatory Sandbox Licensing Application | Singapore's MAS digital-only licenses enable pure-play InsurTechs to bypass capital requirements imposed on traditional balance sheets. |
| Exclusive Bancassurance Renewal Negotiation | China Life anchors state-backed pension distribution through locked partnerships with major lenders, creating persistent premium flows. |
| Parametric Product Development | Vietnam and Philippines micro-enterprises lack standardized property coverage, opening whitespace for weather-indexed commercial lines. |
| Algorithmic Governance Compliance Investment | China's NMPA mandates documented model training data and bias testing protocols before deploying AI-driven pricing engines. |
Study Parameters
The analysis maps life insurance product architectures, non-line health and auto segments, distribution channel economics, and regulatory vintage categories, each validated through chief underwriting officers, digital distribution heads, regulatory affairs leads, and health service partnership directors. Primary fieldwork combined with secondary validation from IRDAI and NMPA product-approval filings, FSA reserve-valuation disclosures, and MAS sandbox licensing records enabled bottom-up and top-down triangulation across premium flow estimates and solvency ratio benchmarks.
Assumptions held fixed include current foreign ownership caps outside India's liberalized regime, existing algorithmic governance standards, and sustained tier-one city affluence concentration; variables included sandbox licensing expansion timelines, health service integration penetration rates, and telematics adoption curves. Segmentation dimensions modeled span product type, inception-year regulatory vintage, insurance application category, and distribution channel structure across the projection horizon. CAGRs derived from policy issuance volume trajectories, premium per policyholder expansion patterns, and channel mix shift assumptions, with specific inputs including agent commission load persistence and digital platform capture rates.
Sensitivities concentrate around regulatory revisions to foreign ownership rules, algorithmic governance tightening, and health service integration partnership exclusivity terms. Forecasts reflect documented assumptions on capital adequacy requirements and distribution cost compression timelines. Material shifts in sandbox licensing scope or reserve-valuation stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Indonesia Life and Non-Life Insurance Market
Life and Non Life Insurance
US Burial Insurance Market
Life and Non Life Insurance
South Korea Life & Non-Life Insurance Market
Life and Non Life Insurance
Canada Life and Non-Life Insurance Market
Life and Non Life Insurance
Asia-Pacific Life and Annuity Insurance Market
Life and Non Life Insurance
Germany Life and Non-Life Insurance Market
Life and Non Life Insurance
Asia Pacific Life & Non-Life Insurance Market
Life and Non Life Insurance
Singapore Life and Non-Life Insurance Market
Life and Non Life Insurance
Global Life and Non-Life Insurance Market
Life and Non Life Insurance
Sweden Life and Non-Life Insurance Market
Life and Non Life Insurance
Austria Life and Non-Life Insurance Market
Life and Non Life Insurance
Russia Life and Non-Life Insurance Market
Life and Non Life Insurance
Poland Life and Non-Life Insurance Market
Life and Non Life Insurance
UAE Life & Non-Life Insurance Market
Life and Non Life Insurance
Brazil Life and Non-Life Insurance Market
Life and Non Life Insurance
Japan Life and Non-Life Insurance Market