
 Malaysia Life Insurance Market | 2026-2036
Malaysia Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Life Insurance Market Insights
Unit-linked product tiers with embedded investment wrappers is reorganizing competitive dynamics across Malaysian life insurance. Great Eastern Life Assurance leverages its bancassurance depth with major banking groups to sustain premium flow. AIA Bhd. anchors its position through agency force density in Penang and Johor. Prudential Assurance Malaysia differentiates via health-rider bundling tied to private hospital networks.
Life insurance constitutes a contractual risk-transfer instrument where policyholders pay regular premiums in exchange for guaranteed death benefits, maturity payouts, or periodic annuities, with technical reserves calculated using mortality tables and discounted cash flow models. The product generates long-duration liabilities that insurers match against sovereign bonds, corporate debt, and equity instruments to maintain solvency margins under Bank Negara Malaysia's RBC framework. Whole life and endowment categories command the largest premium pools due to forced savings culture among middle-income households, while health insurance riders attached to base policies represent the fastest-expanding margin segment. Online platforms as a distribution channel are gaining traction among digital-native customer segments, though insurance agents still dominate policy origination for complex products requiring medical underwriting.
Bank Negara Malaysia governs capital adequacy and consumer protection through the Financial Services Act and Islamic Financial Services Act, while the Life Insurance Association of Malaysia enforces market conduct standards and claims settlement timelines. BNM's digital insurer licensing framework is lowering entry barriers for technology-driven distributors, though strict fit-and-proper requirements for directors constrain speculative entrants. Stakeholders must weigh the trade-off between accelerating digital distribution and preserving agent-channel relationships that still drive persistency ratios in semi-urban and rural districts.
Market Dynamics
Bank Negara Malaysia's risk-based capital framework is compressing product development cycles while simultaneously elevating reserve requirements, forcing insurers to rebalance asset-liability matching strategies.
Growth Catalysts
- Digital Insurer Licensing:Bank Negara Malaysia's streamlined licensing pathway enables technology-driven entrants to bypass traditional capital barriers, accelerating distribution innovation.
- Klang Valley Demographics:Young professionals concentrated in Kuala Lumpur and Selangor exhibit elevated demand for investment-linked wrappers tied to equity exposures.
- Bancassurance Infrastructure:Deep banking partnerships provide captive customer access and embedded product placement at point-of-sale touchpoints.
Market Restraints
- Mortality Table Volatility:Long-duration liabilities expose insurers to basis risk when actual longevity diverges from regulatory prescribed assumptions.
- Agent Channel Concentration:Persistency ratios in semi-urban and rural districts remain dependent on individual agent relationships, creating distribution fragility.
- Sovereign Bond Supply Constraints:Duration-matched local currency government securities face scarcity, compressing investment yields on technical reserves.
Strategic Opportunities
- Johor and Penang Penetration:Agency force density remains below Klang Valley levels, presenting whitespace for targeted recruitment and product localization.
- Health-Rider Convergence:Private hospital network partnerships enable bundled propositions that capture margin expansion in medical inflation-linked coverage.
- Embedded Finance Channels:E-commerce platforms and fintech wallets offer policy origination at transaction moments outside traditional insurance touchpoints.
Industry Challenges
- Actuarial Talent Scarcity:Qualified professionals capable of stochastic modeling under RBC requirements command premium compensation, elevating fixed cost structures.
- Legacy System Integration:Core policy administration platforms require costly middleware development to interface with digital distribution front-ends.
- Medical Underwriting Capacity:Physician network access constrains turnaround times for non-standard risk assessments, degrading customer experience metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Life Insurance Market |
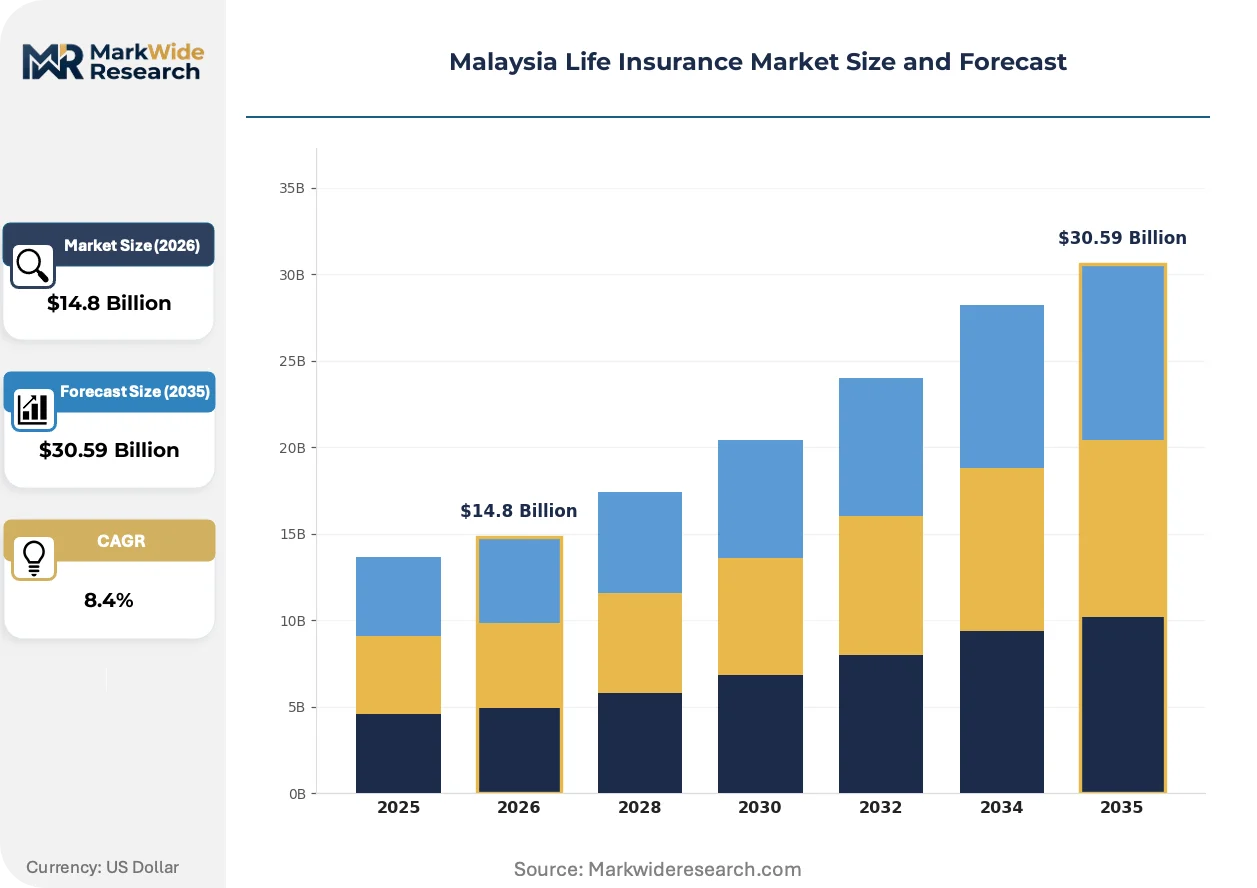
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Term Life, Whole Life, Endowment, Health Insurance Distribution Channel: Banks, Insurance Agents, Online Platforms, Brokers Customer Type: Individual, Family, Corporate, HNWIs Policy Term: 1 Year, 5 Years, 10 Years, Lifetime |
| Companies Covered | Great Eastern Life Assurance (Malaysia) Berhad, AIA Bhd., Prudential Assurance Malaysia Berhad, Etiqa Life Insurance Berhad, Allianz Life Insurance Malaysia Berhad, Hong Leong Assurance Berhad, Sun Life Malaysia Assurance Berhad, Manulife Insurance Berhad, Tokio Marine Life Insurance Malaysia Bhd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Life Insurance Market Trends and Innovations
Technology deployment and regulatory recalibration are compressing traditional distribution hierarchies while elevating data-centric risk selection capabilities across Malaysian life insurance.
Algorithmic underwriting engines is bifurcating the risk assessment process between instant-accept standard lives and referral-track complex cases. Digital-native distributors in Petaling Jaya deploy these tools to compress issuance timelines from weeks to hours. The technology is bifurcating competitive positioning between capital-light direct writers and incumbent agency-heavy models.
Bank Negara Malaysia's Financial Services Act amendments tightened consumer protection standards for investment-linked product disclosures. Insurers must now illustrate downside scenarios with standardized stress-test parameters. Product development teams in Kuala Lumpur are responding by simplifying wrapper structures and reducing equity allocation options.
Subscription-based micro-policies are displacing traditional annual premium collection for mass-market segments. Mobile wallet integration enables automated deduction aligned with salary cycles rather than lump-sum commitments. This pattern concentrates among gig-economy workers in Selangor manufacturing corridors and urban service sectors.
Malaysia Life Insurance Market Segmentation
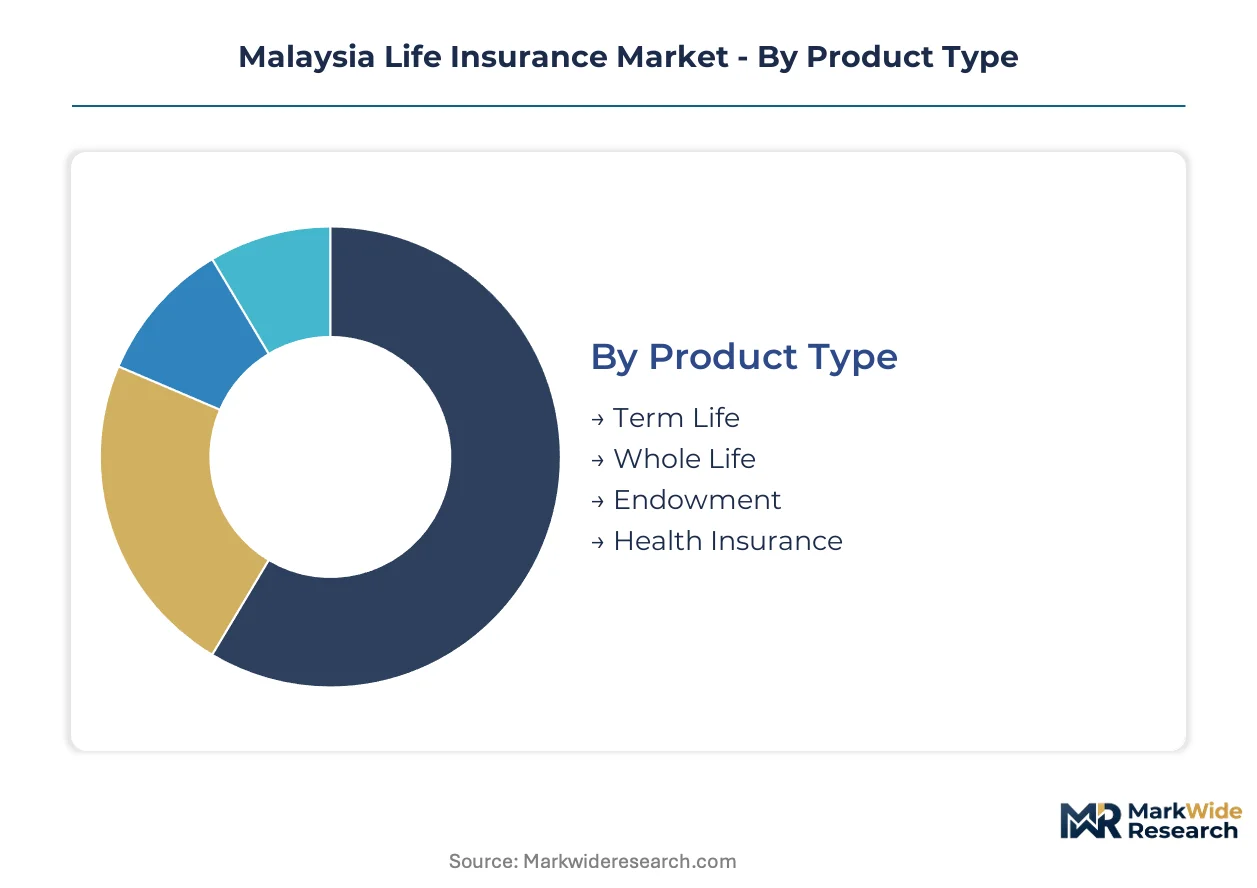
Segmentation in Malaysian life insurance reveals how Bank Negara Malaysia's risk-based capital framework and distribution licensing rules create divergent competitive arenas. Product design, channel economics, and customer acquisition costs vary sharply across these boundaries.
Product Type:
Bank Negara Malaysia applies differentiated reserve requirements and disclosure standards across product categories, directly shaping insurer capital allocation and pricing flexibility.
- Term Life:Pure mortality protection with no cash value accumulation. Demand concentrates among young professionals in Petaling Jaya and central Kuala Lumpur seeking affordable coverage during peak earning years. The stripped-down structure minimizes capital charges under RBC rules.
- Whole Life:Permanent coverage with guaranteed death benefit and accumulating cash reserves. Middle-income households across Selangor favor forced-savings characteristics. Long-duration liabilities strain duration-matching capabilities when sovereign bonds trade scarce.
- Endowment:Savings-linked contracts paying lump sums at maturity or death. Takaful variants compete directly in Muslim-majority districts.
- Health Insurance:Medical expense riders and standalone critical illness coverage. Private hospital network partnerships in Penang and Johor drive rider attachment rates.
Established volume favors Whole Life; emerging adoption favors Health Insurance.
Distribution Channel:
Channel cost structures range from high-commission agency models to technology-fixed digital platforms, with bancassurance occupying a hybrid position.
- Banks:Bancassurance partnerships leverage captive deposit bases and point-of-sale placement. Major banking groups in the Klang Valley corridor sustain premium flow through embedded product offerings. Regulatory caps on commission rates constrain profitability.
- Insurance Agents:Individual representatives dominate complex product origination requiring medical underwriting. Persistency ratios in semi-urban and rural districts outside Kuala Lumpur depend heavily on agent relationships.
- Online Platforms:Digital-native distributors deploy algorithmic underwriting to compress issuance timelines. Mobile wallet integration enables subscription-based micro-policy collection.
- Brokers:Independent intermediaries serve corporate accounts and HNWIs with multi-carrier comparison capabilities.
Agent networks retain the largest premium pool; online platforms are climbing the fastest.
Customer Type:
Customer segmentation determines product complexity, service intensity, and regulatory scrutiny levels under consumer protection mandates.
- Individual:Single-life policies covering personal mortality and health risks. Young professionals in Selangor manufacturing corridors drive uptake of investment-linked wrappers.
- Family:Multi-life coverage spanning breadwinner protection and dependent health benefits. Premium collection aligns with household budgeting cycles.
- Corporate:Group life and employee benefit schemes. Employers in Johor's industrial zones use coverage as retention instruments.
- HNWIs:High-net-worth individuals requiring estate planning and sophisticated wealth transfer structures. Private banking relationships facilitate placement.
Individual policies generate the highest transaction volume; HNWI accounts yield the steepest expansion trajectory.
Policy Term:
Duration selection directly impacts insurer asset-liability matching strategies and exposure to mortality table basis risk.
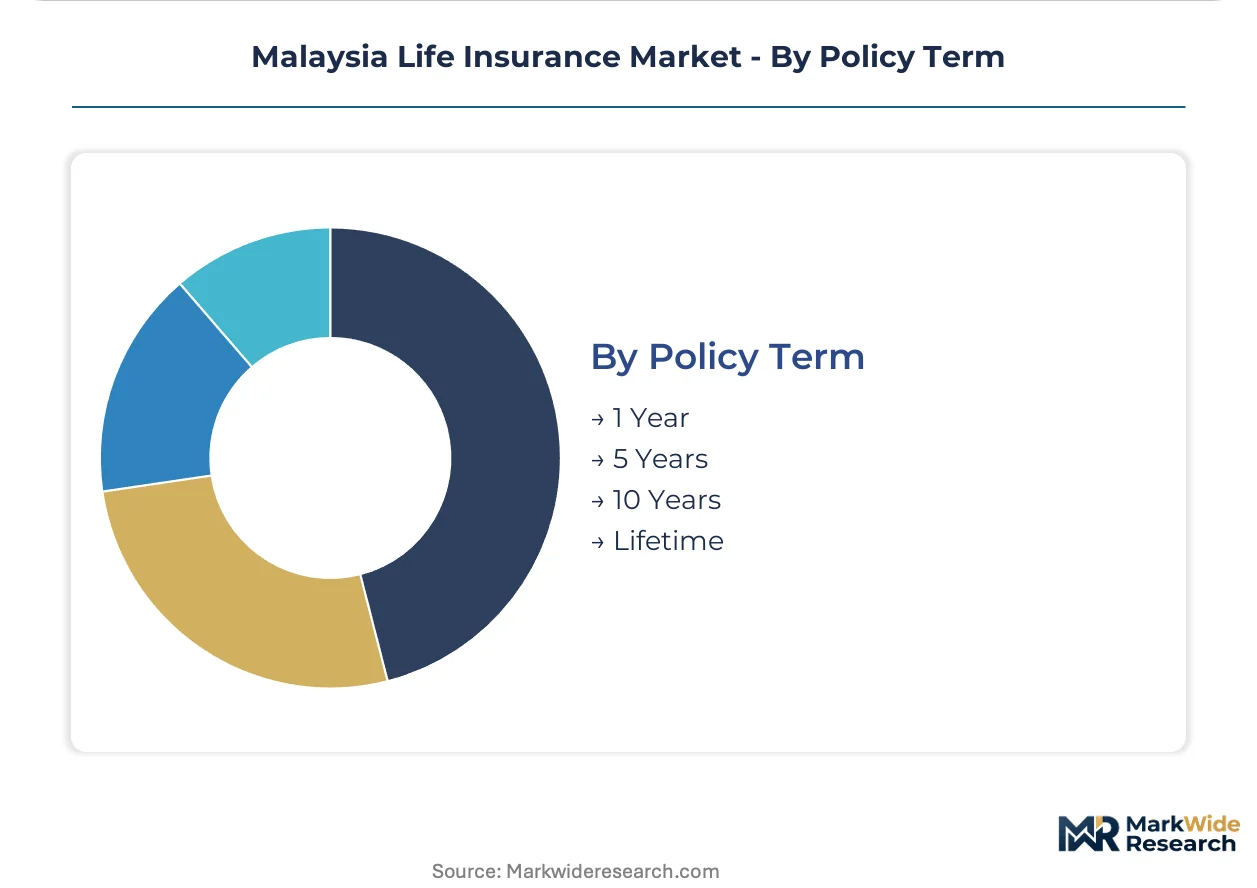
- 1 Year:Annual renewable term with premium adjustment rights. Gig-economy workers favor flexibility over long-term commitment.
- 5 Years:Medium-term horizon balancing affordability with rate stability. Popular among entry-level professionals in urban service sectors.
- 10 Years:Decade-long protection with level premiums. Family breadwinters match coverage to mortgage amortization schedules.
- Lifetime:Permanent coverage extending to mortality. Whole life and endowment structures dominate this category.
Lifetime policies command the largest reserve base; 1-year terms are gaining share fastest among digital-native segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian life insurers export protection products to Singaporean wealth management clients and Indonesian HNWIs seeking ringgit-denominated stability. Cross-border premium flows concentrate through Labuan International Business and Financial Centre.
Klang Valley
Young professionals in Kuala Lumpur and Petaling Jaya drive uptake of investment-linked policies with equity exposure. Bank Negara Malaysia's digital insurer licensing framework accelerates fintech distribution in this corridor. Agency recruitment concentrates in Mont Kiara and Bangsar South financial districts.
Penang
Medical tourism infrastructure supports health-rider bundling with private hospital networks. The state's manufacturing base generates corporate group life demand from electronics and semiconductor employers. Georgetown and Bayan Lepas anchor bancassurance penetration through banking partnerships.
Johor
Proximity to Singapore creates cross-border policy origination for wealth transfer structures. Iskandar Malaysia's special economic zone incentives attract regional insurer back-office operations. Johor Bahru and Pasir Gudang industrial zones sustain employer-sponsored coverage growth.
Sarawak
Rural persistency ratios depend on agent-channel relationships in semi-urban districts. State-level bancassurance partnerships with regional banking groups expand access points. Kuching and Miri serve as distribution hubs for indigenous community outreach programs.
Malaysia Life Insurance Market Competitive Landscape
Listed leaders compete with private specialists across capital structure and distribution depth. The market exhibits moderate consolidation with tiered positioning between bancassurance-heavy incumbents and agency-driven traditionalists. Three archetypes dominate: banking-integrated conglomerates, pan-Asian regional carriers, and domestic specialist underwriters. Competitive moves center on health-rider convergence with hospital networks and embedded finance partnerships with digital wallets.
Among banking-integrated conglomerates, Great Eastern Life Assurance (Malaysia) Berhad and Hong Leong Assurance Berhad exemplify captive distribution through deposit-base access. AIA Bhd. and Prudential Assurance Malaysia Berhad occupy positions as pan-Asian regional carriers with agency force density in secondary cities. These anchors represent divergent capital-light versus capital-intensive pathways under Bank Negara Malaysia's risk-based capital framework.
| Leading Market Players |
|---|
| Great Eastern Life Assurance (Malaysia) Berhad |
| AIA Bhd. |
| Prudential Assurance Malaysia Berhad |
| Etiqa Life Insurance Berhad |
| Allianz Life Insurance Malaysia Berhad |
| Hong Leong Assurance Berhad |
| Sun Life Malaysia Assurance Berhad |
| Manulife Insurance Berhad |
| Tokio Marine Life Insurance Malaysia Bhd. |
| Others |
Pricing and Supply Chain Analysis
Bank Negara Malaysia's risk-based capital framework gates both product qualification and premium differentiation simultaneously. Insurers holding higher capital adequacy ratios command pricing flexibility on investment-linked wrappers, while constrained players compete on stripped-down term life products with minimal reserve charges.
Pricing Analysis
Young professionals in Petaling Jaya and central Kuala Lumpur anchor pricing stratification across premium, standard, and economy tiers. Premium tiers attach equity-linked investment wrappers with private hospital network access; standard tiers offer endowment structures with guaranteed minimums; economy tiers deliver pure mortality protection with digital-only servicing. Price differentiation rests on medical underwriting depth and bancassurance partnership exclusivity. Cost compression in the economy tier intensifies as digital-native distributors automate issuance workflows. Gig-economy workers in Selangor manufacturing corridors exhibit highest price sensitivity; HNWIs seeking cross-border wealth transfer structures show lowest elasticity.
Supply Chain Analysis
Port congestion at Port Klang and container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for medical equipment supporting private hospital network partnerships. Geographic supply concentration draws from Singapore for reinsurance capacity, Labuan for captive structuring, and Hong Kong for investment-linked fund management. Raw material dependencies center on actuarial talent pools, physician network access for underwriting, and sovereign bond supply for duration-matched reserves. Single-source vulnerability in qualified actuarial professionals capable of stochastic RBC modeling creates recruitment bottlenecks. Distribution runs through bancassurance partnerships with major banking groups, agency networks in semi-urban districts, and embedded finance integrations with mobile wallets.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysian life insurance rewards carriers with scarce actuarial capabilities capable of navigating Bank Negara Malaysia's stochastic reserve requirements. The capability gap between RBC-compliant incumbents and capital-light digital entrants is widening competitive moats.
For Market Incumbents: Fortify bancassurance exclusivity through deeper deposit-base integration and captive point-of-sale placement at banking touchpoints. Expand physician network access in Penang and Johor to compress medical underwriting turnaround times. The threat of algorithmic underwriting engines from digital-native distributors demands accelerated legacy system modernization to preserve issuance speed advantages. For New Entrants and Emerging Players: Anchor in Johor's Iskandar Malaysia corridor where agency force density remains below Klang Valley saturation levels. Target gig-economy workers in Selangor manufacturing zones with subscription-based micro-policies integrated into mobile salary cycles. The go-to-market angle centers on embedded finance partnerships with e-commerce platforms at transaction moments outside traditional insurance touchpoints. For Investors and Strategic Acquirers: Bank Negara Malaysia's digital insurer licensing framework reshapes the acquisition landscape by lowering capital barriers for technology-driven distribution models. Long-term viability favors carriers with demonstrated persistency ratios in semi-urban districts and health-rider bundling capabilities tied to private hospital networks. The acquisition target archetype combines algorithmic underwriting competency with existing agency channel relationships in secondary cities. The signal to watch is persistency ratio divergence between digital-only and hybrid distribution models as a predictor of sustainable premium flow.| Strategic Initiative | Industry Significance |
|---|---|
| Health-Rider Bundling | Private hospital network partnerships in Penang and Johor capture medical inflation-linked margin expansion. |
| Algorithmic Underwriting Deployment | Digital-native distributors in Petaling Jaya compress issuance timelines from weeks to hours. |
| Bancassurance Partnership Deepening | Major banking groups in the Klang Valley corridor sustain premium flow through embedded product placement. |
| Agency Force Expansion | Johor and Penang recruitment addresses whitespace where persistency ratios depend on individual relationships. |
| Embedded Finance Integration | E-commerce platforms and fintech wallets enable policy origination at transaction moments outside traditional touchpoints. |
Research Methodology
Cross-validation between regulatory filings and distributor operational data anchors the qualitative findings in this study. Primary interviews with chief actuaries, bancassurance partnership directors, agency force managers, and private hospital network procurement officers combined with secondary validation from Bank Negara Malaysia circulars, Life Insurance Association of Malaysia industry statistics, and insurer statutory returns. Bottom-up policy issuance data triangulates against top-down premium flow estimates across the analysis window.
Sensitivity analysis on mortality assumption variations and sovereign bond yield trajectories informs the analytical framework. Segmentation dimensions modeled include product type, distribution channel, customer archetype, and policy term duration throughout the forecast period. CAGRs derive from cohort-based persistency modeling and new business strain calculations under evolving RBC requirements. Investment-linked wrapper uptake rates and health-rider attachment ratios serve as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable regulatory capital requirements and continued Klang Valley demographic concentration; material deviation would warrant model refresh. Forecasts reflect assumptions on medical underwriting capacity expansion and digital distribution penetration rates. Pandemic mortality shocks, sovereign bond supply disruptions, or abrupt bancassurance commission caps could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Sweden Life and Non-Life Insurance Market
Life and Non Life Insurance
Iran Property and Casualty Insurance Market
Life and Non Life Insurance
Ireland Life and Non-Life Insurance Market
Life and Non Life Insurance
Finland Life and Non-Life Insurance Market
Life and Non Life Insurance
Canada Life and Non-Life Insurance Market
Life and Non Life Insurance
Asia-Pacific Life and Annuity Insurance Market
Life and Non Life Insurance
Germany Life and Non-Life Insurance Market
Life and Non Life Insurance
Asia Life and Non-Life Insurance Market
Life and Non Life Insurance
Singapore Life and Non-Life Insurance Market
Life and Non Life Insurance
Indonesia Life and Non-Life Insurance Market
Life and Non Life Insurance
Japan Life and Non-Life Insurance Market
Life and Non Life Insurance
Global Life and Non-Life Insurance Market
Life and Non Life Insurance
Russia Life and Non-Life Insurance Market
Life and Non Life Insurance
US Burial Insurance Market
Life and Non Life Insurance
Czech Republic Life & Non-Life Insurance Market
Life and Non Life Insurance
Argentina Life and Non-Life Insurance Market