
 Iran Property and Casualty Insurance Market | 2026-2036
Iran Property and Casualty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Iran Property and Casualty Insurance Market Foresight
Digital underwriting platforms is broadening access to previously unserved policyholders across Iran's secondary cities. Iran Insurance leverages its state-backed branch network to sustain dominance in rural commercial coverage. Pasargad Insurance competes through specialized agricultural risk products tied to provincial crop patterns. Asia Insurance anchors its position in Tehran's manufacturing corridor with tailored fire and machinery-breakage policies.
Property and casualty insurance constitutes risk-transfer contracts indemnifying policyholders against physical asset damage, legal liability, or operational interruption, with premiums calibrated through actuarial assessment of loss frequency and severity. The primary purpose centers on stabilizing corporate and household balance sheets against unpredictable financial shocks. Auto liability maintains the largest premium pool among product types, while commercial coverage for manufacturing facilities captures the widest margins due to complex risk-engineering requirements. Construction sector demand within industry verticals is expanding fastest as infrastructure investment accelerates across Iran's provincial development zones.
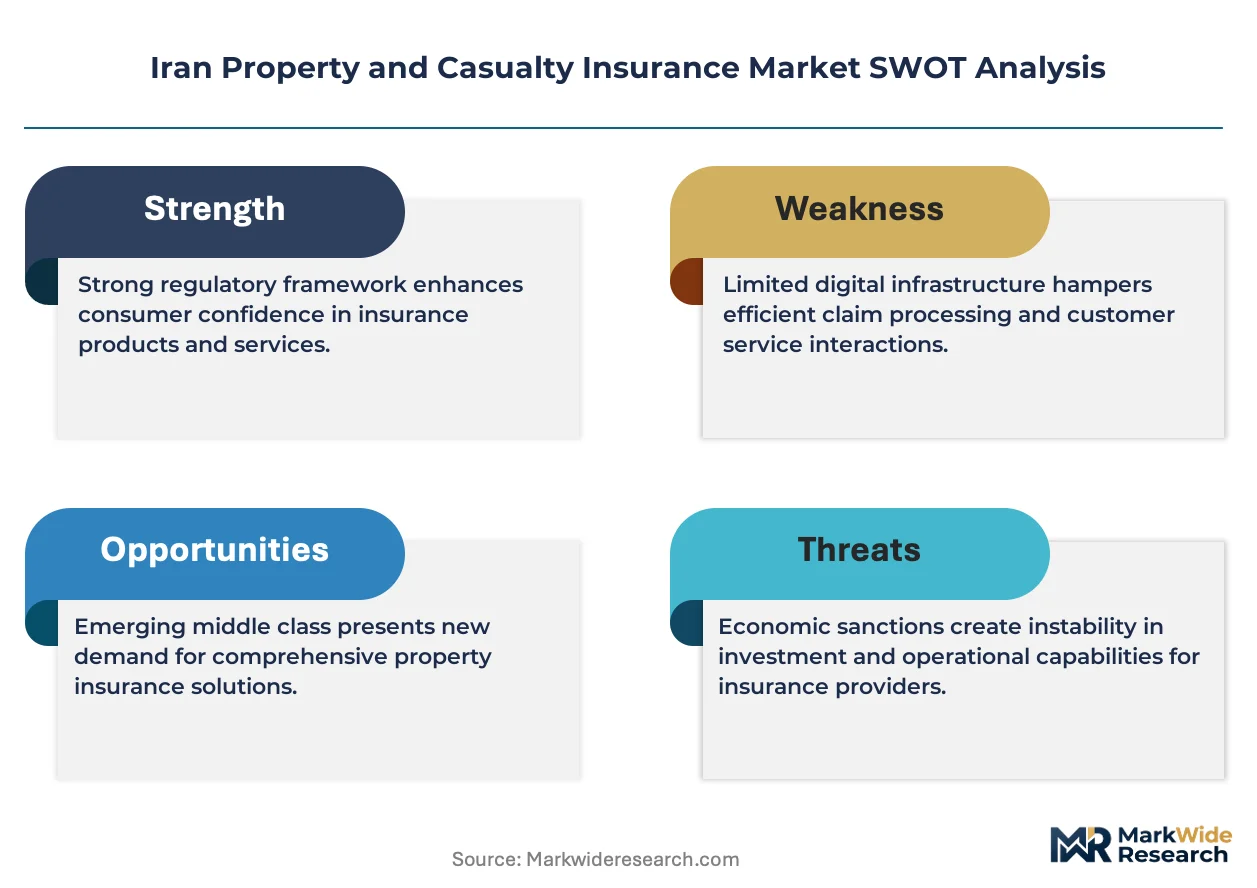
The Central Bank of Iran enforces solvency and reserve requirements that directly shape product pricing and market entry conditions for domestic carriers. BIS-aligned technical standards govern policy wording and claims settlement timelines, while the country's national insurance regulator supervises compliance with consumer protection mandates. Stakeholders must monitor regulatory capital reforms and digital distribution licensing frameworks to anticipate shifts in competitive positioning.
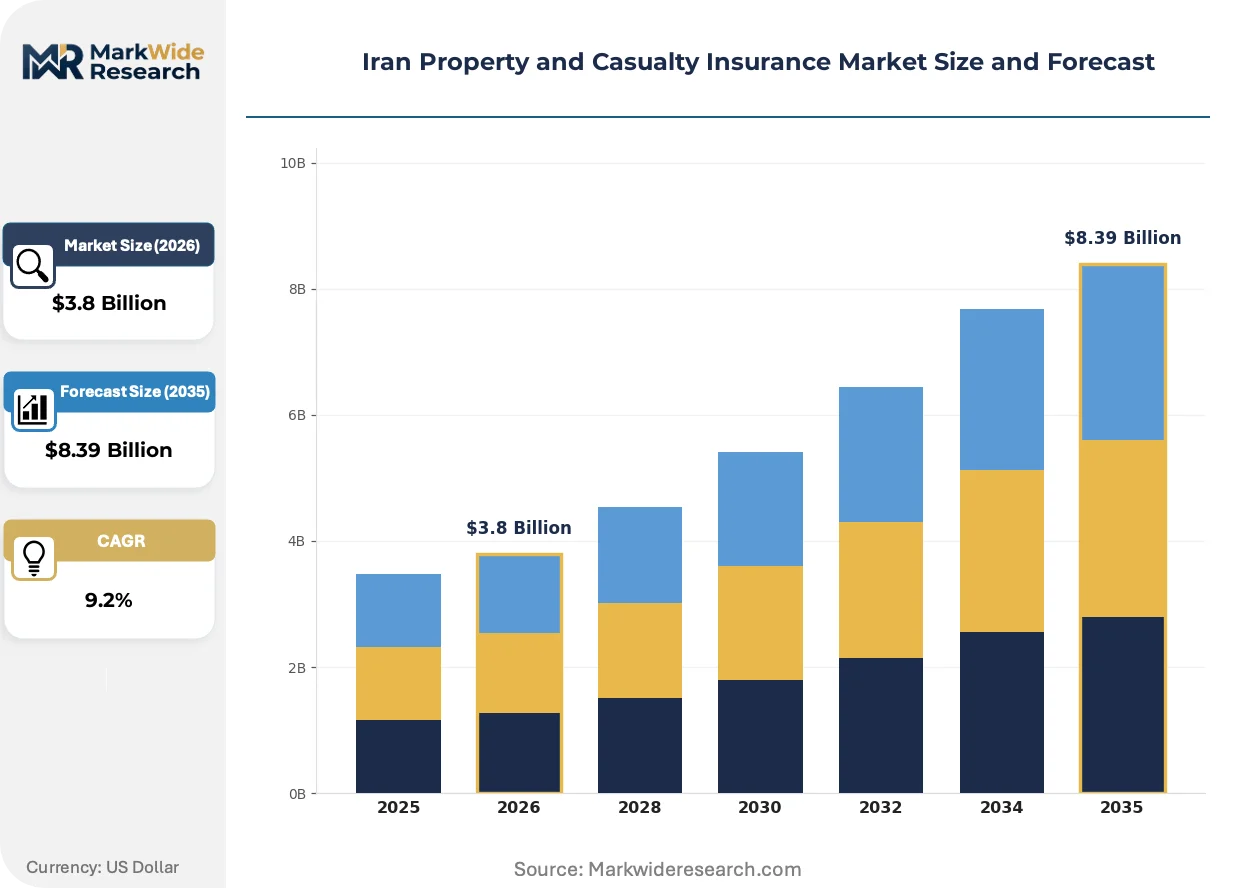
Market Dynamics
The Central Bank of Iran's capital adequacy reforms are compressing underwriting capacity among domestic carriers, forcing portfolio rebalancing toward higher-margin commercial lines and accelerating technology investment to maintain solvency compliance.
Growth Catalysts
- Tehran Manufacturing Corridor Expansion:Industrial facility construction in Alborz and Qom provinces is generating fire and machinery-breakage policy demand. Risk-engineering services attached to these contracts capture premium pricing.
- Central Bank Capital Mandates:Higher reserve requirements are pushing insurers toward commercial property lines with longer-tail liability profiles. This reweights portfolios away from saturated auto liability pools.
- Digital Distribution Licensing:New regulatory frameworks for mobile underwriting platforms are opening secondary city markets previously served only by state-backed branch networks.
Market Restraints
- Reinsurance Access Constraints:International sanctions limit Iranian carriers' ability to cede catastrophe risk to global reinsurers. Domestic retention ratios remain elevated, concentrating earthquake and flood exposure on local balance sheets.
- Agricultural Loss Volatility:Drought frequency in Khuzestan and Kerman provinces creates unpredictable claims severity in crop coverage lines. Actuarial pricing struggles to reflect climate tail risks.
- Foreign Currency Illiquidity:Import-dependent auto parts and construction materials expose property insurers to settlement delays when hard currency for claims is rationed.
Strategic Opportunities
- Mashhad and Tabriz Underpenetration:Secondary urban centers lack specialized commercial coverage for logistics and warehousing facilities. Digital platforms can bypass physical branch buildout costs.
- Agricultural Index Insurance:Satellite-based rainfall and temperature triggers offer alternatives to traditional loss-adjustment models for provincial crop protection.
- Parametric Coverage Convergence:Combining IoT sensors with automated claims settlement creates subscription products for manufacturing interruption risks in Isfahan's industrial zones.
Industry Challenges
- Actuarial Talent Scarcity:Advanced catastrophe modeling and predictive analytics skills are concentrated in Tehran, limiting risk-engineering depth at provincial underwriters.
- Legacy Core System Integration:State-backed carriers operate on decades-old policy administration platforms that resist API connectivity with digital distribution channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iran Property and Casualty Insurance Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home, Auto, Liability, Commercial Industry Vertical: Manufacturing, Construction, Retail, Agriculture End User: Individuals, Small Businesses, Corporations, Government Coverage Type: Fire, Theft, Flood, Earthquake |
| Companies Covered | Iran Insurance, Asia Insurance, Persian Insurance, Alborz Insurance, Pasargad Insurance, Razi Insurance, Karafarin Insurance, Day Insurance, Moallem Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iran Property and Casualty Insurance Market Shifts & Advancements
Telematics and sensor-based risk assessment are displacing traditional inspection-dependent underwriting across Iran's commercial property segment, compressing quote-to-bind timelines while enabling dynamic premium adjustment.
Telematics-enabled fleet monitoring is rewriting commercial auto liability pricing in Tehran's logistics sector. Large transport operators now transmit real-time driver behavior data to underwriters, enabling usage-based premium structures that reward risk reduction. This data stream is compressing traditional actuarial reliance on historical loss triangles.
The Central Bank of Iran's digital distribution licensing framework is mandating API standards for policy comparison platforms. This regulatory push is fragmenting customer acquisition away from captive agency channels toward aggregator sites. Tehran-based manufacturing buyers are migrating fastest to these transparent quote environments.
Construction firms in Isfahan and Fars provinces are unbundling project insurance from general contractor procurement, selecting specialized coverage through direct underwriter relationships rather than bundled EPC contracts. This disintermediation favors carriers with dedicated engineering risk units over generalist providers.
Iran Property and Casualty Insurance Market Segmentation
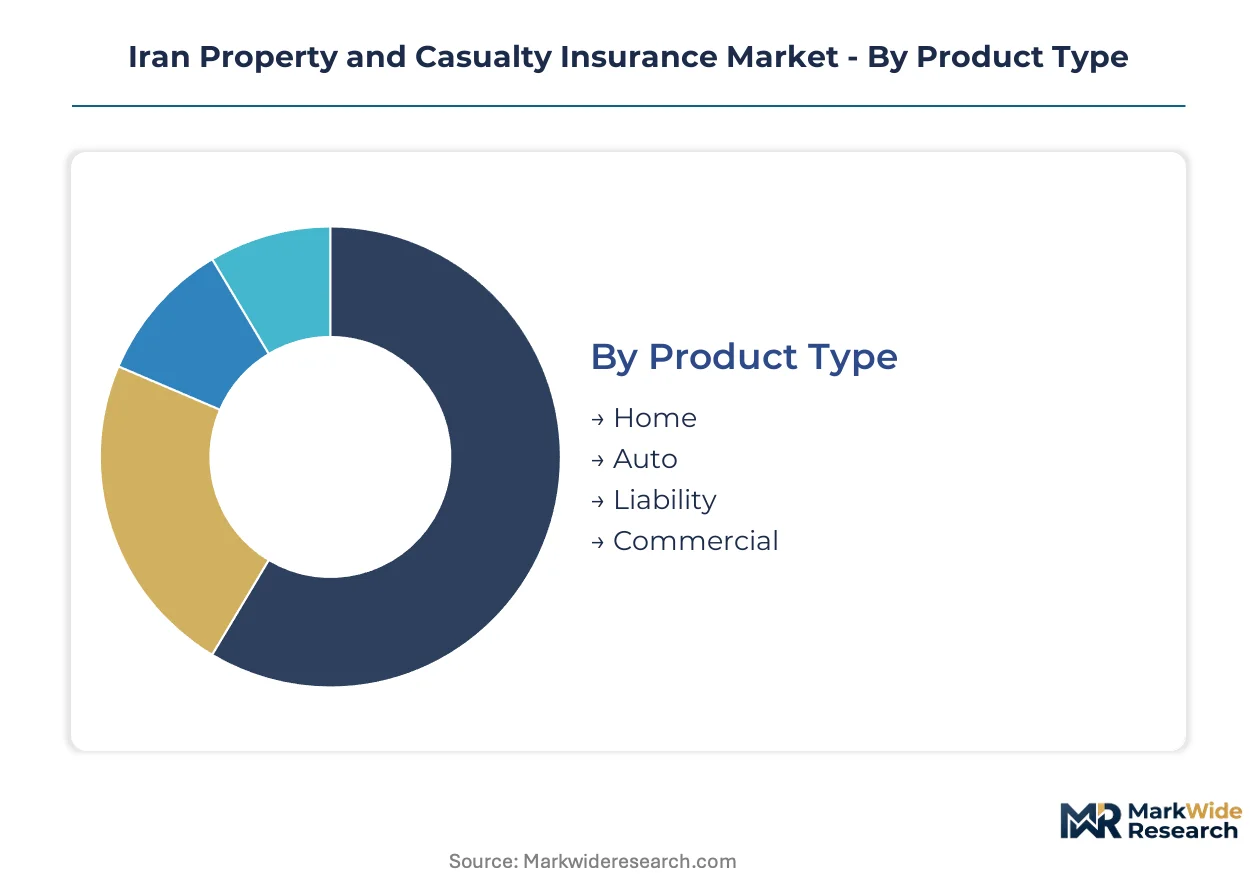
Segmentation in Iran's property and casualty insurance market reveals how carriers allocate capital across risk profiles with varying loss predictability. Product mix decisions by underwriters directly reflect regulatory capital constraints and geographic exposure concentrations.
Product Type:
Standardized personal lines dominate premium volume while customized commercial contracts command wider spreads.
- Home:Residential coverage bundles fire, theft, and liability protection for urban dwellings. Tehran apartment complexes drive policy issuance as mortgage lenders mandate coverage. Deductible structures vary by building age and construction material.
- Auto:Third-party liability constitutes the mandatory coverage pool, with comprehensive optional for newer vehicles. Tehran's dense traffic corridors generate disproportionate claims frequency. Telematics adoption is rewriting pricing models for fleet operators.
- Liability:Professional and product liability coverage protects against legal exposure from operational errors. Manufacturing exporters in Isfahan purchase these policies to satisfy international contract requirements.
- Commercial:Multi-peril packages combine property damage with business interruption protection. Industrial facilities in Alborz province negotiate tailored terms with dedicated risk-engineering support.
Most installed capacity flows through Auto. Expansion is steepest in Commercial.
Industry Vertical:
Margin profiles diverge sharply between capital-intensive heavy industry and dispersed agricultural portfolios.
- Manufacturing:Machinery-breakage and fire policies protect production assets across Tehran's industrial corridor. Risk-engineering services attached to these contracts justify premium pricing above personal lines.
- Construction:Project-specific coverage and contractor liability dominate this vertical. Infrastructure investment in Fars and Isfahan provinces is accelerating policy issuance for earthworks and structural phases.
- Retail:Shopkeeper packages bundle inventory protection with public liability. Secondary city bazaars represent underpenetrated distribution opportunities.
- Agriculture:Crop and livestock coverage faces pricing challenges from drought volatility in Khuzestan. Satellite-based index products are emerging alternatives to traditional loss adjustment.
Manufacturing captures the widest underwriting margins. Construction is gaining share fastest as provincial development zones expand.
End User:
Scale determines service model complexity from standardized retail to negotiated corporate treaties.
- Individuals:Personal auto and home coverage purchased through agency networks or emerging digital platforms. Price sensitivity drives high comparison shopping in Tehran.
- Small Businesses:Shop and office packages with simplified underwriting and rapid issuance. Claims handling efficiency determines carrier retention in this segment.
- Corporations:Customized multi-location programs with dedicated account management. Manufacturing conglomerates negotiate engineering services and loss control consulting.
- Government:State-owned enterprise and public infrastructure coverage often routed through mandated domestic carriers. Procurement processes emphasize solvency ratings over price competition.
Individual policies generate the highest transaction volumes. Corporate accounts deliver the steepest premium expansion.
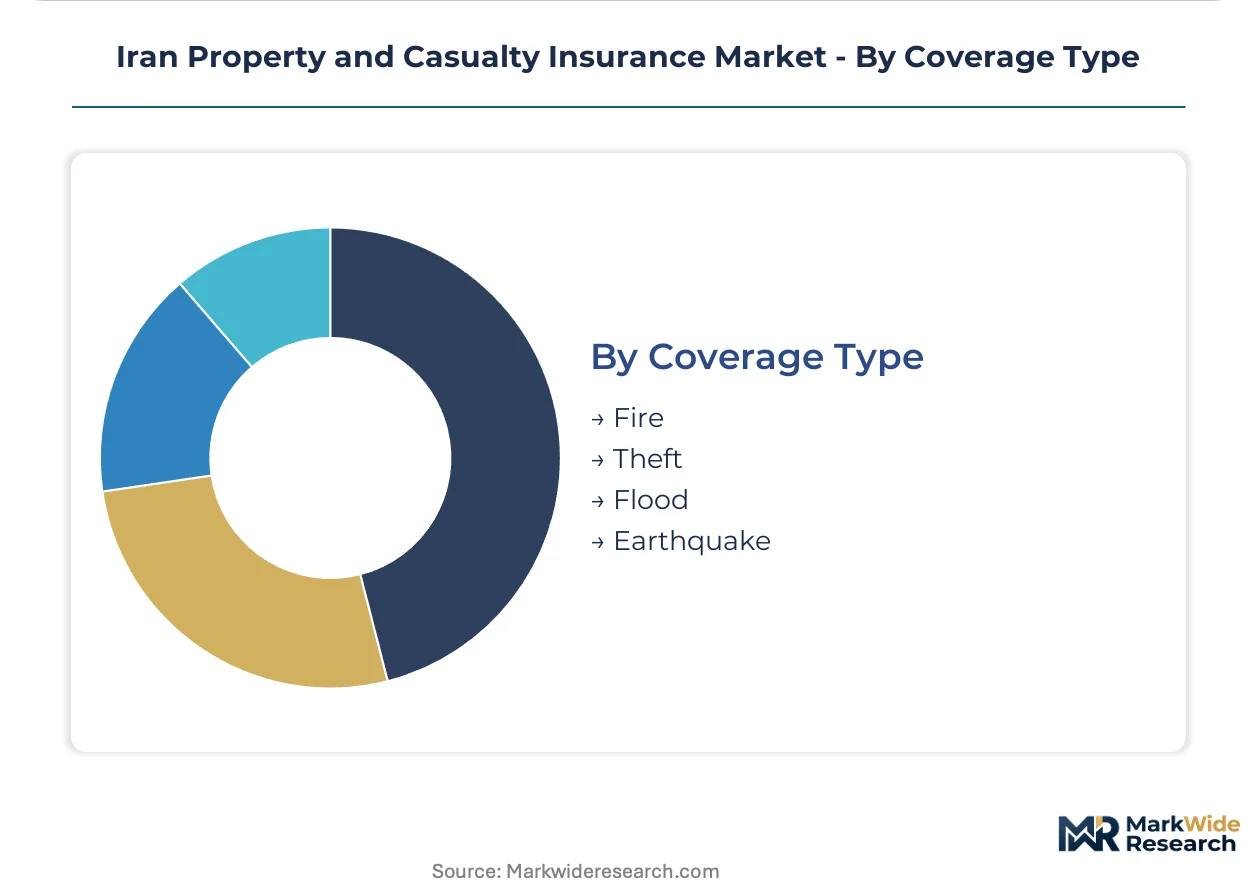
Coverage Type:
Peril-specific pricing reflects Iran's geographic exposure to seismic and hydrological events.
- Fire:Core property damage coverage for buildings and contents. Industrial facilities in Tehran's manufacturing corridor purchase enhanced limits with business interruption extensions.
- Theft:Crime coverage for inventory and equipment, particularly relevant for retail and logistics operations. Claims settlement requires police documentation creating procedural friction.
- Flood:Riverine and flash flood protection concentrated in northern provinces. Reinsurance access constraints limit capacity for catastrophic flood scenarios.
- Earthquake:Structural damage coverage essential across Iran's seismic zones. The Central Bank of Iran mandates minimum penetration rates in high-risk provinces.
Fire coverage dominates policy attachments. Earthquake is climbing fastest as regulatory minimums expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tehran's manufacturing corridor anchors national premium generation as industrial facility construction spreads across provincial development zones. Central Bank capital mandates and digital distribution licensing are compressing underwriting capacity while opening secondary city markets.
Tehran Province
Auto liability and commercial property lines dominate premium flows from the capital's dense industrial zones. The Central Bank of Iran enforces solvency requirements that favor carriers with dedicated risk-engineering units. Manufacturing conglomerates in Tehran's western corridor negotiate tailored fire and machinery-breakage policies with engineering services attached.
Alborz Province
Industrial facility construction in Karaj and surrounding districts generates demand for contractor liability and project-specific coverage. Higher capital adequacy ratios push insurers toward commercial lines with longer-tail profiles. Risk-engineering teams from Tehran-based carriers serve this corridor through satellite offices.
Isfahan Province
Steel and automotive manufacturing clusters drive commercial multi-peril policy issuance across the province. The national insurance regulator supervises compliance with BIS-aligned technical standards for policy wording. Construction firms in Isfahan's industrial zones are unbundling project insurance from general contractor procurement.
Fars Province
Infrastructure investment in Shiraz and regional development zones accelerates earthworks and structural phase coverage demand. Drought volatility creates pricing challenges for agricultural lines in peripheral districts. Satellite-based index products are emerging as alternatives to traditional loss adjustment for crop protection.
East Azerbaijan Province
Tabriz represents an underpenetrated secondary center for logistics and warehousing facility coverage. Digital distribution licensing frameworks enable mobile underwriting platforms to bypass physical branch buildout costs. Manufacturing and trade operations in this northwestern hub seek specialized commercial coverage previously available only through Tehran-based brokers.
Iran Property and Casualty Insurance Market Competitive Landscape
Global majors compete with regional champions across capital adequacy and risk-engineering capabilities, though international reinsurance access constraints limit foreign carrier participation. The market structures around state-backed incumbents with branch network dominance, mid-tier specialists in agricultural and commercial lines, and emerging digital-native platforms. Portfolio rebalancing toward higher-margin commercial segments and technology investment for solvency compliance represent the dominant competitive moves.
Among Tehran-based state-backed carriers, Iran Insurance anchors rural commercial coverage through its branch network infrastructure. Asia Insurance occupies a position in the manufacturing corridor specialist tier with tailored fire and machinery-breakage policies. Pasargad Insurance exemplifies the agricultural risk specialist archetype through provincial crop-pattern products.
| Leading Market Players |
|---|
| Iran Insurance |
| Asia Insurance |
| Persian Insurance |
| Alborz Insurance |
| Pasargad Insurance |
| Razi Insurance |
| Karafarin Insurance |
| Day Insurance |
| Moallem Insurance |
| Others |
Supply & Pricing Matrix
Performance-tier bifurcation between risk-engineered commercial policies and standardized personal lines manifests in both premium calibration and distribution infrastructure. Tehran-based manufacturing conglomerates negotiate engineering-attached fire and machinery-breakage coverage through dedicated account teams, while auto liability pools compete on price through saturated agency networks.
Pricing Analysis
Input-cost pass-through from reinsurance scarcity and foreign currency illiquidity compresses margins on catastrophe-exposed lines. Three-tier pricing structure across premium-engineered, standard-commercial, and economy-personal levels reflects risk-assessment depth. Pricing pressure stems from Central Bank capital mandates pushing carriers toward longer-tail commercial portfolios. Corporate buyers in Isfahan's steel corridor demonstrate lowest price sensitivity due to contract-embedded risk services, while Tehran individual auto policyholders drive comparison shopping.
Supply Chain Analysis
Central Bank solvency certification gates access to commercial line underwriting capacity, concentrating risk-engineering talent in Tehran-based carriers. Domestic retention of catastrophe exposure feeds from limited reinsurance cession to international markets. Supply chain risk centers on single-source vulnerability to foreign currency rationing for import-dependent auto parts and construction materials claims. Distribution runs through state-backed branch networks in rural zones and emerging digital platforms in secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Manufacturing exporters in Isfahan are shifting procurement toward policies with international contract-compliant liability specifications.
For Market Incumbents: To counter digital-native platform encroachment in secondary cities, deepen risk-engineering service bundling for manufacturing corridor accounts and accelerate API-enabled policy administration to reduce legacy system integration friction with mobile distribution channels.
For New Entrants and Emerging Players: Digital broker partnerships in Mashhad and Tabriz offer white-space access to logistics and warehousing coverage underserved by Tehran-centric branch networks. Agricultural index insurance in drought-exposed provinces represents the most penetrable segment through satellite-data partnerships with provincial crop authorities.
For Investors and Strategic Acquirers: Consolidation pressure builds where actuarial talent scarcity constrains provincial underwriter expansion. Long-term viability favors carriers with captive risk-engineering capabilities and Central Bank solvency buffer compliance. Watch for regulatory digital licensing acceleration as inflection signal for platform acquisition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Risk-Engineering Service Expansion | Differentiates commercial property offerings in Tehran's manufacturing corridor through dedicated loss control consulting. |
| Digital Distribution Licensing Compliance | Unlocks secondary city penetration via API-integrated mobile underwriting platforms outside state branch networks. |
| Agricultural Index Product Development | Replaces traditional loss adjustment with satellite-triggered crop protection in drought-volatile Khuzestan and Kerman. |
| Parametric Coverage Convergence | Combines IoT sensors with automated settlement for manufacturing interruption risks in Isfahan industrial zones. |
| Capital Adequacy Buffer Management | Positions carriers for Central Bank reserve requirement compliance while maintaining commercial line underwriting capacity. |
Research Methodology
Direct dialogue with chief underwriting officers, risk-engineering directors, regulatory compliance leads, and digital platform developers grounded qualitative findings. Secondary validation drew from Central Bank of Iran solvency disclosures, national insurance regulator filings, BIS technical standard documents, and provincial development zone infrastructure announcements. Bottom-up policy volume estimates triangulated against top-down premium pool assessments.
Segmented outputs across product type, industry vertical, end user scale, and coverage peril category structured the analytical framework. CAGRs derived from trend-line extrapolation of capital adequacy impacts and digital adoption curves. Forecast inputs incorporated construction sector procurement patterns and satellite-based agricultural insurance penetration assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to international sanctions relief and reinsurance market access restoration. Forecasts reflect documented assumptions around regulatory capital reform implementation pace and digital licensing framework adoption rates. A model refresh is warranted upon material change in Central Bank reserve requirement calibration or secondary city digital platform penetration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Asia-Pacific Life and Annuity Insurance Market
Life and Non Life Insurance
Sri Lanka Life and Non-Life Insurance Market
Life and Non Life Insurance
Canada Life and Non-Life Insurance Market
Life and Non Life Insurance
Teenager Life Insurance Market
Life and Non Life Insurance
Brazil Life and Non-Life Insurance Market
Life and Non Life Insurance
Colombia Life and Non-Life Insurance Market
Life and Non Life Insurance
Global Life and Non-Life Insurance Market
Life and Non Life Insurance
Life Insurance Policy Administration System Market
Life and Non Life Insurance
Austria Life and Non-Life Insurance Market
Life and Non Life Insurance
Germany Life and Non-Life Insurance Market
Life and Non Life Insurance
China Life and Non-Life Insurance Market
Life and Non Life Insurance
Life Reinsurance Market
Life and Non Life Insurance
Japan Life and Non-Life Insurance Market
Life and Non Life Insurance
France Life and Non-Life Insurance Market
Life and Non Life Insurance
US Burial Insurance Market
Life and Non Life Insurance
Ireland Life and Non-Life Insurance Market