
 North America Business Income Insurance Market | 2026-2036
North America Business Income Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
North America Business Income Insurance Market Analytics
California's SB 261 climate disclosure mandate is expanding the addressable market for business income coverage tied to climate-related operational disruptions. Marsh leverages its brokerage scale to structure complex multi-line policies for Fortune 500 clients. AIG anchors its position through proprietary catastrophe modeling that differentiates risk pricing across coastal and inland exposures. Brown & Brown competes by controlling independent agency networks in the Southeast and Midwest.
Business income insurance indemnifies policyholders for net income loss and continuing operating expenses during periods when physical damage or named perils interrupt normal commercial operations, with indemnity periods typically spanning 12 to 24 months and coinsurance clauses requiring 50% to 100% of projected earnings as a coverage floor. Gross Earnings coverage dominates premium volume among established manufacturers with stable revenue baselines, while Extra Expense policies capture faster growth among technology firms requiring immediate access to alternate facilities and redundant cloud infrastructure. Distribution through Insurance Agents and Brokers sustains the largest premium flow, though Online Platforms are gaining traction among startups seeking rapid quote-to-bind cycles without intermediary commissions.
The National Association of Insurance Commissioners coordinates state-level reserving standards that directly affect carrier capacity to underwrite business income lines, while state regulators in New York and Texas enforce separate rate filing requirements that fragment product approval timelines across the region. The SEC's climate risk disclosure rules, though partially stayed, have already prompted publicly traded policyholders to demand more granular coverage documentation for supply chain interruption scenarios. Stakeholders must monitor how federal preemption debates and patchwork state mandates reshape compliance costs and coverage design across the North American footprint.
Market Dynamics
State-level climate disclosure mandates and cyber risk frameworks are forcing carriers to redesign policy language and pricing models across the North American footprint. The collision of physical peril intensification with digital operational dependency is compressing traditional underwriting cycles.
Growth Catalysts
- California SB 261 Climate Mandate:Publicly traded companies must disclose climate-related financial risks, expanding demand for business income coverage tied to weather-driven operational interruptions.
- Manufacturing Sector Expansion:Small and mid-sized manufacturers in the US Northeast are accelerating coverage purchases as supply chain vulnerability awareness rises.
- Cyber-Physical Convergence:Operational technology systems in critical infrastructure now trigger simultaneous property and income loss scenarios, broadening policy attachment points.
Market Restraints
- Catastrophe Model Uncertainty:Secondary peril volatility in inland flood and convective storm zones erodes pricing confidence and capital deployment appetite.
- Reinsurance Capacity Squeeze:Bermuda and London market carriers have tightened retrocession terms, compressing primary carrier underwriting leverage for multi-year policies.
- Regulatory Fragmentation:Separate rate filing requirements in New York and Texas extend product approval timelines and increase compliance overhead.
Strategic Opportunities
- Parametric Policy Structures:Index-triggered coverage for business income loss bypasses traditional loss adjustment friction and accelerates claim settlement.
- Mid-Market Digital Distribution:Online platforms and embedded insurance APIs capture underserved technology startups seeking rapid quote-to-bind cycles.
- SEC Climate Disclosure Rules:Though partially stayed, these rules have conditioned publicly traded policyholders to demand granular supply chain interruption documentation.
Industry Challenges
- Actuarial Talent Scarcity:Shortage of professionals skilled in climate risk modeling and cyber-physical peril quantification constrains product development velocity.
- Legacy System Integration:Carrier core policy administration platforms require costly retrofitting to accommodate parametric triggers and real-time exposure monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Business Income Insurance Market |
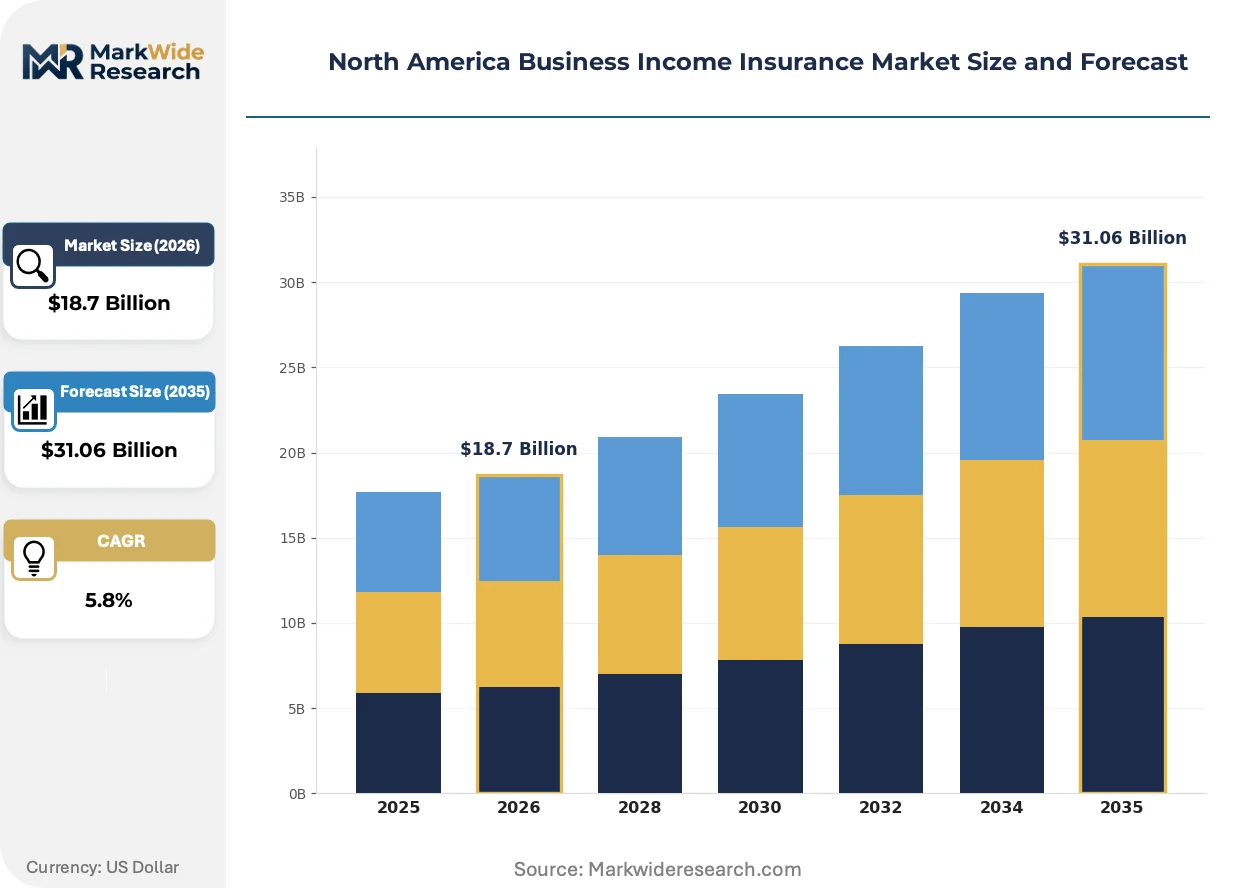
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Gross Earnings, Extra Expense, Rental Income, Business Interruption Business Size: Small Enterprises, Medium Enterprises, Large Corporations, Startups Distribution Channel: Online Platforms, Insurance Agents, Brokers, Direct Sales Industry Vertical: Manufacturing, Retail, Hospitality, Technology |
| Companies Covered | Marsh, Endurance Specialty Insurance, AIG, White Mountains Insurance Group, Radian, Brown & Brown, AJG (Arthur J. Gallagher & Co.), Convex Group, Aon, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Business Income Insurance Market Evolving Landscape
Real-time exposure monitoring and automated underwriting engines are compressing policy issuance from weeks to hours. Carriers that embed these capabilities into distribution partnerships capture premium flow before traditional broker channels respond.
Telematics-enabled risk scoring is electrifying underwriting precision for commercial property portfolios. Mid-market manufacturing clients in tornado-prone corridors adopt sensor networks that feed live building integrity data to carrier pricing engines. This transparency is compressing rate negotiation cycles and enabling dynamic premium adjustments tied to verified risk control investments.
The National Association of Insurance Commissioners coordinates reserving standards that directly affect carrier capacity to underwrite business income lines. State regulators enforce capital adequacy requirements that diverge across the region, fragmenting product rollout timelines. Carriers with multi-state licensing infrastructure respond faster to regulatory arbitrage opportunities than single-state specialists.
Buyer concentration among Fortune 500 risk managers is reshaping distribution economics. Large commercial purchasers now unbundle business income coverage from packaged property policies and negotiate standalone terms through direct carrier relationships. This disintermediation pressure is most visible in the US Northeast corridor, where dense commercial infrastructure supports dedicated captive insurance consultants.
North America Business Income Insurance Market Segmentation
Business income insurance purchasers cycle through coverage upgrades as operational complexity evolves. Renewal decisions hinge on whether existing indemnity structures match current revenue volatility and supply chain exposure.
Coverage Type:
Replacement cycles accelerate when policyholders recognize gaps between legacy indemnity periods and actual business recovery timelines.
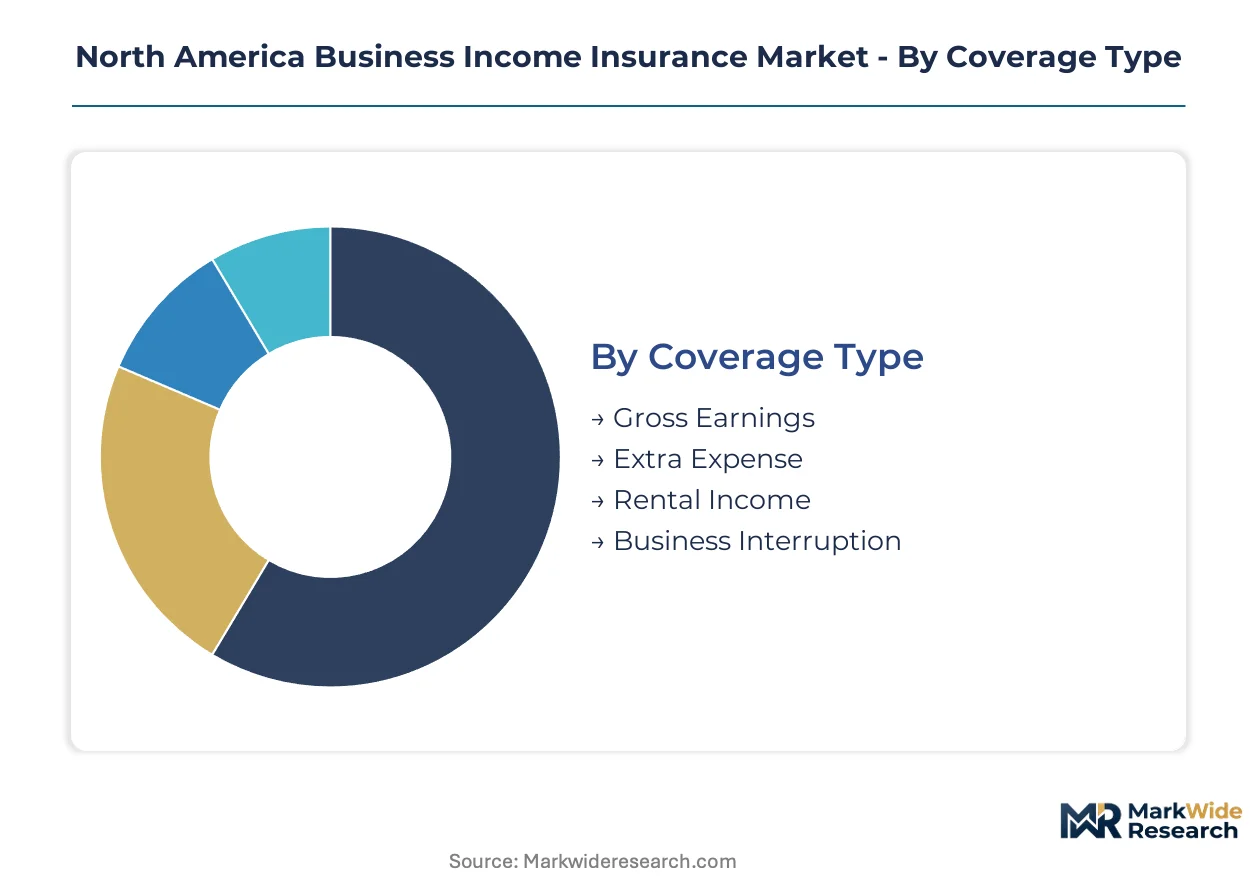
- Gross Earnings:Indemnifies net income loss plus continuing operating expenses using historical revenue baselines as the coverage trigger. Established manufacturers in the US Northeast corridor favor this structure for its predictable claims settlement mechanics amid heightened natural catastrophe exposure.
- Extra Expense:Covers costs to minimize income loss through immediate relocation to alternate facilities or redundant cloud infrastructure. Technology firms across California's innovation clusters drive placements here as cyber-physical convergence demands faster operational restoration.
- Rental Income:Protects commercial property owners against lost lease payments during repair periods. Landlords in Texas metropolitan areas favor this coverage given convective storm volatility affecting tenant retention.
- Business Interruption:Traditional form covering profit loss plus fixed expenses during named peril suspensions. Mid-market retailers in the Midwest maintain this coverage as foundational protection against supply chain disruption.
Volume placements concentrate in Gross Earnings; the faster expansion belongs to Extra Expense.
Business Size:
Cost tier differentiation separates basic indemnity structures from sophisticated multi-line programs with customized waiting periods.
- Small Enterprises:Standardized policies with 50% coinsurance floors and 12-month indemnity windows predominate. Manufacturing sub-sectors across Michigan and Ohio accelerate purchases as supply chain vulnerability awareness rises.
- Medium Enterprises:Hybrid structures blending gross earnings with contingent business interruption riders. These buyers in the Southeast negotiate through independent agency networks seeking competitive rate comparisons.
- Large Corporations:Complex multi-line policies with 24-month indemnity periods and dedicated captive insurance consultants. Fortune 500 risk managers in the US Northeast corridor increasingly unbundle business income from packaged property policies.
- Startups:Rapid quote-to-bind coverage via embedded insurance APIs and online platforms. California technology ventures favor parametric triggers that bypass traditional loss adjustment friction.
Medium Enterprises generate the densest placement flow; Startups are climbing the fastest.
Distribution Channel:
Customer type determines whether buyers tolerate intermediary friction or demand immediate digital execution.
- Online Platforms:Automated underwriting engines compress policy issuance from weeks to hours. Startup technology firms seeking zero-commission transactions dominate this channel's premium flow.
- Insurance Agents:Local market knowledge and relationship-based servicing sustain dominance among small manufacturing clients in the Midwest and Southeast.
- Brokers:Scale advantages enable complex multi-line structuring for large corporate accounts. Marsh leverages brokerage scale to coordinate Fortune 500 placements across state regulatory boundaries.
- Direct Sales:Carrier-employed producers target large accounts with proprietary catastrophe modeling demonstrations. AIG anchors this channel through differentiated risk pricing presentations.
Insurance Agents sustain the largest premium flow; Online Platforms are gaining share fastest.
Industry Vertical:
Geography within the North American footprint aligns vertical exposure concentration with regional peril profiles.
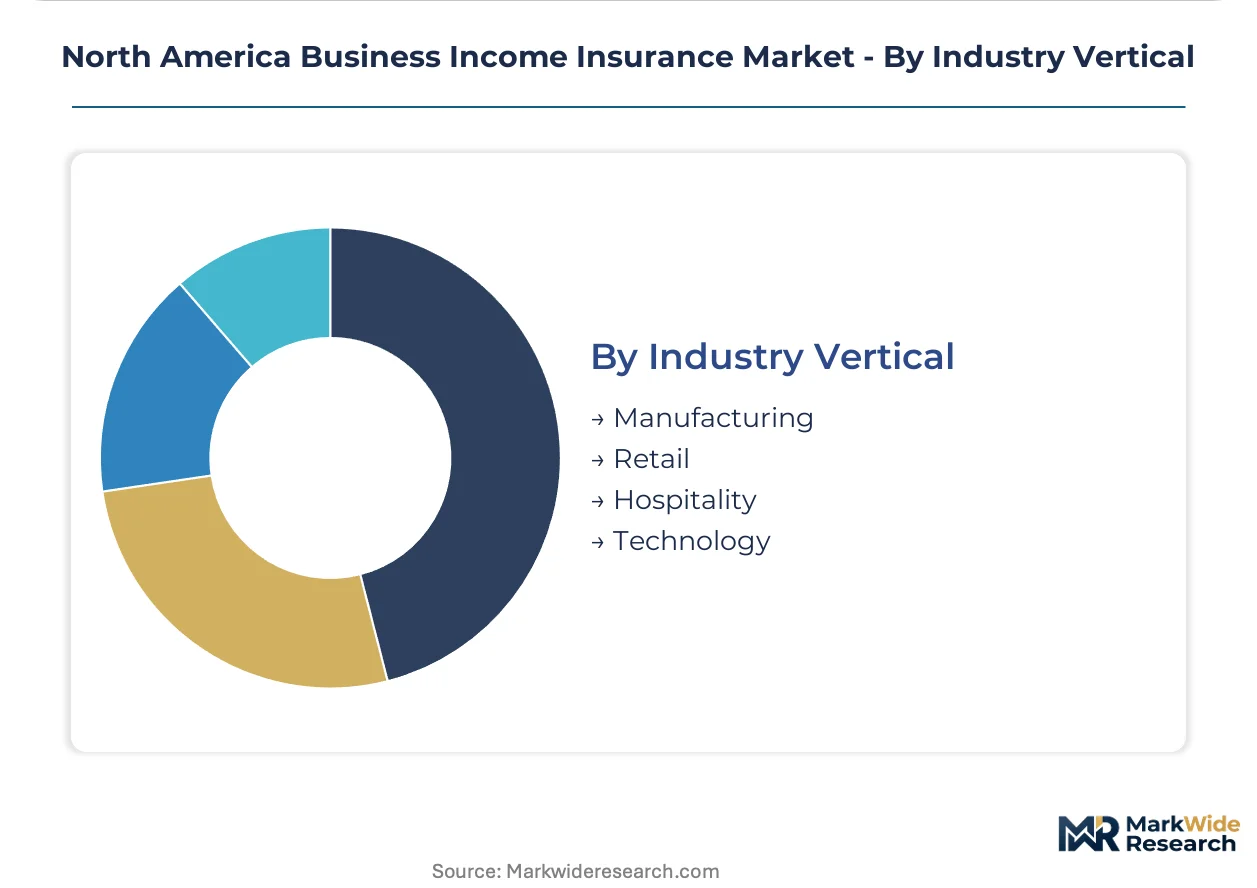
- Manufacturing:Physical asset intensity drives demand for extended indemnity periods covering equipment replacement timelines. Small and mid-sized manufacturers in the US Northeast corridor lead coverage acceleration.
- Retail:Inventory-dependent revenue models require seasonal adjustment clauses within gross earnings calculations. Big-box operators across Texas and Florida prioritize contingent business interruption for supplier failure scenarios.
- Hospitality:Perishable revenue characteristics demand immediate extra expense access to alternate facilities. California resort operators integrate climate disclosure documentation into coverage negotiations.
- Technology:Cloud infrastructure dependency creates simultaneous property and cyber income loss triggers. Firms in California and New York State favor parametric structures with index-based settlement.
Manufacturing anchors the premium base; Technology is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Northeast corridor from Boston through New York to Philadelphia anchors North American business income insurance premium generation. Dense commercial infrastructure and heightened natural catastrophe exposure concentrate risk manager activity in this corridor.
United States
Small and mid-sized manufacturers across Michigan and Ohio accelerate coverage purchases as supply chain vulnerability awareness rises. The SEC's climate risk disclosure rules, though partially stayed, have prompted publicly traded policyholders to demand granular coverage documentation. Fortune 500 risk managers in the US Northeast corridor increasingly unbundle business income from packaged property policies and negotiate standalone terms through direct carrier relationships.
California
Technology firms across California's innovation clusters drive placements in Extra Expense coverage as cyber-physical convergence demands faster operational restoration. SB 261 mandates publicly traded companies to disclose climate-related financial risks, expanding demand for business income coverage tied to weather-driven operational interruptions. Resort operators in Southern California integrate climate disclosure documentation into coverage negotiations with carriers.
Texas
Landlords in Texas metropolitan areas favor Rental Income coverage given convective storm volatility affecting tenant retention. State regulators enforce separate rate filing requirements that extend product approval timelines and increase compliance overhead. Big-box retail operators across Dallas-Fort Worth and Houston prioritize contingent business interruption for supplier failure scenarios.
Canada
Mid-market manufacturing clients in Ontario adopt sensor networks that feed live building integrity data to carrier pricing engines. Health Canada coordinates with provincial regulators on capital adequacy requirements that diverge across the region. Toronto's financial district concentrates brokerage activity for complex multi-line policies serving cross-border commercial operations.
Mexico
Manufacturing sub-sectors in Nuevo León and the Bajío Region accelerate coverage purchases as nearshoring expands operational footprints. The country's national insurance regulator enforces reserving standards that affect carrier capacity to underwrite business income lines. Mexico City's commercial district concentrates demand for standardized policies with 12-month indemnity windows among small enterprises.
North America Business Income Insurance Market Competitive Landscape
The competitive structure tilts toward brokerage-scale intermediaries with multi-state licensing infrastructure. Consolidation pressure concentrates premium flow among large intermediaries capable of structuring complex multi-line policies across regulatory boundaries. Two strategic archetypes dominate: scale-driven brokers leveraging proprietary catastrophe modeling for risk differentiation, and independent agency networks capturing mid-market manufacturing clients through localized relationship servicing. Competitive moves center on geographic expansion through agency network acquisition and technology licensing for automated underwriting engines.
Within the brokerage tier, Marsh and Aon represent scale-driven intermediaries coordinating Fortune 500 placements across state regulatory boundaries. AIG anchors the carrier-direct vector through differentiated risk pricing presentations. Brown & Brown exemplifies the independent agency network model, capturing mid-market flow through controlled distribution in the Southeast and Midwest.
| Leading Market Players |
|---|
| Marsh |
| Endurance Specialty Insurance |
| AIG |
| White Mountains Insurance Group |
| Radian |
| Brown & Brown |
| AJG (Arthur J. Gallagher & Co.) |
| Convex Group |
| Aon |
| Others |
Value Network & Pricing Analysis
Actuarial talent concentration in Bermuda and London drives labor-cost differentials that widen pricing-tier spreads between parametric policies and traditional indemnity structures. Carriers with captive modeling capabilities in these jurisdictions command premium positioning while regional specialists compete on rate.
Pricing Analysis
Value-based pricing anchored to business interruption duration and net income exposure governs premium construction across the North American footprint. Pricing stratifies across Fortune 500 risk managers, mid-market manufacturers, and small enterprises based on indemnity period length and coinsurance floor requirements. Cost compression in the small enterprise tier intensifies as direct-to-consumer platforms eliminate broker commissions. Mid-market buyers exhibit highest price sensitivity due to competing capital allocation priorities.
Supply Chain Analysis
Single-source vulnerability sits with Bermuda and London market carriers providing retrocession capacity to primary underwriters. Catastrophe modeling software draws from California, Texas, and Massachusetts technology clusters. Reinsurance capacity rests on collateralized structures and sidecar vehicles. Tariff exposure through state-by-state rate filing fragmentation elevates compliance overhead. Distribution runs through brokerage networks, independent agencies, and emerging embedded insurance APIs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where proprietary catastrophe modeling capabilities represent the decisive upstream lever separating scale players from commodity competitors.
For Market Incumbents: Lock in exclusive data partnerships with sensor network providers and telematics vendors to harden pricing moats against insurtech challengers. Deepen backward integration into climate risk modeling by acquiring specialist analytics firms. Defend against disintermediation pressure from Fortune 500 direct-carrier relationships through dedicated captive insurance consulting units. For New Entrants and Emerging Players: Enter via parametric policy structures targeting California technology startups seeking index-triggered settlement mechanics. White-space opportunity concentrates in the Southeast independent agency networks where relationship-based servicing lags digital capabilities. Pursue embedded insurance API distribution through commercial property management platforms. For Investors and Strategic Acquirers: Re-rating potential sits with mid-market carriers possessing multi-state licensing infrastructure given regulatory fragmentation across New York and Texas. Long-term viability favors underwriters with demonstrated catastrophe model accuracy across coastal and inland exposures. Monitor SEC climate disclosure rule reinstatement as the critical inflection signal for supply chain interruption coverage demand.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Launch | Index-triggered coverage accelerates claim settlement for California technology firms facing cyber-physical convergence risks. |
| Multi-State Licensing Expansion | Regulatory arbitrage capture across New York and Texas rate filing requirements compresses product rollout timelines. |
| Sensor Network Partnership | Telematics-enabled risk scoring from Midwest manufacturing clients feeds live building integrity data to pricing engines. |
| Captive Insurance Consulting Unit | Dedicated advisory capabilities retain Fortune 500 risk managers unbundling coverage from packaged property policies. |
| Climate Model Acquisition | Proprietary catastrophe differentiation strengthens pricing precision across convective storm and inland flood zones. |
Research Methodology
Multi-period observation of premium volume shifts, indemnity period extensions, and distribution channel migration anchored the trend analysis, supplemented by interviews with underwriting executives, actuarial directors, independent agency principals, and Fortune 500 risk managers. Secondary validation drew from NAIC reserving standard filings, SEC climate disclosure rule dockets, state insurance department rate filing databases, and carrier statutory financial statements. Bottom-up policy count enumeration and top-down premium aggregation were triangulated against broker placement data.
Input-output matrices mapped coverage type demand against business size tiers and industry verticals across the projection horizon. Segmentation dimensions modeled included coverage structure, enterprise scale, distribution channel, and regional regulatory cluster. CAGRs were derived through exponential smoothing of historical placement velocity adjusted for climate mandate adoption curves and cyber-physical convergence penetration. Forecast inputs incorporated reinsurance capacity availability indices and parametric policy adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under SEC rule reinstatement scenarios and secondary peril volatility spikes. Projections reflect assumptions about regulatory harmonization timelines and actuarial talent pipeline recovery. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Iran Property and Casualty Insurance Market
Life and Non Life Insurance
Malaysia Life Insurance Market
Life and Non Life Insurance
Indonesia Life and Non-Life Insurance Market
Life and Non Life Insurance
Japan Life and Non-Life Insurance Market
Life and Non Life Insurance
Sri Lanka Life and Non-Life Insurance Market
Life and Non Life Insurance
Germany Life and Non-Life Insurance Market
Life and Non Life Insurance
Life Reinsurance Market
Life and Non Life Insurance
Singapore Life and Non-Life Insurance Market
Life and Non Life Insurance
Israel Life and Non-Life Insurance Market
Life and Non Life Insurance
Australia Life and Non-Life Insurance Market
Life and Non Life Insurance
USA Life and Non-Life Insurance Market
Life and Non Life Insurance
UAE Life & Non-Life Insurance Market
Life and Non Life Insurance
Ireland Life and Non-Life Insurance Market
Life and Non Life Insurance
France Life and Non-Life Insurance Market
Life and Non Life Insurance
Uruguay Life and Non-Life Insurance Market
Life and Non Life Insurance
Spain Life & Non-Life Insurance Market