
 Ireland Life and Non-Life Insurance Market | 2026-2036
Ireland Life and Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Ireland Life and Non-Life Insurance Market Foresight
SME commercial coverage is repositioning as the fastest-expanding buyer segment among Ireland's indigenous enterprises. Royal London Ireland leverages its mutual ownership structure to sustain pricing discipline in the life pensions segment. Zurich Insurance Company anchors its Irish operations through specialty commercial lines serving multinational subsidiaries domiciled in Dublin.
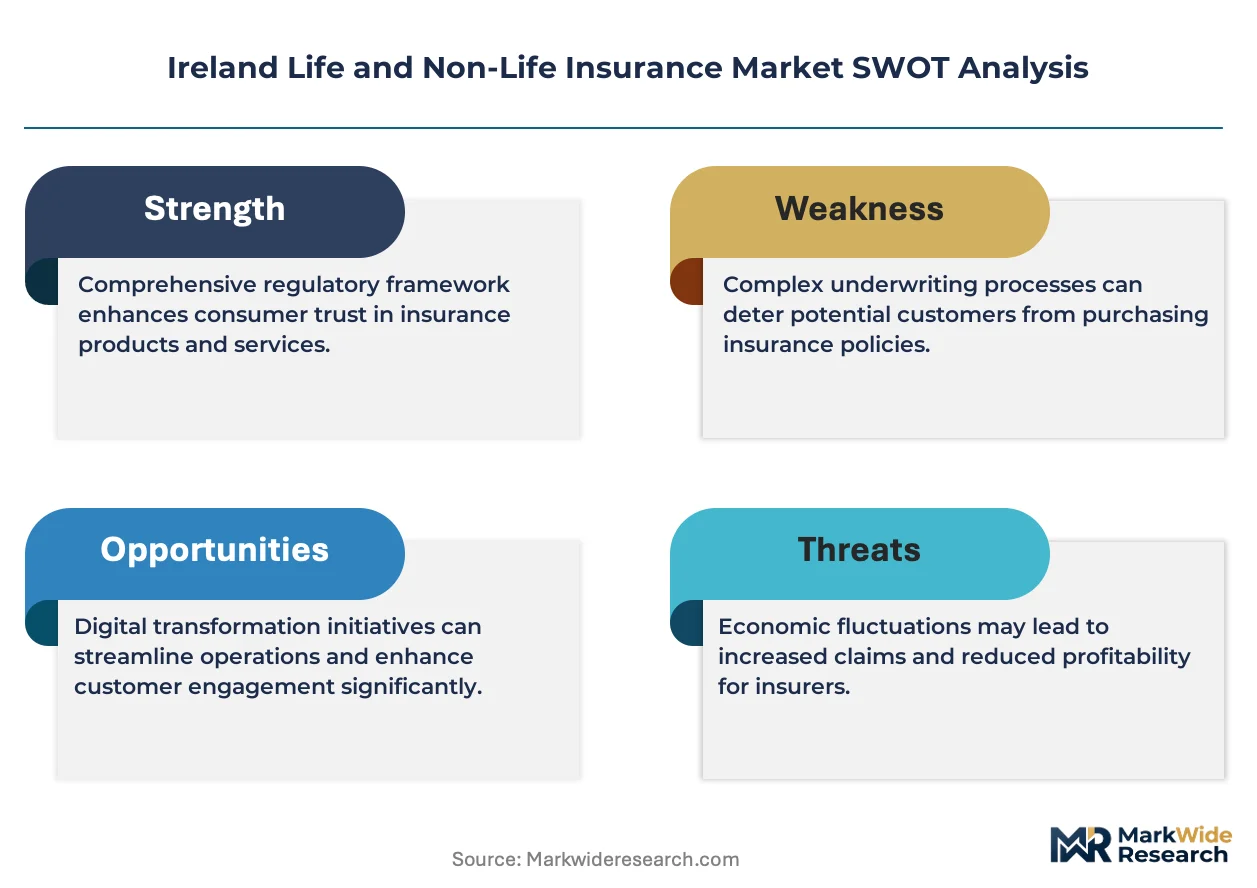
Ireland Life and Non-Life Insurance constitutes a dual-structure financial services sector encompassing mortality-risk contracts with actuarially determined reserves and property-casualty instruments priced through probabilistic loss modeling. The sector operates under Solvency II capital requirements with risk-based reserving thresholds that determine product viability and distributor compensation structures. Life Policies and Whole Life contracts within the Policy Duration dimension retain the deepest margin pools due to long-duration liability matching and investment income capture. Health Insurance distribution through Brokers channels exhibits the most rapid structural expansion as employer-sponsored schemes displace individual direct purchases.
The Central Bank of Ireland enforces Solvency II transposition through granular capital add-ons and recovery planning mandates that reshape product design and reinsurance purchasing. EIOPA's supervisory convergence standards further calibrate cross-border passporting permissions for Irish-domiciled carriers operating across EU member states. Stakeholders must monitor evolving conduct accountability rules and digital distribution licensing requirements as the regulatory perimeter tightens around algorithmic underwriting and price-walking prohibitions.
Market Dynamics
The Central Bank of Ireland's Individual Accountability Framework is compressing operational timelines across underwriting and claims functions, forcing distributors to restructure compliance workflows before enforcement deadlines crystallize.
Growth Catalysts
- Corporate Pension Expansion:Technology sector employers in Dublin are widening defined-contribution scheme participation, pulling new cohorts into long-duration life products with automatic enrollment mechanics.
- Solvency II Transposition:Ireland's granular capital add-ons are creating regulatory clarity that attracts captive reinsurers to domicile at the International Financial Services Centre, deepening local risk-pooling capacity.
- Algorithmic Underwriting:Machine learning models deployed for mortality risk scoring are compressing policy issuance cycles from weeks to days, unlocking broker channel throughput.
Market Restraints
- Interest Rate Sensitivity:Long-duration life reserves face mark-to-market volatility when European Central Bank policy rates shift, compressing investment income spreads that back guaranteed annuity products.
- Reinsurance Supply Concentration:Bermuda and London market capacity providers dominate catastrophe excess-of-loss coverage for Irish property-casualty carriers, creating single-source dependency for peak perils.
- Legacy System Technical Debt:Core policy administration platforms running on 1990s architectures constrain real-time data extraction for regulatory reporting, forcing parallel manual reconciliation processes.
Strategic Opportunities
- Cork-Galway Corridor Penetration:Indigenous SME clusters outside Dublin exhibit sub-40% commercial coverage rates, offering broker expansion terrain with lower customer acquisition costs than saturated capital markets.
- Embedded Distribution Partnerships:Fintech payroll platforms are opening API-accessible channels for micro-life and income protection products, bypassing traditional intermediary economics.
- EIOPA Supervisory Convergence:Passporting standardization across EU member states is reducing compliance fragmentation for Irish-domiciled carriers expanding into Benelux and Nordic markets.
Industry Challenges
- Actuarial Talent Scarcity:Solvency II technical provision specialists command premium compensation, constraining mid-tier carriers from building in-house capital modeling capabilities.
- Claims System Integration Complexity:Legacy mainframe claims platforms resist API connectivity with new fraud detection algorithms, delaying real-time anomaly flagging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ireland Life and Non-Life Insurance Market |
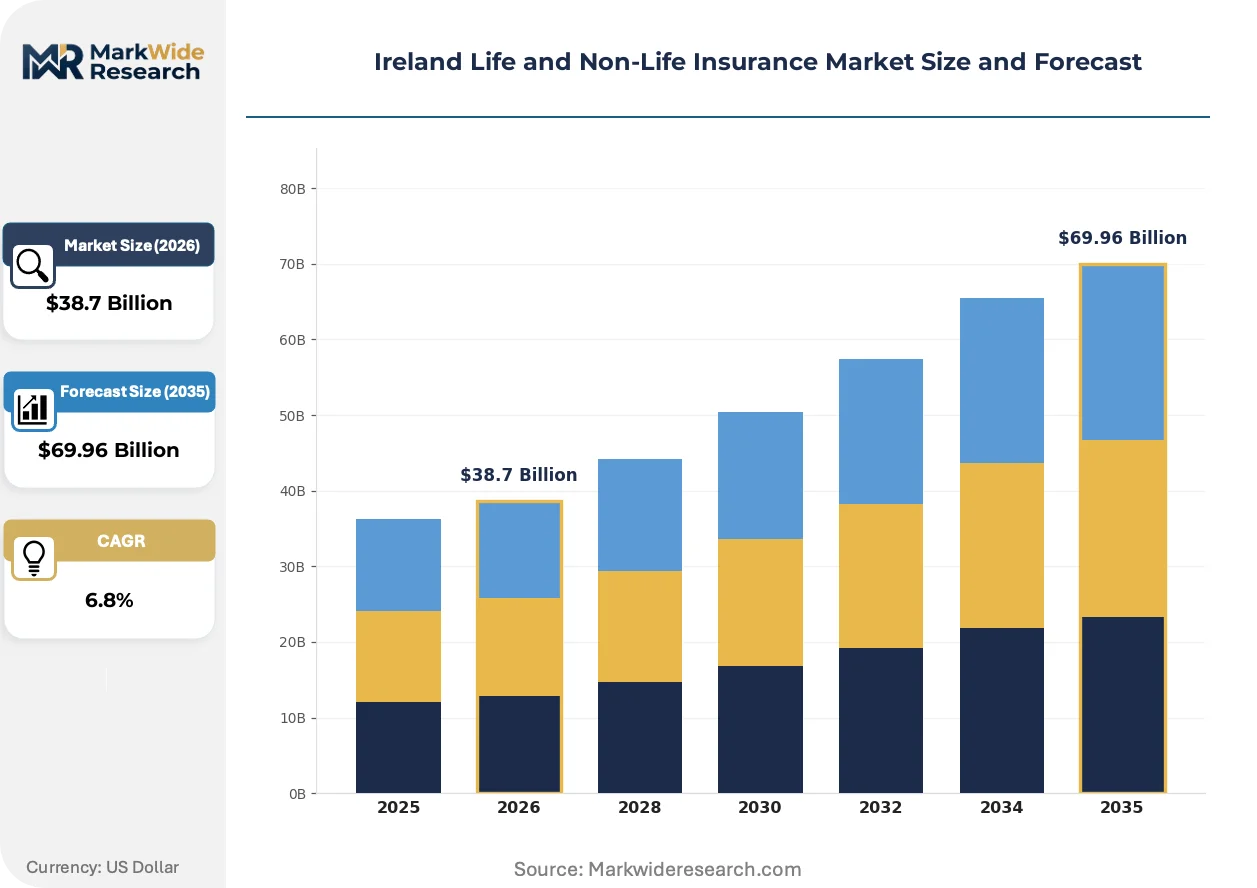
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Policies, Health Insurance, Property Insurance, Vehicle Insurance Customer Type: Individuals, Families, Corporations, SMEs Distribution Channel: Online, Brokers, Agents, Direct Sales Policy Duration: Short-term, Long-term, Whole Life, Term Life |
| Companies Covered | Royal London Ireland, Carne Global Financial Services Limited, Zurich Insurance Company, Inaza, MetLife, Aon, Fineos Corporation Limited, Teambase Ireland, Allianz Re Dublin, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ireland Life and Non-Life Insurance Market Shifts & Advancements
Digital distribution infrastructure is fragmenting traditional broker hierarchies while regulatory technology investments absorb compliance budgets that previously flowed to product development.
Cloud-native policy administration platforms is modularizing core insurance operations into microservices that carriers can deploy, scale, or replace independently. Mid-sized Irish life offices are migrating from monolithic legacy stacks to containerized architectures, enabling faster product configuration without full system replacement cycles. This modularizing is compressing time-to-market for new riders and reducing dependency on single-vendor lock-in.
The Central Bank of Ireland's conduct accountability rules are mandating named individual responsibility for pricing and claims decisions, extending personal liability to senior underwriting managers. Irish carriers are reconstituting governance committees with documented decision trails to satisfy upcoming attestation requirements. Life and pension product development teams are most affected, slowing product launches while compliance infrastructure catches up to procedural mandates.
Employer-sponsored health schemes are displacing individual direct purchases as the dominant distribution path for medical expense coverage. Large technology and pharmaceutical employers in Dublin's financial services cluster are negotiating group rates that undercut retail premiums, consolidating purchasing power. This concentration is most visible among multinational subsidiaries with standardized benefits across European operations, where Irish employees receive coverage as automatic employment terms rather than discretionary purchases.
Ireland Life and Non-Life Insurance Market Segmentation
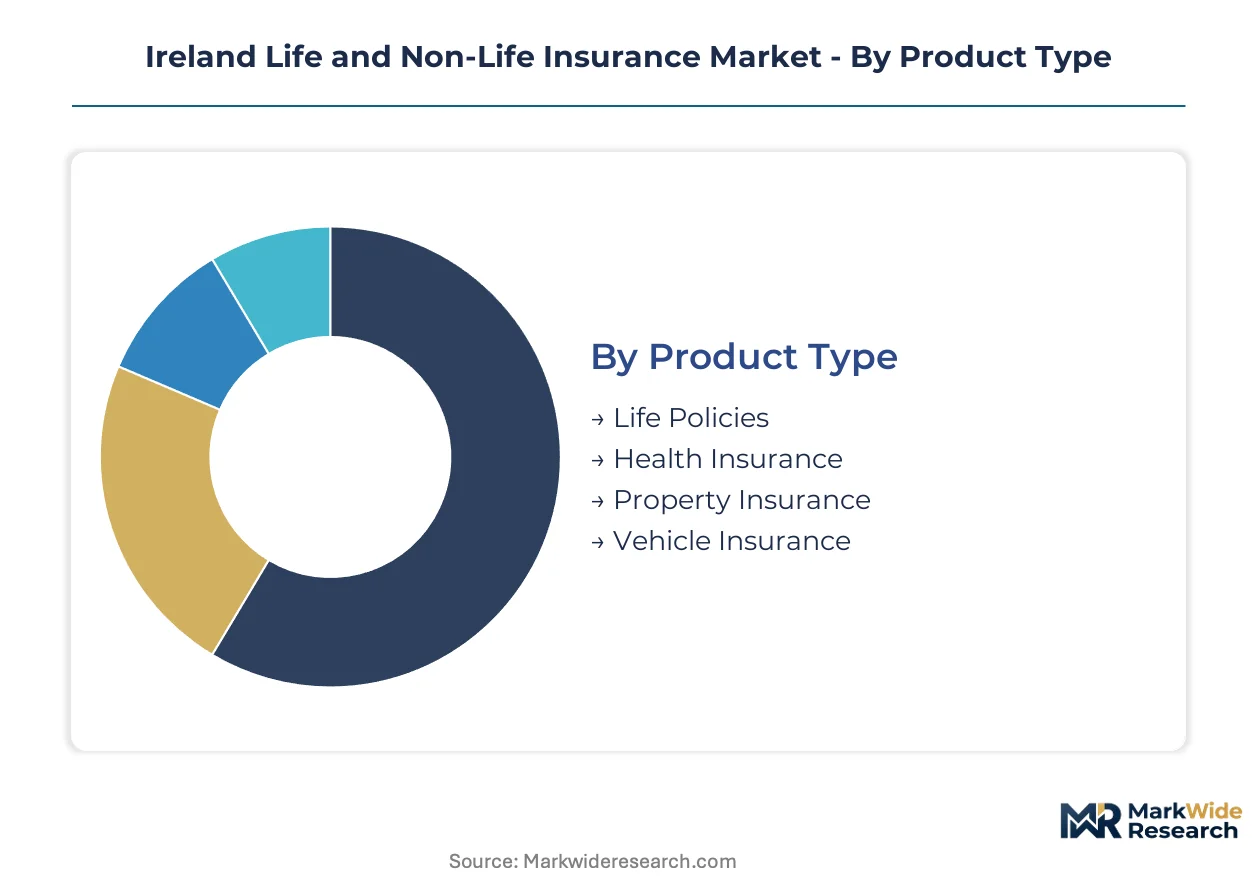
Segmentation reveals how Ireland's dual-structure insurance sector allocates capital between mortality-risk reserves and property-casualty instruments. Each dimension shapes distributor compensation, regulatory capital requirements, and reinsurance purchasing patterns differently.
Product Type:
Product replacement cycles accelerate as Solvency II capital add-ons force carriers to retire legacy offerings with inadequate risk-adjusted returns.
- Life Policies:Mortality-risk contracts with actuarially determined reserves backing defined-benefit and defined-contribution pension schemes. Dublin's technology employers are widening automatic enrollment, pulling new workforce cohorts into long-duration products with guaranteed annuity features.
- Health Insurance:Medical expense coverage distributed through employer-sponsored schemes displacing individual direct purchases. Large pharmaceutical and technology employers in the International Financial Services Centre negotiate group rates that undercut retail premiums, consolidating purchasing power.
- Property Insurance:Probabilistic loss modeling prices catastrophe and commercial property risks. Bermuda and London market reinsurers dominate excess-of-loss capacity for Irish carriers, creating single-source dependency for peak perils.
- Vehicle Insurance:Motor liability and comprehensive coverage regulated through the country's national insurance regulator. Telematics-enabled pricing is compressing risk pools but legacy claims platforms delay real-time fraud detection integration.
Volume placements concentrate in Life Policies; the faster expansion belongs to Health Insurance.
Customer Type:
Cost tier differentiation separates mass-market individual purchasers from institutional buyers with captive risk management capabilities.
- Individuals:Retail purchasers of term life, motor, and household coverage through direct and intermediary channels. Premium sensitivity drives price comparison platform usage, eroding traditional broker attachment rates.
- Families:Multi-life purchasing units seeking bundled health and life protection. Cork-Galway corridor households exhibit sub-40% commercial coverage penetration, offering lower customer acquisition costs than saturated Dublin markets.
- Corporations:Multinational subsidiaries domiciled at the International Financial Services Centre purchasing specialty commercial lines and captive reinsurance structures. Standardized benefits across European operations consolidate Irish employee coverage as automatic employment terms.
- SMEs:Indigenous enterprises outside Dublin's financial services cluster repositioning as the fastest-expanding buyer segment. Broker expansion into regional SME clusters encounters less competition than capital market saturation.
Corporations dominate premium volume; SMEs are climbing the fastest as regional penetration deepens.
Distribution Channel:
Channel economics fragment as digital infrastructure absorbs compliance budgets that previously flowed to product development and intermediary incentives.
- Online:Direct-to-consumer platforms and price comparison engines. Algorithmic underwriting compresses policy issuance cycles from weeks to days, unlocking throughput for standardized products.
- Brokers:Independent intermediaries dominating health insurance distribution as employer-sponsored schemes displace individual purchases. The Central Bank of Ireland's Individual Accountability Framework forces restructuring of compliance workflows before enforcement deadlines.
- Agents:Tied representatives focused on rural and older demographic segments with lower digital literacy. Legacy commission structures face pressure from embedded fintech partnerships.
- Direct Sales:Carrier-owned channels and bancassurance arrangements. Royal London Ireland leverages mutual ownership to sustain pricing discipline without shareholder dividend pressure.
Brokers retain the deepest volume; online channels are gaining share fastest through API-accessible embedded distribution.
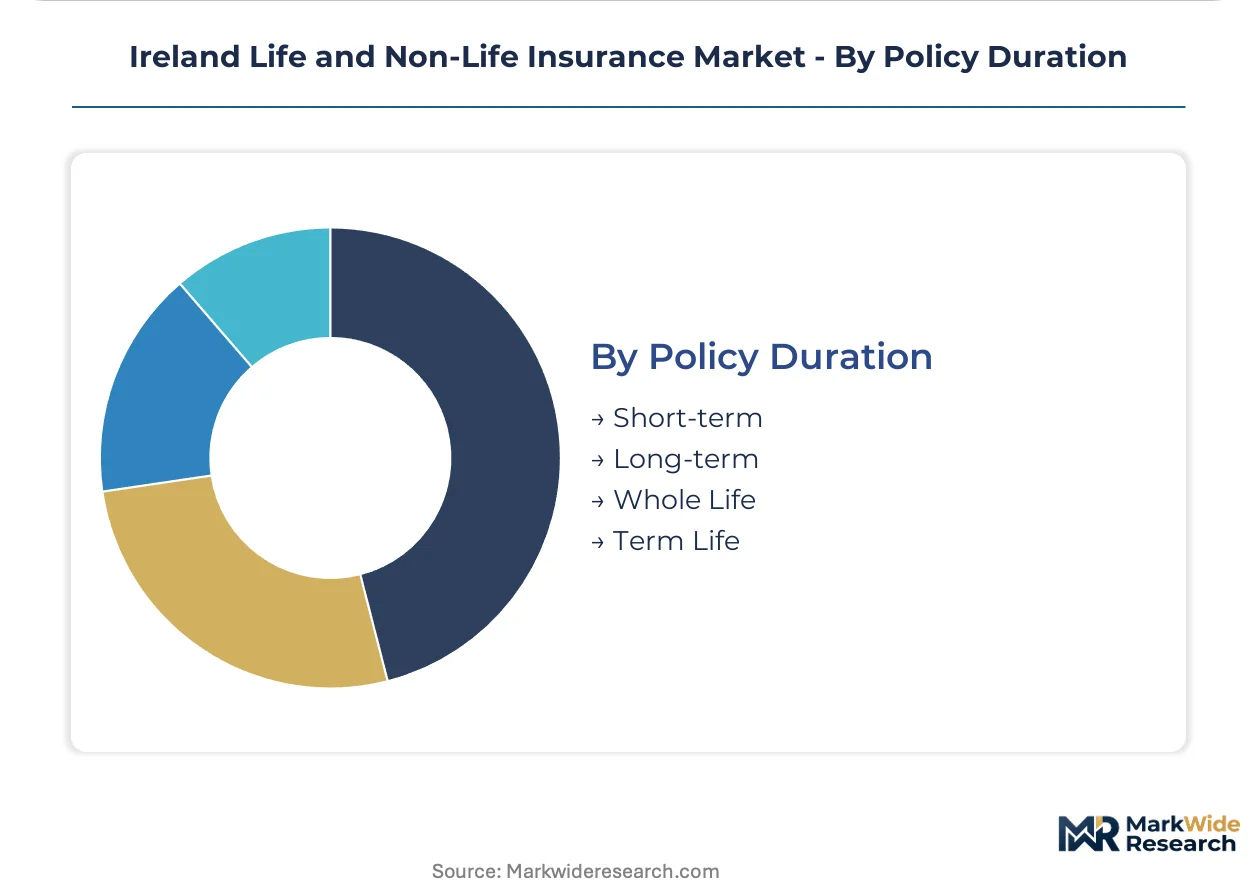
Policy Duration:
Maturity-based reserving requirements create margin differentiation between short-tail property-casualty and long-tail life liabilities.
- Short-term:Annual renewable contracts for motor and property coverage. European Central Bank rate volatility compresses investment income spreads, pressuring pricing adequacy.
- Long-term:Multi-year life and pension products with liability duration matching. Actuarial talent scarcity constrains mid-tier carriers from building in-house Solvency II technical provision capabilities.
- Whole Life:Permanent mortality coverage with cash value accumulation. Deepest margin pools derive from long-duration liability matching and captive investment income capture.
- Term Life:Pure protection products with no cash value component. Simplified underwriting enables digital distribution but limits cross-selling attachment.
Whole Life commands the thickest margins; Long-term policies show the steepest expansion trajectory as pension auto-enrollment widens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ireland's insurance production concentrates in Dublin's International Financial Services Centre, while consumption distributes across regional SME clusters and corporate employee bases. The capital's captive reinsurer ecosystem generates cross-border premium flows that exceed domestic policyholder demand.
Dublin
Technology sector employers widen defined-contribution pension participation through automatic enrollment mechanics. The Central Bank of Ireland enforces Solvency II transposition through granular capital add-ons that reshape product design. Specialist brokers and captive reinsurers cluster around the International Financial Services Centre, deepening local risk-pooling capacity for multinational subsidiaries.
Cork
Indigenous pharmaceutical and manufacturing enterprises drive commercial property and liability coverage expansion. The country's national insurance regulator mandates recovery planning that affects regional carrier operations. SME clusters exhibit sub-40% commercial coverage penetration, offering broker expansion terrain with lower customer acquisition costs than saturated capital markets.
Galway
Medical device and ICT employers negotiate group health rates that consolidate purchasing power among technology workforces. Employer-sponsored schemes displace individual direct purchases as the dominant distribution path. Regional households seek bundled health and life protection through intermediary channels less saturated than Dublin's broker hierarchy.
Limerick
Aviation leasing and engineering services create specialty commercial lines demand among multinational back-office operations. EIOPA's supervisory convergence standards calibrate cross-border passporting permissions for carriers operating from Shannon's financial services zone. Mid-sized indigenous enterprises reposition as the fastest-expanding buyer segment for commercial coverage outside the capital.
Ireland Life and Non-Life Insurance Market Competitive Landscape
Top-tier vendors anchor the mutual and multinational tier, while mid-cap specialists and insurtech platforms occupy fragmented niches. Dublin's International Financial Services Centre concentrates carrier domiciliation decisions, creating geographic clustering around regulatory expertise. Two strategic archetypes dominate: mutual ownership structures that sustain pricing discipline without shareholder dividend pressure, and captive reinsurer operations that leverage EU passporting rights. Competitive moves concentrate on embedded distribution partnerships and cloud-native policy administration migration.
Among Ireland-based and internationally domiciled carriers, Royal London Ireland represents mutual ownership archetypes that leverage structural advantages in life pensions. Zurich Insurance Company exemplifies multinational specialty commercial line positioning serving captive structures. Fineos Corporation Limited occupies the insurtech platform tier that enables carrier digitization without core system replacement cycles.
| Leading Market Players |
|---|
| Royal London Ireland |
| Carne Global Financial Services Limited |
| Zurich Insurance Company |
| Inaza |
| MetLife |
| Aon |
| Fineos Corporation Limited |
| Teambase Ireland |
| Allianz Re Dublin |
| Others |
Supply & Pricing Matrix
Actuarial talent scarcity in Dublin's International Financial Services Centre widens labor-cost differentials between tier-one mutual carriers and mid-tier specialists, compressing pricing-tier spreads as Solvency II technical provision specialists command premium compensation that smaller carriers cannot match.
Pricing Analysis
Margin tightening in long-duration life products reflects European Central Bank rate volatility compressing investment income spreads that back guaranteed annuity features. Pricing stratifies across premium mutual ownership structures, standard shareholder-owned tiers, and economy direct-to-consumer channels, with quality grade and distribution complexity as primary differentiation drivers. Cost-down pressure on mid-tier carriers accelerates because actuarial talent scarcity constrains in-house capital modeling capabilities. Retail individual purchasers exhibit highest price sensitivity through comparison platform usage, while multinational corporate purchasers show lowest sensitivity due to standardized benefits procurement.
Supply Chain Analysis
Freight costs for reinsurance treaty documentation and regulatory filing materials concentrate supply chain expenditure between Ireland, Bermuda, and London market capacity providers. Raw material dependencies center on actuarial software licenses, cloud computing infrastructure, and compliance technology platforms. Single-source vulnerability dominates catastrophe excess-of-loss coverage where Bermuda and London market reinsurers control peak peril capacity. Distribution runs through broker intermediaries for health and commercial lines, with embedded fintech partnerships emerging for micro-life products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ireland's insurance sector sits in a technology-transition phase as cloud-native policy administration platforms replace legacy 1990s mainframe architectures that constrain real-time data extraction.
For Market Incumbents: To counter embedded fintech distribution partnerships eroding traditional broker economics, Royal London Ireland and mutual ownership archetypes should deepen captive investment income capture through long-duration liability matching while accelerating API connectivity with payroll platform providers to retain employer-sponsored scheme access. For New Entrants and Emerging Players: Begin with Cork-Galway corridor SME commercial coverage where sub-40% penetration rates offer lower customer acquisition costs than saturated Dublin markets, targeting indigenous pharmaceutical and manufacturing enterprises with modular cloud-native policy administration that bypasses legacy system replacement cycles. For Investors and Strategic Acquirers: The window for entry favors insurtech platform specialists with containerized microservices architectures, as mid-sized Irish life offices migrate from monolithic stacks. Watch Central Bank of Ireland Individual Accountability Framework enforcement timelines as inflection indicator for compliance technology demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Containerized microservices enable Royal London Ireland to compress product configuration cycles without full system replacement. |
| Embedded Distribution Partnership | API-accessible fintech payroll platforms bypass traditional broker economics for micro-life penetration. |
| Regional SME Expansion | Cork-Galway corridor broker expansion encounters less competition than Dublin's saturated capital markets. |
| Captive Reinsurer Domiciliation | Solvency II regulatory clarity attracts Bermuda and London capacity providers to deepen local risk-pooling. |
| Compliance Technology Investment | Named individual responsibility mandates force governance committee reconstitution with documented decision trails. |
Research Methodology
Multi-period observation of premium volume flows, distribution channel economics, and regulatory capital requirement changes anchored the trend analysis, supplemented by interviews with chief actuaries, broker network heads, compliance officers at the Central Bank of Ireland, and technology procurement leads at multinational carriers. Secondary validation drew from Solvency II regulatory filings, EIOPA supervisory convergence reports, Irish Life and Non-Life Insurance sector trade data, and cloud infrastructure vendor disclosures. Bottom-up policy-level data triangulated against top-down sector aggregates to reconcile volume estimates.
Segment-weighting across product type, customer archetype, distribution channel, and policy duration dimensions shaped the analytical framework, with mortality-risk reserves and property-casualty instruments modeled separately due to divergent capital treatment. CAGRs derived from fitted growth curves applied to base-year observations, with algorithmic underwriting adoption curves and pension auto-enrollment participation rates as industry-specific forecast inputs across the projection horizon.
Underlying measurement precision varies by segment; Dublin corporate pension data carries tighter precision than regional SME penetration estimates due to disclosure granularity differences. Forecasts reflect assumptions about European Central Bank rate trajectories and EIOPA passporting standardization timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Spain Life & Non-Life Insurance Market
Life and Non Life Insurance
Finland Life and Non-Life Insurance Market
Life and Non Life Insurance
North America Business Income Insurance Market
Life and Non Life Insurance
UAE Life and Annuity Insurance Market
Life and Non Life Insurance
Sri Lanka Life and Non-Life Insurance Market
Life and Non Life Insurance
UAE Life & Non-Life Insurance Market
Life and Non Life Insurance
USA Life and Non-Life Insurance Market
Life and Non Life Insurance
Sweden Life and Non-Life Insurance Market
Life and Non Life Insurance
Group Life Insurance Market
Life and Non Life Insurance
Iran Property and Casualty Insurance Market
Life and Non Life Insurance
Global Life and Non-Life Insurance Market
Life and Non Life Insurance
South Korea Life & Non-Life Insurance Market
Life and Non Life Insurance
France Life and Non-Life Insurance Market
Life and Non Life Insurance
Australia Life and Non-Life Insurance Market
Life and Non Life Insurance
Burial Insurance Market
Life and Non Life Insurance
Asia-Pacific Life and Annuity Insurance Market