
 Asia-Pacific Life and Annuity Insurance Market | 2026-2036
Asia-Pacific Life and Annuity Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Life and Annuity Insurance Market Outlook
Cloud-native core policy administration is tilting product development cycles from months to weeks across the Asia-Pacific life insurance sector. AIA Group leverages its Pan-Asian digital platform to sustain premium growth across multiple Southeast Asian markets. China Life Insurance anchors its competitive stance through proprietary agency networks spanning rural counties and provincial capitals. Ping An Insurance differentiates via integrated health-to-wealth ecosystems that bind life policies with medical services and banking products.
Asia-Pacific life and annuity insurance encompasses long-duration risk transfer contracts where insurers collect periodic or lump-sum premiums in exchange for guaranteed death benefits, survival payouts, or income streams structured over decades; these instruments pool mortality and longevity risk across millions of policyholders while deploying float into regulated investment portfolios to meet future liabilities. Whole life and term life products dominate premium volumes across the region, though universal life is gaining traction among affluent segments seeking flexible premium schedules. Distribution through banks and direct digital channels is displacing traditional agency models fastest in South Korea and Singapore, where regulatory sandboxes have accelerated insurtech licensing.
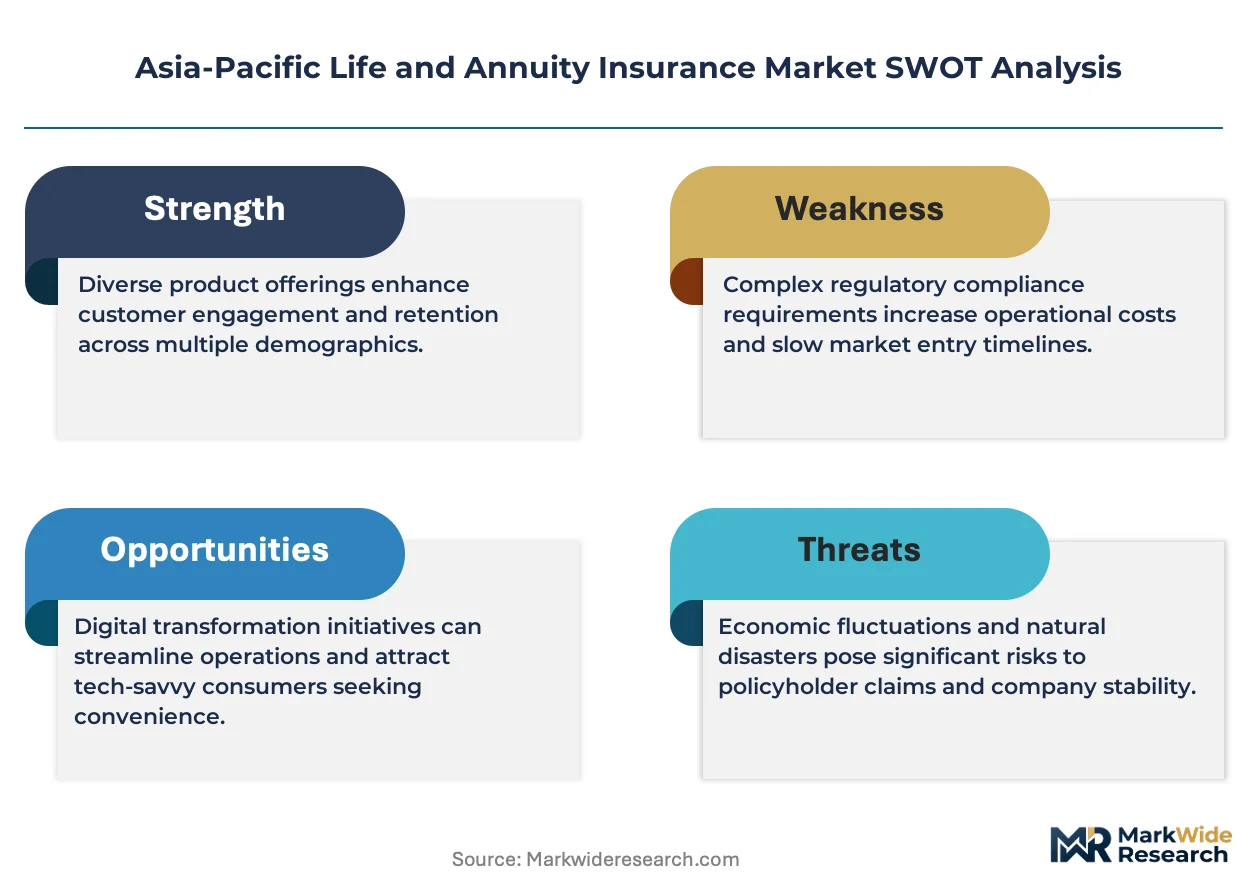
Japan's FSA and Australia's APRA enforce stringent solvency frameworks that shape capital allocation toward lower-risk asset classes and constrain product innovation timelines. India's IRDAI and China's CBIRC mandate electronic policy standards and customer protection protocols that raise compliance costs but reduce mis-selling exposure. Stakeholders must monitor how cross-border data localization requirements across ASEAN markets will fragment cloud infrastructure strategies and alter partnership economics for foreign insurers seeking regional scale.
Market Dynamics
Cloud-native core systems are compressing product development cycles from months to weeks across Asia-Pacific life insurers, forcing incumbents to rebuild legacy infrastructure or cede ground to digitally native competitors. This technological inflection is redistributing competitive advantage toward carriers with modular, API-driven architectures.
Growth Catalysts
- India's IRDAI digitization mandates:Electronic policy standards and e-KYC protocols accelerate policy issuance velocity while reducing documentation friction for rural and semi-urban applicants.
- Longevity risk transfer instruments:Rising life expectancy across Japan, South Korea, and Singapore expands addressable demand for annuitization products and deferred income solutions.
- Bancassurance channel deepening:Strategic partnerships between insurers and banking networks in Indonesia, Thailand, and the Philippines penetrate mass-affluent segments previously unreachable through agency models.
Market Restraints
- Solvency capital intensity:Japan's FSA and Australia's APRA impose risk-based capital requirements that constrain insurers from deploying float into higher-yielding alternative assets.
- Legacy system debt:Decades-old policy administration platforms at established carriers create integration friction with modern distribution APIs and claims automation tools.
- Mortality assumption volatility:Pandemic-era experience uncertainty and post-COVID mortality pattern shifts complicate pricing precision for term and whole life products.
Strategic Opportunities
- Vietnam and Philippines underpenetration:Insurance density below 2% of GDP in these markets creates first-mover advantages for carriers establishing proprietary agency networks.
- Health-to-wealth ecosystem convergence:Integration of life policies with telemedicine subscriptions, wellness apps, and preventive health screening creates stickier customer relationships.
- China's NMPA regulatory sandbox:Pilot programs for AI-driven underwriting and claims adjudication open pathways for algorithmic risk selection in tier-2 and tier-3 cities.
Industry Challenges
- Actuarial and data science talent scarcity:Competition for professionals capable of building predictive mortality models and embedded insurance pricing engines intensifies compensation costs.
- Cross-border data localization fragmentation:Divergent ASEAN requirements for customer data residency complicate cloud infrastructure strategies for regional carriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Life and Annuity Insurance Market |
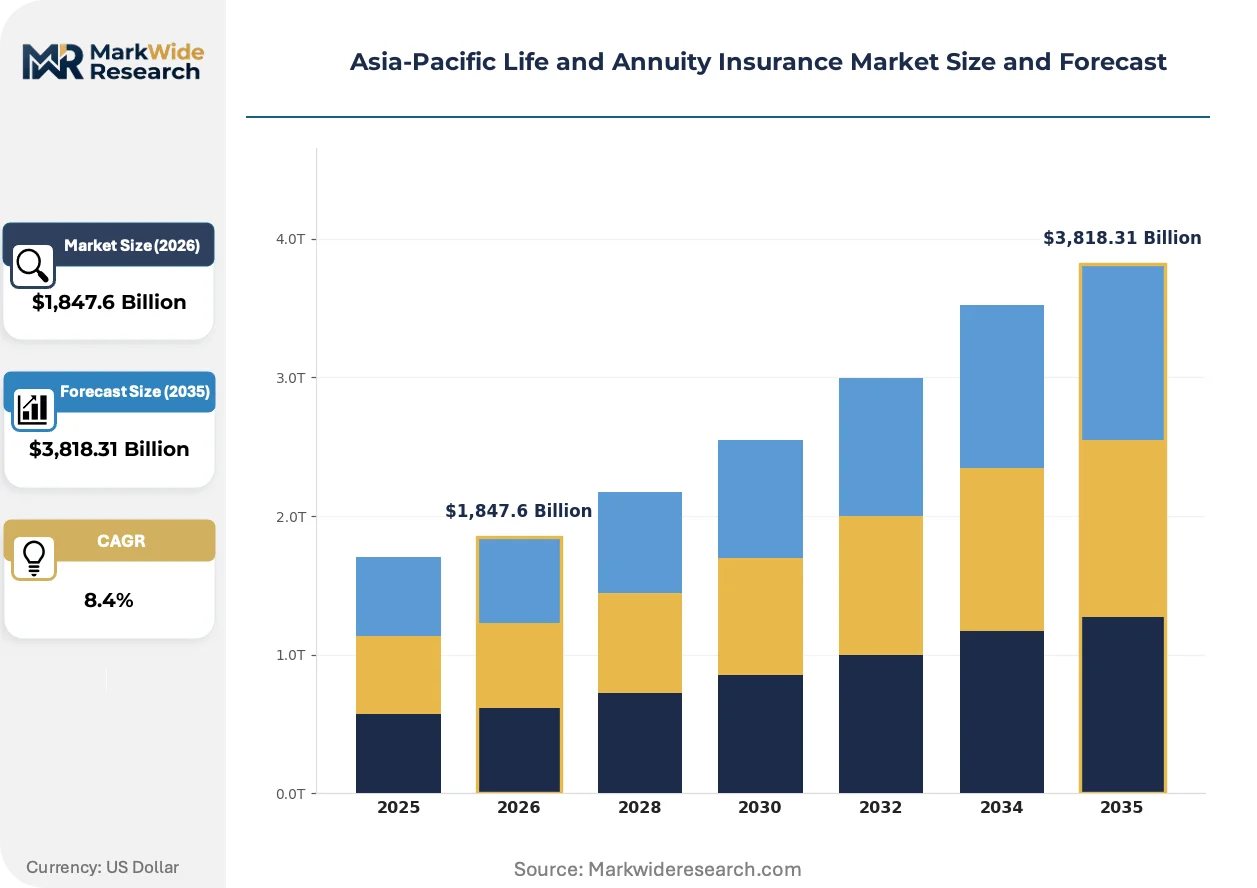
| Market Size in 2026 | $1,847.6 Billion |
| Market Size in 2035 | $3,818.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Life, Term Life, Universal Life, Variable Life Distribution Channel: Direct Sales, Brokers, Agencies, Banks End User: Individuals, Corporates, Institutions, Small Businesses Policy Type: Single Premium, Regular Premium, Group Insurance, Retirement Plans |
| Companies Covered | AIA Group, China Life Insurance, Nippon Life Insurance, Prudential plc, Manulife Financial, Life Insurance Corporation of India, Ping An Insurance, HDFC Life Insurance, Dai-ichi Life, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Life and Annuity Insurance Market Strategic Shifts
Embedded insurance distribution and parametric product structures are dissolving traditional boundaries between life coverage and adjacent financial services. Carriers are racing to embed protection into banking, e-commerce, and wealth management touchpoints before distribution economics permanently shift.
Blockchain-enabled smart contracts are digitizing claims settlement workflows by automating beneficiary verification and payout execution upon mortality confirmation. Mid-sized insurers in Singapore and Hong Kong are piloting these systems to compress claims cycles from weeks to hours. The technology is digitizing trust mechanisms that previously required manual notarization and document authentication.
China's CBIRC and India's IRDAI are mandating interoperable data standards for policy portability and customer consent management. These frameworks force carriers to re-architect customer data platforms around open API specifications rather than proprietary silos. Product development teams in both markets are responding by modularizing policy components to enable faster recombination.
Direct-to-consumer digital channels are displacing traditional agency hierarchies among younger policyholders in South Korea and Australia. Insurtech platforms offer instant quote comparison and simplified underwriting through wearable data integration. This behavioral pivot is most pronounced among millennials purchasing term life products through mobile-native interfaces rather than agent-mediated consultations.
Asia-Pacific Life and Annuity Insurance Market Segmentation
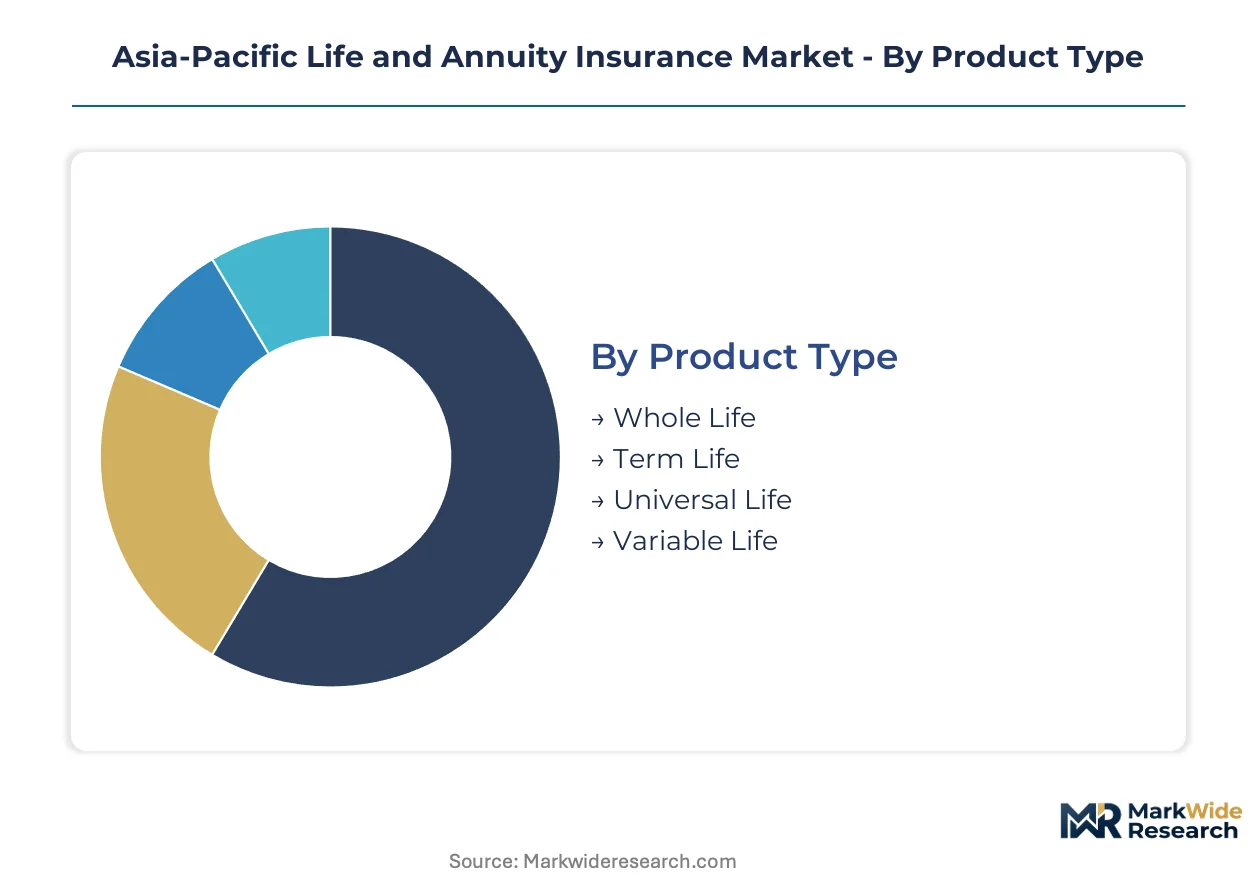
Asia-Pacific life insurers structure portfolios across four distinct dimensions. Product architecture, distribution economics, buyer profiles, and premium mechanics each govern capital allocation and pricing precision differently across the region.
Product Type:
Cost tier segmentation separates guaranteed-benefit products from investment-linked alternatives with divergent capital intensity and margin profiles.
- Whole Life:Permanent coverage combining death protection with cash value accumulation through insurer-managed portfolios. Demand concentrates among affluent households in Singapore and Hong Kong seeking estate planning instruments with stable surrender values.
- Term Life:Pure mortality protection without savings components, priced on renewable annual rates or level premiums over fixed durations. India's tier-2 cities and South Korea's millennial workforce are rotating toward this structure as digital direct-to-consumer platforms compress distribution costs.
- Universal Life:Flexible premium schedules and adjustable death benefits linked to declared crediting rates. Japan's aging policyholders favor this format for its transparency in crediting methodology.
- Variable Life:Death benefits fluctuating with underlying investment account performance, typically equity or balanced fund options. Australia's SMSF trustees deploy these for tax-advantaged wealth accumulation.
Whole Life holds installed capacity. Term Life is rotating up the share rankings.
Distribution Channel:
Application-based segmentation traces how policyholder acquisition costs and persistency rates vary by intermediary structure.
- Direct Sales:Insurer-controlled digital platforms and call centers eliminating intermediary commissions. South Korea's KakaoBank integration and Australia's Compare the Market aggregators are expanding this channel fastest among term life purchasers.
- Brokers:Independent intermediaries representing multiple carriers with fiduciary duty to advise on optimal product fit. Commercial coverage procurement in Singapore and Hong Kong relies heavily on broker networks for complex multi-life arrangements.
- Agencies:Captive or affiliated salesforces with exclusive carrier relationships, dominant in rural India and provincial China where trust-based selling persists. China's NMPA licensing requirements and India's IRDAI commission caps are compressing agency economics.
- Banks:Bancassurance partnerships leveraging branch networks and deposit customer data for cross-selling. Indonesia's Bank Mandiri and Thailand's SCB partnerships demonstrate deepening penetration into mass-affluent segments previously unreachable through traditional channels.
Agencies hold installed capacity. Direct Sales is rotating up the share rankings.
End User:
Customer type segmentation distinguishes retail protection needs from institutional risk transfer with fundamentally different pricing and servicing models.
- Individuals:Personal policyholders purchasing family protection, retirement income, or estate liquidity. Southeast Asia's expanding middle class in Vietnam and the Philippines is driving retail premium growth as insurance density climbs from sub-2% GDP bases.
- Corporates:Employers sponsoring group life and key person coverage for executive retention. Australia's APRA-regulated superannuation funds and Japan's corporate pension schemes represent concentrated demand for institutional annuitization.
- Institutions:Pension funds, insurers, and reinsurers seeking longevity risk transfer or asset-liability matching instruments. Singapore's reinsurance hub and Hong Kong's captive domicile structure facilitate regional risk pooling.
- Small Businesses:Partnership-owned enterprises securing buy-sell agreements and debt protection. India's MSME sector generates emerging demand through IRDAI-simplified microinsurance frameworks.
Individuals hold installed capacity. Corporates is rotating up the share rankings.
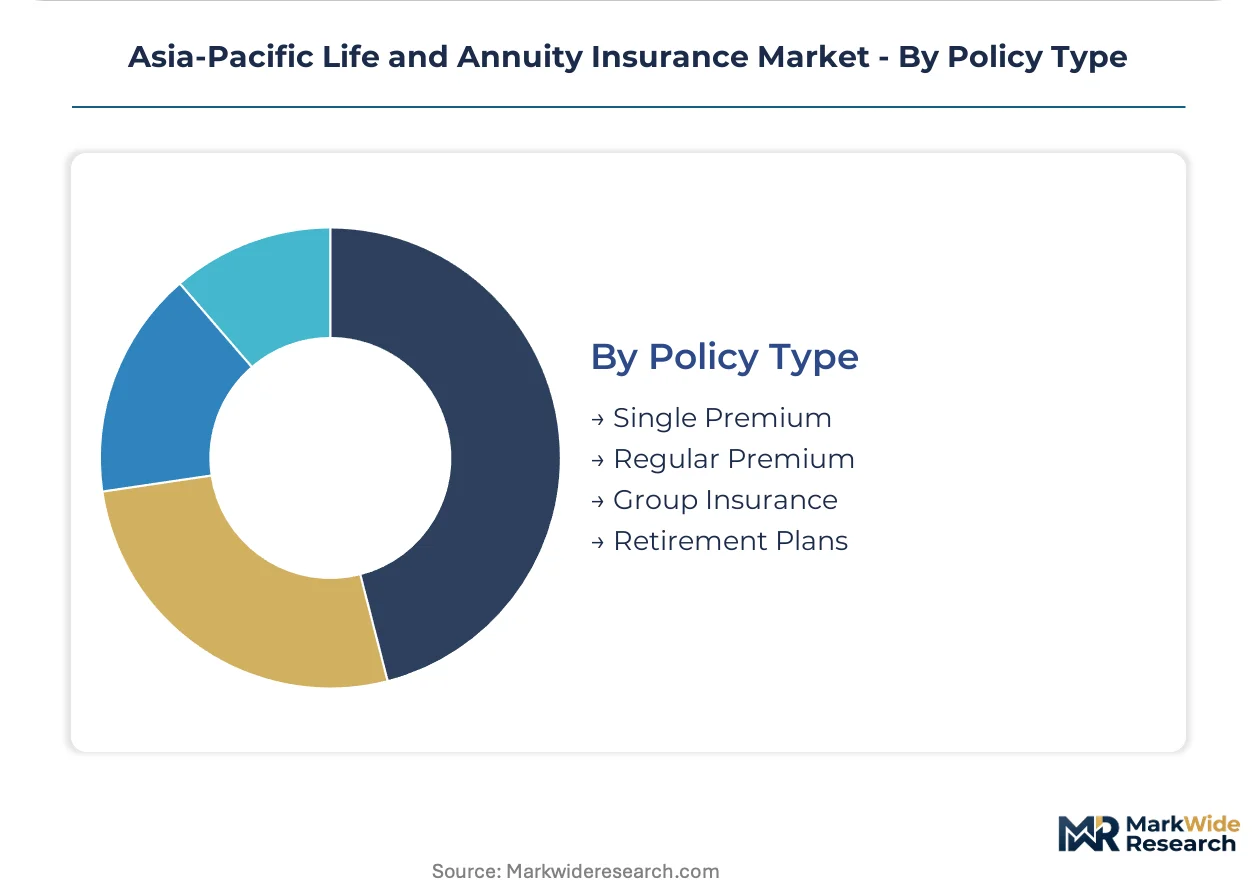
Policy Type:
Premium mechanics segmentation governs insurer cash flow timing, investment horizon, and lapse risk exposure.
- Single Premium:Lump-sum payment at inception generating immediate full commission and locked-in crediting rates. China's high-net-worth segment favors this structure for wealth transfer efficiency under NMPA disclosure rules.
- Regular Premium:Periodic payments—monthly, quarterly, or annual—spreading acquisition costs and reducing policyholder liquidity constraints. India's SIP-modeled insurance purchasing through mobile wallets is expanding this format fastest.
- Group Insurance:Master contracts covering employee populations under simplified underwriting with experience-rated renewals. Japan's declining workforce participation is pressuring group persistency rates.
- Retirement Plans:Deferred annuities and income drawdown products addressing longevity risk through systematic decumulation. Australia's compulsory superannuation system and Singapore's CPF-integrated plans represent mature market structures.
Regular Premium holds installed capacity. Retirement Plans is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's reinsurance hub channels longevity risk transfer instruments into Tokyo and Sydney pension funds, while Hong Kong's captive domicile structures intermediate capital flows between mainland Chinese carriers and ASEAN distribution networks.
China
Tier-2 and tier-3 cities generate premium growth through bancassurance partnerships and mobile wallet integration. The National Medical Products Administration's regulatory sandbox pilots AI-driven underwriting algorithms in provincial capitals. Shanghai's Lujiazui financial district hosts Ping An Insurance's integrated health-to-wealth ecosystem development.
India
Tier-2 urban centers drive policy issuance velocity through electronic KYC protocols and simplified microinsurance frameworks. The Insurance Regulatory and Development Authority of India mandates electronic policy standards that reduce documentation friction for semi-urban applicants. Mumbai's financial district anchors bancassurance partnership negotiations between carriers and banking networks.
Japan
Aging policyholders expand demand for universal life products with transparent crediting methodologies. The Financial Services Agency enforces risk-based capital requirements that constrain deployment into alternative assets. Tokyo's insurance corridor concentrates actuarial talent and longevity risk modeling capabilities for regional reinsurance.
South Korea
Millennial workforce segments rotate toward term life products through digital direct-to-consumer platforms. Regulatory sandboxes accelerate insurtech licensing for instant quote comparison services. Seoul's fintech cluster hosts KakaoBank integration pilots that compress distribution costs for pure protection products.
Australia
Compulsory superannuation system structures drive institutional demand for retirement income and deferred annuity solutions. The Australian Prudential Regulation Authority enforces stringent solvency frameworks shaping capital allocation toward lower-risk asset classes. Sydney's financial district concentrates group life procurement for corporate pension schemes.
Asia-Pacific Life and Annuity Insurance Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent distribution economics. The market structure tiers between integrated financial conglomerates with captive banking networks and focused life carriers with proprietary agency footprints. Strategic archetypes include ecosystem builders binding health services with wealth products, bancassurance specialists leveraging deposit customer data, and direct-to-consumer platforms eliminating intermediary commissions. Dominant competitive moves encompass cloud-native core system replacement and cross-border partnership formation to circumvent data localization barriers.
Among Pan-Asian platform operators, AIA Group and Prudential plc occupy positions spanning multiple Southeast Asian markets through modular digital architectures. Within China-focused integrated carriers, China Life Insurance and Ping An Insurance exemplify divergent paths—one anchoring rural county penetration through exclusive agency networks, the other converging medical services with banking products. Japan's mutual-based specialists, represented by Nippon Life Insurance and Dai-ichi Life, sit within legacy policy administration constraints that create integration friction with modern distribution APIs.
| Leading Market Players |
|---|
| AIA Group |
| China Life Insurance |
| Nippon Life Insurance |
| Prudential plc |
| Manulife Financial |
| Life Insurance Corporation of India |
| Ping An Insurance |
| HDFC Life Insurance |
| Dai-ichi Life |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in actuarial talent pools across Singapore and Hong Kong tightens pricing discipline for complex longevity products while compressing margins on standardized term coverage. This utilization imbalance pushes carriers toward modular product architectures that separate high-touch advisory services from automated direct-to-consumer issuance.
Pricing Analysis
Legacy mainframe-to-cloud migration costs create a generational pricing gap: incumbent carriers price whole life products to recover technical debt while digital-native entrants undercut on term life through API-driven distribution. Premium-mid-economy pricing differentiation separates advised estate planning instruments from self-service pure protection. Cost compression in mass-market term products intensifies as India's IRDAI commission caps squeeze agency economics. Retail buyers in Vietnam and the Philippines exhibit highest price sensitivity, while Singapore's high-net-worth segment absorbs advisory fees for complex universal life structures.
Supply Chain Analysis
Tariff exposure between China and ASEAN markets fragments cloud infrastructure strategies for regional carriers seeking unified policy administration platforms. Technology sourcing concentrates in India, Singapore, and South Korea, with core systems integration drawing from specialized insurtech vendors and captive IT development centers. Single-source vulnerability in legacy policy administration platforms at Japan's mutual carriers creates integration friction with modern distribution APIs. Distribution runs through bancassurance partnerships in Indonesia and Thailand, direct digital channels in South Korea and Australia, and proprietary agency networks in rural India and provincial China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Actuarial and data science capability gaps constrain product innovation velocity, forcing carriers to compete through channel control rather than pricing precision. The shortage of professionals capable of building predictive mortality models intensifies compensation costs and extends development timelines for algorithmic underwriting systems.
For Market Incumbents: Insulate proprietary agency networks in rural India and tier-3 Chinese cities against digital-native disintermediation by embedding telemedicine and wellness services into policy structures. Accelerate cloud-native core system replacement to compress product development cycles before modular competitors capture term life market share. Vertical integration into health services creates stickier customer relationships that resist price-based switching.
For New Entrants and Emerging Players: Vietnam's insurance density below 2% of GDP offers first-mover advantages for carriers establishing direct digital distribution before incumbent bancassurance partnerships solidify. Target Philippines microinsurance segments through mobile wallet integration and simplified underwriting protocols. Partner with regional reinsurers in Singapore to access capital efficiency without building full actuarial capabilities in-house.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among carriers with embedded health-to-wealth ecosystems that generate policy persistency through service integration rather than surrender charge mechanics. Long-term viability across the projection horizon favors acquisition targets with modular API architectures enabling rapid product recombination. Monitor China's NMPA regulatory sandbox approvals for AI-driven underwriting as an inflection signal for algorithmic risk selection adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Core Replacement | Compresses product development cycles from months to weeks at AIA Group and regional competitors. |
| Bancassurance Partnership Deepening | Penetrates mass-affluent segments in Indonesia and Thailand through Bank Mandiri and SCB networks. |
| Health-to-Wealth Ecosystem Convergence | Binds life policies with telemedicine at Ping An Insurance to reduce lapse rates through service stickiness. |
| Regulatory Sandbox Participation | Opens AI-driven underwriting pathways in China's tier-2 cities under NMPA pilot programs. |
| Cross-Border Data Architecture | Navigates ASEAN localization requirements to enable regional scale for Singapore-based reinsurers. |
Study Parameters
Two parallel data streams informed the analysis: structured conversations with chief actuaries, digital transformation officers, bancassurance partnership directors, and IRDAI compliance leads; and secondary validation against regulatory filings from China's CBIRC and India's IRDAI, alongside premium volume disclosures and reinsurance treaty data. Bottom-up policy issuance modeling triangulated with top-down macroeconomic projections across the analysis window.
Forecast inputs span product architecture, distribution channel economics, buyer risk profiles, and premium payment mechanics, with CAGRs derived from regression analysis against demographic transition rates and insurance density convergence patterns. Mortality assumption volatility and pandemic-era experience uncertainty factored into pricing precision sensitivity testing.
Practitioners should monitor regulatory digitization mandates and cross-border data localization rulings for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
France Life and Non-Life Insurance Market
Life and Non Life Insurance
US Burial Insurance Market
Life and Non Life Insurance
Poland Life and Non-Life Insurance Market
Life and Non Life Insurance
Finland Life and Non-Life Insurance Market
Life and Non Life Insurance
Ireland Life and Non-Life Insurance Market
Life and Non Life Insurance
Indonesia Life and Non-Life Insurance Market
Life and Non Life Insurance
Sweden Life and Non-Life Insurance Market
Life and Non Life Insurance
Global Life and Non-Life Insurance Market
Life and Non Life Insurance
China Life and Non-Life Insurance Market
Life and Non Life Insurance
Burial Insurance Market
Life and Non Life Insurance
Asia Pacific Life & Non-Life Insurance Market
Life and Non Life Insurance
Asia Life and Non-Life Insurance Market
Life and Non Life Insurance
Argentina Life and Non-Life Insurance Market
Life and Non Life Insurance
UAE Life and Annuity Insurance Market
Life and Non Life Insurance
Russia Life and Non-Life Insurance Market
Life and Non Life Insurance
Greece Life and Non-Life Insurance Market