
 Israel Life and Non-Life Insurance Market | 2026-2036
Israel Life and Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Life and Non-Life Insurance Market Foresight
Market Context
A capital-intensity divergence between legacy incumbents and digital challengers is rotating competitive dynamics across the Israeli insurance landscape. Harel Insurance Investments & Finance Services leverages its integrated asset-management arm to sustain pricing power in long-duration life products. Migdal Holdings anchors its position through an expansive agency network that controls distribution in secondary cities. Direct Insurance competes on stripped-down term-life and property offerings, while Shirbit Insurance specializes in online-first customer acquisition with minimal intermediary cost.
Technical Definition and Structural Segments
Israel life and non-life insurance encompasses risk-pooling contracts where insurers collect premiums to provide mortality, morbidity, property, and liability coverage under regulatory capital-reserve requirements. Products span whole life, term life, universal life, and endowment policies alongside health, property, casualty, and liability coverage, with pricing calibrated through mortality tables, catastrophe models, and investment-yield assumptions. The coverage-type dimension shows health and property insurance commanding the deepest premium pools due to mandatory participation incentives and mortgage-linked demand, while liability coverage is accelerating fastest as litigation frequency and cyber-risk exposure climb among Israeli corporates. Distribution channel structure reveals brokers still dominating commercial lines placement, though online direct sales are displacing agent-mediated household policies in younger demographics.
Regulatory Framework and Outlook
The Capital Markets Insurance and Savings Division of the Israel Ministry of Finance governs solvency ratios, reserve adequacy, and product-approval timelines, while the Bank of Israel monitors systemic risk concentrations among insurer investment portfolios. These frameworks shape demand by mandating minimum coverage levels for mortgage origination and restricting foreign-currency-denominated policy offerings. The Anti-Money Laundering Authority imposes customer-due-diligence standards that elevate compliance costs for cross-border premium flows. Stakeholders must monitor how proposed amendments to the Insurance Supervision Law affect captive capital requirements and whether regulator pressure to reduce equity-market exposure will redirect insurer allocations toward domestic fixed-income instruments.
Market Dynamics
Digital actuarial platforms are compressing pricing cycles across the Israeli insurance sector as carriers race to meet tightened solvency reporting requirements from the Capital Markets Insurance and Savings Division.
Growth Catalysts
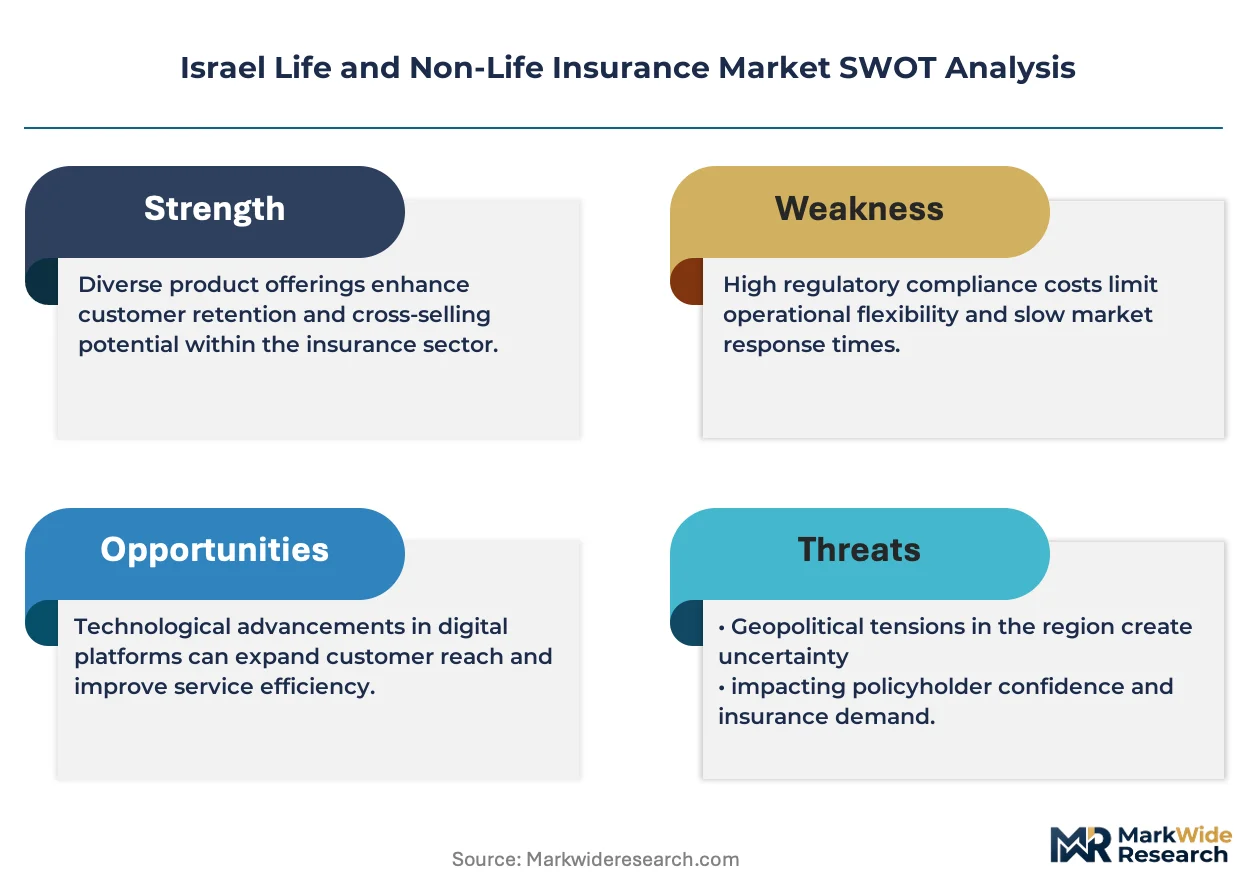
- Mandatory mortgage-linked coverage:The Ministry of Finance mandates minimum property insurance for mortgage origination, creating automatic premium volume in the central district around Gush Dan.
- Cyber liability expansion:Tel Aviv technology firms are scaling group health and cyber coverage as workforce risks evolve beyond traditional occupational hazards.
- Online direct channels:Digital-first acquisition models are stripping intermediary costs and capturing younger demographics previously served by agency networks.
Market Restraints
- Foreign-currency policy restrictions:The Ministry of Finance limits foreign-denominated offerings, constraining product diversification for internationally exposed corporates.
- Compliance cost elevation:The Anti-Money Laundering Authority imposes customer-due-diligence standards that inflate operational overhead for cross-border premium flows.
- Legacy system integration friction:Incumbent carriers face technical debt burdens when connecting digital platforms to decades-old policy administration systems.
Strategic Opportunities
- Peripheral region penetration:Secondary cities outside Gush Dan show underdeveloped corporate policy density relative to premium potential.
- Health-technology convergence:Wearable data streams and predictive analytics enable dynamic underwriting models for individualized life products.
- Captive capital restructuring:Proposed amendments to the Insurance Supervision Law may create regulatory tailwinds for alternative risk financing vehicles.
Industry Challenges
- Actuarial talent scarcity:The shift toward digital platforms demands data science capabilities that traditional Israeli actuarial training programs have not prioritized.
- Investment portfolio rebalancing:Bank of Israel pressure to reduce equity-market exposure forces rapid reallocation toward domestic fixed-income instruments with compressed yields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Life and Non-Life Insurance Market |
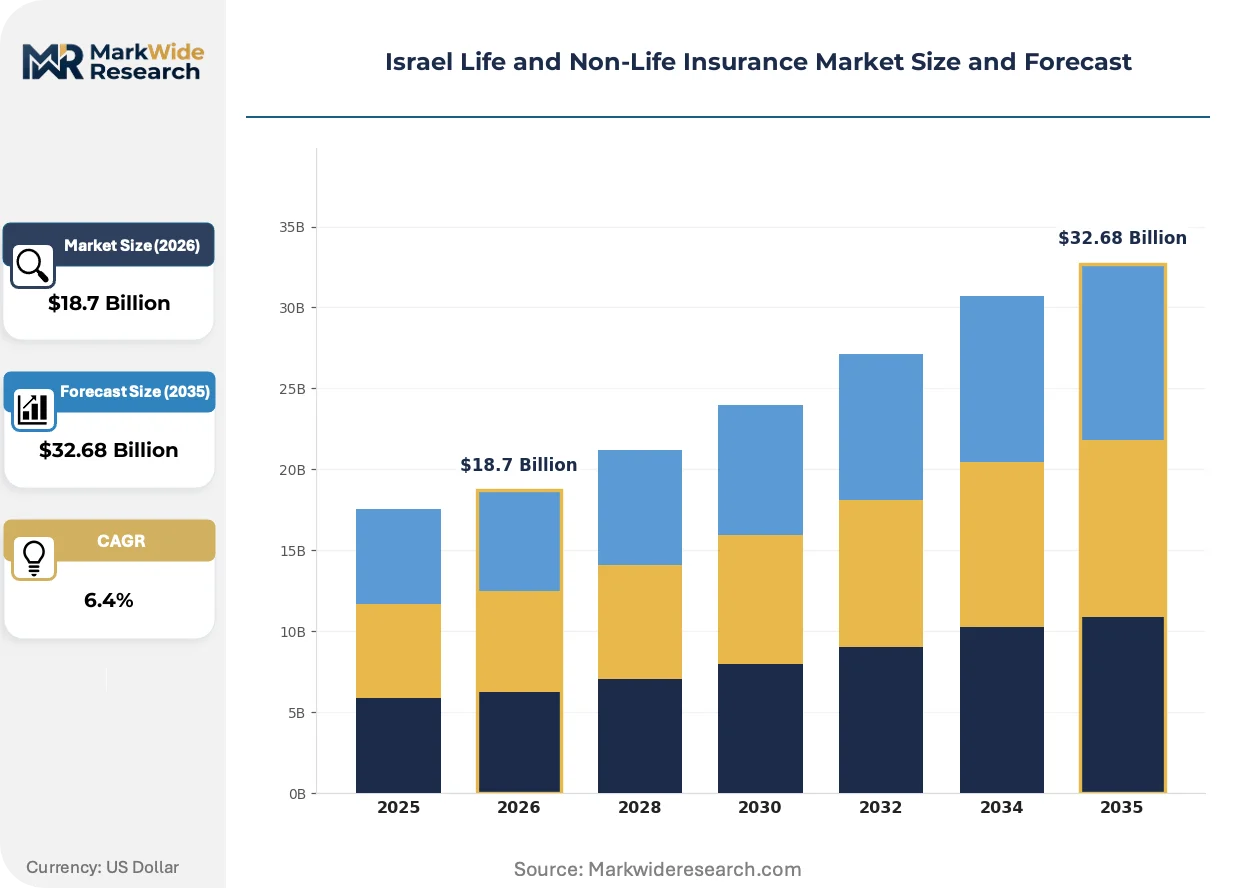
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Whole Life, Term Life, Universal Life, Endowment Distribution Channel: Direct Sales, Brokers, Online, Agents Customer Demographics: Families, Individuals, Corporates, Seniors Coverage Type: Health Insurance, Property Insurance, Casualty Insurance, Liability Insurance |
| Companies Covered | Clal Insurance Enterprises, Ayalon Insurance, Harel Insurance Investments & Finance Services, Direct Insurance, IDI Insurance, The Phoenix, Migdal Holdings, Shirbit Insurance, Menora Mivtachim, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Life and Non-Life Insurance Market Shifts & Advancements
Telematics-enabled underwriting and automated claims processing are compressing operational timelines across Israeli life and non-life lines, forcing incumbents to rebuild core systems or cede share to digital challengers.
Machine learning risk scoring is decomposing traditional mortality table dependencies by ingesting real-time behavioral data from wearable devices and electronic health records. Younger policyholders in Tel Aviv and Haifa are adopting these usage-adjusted products fastest. This technology is decomposing the uniform pricing pools that once subsidized cross-subsidization between risk tiers.
The Capital Markets Insurance and Savings Division's tightened solvency reporting requirements are compressing reserve calculation timelines and mandating granular asset-liability matching disclosures. Mid-sized carriers are accelerating cloud-based actuarial platform investments to meet quarterly submission deadlines. Health and long-duration life product lines face the steepest compliance burden given their duration mismatch sensitivity.
Channel disintermediation is fragmenting household policy acquisition patterns as direct online platforms peel younger demographics from agency-mediated distribution. Broker networks still dominate commercial lines placement in Jerusalem and Beersheba, but stripped-down term-life and property products migrate steadily toward self-service portals. This behavioral pivot concentrates profitability pressure on carriers with fixed agency cost bases.
Israel Life and Non-Life Insurance Market Segmentation
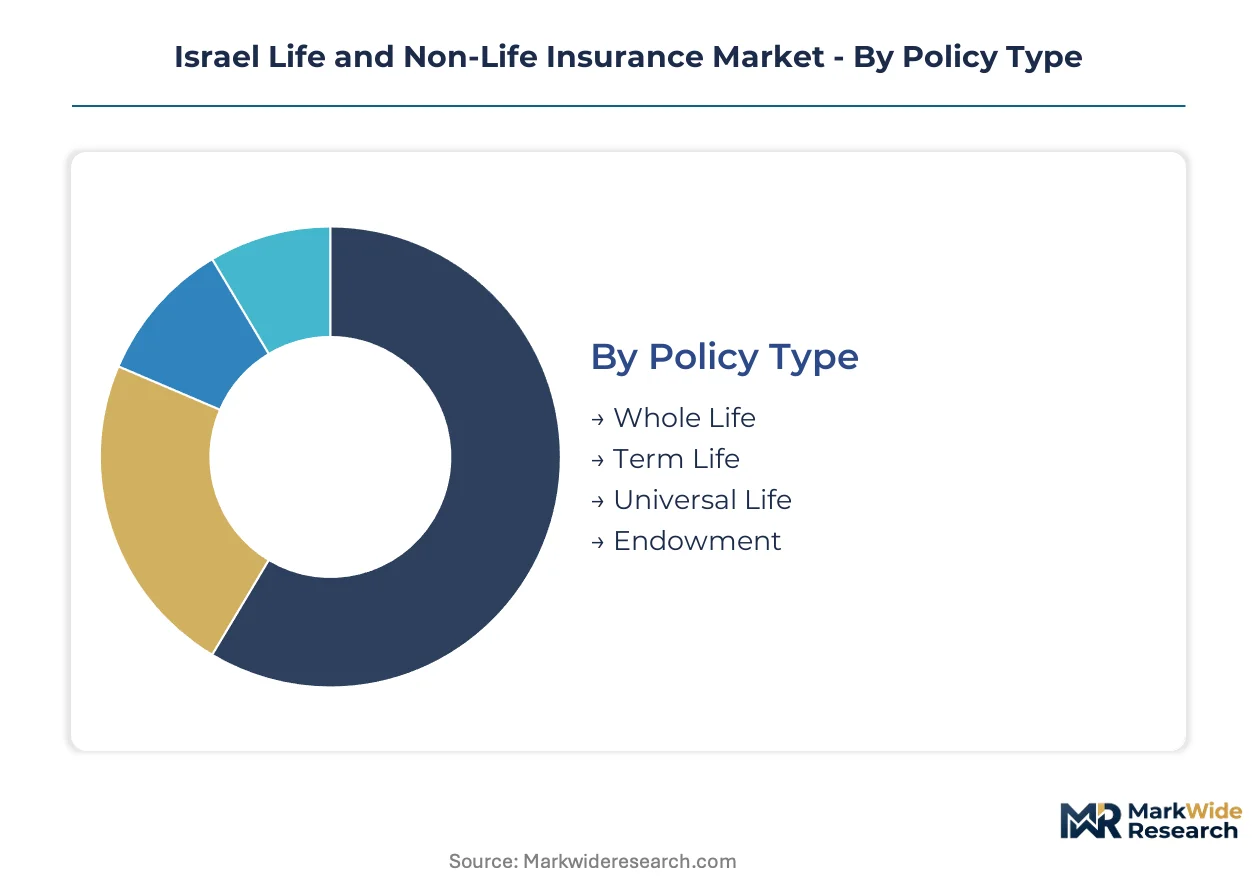
Israeli insurers calibrate product design and capital allocation through four intersecting segment dimensions. Policy type and coverage type determine reserve requirements under Capital Markets Insurance and Savings Division rules, while distribution channel and customer demographics shape acquisition economics in the Gush Dan concentration zone.
Policy Type:
Long-duration products flow through agency networks that dominate secondary cities, while stripped-down term offerings migrate toward direct digital channels in Tel Aviv and Haifa.
- Whole Life:Permanent coverage with cash value accumulation tied to insurer investment portfolios. Demand concentrates among families in Jerusalem and central district suburbs seeking estate planning instruments, constrained by Bank of Israel pressure on equity-heavy reserve backing.
- Term Life:Pure mortality protection with fixed premiums over defined periods. Younger demographics in Tel Aviv technology corridors adopt these through online direct platforms, stripping intermediary costs from the acquisition stack.
- Universal Life:Flexible premium and death benefit structures with transparent cost-of-insurance charges. Corporate policyholders use these for executive benefit arrangements, though foreign-currency denomination restrictions limit international holding company applications.
- Endowment:Savings-linked mortality contracts maturing at specified dates. Seniors in Haifa and peripheral regions favor these for predictable payout timelines, aligning with mandatory mortgage-linked coverage requirements.
Whole life dominates installed base. Term life is where expansion concentrates.
Distribution Channel:
Channel economics stratify sharply between fixed-cost agency infrastructure and variable-cost digital acquisition, with broker networks capturing commercial line complexity premiums.
- Direct Sales:Insurer-employed representatives targeting standardized product categories. Property and casualty policies in Gush Dan residential clusters flow through this channel, compressed by online price transparency.
- Brokers:Independent intermediaries placing complex commercial risks. Cyber liability and group health for Tel Aviv technology firms concentrate here, where coverage customization justifies placement fees.
- Online:Self-service portals with algorithmic underwriting engines. Term life and stripped-down property products gain share fastest among demographics under 40, though legacy system integration friction slows incumbent carrier deployment.
- Agents:Tied representatives with exclusive carrier relationships. Secondary cities outside the central district maintain this channel's relevance for whole life and endowment products requiring face-to-face trust formation.
Agents dominate installed base. Online is where expansion concentrates.
Customer Demographics:
Risk pooling mechanics and regulatory capital treatment vary substantially across demographic cohorts, driving product-specific pricing architectures.
- Families:Multi-life household units seeking bundled coverage solutions. Health and property insurance demand concentrates in Gush Dan mortgage origination corridors, where mandatory participation incentives create automatic premium volume.
- Individuals:Single-policy purchasers with portable coverage needs. Term life and individual health products attract this segment through digital channels, though Anti-Money Laundering Authority compliance costs elevate cross-border premium friction.
- Corporates:Employer-sponsored group risk arrangements. Cyber liability and group health scaling among Tel Aviv technology firms drives fastest expansion, as workforce risks evolve beyond traditional occupational hazard frameworks.
- Seniors:Policyholders over 60 with mortality table sensitivity. Endowment and whole life products align with estate liquidity planning in Jerusalem and Haifa, constrained by duration mismatch sensitivity under tightened solvency reporting.
Families dominate installed base. Corporates are where expansion concentrates.
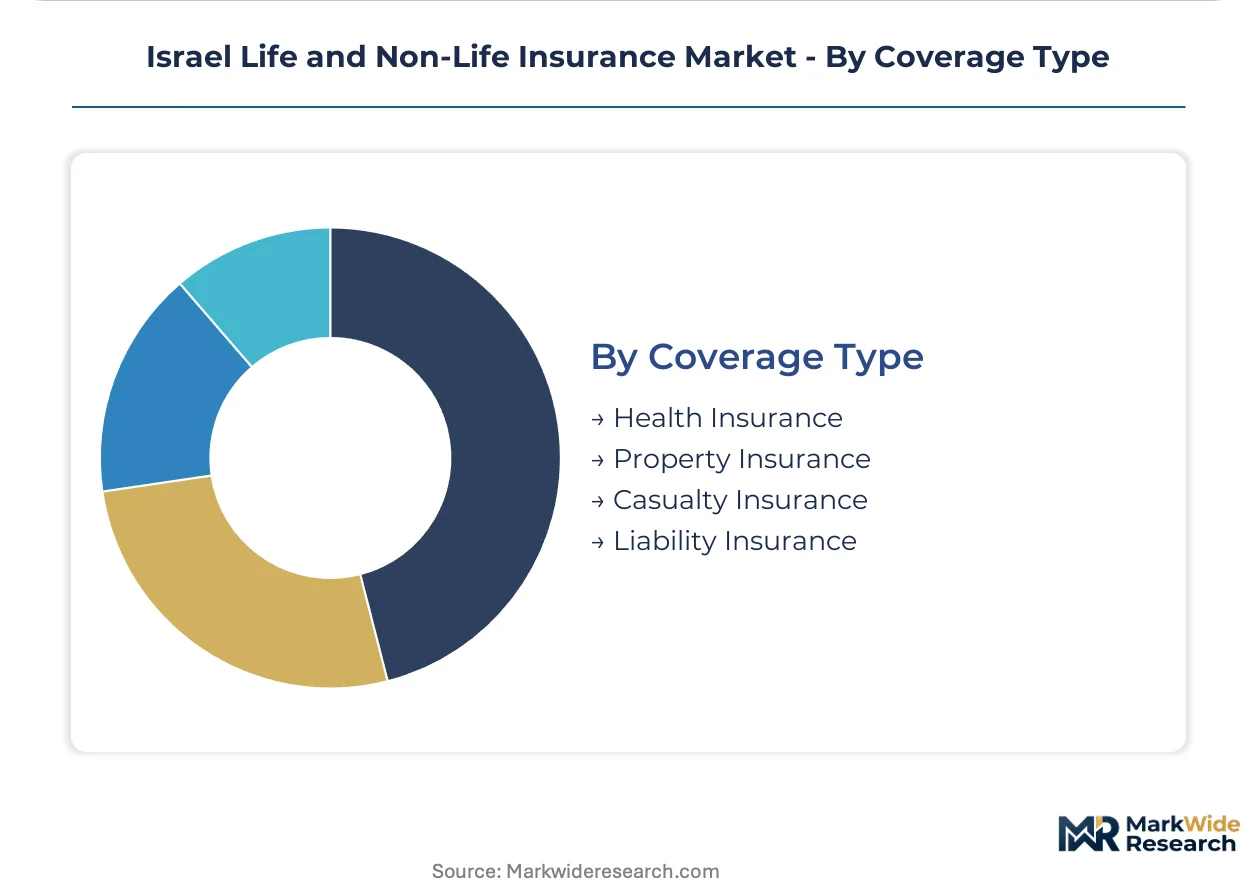
Coverage Type:
Reserve calculation complexity and regulatory scrutiny intensity differentiate coverage categories, with health and long-duration life lines facing steepest compliance burdens.
- Health Insurance:Morbidity risk pooling with medical expense reimbursement structures. Mandatory participation incentives and wearable data integration drive demand in Tel Aviv and central district corridors, where predictive analytics enable dynamic underwriting models.
- Property Insurance:Physical asset protection against damage and loss perils. Mortgage-linked origination requirements create automatic volume in Gush Dan, though catastrophe model calibration faces climate volatility uncertainty.
- Casualty Insurance:Accident and injury liability coverage for individuals and enterprises. Secondary cities show underdeveloped policy density relative to premium potential, presenting peripheral region penetration opportunities.
- Liability Insurance:Third-party obligation protection spanning professional and product domains. Cyber liability accelerates fastest among Israeli corporates as litigation frequency climbs, though foreign-currency policy restrictions constrain international exposure hedging.
Property insurance dominates installed base. Liability insurance is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Tel Aviv technology corridors show the least price sensitivity for cyber liability and group health coverage, while peripheral region households exhibit acute elasticity on stripped-down term-life and property products. This divergence concentrates premium volume in the central district around Gush Dan, where corporate policy density outpaces national averages by substantial margins.
Central District (Gush Dan)
Mandatory mortgage-linked property insurance and employer-sponsored group health arrangements drive automatic premium generation across Tel Aviv, Ramat Gan, and Petah Tikva technology corridors. The Capital Markets Insurance and Savings Division enforces solvency reporting requirements that compress reserve calculation timelines for carriers operating here. Cyber liability coverage accelerates fastest among venture-backed software firms clustered in Tel Aviv's Rothschild Boulevard ecosystem.
Jerusalem
Whole life and endowment products dominate household demand as families prioritize estate planning instruments with cash value accumulation features. The Ministry of Finance restricts foreign-currency-denominated policy offerings, constraining international exposure hedging for Jerusalem-based holding companies. Agency networks maintain distribution control across the city's religious and secular demographic segments, preserving face-to-face trust formation for long-duration contracts.
Haifa
Individual health and wearable-integrated underwriting models attract younger demographics in the Haifa Bay metropolitan area, where predictive analytics enable dynamic premium adjustments. The Anti-Money Laundering Authority imposes customer-due-diligence standards that elevate compliance costs for cross-border premium flows through Haifa's port-linked commercial corridors. Seniors favor endowment products for predictable payout timelines aligned with retirement liquidity planning.
Southern District (Beersheba)
Secondary city underpenetration creates expansion opportunities for direct online channels targeting term-life and stripped-down property coverage. The Ministry of Finance mandates minimum coverage levels for mortgage origination, yet broker networks still dominate commercial lines placement. Cyber liability growth lags Tel Aviv benchmarks as technology firm density remains comparatively thin.
Northern District (Nazareth Illit, Afula)
Casualty insurance shows underdeveloped policy density relative to population-scale premium potential, presenting peripheral region penetration targets for digital-first carriers. Agency-mediated distribution persists for whole life products requiring face-to-face consultation. The Bank of Israel monitors systemic risk concentrations among insurer investment portfolios backing policies written across this region.
Israel Life and Non-Life Insurance Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with Harel Insurance Investments & Finance Services and Migdal Holdings anchoring the upper stratum through captive asset-management capabilities and expansive agency infrastructure respectively. Direct Insurance and Shirbit Insurance occupy the challenger tier, competing on stripped-down digital acquisition models that strip intermediary costs from household policy stacks. The competitive dynamic rotates around two dominant moves: cloud-based actuarial platform deployment to meet tightened solvency reporting deadlines, and channel disintermediation investments to capture younger demographics migrating toward self-service portals.
Within the integrated leader tier, Harel Insurance Investments & Finance Services exemplifies the asset-management-anchored archetype, while Migdal Holdings represents distribution-scale defenders controlling secondary city placement. Direct Insurance occupies a position among digital challengers stripping acquisition costs from term-life and property offerings. Shirbit Insurance anchors the online-first specialist archetype with minimal intermediary infrastructure. These three firms collectively illustrate the capital-intensity divergence separating legacy incumbents from technology-enabled challengers across the Israeli insurance landscape.
| Leading Market Players |
|---|
| Clal Insurance Enterprises |
| Ayalon Insurance |
| Harel Insurance Investments & Finance Services |
| Direct Insurance |
| IDI Insurance |
| The Phoenix |
| Migdal Holdings |
| Shirbit Insurance |
| Menora Mivtachim |
| Others |
Supply & Pricing Matrix
Ninety-day reserve calculation cycles compress pricing power for mid-sized carriers unable to deploy cloud-based actuarial platforms, concentrating margin advantage among integrated leaders with captive asset-management arms. The Capital Markets Insurance and Savings Division's tightened solvency reporting requirements feed directly into pricing architecture, as carriers with faster data infrastructure capture younger demographics through dynamic premium adjustments while legacy systems force static rate cards.
Pricing Analysis
Policy renewal and cross-sell revenue streams drive lifetime value across Israeli life and non-life lines, with carriers calibrating acquisition discounts against expected duration. Three-tier pricing structure across premium, standard, and economy levels segments risk pools by underwriting depth and service bundling. Pricing pressure stems from digital challengers stripping intermediary costs from term-life and property stacks. Younger demographics in Tel Aviv technology corridors show least price sensitivity for cyber liability coverage, while peripheral region households exhibit acute elasticity on stripped-down household policies.
Supply Chain Analysis
Israel and the United States anchor actuarial software development and cloud infrastructure deployment for Israeli carriers, with India supplying back-office policy administration talent. Proprietary underwriting engines draw from mortality table databases, catastrophe modeling platforms, and wearable data streams. Single-source vulnerability concentrates in legacy policy administration systems where decades-old architectures resist API integration. Distribution runs through broker networks for commercial lines and self-service portals for standardized household products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Israeli insurance market tracks a cyclical recovery pattern as interest rate normalization restores investment yield assumptions that compressed long-duration product profitability through recent low-rate periods.
For Market Incumbents: Secure cloud-based actuarial platform deployment ahead of quarterly solvency reporting deadlines to defend pricing power against digital challengers. Consolidate agency network control in secondary cities where face-to-face trust formation still dominates whole life and endowment placement. The threat of channel disintermediation intensifies as Shirbit Insurance and Direct Insurance strip acquisition costs from younger demographics. For New Entrants and Emerging Players: Capital Markets Insurance and Savings Division certification fast-tracks for cyber liability products open white-space penetration among Tel Aviv technology firms scaling group coverage. Target peripheral region households in Beersheba and Nazareth Illit with stripped-down term-life and property products through self-service portals. Deploy usage-adjusted underwriting models integrating wearable data streams as the primary go-to-market differentiator. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated financial conglomerates seeking to divest non-core insurance operations amid capital reallocation pressures. Long-term viability over the coming decade hinges on digital infrastructure depth and agency network optionality rather than scale alone. Watch for amendments to the Insurance Supervision Law affecting captive capital requirements as the signal for alternative risk financing vehicle proliferation.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Actuarial Platform Deployment | Meets Capital Markets Insurance and Savings Division solvency reporting compression timelines. |
| Channel Disintermediation Investment | Captures younger demographics migrating from agency-mediated to self-service policy acquisition. |
| Cyber Liability Product Expansion | Addresses litigation frequency escalation among Tel Aviv technology firm corporates. |
| Wearable Data Integration | Enables dynamic underwriting models decomposing traditional mortality table dependencies. |
| Peripheral Region Agency Partnership | Penetrates underdeveloped corporate policy density in secondary cities outside Gush Dan. |
Research Methodology
Cross-validation between primary interviews with Israeli insurance executives and secondary analysis of Capital Markets Insurance and Savings Division regulatory filings anchors the qualitative findings. Stakeholder consultations spanned chief actuaries, digital transformation leads at tier-one carriers, broker network principals, and Bank of Israel supervisory staff. Secondary sources included Ministry of Finance solvency reports, insurer statutory financial statements, and Bank of Israel systemic risk assessments. Bottom-up policy volume estimates triangulated against top-down premium pool calculations.
Sensitivity analysis tested forecast outputs against interest rate trajectory variations and regulatory amendment scenarios across the projection horizon. Segmentation dimensions modeled include policy type, coverage category, distribution channel, and customer demographic cohort. CAGRs derived from historical premium growth patterns adjusted for structural shifts in digital channel penetration and mandatory coverage expansion. Investment yield assumptions and mortality improvement factors served as key forecast inputs.
Underlying assumptions cover stable regulatory capital treatment and gradual interest rate normalization, with deviation risk concentrated in accelerated solvency rule amendments or equity market dislocation forcing rapid portfolio rebalancing. Recalibration cycles align with material shifts in Capital Markets Insurance and Savings Division reporting requirements or Bank of Israel investment concentration limits.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Life Insurance Policy Administration System Market
Life and Non Life Insurance
Germany Life and Non-Life Insurance Market
Life and Non Life Insurance
Poland Life and Non-Life Insurance Market
Life and Non Life Insurance
Peru Life and Non-Life Insurance Market
Life and Non Life Insurance
Spain Life & Non-Life Insurance Market
Life and Non Life Insurance
South Korea Life & Non-Life Insurance Market
Life and Non Life Insurance
Denmark Life and Non-Life Insurance Market
Life and Non Life Insurance
UAE Life and Annuity Insurance Market
Life and Non Life Insurance
USA Life and Non-Life Insurance Market
Life and Non Life Insurance
Japan Life and Non-Life Insurance Market
Life and Non Life Insurance
Finland Life and Non-Life Insurance Market
Life and Non Life Insurance
North America Business Income Insurance Market
Life and Non Life Insurance
Sri Lanka Life and Non-Life Insurance Market
Life and Non Life Insurance
Canada Life and Non-Life Insurance Market
Life and Non Life Insurance
Iran Property and Casualty Insurance Market
Life and Non Life Insurance
Singapore Life and Non-Life Insurance Market