
 Austria Life and Non-Life Insurance Market | 2026-2036
Austria Life and Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Austria Life and Non-Life Insurance Market Outlook
EU Green Deal compliance is shifting capital requirements for Austrian underwriters. Vienna Insurance Group leverages its bancassurance network to sustain premium volume across Central European markets. UNIQA Insurance Group AG anchors its position through direct digital channels that reduce acquisition costs. Generali Versicherung AG differentiates via specialized property coverage for industrial manufacturing clients.
Austria Life and Non-Life Insurance encompasses risk transfer contracts issued by domestic carriers, governed by Solvency II capital adequacy ratios and local supervisory reporting standards, designed to indemnify policyholders against mortality, morbidity, property damage, and third-party liability exposures. Life Insurance and Health Insurance command the deepest margin pools due to long-duration premium streams and cross-selling potential into retirement products. Property Insurance and Liability Insurance face intensifying price competition as Online Platforms and Brokers disintermediate traditional agent networks.
The Financial Market Authority and Oesterreichische Nationalbank enforce Solvency II-derived capital buffers while EIOPA coordinates stress-testing protocols across EU member states. These frameworks elevate compliance costs but also consolidate market access around well-capitalized incumbents. Stakeholders must monitor how the EU AI Act's risk-classification rules reshape automated claims processing and pricing algorithms.
Market Dynamics
Solvency II capital adequacy ratios and the EU AI Act's risk-classification framework are compressing underwriting margins while forcing algorithmic redesign across Austrian carriers.
Growth Catalysts
- EU Green Deal capital reallocation:Compliance mandates redirect institutional investment into sustainable insurance-linked securities, expanding premium pools for climate-resilient coverage products.
- Small business liability expansion:Upper Austria's manufacturing SMEs are broadening group liability policies to cover cyber and environmental risks previously excluded from standard contracts.
- Telematics integration:Usage-based motor insurance models leverage real-time driving data to refine risk pricing and reduce adverse selection in personal auto lines.
Market Restraints
- Sovereign debt concentration:Austrian insurers hold substantial domestic bond portfolios, exposing capital reserves to interest rate volatility from Oesterreichische Nationalbank monetary policy shifts.
- Distribution cost inflation:Broker commissions and digital acquisition spending consume disproportionate shares of premium income relative to EU peer markets.
- Longevity risk miscalculation:Persistently low mortality improvement assumptions in legacy life portfolios create reserve adequacy gaps under EIOPA stress-testing protocols.
Strategic Opportunities
- Vienna corporate captive formation:Multinational headquarters in the capital are establishing self-insurance vehicles to retain risk and access reinsurance markets directly.
- Parametric agricultural coverage:Satellite-indexed drought and flood policies address coverage gaps for Styrian and Lower Austrian farming cooperatives underserved by traditional indemnity contracts.
- AI Act compliance services:Automated underwriting audits and algorithmic documentation tools create B2B revenue streams as carriers race to meet EU regulatory deadlines.
Industry Challenges
- Actuarial-technologist integration:Underwriting teams lack sufficient data science capacity to operationalize machine learning models at production scale.
- Legacy system interoperability:Policy administration platforms from the 1990s resist API connectivity with modern distribution portals and claims automation tools.
- EIOPA reporting latency:Quarterly Solvency II submissions consume analytical resources that could otherwise deploy toward product development or pricing refinement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Austria Life and Non-Life Insurance Market |
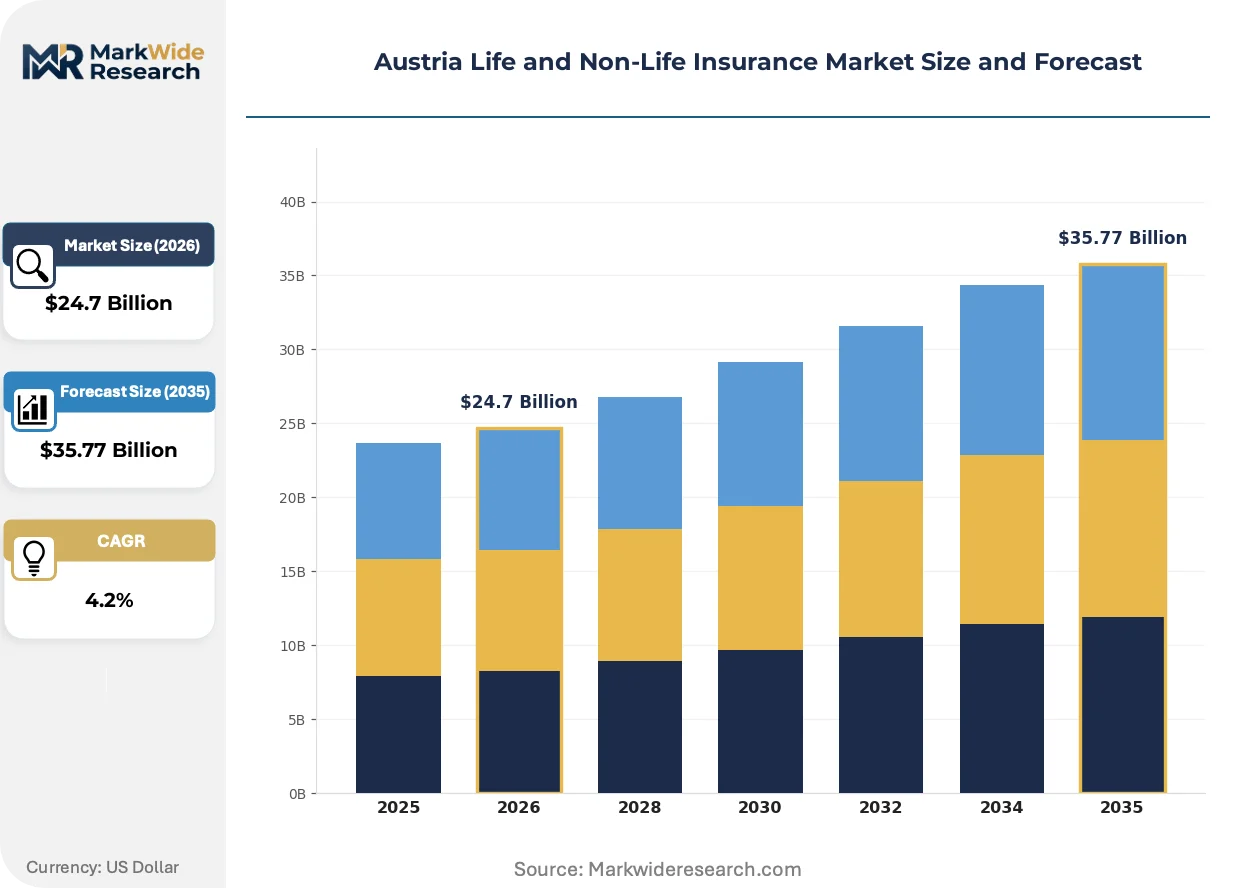
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $35.77 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
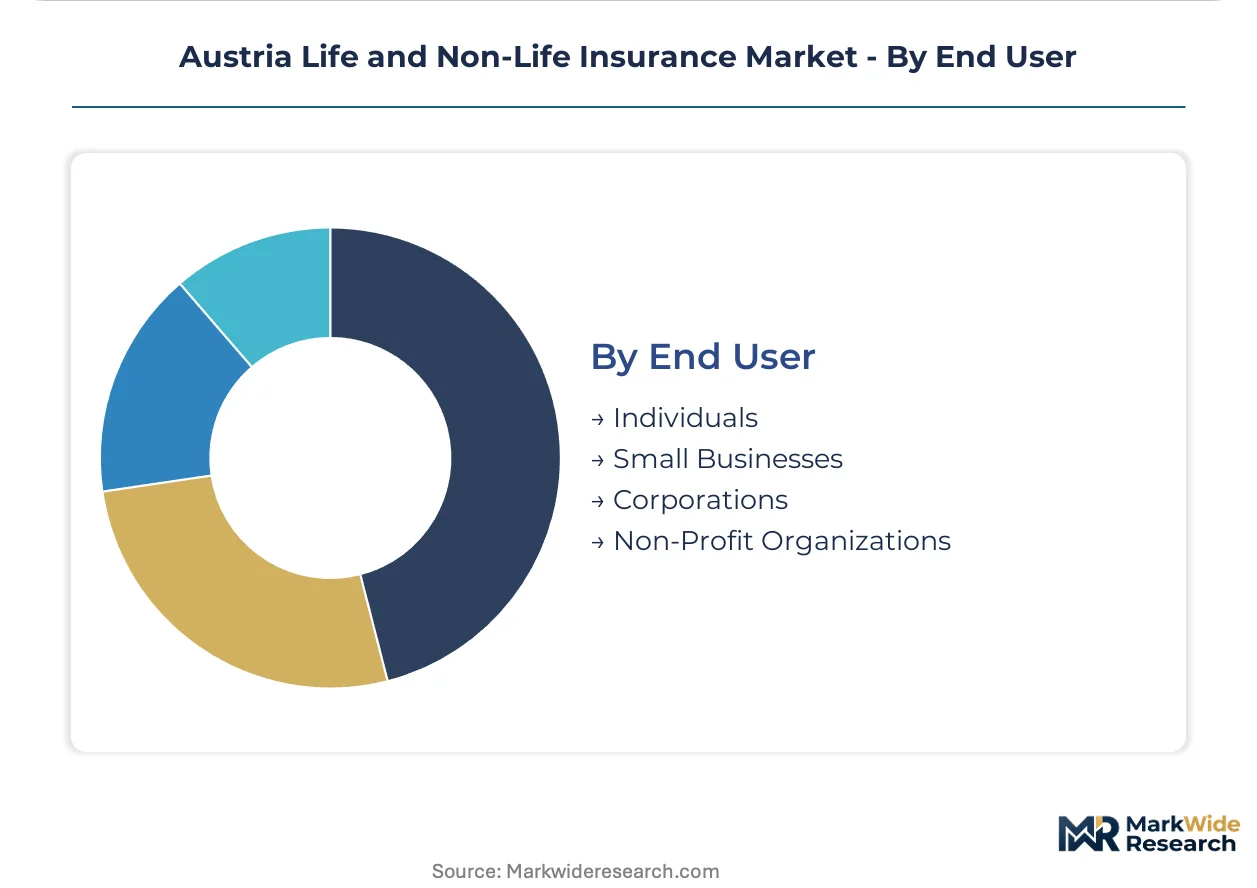
| Segmentation | Product Type: Life Insurance, Health Insurance, Property Insurance, Liability Insurance Distribution Channel: Brokers, Agents, Direct Sales, Online Platforms Coverage Type: Individual Plans, Group Plans, Comprehensive Coverage, Basic Coverage End User: Individuals, Small Businesses, Corporations, Non-Profit Organizations |
| Companies Covered | Vienna Insurance Group, UNIQA Insurance Group AG, Generali Versicherung AG, Allianz Österreich, Grazer Wechselseitige Versicherung, Ergo Versicherung AG, Merkur Versicherung AG, Helvetia Versicherungen AG, Oberösterreichische Versicherung AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Austria Life and Non-Life Insurance Market Strategic Shifts
Algorithmic decision-making and channel disintermediation are restructuring how Austrian carriers price risk, distribute products, and engage policyholders across life and non-life segments.
Embedded insurance APIs are electrifying the point-of-sale coverage experience by integrating policy activation directly into e-commerce checkout flows and banking applications. Retailers and fintech platforms in Vienna are adopting these interfaces to offer instant product warranty and travel protection without redirecting customers to insurer websites. This convergence is compressing traditional agent-mediated distribution economics and redirecting commission pools toward technology infrastructure providers.
The EU AI Act's risk-tiered governance framework is mandating human oversight for high-stakes automated underwriting decisions affecting life insurance eligibility and premium setting. Austrian carriers must maintain audit trails demonstrating algorithmic explainability and non-discrimination across protected characteristics. Life and health lines face the steepest compliance burdens as they rework pricing engines to satisfy EIOPA supervisory expectations by 2026 implementation deadlines.
Direct digital purchasing is displacing traditional broker relationships among younger demographic cohorts seeking transparent pricing and instantaneous policy documentation. Online aggregators and insurer-owned direct channels now capture majority share of personal motor and household policy origination in urban centers. This behavioral pivot concentrates in Vienna and Salzburg, where smartphone penetration and digital literacy rates exceed rural provincial averages by substantial margins.
Austria Life and Non-Life Insurance Market Segmentation

Segmentation reveals how capital allocation, regulatory burdens, and distribution economics vary across Austrian insurance lines. Life and health products demand long-duration asset-liability matching, while property and liability lines turn on underwriting cycle timing and broker commission structures.
Product Type:
Capital intensity peaks in segments requiring multi-decade reserve backing and sophisticated investment portfolios to match duration risk.
- Life Insurance:Long-duration contracts necessitate substantial sovereign bond portfolios and Solvency II-compliant matching adjustment structures. Vienna Insurance Group and UNIQA deploy dedicated ALM teams to manage interest rate risk on guaranteed products sold to Upper Austrian savers.
- Health Insurance:Supplementary medical coverage combines recurring premium streams with inflation-linked benefit escalation. Demand clusters in Vienna's corporate employee benefit schemes where employers seek to top up statutory social insurance gaps.
- Property Insurance:Short-tail claims resolution and catastrophe reinsurance dependence define capital requirements. Styrian industrial manufacturing clients drive specialized coverage for flood and hail exposure.
- Liability Insurance:Long-tail asbestos and environmental reserves demand conservative discount rate assumptions. Upper Austrian SME group policies increasingly embed cyber and D&O extensions.
Most installed capacity flows through Life Insurance. Expansion is steepest in Health Insurance.
Distribution Channel:
Customer acquisition cost structures diverge sharply between human-mediated and digital-native pathways, reshaping carrier economics.
- Brokers:Independent intermediaries command 15-25% commission loads on commercial lines but deliver sophisticated risk advisory to manufacturing clients. Salzburg and Linz broker networks retain stronghold in mid-market corporate placement.
- Agents:Tied representatives generate predictable personal lines volume through embedded banking relationships. Vienna Insurance Group's bancassurance network leverages this channel across Oesterreichische Nationalbank-supervised institutions.
- Direct Sales:Insurer-employed advisors target affluent individual segments with complex wealth-transfer products. High fixed cost base limits this model to carriers with sufficient scale.
- Online Platforms:Aggregator websites and insurer direct portals capture urban motor and household policy origination. Smartphone penetration gaps disadvantage this channel in rural Vorarlberg and Carinthia.
Broker-mediated placement dominates commercial lines premium volume. Online Platforms are climbing the fastest among personal lines origination.
Coverage Type:
Pricing sophistication and claims adjudication complexity scale with benefit comprehensiveness and policyholder aggregation.
- Individual Plans:Underwritten at the single-life level with full medical disclosure requirements. Vienna's professional services employees purchase high-limit disability income riders.
- Group Plans:Experience-rated pooling spreads risk across employer cohorts, reducing per-capita acquisition costs. Manufacturing SMEs in Upper Austria expand group liability to cover emerging cyber exposures.
- Comprehensive Coverage:All-risk property forms and whole-life packages bundle multiple perils with limited sub-limits. Capital charges under Solvency II standard formula exceed modular alternatives.
- Basic Coverage:Named-peril fire and term life products compete on price through stripped-down benefit structures. Online Platforms dominate distribution given minimal advisory requirements.
Group Plans capture the deepest corporate premium pools. Individual Plans are gaining share fastest among digitally-engaged demographic cohorts.
End User:
Risk sophistication and purchasing process complexity determine service intensity and margin potential across buyer categories.
- Individuals:Mass-market policyholders purchase standardized products through price-comparison portals. Vienna and Salzburg urban centers show highest direct digital adoption rates.
- Small Businesses:Upper Austrian manufacturing SMEs require tailored property and liability bundles with industry-specific endorsements. Broker relationships remain essential for coverage adequacy review.
- Corporations:Multinational headquarters in Vienna establish captive self-insurance vehicles to access reinsurance markets directly. EIOPA supervisory reporting applies to these specialized structures.
- Non-Profit Organizations:Social service providers and cultural institutions purchase limited coverage with tight budget constraints. Premium volume concentrates in Vienna's museum and healthcare charity sectors.
Corporations generate the highest per-account premium concentration. Small Businesses are expanding coverage breadth fastest as cyber and environmental risks penetrate standard policy forms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Actuarial talent pools and supervisory expertise cluster in Vienna's financial district, anchoring Austria's insurance infrastructure. Upper Austria's manufacturing density generates concentrated commercial liability demand. Styrian agricultural cooperatives drive parametric coverage innovation.
Vienna
Corporate headquarters and reinsurance treaty negotiations concentrate premium flows in the capital. The Financial Market Authority enforces Solvency II capital buffers through quarterly reporting protocols. Multinational captives in Vienna's 1st and 3rd districts access international reinsurance markets directly.
Upper Austria
Manufacturing SMEs in Linz and Wels expand group liability policies to embed cyber and environmental endorsements. Oesterreichische Nationalbank interest rate shifts expose local bond-heavy investment portfolios to duration risk. Industrial property coverage for flood-exposed facilities commands specialized underwriting attention.
Styria
Agricultural cooperatives seek satellite-indexed drought policies as traditional indemnity contracts leave coverage gaps. EU Green Deal compliance redirects institutional capital toward climate-resilient insurance-linked securities. Graz-based brokers intermediate parametric solutions for farming clients in the Enns and Mur valleys.
Salzburg
Tourism-dependent hospitality businesses drive seasonal property and business interruption coverage cycles. Broker networks retain stronghold in mid-market commercial placement despite digital channel encroachment. The city's affluent demographic sustains demand for high-limit individual disability income products.
Austria Life and Non-Life Insurance Market Competitive Environment
The competitive structure tilts toward bancassurance-integrated conglomerates with captive distribution networks. Three carrier archetypes dominate: Vienna-headquartered multinationals leveraging Central European scale, mutual insurers preserving regional policyholder loyalty, and direct digital specialists compressing acquisition costs through proprietary platforms. Consolidation pressure manifests in strategic partnerships between legacy carriers and insurtech infrastructure providers, plus selective portfolio diversification into parametric and embedded coverage lines.
Within the bancassurance-integrated tier, Vienna Insurance Group exemplifies the network economics of tied banking relationships. UNIQA Insurance Group AG occupies a position as the direct digital archetype, reducing distribution friction through proprietary online channels. Generali Versicherung AG anchors the specialized commercial segment, representing carriers that differentiate through industrial manufacturing expertise rather than scale or channel efficiency.
| Leading Market Players |
|---|
| Vienna Insurance Group |
| UNIQA Insurance Group AG |
| Generali Versicherung AG |
| Allianz Österreich |
| Grazer Wechselseitige Versicherung |
| Ergo Versicherung AG |
| Merkur Versicherung AG |
| Helvetia Versicherungen AG |
| Oberösterreichische Versicherung AG |
| Others |
Value Chain & Pricing Dynamics
Commission loads for broker-mediated commercial lines flow downstream from Vienna's bancassurance networks through Salzburg and Linz intermediaries, stratifying into premium advisory tiers for manufacturing SMEs and stripped-down digital offerings for standardized personal lines.
Pricing Analysis
Bundled advisory services with embedded risk assessment command 15-25% commission structures for Upper Austrian manufacturing clients, while unbundled direct digital channels compress acquisition costs below 10% for urban motor and household policies. Price differentiation rests on distribution complexity and policy customization depth. Cost compression in personal auto lines is intensifying because telematics-enabled usage-based models erode traditional risk-pooling economics. Small businesses in industrial zones show lowest price sensitivity due to regulatory-driven coverage mandates, whereas individual mass-market buyers in Vienna and Salzburg comparison-shop aggressively across aggregator platforms.
Supply Chain Analysis
Direct-to-corporate channels handle captive formation demand from Vienna-headquartered multinationals, while broker-mediated pathways serve mid-market commercial placement across provincial manufacturing clusters. Risk capital concentrates in Germany, Switzerland, and domestic Austrian reinsurance pools for long-tail liability exposures. Raw material dependencies include sovereign bond portfolios for duration-matched life reserves, satellite data feeds for parametric agricultural indices, and cloud infrastructure for algorithmic underwriting platforms. Single-source vulnerability sits with legacy policy administration systems from the 1990s that resist API connectivity with modern distribution portals. Distribution runs through Vienna Insurance Group's bancassurance network, UNIQA's proprietary digital platform, and independent broker channels in Linz and Graz.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Austria's insurance market functions as a geographic-arbitrage play between Vienna's regulatory-supervised corporate segment and Upper Austria's underserved SME parametric coverage gaps, exploiting Solvency II compliance cost differentials across capital intensity tiers.
For Market Incumbents: Extend bancassurance network lock-in through exclusive product bundling with Oesterreichische Nationalbank-supervised institutions, and deepen captive reinsurance capacity for Vienna-headquartered multinational self-insurance vehicles. Direct digital specialists threaten personal lines margin pools through telematics-enabled price transparency. Channel control represents the critical defensive lever against disintermediation. For New Entrants and Emerging Players: Broker networks in Styria and Lower Austria present the most penetrable white-space target for satellite-indexed agricultural parametric products underserved by traditional indemnity contracts. Graz-based farming cooperatives lack adequate drought and flood coverage. A go-to-market angle through Graz-based intermediaries with embedded climate data partnerships unlocks this segment. For Investors and Strategic Acquirers: Consolidation pressure builds where legacy carriers face EIOPA reporting burdens and AI Act compliance deadlines that strain analytical resource allocation. Long-term viability over the coming decade favors carriers with scalable direct digital infrastructure and Solvency II-compliant matching adjustment capabilities. Target acquisition archetypes include regional mutuals with captive policyholder bases but deficient technology stacks. The signal to watch is regulatory-driven capital reallocation toward climate-resilient insurance-linked securities.| Strategic Initiative | Industry Significance |
|---|---|
| AI Act Compliance Infrastructure | Automated underwriting audit tools capture B2B revenue from carriers facing EIOPA deadlines. |
| Parametric Product Development | Satellite-indexed coverage addresses Styrian farming cooperative gaps left by traditional contracts. |
| Bancassurance Network Expansion | Tied banking relationships sustain premium volume across Oesterreichische Nationalbank-supervised channels. |
| Captive Reinsurance Capacity Buildout | Vienna-headquartered multinationals access direct reinsurance markets through self-insurance vehicles. |
| Legacy System API Integration | Policy administration modernization enables connectivity with distribution portals and claims automation. |
Study Parameters
Multiple input streams — actuarial executives at Vienna Insurance Group and UNIQA, broker principals in Linz and Graz, Financial Market Authority supervisory officials, and reinsurance treaty underwriters — were reconciled against Solvency II regulatory filings, EIOPA stress-testing disclosures, Oesterreichische Nationalbank monetary policy reports, and trade association premium statistics. Bottom-up policy-level data triangulated against top-down carrier balance sheet analysis.
Historical premium trends cross-referenced against panel input from distribution channel heads informed the analytical framework across the analysis window. Segmentation dimensions modeled include product type, distribution channel, coverage comprehensiveness, and end-user sophistication tier. CAGRs derived from asset-liability growth trajectories and regulatory capital requirement projections. Forecast inputs incorporated EU AI Act implementation timelines and EU Green Deal capital reallocation patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Oesterreichische Nationalbank interest rate volatility and EIOPA mortality assumption revisions. The analysis reflects documented assumptions regarding regulatory implementation schedules and technological adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Malaysia Life Insurance Market
Life and Non Life Insurance
UAE Life & Non-Life Insurance Market
Life and Non Life Insurance
Japan Life and Non-Life Insurance Market
Life and Non Life Insurance
Asia-Pacific Life and Annuity Insurance Market
Life and Non Life Insurance
Burial Insurance Market
Life and Non Life Insurance
Canada Life and Non-Life Insurance Market
Life and Non Life Insurance
Spain Life & Non-Life Insurance Market
Life and Non Life Insurance
Denmark Life and Non-Life Insurance Market
Life and Non Life Insurance
North America Business Income Insurance Market
Life and Non Life Insurance
Germany Life and Non-Life Insurance Market
Life and Non Life Insurance
Argentina Life and Non-Life Insurance Market
Life and Non Life Insurance
Uruguay Life and Non-Life Insurance Market
Life and Non Life Insurance
Norway Life and Non-Life Insurance Market
Life and Non Life Insurance
Life Insurance Policy Administration System Market
Life and Non Life Insurance
Group Life Insurance Market
Life and Non Life Insurance
Peru Life and Non-Life Insurance Market