
 Yarrow Market | 2026-2036
Yarrow Market Size, Share, and Industry Trends Forecast 2026-2036
Yarrow Market Analytics
Balkan wild-crafter cooperatives is repositioning toward certified organic harvesting to secure premium export channels. Amphora Aromatics Ltd leverages backward integration into distillery operations across Bulgaria and Albania to lock in raw material quality. Bristol Botanicals Ltd anchors its competitive stance through exhaustive phytochemical documentation that satisfies pharmaceutical buyer audits. Neal's Yard Remedies differentiates via retail channel control, operating dedicated storefronts that bypass conventional wholesale markups.
Yarrow (Achillea millefolium) denotes a perennial herb whose flowering tops yield 0.2–0.5% essential oil rich in chamazulene, proazulenes, and sesquiterpene lactones, with industrial harvests timed to full bloom for maximal active compound concentration. Dried herb segments dominate volume throughput due to lower processing overhead and broader formulation compatibility across tea and capsule applications. Essential oil commands the steepest margin pool, constrained by extraction yield limits and organic certification premiums. Tincture applications in herbal remedies are gaining fastest, propelled by home-use convenience and practitioner channel expansion.
The EU Herbal Medicines Directive and EMA quality guidelines enforce batch-to-batch consistency for yarrow-containing products, elevating testing costs but filtering low-grade suppliers from regulated channels. FDA dietary supplement cGMP rules and USDA organic certification create parallel compliance tracks for US-bound shipments, with dual-certified material capturing price premiums. Stakeholders must monitor evolving monograph standards and pollinator-protection regulations that could restrict wild-harvest volumes across key sourcing territories.
Market Dynamics
The EU Herbal Medicines Directive is compressing supplier margins through mandatory batch-to-batch consistency testing while simultaneously filtering low-grade competitors from regulated channels.
Growth Catalysts
- Phytotherapy reimbursement:Germany's statutory health insurance framework covers prescribed herbal remedies, creating predictable demand for pharmaceutical-grade yarrow extracts.
- EMA quality guidelines:Elevated documentation standards reward suppliers with exhaustive phytochemical profiling, tilting procurement toward audited botanical houses.
- Home-use convenience:Practitioner channel expansion for tincture formats is pulling volume from traditional tea preparations into standardized dosing applications.
Market Restraints
- Wild-harvest volume limits:Pollinator-protection regulations across Bulgarian and Albanian sourcing territories restrict seasonal collection quotas.
- Extraction yield ceilings:Essential oil recovery caps at 0.2–0.5% of flowering top mass, constraining margin expansion regardless of scale.
- Dual certification costs:USDA organic and EU organic equivalence requirements impose parallel audit tracks for US-bound shipments.
Strategic Opportunities
- Certified organic wild-crafting:Balkan cooperatives repositioning toward premium export channels can capture price multiples over conventional material.
- Retail channel control:Dedicated storefront models bypass wholesale markups and build direct consumer relationships in urban wellness markets.
- Practitioner formulary inclusion:Tincture applications are penetrating clinical herbalist protocols previously dominated by dried herb preparations.
Industry Challenges
- Phytochemical standardization expertise:Scarcity of analytical chemists capable of chamazulene quantification and sesquiterpene lactone profiling bottlenecks quality documentation.
- Distillery equipment retrofit cycles:Steam distillation infrastructure requires capital replacement to meet organic certification segregation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yarrow Market |
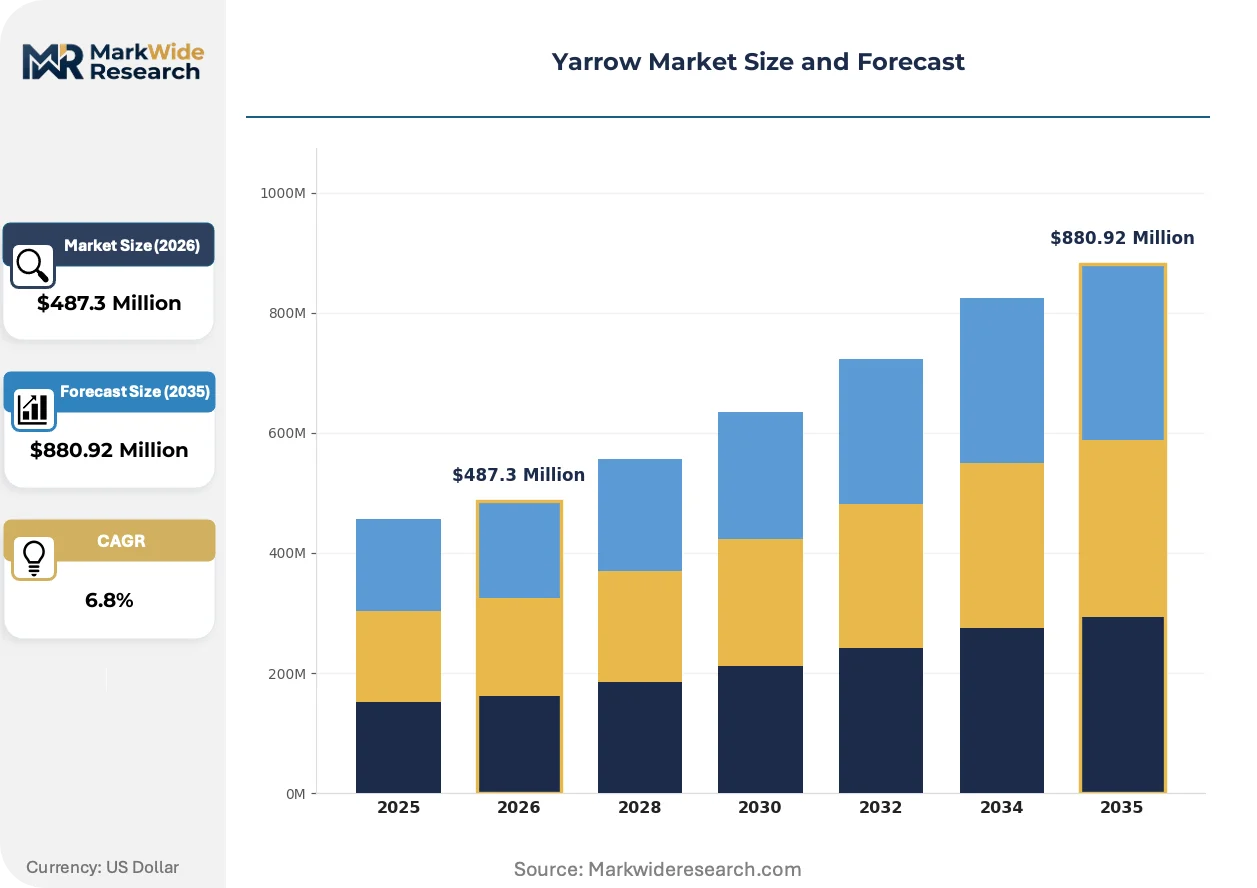
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oil, Dried Herb, Tincture, Powder Application: Pharmaceuticals, Cosmetics, Dietary Supplements, Herbal Remedies End User: Healthcare Providers, Consumers, Cosmetic Manufacturers, Food Industry Distribution Channel: Online Stores, Health Food Stores, Pharmacies, Wholesale |
| Companies Covered | Amphora Aromatics Ltd, Bristol Botanicals Ltd, Carruba Inc, Mother Bay Spice Company, Neal’s Yard Remedies, NHR Organic Oils, Organic Infusions Inc, Penta Manufacturing, Starwest Botanicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yarrow Market Evolving Landscape
Supercritical CO2 extraction is absorbing capital and technical attention as formulators seek higher chamazulene retention than conventional steam distillation permits.
Supercritical CO2 extraction systems operate at lower thermal thresholds than steam distillation, preserving heat-sensitive proazulenes that degrade in conventional processing. Pharmaceutical formulators in Germany and Switzerland are specifying CO2-derived extracts for wound-healing applications. This technology is absorbing market share from traditional distillery methods in premium therapeutic segments.
The EU Green Deal's pollinator protection mandates are tightening seasonal harvest windows across Bulgarian and Romanian wild-crafting territories. Industrial buyers must now document collection GPS coordinates and flowering-stage verification to satisfy EFSA traceability requirements. Suppliers with backward-integrated harvesting operations are absorbing compliance costs more efficiently than fragmented wild-crafter networks.
Home-practitioner channels are displacing retail pharmacy distribution for tincture-format yarrow products. German phytotherapy clinics now direct patients to direct-to-consumer portals rather than conventional Apotheke fulfillment. This channel rotation concentrates in metropolitan regions where telemedicine herbal consultations have normalized post-pandemic.
Yarrow Market Segmentation
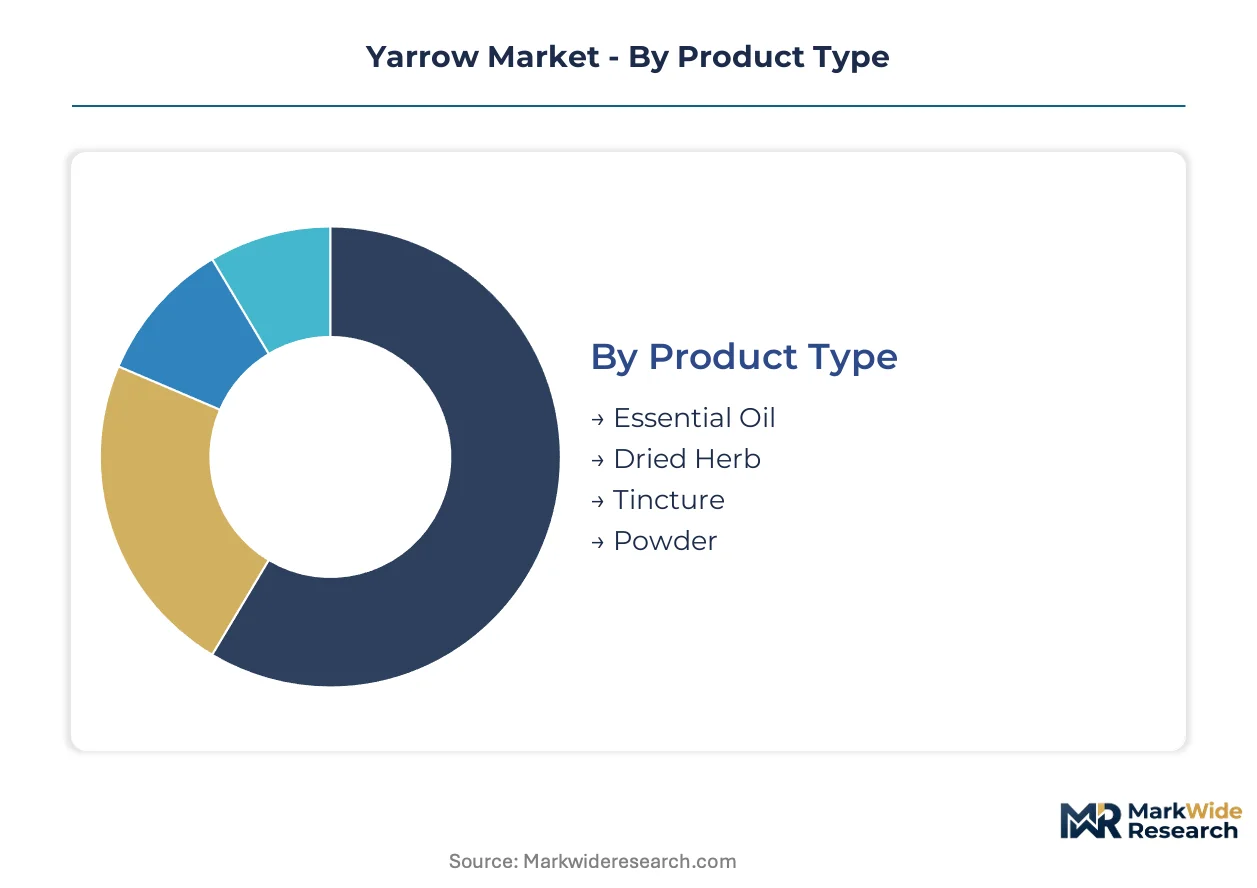
Yarrow's commercial structure splits sharply between high-volume commodity grades and certified premium extracts. Pharmaceutical buyers and cosmetic formulators drive divergent specification requirements across each segment boundary.
Product Type:
Dried herb dominates volume throughput while essential oil captures the steepest margin premium, reflecting extraction economics and certification tiers.
- Essential Oil:Steam-distilled flowering tops yield 0.2–0.5% oil rich in chamazulene and proazulenes. German pharmaceutical formulators specify CO2-extracted variants for wound-healing applications where heat-sensitive compound retention matters.
- Dried Herb:Lower processing overhead and broader formulation compatibility support tea and capsule manufacturing at scale. Bulgarian wild-crafter cooperatives supply bulk volumes under EU organic equivalence protocols.
- Tincture:Standardized dosing convenience accelerates practitioner channel penetration. Home-use formats are displacing traditional tea preparations in metropolitan wellness markets.
- Powder:Milled aerial parts serve encapsulation and functional food integration. Grinding operations concentrate in Albania and Romania where distillery co-location reduces handling costs.
Today's leader: Dried Herb. Tomorrow's challenger: Tincture.
Application:
Pharmaceutical-grade specifications command the tightest quality documentation while cosmetic applications absorb organic certification premiums most readily.
- Pharmaceuticals:EMA quality guidelines enforce batch-to-batch consistency for anti-inflammatory and wound-healing formulations. Exhaustive phytochemical profiling satisfies pharmaceutical buyer audits in Germany and Switzerland.
- Cosmetics:Chamazulene's blue coloration and skin-soothing properties drive demand in premium skincare. Neal's Yard Remedies and similar houses specify certified organic material for dedicated retail channels.
- Dietary Supplements:FDA cGMP rules and USDA organic certification create parallel compliance tracks for US-bound shipments. Capsule and tablet manufacturers favor powdered herb for blending efficiency.
- Herbal Remedies:Traditional medicine integration in Germany supports sustained offtake through phytotherapy reimbursement. Practitioner protocols increasingly specify tincture over dried herb for dosing precision.
Pharmaceuticals anchor current procurement volumes. Herbal Remedies are climbing the fastest as telemedicine consultations normalize post-pandemic.
End User:
Healthcare provider procurement tilts toward standardized extracts while consumer direct channels reward brand-controlled retail positioning.
- Healthcare Providers:German phytotherapy clinics direct patients to specific extract grades with documented sesquiterpene lactone content. Reimbursement eligibility requires EMA-compliant documentation.
- Consumers:Dedicated storefront models bypass wholesale markups in urban wellness markets. Direct-to-consumer portals concentrate in metropolitan regions with established herbal consultation networks.
- Cosmetic Manufacturers:Formulators specify organic-certified essential oil for premium positioning. Amphora Aromatics Ltd's backward-integrated distillery operations lock in raw material quality for this segment.
- Food Industry:Functional beverage and fortified food applications absorb lower-grade powdered material. Flavor stability requirements favor milder extraction variants.
Healthcare Providers currently dominate pharmaceutical-grade procurement. Consumers represent the steepest expansion trajectory as channel control strategies mature.
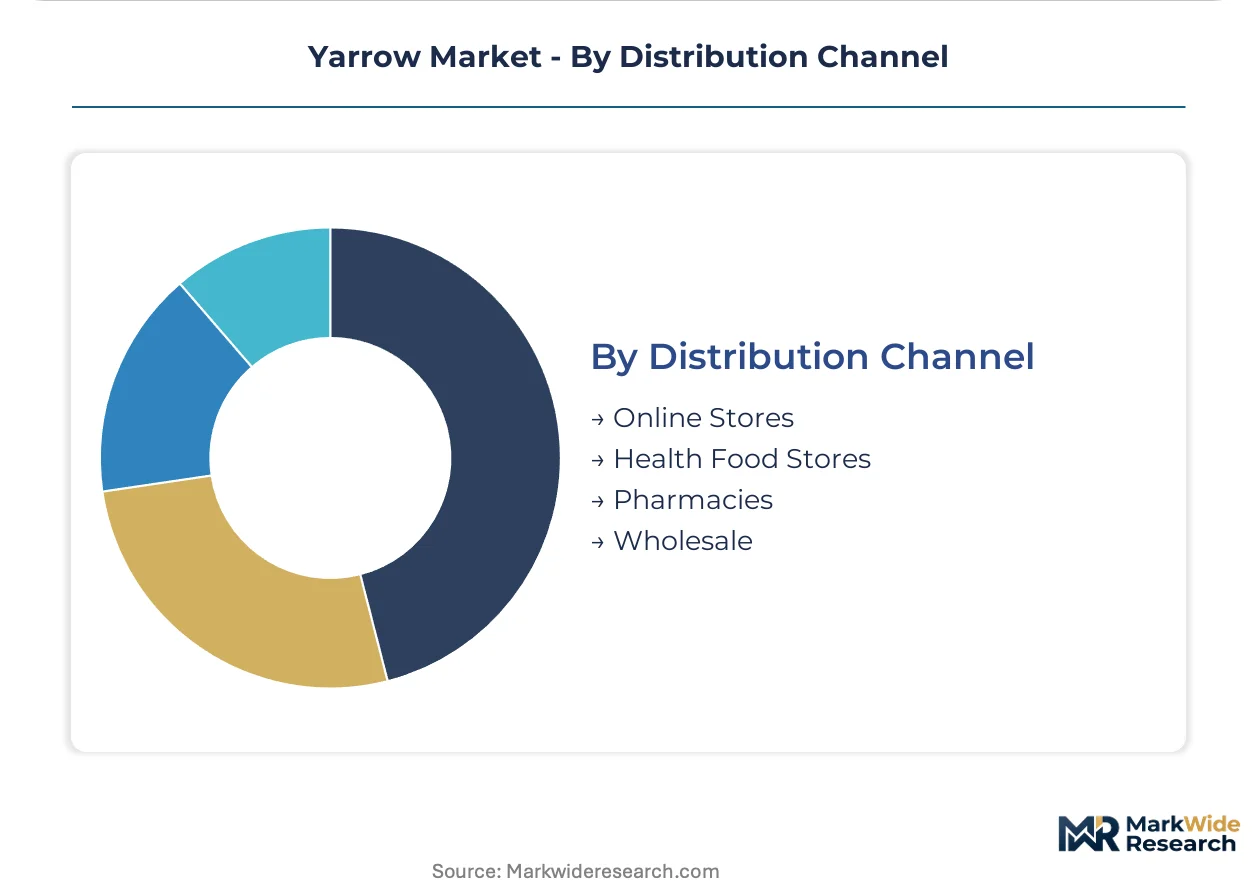
Distribution Channel:
Channel selection reflects buyer sophistication tiers, with practitioner-directed sales bypassing conventional retail entirely.
- Online Stores:Telemedicine herbal consultations normalize digital fulfillment for tincture and capsule formats. German clinics now route patients to direct portals rather than Apotheke pickup.
- Health Food Stores:Shelf placement competes on organic certification visibility and practitioner endorsement. Bristol Botanicals Ltd anchors this channel through exhaustive documentation.
- Pharmacies:Statutory reimbursement eligibility restricts pharmacy distribution to EMA-compliant extracts. Documentation burdens filter low-grade suppliers from this channel.
- Wholesale:Bulk dried herb moves through fragmented wild-crafter networks to industrial processors. GPS coordinate documentation and flowering-stage verification now satisfy EFSA traceability requirements.
Pharmacies hold the premium position today. Online Stores are gaining share fastest as practitioner channel rotation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory phytotherapy reimbursement generates pharmaceutical-grade demand that contrasts sharply with Bulgaria's wild-crafter cooperative networks supplying bulk dried herb volumes.
Germany
Pharmaceutical formulators drive demand for standardized yarrow extracts through the statutory health insurance framework covering prescribed herbal remedies. EMA quality guidelines enforce batch-to-batch consistency documentation for anti-inflammatory applications. The Baden-Württemberg and Bavaria clusters concentrate distillation and extraction operations serving domestic and Swiss buyers.
Bulgaria
Wild-crafter cooperatives supply bulk dried herb volumes under tightening EU Green Deal pollinator protection mandates. The country's national pharmaceutical regulator aligns collection GPS documentation with EFSA traceability requirements. Rose Valley and Balkan Mountain sub-regions anchor certified organic harvesting repositioning toward premium export channels.
Albania
Distillery co-location with grinding operations reduces handling costs for powdered herb shipments to functional food manufacturers. EU organic equivalence protocols impose parallel audit tracks for material bound for German and Italian processors. Northern mountain territories concentrate backward-integrated harvesting operations locking in raw material quality.
Switzerland
Swissmedic standards for wound-healing formulations specify CO2-extracted yarrow variants with documented sesquiterpene lactone content. The country's national pharmaceutical regulator maintains stricter monograph standards than baseline EU requirements. Basel and Zurich pharmaceutical corridors absorb premium extracts for clinical herbalist protocols.
United States
FDA dietary supplement cGMP rules and USDA organic certification create dual compliance tracks for botanical extract imports. Capsule and tablet manufacturers in the dietary supplements segment favor powdered herb for blending efficiency. Pacific Northwest and Mountain West regions concentrate practitioner-directed tincture distribution through telemedicine herbal consultation networks.
Yarrow Market Competitive Landscape
Balkan producers anchor the commodity-grade tier; British and North American specialists hold premium positioning through retail channel control and exhaustive documentation. Supplier concentration splits between fragmented wild-crafter networks and integrated distillery operations. Three archetypes dominate: certified organic wild-crafting cooperatives, backward-integrated aromatics houses, and brand-controlled retail operators. Competitive moves concentrate on distillery equipment retrofit cycles for organic segregation and practitioner formulary inclusion for tincture formats.
Within the British specialist tier, Bristol Botanicals Ltd and Neal's Yard Remedies occupy distinct positioning vectors. Bristol Botanicals Ltd exemplifies the documentation-intensive archetype serving pharmaceutical buyer audits. Neal's Yard Remedies represents retail channel control through dedicated storefront models. Amphora Aromatics Ltd anchors the backward-integrated distillery archetype across Bulgarian and Albanian sourcing territories. These three companies collectively illustrate the geographic and strategic segmentation binding Balkan supply origins to Western European and North American demand endpoints.
| Leading Market Players |
|---|
| Amphora Aromatics Ltd |
| Bristol Botanicals Ltd |
| Carruba Inc |
| Mother Bay Spice Company |
| Neal's Yard Remedies |
| NHR Organic Oils |
| Organic Infusions Inc |
| Penta Manufacturing |
| Starwest Botanicals |
| Others |
Value Network & Pricing Analysis
Family-owned Bulgarian wild-crafter cooperatives anchor upstream supply, their organic certification investments translating directly into price premiums that German pharmaceutical buyers absorb without volume elasticity. This ownership structure resists rapid capacity scaling, creating persistent tightness in certified material that backward-integrated distillery operators exploit through captive supply arrangements.
Pricing Analysis
Capacity additions in Albania are reshaping price floors for powdered herb segments as distillery co-location spreads grinding operations across northern mountain territories. Three-tier pricing structure across premium, standard, and economy levels separates CO2-extracted pharmaceutical grades from steam-distilled cosmetic variants and conventional dried herb commodities. Cost compression in essential oil tiers is intensifying because extraction yield ceilings cap at 0.5% regardless of scale investment. Cosmetic manufacturers prove least price-sensitive, absorbing organic certification premiums for chamazulene-rich skincare positioning, while functional food blenders drive hardest bargain on bulk powdered material.
Supply Chain Analysis
Freight consolidation from Balkan Mountain sub-regions to German pharmaceutical corridors determines landed cost competitiveness for certified organic shipments. Supply concentrates in Bulgaria, Albania, and Romania, with wild-crafter cooperatives drawing from flowering top biomass, steam distillation equipment, and organic audit infrastructure. Single-source vulnerability runs through fragmented wild-harvest networks facing EU Green Deal pollinator protection quota restrictions. Distribution runs through practitioner-directed portals displacing conventional Apotheke fulfillment, particularly in German metropolitan telemedicine consultation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The yarrow market functions as a stable compounder, with Germany's statutory phytotherapy reimbursement creating predictable offtake that smooths demand volatility across economic cycles.
For Market Incumbents: Deepen backward integration into certified organic harvesting territories to lock in raw material security against tightening EU pollinator protection mandates. Invest in supercritical CO2 extraction capacity to capture pharmaceutical-grade premiums that steam-distilled competitors cannot match. Defensive consolidation should target analytical chemistry capabilities for chamazulene quantification, where talent scarcity bottlenecks quality documentation. For New Entrants and Emerging Players: Telemedicine herbal consultation networks represent the most penetrable channel vector, with practitioner-directed tincture sales climbing fastest as German clinics normalize digital fulfillment. Target US dietary supplement manufacturers seeking dual-certified USDA-EU organic material for capsule applications, where compliance documentation barriers filter incumbent competition. A go-to-market angle anchored in GPS-verified wild-harvest traceability satisfies EFSA requirements that fragmented cooperatives struggle to document. For Investors and Strategic Acquirers: Pharmaceutical formulators seeking wound-healing extract pipelines are the most active acquirer in this space, prioritizing audited botanical houses with exhaustive sesquiterpene lactone profiling. Long-term viability rests on regulatory compliance moats rather than commodity scale, with five-to-ten-year windows favoring certified organic positioning over conventional volume plays. The signal to monitor is EMA monograph revision timing, which could elevate documentation standards and accelerate supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Organic Wild-Crafting Conversion | Balkan cooperatives capture price multiples through EU organic equivalence protocols that German buyers mandate. |
| Supercritical CO2 Extraction Deployment | Swissmedic and EMA-compliant pharmaceutical formulators specify CO2-derived extracts for heat-sensitive compound retention. |
| Practitioner Channel Direct Portal Launch | German phytotherapy clinics now route patients to direct-to-consumer fulfillment bypassing Apotheke markups. |
| Backward Distillery Integration | Amphora Aromatics Ltd's Bulgarian and Albanian distillery operations lock in raw material quality for cosmetic manufacturers. |
| Analytical Chemistry Capability Acquisition | Scarcity of chamazulene quantification expertise bottlenecks pharmaceutical buyer audit satisfaction. |
Research Methodology
Bottom-up phytotherapy formulation modeling reconciled against top-down wild-harvest volume tracking forms the analytical core of this study. Primary interviews with herbal remedy formulators, phytotherapy clinic directors, organic certification auditors, and Balkan cooperative harvest leaders combined with secondary validation from EMA quality guidelines, EU Green Deal pollinator protection mandates, FDA cGMP dietary supplement rules, and USDA organic certification databases. Triangulation across supply-side distillery capacity surveys and demand-side pharmaceutical procurement patterns ensures cross-verified volume and value estimates.
Historical trendline analysis of dried herb, essential oil, tincture, and powder segment trajectories established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product type, application category, end-user archetype, and distribution channel, with regional regulatory cluster effects embedded throughout. CAGRs derive from weighted average growth contributions across these segments, incorporating extraction yield economics, certification penetration curves, and practitioner channel expansion rates as industry-specific forecast inputs.
Underlying measurement precision varies by segment; pharmaceutical-grade extracts and certified organic essential oils carry tighter precision than commodity dried herb volumes subject to weather-dependent wild-harvest variability. Forecasts reflect assumptions regarding EMA monograph stability, pollinator protection quota enforcement consistency, and telemedicine herbal consultation normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
India Greenhouse Horticulture Market
Vegetables
North America Microgreens Market
Vegetables
IQF Vegetables Market
Vegetables
Greenhouse Produce Market
Vegetables
Carrots and Turnips Market
Vegetables
Vegetable Chutney Market
Vegetables
Field Peas Market
Vegetables
Vegetable Grader Market
Vegetables
Canada Microgreens Market
Vegetables
Greenhouse Bell Pepper Market
Vegetables
Butternut Squash Market
Vegetables
Garlic Market
Vegetables
Air Dried Vegetables Market
Vegetables
UAE Tomato Market
Vegetables
Ghana Fruit and Vegetable Market
Vegetables
Garden Cress Market