
 Dehydrated Vegetables Market | 2026-2036
Dehydrated Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Dehydrated Vegetables Market Analysis
Contract dehydration services and toll-processing agreements are repositioning how vegetable processors monetize capacity, shifting revenue from commodity sales to fee-based manufacturing partnerships. Olam Food Ingredients leverages its integrated supply chain across multiple continents to secure consistent raw vegetable flows. Silva International sustains competitive positioning through specialized air-drying and freeze-drying capabilities for premium foodservice accounts. BCFoods anchors North American supply through its California processing footprint and direct agricultural relationships.
Dehydrated vegetables are plant-based food products from which moisture has been removed through controlled thermal, air-drying, freeze-drying, or vacuum processes, typically reducing water activity below 0.60 to inhibit microbial growth and preserve nutritional integrity for extended storage. These products serve industrial food manufacturers, foodservice operators, and retail consumers seeking ingredient stability, reduced shipping weight, and year-round availability independent of harvest cycles. Dehydrated onions and dehydrated carrots occupy the largest volume positions within the product type dimension, reflecting their ubiquity across soup bases, seasoning blends, and processed food formulations. Ready-to-eat meals represent the fastest-expanding end-use category as convenience-oriented consumers and institutional buyers prioritize shelf-stable meal components with minimal preparation requirements.
The FDA enforces Current Good Manufacturing Practice regulations and hazard analysis requirements for low-acid foods that directly govern dehydration facility operations, sanitation protocols, and finished-product specifications across the United States. USDA grading standards and the National Organic Program certification framework further differentiate market access tiers for dehydrated vegetable suppliers targeting premium retail and foodservice segments. Stakeholders must monitor evolving clean-label expectations and emerging state-level packaging waste regulations that could reshape material specifications and distribution economics across key production regions.
Market Dynamics
Contract dehydration services are fundamentally restructuring vegetable processor economics, converting fixed asset burdens into variable fee structures while concentrating capacity ownership among specialized toll operators with multi-continent sourcing networks.
Growth Catalysts
- USDA Organic Certification:The National Organic Program creates premium pricing tiers for certified dehydrated vegetables, expanding revenue pools for compliant processors serving retail and foodservice channels.
- Freeze-drying technology:Advanced lyophilization preserves cellular structure and rehydration performance, opening premium applications in ready-to-eat meals and specialty ingredient formulations.
- India's PLI scheme for food processing:Production-linked incentives accelerate domestic dehydration capacity expansion, strengthening export competitiveness and import substitution for processed vegetable inputs.
Market Restraints
- Energy cost volatility:Thermal dehydration remains energy-intensive; natural gas and electricity price swings directly compress processor margins across European and North American operations.
- Raw material concentration:Onion and carrot supply clusters in specific growing regions expose processors to weather-driven harvest variability and quality inconsistency.
- Fresh vegetable substitution:Shortened cold-chain logistics and modified atmosphere packaging enable extended fresh produce distribution, competing with dehydrated alternatives in foodservice procurement.
Strategic Opportunities
- Southeast Asian food manufacturing:Vietnam and Indonesia's expanding instant noodle and seasoning industries present underdeveloped demand for dehydrated onion and garlic inputs.
- Cell-cultured meat integration:Plant-based scaffolding and flavor base applications for cultivated protein products create novel demand for precision-dehydrated vegetable matrices.
- E-commerce direct-to-foodservice:Platform-based procurement bypasses traditional distributor markups, enabling margin capture and customer relationship control for mid-scale processors.
Industry Challenges
- Lyophilization engineering talent scarcity:Specialized equipment operation and process optimization expertise remains concentrated among legacy freeze-drying facilities, constraining capacity scaling.
- Multi-jurisdiction organic equivalency:Divergent certification requirements between USDA, EU organic regulations, and India's NPOP create administrative burden and market access friction for exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dehydrated Vegetables Market |
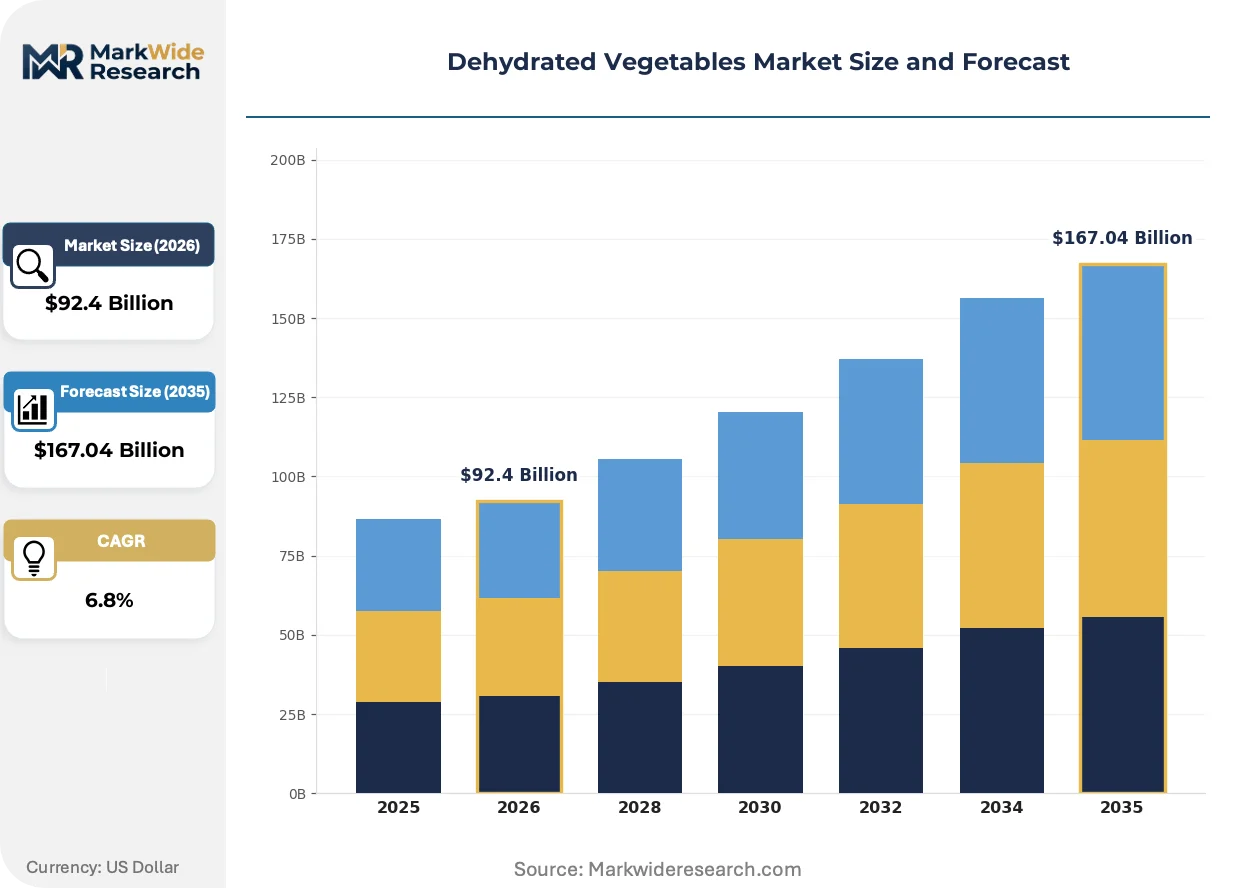
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $167.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dehydrated Carrots, Dehydrated Onions, Dehydrated Spinach, Dehydrated Peas End Use: Food Processing, Snacks, Soups, Ready-to-Eat Meals Packaging Type: Bulk Packaging, Retail Packaging, Pouches, Jars Distribution Channel: Supermarkets, Online Retail, Wholesale, Direct Sales |
| Companies Covered | Silva International, Garlico Industries, Olam Food Ingredients, BCFoods, Mercer Foods, Sensient, Jain Farm Fresh Foods, Eurocebollas, Van Drunen Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dehydrated Vegetables Market Emerging Trajectories
Dehydration technology convergence with precision agriculture and digital process control is compressing quality variance while enabling lot-level traceability demanded by downstream food manufacturers.
Microwave-assisted drying is expanding into commercial vegetable processing, combining volumetric heating with reduced thermal degradation to preserve color compounds and volatile flavor profiles. Ready-to-eal meal manufacturers in Japan and South Korea are adopting this technology at pilot scale. The approach is expanding into premium soup base and seasoning applications where rehydration speed and sensory fidelity command price premiums.
REACH chemical safety registrations and evolving EU packaging waste directives are forcing reformulation of anti-caking agents and oxygen scavengers used in dehydrated vegetable packaging. Industrial consequence includes accelerated substitution of synthetic additives with rice hull-derived and mineral-based alternatives. German and Dutch processors are responding fastest, driven by retailer sustainability scorecards and extended producer responsibility frameworks.
Consolidated food manufacturers are unbundling ingredient specification from supply contracting, separating technical qualification from volume purchasing to introduce competitive bidding among approved suppliers. This procurement restructuring compresses incumbent processor margins while creating entry pathways for specialized dehydration facilities with single-product excellence. The shift is most visible in North American soup and sauce manufacturing, where procurement teams now manage distinct vendor pools for technical compliance versus commercial terms.
Dehydrated Vegetables Market Segmentation
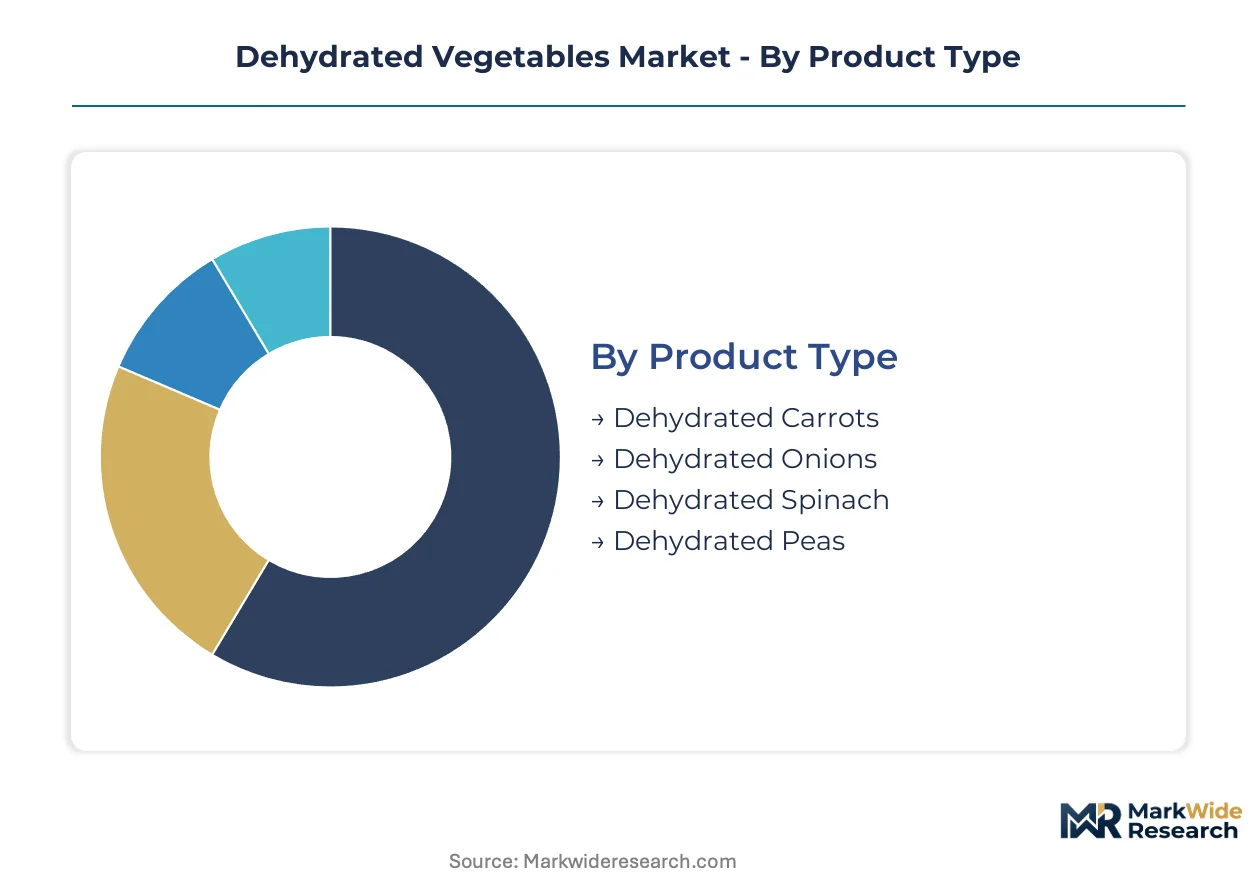
Dehydrated vegetable procurement decisions hinge on moisture-content specifications, rehydration performance, and certification requirements that vary sharply across food manufacturing, foodservice, and retail channels. Segment-level differentiation determines pricing power, margin structure, and regulatory compliance burden for processors and their customers.
Product Type:
USDA Organic Program and FDA low-acid food regulations impose distinct testing and documentation requirements on each vegetable category, with root vegetables facing stricter microbiological surveillance than leafy varieties.
- Dehydrated Carrots:Beta-carotene retention rates above 85% distinguish premium grades from commodity tiers. Soup base manufacturers in the United States and Germany concentrate procurement here, though carrot supply clusters in California and Haryana expose processors to irrigation-dependent harvest variability.
- Dehydrated Onions:Pungency compounds and volatile oil content determine flavor intensity ratings for seasoning blend applications. India's Nashik and Gujarat production belts supply both domestic processors and export channels, with FSSAI-mandated moisture caps shaping finished-product specifications.
- Dehydrated Spinach:Iron and folate preservation through rapid air-drying meets infant food and nutraceutical ingredient standards.
- Dehydrated Peas:Starch gelatinization control during thermal processing maintains texture integrity for instant noodle inclusions.
Dehydrated onions sit at the top of the volume ranking, with dehydrated carrots climbing the fastest.
End Use:
Customer technical requirements diverge sharply: food manufacturers prioritize lot-to-lot consistency and traceability documentation, while retail channels emphasize visual appeal and resealable convenience features.
- Food Processing:Industrial buyers specify water activity below 0.60 and particle size distribution for seamless integration into seasoning matrices, soup bases, and sauce formulations. FDA hazard analysis protocols govern supplier qualification.
- Snacks:Vegetable chip and puff applications demand crispness retention and low oil absorption coefficients. Clean-label positioning accelerates substitution of synthetic flavor enhancers with vegetable-derived alternatives.
- Soups:Rehydration speed and cellular structure recovery determine sensory acceptance in premium and economy product tiers.
- Ready-to-Eat Meals:Shelf-stable meal kits and military rations require extended durability without refrigeration, driving freeze-drying adoption where budget permits.
Food processing commands the largest revenue pool, with ready-to-eat meals gaining share fastest.
Packaging Type:
Extended producer responsibility frameworks in Germany and the Netherlands are forcing migration from multi-layer laminates toward mono-material or fiber-based alternatives, reshaping capital allocation across packaging lines.
- Bulk Packaging:10-25 kg multi-wall paper bags and food-grade totes serve industrial food manufacturers with high-volume, low-frequency procurement patterns. Oxygen scavenger specifications vary by destination market.
- Retail Packaging:Stand-up pouches with resealable zip closures and clear windows dominate supermarket placement, with shelf impact and portion control driving format innovation.
- Pouches:Single-serve and recipe-portion formats target convenience-oriented consumers and camping/outdoor recreation segments.
- Jars:Glass and PET containers preserve aroma integrity for premium herb and specialty vegetable blends in gift and gourmet channels.
Bulk packaging handles the greatest tonnage, with pouches expanding most quickly.
Distribution Channel:
Platform-based procurement is disintermediating traditional wholesale relationships in North American and European foodservice, compressing distributor margins while rewarding processors with direct customer data access.
- Supermarkets:Category management and private-label development programs create volume concentration among retail-aligned processors with national distribution capability.
- Online Retail:Direct-to-consumer and subscription models enable margin capture and brand relationship building, though fulfillment economics favor lightweight, high-value products.
- Wholesale:Foodservice distributors and ingredient brokers maintain relevance through technical service, credit extension, and consolidated sourcing for smaller manufacturers.
- Direct Sales:Contract dehydration agreements and toll-processing partnerships convert processor capacity into fee-based revenue streams independent of commodity price cycles.
Wholesale channels still move the largest volumes, with online retail showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between jurisdictions are redirecting dehydration capacity toward regions with streamlined compliance frameworks and subsidized energy inputs. Processors migrate operations to exploit gaps in inspection frequency, organic certification reciprocity, and environmental permitting timelines.
United States
FDA low-acid food regulations and USDA organic standards impose rigorous documentation burdens on domestic processors. California's Central Valley hosts the densest concentration of carrot and onion dehydration facilities, where water rights constraints and labor costs now pressure margin structures. Midwestern states attract toll-processing investments due to lower facility certification overhead.
India
FSSAI-mandated moisture caps and the PLI scheme for food processing accelerate capacity expansion in Nashik and Gujarat. Jain Farm Fresh Foods and domestic processors supply export channels and local ready-to-meal producers from these clusters. The NPOP organic framework creates administrative friction for exporters targeting EU and US markets simultaneously.
Germany
REACH chemical safety registrations and extended producer responsibility frameworks force rapid packaging reformulation. Dutch and German processors lead substitution of synthetic anti-caking agents with rice hull-derived alternatives. The Emsland region concentrates potato and vegetable drying infrastructure serving Central European soup manufacturers.
China
GB standards for dehydrated vegetables and MIIT industrial upgrading programs shape facility modernization timelines. Shandong and Xinjiang production belts dominate onion and garlic dehydration for export markets. Dual carbon goals are elevating energy costs for thermal processors, accelerating microwave-assisted drying pilot programs.
Vietnam
Emerging instant noodle and seasoning industries generate underdeveloped demand for dehydrated onion and garlic inputs. Ho Chi Minh City and the Mekong Delta host nascent dehydration capacity serving ASEAN food manufacturers. Regulatory harmonization with Codex Alimentarius standards remains incomplete, creating technical barriers for EU-bound exports.
Dehydrated Vegetables Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with foodservice and retail channels favoring established brand recognition while industrial procurement rewards toll-processing flexibility. The vendor base organizes into three tiers: integrated agricultural processors with captive raw material supply, specialized dehydration facilities with single-product excellence, and diversified ingredient houses with broad portfolio coverage. Consolidation pressure concentrates among mid-scale operators lacking either backward integration or premium technology positioning. Dominant competitive moves include capacity expansion in low-cost jurisdictions and strategic partnerships with ready-to-eal meal manufacturers seeking dedicated supply lines.
Within the integrated processor tier, Olam Food Ingredients and BCFoods exemplify archetypes leveraging multi-continent sourcing networks and direct agricultural relationships respectively. Silva International occupies a position among specialized dehydration facilities with differentiated drying technology capabilities. Jain Farm Fresh Foods anchors the India-centric supply vector serving both export channels and domestic food manufacturing demand.
| Leading Market Players |
|---|
| Silva International |
| Garlico Industries |
| Olam Food Ingredients |
| BCFoods |
| Mercer Foods |
| Sensient |
| Jain Farm Fresh Foods |
| Eurocebollas |
| Van Drunen Farms |
| Others |
Supply Flow & Price Mechanics
Captive backward integration into California's Central Valley carrot and onion growing regions anchors supply positions for North American processors while simultaneously locking in cost advantages that translate into pricing power over toll-dependent competitors. This integration pattern concentrates procurement leverage among operators with direct agricultural relationships, compressing margins for processors forced to source through spot markets or contract farming arrangements.
Pricing Analysis
Distributor margin layers absorb 12-18 percentage points between dehydration facilities and food manufacturing customers, though direct-to-OEM contracting is eroding this spread. Three-tier pricing structure across premium freeze-dried, standard air-dried, and economy sun-dried levels separates certification-grade product from commodity tiers. Pricing pressure stems from energy cost volatility in European thermal processing, with natural gas price swings compressing margins. Foodservice distributors exhibit highest price sensitivity due to thin operating margins, while infant food manufacturers show lowest sensitivity given stringent quality requirements.
Supply Chain Analysis
Regional distribution centers in California's Central Valley, India's Nashik-Gujarat corridor, and China's Shandong province form hub-and-spoke patterns radiating toward coastal export terminals. Raw material flows draw from onion clusters in Nashik, carrot belts in Haryana and California, and garlic concentrations in Shandong and Xinjiang. Single-source vulnerability runs through India's monsoon-dependent irrigation systems for carrot quality consistency. Distribution runs through food-grade totes and multi-wall bags for industrial buyers, with retail pouches and jars serving supermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
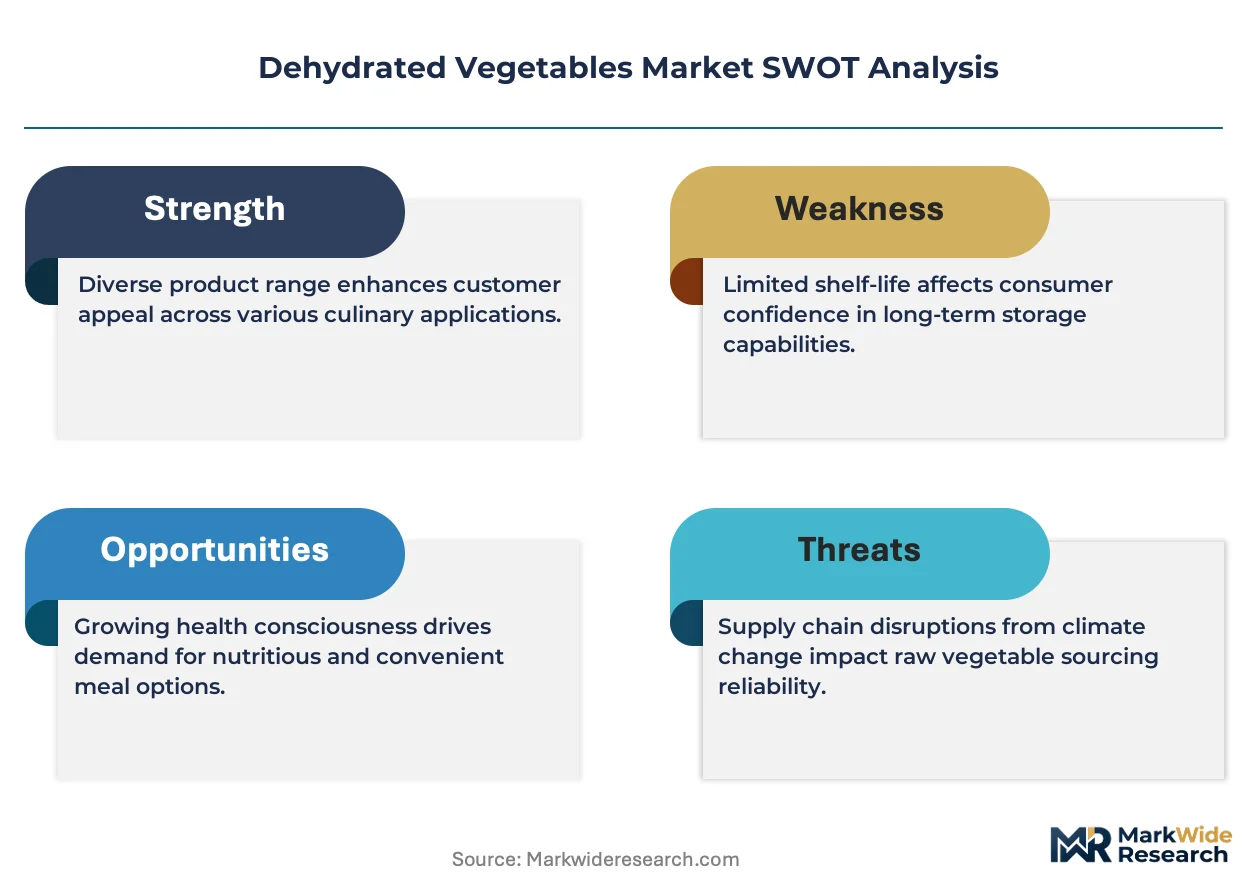
Geographic-arbitrage economics favor capacity migration from European energy-cost jurisdictions toward India's PLI-subsidized processing zones, exploiting the regulatory cost differential between REACH compliance burdens and streamlined FSSAI frameworks.
For Market Incumbents: Deepen captive supply control over California water rights and Haryana irrigation partnerships to defend against fresh vegetable substitution enabled by cold-chain compression. Freeze-drying capacity expansion in low-energy-cost jurisdictions counters margin pressure from European natural gas volatility. Prioritize USDA Organic and EU organic equivalency certification to maintain premium tier access. For New Entrants and Emerging Players: Foodservice platform partnerships offer white-space entry around Vietnam's underdeveloped instant noodle ingredient supply and Indonesia's seasoning manufacturing expansion. Toll-processing agreements with mid-scale soup manufacturers bypass entrenched distributor relationships. Target ready-to-eat meal manufacturers seeking dedicated dehydration lines with flexible minimum order quantities. For Investors and Strategic Acquirers: Roll-up economics work for specialized dehydration facilities with single-product excellence because procurement unbundling at consolidated food manufacturers is fragmenting supplier relationships and creating acquisition currency for technical qualification assets. Five-to-ten year viability hinges on microwave-assisted drying technology maturation beyond pilot scale. Watch for freeze-drying engineering talent scarcity easing as university programs respond to capacity expansion signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Irrigation Assets | Direct water rights control in California and Haryana insulates harvest variability exposure. |
| Freeze-Drying Capacity Expansion | Lyophilization investment captures premium ready-to-eat meal demand from military and camping segments. |
| PLI Scheme Capacity Utilization | Indian government incentives accelerate export-competitive dehydration facility commissioning in Nashik. |
| Platform-Based Direct Procurement | E-commerce foodservice bypasses traditional distributor markups for mid-scale processor margin capture. |
| Organic Equivalency Certification Investment | Multi-jurisdiction USDA-EU-NPOP compliance unlocks premium retail channel access across export markets. |
Methodological Framework
Multiple input streams — dehydration facility operations data, agricultural procurement patterns, and regulatory filing analysis — were reconciled through structured primary interviews with plant managers, food manufacturing procurement leads, and FSSAI compliance officers, cross-checked against USDA organic certification databases, FDA low-acid food facility registrations, and customs trade flow records. Bottom-up capacity modeling and top-down demand estimation triangulated volume figures across the projection horizon.
Historical capacity utilization patterns were cross-referenced against panel input from toll-processing operators and contract dehydration service providers to anchor growth assumptions. Segmentation dimensions modeled include drying technology tier, certification grade, end-use application, and regional production hub clustering. CAGRs were derived from slope analysis of installed capacity expansion timelines correlated with PLI scheme disbursement schedules and energy cost trajectory assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lyophilization equipment cost curves and REACH packaging reformulation compliance timelines. Forecasts reflect documented assumptions around India's irrigation infrastructure investment and European natural gas price stabilization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Air Dried Vegetables Market
Vegetables
Europe Flowers and Ornamental Plants Market
Vegetables
Netherlands Greenhouse Horticulture Market
Vegetables
Peas Market
Vegetables
Dried Mushroom Market
Vegetables
Yarrow Market
Vegetables
Vegetable Chutney Market
Vegetables
Zimbabwe Fruits and Vegetables Market
Vegetables
North America Peas Market
Vegetables
UAE Tomato Market
Vegetables
Hydroponic Vegetable Market
Vegetables
North America Microgreens Market
Vegetables
United States Microgreens Market
Vegetables
Vegetable Grader Market
Vegetables
Sprouts Market
Vegetables
Yam Products Market