
 Canada Microgreens Market | 2026-2036
Canada Microgreens Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Microgreens Market Insights
The shift from single-source produce distributors to multi-source vertical farm networks is decoupling microgreens procurement from traditional agricultural supply chains in Canada. GoodLeaf Farms leverages controlled-environment agriculture to sustain year-round output regardless of Prairie weather extremes. Living Earth Farm anchors its position through hyperlocal distribution to Ontario restaurants and caterers. AeroFarms competes on technology leadership in automated nutrient delivery systems for consistent crop yields.
Canada microgreens constitute young vegetable seedlings harvested 7-21 days after germination, typically 1-3 inches tall with concentrated nutrient profiles up to 40 times denser than mature greens, serving culinary garnish and functional food applications. Arugula and radish varieties dominate restaurant procurement due to peppery flavor intensity and plate presentation value. Pea shoots represent the fastest-expanding grocery segment as consumers adopt home preparation routines. Online retail channels capture margin pools through subscription models that bypass wholesale intermediaries.
Health Canada's Safe Food for Canadians Regulations mandate preventive controls and traceability documentation for fresh produce operations, while CFIA inspection protocols shape facility design investments. The Canadian Food Inspection Agency enforces grade standards that differentiate premium microgreens from commodity sprouts in retail labeling. Provincial organic certification bodies in British Columbia and Quebec create tiered market access requirements. Stakeholders must monitor evolving provincial greenhouse gas regulations that could alter energy cost structures for indoor growing operations.
Market Dynamics
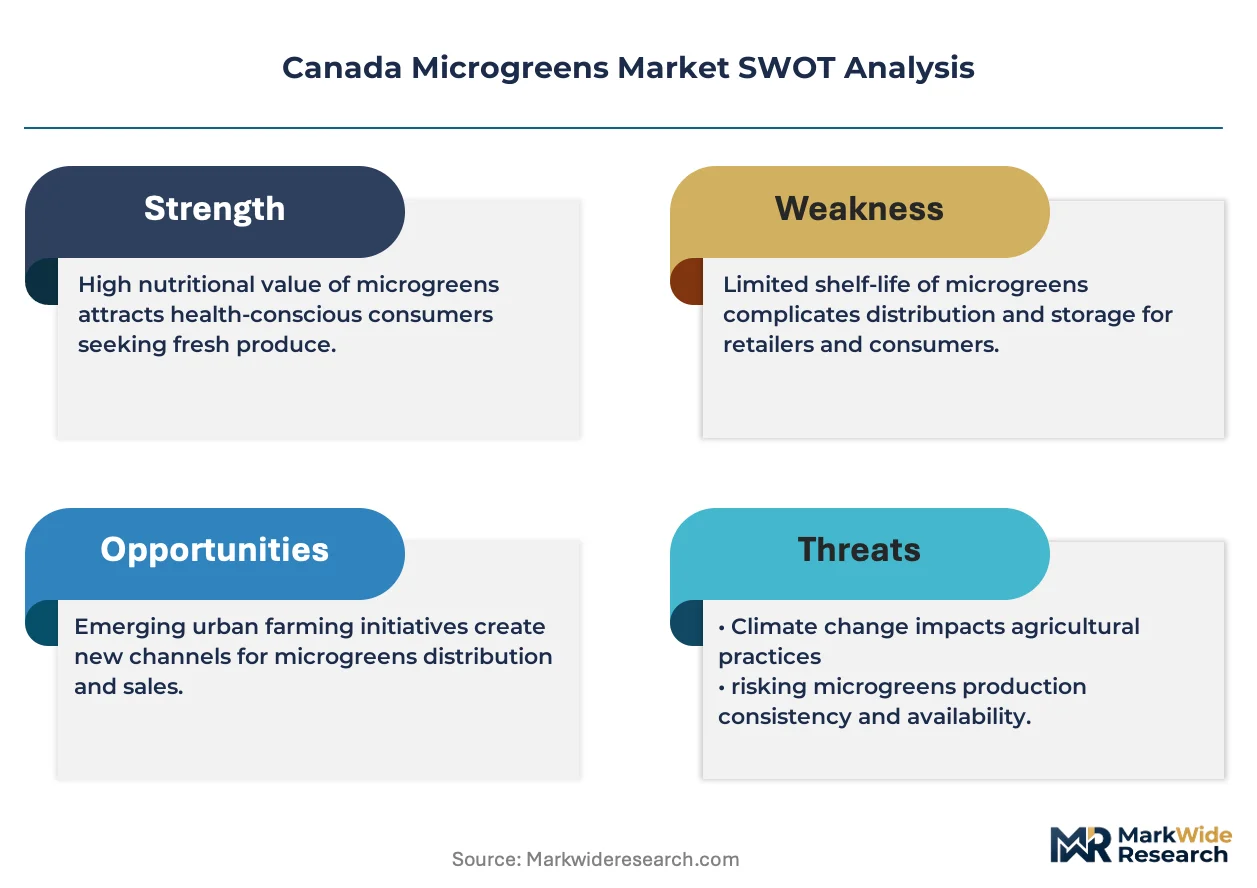
Controlled-environment agriculture is severing Canadian microgreens from Prairie weather dependency and traditional distributor networks, while Health Canada's traceability mandates force facility-level investments that favor capitalized vertical farm operators over conventional greenhouse growers.
Growth Catalysts
- Safe Food for Canadians Regulations:Preventive control mandates are filtering out informal growers and consolidating volume among certified indoor operators with documented traceability systems.
- Fine-dining procurement:Toronto and Vancouver restaurants now contract directly with vertical farms for living product with 14-day harvest-to-plate cycles, bypassing wholesale intermediaries.
- Pea shoot adoption:Home preparation routines in Ontario and British Columbia are expanding retail shelf space for grocery-format microgreens beyond restaurant supply.
Market Restraints
- Energy cost volatility:Indoor growing operations face exposure to provincial electricity rate structures, particularly in jurisdictions with carbon pricing mechanisms affecting heating and lighting loads.
- Input concentration:Specialized growing media and automated nutrient delivery systems rely on limited North American suppliers, creating vulnerability to supply shocks.
- Substitution from mature greens:Organic baby spinach and kale occupy adjacent shelf space at lower price points, pressuring margin capture in mass retail channels.
Strategic Opportunities
- Quebec market penetration:Montreal's restaurant density and provincial organic certification infrastructure remain underdeveloped relative to Ontario's maturity.
- Subscription channel innovation:Direct-to-consumer weekly harvest boxes bypass retail slotting fees and capture full margin pools from urban households.
- Provincial greenhouse gas regulations:Emerging carbon accounting frameworks may advantage low-emission indoor operations in public procurement and institutional foodservice contracts.
Industry Challenges
- Controlled-environment agronomy talent:The intersection of horticultural science and automation engineering lacks established training pipelines, constraining facility expansion timelines.
- CFIA grade standard compliance:Differentiation between microgreens and commodity sprouts in labeling requires analytical testing investments that strain emerging operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Microgreens Market |
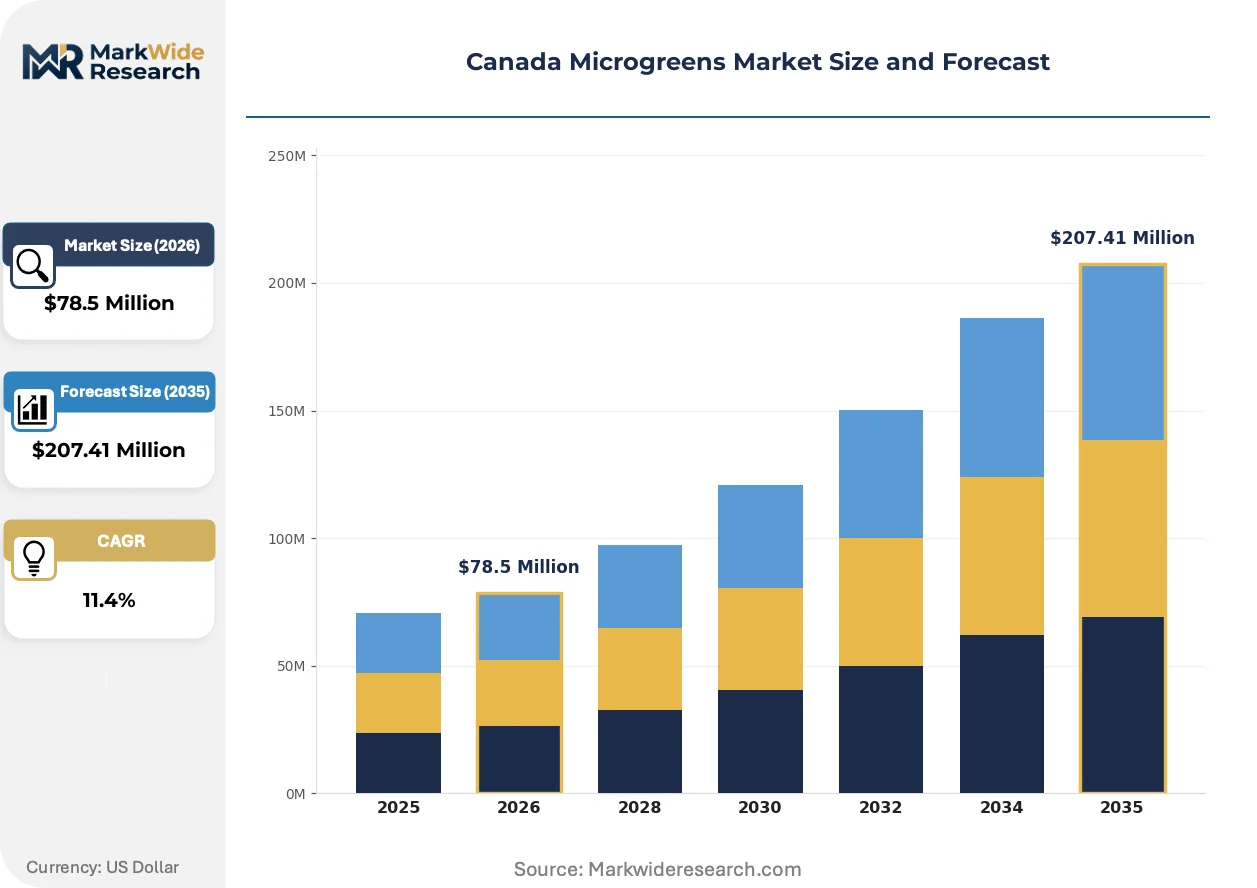
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $207.41 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arugula, Radish, Pea Shoots, Sunflower End User: Restaurants, Grocery Stores, Home Consumers, Catering Services Distribution Channel: Online Retail, Wholesale, Direct Sales, Farmers' Markets Packaging Type: Clamshell, Bags, Trays, Bulk |
| Companies Covered | GoodLeaf Farms, Living Earth Farm, AeroFarms, Bowery Farming Inc., Gotham Greens, Fresh Origins, Charlie's Produce, Madar Farms, Teshuva Agricultural Projects Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Microgreens Market Trends and Innovations
Automation and regulatory precision are compressing production cycles and reconfiguring buyer relationships across Canadian microgreens supply chains. Three developments are actively restructuring competitive positioning.
Automated nutrient delivery systems with real-time pH and EC monitoring are decentralizing production expertise away from master growers toward algorithmic control. Mid-scale vertical farms in Ontario and Alberta are deploying these systems to achieve batch consistency previously requiring decades of greenhouse experience. The technology is decentralizing quality assurance from individual expertise to replicable facility standards, enabling rapid geographic replication without talent bottlenecks.
Health Canada's Safe Food for Canadians Regulations tightened preventive control and traceability documentation requirements for fresh-cut produce operations in 2019. CFIA inspection protocols now shape facility design investments, with unannounced audits verifying environmental monitoring and sanitation records. Small-scale soil-based growers face disproportionate compliance burdens, accelerating consolidation toward purpose-built indoor operations with integrated documentation systems.
Restaurant procurement teams are abandoning weekly produce distributor orders in favor of direct vertical farm contracts with guaranteed harvest schedules. Toronto's fine-dining clusters now specify living product delivered within 24 hours of harvest, displacing cut-and-chilled alternatives. This pattern is most visible in Ontario's Greater Toronto Area, where restaurant density supports dedicated delivery routes and inventory turns justify premium positioning.
Canada Microgreens Market Segmentation
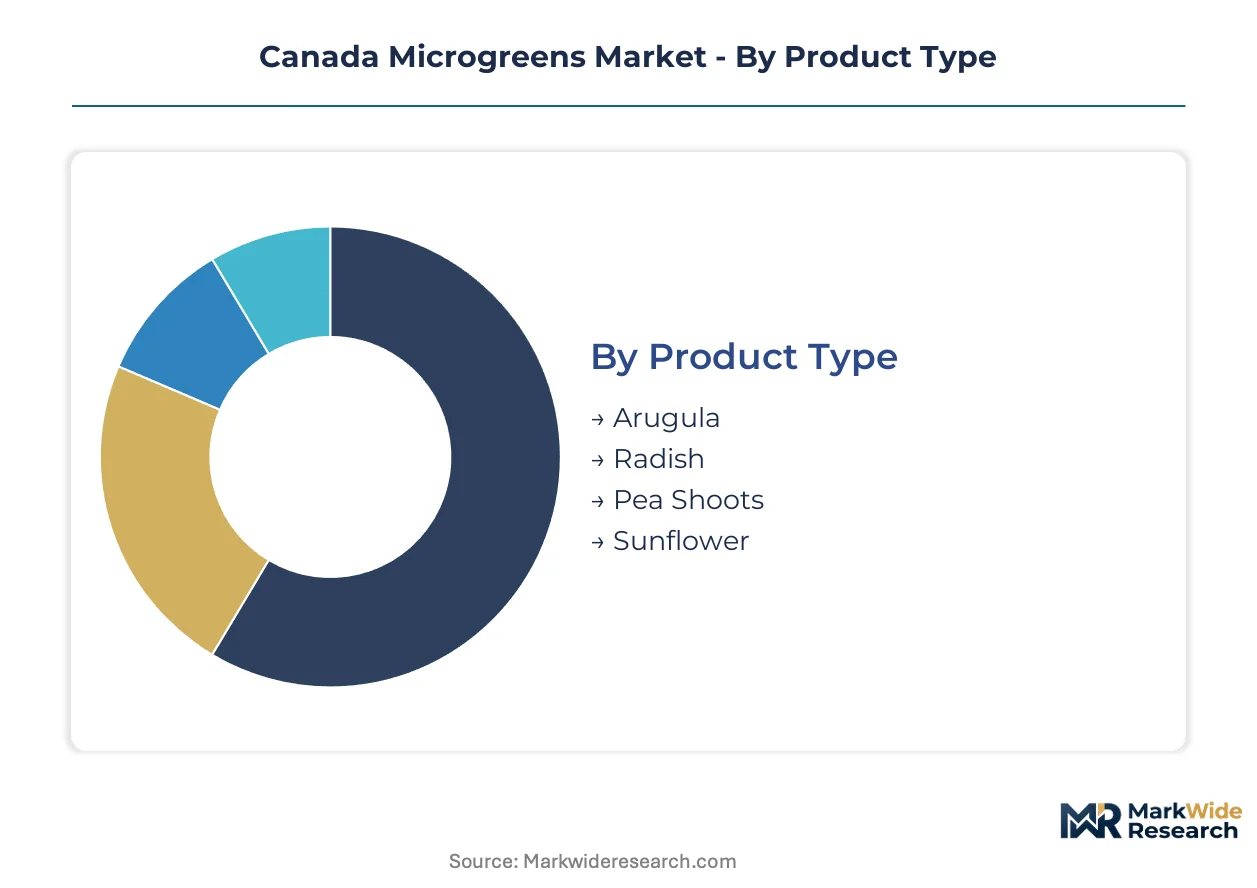
Microgreens segmentation in Canada reflects divergent supply chain requirements between living product for foodservice and packaged retail formats. Each category maps distinct margin pools, regulatory exposure, and capital intensity profiles across the value chain.
Product Type:
Flavor intensity and harvest-to-plate shelf stability define varietal selection for indoor growing systems.
- Arugula:Peppery isothiocyanate profile delivers concentrated flavor at 1-2 inch height, making it the default garnish for Toronto fine-dining establishments seeking visual plate contrast. Ontario restaurants contract directly with vertical farms for living arugula with 10-day harvest cycles.
- Radish:Anthocyanin-rich purple and red varieties command premium positioning through color differentiation on white plates. Vancouver's seafood-focused restaurants favor radish microgreens for their wasabi-adjacent heat profile and coastal supply chain proximity.
- Pea Shoots:Mild sweetness and tender texture expand home preparation adoption in Ontario and British Columbia grocery channels.
- Sunflower:Substantial leaf structure and nutty flavor suit catering bulk applications and sandwich builds.
Mature deployment sits with arugula and radish in restaurant supply chains. Newer deployment is concentrated in pea shoots for retail home consumption.
End User:
Buyer sophistication and inventory turnover velocity create tiered procurement patterns across Canadian food systems.
- Restaurants:Toronto and Vancouver fine-dining establishments now specify living product with documented harvest timestamps, displacing cut-and-chilled alternatives through direct vertical farm contracts. Plate presentation requirements drive 14-day maximum farm-to-fork cycles.
- Grocery Stores:Ontario's premium banners allocate expanded refrigerated shelf space to clamshell-packaged pea shoots and sunflower varieties as home meal preparation routines expand.
- Home Consumers:Subscription box services in Montreal and Calgary bypass retail intermediaries with weekly living product deliveries.
- Catering Services:Event volume demands in Vancouver and Toronto favor bulk tray formats with 48-hour shelf stability for buffet presentation.
Volume concentrates in restaurant procurement with premium pricing. Steepest expansion trajectory belongs to home consumer subscription channels.
Distribution Channel:
Channel selection determines margin capture and traceability documentation burdens under Health Canada regulations.
- Online Retail:Subscription models capture full margin pools from urban households while building harvest forecasting data for vertical farm operators.
- Wholesale:Traditional produce distributors face displacement as restaurants bypass intermediaries for direct farm relationships.
- Direct Sales:Living Earth Farm and GoodLeaf Farms anchor hyperlocal delivery routes to Toronto restaurant clusters with dedicated refrigerated transport.
- Farmers' Markets:Soil-based growers in British Columbia's Okanagan Valley serve weekend retail traffic with limited scale.
Direct sales dominate premium living product. Online retail is gaining share fastest in home consumer segments.
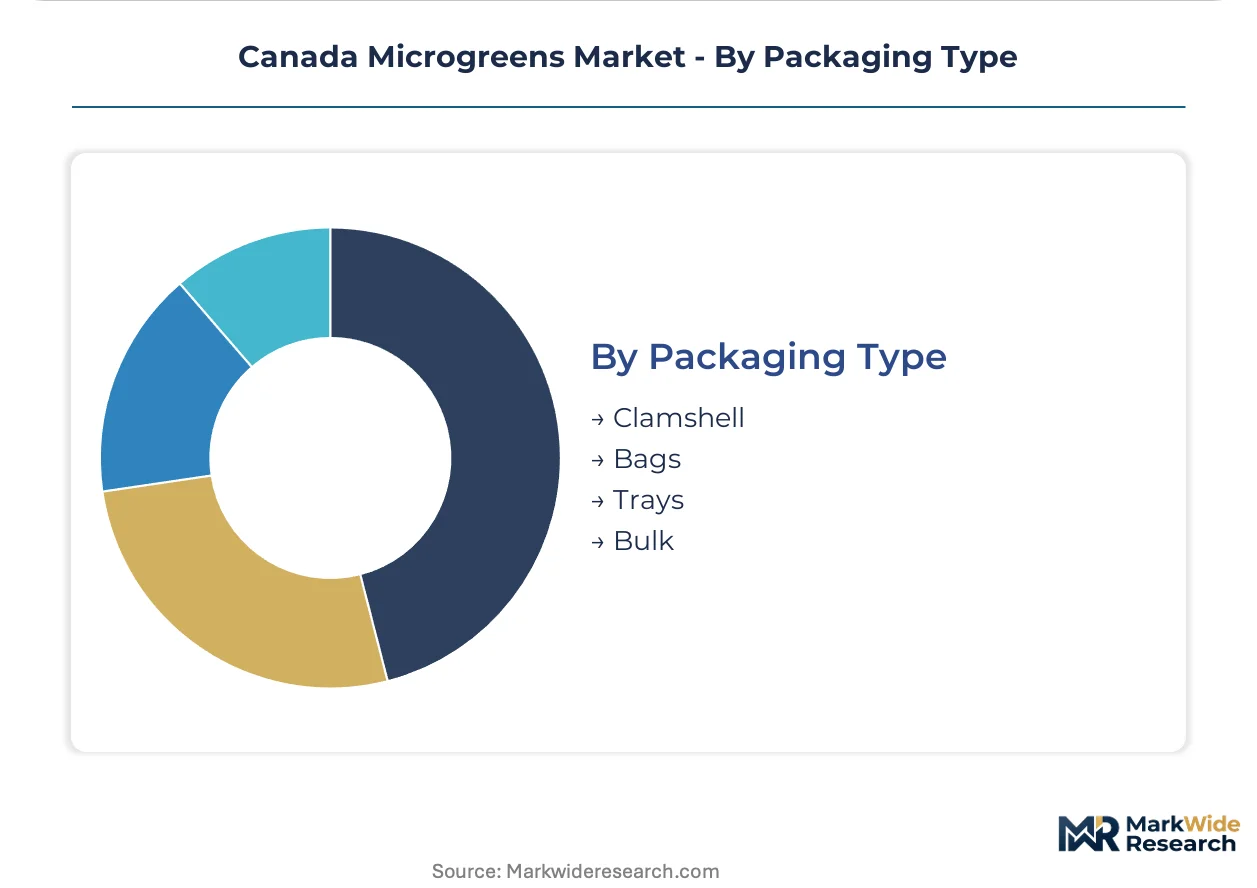
Packaging Type:
Packaging format aligns with shelf life requirements and CFIA labeling standards for fresh-cut produce.
- Clamshell:Rigid PET containers with modified atmosphere properties extend retail shelf life to 7 days for grocery channel pea shoots and arugula.
- Bags:Perforated film suits high-turnover restaurant supply with 48-hour consumption windows.
- Trays:Living product in soil-based trays serves catering and restaurant accounts requiring harvest-on-site presentation.
- Bulk:Unpackaged totes for institutional foodservice and high-volume catering operations in Vancouver and Toronto event venues.
Clamshell deployment is mature in grocery retail. Living tray formats represent newer deployment in fine-dining supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fertile soil regions in southern Ontario anchor Canadian microgreens cultivation, with controlled-environment facilities clustering near major urban demand centers rather than traditional agricultural belts.
Ontario
Toronto's restaurant density drives direct vertical farm contracts for living arugula and radish microgreens with 10-day harvest cycles. Health Canada's Safe Food for Canadians Regulations mandate preventive controls and traceability documentation that favor capitalized indoor operators in the Greater Toronto Area. Guelph-Waterloo hosts research partnerships between the University of Guelph and commercial growers developing automated nutrient delivery protocols.
Quebec
Montreal's fine-dining scene generates emerging demand for hyperlocal microgreens procurement previously served by Ontario distributors. The province's organic certification infrastructure through Quebec Vrai creates tiered market access requirements distinct from federal standards. Laval's greenhouse conversion projects are repurposing legacy floriculture facilities for controlled-environment microgreens production.
British Columbia
Vancouver's seafood-focused restaurants favor radish microgreens for wasabi-adjacent heat profiles and coastal supply chain proximity. The province's carbon pricing mechanisms affect energy cost structures for indoor growing operations in the Lower Mainland. Okanagan Valley soil-based growers serve weekend farmers' market traffic with limited scale against indoor competitors.
Alberta
Calgary's home consumer subscription channels bypass retail intermediaries with weekly living product deliveries. Provincial electricity rate structures expose indoor operations to heating and lighting cost volatility during Prairie winter extremes. Edmonton research facilities are testing LED spectrum optimization for pea shoot varieties targeting grocery expansion.
Atlantic Canada
Halifax restaurant clusters show nascent direct procurement patterns following Ontario and British Columbia models. The region's lagging vertical farm infrastructure depends on air-freighted supply from central Canada. Saint John's institutional foodservice contracts represent potential early adopters for low-emission indoor operations under emerging carbon accounting frameworks.
Canada Microgreens Market Competitive Landscape
Direct vertical farm contracts dominate the current landscape as restaurants abandon traditional produce distributors. The market structures around three tiers: capitalized multi-facility operators with automated systems, mid-scale regional growers serving single metropolitan areas, and legacy soil-based producers constrained by seasonal output. Strategic archetypes include technology-led yield optimizers, hyperlocal distribution specialists, and research-backed variety developers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as operators secure dedicated restaurant supply agreements and grocery retail shelf space.
Among controlled-environment specialists, GoodLeaf Farms exemplifies the multi-facility technology tier with year-round output capabilities, while Living Earth Farm anchors hyperlocal distribution positioning through dedicated Toronto restaurant routes. AeroFarms represents the research-intensive archetype with automated nutrient delivery systems that achieve batch consistency without legacy greenhouse expertise. These three operators collectively illustrate how capital intensity and geographic focus stratify competitive positioning under Health Canada's traceability mandates.
| Leading Market Players |
|---|
| GoodLeaf Farms |
| Living Earth Farm |
| AeroFarms |
| Bowery Farming Inc. |
| Gotham Greens |
| Fresh Origins |
| Charlie's Produce |
| Madar Farms |
| Teshuva Agricultural Projects Ltd. |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up vertical farm specialists in Ontario and British Columbia are consolidating production capacity under unified ownership structures that enforce pricing discipline through harvest scheduling coordination and shared logistics infrastructure. These ownership patterns concentrate supply-side leverage among capitalized indoor operators capable of absorbing Health Canada compliance costs while maintaining premium positioning against fragmented soil-based competitors.
Pricing Analysis
Service bundling distinguishes living tray formats with on-site harvest support from unbundled clamshell retail products lacking technical assistance. Three-tier pricing structure across premium living product, standard packaged retail, and economy bulk formats stratifies the market, with certification grade under Health Canada's Safe Food for Canadians Regulations and volume scale driving price differentiation. Pricing pressure stems from organic baby spinach and mature greens occupying adjacent shelf space at lower price points, compressing margins in mass retail channels. Grocery stores exhibit highest price sensitivity due to slotting fee structures, while fine-dining establishments prioritize harvest-to-plate velocity over unit cost.
Supply Chain Analysis
Reverse logistics for living product returns and tray refurbishment flows are minimal given perishable harvest cycles, though nutrient solution recycling and growing media recovery operate at facility level. Geographic supply concentrates in Canada, with secondary dependencies on United States suppliers for specialized LED systems and automated nutrient delivery components. Raw material inputs hinge on peat-based growing media, precision fertilizer formulations, and climate control equipment from limited North American suppliers. Single-source vulnerability in automated nutrient delivery systems creates exposure to supply shocks. Distribution runs through direct vertical farm contracts for premium living product, bypassing wholesale intermediaries previously dominant in produce supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controlled-environment agronomy talent scarcity constrains facility expansion timelines across Canadian microgreens production, propping pricing power for incumbent operators with established technical teams and documented harvest consistency.
For Market Incumbents: Lock in exclusive supply agreements with Toronto and Vancouver fine-dining clusters before emerging vertical farm operators achieve scale, while deepening backward integration into automated nutrient delivery system maintenance to reduce supplier concentration risk. Health Canada's evolving traceability documentation requirements favor operators with integrated facility-level monitoring systems, making certification investment a critical defensive lever against mid-scale regional growers lacking capital for compliance infrastructure. For New Entrants and Emerging Players: Restaurant procurement teams in Montreal represent the most penetrable buyer segment given underdeveloped local vertical farm infrastructure and continued reliance on Ontario distributors. Direct sales channel partnerships with Quebec's organic certification bodies through Quebec Vrai create differentiated market access unavailable to non-certified competitors. Subscription box services targeting Calgary and Edmonton home consumers bypass retail slotting fees while building harvest forecasting capabilities that attract institutional capital. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Ontario vertical farms with established Health Canada compliance infrastructure but constrained expansion capital during electricity rate volatility periods. Long-term viability across the analysis window depends on automation engineering capabilities that reduce talent dependency and enable geographic replication. Monitor provincial greenhouse gas regulation implementation timelines as inflection indicators for low-emission indoor operation advantages in public procurement contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Nutrient Delivery Deployment | Algorithmic pH and EC monitoring decentralizes quality assurance from individual growers to replicable facility standards. |
| Direct Restaurant Contract Expansion | Toronto fine-dining clusters now specify living product with documented harvest timestamps displacing cut-and-chilled alternatives. |
| Quebec Market Penetration | Montreal's restaurant density and provincial organic certification infrastructure remain underdeveloped relative to Ontario maturity. |
| Subscription Channel Development | Weekly harvest boxes bypass retail slotting fees and capture full margin pools from urban households. |
| CFIA Grade Standard Compliance Investment | Analytical testing capabilities differentiate premium microgreens from commodity sprouts in retail labeling requirements. |
Research Methodology
Independent corroboration across vertical farm operations executives, restaurant procurement managers, and CFIA compliance officers underwrites the qualitative findings, validated against Health Canada regulatory filings, provincial organic certification body records, and controlled-environment agriculture trade association data. Primary interviews with automated systems engineers and grocery category buyers combined with secondary sources including customs records for growing media imports and utility rate filings for provincial electricity structures. Bottom-up facility capacity assessments triangulated against top-down market value estimates derived from restaurant procurement spend patterns and retail scanner data.
Rate-of-change decomposition across the analysis window separates volume expansion from price trajectory components, with segmentation modeling across product type, end user, distribution channel, and packaging format dimensions. CAGRs were derived from installed capacity growth rates, yield per square foot improvements from LED spectrum optimization, and penetration assumptions for subscription channels versus traditional retail. Forecast inputs include provincial electricity rate structures affecting heating and lighting cost volatility, and Health Canada inspection protocol enforcement intensity shaping facility-level compliance investment requirements.
Caveats apply where provincial greenhouse gas regulation implementation or carbon pricing mechanism expansion could materially shift the outlook for indoor growing operation cost structures. Forecasts reflect assumptions regarding automation technology adoption curves and restaurant procurement team willingness to abandon traditional produce distributors. Practitioners should monitor CFIA unannounced audit frequency and provincial organic certification body enforcement patterns for early signals of compliance burden redistribution across operator scale tiers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Global Indoor Plant Market
Vegetables
Italy Greenhouse Horticulture Market
Vegetables
North America Sweet Potatoes Market
Vegetables
Dry Onion Market
Vegetables
North America Peas Market
Vegetables
Squash Market
Vegetables
Yams Market
Vegetables
India Greenhouse Horticulture Market
Vegetables
Fresh Vegetables Market
Vegetables
Garlic Market
Vegetables
Qatar Greenhouse Market
Vegetables
Artichokes Market
Vegetables
IQF Vegetables Market
Vegetables
Field Peas Market
Vegetables
Peas Market
Vegetables
Canada Greenhouse Horticulture Market