
 United States Conveyor Belt Market | 2026-2036
United States Conveyor Belt Market Size, Share, and Industry Trends Forecast 2026-2036
United States Conveyor Belt Market Intelligence
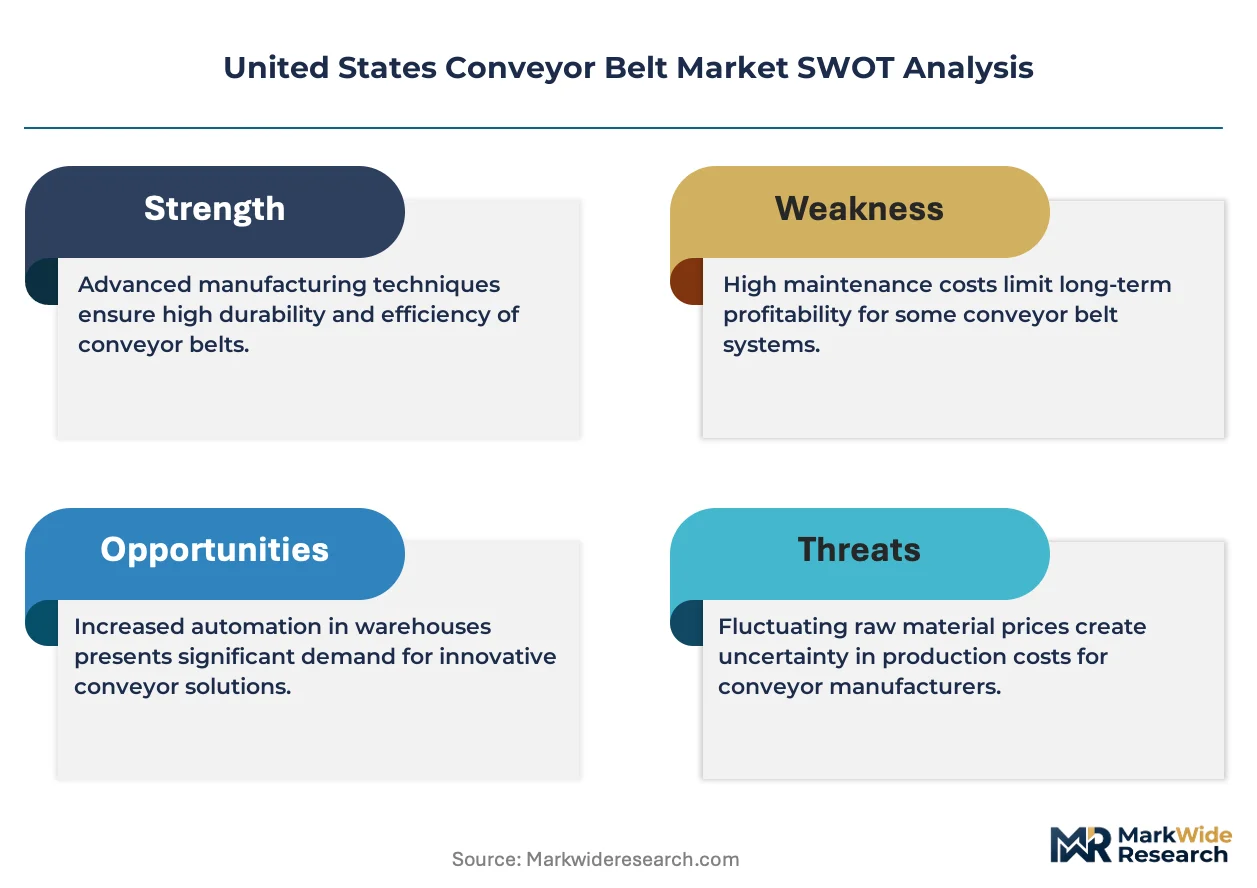
Skilled conveyor maintenance technician availability is collapsing across the industrial Midwest, forcing end-users toward predictive maintenance contracts and forcing OEMs to expand field service networks. Fenner Dunlop Conveyor leverages its Appalachian manufacturing footprint to sustain same-day belt splicing services for mining clients. Hytrol Conveyor Co., Inc. anchors its position through a dense distributor network that controls aftermarket parts availability in the Southeast. LEWCO, Inc. specializes in engineered-to-order belt systems for automotive tier suppliers navigating just-in-sequence delivery requirements.
A conveyor belt is a continuous moving band of fabric, rubber, or metal that transports bulk materials or discrete items between processing, storage, and loading points, typically specified by tensile strength rating, cover grade abrasion resistance, and pulley diameter compatibility. The primary purpose is to reduce material handling labor and enable consistent throughput in high-volume production and distribution environments. Heavy-duty rubber belts dominate mining and aggregate applications where MSHA fire-resistance certification commands premium positioning, while modular plastic belts are displacing fabric alternatives in food processing washdown environments. The logistics end-user segment is expanding fastest as e-commerce fulfillment centers adopt zone-based conveyor architectures, though fixed installations still occupy the majority of installed base value due to infrastructure longevity.
MSHA standards govern underground belt fire resistance and static conductivity, while OSHA regulates conveyor guard design and lockout-tagout procedures for maintenance access. The Department of Transportation's port infrastructure grants are indirectly stimulating belt system demand at coastal intermodal terminals. Stakeholders must monitor whether proposed silica dust rules expand beyond mining into downstream aggregate handling, as this would trigger belt enclosure and ventilation retrofits across multiple end-use categories.
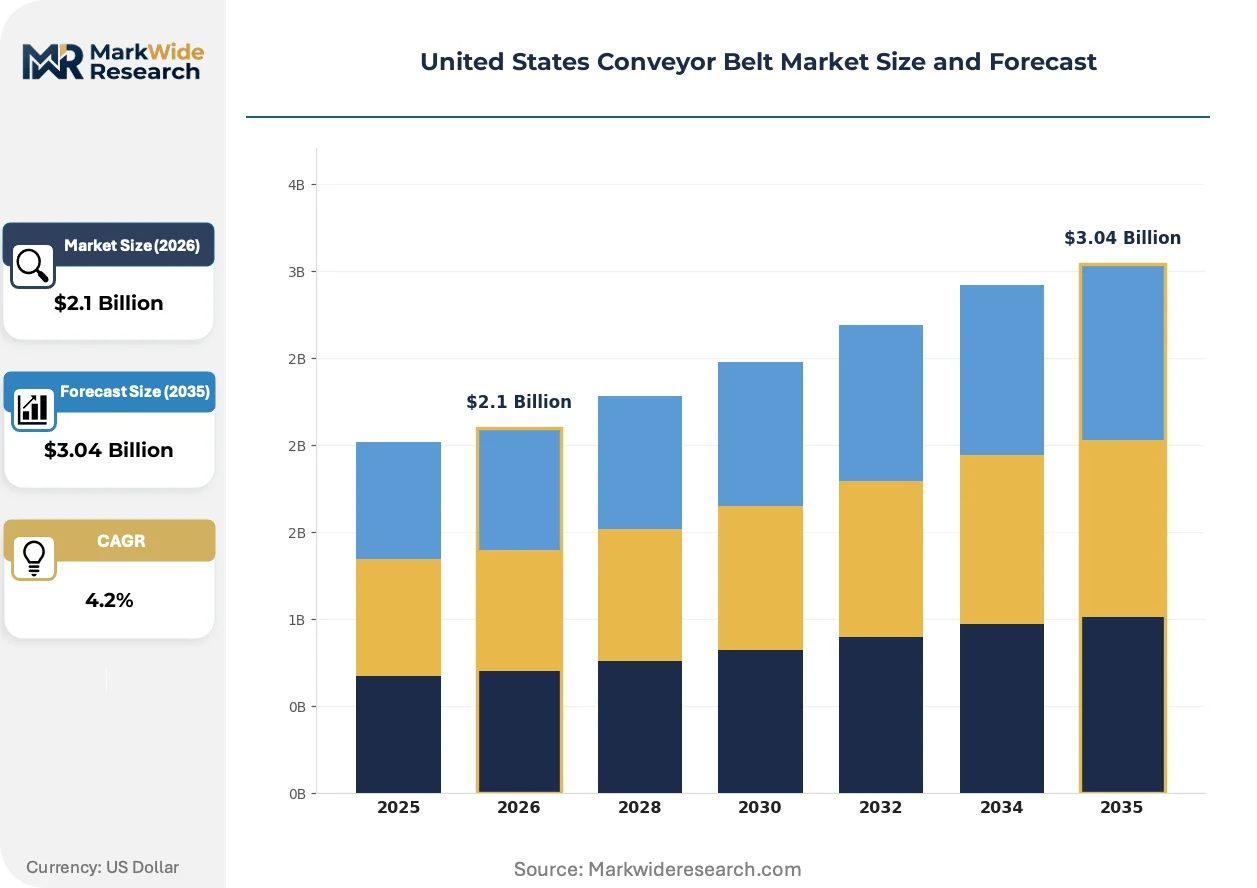
Market Dynamics
Replacement cycles for underground mining belts are compressing as MSHA fire-resistance standards tighten, while logistics operators in the Southeast and Southwest are expanding belt system deployments to match e-commerce fulfillment center construction.
Growth Catalysts
- MSHA Fire-Resistance Mandates:Updated underground belt standards are forcing mining operators to accelerate capital replacement schedules, creating sustained demand for certified heavy-duty rubber systems.
- Texas Petrochemical Expansion:Port and chemical processing infrastructure investments along the Gulf Coast are driving heavy-duty conveyor installations for bulk material handling.
- Zone-Based Fulfillment Architecture:E-commerce distribution centers are adopting modular conveyor configurations to enable same-day order processing velocity.
Market Restraints
- Steel Cord Supply Concentration:Domestic sourcing of high-tensile steel cord reinforcement remains dependent on limited North American wire rope manufacturers.
- Skilled Technician Scarcity:The industrial Midwest faces collapsing availability of certified belt splicing technicians, extending maintenance response times.
- Silica Dust Rule Uncertainty:Proposed OSHA expansion of respirable crystalline silica standards beyond mining into aggregate handling threatens retrofitted enclosure costs.
Strategic Opportunities
- Appalachian Mining Service Density:Same-day splicing capabilities in coal country remain underdeveloped relative to equipment replacement demand.
- Predictive Maintenance Contracts:Technician shortages are creating white space for OEMs to capture recurring revenue through sensor-enabled belt monitoring services.
- Automotive Just-in-Sequence Integration:Tier suppliers require engineered-to-order belt systems capable of sequenced parts delivery to assembly lines.
Industry Challenges
- Belt Splicing Certification Bottlenecks:MSHA-approved hot splice training programs operate at insufficient capacity to replace retiring technicians.
- Legacy System Integration Friction:New zone-based conveyor architectures face compatibility constraints with fixed infrastructure in established distribution centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Conveyor Belt Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lightweight, Medium-duty, Heavy-duty, Modular End User: Manufacturing, Mining, Food Processing, Logistics Material: Rubber, PVC, Polyurethane, Steel Installation: Fixed, Portable, Mobile, Custom |
| Companies Covered | BEUMER Corporation, LEWCO, Inc., Hytrol Conveyor Co., Inc., Material Handling Systems, Inc., Eriez, Intelligrated, Inc., Daifuku North America Corp., Fenner Dunlop Conveyor, Superior Industries, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Conveyor Belt Market Strategic Shifts & Innovations
Material specifications and procurement patterns are diverging across end-use verticals as regulatory pressure and automation requirements reshape belt system design priorities.
Modular plastic belting is fragmenting traditional fabric belt dominance in food processing environments. Washdown-compatible thermoplastic modules enable rapid sanitation cycles between production runs. Dairy and protein processors in the Upper Midwest are replacing fabric alternatives at accelerated rates, compressing the installed base value of legacy materials.
OSHA lockout-tagout enforcement for conveyor maintenance access is intensifying guard design requirements. The standard mandates physical isolation of energy sources during belt servicing, forcing redesign of tail pulley enclosures. Mining operators in Appalachia and the Mountain West are retrofitting legacy systems to comply, absorbing unplanned capital deployment.
Buyer concentration among third-party logistics providers is compressing vendor negotiation cycles. Large fulfillment operators are consolidating belt system specifications to reduce spare parts inventory complexity. This pattern is most visible in Texas and Georgia, where mega-facility operators are standardizing on single-source modular architectures to accelerate commissioning timelines.
United States Conveyor Belt Market Segmentation
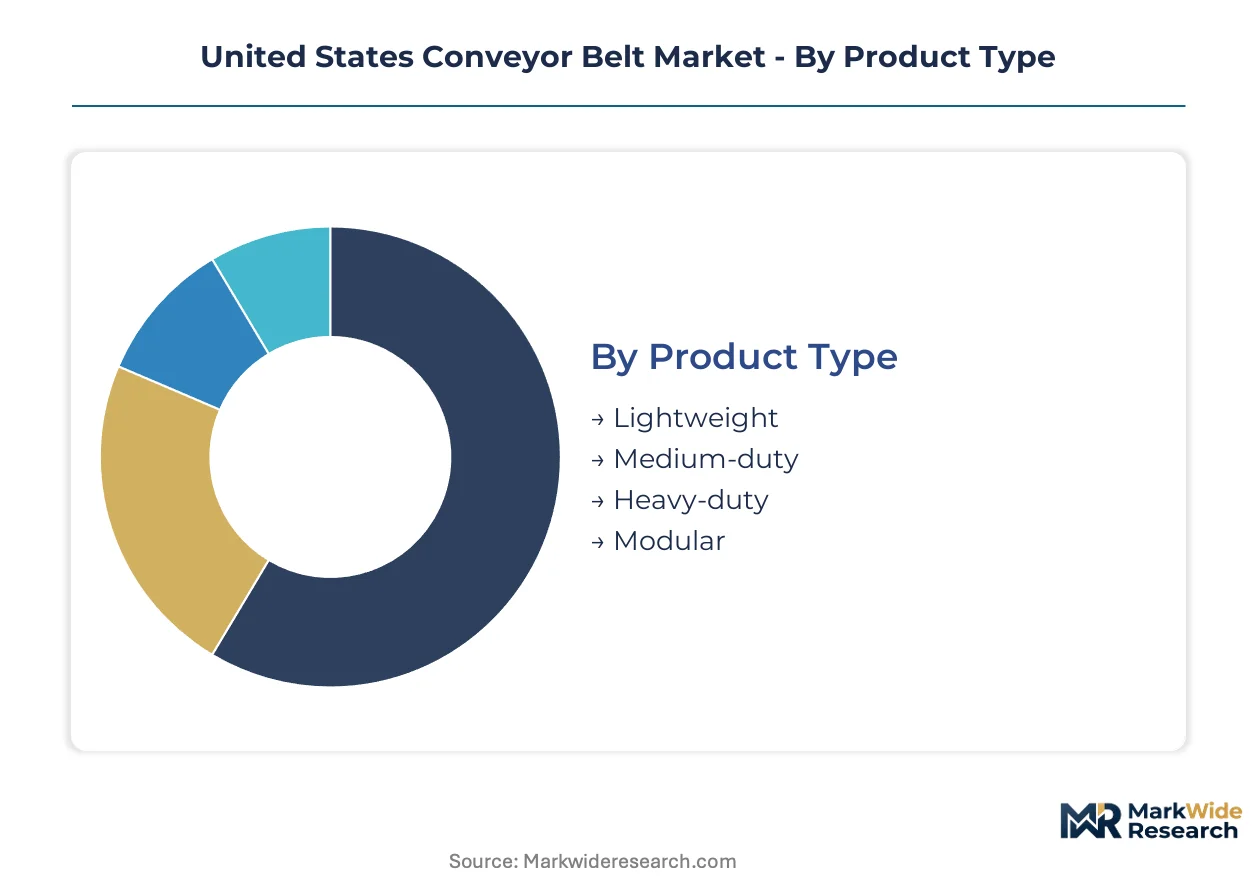
Conveyor belt procurement patterns diverge sharply across end-use verticals, with material specifications and installation architectures shaped by distinct regulatory pressures and throughput requirements. Understanding segment-level substitution dynamics enables suppliers to align R&D investment with defensible positioning.
Product Type:
Modular plastic systems are displacing fabric alternatives in washdown-intensive environments, while heavy-duty rubber retains irreplaceable positioning in MSHA-regulated underground mining.
- Lightweight:Fabric-reinforced belts with low tensile ratings serve parcel sortation and light manufacturing. Demand concentrates in Southeast logistics hubs where e-commerce fulfillment centers prioritize energy-efficient drive motor compatibility.
- Medium-duty:Multi-ply construction balances abrasion resistance with flexibility for automotive tier suppliers. Michigan and Ohio assembly corridors drive specification standardization around 3-ply EP carcass designs.
- Heavy-duty:Steel cord or solid woven carcasses rated above 1000 N/mm handle mining overburden and petrochemical bulk transfer. Texas Gulf Coast port expansions are accelerating installations for coal and aggregate export terminals.
- Modular:Interlocking thermoplastic segments enable rapid sanitation and directional reconfiguration. Dairy processors in Wisconsin and protein packers in Georgia are replacing legacy fabric belts at compressed replacement cycles.
Heavy-duty rubber anchors the volume base while modular plastic gains share at the steepest rate.
End User:
Logistics operators command the most consolidated procurement leverage, forcing specification standardization across multi-facility networks.
- Manufacturing:Assembly line integration demands precise speed control and parts-present sensors. Automotive tier suppliers in the Southeast specify engineered-to-order systems for just-in-sequence delivery synchronization.
- Mining:Underground coal and surface aggregate operations require MSHA-certified fire-resistant constructions. Appalachian replacement cycles are compressing as updated flame-resistance standards accelerate capital deployment.
- Food Processing:USDA-inspected facilities mandate washdown-compatible materials with embedded antimicrobial additives. Poultry processors in the Delmarva Peninsula and dairy cooperatives in the Upper Midwest drive modular plastic adoption.
- Logistics:Zone-based fulfillment architectures require modular configurations enabling same-day order velocity. Texas and Georgia mega-facility operators are consolidating vendor relationships to reduce spare parts inventory complexity.
Logistics commands the steepest expansion trajectory while mining retains the highest average selling prices through regulatory certification premiums.
Material:
Cost tier stratification separates commodity PVC from specification-grade polyurethane and steel-reinforced constructions.
- Rubber:Natural and synthetic polymer compounds dominate heavy-load applications with high abrasion exposure. Mining operators in West Virginia and Kentucky specify SBR-NR blends meeting MSHA flame-resistance mandates.
- PVC:Thermoplastic formulations offer chemical resistance at lower unit costs for general manufacturing. Light assembly operations in the industrial Midwest standardize on PVC for cost-containment in non-critical paths.
- Polyurethane:Cast thermoset constructions deliver superior cut resistance and load-bearing precision. Food processing OEMs specify polyurethane for direct product contact zones requiring extended service intervals.
- Steel:High-tensile cord reinforcement enables single-flight conveying over extreme distances and elevations. Copper mining in Arizona and bulk export terminals along the Mississippi River depend on steel cord for structural integrity.
Rubber retains the largest installed base value while polyurethane expands most quickly in premium food-grade applications.
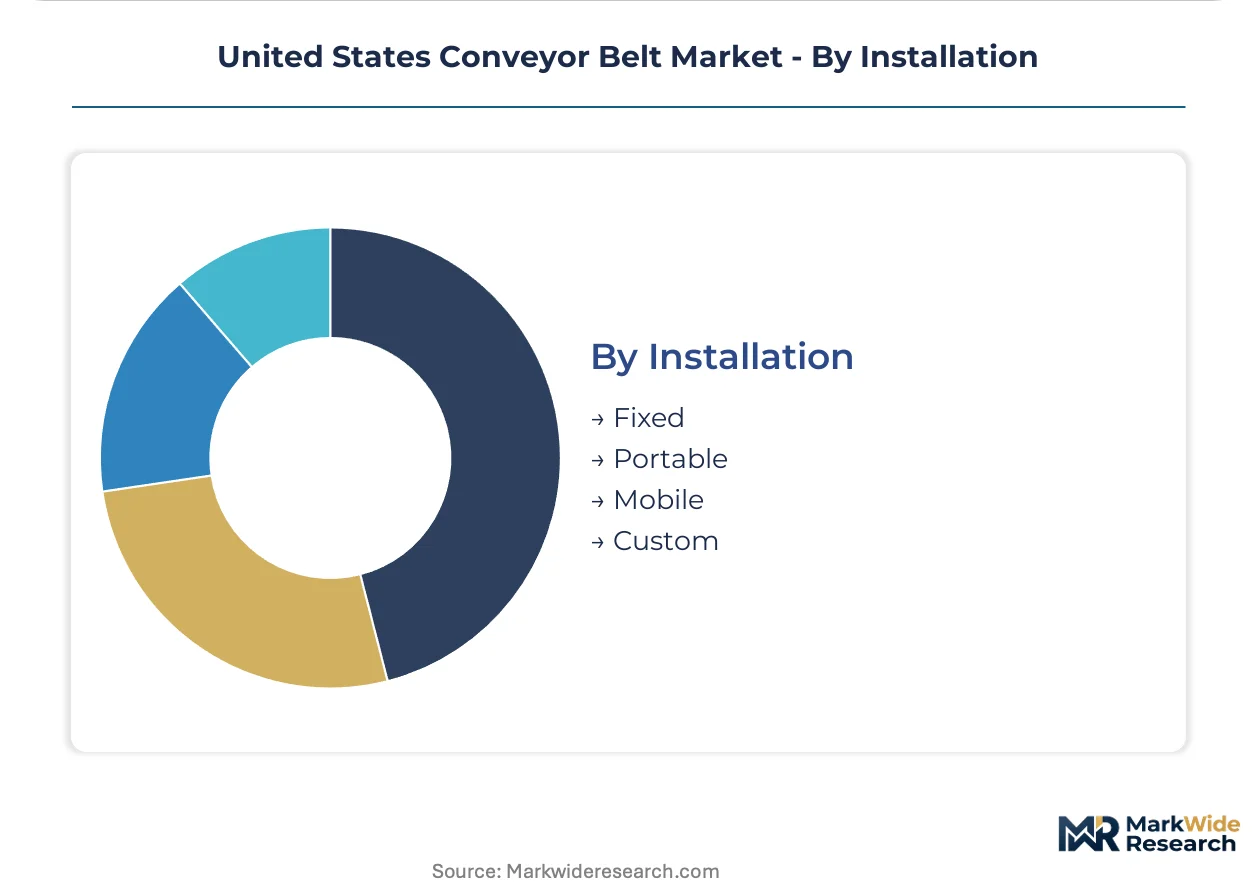
Installation:
Mobility requirements separate permanent infrastructure investments from flexible capacity augmentation strategies.
- Fixed:Permanent structural mounting with embedded support frameworks dominates established production facilities. Petrochemical complexes along the Texas Gulf Coast deploy fixed heavy-duty systems with 20-year design lifecycles.
- Portable:Skid-mounted or trailer-based configurations enable rapid redeployment across construction and aggregate sites. Quarries in the Mountain West utilize portable systems to follow excavation face progression.
- Mobile:Self-propelled units with integrated power and control systems serve intermittent bulk transfer needs. Port intermodal terminals in California deploy mobile conveyors for vessel-to-rail container stuffing operations.
- Custom:Engineered-to-order geometries address spatial constraints and specialized handling requirements. Automotive assembly plants in South Carolina specify custom curved configurations for sequenced parts delivery.
Fixed installations anchor capital deployment volumes while mobile configurations address the fastest-growing demand for operational flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the United States diverge sharply between bulk-material corridors and parcel-handling hubs, with regulatory pressure and infrastructure investment driving distinct procurement priorities in each sub-region.
Southeast
Logistics operators in Georgia and Florida are deploying zone-based conveyor architectures to match e-commerce fulfillment center construction. OSHA lockout-tagout enforcement for maintenance access is intensifying guard design requirements across distribution networks. Atlanta anchors the densest concentration of mega-facility operators standardizing on single-source modular systems.
Southwest
Texas petrochemical complexes and Gulf Coast port terminals are accelerating heavy-duty steel-cord installations for coal and aggregate export handling. Department of Transportation port infrastructure grants are indirectly stimulating belt system demand at coastal intermodal terminals. Houston and Corpus Christi drive specification standardization around 20-year design lifecycle fixed systems.
Appalachia
Underground coal operations in West Virginia and Kentucky face compressed replacement cycles as MSHA fire-resistance standards tighten. MSHA-approved hot splice training programs operate at insufficient capacity to replace retiring technicians. The Mountain West coal belt sustains demand for SBR-NR blend constructions meeting flame-resistance mandates.
Industrial Midwest
Automotive tier suppliers in Michigan and Ohio specify engineered-to-order belt systems for just-in-sequence delivery synchronization. Skilled conveyor maintenance technician availability is collapsing across the region, forcing end-users toward predictive maintenance contracts. Detroit and Toledo assembly corridors standardize on 3-ply EP carcass designs for medium-duty applications.
Mountain West
Copper mining in Arizona and surface aggregate quarries depend on steel-cord reinforcement for single-flight conveying over extreme elevations. Portable skid-mounted configurations enable rapid redeployment across construction sites following excavation face progression. Phoenix and Tucson anchor bulk-material handling infrastructure serving southwestern construction markets.
United States Conveyor Belt Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding specification-grade certification premiums and the lower tier competing on aftermarket responsiveness. The market structure reflects consolidation around heavy-duty mining-grade suppliers and fragmentation across modular logistics specialists. Two strategic archetypes dominate: vertically integrated manufacturers with captive steel-cord supply and regional service networks with dense field technician deployment. Competitive moves center on predictive maintenance contract capture and Appalachian service density expansion.
Within the integrated manufacturing tier, Fenner Dunlop Conveyor and Hytrol Conveyor Co., Inc. anchor distinct positioning vectors. Fenner Dunlop leverages its Appalachian manufacturing footprint to sustain same-day belt splicing services for mining clients. Hytrol anchors its position through a distributor network that controls aftermarket parts availability in the Southeast. LEWCO, Inc. sits within the engineered-to-order specialist tier, occupying a position serving automotive tier suppliers navigating just-in-sequence delivery requirements.
| Leading Market Players |
|---|
| BEUMER Corporation |
| LEWCO, Inc. |
| Hytrol Conveyor Co., Inc. |
| Material Handling Systems, Inc. |
| Eriez |
| Intelligrated, Inc. |
| Daifuku North America Corp. |
| Fenner Dunlop Conveyor |
| Superior Industries, Inc. |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts with petrochemical and port operators lock in multi-year supply access for heavy-duty steel-cord manufacturers while anchoring price visibility against raw material volatility. These arrangements concentrate procurement leverage among Texas Gulf Coast infrastructure developers, compressing negotiation cycles for modular logistics systems in parallel.
Pricing Analysis
Contract-based long-term offtake dominates heavy-duty rubber procurement, with MSHA certification tier and volume scale driving price differentiation between Appalachian mining operators and coastal export terminals. Pricing pressure stems from skilled technician scarcity forcing predictive maintenance bundling, while logistics buyers in Georgia and Texas exhibit highest price sensitivity due to standardized modular specifications.
Supply Chain Analysis
The United States and Canada anchor steel-cord reinforcement production, while Mexico feeds fabricated belt components for light-duty applications. Domestic supply draws from SBR-NR polymer compounds and high-tensile wire rope, with single-source vulnerability concentrated in MSHA-approved hot splice training capacity. Distribution runs through OEM field service networks and regional distributor partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards operators who control scarce splicing certification capacity and dense Appalachian service footprints, as technician availability constraints reshape competitive moats around maintenance responsiveness rather than manufacturing scale alone.
For Market Incumbents: Secure MSHA-approved training program expansion to capture retiring technician replacement demand, while tightening distributor exclusivity in Southeast logistics corridors against modular plastic substitution threats. Backward integration into steel-cord supply hedges raw material concentration risk. For New Entrants and Emerging Players: Lead with predictive maintenance platform development targeting Midwest automotive tier suppliers, where just-in-sequence integration requirements outpace incumbent service density. White space concentrates in sensor-enabled belt monitoring for distribution centers in Texas and Georgia. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated manufacturers with captive Appalachian service networks, as these assets compound pricing power across replacement cycle compression. The inflection signal to watch is OSHA silica dust rule expansion triggering enclosure retrofit demand beyond mining.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Contract Expansion | Sensor-enabled monitoring captures recurring revenue from technician-scarce Midwest automotive corridors. |
| MSHA Certification Training Scale-Up | Hot splice program capacity locks in Appalachian mining replacement cycle participation. |
| Modular Plastic Belting Manufacturing | Thermoplastic production lines serve Georgia and Wisconsin food processing washdown conversion. |
| Backward Integration into Steel-Cord Supply | Captive wire rope production insulates against North American manufacturer concentration risk. |
| Zone-Based Fulfillment Architecture Partnership | Collaboration with Texas mega-facility operators standardizes spare parts inventory specifications. |
Research Approach
The analysis maps heavy-duty rubber, modular plastic, lightweight fabric, and medium-duty multi-ply segments, each validated through maintenance directors at mining operations, plant engineers at automotive tier suppliers, procurement leads at third-party logistics providers, and aftermarket service heads at OEM distribution networks. Primary interview findings triangulate against MSHA regulatory filings, OSHA enforcement databases, port authority capital expenditure disclosures, and SEC 10-K supply chain disclosures, with bottom-up installation data reconciled against top-down end-use consumption estimates.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. The analytical framework models product type, end-user vertical, material composition, and installation mobility, with CAGRs derived from regression analysis of replacement cycle compression and infrastructure investment patterns. Industry-specific inputs include MSHA fire-resistance mandate implementation timelines and e-commerce fulfillment center construction permits.
Forecasts assume regulatory continuity in MSHA underground belt standards and OSHA lockout-tagout enforcement; material policy shifts would require re-modeling of replacement demand timing and retrofit capital allocation. Recalibration cycles align with material shifts in silica dust rule promulgation and port infrastructure grant disbursement velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
India Automated Material Handling (AMH) Market
Material Handling Equipment
Rubber Tired Gantry (RTG) Crane Market
Material Handling Equipment
Ball Screw Support Unit Market
Material Handling Equipment
Belt Scales Market
Material Handling Equipment
Global Pipe and Tube Bending Machine Market
Material Handling Equipment
Hose Pump Market
Material Handling Equipment
Slitting Machines Market
Material Handling Equipment
Global Warehouse Racking Market
Material Handling Equipment
Pipe Belt Conveyor Market
Material Handling Equipment
Level Loader Market
Material Handling Equipment
Global Rolling Mill Rolls Market
Material Handling Equipment
Container Handler Market
Material Handling Equipment
Hot-Rolling Mill and Cold-Rolling Mill Market
Material Handling Equipment
Global Air Cannon System Market
Material Handling Equipment
Pneumatic Caster Market
Material Handling Equipment
Dock Levelers Market