
 Spring Shackles Market | 2026-2036
Spring Shackles Market Size, Share, and Industry Trends Forecast 2026-2036
Spring Shackles Market Analytics
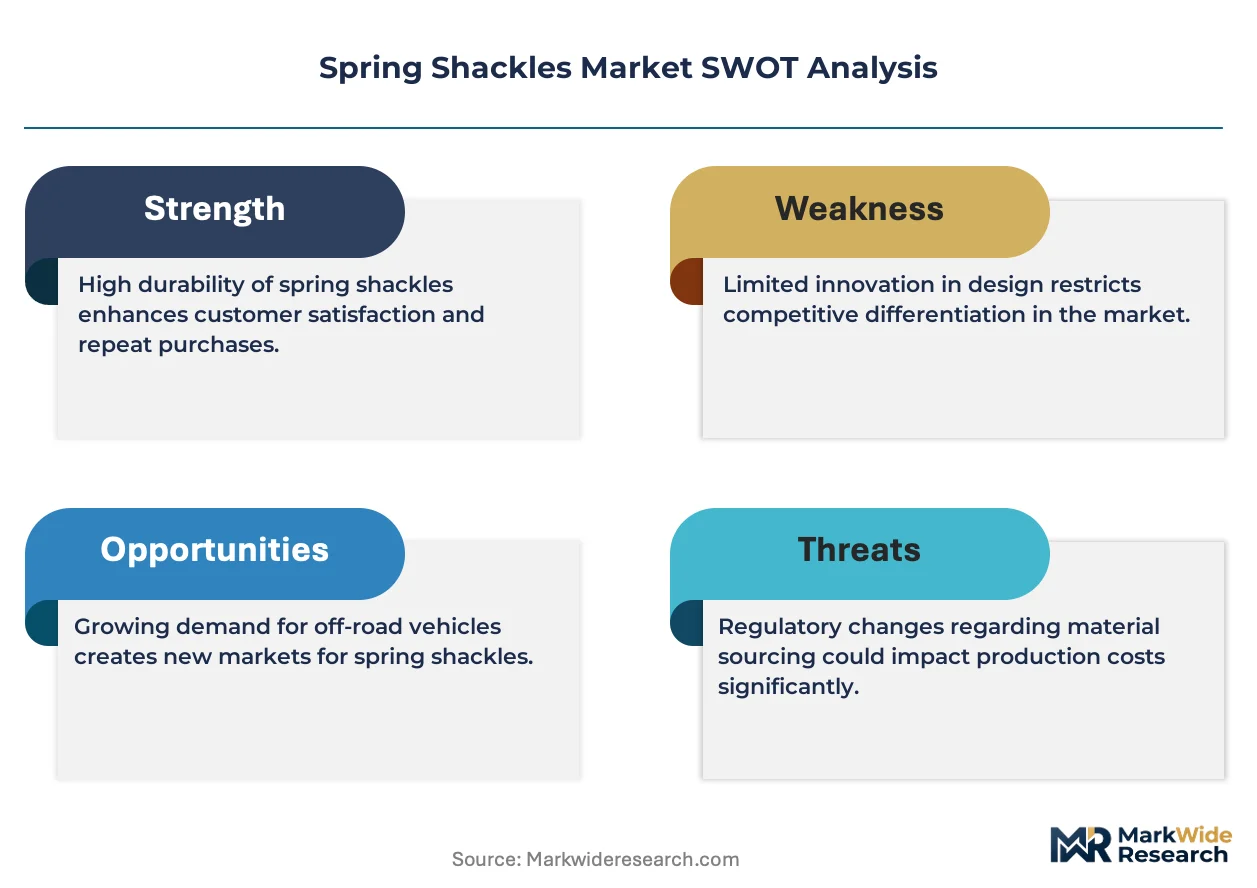
High-strength alloy forging is rewriting the manufacturing economics of spring shackle production, enabling thinner cross-sections without sacrificing fatigue life. Hendrickson USA, L.L.C. leverages its integrated foundry network to control material specifications from melt to finish. Jamna Auto Industries anchors its position through dedicated capacity serving Indian commercial vehicle OEMs. NHK Spring Co., Ltd. differentiates via precision coil processing expertise inherited from its broader automotive spring portfolio.
Spring shackles are U-shaped or looped mechanical links that connect leaf springs or coil assemblies to vehicle chassis frames, typically manufactured from medium-carbon or alloy steel through hot forging, quenching, and tempering to achieve tensile strengths exceeding 1200 MPa. Their primary purpose is to permit controlled articulation of the suspension system while maintaining axial alignment under dynamic load. Steel material grades dominate the installed base due to established fatigue performance and repair infrastructure, though composite formulations are gaining traction in weight-sensitive aerospace applications. The automotive application segment carries the largest volume footprint, while marine and industrial niches command premium pricing for corrosion-resistant specifications.
The National Highway Traffic Safety Administration enforces FMVSS standards governing suspension component integrity under cyclic loading, directly shaping product validation protocols for suppliers serving the US aftermarket. EPA corrosion prevention regulations and ISO 9001 quality management requirements add compliance layers that filter smaller fabricators from OEM supply chains. Stakeholders must monitor evolving material substitution trends and regulatory harmonization between North American and European testing protocols to anticipate certification cost shifts.
Market Dynamics
Heavy-duty commercial vehicle fleets are accelerating replacement cycles for suspension components as NHTSA enforcement of FMVSS 126 stability control mandates intensifies axle load scrutiny across interstate corridors.
Growth Catalysts
- DOT Safety Mandates:Evolving Federal Motor Carrier Safety Administration hours-of-service rules compress fleet downtime, driving preventive maintenance schedules for wear-critical shackle assemblies.
- High-Strength Alloy Forging:Hot-forming advances enable 15% mass reduction in shackle cross-sections while maintaining 1200 MPa tensile thresholds, opening retrofit demand from weight-conscious operators.
- Freight Tonnage Expansion:United States intermodal container volumes sustain replacement part throughput at independent service centers and dealer networks.
Market Restraints
- Scrap Steel Volatility:Medium-carbon and alloy steel feedstock prices fluctuate with electric arc furnace capacity utilization, compressing forging margin structures.
- OEM Supply Chain Concentration:Tier-1 suspension integrators in Michigan and Ohio control specification-setting, limiting aftermarket pricing autonomy for independent fabricators.
- Composite Substitution Threat:Carbon-epoxy leaf spring systems in aerospace ground support equipment eliminate shackle requirements entirely in weight-critical niches.
Strategic Opportunities
- Corrosion-Resistant Marine Specifications:Saltwater-exposed workboat fleets in Louisiana and Florida generate premium pricing for hot-dip galvanized and stainless-steel shackle variants.
- Rebuild-versus-Replace Programs:Fleet sustainability initiatives favor remanufactured suspension links, creating service revenue streams distinct from new part sales.
- Precision Coil Processing Convergence:Integration of CNC bending with robotic welding is hybridizing production economics for low-volume custom shackle orders.
Industry Challenges
- FMVSS Validation Timelines:NHTSA cyclic loading certification protocols extend product launch cycles by 8-14 months for modified geometries.
- Heat Treatment Skill Scarcity:Quenching and tempering expertise required for 1200 MPa fatigue performance concentrates among aging workforce cohorts in Great Lakes forging clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spring Shackles Market |
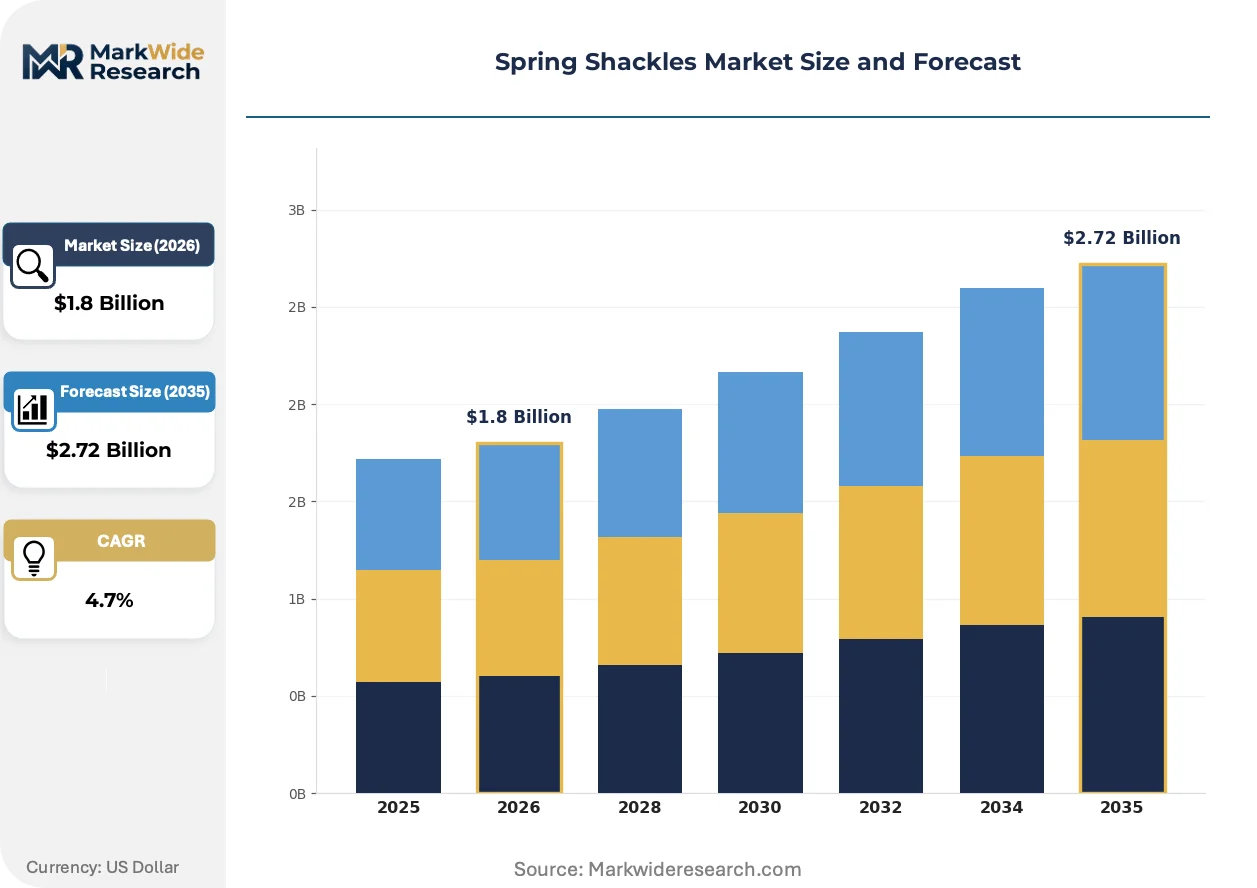
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Spring, Double Spring, Coil Spring, Leaf Spring Material: Steel, Aluminum, Composite, Titanium Application: Automotive, Aerospace, Marine, Industrial Size: Small, Medium, Large, Custom |
| Companies Covered | Hendrickson USA, L.L.C., Jamna Auto Industries, NHK Spring Co., Ltd., RSB Group, Dobinsons Spring, Dorman Products Inc, Frauenthal Group, Sogefi Group, Dayton Parts, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spring Shackles Market Evolving Landscape
Digital thread integration across forging operations is compressing design-to-die lead times while predictive maintenance algorithms reshape fleet procurement of wear components.
Induction hardening with real-time pyrometry is hybridizing surface treatment economics, enabling case-depth uniformity previously achievable only through slower flame methods. Heavy-truck remanufacturers in the Midwest are adopting this hybrid approach to extend shackle fatigue life for second-use applications. The technology is compressing cost differentials between new and rebuilt suspension links.
EPA corrosion prevention regulations under the Toxic Substances Control Act are restricting hexavalent chromium conversion coatings historically applied to military and marine-grade shackles. Suppliers are migrating to trivalent chromium and zinc-nickel alternatives, with qualification costs falling most heavily on small-batch fabricators serving defense aftermarket channels.
Fleet procurement departments are unbundling suspension service from comprehensive maintenance contracts, creating direct purchasing relationships with component manufacturers. Independent repair facilities in Texas and California are capturing this disintermediated volume through e-commerce platforms that bypass traditional parts distribution hierarchies.
Spring Shackles Market Segmentation
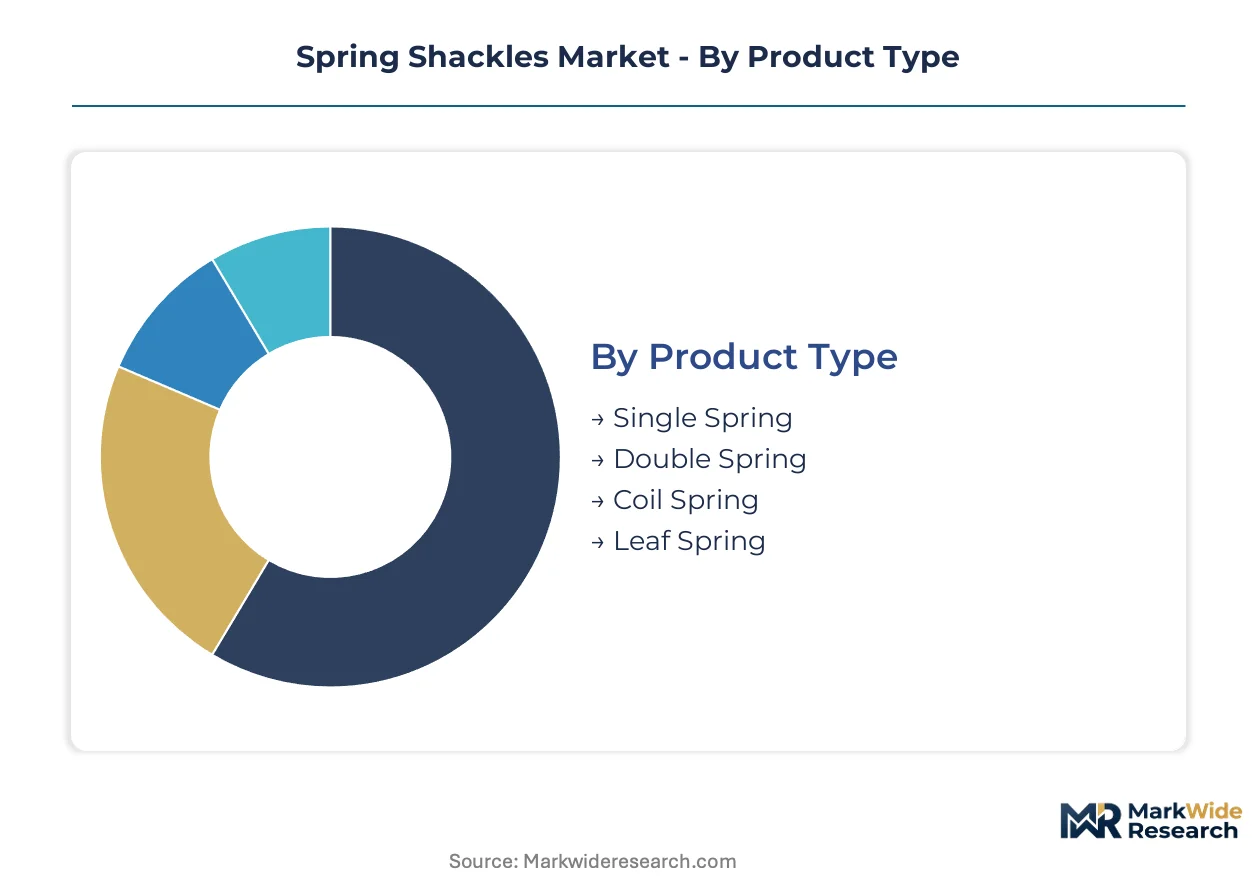
Spring shackle segmentation reflects divergent technical requirements across load-bearing specifications and environmental exposure conditions. Product architecture, material selection, and dimensional class each create distinct procurement channels and margin profiles for suppliers serving heterogeneous end-use markets.
Product Type:
Mature forged designs dominate commercial vehicle replacement volumes, while emerging coil-integrated configurations capture share in lightweight suspension architectures.
- Single Spring:U-shaped forged links with single pivot geometry serve light-duty trucks and utility trailers where cost minimization outweighs articulation range. Demand concentrates in United States independent repair facilities serving owner-operator fleets under FMVSS 126 compliance pressure.
- Double Spring:Dual-loop configurations with redundant load paths address heavy-haul applications exceeding 20,000 lb axle ratings. North American freight tonnage expansion sustains replacement throughput at dealer networks serving interstate carriers.
- Coil Spring:Integrated shackle-spring assemblies for independent rear suspensions reduce part count in passenger vehicle architectures. OEM specification control limits aftermarket pricing autonomy.
- Leaf Spring:Traditional multi-leaf stack interfaces retain dominance in vocational trucks and military ground vehicles. Established fatigue performance and repair infrastructure sustain installed base longevity.
Leaf Spring configurations retain volume leadership; Coil Spring variants hold the steepest expansion curve in passenger vehicle lightweighting programs.
Material:
Cost tier stratification separates commodity steel grades from premium alloys and experimental composites, with qualification barriers determining supplier participation.
- Steel:Medium-carbon and alloy grades processed through hot forging, quenching, and tempering achieve tensile strengths exceeding 1200 MPa. Scrap volatility compresses forging margin structures across Great Lakes production clusters.
- Aluminum:Forged 7075-T6 and similar alloys deliver 40% mass reduction for aerospace ground support equipment. Weight-critical commercial vehicle retrofits in California generate niche demand.
- Composite:Carbon-epoxy formulations eliminate corrosion liability in marine environments. Saltwater-exposed workboat fleets in Louisiana and Florida absorb premium pricing for extended service intervals.
- Titanium:Ti-6Al-4V aerospace grades command extreme price multiples for military and space launch applications. Limited domestic melting capacity constrains supply expansion.
Steel retains volume leadership; Composite formulations gain share fastest in corrosion-sensitive niches.
Application:
Customer type differentiation separates high-volume fleet procurement from specification-driven aerospace and marine channels with divergent certification requirements.
- Automotive:Light, medium, and heavy-duty vehicle suspensions generate the largest unit demand. United States intermodal container volumes sustain replacement part throughput at service centers.
- Aerospace:Ground support equipment and landing gear linkages require NDT-traceable material certifications. FAA validation protocols extend supplier qualification timelines.
- Marine:Saltwater immersion demands hot-dip galvanized or stainless-steel specifications. Gulf Coast workboat operators prioritize extended corrosion warranties.
- Industrial:Mining, agriculture, and material handling equipment subject shackles to abrasive and impact loading. Remanufactured links capture sustainability-focused procurement.
Automotive retains volume leadership; Marine specifications expand most quickly on offshore energy infrastructure investment.
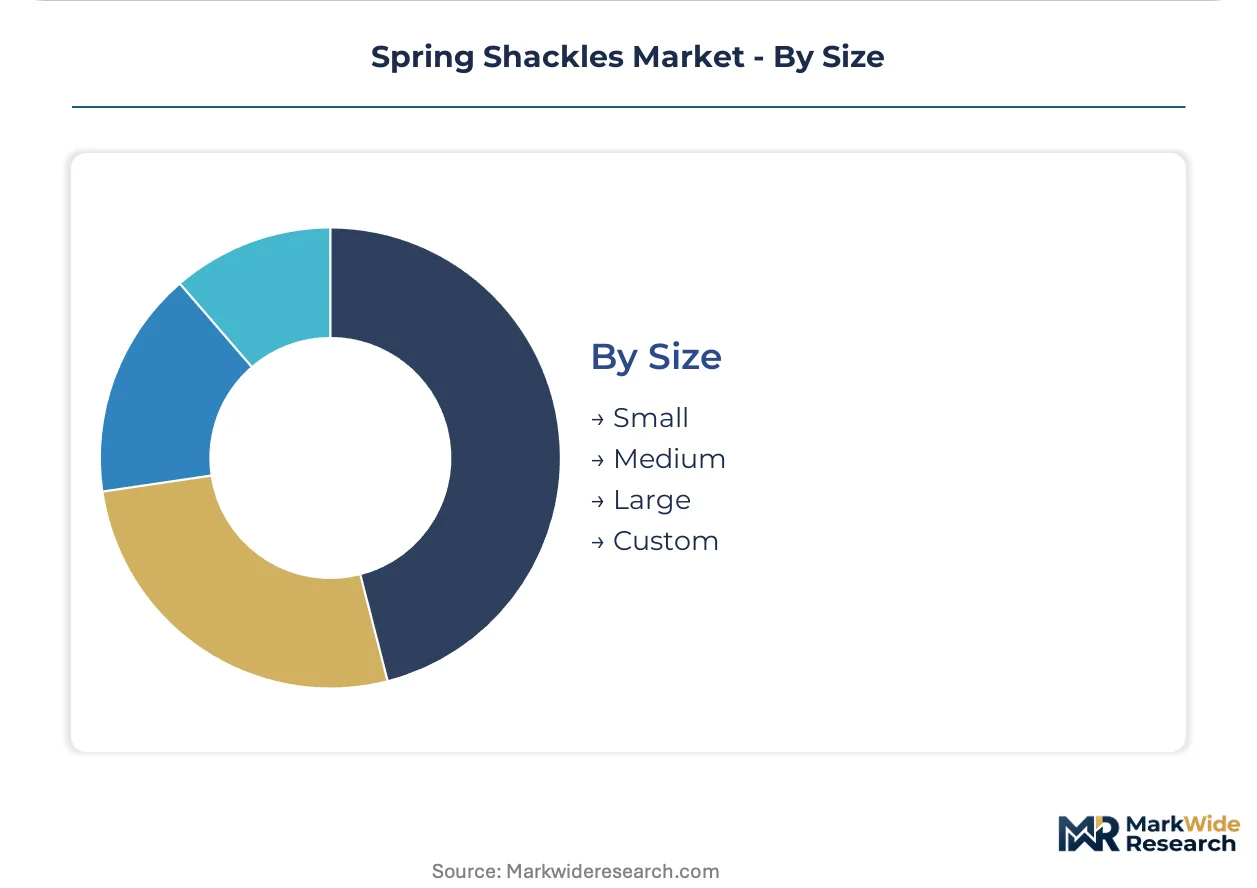
Size:
Volume concentration in standardized dimensions contrasts with margin accretion in engineered-to-order geometries requiring CNC bending and robotic welding integration.
- Small:Light-duty links under 4-inch eye spacing serve passenger vehicles and compact utility trailers. High-volume production amortizes tooling across multi-platform OEM programs.
- Medium:Mid-range dimensions dominate Class 3-6 commercial vehicle suspensions. Fleet standardization sustains replacement part demand.
- Large:Heavy-haul and mining truck applications exceed 8-inch eye spacing with custom bushing configurations. Forging press capacity constraints limit supplier participation.
- Custom:Engineered geometries for prototype vehicles and restoration projects command 3-5x standard pricing. Low-volume CNC bending hybridizes production economics.
Medium sizes retain volume leadership; Custom specifications climb the fastest on restoration and prototype vehicle activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement departments in the United States drive the largest replacement part volumes, while German automotive OEMs and Indian commercial vehicle manufacturers anchor production demand across distinct regulatory environments.
United States
Intermodal freight tonnage expansion sustains aftermarket throughput at independent service centers in Texas and California. NHTSA enforcement of FMVSS 126 stability control mandates intensifies axle load scrutiny across interstate corridors. Detroit-area forging clusters concentrate heat treatment expertise for heavy-haul shackle specifications.
Germany
Premium automotive OEMs specify precision coil-integrated shackle assemblies for lightweight passenger vehicle architectures. KBA type-approval requirements govern suspension component validation under EU safety frameworks. Baden-Württemberg suppliers leverage precision engineering capabilities inherited from broader automotive spring portfolios.
India
Commercial vehicle OEMs drive dedicated forging capacity serving domestic fleet renewal cycles. BIS certification mandates shape material specification protocols for axle load-bearing components. Jamnagar and Pune industrial corridors concentrate hot-forging infrastructure for medium-duty truck suspensions.
Japan
Precision coil processing expertise supports hybrid vehicle suspension architectures demanding reduced unsprung mass. METI industrial standards govern fatigue performance testing for automotive chassis components. Chubu region suppliers integrate CNC bending with robotic welding for low-volume custom orders.
China
Domestic heavy-duty truck production sustains forging demand for leaf spring interface components. GB standards and MIIT regulations establish tensile strength thresholds for commercial vehicle suspension links. Shandong Peninsula clusters control medium-carbon steel feedstock integration from melt to finish.
Spring Shackles Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply hierarchies. OEM-integrated suspension suppliers in Michigan and Ohio dominate specification-setting for new vehicle programs, while independent fabricators capture aftermarket replacement cycles through dealer networks and e-commerce platforms. Three archetypes define competitive positioning: integrated foundry operators controlling material specifications, precision coil processing specialists, and regional forging houses serving fleet maintenance channels. Dominant competitive moves include backward integration into steel feedstock sourcing and geographic expansion through remanufacturing facility licensing.
Among North American-based fabricators, Hendrickson USA, L.L.C. represents the integrated foundry archetype with captive control over alloy specifications from melt to finish. Jamna Auto Industries exemplifies dedicated capacity alignment serving single-region commercial vehicle OEMs. NHK Spring Co., Ltd. occupies a position reflecting precision coil processing convergence with broader automotive spring portfolios.
| Leading Market Players |
|---|
| Hendrickson USA, L.L.C. |
| Jamna Auto Industries |
| NHK Spring Co., Ltd. |
| RSB Group |
| Dobinsons Spring |
| Dorman Products Inc |
| Frauenthal Group |
| Sogefi Group |
| Dayton Parts, LLC |
| Others |
Value Network & Pricing Analysis
Great Lakes forging clusters concentrate medium-carbon and alloy steel feedstock conversion, anchoring margin capture at heat treatment specialists serving FMVSS-certified OEM supply chains. Scrap volatility at electric arc furnaces compresses forging economics, pushing independent fabricators toward remanufactured link programs or corrosion-resistant marine specifications where pricing power persists.
Pricing Analysis
Cost-plus contracts indexed to Midwest scrap steel benchmarks dominate procurement between Tier-1 suspension integrators and forging houses. Pricing stratifies across FMVSS-certified OEM tiers, hot-dip galvanized marine variants, and standard aftermarket grades. Cost compression in commodity steel shackles is intensifying because electric arc furnace utilization swings erode fixed-margin structures. Fleet procurement departments exhibit highest price sensitivity, while aerospace ground support equipment buyers prioritize NDT-traceable certifications over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates at Detroit-area forging clusters, Jamnagar-Pune industrial corridors, and Chubu region precision coil processors. Supply draws from medium-carbon steel billets, alloy additives for 1200 MPa tensile grades, and zinc-nickel corrosion coatings replacing hexavalent chromium. Single-source vulnerability concentrates at aging heat treatment facilities in Great Lakes states. Distribution runs through OEM captive networks, independent dealer hierarchies, and disintermediated e-commerce platforms serving Texas and California fleet maintenance channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heat treatment expertise for 1200 MPa fatigue performance concentrates among workforce cohorts nearing retirement, creating replacement risk for forging operations dependent on quenching and tempering precision.
For Market Incumbents: Harden specification control by backward integration into alloy steel feedstock sourcing from melt to finish. Lock in captive heat treatment capacity through apprenticeship pipelines and robotic induction hardening deployment. Composite substitution in aerospace ground support equipment and EPA corrosion coating transitions threaten legacy process margins. For New Entrants and Emerging Players: Louisiana and Florida workboat fleets present underpenetrated demand for hot-dip galvanized and stainless-steel shackle variants at premium pricing. Precision coil processing convergence with CNC bending offers entry path for low-volume custom orders. Target rebuild-versus-replace sustainability programs as fleet procurement departments unbundle suspension service from comprehensive maintenance contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive spring specialists holding precision coil processing capabilities but lacking FMVSS validation infrastructure. Long-term viability hinges on regulatory harmonization between North American and European testing protocols. Monitor NHTSA enforcement intensity on FMVSS 126 stability control mandates as aftermarket volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Feedstock | Hendrickson USA controls material specifications from melt to finish, insulating margin from scrap volatility. |
| Robotic Induction Hardening Deployment | Midwest remanufacturers compress cost differentials between new and rebuilt suspension links. |
| Marine Specification Certification | Gulf Coast workboat operators absorb premium pricing for extended corrosion warranties. |
| E-Commerce Platform Disintermediation | Texas and California independent repair facilities bypass traditional parts distribution hierarchies. |
| Heat Treatment Apprenticeship Pipelines | Great Lakes forging clusters address skill scarcity among aging quenching and tempering workforce cohorts. |
Research Methodology
A standing panel of fleet maintenance directors, OEM suspension procurement managers, aftermarket distributor operations heads, and heat treatment facility supervisors provided ongoing calibration across the study. Primary fieldwork combined structured interviews with secondary validation from NHTSA FMVSS filings, EPA Toxic Substances Control Act corrosion prevention guidance, and customs records tracking medium-carbon steel billet flows. Bottom-up unit demand modeling triangulated against top-down freight tonnage expansion indicators.
Scenario bracketing around DOT enforcement intensity, scrap steel price bands, and composite substitution penetration shaped projection ranges across the analysis window. Segmentation dimensions modeled include product architecture, material grade tier, end-use application, and dimensional class. CAGRs derived from replacement cycle frequencies tied to fleet renewal patterns and axle load regulation compliance timelines. Forecast inputs incorporated intermodal container volume trajectories and electric arc furnace capacity utilization assumptions.
Practitioners should monitor NHTSA FMVSS 126 enforcement intensity, EPA coating regulation qualification cost burdens, and electric arc furnace scrap price volatility for early signals requiring forecast revision. Quarterly review of fleet preventive maintenance schedule compression and remanufactured link adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Truck Mounted Cranes Market
Material Handling Equipment
Industrial Carts Market
Material Handling Equipment
Conveyors and Belt Loaders Market
Material Handling Equipment
Autonomous Material Handling Equipment Market
Material Handling Equipment
Trencher Attachments Market
Material Handling Equipment
Air Classifying Mill Market
Material Handling Equipment
Pharmaceutical Material Handling Equipment Market
Material Handling Equipment
Hi Lift Jack Market
Material Handling Equipment
Conveyor Belt Market
Material Handling Equipment
Hoist Controller Market
Material Handling Equipment
Material Handling Automation Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Europe Conveyors Market
Material Handling Equipment
Vertical Platform Lift Market
Material Handling Equipment
Clinching Machines Market
Material Handling Equipment
Hydraulic Seals Market