
 Aluminum-Free Natural Food Color Market | 2026-2036
Aluminum-Free Natural Food Color Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum-Free Natural Food Color Market Outlook
The capital-intensity divergence between integrated extractors and formulation-only suppliers is rotating competitive advantage toward upstream botanical sourcing. Döhler GmbH leverages its vertical orchard networks across Mediterranean growing regions to secure pigment consistency. GNT Group B.V. anchors its position through proprietary spirulina extraction infrastructure that reduces batch-to-batch variation. Sensient Technologies Corporation differentiates via encapsulated delivery systems that improve light stability in finished applications.
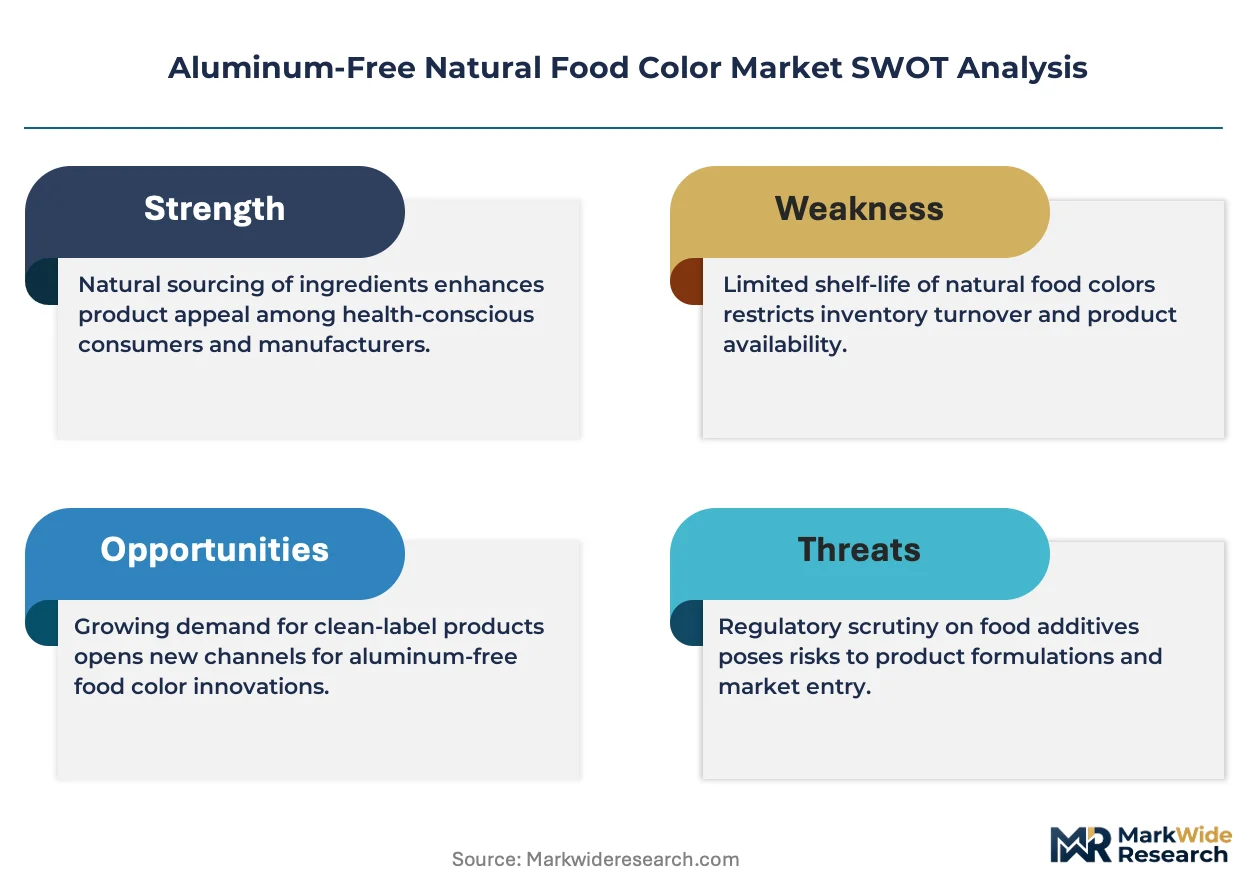
Aluminum-free natural food color comprises water-dispersible or oil-soluble pigments derived from vegetable, fruit, or botanical sources, typically standardized to specific color intensity measured in EBC units or absorbance values at defined wavelengths, and formulated without aluminum-based lake substrates to meet clean-label specifications. Its primary purpose is to restore or enhance visual appeal in processed foods where thermal processing, pH shifts, or storage conditions degrade native color. Beet juice dominates volume in dairy and beverage applications where anthocyanin stability challenges limit turmeric alternatives. Carrot juice competes aggressively in baking segments where beta-carotene pro-vitamin positioning commands formulation premiums. Spinach extract occupies niche premium positioning across organic confectionery lines where chlorophyllin copper complex alternatives face regulatory restrictions.
EFSA aluminum lake restrictions under EU food additive regulations, FDA color additive certification requirements, and Japan's Ministry of Health standards for natural color specifications collectively elevate compliance costs while accelerating aluminum-free substitution timelines. REACH chemical registration obligations in Europe further constrain novel pigment introduction pathways. Stakeholders must monitor evolving regulatory divergence between jurisdictions and pre-position dual-compliant formulation platforms before enforcement deadlines crystallize competitive displacement.
Market Dynamics
Clean-label regulatory mandates across multiple jurisdictions are forcing simultaneous aluminum lake phase-outs while pigment stability requirements intensify, compressing formulation timelines and elevating R&D burn rates for suppliers without captive extraction infrastructure.
Growth Catalysts
- EFSA aluminum lake restrictions:The European Union's additive reclassification under Regulation 1333/2008 accelerates substitution demand from confectionery and beverage manufacturers seeking compliant label claims.
- India processed food sector:FSSAI enforcement of natural color purity standards in packaged foods drives procurement shifts toward certified aluminum-free alternatives in dairy and bakery segments.
- Spirulina extraction infrastructure:Proprietary cultivation-to-powder systems reduce phycocyanin degradation rates, enabling broader deployment in pH-sensitive applications previously reserved for synthetic blues.
Market Restraints
- Anthocyanin thermal degradation:Beet and berry-derived pigments lose intensity above 85°C, restricting penetration into UHT dairy and retorted sauces where carmine lakes previously dominated.
- Mediterranean orchard concentration:Safflower, paprika, and annatto sourcing clusters in Spain and Morocco create weather-dependent supply volatility for oil-soluble orange-yellow formulations.
- Japan METI additive standards:Natural color specifications requiring batch-level heavy metal testing impose compliance costs that deter mid-tier suppliers from market entry.
Strategic Opportunities
- Germany natural ingredient clusters:Concentrated extraction and formulation expertise around Hamburg and Munich enables partnership models for Asian suppliers seeking European market access.
- Encapsulated delivery convergence:Liposome and cyclodextrin technologies combined with natural pigments extend light and oxygen stability, opening snack and cereal applications.
- Clean-label confectionery channel:Direct-to-manufacturer platforms bypass traditional distribution markups, capturing margin from premium organic chocolate and gummy segments.
Industry Challenges
- Phytochemical standardization expertise:Scarce analytical chemists capable of correlating spectral data with finished-product color consistency command compensation premiums that strain mid-cap R&D budgets.
- Dual-compliant formulation platforms:Pre-positioning simultaneous EU, FDA, and Japan-compliant variants requires parallel stability testing protocols that extend product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum-Free Natural Food Color Market |
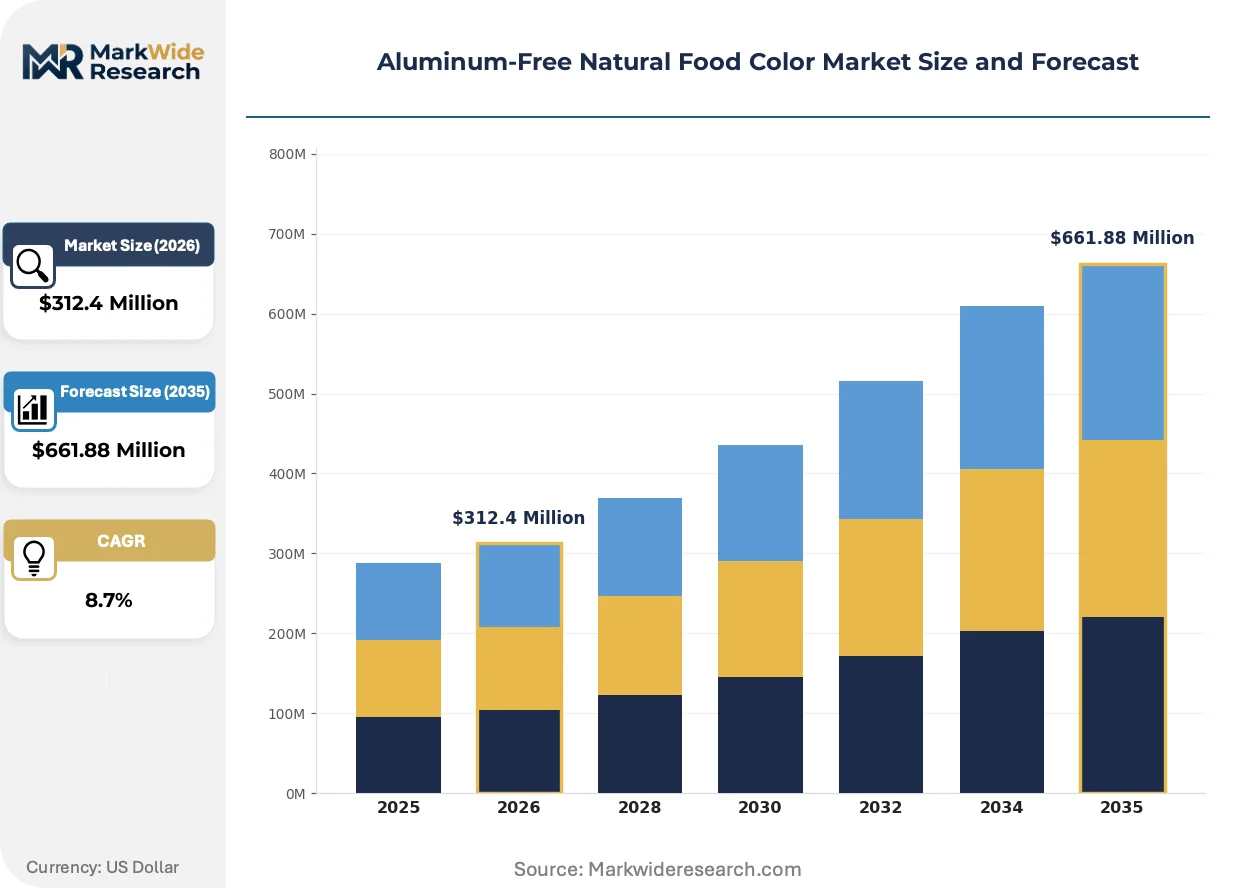
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beet Juice, Spinach Extract, Turmeric Powder, Carrot Juice Application: Baking, Beverages, Confectionery, Dairy End User: Food Manufacturers, Restaurants, Catering Services, Home Cooks Packaging Type: Glass Bottles, Pouches, Drums, Sachets |
| Companies Covered | Döhler GmbH, Givaudan SA, ADM, DDW The Color House, Kalsec Inc., NATUREX, Sensient Technologies Corporation, GNT Group B.V., Chr. Hansen A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum-Free Natural Food Color Market Strategic Shifts
Microencapsulation and fermentation-derived pigments are compressing the performance gap between natural and synthetic colorants, while regulatory divergence between jurisdictions forces modular formulation architectures.
Encapsulated natural color systems using modified starch and gum arabic matrices is miniaturizing protection layers around anthocyanin and carotenoid molecules. Dairy alternative manufacturers in Germany and the Netherlands are adopting these systems at pilot scale. The technology is miniaturizing degradation pathways, enabling natural pigments to survive extended shelf-life distribution previously reserved for aluminum lake formulations.
REACH chemical registration obligations under ECHA guidelines now require full toxicological dossiers for novel botanical extracts, including subchronic studies and exposure assessments. This documentation burden favors incumbent suppliers with existing registration portfolios. Natural color categories lacking historical food use in Europe before 1997 face Novel Food authorization pathways that delay commercialization by 18-24 months.
Ingredient procurement from food manufacturers is consolidating toward fewer, vertically capable suppliers who control extraction through finished formulation. Large North American CPG buyers now mandate supplier-owned cultivation or long-term orchard contracts as qualification criteria. This pattern concentrates procurement decisions among procurement directors at headquarters locations, reducing influence of regional formulation specialists.
Aluminum-Free Natural Food Color Market Segmentation
Aluminum-free natural food color suppliers configure product portfolios around pigment stability requirements that vary sharply across thermal processing intensities and pH environments. Segmentation discipline separates volume-driven commodity extracts from premium positioning in clean-label applications where regulatory compliance costs create tiered entry barriers.
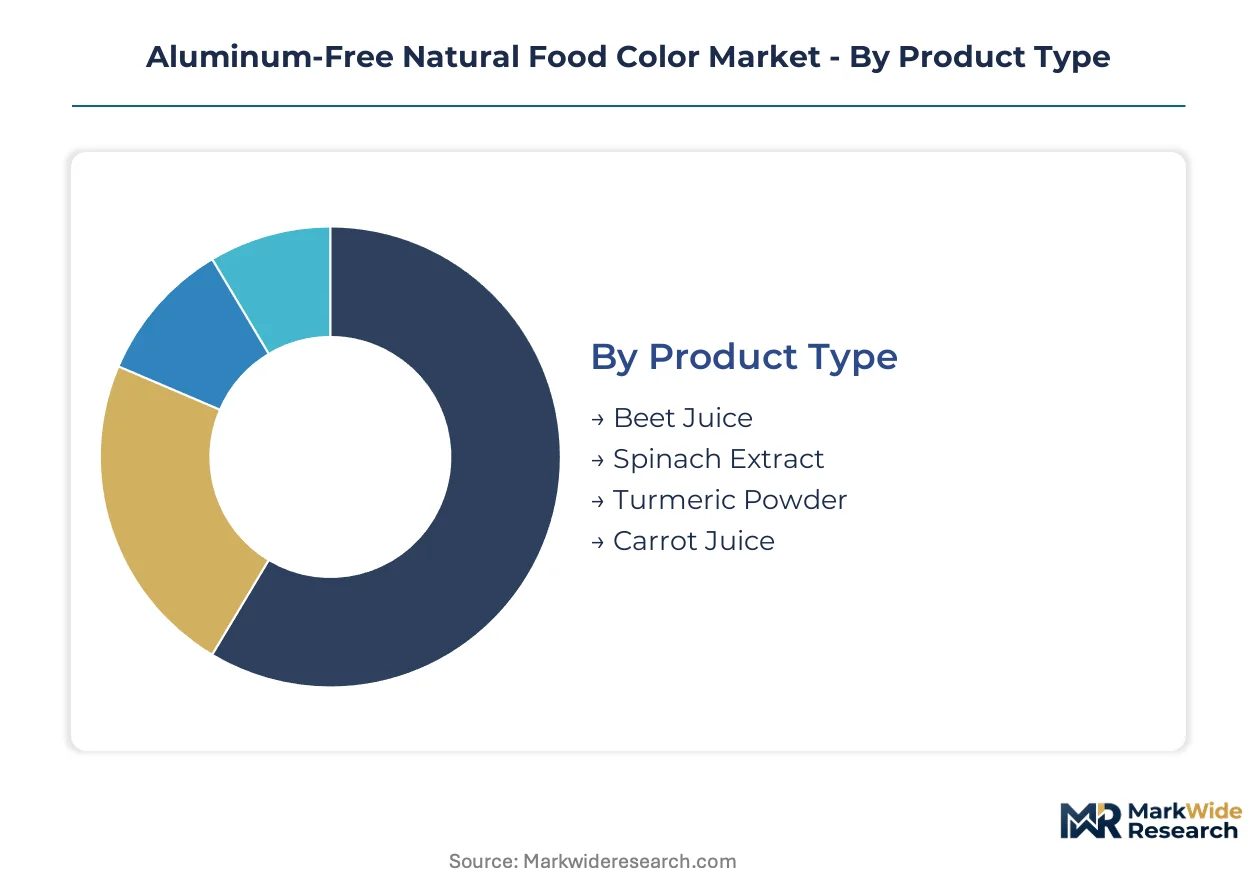
Product Type:
EFSA aluminum lake restrictions under EU Regulation 1333/2008 have reclassified formulation requirements, concentrating procurement specifications on heavy metal thresholds and color intensity standardization measured in EBC units.
- Beet Juice:Anthocyanin-rich water-soluble pigment standardized to specific betacyanin content, typically exhibiting thermal degradation above 85°C. Demand concentrates in German dairy alternative manufacturers where UHT processing limitations restrict deployment to refrigerated beverage lines and fresh cheese applications.
- Carrot Juice:Beta-carotene dominant oil-dispersible extract with pro-vitamin A positioning that commands formulation premiums. Baking segments in India absorb volume where FSSAI enforcement of natural color purity standards accelerates substitution from synthetic carotenoids in packaged biscuits and bread.
- Spinach Extract:Chlorophyll-derived pigment occupying niche premium positioning across organic confectionery lines where chlorophyllin copper complex alternatives face regulatory restrictions.
- Turmeric Powder:Curcumin-based yellow pigment with established GRAS status but limited pH stability below 3.0, restricting penetration into acidic beverage categories.
Established volume favors beet juice; emerging adoption favors carrot juice.
Application:
Cost tier differentiation separates commodity color restoration from premium visual positioning where thermal resilience commands ingredient premiums.
- Confectionery:Gummy and chocolate applications require light-stable pigments with encapsulated delivery systems to prevent surface fading during retail display. Clean-label confectionery channels in Germany and the Netherlands drive procurement consolidation toward vertically integrated suppliers with proprietary spirulina extraction infrastructure.
- Beverages:pH-sensitive anthocyanin formulations dominate dairy alternatives and juices where color intensity degradation during pasteurization limits shelf-life claims. India's expanding processed food sector absorbs volume as FSSAI standards tighten additive disclosure requirements.
- Baking:Heat-stable carotenoid demand concentrates in industrial biscuit and bread manufacturing where thermal processing exceeds 180°C.
- Dairy:Yogurt and fresh cheese applications favor water-dispersible beet and berry extracts with lower thermal exposure thresholds.
Confectionery captures premium pricing tiers; beverages represent the fastest-growing trajectory by volume.
End User:
Customer type fragmentation separates industrial procurement scale from fragmented foodservice purchasing patterns.
- Food Manufacturers:Large North American CPG buyers mandate supplier-owned cultivation or long-term orchard contracts as qualification criteria, concentrating procurement decisions among headquarters-based procurement directors. Direct-to-manufacturer platforms bypass traditional distribution markups in premium organic segments.
- Restaurants:Mid-tier dining chains in India adopt aluminum-free alternatives for menu transparency claims without the formulation stability requirements of retail packaged goods.
- Catering Services:Institutional volume procurement favors cost-optimized standard-grade extracts with basic heavy metal certification.
- Home Cooks:Retail sachet and small-format packaging channels serve specialty baking enthusiasts through e-commerce direct distribution.
Food manufacturers anchor procurement volume; restaurants are expanding most quickly as clean-label positioning penetrates foodservice.
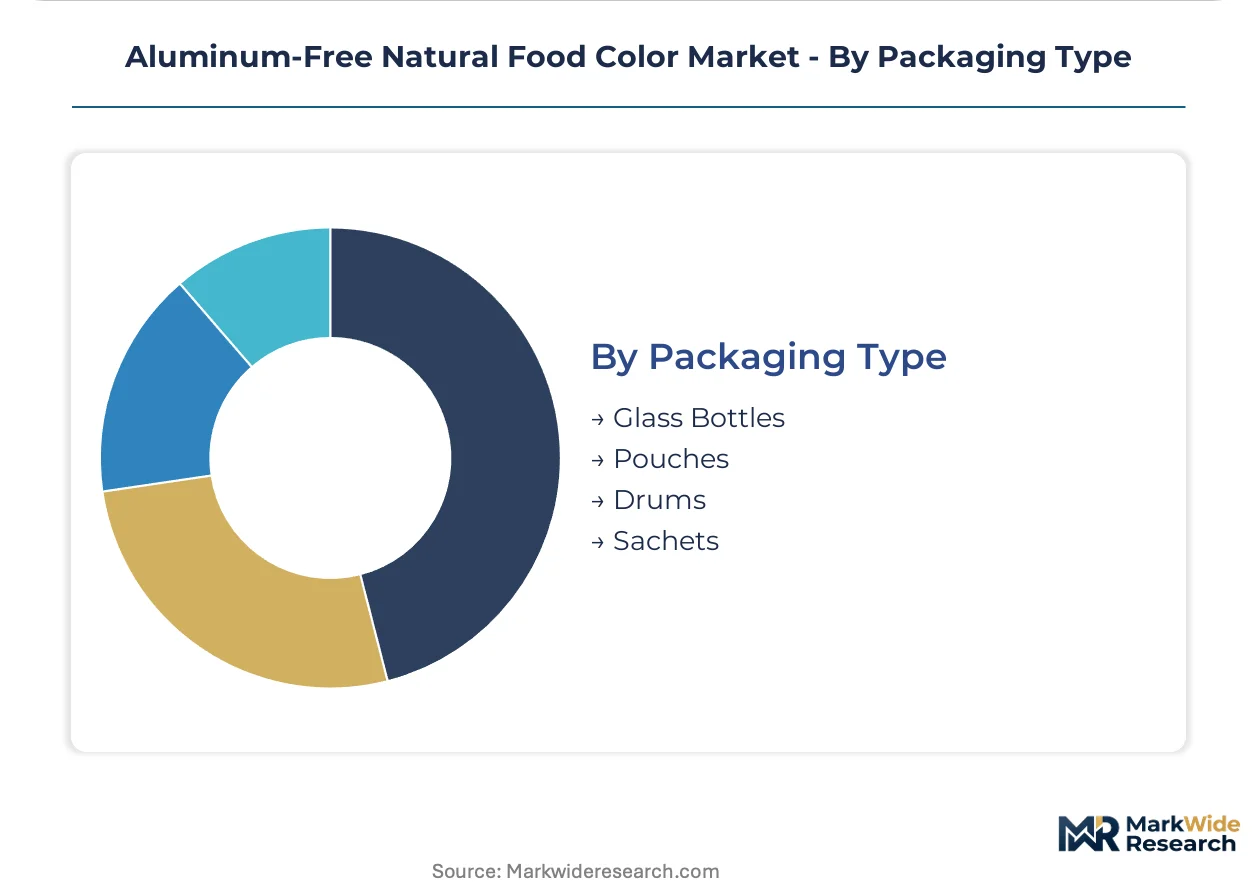
Packaging Type:
Supply concentration in Mediterranean orchard clusters for oil-soluble pigments shapes protective packaging requirements against oxidation and light degradation.
- Drums:Industrial-scale bulk liquid extracts for food manufacturers with captive formulation facilities and rapid inventory turnover.
- Glass Bottles:Premium retail and foodservice formats where oxygen barrier properties extend shelf life for high-value oil-soluble carotenoids.
- Pouches:Flexible intermediate formats for mid-scale bakeries and confectionery producers with moderate throughput requirements.
- Sachets:Single-use precision dosing for foodservice and home cooking segments where portion control reduces waste.
Drums dominate industrial procurement; pouches gain share fastest in mid-tier food manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of aluminum-free natural food colors concentrate from Mediterranean extraction clusters toward North American and Asian formulation hubs, with import dependency patterns reshaping procurement strategies across major processed food markets.
Germany
Clean-label confectionery manufacturers around Hamburg and Munich drive procurement volume for spirulina-derived blue pigments. EFSA aluminum lake restrictions under EU Regulation 1333/2008 mandate reformulation timelines that favor local suppliers with captive extraction infrastructure. The country's natural ingredient processing clusters now anchor European distribution networks for beet and carrot juice concentrates.
United States
Large CPG buyers mandate supplier-owned cultivation or long-term orchard contracts as qualification criteria, concentrating procurement decisions among headquarters-based procurement directors. FDA color additive certification requirements elevate compliance costs for imported extracts. California-based dairy alternative manufacturers pilot encapsulated anthocyanin systems for extended shelf-life claims.
India
FSSAI enforcement of natural color purity standards in packaged foods accelerates substitution from synthetic carotenoids in biscuit and bread manufacturing. The country's expanding processed food sector absorbs volume in dairy and bakery segments. Maharashtra and Gujarat host emerging formulation facilities serving domestic and export markets.
Japan
METI food additive standards requiring batch-level heavy metal testing impose compliance costs that filter mid-tier suppliers from market entry. Domestic manufacturers prioritize phycocyanin stability improvements for pH-sensitive applications. Tokyo-based procurement offices coordinate regional sourcing from spirulina cultivation networks.
Brazil
Annato and paprika sourcing from domestic orchard clusters reduces import dependency for oil-soluble orange-yellow formulations. ANVISA regulatory alignment with CODEX standards enables export qualification to European markets. São Paulo-state food manufacturers integrate South American botanical extracts into clean-label product lines.
Aluminum-Free Natural Food Color Market Competitive Environment
Concentration sits with integrated extractors controlling upstream botanical sourcing through captive orchard networks and proprietary cultivation infrastructure. The vendor base stratifies across three tiers: multinational ingredient conglomerates with full formulation capabilities, regional specialists with single-pigment extraction depth, and commodity traders lacking standardization expertise. Dominant competitive moves include backward integration into Mediterranean and tropical growing regions, plus technology licensing agreements for encapsulated delivery systems.
Within the integrated extraction tier, Döhler GmbH and GNT Group B.V. represent archetypes of vertical control over pigment supply chains, while Sensient Technologies Corporation exemplifies formulation-led positioning emphasizing delivery technology. These three entities anchor competitive dynamics through distinct capability emphases rather than overlapping strategic postures.
| Leading Market Players |
|---|
| Döhler GmbH |
| Givaudan SA |
| ADM |
| DDW The Color House |
| Kalsec Inc. |
| NATUREX |
| Sensient Technologies Corporation |
| GNT Group B.V. |
| Chr. Hansen A/S |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Mediterranean extraction facilities shapes both supply concentration and price floors for aluminum-free natural food colors. Scale economies in spirulina cultivation and carrot juice concentration create tiered entry barriers that filter mid-tier suppliers from premium pigment segments.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the aluminum-free natural food color market. Three-tier pricing structure across premium, standard, and economy levels separates encapsulated delivery systems from commodity extracts and unstandardized raw botanicals. Price differentiation stems from certification grade—EFSA-compliant variants command premiums over basic heavy metal-certified alternatives—and vertical integration depth. Cost compression in standard-grade beet juice concentrates is intensifying because Indian and Chinese suppliers are expanding extraction capacity. Food manufacturers with captive formulation facilities exhibit lowest price sensitivity; mid-tier bakeries and regional confectionery producers show highest sensitivity.
Supply Chain Analysis
Inventory cycles for oil-soluble carotenoids extend 8-14 weeks due to Mediterranean harvest seasonality and subsequent extraction scheduling. Geographic supply concentration centers on Spain and Morocco for paprika and safflower, India for turmeric and annatto, and Germany for spirulina-derived phycocyanin. Raw material dependencies include specific betacyanin-rich beet cultivars, high-curcumin turmeric rhizomes, and temperature-sensitive spirulina biomass. Single-source vulnerability runs through proprietary extraction infrastructure controlled by integrated suppliers like GNT Group B.V. Distribution runs through direct-to-manufacturer platforms for large CPG buyers and specialized ingredient distributors for mid-tier food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum-free natural food color incumbents face substitution defense against fermentation-derived pigments and synthetic biology alternatives that compress the performance gap with natural extracts.
For Market Incumbents: Fortify upstream control over Mediterranean orchard networks and tropical cultivation zones to secure pigment consistency against weather-driven supply volatility. Deepen proprietary extraction infrastructure investments—particularly in spirulina phycocyanin and encapsulated delivery systems—to maintain performance differentiation against emerging fermentation-derived competitors. EFSA enforcement timelines for aluminum lake phase-outs create regulatory leverage for compliant incumbents. For New Entrants and Emerging Players: FSSAI fast-track certification for natural color purity standards offers entry pathway into India's expanding processed food sector. Target mid-tier bakery and dairy alternative manufacturers in Maharashtra and Gujarat seeking certified alternatives to synthetic carotenoids. White-space exists in clean-label confectionery channels where direct-to-manufacturer platforms bypass traditional distribution markups. Pursue partnership models with German natural ingredient clusters for European market access rather than standalone facility investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated extractors with captive cultivation infrastructure over formulation-only suppliers facing margin compression. Long-term viability rests on regulatory divergence between jurisdictions forcing dual-compliant formulation platforms that favor incumbents with existing registration portfolios. Acquisition target archetype: regional specialists with single-pigment extraction depth in underserved geographies. Signal to watch: Novel Food authorization timelines under ECHA guidelines that delay commercialization for novel botanical extracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Orchard ownership in Spain and Morocco reduces weather-dependent supply volatility for oil-soluble formulations. |
| Encapsulated Delivery System Development | Liposome and cyclodextrin technologies extend light stability for snack and cereal applications. |
| Dual-Compliant Formulation Pre-Positioning | Parallel EU-FDA-Japan testing protocols capture substitution demand before enforcement deadlines crystallize. |
| Direct-to-Manufacturer Platform Launch | Bypassing traditional distribution markups captures margin from premium organic chocolate and gummy segments. |
| Proprietary Spirulina Infrastructure Expansion | Cultivation-to-powder systems reduce phycocyanin degradation rates for pH-sensitive beverage applications. |
Study Parameters
A spread of perspectives from extraction facility managers, procurement directors at North American CPG buyers, FSSAI regulatory affairs specialists, and German natural ingredient formulators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through EFSA additive reclassification documents, FSSAI enforcement circulars, customs data on beet and carrot juice concentrate trade flows, and SEC filings from listed ingredient suppliers. Bottom-up triangulation across pigment-specific volume estimates and top-down cross-checks against total processed food colorant expenditure anchored the analytical framework.
Segmentation dimensions modeled include pigment source type, thermal stability tier, application processing intensity, end-user procurement scale, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for substitution elasticity and enforcement timeline probability. Forecast inputs incorporated EFSA aluminum lake phase-out schedules, FSSAI purity standard adoption curves, and spirulina cultivation capacity expansion announcements across the projection horizon.
The analysis sits within stated boundaries; outcomes outside sustained EFSA enforcement, stable Mediterranean growing conditions, or continued FSSAI tightening would require recalibration. Forecasts reflect documented assumptions about regulatory divergence persistence and clean-label premium retention. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Dairy Stabilizer Market
Food Additives and Ingredients
Acetylated Distarch Phosphate Market
Food Additives and Ingredients
Food Antimicrobial Additives Market
Food Additives and Ingredients
Natural Food Additives Market
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
United Kingdom Anti Caking Market
Food Additives and Ingredients
Emulsifiers Market
Food Additives and Ingredients
North America Food Stabilizers Market
Food Additives and Ingredients
United States Food Enzymes Market
Food Additives and Ingredients
Dairy Enzymes Market
Food Additives and Ingredients
Global Flaked Shortenings Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
Carrageenan Gum Market
Food Additives and Ingredients
Polyglycerol Esters of Fatty Acids Market
Food Additives and Ingredients
Argentina Food Acidulants Market
Food Additives and Ingredients
Transglutaminase Market